
 Lighting Contactor Market | 2026-2036
Lighting Contactor Market Size, Share, and Industry Trends Forecast 2026-2036
Lighting Contactor Market Intelligence
UL 508 certification is rotating the competitive field by mandating specific endurance and temperature-rise thresholds for industrial control equipment. Schneider Electric leverages captive supply chains for electromechanical cores across European manufacturing nodes. ABB Ltd. anchors its position through IEC-compliant modular platforms serving utility-scale street lighting networks. Siemens AG differentiates via solid-state contactor R&D intensity focused on semiconductor-grade thermal management.
A lighting contactor is an electrically operated switch designed to control high-current lighting circuits, typically rated between 20 and 1200 amperes with silver-alloy contacts to withstand repetitive switching cycles and inrush currents from ballast or LED driver loads. The device serves to automate illumination systems in commercial, industrial, and municipal infrastructure where manual switching proves impractical at scale. Electromechanical contactors still occupy the largest revenue pool due to replacement demand in legacy fluorescent and HID installations, though solid-state variants capture margin in applications demanding zero-contact arcing and million-cycle durability. DIN rail mounted configurations lead new installation volume in European commercial buildings where panel density and service accessibility drive specification, while flush mounted units dominate North American retrofit channels constrained by existing junction box footprints.
NEMA standards in the United States, IEC 60947 internationally, and the EU Ecodesign Directive collectively tighten efficiency and material-content requirements, forcing redesigns of coil assemblies and contact materials to reduce standby losses and eliminate restricted substances. The EPA Energy Star program for commercial buildings indirectly shapes demand by rewarding integrated lighting control strategies that specify certified contactors. Stakeholders must monitor semiconductor supply continuity for solid-state product lines and evaluate backward integration into contact material processing as a hedge against silver price volatility and regulatory metal-content restrictions.
Market Dynamics
NEMA and IEC standards are forcing coil redesigns and contact material substitutions across the lighting contactor supply base, compressing legacy product margins while opening premium positioning for certified platforms.
Growth Catalysts
- Smart City Deployments:Municipal street lighting automation in United States, China, and Germany is pulling demand for utility-grade contactors with remote monitoring capabilities.
- EU Ecodesign Directive:Standby loss limits are mandating high-efficiency coil assemblies, accelerating replacement cycles in European commercial buildings.
- Silver-Alloy Contact Technology:Advanced metallurgy extending contact life to million-cycle ratings is opening specification in high-frequency LED driver applications.
Market Restraints
- Silver Price Volatility:Contact material costs fluctuate with precious metal markets, squeezing margins on electromechanical product lines.
- Semiconductor Supply Concentration:Solid-state contactor production depends on concentrated silicon carbide and IGBT supply chains in East Asia.
- Legacy Fluorescent Decline:Ballast-compatible contactor demand is contracting as HID and fluorescent installations reach end-of-life without replacement.
Strategic Opportunities
- India Smart Cities Mission:Underpenetrated municipal infrastructure presents white space for IEC-compliant modular contactor platforms.
- EPA Energy Star Integration:Certification-driven procurement in US commercial buildings rewards contactors embedded in whole-building control strategies.
- Solid-State Convergence:Semiconductor-grade thermal management married with wireless control modules enables premium positioning in zero-arcing applications.
Industry Challenges
- UL 508 Certification Timelines:Endurance and temperature-rise testing protocols extend product launch cycles by 8-14 months for new electromechanical designs.
- Legacy Panel Integration:DIN rail and flush mount form factor incompatibilities complicate retrofit specifications in North American junction box footprints.
- RoHS Compliance Complexity:Restricted substance elimination in contact alloys requires metallurgical R&D coordination across multiple supplier tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lighting Contactor Market |
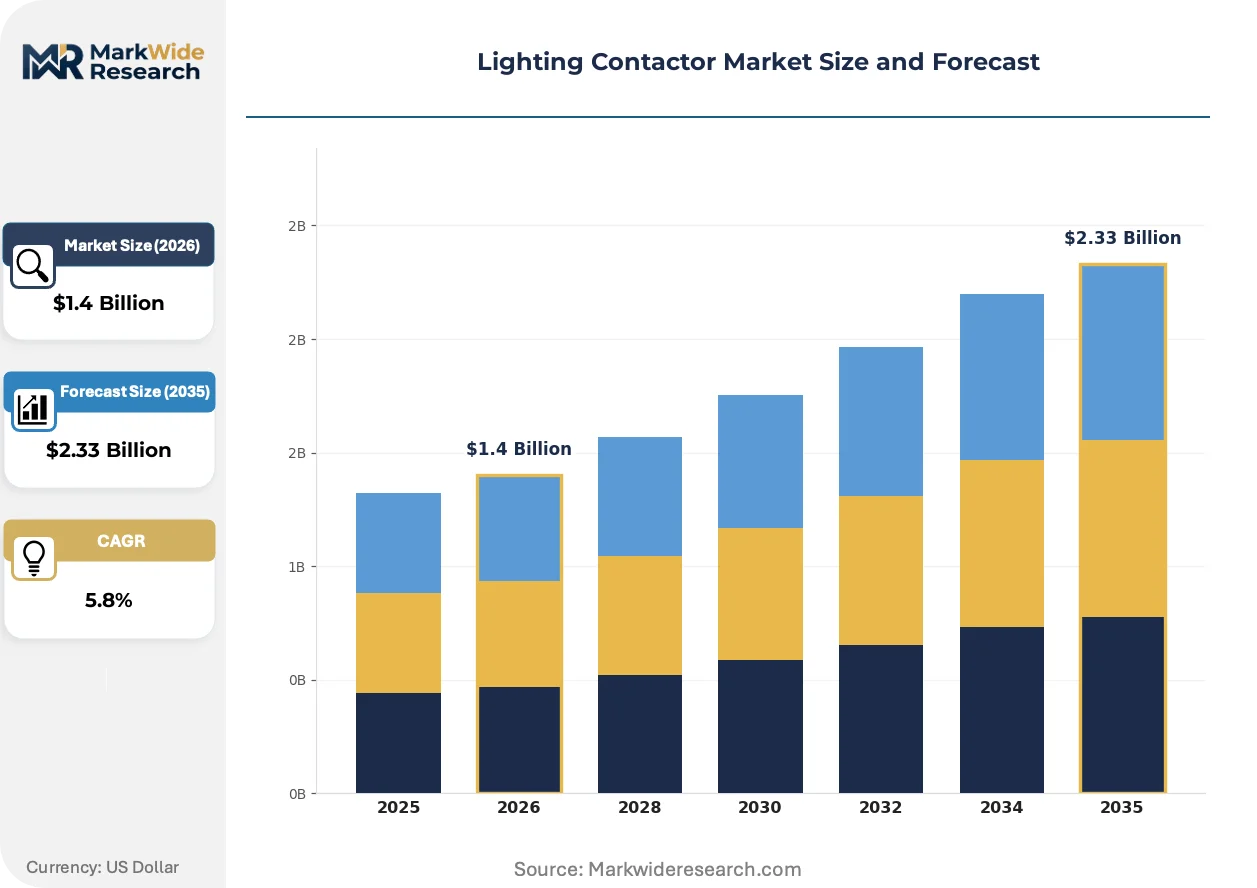
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical, Solid State, Hybrid, Modular Application: Commercial Buildings, Street Lighting, Industrial Facilities, Outdoor Signage Installation Type: Surface Mounted, Flush Mounted, DIN Rail Mounted, Panel Mounted End User: Electrical Contractors, Facility Managers, Property Developers, Maintenance Services |
| Companies Covered | ABB Ltd., Schneider Electric SE, Siemens AG, Eaton Corporation, Rockwell Automation, Inc., Legrand S.A., General Electric, Honeywell International Inc., Sprecher+Schuh, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lighting Contactor Market Strategic Shifts & Innovations
Solid-state switching architectures are compressing the traditional electromechanical dominance window, while regulatory efficiency mandates and procurement digitization reshape how buyers evaluate lifecycle performance.
Silicon carbide-based solid-state contactors handle inrush currents from LED drivers without contact arcing, enabling adoption in high-frequency switching environments such as sports arena lighting and broadcast studios. Facility managers in Germany and Japan are specifying these platforms for maintenance-cycle reduction. The technology is miniaturizing thermal management footprints, allowing panel density improvements that DIN rail configurations previously could not achieve.
EPA Energy Star program requirements for commercial building certification now indirectly specify lighting control components, pushing contactor selection into integrated system procurement rather than standalone electrical specification. Building automation contractors in the United States are bundling certified contactors with sensor networks to meet whole-building efficiency thresholds. This regulatory compression is favoring suppliers with captive testing laboratories and pre-certified platform families.
Lifecycle cost modeling is displacing first-cost procurement in municipal and commercial segments, with buyers calculating contact replacement labor against solid-state durability premiums. Electrical distributors in China and Germany are unbundling after-sales service contracts from hardware sales to capture recurring revenue streams. This behavioral shift is most visible in utility-scale street lighting networks where million-cycle ratings translate to measurable maintenance budget reductions.
Lighting Contactor Market Segmentation
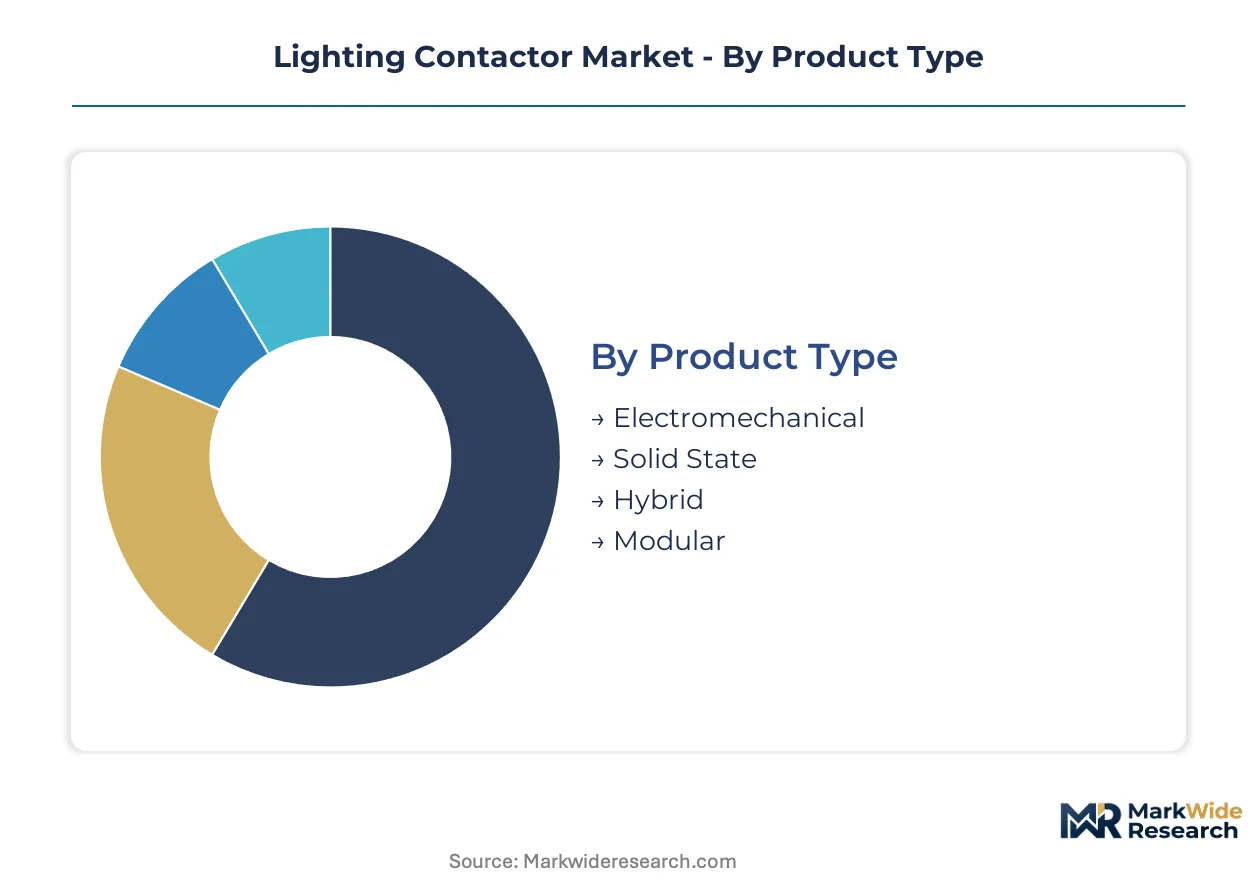
Segmentation in lighting contactors reveals how procurement channels, installation constraints, and end-user sophistication reshape product positioning. Each dimension carries distinct margin structures and certification requirements that determine competitive viability across municipal, commercial, and industrial deployment contexts.
Product Type:
Channel mix varies sharply: electromechanical units flow through electrical distributors serving retrofit contractors, while solid-state and hybrid platforms reach end-users via building automation integrators and OEM lighting manufacturers.
- Electromechanical:Silver-alloy contact assemblies rated for 20-1200 amperes dominate replacement demand in legacy fluorescent and HID installations. Municipal street lighting networks in the United States and Germany specify these for ballast-compatible retrofits where first-cost sensitivity overrides lifecycle optimization.
- Solid State:Silicon carbide switching architectures eliminate contact arcing entirely, enabling million-cycle durability in high-frequency LED driver applications. Broadcast studios and sports arena lighting in Japan specify these platforms for maintenance-cycle reduction and thermal footprint miniaturization.
- Hybrid:Combines electromechanical power handling with solid-state control logic for mid-tier commercial buildings seeking partial arc suppression without full semiconductor cost premiums.
- Modular:IEC-compliant platform architectures allow field-configurable pole counts and coil voltages, serving utility-scale street lighting networks requiring standardized spares inventory.
By volume, electromechanical leads. By growth pace, solid-state is climbing the fastest.
Application:
Cost tier stratification separates specification: premium solid-state contactors cluster in high-occupancy commercial and broadcast environments, while standard electromechanical units serve price-sensitive municipal street lighting.
- Commercial Buildings:EPA Energy Star certification requirements drive integrated control strategies specifying certified contactors with sensor network compatibility. Building automation contractors in the United States bundle these with whole-building efficiency packages.
- Street Lighting:Smart city deployments in China, Germany, and the United States pull demand for utility-grade contactors with remote monitoring capabilities and million-cycle ratings to reduce maintenance budget exposure.
- Industrial Facilities:Heavy inrush current tolerance and NEMA 4X enclosure ratings dominate specification for manufacturing plants with high-bay HID and LED high-mast installations.
- Outdoor Signage:Compact DIN rail configurations serve retail and hospitality sectors requiring discrete panel mounting for illuminated facade and pylon lighting systems.
Street lighting commands the largest absolute volume. Commercial buildings exhibit the steepest expansion trajectory as Energy Star procurement tightens.
Installation Type:
Volume concentration tracks regional electrical code inheritance: DIN rail dominates European new construction, flush mounted retains North American retrofit share, and surface mounted captures industrial expansion in underpenetrated markets.
- Surface Mounted:Exposed enclosure designs serve industrial temporary lighting and construction site applications where junction box infrastructure is absent or non-standard.
- Flush Mounted:North American retrofit channels constrained by existing junction box footprints specify these for commercial building upgrades without structural modification.
- DIN Rail Mounted:Standardized 35mm rail configurations maximize panel density and service accessibility in European commercial buildings and German industrial facilities.
- Panel Mounted:Custom cutout integration serves OEM lighting manufacturers and large-scale facility builds requiring factory-preconfigured control assemblies.
DIN rail mounted leads in new installation volume. Flush mounted retains largest installed base for replacement demand.
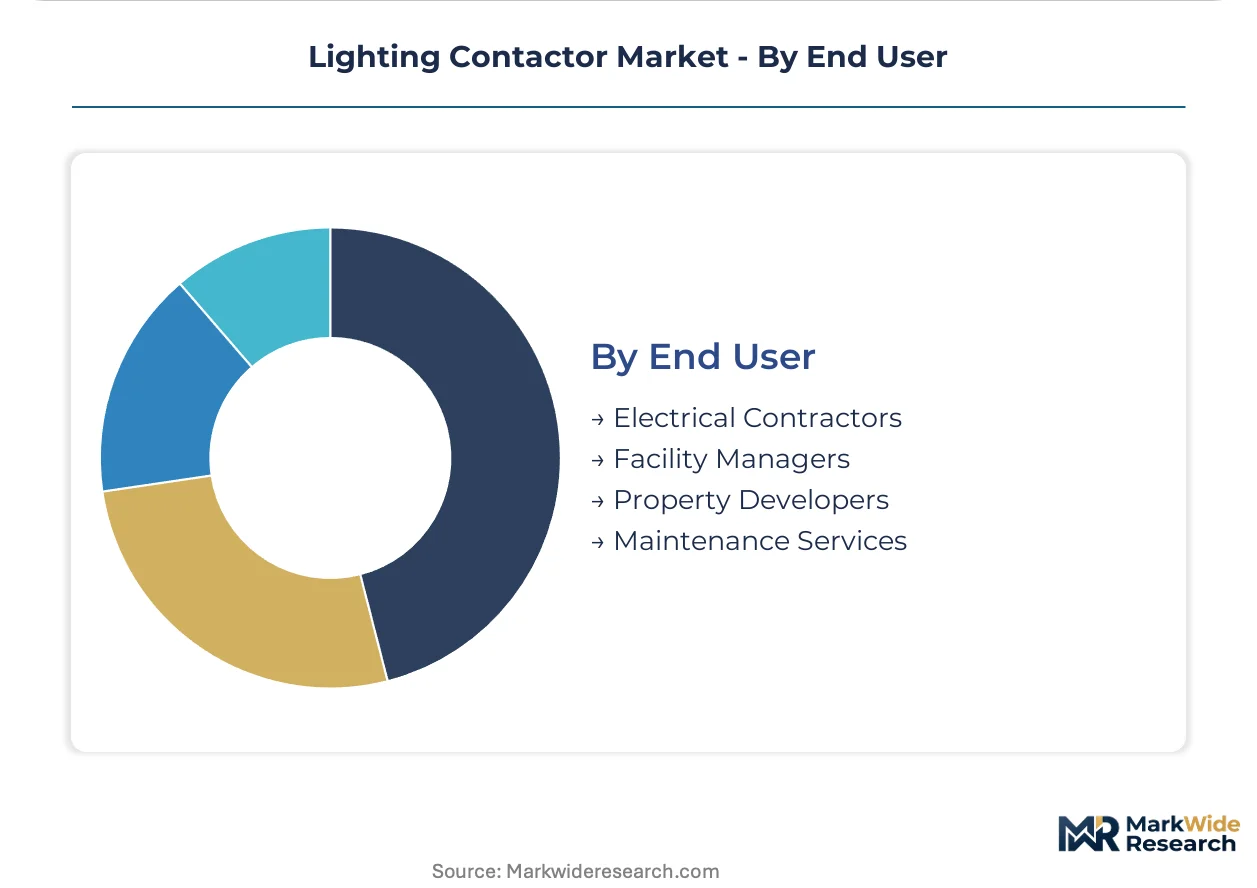
End User:
Customer type determines purchasing modality: electrical contractors buy on availability and first-cost, facility managers prioritize lifecycle cost modeling, and property developers seek pre-certified platforms for green building compliance.
- Electrical Contractors:Distributor stocking programs and same-day availability drive procurement for commercial retrofit and maintenance call-out scenarios.
- Facility Managers:Lifecycle cost calculations weighing contact replacement labor against solid-state durability premiums reshape specification toward million-cycle rated platforms.
- Property Developers:LEED and BREEAM pre-certification requirements favor suppliers with captive testing laboratories and pre-certified platform families for new construction.
- Maintenance Services:After-sales service contracts unbundled from hardware sales capture recurring revenue in utility-scale street lighting networks where downtime penalties apply.
Electrical contractors represent the largest transaction volume. Facility managers are gaining share fastest as procurement digitization enables lifecycle modeling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility managers and electrical contractors concentrate procurement in three distinct national markets where regulatory pressure and infrastructure renewal cycles overlap. Municipal buyers in the United States, China, and Germany currently absorb the majority of utility-grade contactor volume.
United States
Commercial building retrofits and smart city street lighting deployments drive specification. EPA Energy Star certification requirements push integrated control strategies that bundle certified contactors with sensor networks. Los Angeles and New York City municipal authorities specify million-cycle rated units for LED street lighting conversions to reduce maintenance budget exposure.
Germany
Industrial facility upgrades and DIN rail panel standardization anchor demand. EU Ecodesign Directive standby loss limits force coil assembly redesigns, accelerating replacement cycles in commercial buildings. The Ruhr industrial cluster and Bavarian manufacturing belt specify IEC-compliant modular platforms for standardized spares inventory.
China
Municipal infrastructure expansion and smart city pilot programs absorb volume. National standards tightening energy efficiency thresholds for public lighting equipment shape procurement criteria. Shenzhen and Shanghai urban lighting authorities deploy remote-monitoring-capable contactors in district-scale LED conversions.
India
Underpenetrated municipal infrastructure and Smart Cities Mission funding create specification white space. Central Electricity Authority guidelines for public lighting efficiency influence tender requirements. Delhi-Mumbai Industrial Corridor projects and Bangalore municipal upgrades drive initial modular platform adoption.
Lighting Contactor Market Key Industry Players
Player mix skews toward diversified industrial conglomerates with captive electromechanical component supply chains. Consolidation around integrated control equipment portfolios leaves limited room for pure-play specialists. Three archetypes dominate: European-headquartered modular platform providers, North American safety-certified industrial control houses, and diversified automation conglomerates with semiconductor-grade thermal management capabilities. Capacity expansion in Asian manufacturing nodes and backward integration into contact material processing represent the dominant competitive vectors.
Among European-headquartered providers, Schneider Electric SE and ABB Ltd. exemplify the diversified conglomerate archetype with broad industrial control portfolios. Siemens AG occupies a position on the semiconductor-grade thermal management vector. These three entities collectively represent how captive supply chain control and pre-certified platform families define viable positioning against tightening NEMA and IEC efficiency mandates.
| Leading Market Players |
|---|
| ABB Ltd. |
| Schneider Electric SE |
| Siemens AG |
| Eaton Corporation |
| Rockwell Automation, Inc. |
| Legrand S.A. |
| General Electric |
| Honeywell International Inc. |
| Sprecher+Schuh |
| Others |
Cost & Logistics Intelligence
Silver-to-copper contact alloy substitution is redrawing procurement geography from East Asian refineries toward European metallurgical processors while compressing electromechanical tier pricing premiums. This material transition simultaneously elevates solid-state contactor margins as buyers absorb semiconductor-grade thermal management costs.
Pricing Analysis
Cost-plus contracts indexed to London Bullion Market Association silver pricing dominate electromechanical procurement for municipal street lighting networks. Three-tier pricing structure across IEC-certified modular, UL-listed industrial, and economy-grade residential tiers separates specification. Cost compression in economy-grade fluorescent retrofit channels is intensifying because legacy ballast demand collapses without replacement. Municipal buyers in Germany exhibit lowest price sensitivity due to lifecycle cost modeling mandates, while Indian electrical contractors in Smart Cities tenders show highest sensitivity to first-cost positioning.
Supply Chain Analysis
Inbound logistics costs from Shanghai port congestion and trans-Pacific container availability constraints are elevating landed costs for silicon carbide substrate imports. Manufacturing concentrates in China for electromechanical coil assemblies, Germany for DIN rail enclosures, and Japan for solid-state switching modules. Silver-alloy contact processing draws from Mexican mining concentrates and German refining capacity. Single-source vulnerability sits with concentrated silicon carbide wafer supply from East Asian foundries. Distribution runs through electrical distributors serving retrofit contractors, building automation integrators for solid-state platforms, and OEM lighting manufacturers for panel-mounted configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from million-cycle maintenance contracts and remote monitoring subscriptions is expanding faster than hardware unit sales in utility-scale street lighting networks. This recurring-revenue layer justifies platform consolidation investments ahead of pure product-market-share plays.
For Market Incumbents: Fortify captive contact material processing through backward integration into silver-alloy refining or copper-substitute metallurgy R&D. Solid-state switching architectures from semiconductor-grade thermal management specialists threaten electromechanical margin pools in broadcast and sports arena verticals. Certification investment in pre-certified UL 508 and IEC 60947 platform families locks out challenger brands from EPA Energy Star-integrated procurement channels. For New Entrants and Emerging Players: Differentiate on wireless control module integration for smart city street lighting deployments where incumbent electromechanical portfolios lack embedded connectivity. India's Smart Cities Mission presents the most penetrable geography given underpenetrated municipal infrastructure and IEC standard adoption gaps. Target building automation integrators rather than electrical distributors to bypass incumbent channel control and capture premium positioning through system-level specification. For Investors and Strategic Acquirers: EU Ecodesign Directive standby loss enforcement reshapes the acquisition landscape toward high-efficiency coil assembly capabilities and RoHS-compliant contact metallurgy expertise. Long-term viability centers on suppliers with captive testing laboratories and modular platform architectures spanning electromechanical-to-solid-state transition. Watch for UL 508 certification timeline compression as signal of regulatory barrier elevation that favors scaled incumbents over specialist challengers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contact Metallurgy | Captive silver-alloy processing hedges LBMA price volatility and RoHS compliance complexity. |
| Solid-State Thermal Management R&D Partnership | Silicon carbide switching expertise captures broadcast studio and sports arena specification migration. |
| Pre-Certified Platform Family Expansion | UL 508 and IEC 60947 pre-certification accelerates EPA Energy Star procurement channel access. |
| Wireless Control Module Acquisition | Embedded connectivity capabilities differentiate municipal smart city tenders from electromechanical incumbents. |
| India Manufacturing Footprint Establishment | Local assembly addresses Smart Cities Mission tender requirements and reduces trans-Pacific logistics exposure. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with electrical contractors, facility managers, building automation integrators, and municipal procurement officers; and secondary validation through UL certification databases, IEC standard documentation, EPA Energy Star qualified products lists, and customs trade records for silver-alloy contact material flows. Bottom-up unit shipment estimates from distributor channel checks triangulated against top-down market sizing from regulatory mandate implementation timelines.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning product type (electromechanical, solid-state, hybrid, modular), installation configuration (DIN rail, flush mounted, surface mounted, panel mounted), application vertical (commercial buildings, street lighting, industrial facilities, outdoor signage), and end-user archetype (electrical contractors, facility managers, property developers, maintenance services). CAGRs derived from regression against historical replacement cycle data and regulatory-driven acceleration factors including EU Ecodesign Directive compliance deadlines and smart city deployment schedules.
Material uncertainties — silver price volatility, semiconductor supply continuity disruptions, and municipal budget cycle delays — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and infrastructure funding continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Transient Protection Device Market
Electrical Equipment
France DC Motors Market
Electrical Equipment
Insulator Market
Electrical Equipment
Global EMC Filtration Market
Electrical Equipment
Air Circuit Breaker Market
Electrical Equipment
Electrical Fuses Market
Electrical Equipment
Vacuum Interrupter Market
Electrical Equipment
Medium Voltage Circuit Breakers Market
Electrical Equipment
High Voltage PTC Heater Market
Electrical Equipment
Global Sealed DC Contactor Market
Electrical Equipment
North America Low Voltage Induction Motors Market
Electrical Equipment
Electrical Steel Coatings Market
Electrical Equipment
Busbar Trunking System Market
Electrical Equipment
High-Vacuum Fiber Feedthrough Flanges Market
Electrical Equipment
Copper and Aluminum Terminal Blocks Market
Electrical Equipment
Europe Circuit Breakers Market