
 Busbar Trunking System Market | 2026-2036
Busbar Trunking System Market Size, Share, and Industry Trends Forecast 2026-2036
Busbar Trunking System Market Analysis
The EU Green Deal's building renovation mandates is realigning power distribution specifications across European commercial real estate. Eaton leverages its integrated manufacturing footprint to supply certified low-loss trunking assemblies. Siemens anchors its position through intensive R&D in fire-resistant insulation systems. Schneider Electric competes on channel density, controlling specification relationships with large electrical contractors.
A busbar trunking system comprises enclosed conductor bars—typically copper or aluminum—housed within protective steel or aluminum casings with insulated supports, designed to distribute electrical power at low voltage across buildings and industrial plants. Multi-core configurations dominate commercial installations where space constraints and branching flexibility matter most, while aluminum material segments are gaining share as procurement shifts toward lighter, cost-optimized assemblies for vertical high-rise routing. Surface mounted installation retains the largest volume base in retrofit applications, though integrated designs are capturing new construction specifications where architects prioritize concealed mechanical zones.
CE marking under the EU's Low Voltage Directive and IEC 61439-6 standards govern product compliance and market access across European jurisdictions, while China's GB standards and MIIT energy efficiency certifications shape domestic manufacturing requirements. India's BIS certification mandates and CEA grid connectivity rules are tightening product testing protocols for trunking used in power plant auxiliary distribution. Stakeholders must track evolving fire safety classifications and material traceability requirements as regulatory divergence between jurisdictions intensifies compliance complexity.
Market Dynamics
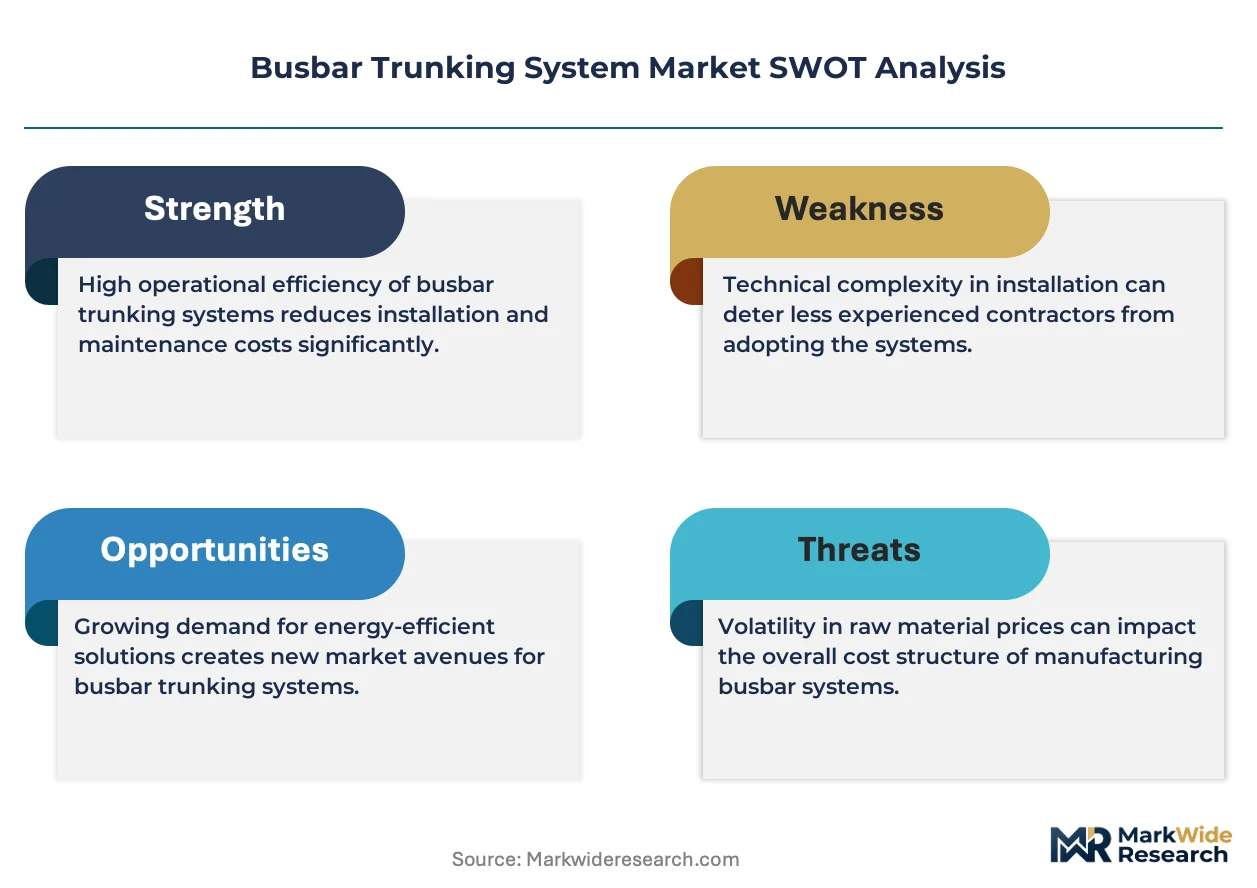
Material substitution from copper to aluminum is compressing procurement costs while forcing manufacturers to reengineer jointing systems and thermal management architectures across high-rise and industrial installations.
Growth Catalysts
- EU Green Deal building renovation mandates:Commercial real estate retrofits across Germany, France, and Italy are accelerating replacement cycles for legacy power distribution infrastructure in aging office stock.
- Data center electrical infrastructure expansion:Hyperscale facility operators in Northern Virginia, Frankfurt, and Singapore are specifying high-density busbar trunking for 400V+ rack-level power distribution.
- MIIT energy efficiency certifications:China's domestic manufacturing requirements are tightening product efficiency thresholds, filtering low-performance imports and consolidating local supply chains.
Market Restraints
- Copper price volatility:LME copper futures swings above 15% annually are destabilizing input cost planning for OEMs committed to premium conductor specifications.
- Fire-resistant insulation R&D intensity:Silicone and ceramic-based barrier materials require multi-year development cycles, locking smaller manufacturers out of certified product tiers.
- Low-voltage switchgear substitution:Modular breaker-based distribution systems are capturing retrofit specifications in sub-800A applications where flexibility outweighs density.
Strategic Opportunities
- Southeast Asian manufacturing corridors:Industrial facility construction in Vietnam's northern provinces and Indonesia's Batang region is creating demand for weather-resistant outdoor-rated trunking systems.
- Integrated building management convergence:Busbar trunking with embedded temperature and current monitoring is converging with IoT platforms to enable predictive maintenance contracts.
- India PLI scheme for electrical equipment:Domestic production incentives are attracting component localization investments that reduce landed cost for power plant auxiliary distribution.
Industry Challenges
- Fire safety classification harmonization:Divergent testing protocols between IEC 61439-6 and national variants in the UK, UAE, and Australia are fragmenting certification requirements for multinational projects.
- Skilled installation labor scarcity:Certified busbar jointing technicians are concentrated in mature markets, constraining deployment velocity in emerging construction hotspots.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Busbar Trunking System Market |
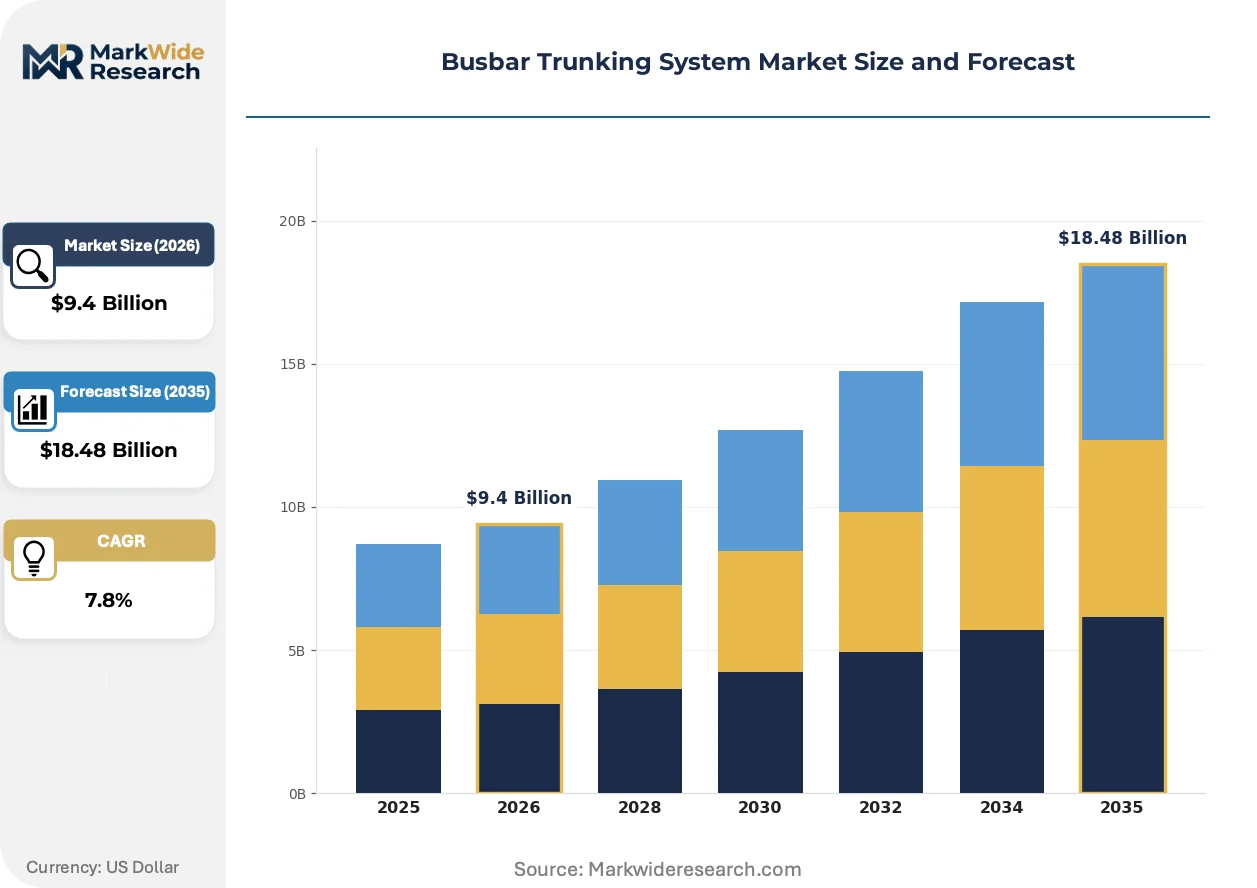
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $18.48 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Core, Multi-Core, Bended, Accessories End User: Commercial Buildings, Industrial Facilities, Power Plants, Data Centers Installation Type: Surface Mounted, Concealed, Integrated, Ceiling Mounted Material: Copper, Aluminum, Steel, Insulated |
| Companies Covered | Eaton, Godrej, ABB, EAE Elektrik, C&S Electric, Siemens, Legrand, LS Cable, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Busbar Trunking System Market Emerging Trajectories
Electrification intensity in vertical buildings and cleanroom manufacturing is forcing power distribution architectures toward higher ampacity density and embedded intelligence. Three developments are redefining competitive positioning.
Aluminum alloy conductor technology is converging with advanced plating processes to achieve copper-comparable conductivity at 40% lower mass. High-rise developers in Dubai and Mumbai are specifying these assemblies for vertical riser applications where structural load limits constrain traditional copper designs. The technology is converging with computational fluid dynamics modeling to optimize natural convection cooling without forced ventilation.
REACH substance restrictions on halogenated flame retardants are compelling insulation compound reformulation across European supply chains. Manufacturers serving German automotive and French nuclear sectors are accelerating mineral-filled polymer adoption to maintain CE marking compliance. The regulation is compressing product development timelines while elevating R&D budgets for compliant material qualification.
Electrical contractor specification control is consolidating around bundled procurement agreements with integrated MEP contractors. Large infrastructure projects in Saudi Arabia's NEOM and Qatar's Lusail are bypassing traditional distributor networks for direct manufacturer relationships. This channel compression is forcing OEMs to build project-dedicated technical sales teams and localized fabrication capabilities.
Busbar Trunking System Market Segmentation
Busbar trunking procurement decisions hinge on installation environment constraints, ampacity requirements, and material cost structures. Specification engineers weight thermal performance against structural load limits differently across vertical buildings, cleanroom manufacturing, and hyperscale data halls.
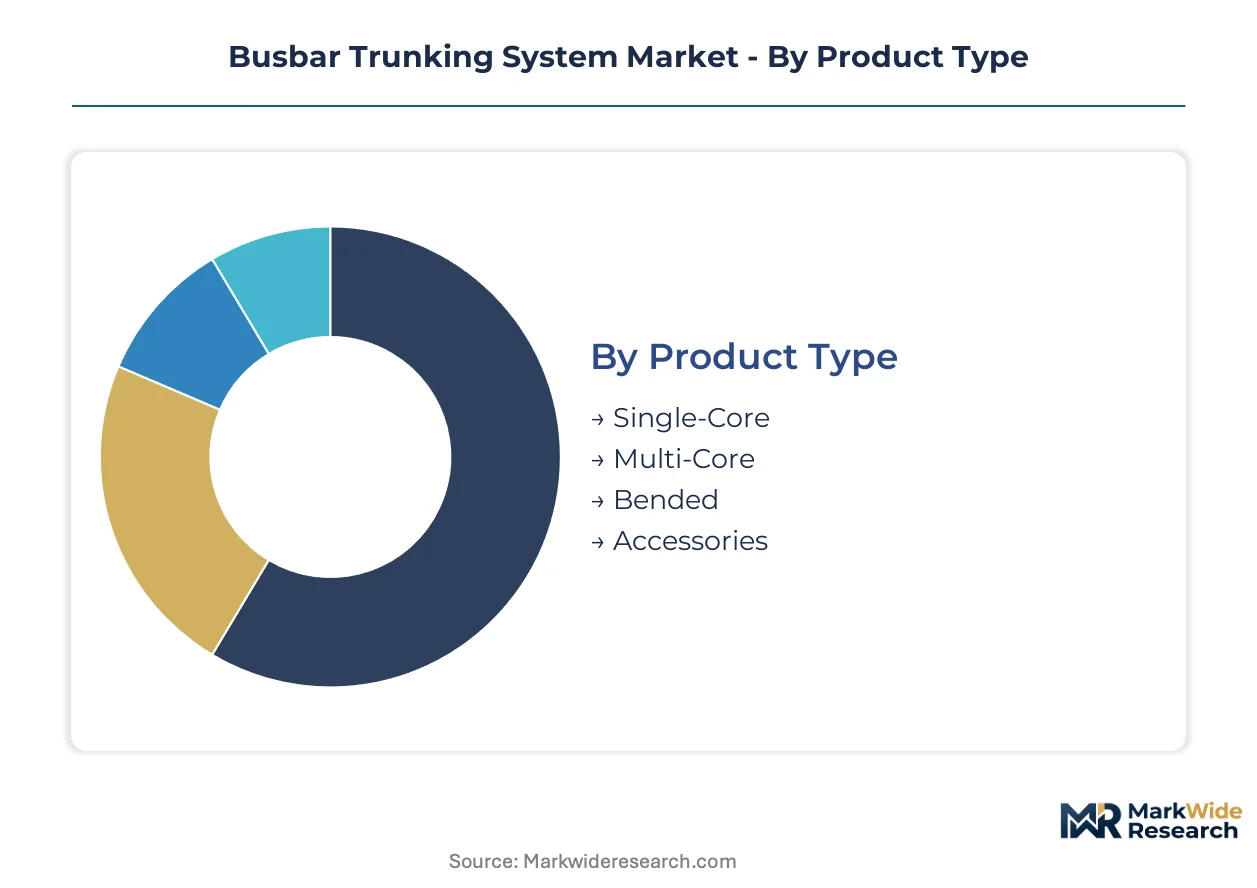
Product Type:
Standalone feeder trunking dominates open industrial floors where branching flexibility matters less than raw ampacity, while embedded multi-core configurations integrate into ceiling plenums and raised-floor data center environments where space economics favor consolidated conductor packaging.
- Single-Core:High-ampacity individual conductor bars engineered for heavy industrial feeder circuits requiring 1000A+ continuous rating. Demand concentrates in German automotive stamping plants and South Korean battery gigafactories where single large loads dwarf distributed branch circuits.
- Multi-Core:Three or four-phase conductor assemblies with integrated neutral and ground within a common enclosure, optimized for commercial building distribution where multiple tap-off points serve tenant panels. UAE high-rise developers in Dubai Marina and Business Bay specify these for vertical riser applications where structural engineers impose strict weight-per-floor limits.
- Bended:Pre-fabricated directional assemblies with factory-formed elbows and tees reducing field jointing labor. Indian metro rail projects in Mumbai and Delhi specify these for tunnel curvature compliance.
- Accessories:Tap-off boxes, end caps, and jointing hardware completing installation integrity. Brazil's industrial corridor purchases spike during facility commissioning windows.
Multi-core leads volumes today; bended configurations are gaining share fastest in infrastructure megaprojects.
End User:
Cost tier stratification separates mission-critical uptime specifications from price-sensitive commodity procurement, with data center operators paying premiums for monitored intelligent trunking while industrial buyers prioritize first-cost minimization.
- Commercial Buildings:Office towers, retail complexes, and hospitality properties specifying 200-800A distribution for tenant sub-panels. Singapore's Marina Bay financial district retrofits are replacing legacy cable bus with aluminum trunking to meet BCA Green Mark energy efficiency thresholds.
- Industrial Facilities:Manufacturing plants and process industries demanding ruggedized enclosures against chemical exposure and mechanical impact. Vietnam's northern provinces—Bac Ninh and Hai Phong—are absorbing weather-resistant outdoor-rated systems for electronics assembly campuses.
- Power Plants:Auxiliary distribution in generation facilities requiring fire-resistant insulation and seismic qualification. India's CEA grid connectivity rules are tightening BIS certification protocols for these installations.
- Data Centers:Hyperscale and colocation facilities specifying 400V+ rack-level power distribution with embedded temperature monitoring. Northern Virginia's Ashburn-Dulles corridor and Frankfurt's FLAP market are driving specification intensity for high-density busbar trunking.
Industrial facilities lead volumes today; data centers are expanding most quickly as AI training clusters multiply rack power densities.
Installation Type:
Application context determines mounting architecture selection, with retrofit constraints preserving surface-mounted dominance while new construction specifications favor concealed integration matching architectural mechanical zone planning.
- Surface Mounted:Exposed wall or ceiling attachment enabling rapid retrofit deployment without structural penetration. Aging European office stock in Milan and Madrid relies on these for EU Green Deal renovation mandates.
- Concealed:Recessed installation within wall cavities and ceiling soffits preserving interior aesthetic continuity. Saudi Arabia's NEOM linear city specifications are requiring these for hospitality and residential districts.
- Integrated:Factory-coordinated with raised-floor or ceiling-plenum systems in cleanroom and data hall environments. Singapore's Tuas data center campus deploys these for hot-aisle containment integration.
- Ceiling Mounted:Suspended distribution for open industrial bays and warehouse facilities. Indonesia's Batang integrated industrial estate specifies these for fabrication halls with overhead crane clearance requirements.
Surface mounted leads volumes today; integrated designs are climbing the fastest in new construction specifications.
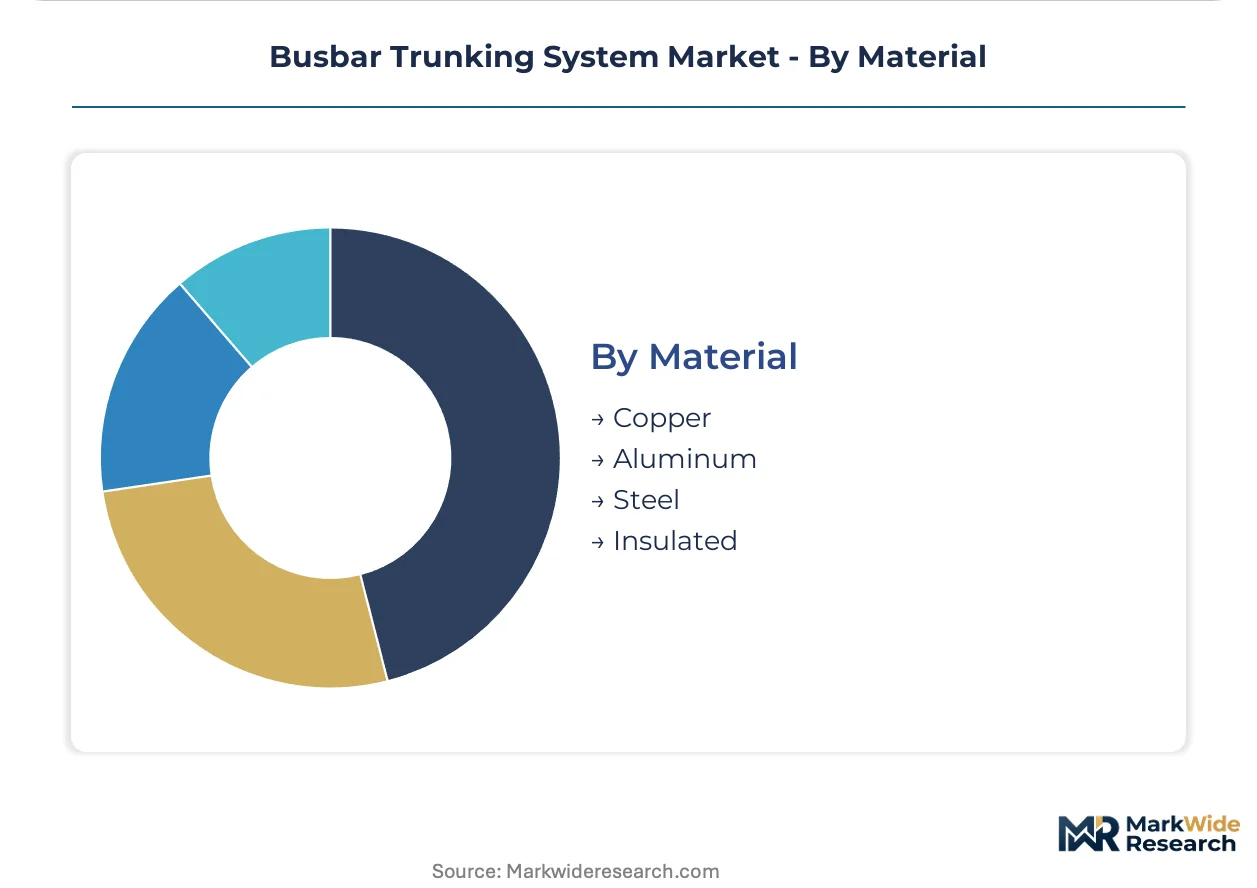
Material:
Supply concentration and price volatility exposure differentiate procurement strategies, with copper-dependent OEMs hedging LME futures while aluminum-adopting manufacturers capture structural weight-constrained vertical building specifications.
- Copper:Electrolytic-grade conductors delivering maximum conductivity for high-density applications where every ampere of thermal headroom matters. Frankfurt hyperscale facilities continue specifying these for 400V rack distribution despite price volatility.
- Aluminum:Lightweight alloy conductors with tin or silver plating achieving conductivity-to-weight ratios enabling high-rise vertical risers. China's dual carbon goals and GB standard efficiency mandates are accelerating domestic manufacturing transitions.
- Steel:Protective enclosure casings providing mechanical protection and electromagnetic shielding. German automotive plants specify galvanized steel housings for weld-shop electromagnetic compatibility.
- Insulated:Mineral-filled polymer and ceramic-barrier compounds achieving fire-resistant ratings without halogenated flame retardants. REACH restrictions are forcing compound reformulation across European supply chains.
Copper leads volumes today; aluminum is gaining share fastest as procurement shifts toward lighter, cost-optimized assemblies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified busbar jointing technicians concentrate in mature industrial markets, constraining deployment velocity in emerging construction corridors where demand is accelerating fastest.
China
MIIT energy efficiency certifications and dual carbon goals are filtering low-performance imports while consolidating domestic aluminum trunking supply chains. GB standards now mandate stricter efficiency thresholds for building electrical distribution. Manufacturing corridors in Guangdong and Jiangsu provinces are absorbing weather-resistant outdoor-rated systems for electronics assembly campuses.
Germany
EU Green Deal building renovation mandates are accelerating replacement cycles for legacy power distribution infrastructure in aging office stock across Berlin and Frankfurt. REACH substance restrictions on halogenated flame retardants are compelling insulation compound reformulation across domestic supply chains. Automotive stamping plants in Bavaria and Baden-Württemberg specify single-core high-ampacity trunking for heavy industrial feeder circuits.
United States
Hyperscale data center operators in Northern Virginia's Ashburn-Dulles corridor are specifying high-density busbar trunking for 400V+ rack-level power distribution. FERC grid interconnection rules shape auxiliary distribution requirements for power plant installations. Industrial construction in Texas and Arizona is driving demand for surface-mounted retrofit systems in expanding manufacturing zones.
India
BIS certification mandates and CEA grid connectivity rules are tightening product testing protocols for trunking used in power plant auxiliary distribution. PLI scheme incentives for electrical equipment are attracting component localization investments. Metro rail projects in Mumbai and Delhi specify pre-fabricated bended configurations for tunnel curvature compliance.
United Arab Emirates
High-rise developers in Dubai Marina and Business Bay specify multi-core aluminum assemblies for vertical riser applications where structural engineers impose strict weight-per-floor limits. MOHAP building safety regulations align with international fire-resistant insulation standards. NEOM linear city specifications in Saudi Arabia are requiring concealed installation designs for hospitality and residential districts.
Busbar Trunking System Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the busbar trunking landscape, with integrated manufacturers controlling specification relationships through bundled procurement agreements. The vendor base separates into three strategic archetypes: diversified electrical conglomerates with integrated manufacturing footprints, specialized trunking fabricators focused on regional project execution, and component suppliers feeding into third-party assembly networks. M&A activity concentrates on acquiring certified fabrication capabilities in high-growth corridors, while capacity expansion targets localized production to bypass distributor networks in megaproject markets.
Within the diversified conglomerate tier, Eaton, Siemens, and Schneider Electric exemplify integrated manufacturing strategies that span protective enclosures through intelligent monitoring systems. Schneider Electric occupies a position emphasizing channel density and specification control with large electrical contractors, while Siemens exemplifies intensive R&D positioning in fire-resistant insulation systems. Eaton anchors a manufacturing footprint optimized for certified low-loss trunking assemblies serving European commercial real estate retrofits. These three entities represent the premium-tier vector where bundled procurement agreements and direct manufacturer relationships are displacing traditional distributor networks in Saudi Arabia's NEOM and Qatar's Lusail infrastructure developments.
| Leading Market Players |
|---|
| Eaton |
| Godrej |
| ABB |
| EAE Elektrik |
| C&S Electric |
| Siemens |
| Legrand |
| LS Cable |
| Schneider Electric |
| Others |
Supply Flow & Price Mechanics
LME copper futures volatility cascades through busbar trunking supply chains into three distinct procurement tiers, compressing margins for copper-dependent OEMs while aluminum-adopting manufacturers capture structural weight-constrained specifications in Dubai and Mumbai high-rises.
Pricing Analysis
Bundled engineering-procurement-installation contracts versus unbundled component sales define the dominant pricing split. Three-tier pricing structure across intelligent-monitored, fire-rated certified, and standard commercial grades separates data center operators paying premiums for embedded sensors from industrial buyers prioritizing first-cost minimization. Cost compression in aluminum alloy segments is intensifying because Chinese GB standard efficiency mandates are filtering low-performance imports. Power plant auxiliary distributors under CEA grid connectivity rules exhibit the highest price sensitivity, while hyperscale data center operators in Northern Virginia show the least.
Supply Chain Analysis
Certified busbar jointing technician scarcity in Vietnam's northern provinces and Indonesia's Batang region constrains fabrication capacity expansion despite accelerating demand. Manufacturing gravity centers on China, Germany, and India, with raw material supply drawing from Chilean copper concentrate, Australian bauxite for aluminum alloys, and Korean silicone compounds for insulation. Single-source vulnerability in halogen-free mineral-filled polymer feedstock from German chemical suppliers elevates reformulation risk under REACH restrictions. Distribution runs through integrated MEP contractors in Saudi Arabia's NEOM and Qatar's Lusail, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Busbar trunking procurement is shifting toward intelligent-monitored specifications as AI training clusters multiply rack power densities, favoring manufacturers with certified fabrication capabilities and embedded sensor integration.
For Market Incumbents: Extend fire-resistant insulation R&D investments to maintain CE marking compliance as REACH substance restrictions compress product development timelines. Backward integration into aluminum alloy casting secures supply chain control against LME copper volatility. Channel control through direct manufacturer relationships with large electrical contractors defends specification position against modular breaker-based distribution substitutes in sub-800A retrofit applications. For New Entrants and Emerging Players: Direct-to-contractor digital platforms offer the lowest-friction entry path into fragmented Southeast Asian manufacturing corridors. Weather-resistant outdoor-rated trunking for Vietnam's Bac Ninh electronics campuses and Indonesia's Batang integrated industrial estate represents the most penetrable white space. Specification support services bundled with localized fabrication capabilities anchor the essential go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized trunking fabricators holding certified jointing technician networks in high-growth corridors where demand outpaces skilled labor supply. Long-term viability rests on aluminum alloy conductor technology convergence with computational fluid dynamics thermal modeling. Watch MIIT energy efficiency certification thresholds as the inflection signal for domestic Chinese supply chain consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum Alloy Conductor Scale-Up | Guangdong and Jiangsu manufacturing corridors absorb plating-process capacity for dual carbon compliance. |
| Fire-Resistant Insulation Reformulation | Mineral-filled polymer adoption maintains CE marking as REACH restrictions eliminate halogenated alternatives. |
| Embedded Sensor Integration | Temperature and current monitoring convergence with IoT platforms enables predictive maintenance contracts in Frankfurt hyperscale facilities. |
| Certified Jointing Technician Training | Vietnam and Indonesia deployment velocity constraints ease as localized fabrication capabilities expand. |
| Direct MEP Contractor Relationships | NEOM and Lusail megaprojects bypass distributor networks for bundled procurement agreements. |
Methodological Framework
Bottom-up data center and industrial facility modeling reconciled against top-down copper and aluminum supply tracking forms the analytical core of this study. Primary interviews with electrical contractors, MEP procurement managers, OEM specification engineers, and plant maintenance directors combined with secondary validation from IEC 61439-6 certification databases, MIIT energy efficiency filings, BIS product registrations, and customs trade data. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map conductor material flows through enclosure fabrication, insulation compounding, and final assembly stages across the projection horizon. Segmentation dimensions include product type, end-use sector, installation architecture, and material composition, with CAGRs derived from regression analysis against macro construction indicators and data center capex cycles. Forecast inputs incorporate GB standard efficiency thresholds and EU Green Deal renovation mandates.
The model assumes a particular technology adoption path for aluminum alloy conductor plating; alternative pathways achieving copper-comparable conductivity through graphene composite or carbon nanotube integration would alter the outlook. Forecasts reflect assumptions about skilled technician training pipeline expansion and REACH substance restriction timelines. Material deviation in MIIT certification stringency or LME copper volatility spikes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Insulator Market
Electrical Equipment
Lighting Contactor Market
Electrical Equipment
High Voltage Commercial Switchgear Market
Electrical Equipment
Magnetic Contactors Market
Electrical Equipment
North America Circuit Breakers Market
Electrical Equipment
Ground Fault Circuit Interrupter Market
Electrical Equipment
Global Digital Panel Meter Market
Electrical Equipment
HID Ballast Market
Electrical Equipment
France DC Motors Market
Electrical Equipment
Switchgear Monitoring System Market
Electrical Equipment
Electrical Enclosures Market
Electrical Equipment
Voltage Transformer Market
Electrical Equipment
Electronically Commutated (EC) Fan Market
Electrical Equipment
Hermetic Reciprocating Refrigerator Compressor Market
Electrical Equipment
Global Dehydrating Breather Market
Electrical Equipment
Pad-Mounted Transformer Market