

High-Vacuum Fiber Feedthrough Flanges Market Size, Share, and Industry Trends Forecast 2026-2036
High-Vacuum Fiber Feedthrough Flanges Market Insights
Equipment leasing and project finance for vacuum infrastructure is fragmenting the competitive landscape for high-vacuum fiber feedthrough flanges. Thorlabs leverages its broad photonics portfolio to sustain R&D intensity across multiple seal technologies. VACOM anchors its position through geographic dominance in European vacuum component supply chains. Diamond SA differentiates via specialized glass-to-metal hermetic sealing expertise for extreme UHV environments.
High-vacuum fiber feedthrough flanges are hermetic interface devices that route optical signals across pressure boundaries, typically achieving leak rates below 10⁻¹¹ mbar·l/s through brazed or indium-sealed metal-ceramic assemblies. These components enable real-time spectroscopy, plasma diagnostics, and process monitoring inside semiconductor etch chambers, deposition systems, and scientific instruments. Metallic flanges currently occupy the largest volume share due to compatibility with standard CF/KF vacuum fittings, while sealed feedthroughs represent the fastest-expanding technology category as lithography toolmakers demand pre-tested, warranty-backed subassemblies. Custom flanges command the deepest margin pools because each particle accelerator beamline and aerospace vacuum chamber requires application-specific fiber counts, wavelengths, and thermal budgets.
FDA oversight of medical device sterilization chambers and EPA emissions monitoring requirements shape hermetic sealing specifications in the United States, while REACH restrictions on lead-based solders and RoHS substance limits redirect European manufacturers toward indium and gold-tin braze alloys. Japan's METI industrial standards and JIS certification protocols govern vacuum component reliability for domestic semiconductor equipment exports. Stakeholders must monitor how evolving vacuum integrity standards for EUV lithography tools reshape material qualification timelines and supplier certification burdens.
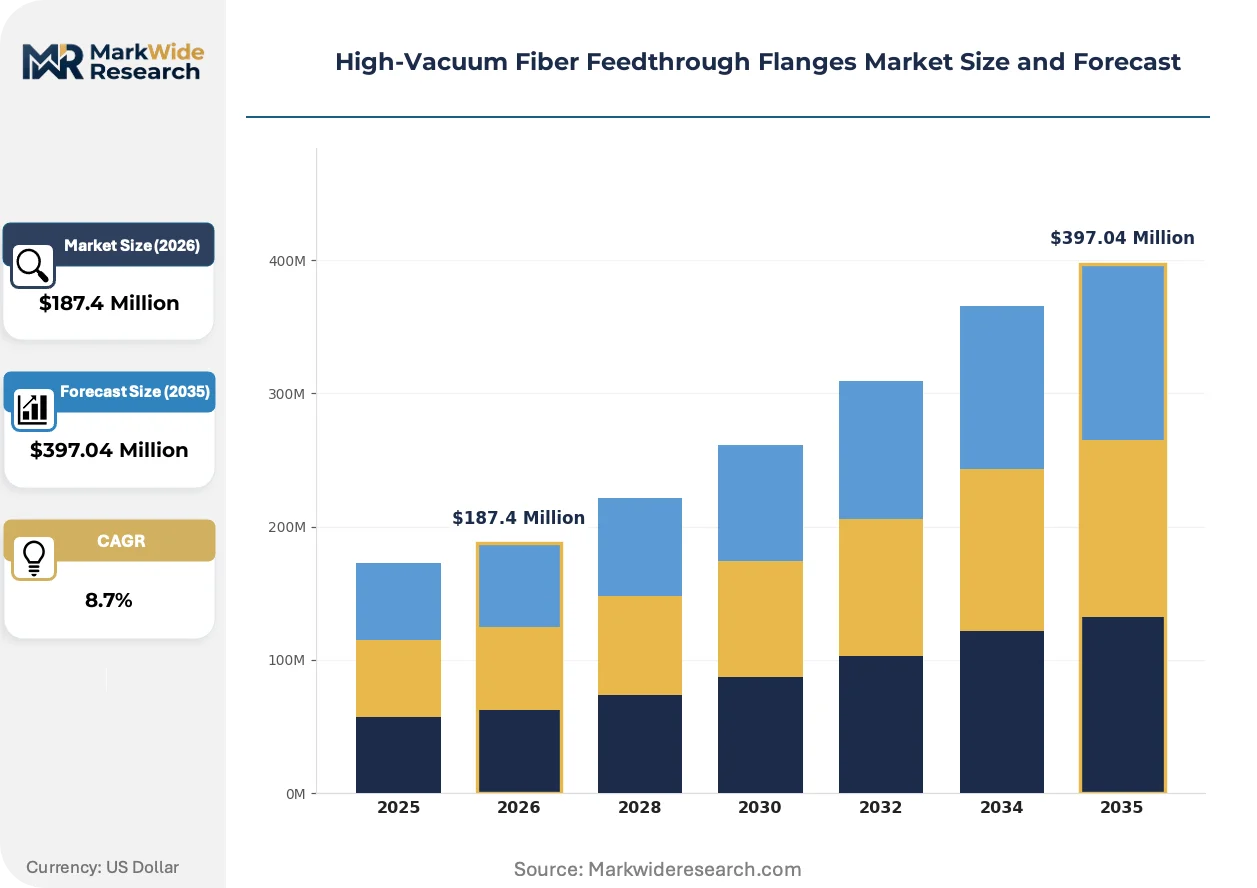
Market Dynamics
Semiconductor lithography toolmakers are consolidating vacuum component suppliers into pre-qualified vendor lists, compressing qualification timelines and forcing feedthrough manufacturers to absorb certification costs upfront.
Growth Catalysts
- EUV Lithography Ramp:Next-generation chip fabrication requires real-time optical monitoring inside vacuum chambers, pulling fiber feedthrough volumes into deposition and etch tool supply chains.
- REACH Substance Restrictions:European bans on lead-based solders are accelerating indium and gold-tin braze alloy adoption, creating technology upgrade cycles across installed base retrofits.
- Particle Accelerator Construction:Germany, Japan, and the United States are commissioning new synchrotron and free-electron laser facilities requiring custom multi-fiber feedthrough arrays.
Market Restraints
- Precious Metal Input Volatility:Gold and indium price swings compress margin predictability for brazed seal manufacturers locked into fixed-price OEM contracts.
- Supplier Concentration in German Vacuum Clusters:CF and KF flange machining capacity concentrates in Baden-Württemberg and Bavaria, creating geographic chokepoints during demand surges.
- Hermetic Ceramic Substitution Limits:Polymer-based vacuum seals remain incompatible with UHV bakeout temperatures above 200°C, constraining cost-down pathways.
Strategic Opportunities
- Medical Sterilization Chambers:FDA oversight of hospital autoclave validation is creating demand for fiber-coupled spectroscopic sterility assurance in United States device manufacturing.
- Quantum Computing Cryostats:Dilution refrigerator manufacturers require optical access for qubit control, opening a nascent application segment with distinct thermal cycling specifications.
- EU Green Deal Funding:European accelerator and fusion research programs are channeling public capital into vacuum infrastructure, subsidizing feedthrough procurement for domestic suppliers.
Industry Challenges
- Vacuum Brazing Skill Scarcity:Specialized technicians capable of indium and ceramic-metal sealing are retiring faster than apprenticeship programs replenish the workforce.
- EUV Tool Certification Timelines:ASML and Nikon qualification protocols demand 18-24 month validation cycles, freezing design changes and delaying revenue recognition.
- Legacy Chamber Retrofit Integration:Installing fiber feedthroughs into existing semiconductor tools requires custom flange adapters, multiplying engineering hours per order.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Vacuum Fiber Feedthrough Flanges Market Trends and Innovations
Digital twin technology is compressing the design-test-qualify cycle for vacuum components, while regulatory substance bans and buyer consolidation are reshaping supplier relationships.
Glass-to-metal hermetic sealing is virtualizing the traditional metal-flange dominant design. This technology achieves leak rates below 10⁻¹¹ mbar·l/s through matched thermal expansion coefficients. Lithography OEMs in Japan and the Netherlands are specifying pre-brazed sealed feedthrough subassemblies to reduce field installation risk. The technology is virtualizing component-level procurement into subsystem sourcing, elevating warranty and traceability requirements.
REACH Annex XVII restrictions on lead and cadmium are forcing alloy reformulation across European supply chains. Manufacturers are qualifying indium-silver and gold-tin eutectic compositions to maintain hermeticity without restricted substances. German vacuum component suppliers face the steepest recertification burden, as their installed base dominance requires simultaneous legacy support and new alloy production.
Consolidated procurement through semiconductor OEM approved vendor lists is displacing spot purchasing. Toolmakers like ASML and Applied Materials are mandating single-source accountability for vacuum subsystem performance. This concentrates volume with feedthrough manufacturers possessing in-house brazing, fiber termination, and vacuum testing capabilities. The shift is most visible in Dutch and German lithography supply chains, where tier-two component vendors are exiting or seeking acquisition.
High-Vacuum Fiber Feedthrough Flanges Market Segmentation
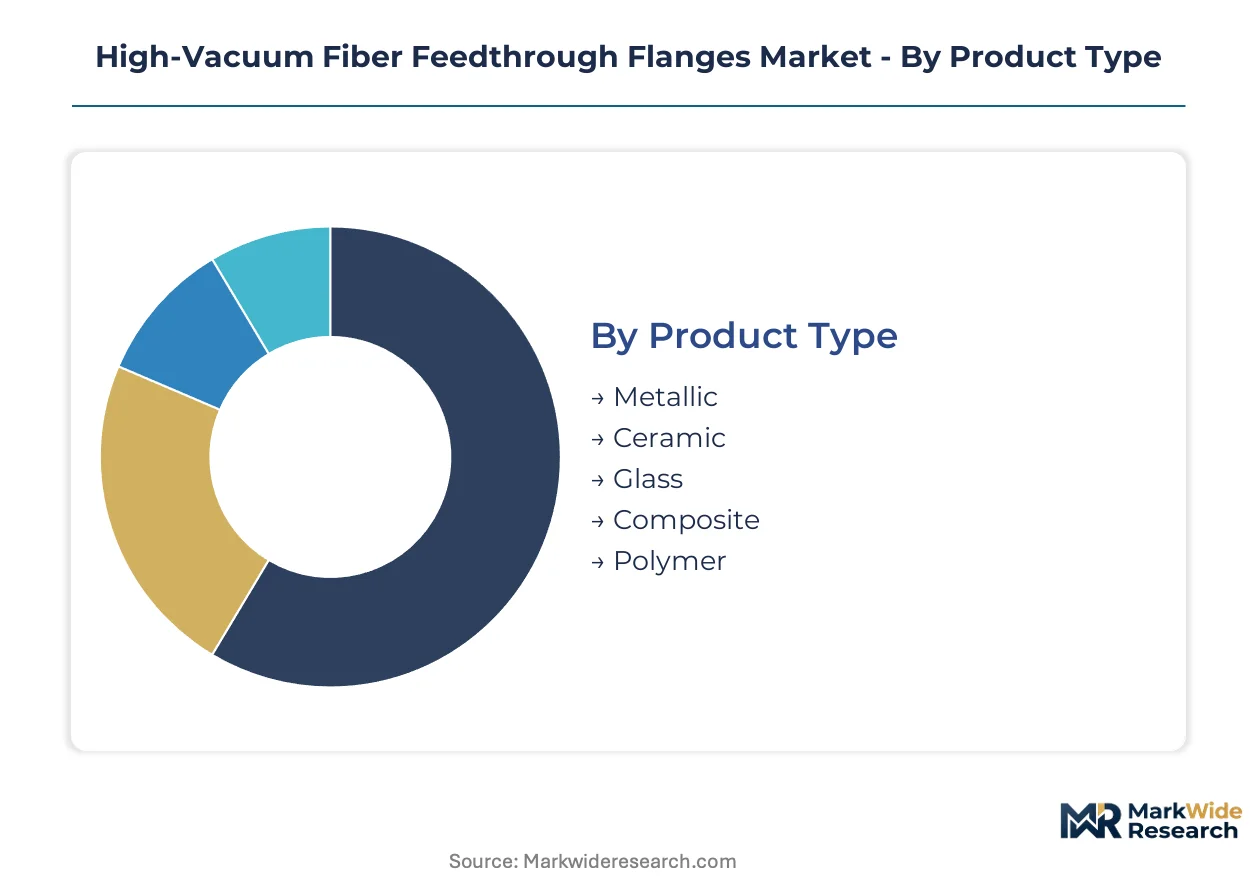
Segmentation in high-vacuum fiber feedthrough flanges reveals how technical specifications, certification burdens, and end-use reliability requirements fragment purchasing behavior across semiconductor, scientific, and defense verticals.
Product Type:
After-sales service intensity varies sharply by material family, with metallic and ceramic variants demanding specialized vacuum brazing recertification while polymer solutions require more frequent replacement protocols.
- Metallic:Stainless steel and aluminum alloys dominate CF/KF flange interfaces due to thermal expansion matching with standard vacuum chambers. Semiconductor fabrication facilities in Germany and Japan specify metallic feedthroughs for EUV lithography tools where bakeout cycles exceed 200°C.
- Ceramic:Alumina and sapphire-based seals achieve the lowest helium leak rates through matched metal-ceramic brazing. Particle accelerator beamlines in the United States and Switzerland commission custom ceramic arrays for radiation-hard optical monitoring.
- Glass:Borosilicate and fused silica windows enable UV transmission for plasma diagnostics. R&D laboratories favor glass feedthroughs for spectroscopic access in deposition system retrofits.
- Composite:Hybrid metal-ceramic constructions balance hermeticity with fiber count density. Aerospace instrumentation manufacturers specify composites for satellite thermal vacuum chambers.
- Polymer:Perfluoroelastomer and PEEK seals serve rough vacuum applications below 10⁻⁶ mbar. Quality control labs adopt polymer solutions for cost-sensitive leak detection systems.
Metallic flanges hold the largest share; momentum sits with ceramic variants as EUV toolmakers tighten leak rate specifications.
Technology:
Cost tier stratification separates commodity standard flanges from engineered solutions where brazing alloy selection and pre-qualification testing command substantial premiums.
- Standard Flanges:Catalog CF and KF configurations with fixed fiber counts serve replacement part demand. Vacuum coating equipment operators in the United States and Germany purchase standard flanges through distributor networks.
- Custom Flanges:Application-specific geometries accommodate non-standard chamber penetrations and multi-fiber arrays. Particle accelerator programs in Japan and Switzerland commission custom designs with 18-24 month qualification timelines.
- Sealed Feedthroughs:Pre-brazed and vacuum-tested subassemblies reduce field installation risk. ASML and Applied Materials mandate sealed feedthroughs for lithography tool supply chains.
- Epoxy Sealed:Room-temperature curing adhesives serve temporary research setups and prototype chambers. University laboratories utilize epoxy solutions for experimental flexibility.
- Brazed:High-temperature metal joining achieves UHV compatibility through gold-tin or indium-silver alloys. REACH compliance in Europe accelerates brazed seal adoption over lead-based alternatives.
- Indium Sealed:Low-temperature indium wire gaskets enable reusable flange connections. Scientific research facilities specify indium seals for frequent chamber reconfiguration.
Sealed feedthroughs claim the steepest expansion trajectory as OEM procurement shifts toward subsystem accountability.
Application:
Volume concentration tracks capital expenditure cycles in semiconductor equipment, with lithography tool refresh programs and new fab construction driving procurement spikes.
- Semiconductor Fabrication:EUV and DUV lithography systems require real-time optical monitoring inside vacuum chambers. Taiwan Semiconductor Manufacturing and Samsung Foundry specify fiber feedthroughs for etch and deposition tool integration.
- Scientific Research:Synchrotron and free-electron laser facilities demand custom multi-channel arrays. DESY in Germany and SLAC in the United States commission specialized feedthroughs for beamline diagnostics.
- Vacuum Coating:Optical thin-film deposition systems utilize feedthroughs for in-situ thickness monitoring. Toolmakers in Bavaria cluster serve automotive and display coating markets.
- Particle Accelerators:High-energy physics facilities require radiation-resistant hermetic seals. CERN in Switzerland and KEK in Japan deploy fiber feedthroughs for accelerator upgrade programs.
- Aerospace Instrumentation:Satellite thermal vacuum chambers and space simulation facilities specify lightweight, high-reliability seals. NASA and ESA contractors qualify feedthroughs for thermal cycling extremes.
Semiconductor fabrication commands the deepest revenue pool; aerospace instrumentation offers the fastest volume climb.
End User:
Customer type determines procurement modality, with defense contractors and optical communication firms demanding traceability documentation that R&D laboratories rarely require.
- R&D Laboratories:University and government research facilities prioritize experimental flexibility over standardization. Max Planck Institutes and national laboratories in Germany purchase through academic procurement frameworks.
- Manufacturing Units:Semiconductor fabs and coating facilities specify production-grade seals with warranty-backed performance. Intel and GlobalFoundries maintain approved vendor lists for vacuum component sourcing.
- Quality Control Labs:Metrology and calibration facilities utilize feedthroughs for leak detection and vacuum gauge verification. Third-party testing laboratories in the United States serve FDA-regulated medical device manufacturers.
- Optical Communication Firms:Fiber laser and telecom equipment makers integrate feedthroughs into hermetic package designs. Coherent and IPG Photonics specify seals for high-power laser modules.
- Defense Contractors:Classified programs demand domestic sourcing and ITAR compliance. Lockheed Martin and Northrop Grumman require traceability documentation for vacuum components in satellite payloads.
Manufacturing units generate the largest order flow; defense contractors exhibit the most rigid qualification protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from German vacuum component clusters dominate trade balances, while import dependence characterizes emerging Asian fab construction. Japan and the United States maintain near-autarky in specialized lithography-grade feedthroughs. Regional supply chains fragment along EUV tool qualification lines.
Germany
Baden-Württemberg and Bavaria host precision machining clusters serving ASML and Zeiss supply chains. REACH Annex XVII restrictions on lead-based solders force alloy reformulation across brazed seal manufacturers. DESY in Hamburg and the Karlsruhe Institute of Technology commission custom multi-fiber arrays for accelerator programs.
United States
SLAC National Accelerator and Lawrence Berkeley National Laboratory drive demand for radiation-hard ceramic feedthroughs. FDA oversight of medical device sterilization chambers shapes hermetic sealing specifications for hospital autoclave suppliers. NASA contractors in California and Colorado qualify lightweight seals for satellite thermal vacuum testing.
Japan
METI industrial standards and JIS certification protocols govern vacuum component reliability for domestic semiconductor equipment exports. KEK in Tsukuba and RIKEN in Saitama deploy fiber feedthroughs for synchrotron upgrade programs. Tokyo and Osaka prefectures concentrate precision brazing expertise for EUV lithography subsystems.
Netherlands
ASML's Veldhoven headquarters anchors lithography tool supply chain consolidation. Single-source accountability mandates compress qualification timelines for vacuum subsystem vendors. Eindhoven's high-tech campus clusters photonics integration expertise serving pre-brazed feedthrough procurement.
Switzerland
CERN in Geneva commissions custom feedthrough arrays for Large Hadron Collider luminosity upgrades. Swissmedic oversight of medical device manufacturing extends to vacuum sterilization validation requirements. The Arc Lémanique region concentrates precision engineering for scientific instrumentation.
High-Vacuum Fiber Feedthrough Flanges Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in seal technology and fiber termination. The vendor base stratifies between lithography OEM-approved suppliers and spot-market distributors serving R&D laboratories. Two archetypes dominate: photonics conglomerates with broad vacuum portfolios, and European vacuum component houses with geographic lock-in. Competitive moves center on pre-qualification testing investments and backward integration into brazing alloys.
Among photonics-anchored conglomerates, Thorlabs exemplifies the R&D-intensive archetype spanning multiple seal technologies. VACOM and Diamond SA occupy positions within European vacuum supply chains, with the latter representing specialized glass-to-metal hermetic sealing expertise. These three entities illustrate how qualification depth and geographic concentration determine competitive positioning.
| Leading Market Players |
|---|
| Thorlabs |
| VACOM |
| Diamond SA |
| SQS |
| Hositrad |
| Engionic |
| OEfind |
| SOLID SEALING TECHNOLOGY |
| SEDI-ATI Fibres Optiques |
| Others |
Pricing and Supply Chain Analysis
Precious metal input volatility in gold and indium markets compresses margin predictability for brazed seal manufacturers, forcing a three-tier pricing structure across premium, standard, and economy levels while simultaneously concentrating procurement power with vertically integrated OEMs who can absorb alloy cost swings through captive supply arrangements.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing across the market. Price differentiation rests on certification grade—REACH-compliant indium-silver alloys command substantial premiums over legacy lead-based alternatives—and volume scale, with lithography toolmakers extracting double-digit discounts through consolidated procurement. Cost compression in standard metallic flanges is intensifying because German machining clusters face capacity constraints during demand surges. R&D laboratories exhibit the highest price sensitivity due to spot purchasing patterns, while ASML-approved vendors face the lowest sensitivity given single-source accountability mandates.
Supply Chain Analysis
ITAR and dual-use export controls on precision brazing equipment limit technology transfer into emerging vacuum component manufacturing regions. Geographic supply concentration centers on Germany, Japan, and the United States, with Baden-Württemberg and Bavaria hosting critical CF/KF flange machining capacity. Raw material dependencies draw from South African platinum group metals, Chinese rare earth processing, and Swiss precision glass manufacturing. Single-source vulnerability in indium refining creates chokepoint exposure. Distribution runs through semiconductor OEM approved vendor lists rather than open distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against polymer-based vacuum seal technologies that could disrupt UHV applications if thermal cycling performance improves.
For Market Incumbents: Build certification moats through preemptive REACH Annex XVII compliance investments before alloy reformulation deadlines tighten. Absorb upfront qualification costs for ASML and Nikon vendor lists to freeze out tier-two competitors. Backward integration into indium-silver alloy production hedges against precious metal price volatility while capturing margin pools currently flowing to specialty metal suppliers. For New Entrants and Emerging Players: Aerospace instrumentation clusters in Colorado and California represent underpenetration relative to semiconductor fabrication concentration. Target NASA and ESA contractor qualification programs where domestic sourcing requirements limit incumbent geographic lock-in. Lead with lightweight composite feedthrough designs that address satellite thermal cycling specifications underserved by metallic-dominant portfolios. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors acquisition of European vacuum component houses with in-house brazing capabilities. Long-term viability hinges on exposure to EUV lithography tool refresh cycles and particle accelerator construction programs rather than cyclical R&D laboratory demand. Watch ASML supplier list expansion announcements as the inflection indicator for volume concentration shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brazing Alloys | Captures margin from precious metal suppliers while securing REACH-compliant indium-silver supply. |
| Pre-Qualified Sealed Feedthrough Subassemblies | Reduces field installation risk for ASML lithography tool supply chains demanding subsystem accountability. |
| Domestic Sourcing Certification Investment | Unlocks NASA and defense contractor procurement restricted by ITAR compliance requirements. |
| Glass-to-Metal Hermetic Sealing R&D | Addresses EUV toolmaker leak rate specifications below 10⁻¹¹ mbar·l/s through matched thermal expansion. |
| EU Green Deal Funding Alignment | Channels public capital into accelerator and fusion research vacuum infrastructure procurement. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with vacuum component procurement managers at lithography OEMs, brazing technicians at German seal manufacturers, particle accelerator beamline engineers at DESY and SLAC, and FDA compliance officers at medical device sterilization chamber suppliers. Secondary validation drew from REACH Annex XVII regulatory filings, JIS certification protocols, ASML supplier qualification documentation, and customs trade data for vacuum component exports. Bottom-up fiber feedthrough shipment estimates triangulated against top-down semiconductor capital expenditure forecasts.
Calibration against historical brazing alloy price cycles and lithography tool installation data shaped projections across the analysis window. Segmentation dimensions modeled include product type, sealing technology, application vertical, and end-user procurement modality. CAGRs derived from slope-log regression of equipment spending correlations. Forecast inputs incorporated EUV lithography ramp schedules and particle accelerator construction pipelines without year-specific project commitments.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese vacuum component entrants or rapid polymer seal thermal performance breakthroughs would shift outcomes. Material shifts in REACH substance restrictions or indium supply disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.