
 Medium Voltage Circuit Breakers Market | 2026-2036
Medium Voltage Circuit Breakers Market Size, Share, and Industry Trends Forecast 2026-2036
Medium Voltage Circuit Breakers Market Foresight
IEC 62271-100 certification-grade specifications is redrawing competitive boundaries for medium voltage circuit breakers. Schneider Electric leverages its European manufacturing base to sustain premium positioning in gas-insulated systems. ABB anchors its portfolio around vacuum interruption technology with deep R&D investment in digital monitoring integration. Siemens differentiates through microprocessor-based protection relays bundled with breaker hardware.
Medium voltage circuit breakers are electrical switching devices rated between 1 kV and 52 kV, designed to interrupt fault currents under load conditions using vacuum, SF6 gas, or air as the arc-quenching medium; they protect transformers, generators, and distribution feeders from overload damage. Vacuum circuit breakers now dominate new installations due to SF6 phase-out mandates and superior operational longevity exceeding 10,000 mechanical cycles. Gas-insulated variants retain share in space-constrained urban substations where footprint reduction justifies higher capital outlay. Electromechanical protection technology still occupies the installed base, though microprocessor-based systems capture replacement demand for predictive maintenance capability.
Utilities procurement departments increasingly require IEC 62271-100 type-test certification and IEEE C37.04 compliance documentation before tender qualification. EPA regulations on SF6 emissions are forcing manufacturers to accelerate dry air and vacuum alternatives for the US market. Stakeholders must monitor how grid digitization mandates from regulators in Germany, India, and China reshape breaker specification sheets and service revenue models.
Market Dynamics
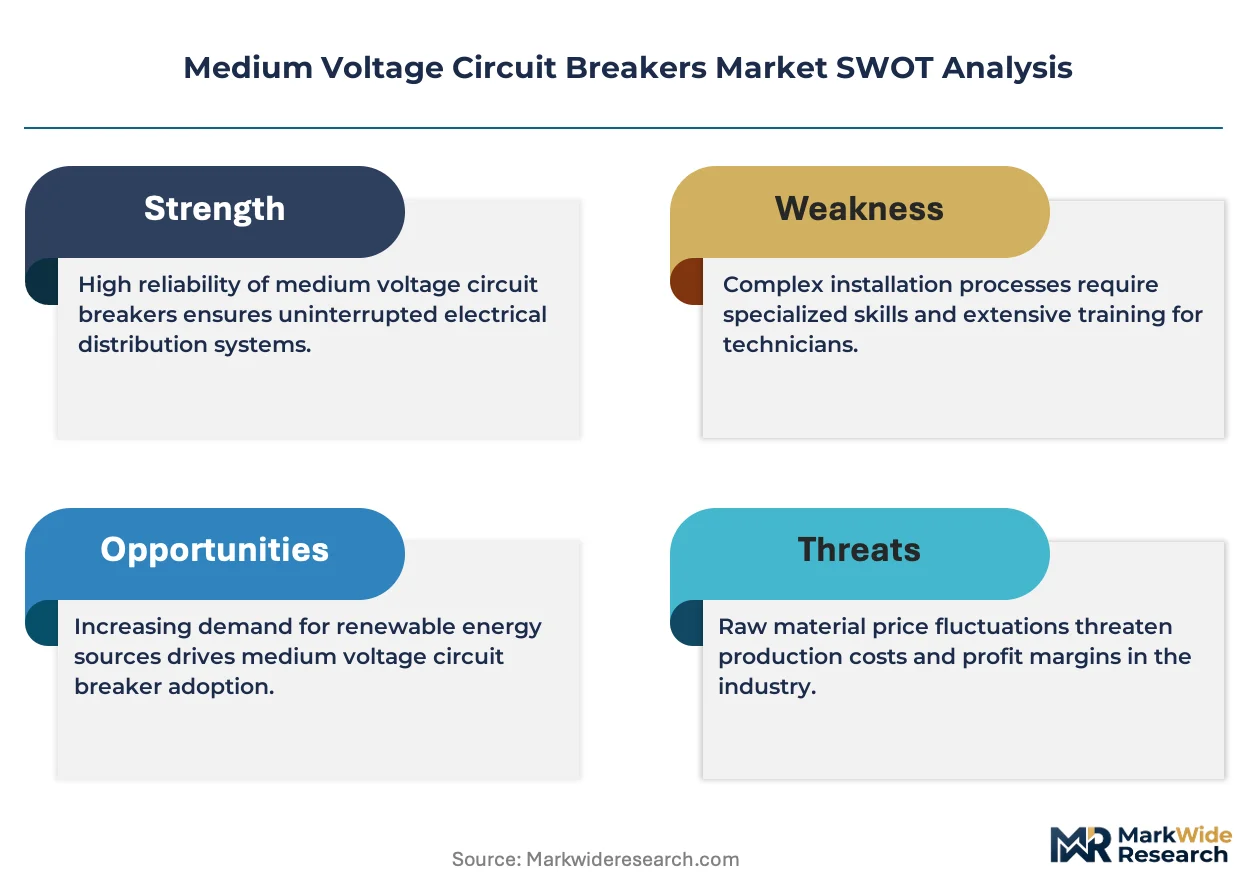
SF6 phase-out mandates from the EPA and EU F-Gas Regulation are forcing manufacturers to reengineer arc-quenching systems around vacuum and dry air alternatives, compressing R&D timelines and redrawing competitive boundaries.
Growth Catalysts
- Grid Modernization Mandates:China's State Grid and India's Central Electricity Authority are accelerating transmission infrastructure investments, expanding procurement of 36 kV and 52 kV rated breakers for substation upgrades.
- IEC 62271-100 Certification:Type-test documentation requirements are filtering out non-compliant suppliers, concentrating tender awards among certified manufacturers with in-house testing facilities.
- Vacuum Interruption Technology:Operational longevity exceeding 10,000 mechanical cycles and zero greenhouse gas footprint are displacing SF6-dependent designs in new utility installations.
Market Restraints
- Copper and Silver Contact Costs:Precious metal price volatility in contact assemblies is compressing gross margins for manufacturers without backward integration into contact production.
- SF6 Inventory Stranding:Utilities holding gas-insulated breaker fleets face accelerated depreciation as EPA emissions reporting tightens and reclamation costs escalate.
- Technical Limitation in High-Altitude Applications:Vacuum breakers experience dielectric strength degradation above 3,000 meters elevation, restricting deployment in Andean and Himalayan substations.
Strategic Opportunities
- Digital Monitoring Convergence:Integration of IoT sensors with microprocessor-based protection relays is creating predictive maintenance revenue streams beyond hardware sales.
- Urban Space Constraints:Gas-insulated switchgear retains share in Tokyo, London, and New York underground substations where footprint reduction justifies 40-60% capital premiums.
- India's PLI Scheme for Electrical Equipment:Production-linked incentives for domestic manufacturing are attracting capacity expansion for 12 kV-36 kV breaker assembly.
Industry Challenges
- Skill Gap in Protection Relay Programming:Utilities report 18-24 month lead times for commissioning engineers capable of configuring IEC 61850-compliant microprocessor systems.
- Certification Timeline Compression:IEC 62271-100 type-test cycles now require 14-18 months, delaying product launches and freezing specification sheets mid-development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medium Voltage Circuit Breakers Market |
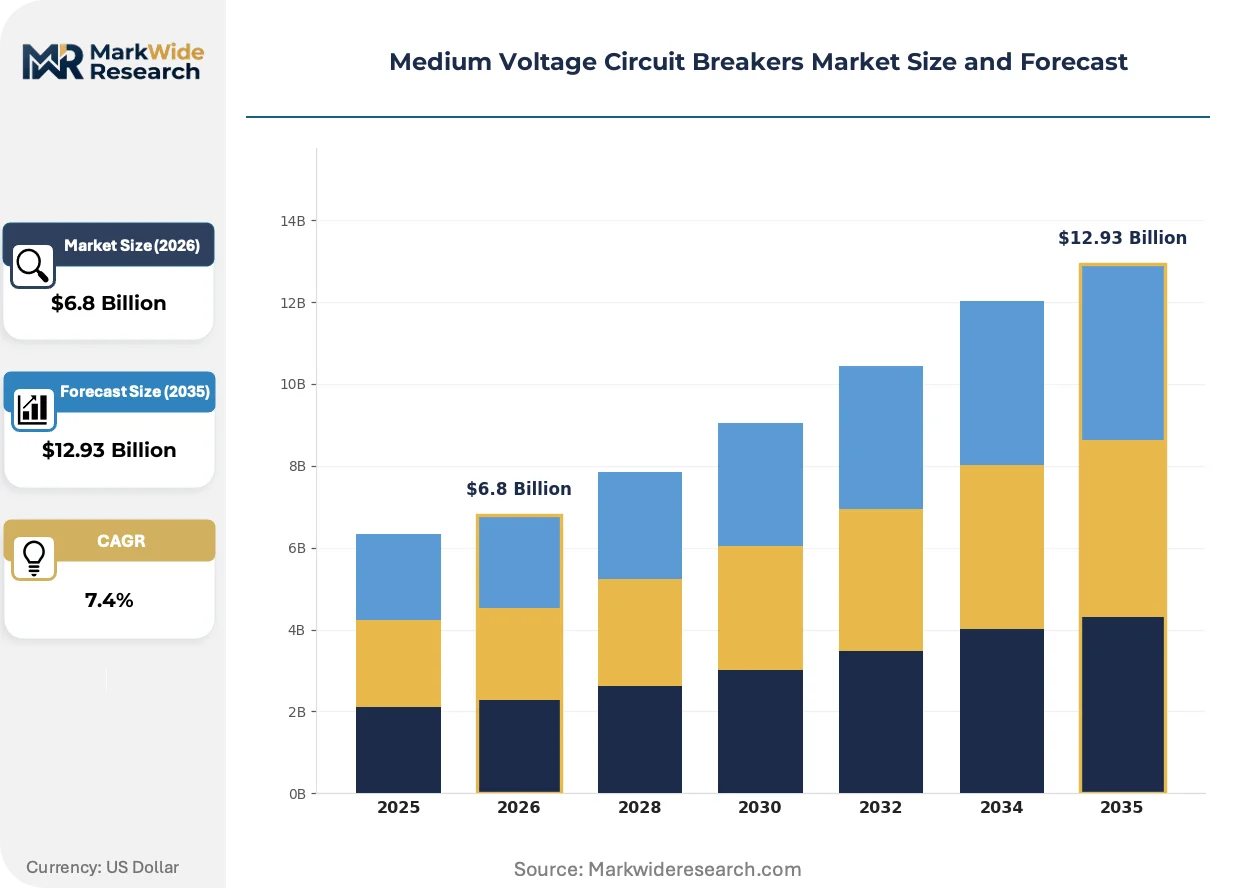
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Insulated, Gas Insulated, Oil Insulated, Vacuum Circuit Breakers Technology: Microprocessor-Based, Electromechanical, Digital, Analog End User: Utilities, Industrial Sector, Commercial Buildings, Renewable Energy Installation Type: Indoor, Outdoor, Mobile, Fixed |
| Companies Covered | Eaton, General Electric, Schneider Electric, CG Power, Fuji Electric, ABB, Mitsubishi Electric, Tavrida Electric, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medium Voltage Circuit Breakers Market Shifts & Advancements
Arc-quenching medium selection is splitting the installed base along regulatory fault lines, while digital integration and procurement centralization are rewriting vendor-customer relationships across transmission and distribution utilities.
Vacuum interruption technology is bifurcating the medium voltage breaker market between environmentally compliant new installations and legacy SF6 fleets facing stranded asset risk. European utilities under EU F-Gas Regulation pressure are adopting vacuum designs at replacement cycles compressed from 25 to 15 years. This technology shift is compressing service revenue from gas handling and reclamation while expanding hardware replacement volumes.
The EPA's SF6 emissions reporting requirements and mandatory leak detection programs are forcing US utilities to inventory and seal gas-insulated breaker installations. Industrial consequence includes accelerated capital planning for vacuum alternatives and contracted maintenance windows for existing SF6 assets. Distribution cooperatives in the Midwest and Southeast are most affected, responding with bundled procurement of vacuum breakers and digital monitoring packages.
Centralized procurement through federal and state-level tender boards is displacing decentralized utility purchasing in India, Brazil, and South Africa. Aggregated volume commitments are favoring manufacturers with scale-certified production and multi-year delivery capacity. This consolidation is most visible in India's state transmission utilities, where tender lots now specify 500-1,000 unit commitments with 10-year spare parts guarantees.
Medium Voltage Circuit Breakers Market Segmentation
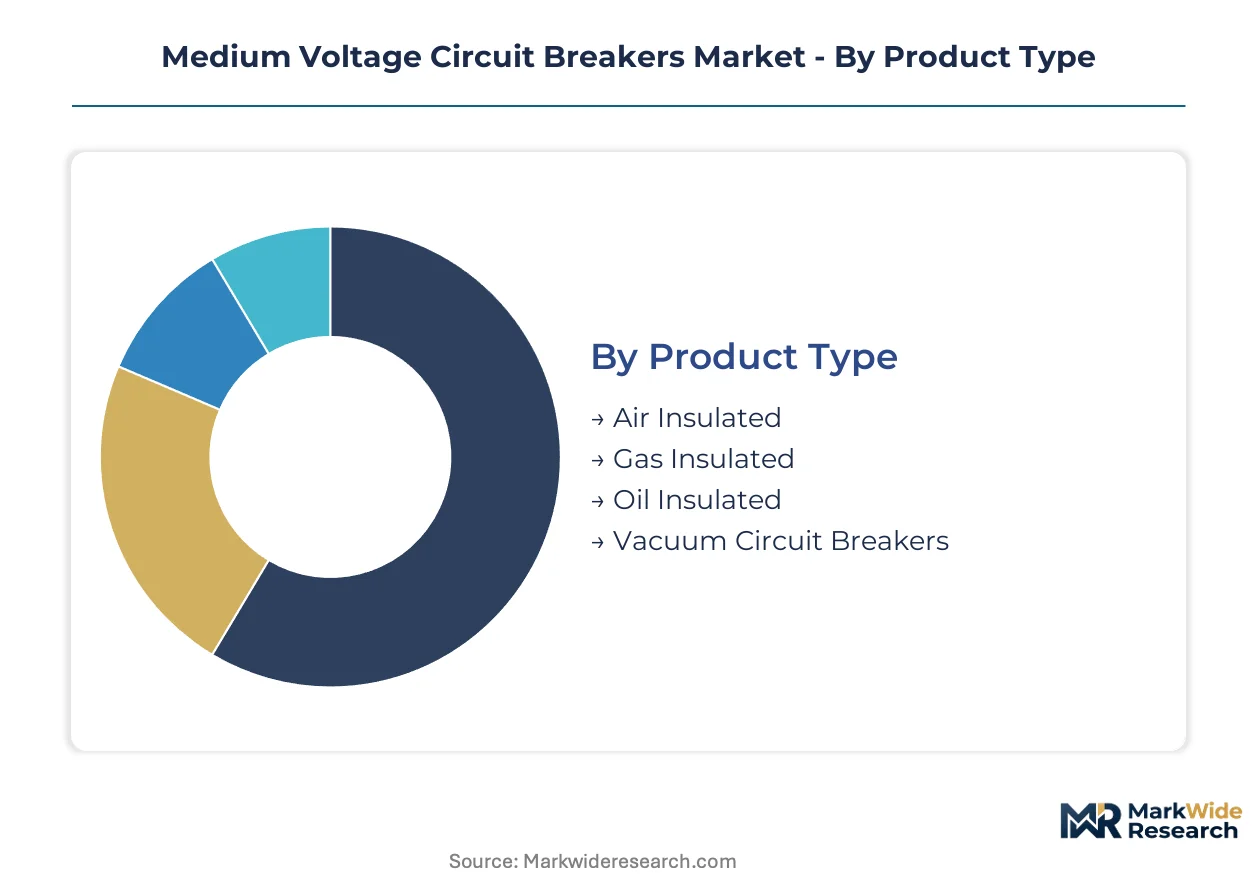
Segmentation in medium voltage circuit breakers reveals how technology choices, regulatory pressures, and installation constraints fragment procurement patterns across utilities and industrial buyers. Understanding these divides exposes where manufacturers must configure certification-grade portfolios versus cost-optimized alternatives.
Product Type:
Geographic regulatory spread shapes arc-quenching medium selection, with vacuum and dry air designs dominating export markets under emissions constraints while gas-insulated variants retain domestic share in space-constrained urban centers.
- Vacuum Circuit Breakers:Ceramic or metal-bellows sealed vacuum interrupters achieve dielectric recovery within milliseconds, eliminating arc byproducts entirely. Demand concentrates in Germany and China where EU F-Gas Regulation and national dual carbon goals mandate SF6 phase-out timelines. EPA emissions reporting in the United States accelerates utility migration toward this zero-GHG footprint technology.
- Gas Insulated:SF6 or dry air-filled chambers deliver compact footprint and superior dielectric strength for high-current interruption. Retains procurement priority in Tokyo, London, and New York underground substations where real estate premiums justify capital outlay premiums.
- Air Insulated:Open-air arc chutes with magnetic blowout coils suit outdoor installations with generous clearances. Indian state transmission utilities specify these for rural 33 kV substations under PLI scheme domestic manufacturing incentives.
- Oil Insulated:Mineral oil quenching with conservator tanks persists in legacy transformer-bay installations. Brazil's distribution cooperatives maintain these for 15 kV-25 kV rural feeders where replacement capital remains constrained.
Vacuum designs command the established base. The steepest expansion runs through dry air alternatives reengineered for gas-insulated footprints.
Technology:
Protection system architecture stratifies along customer sophistication tiers, with microprocessor platforms capturing premium utility tenders while electromechanical units serve replacement cycles in cost-sensitive markets.
- Microprocessor-Based:IEC 61850-compliant relay platforms enable predictive maintenance through waveform capture and trip-curve analytics. Concentrates in United States investor-owned utilities where FERC reliability standards and NERC compliance documentation require event logging.
- Digital:Solid-state trip units with programmable time-current characteristics bridge legacy electromechanical footprints and full microprocessor integration. India's Central Electricity Authority mandates these for new 36 kV substations under grid modernization directives.
- Electromechanical:Thermal-magnetic or dashpot time-delay mechanisms require no external power source. Persists in Southeast Asian distribution networks where commissioning engineer scarcity extends replacement timelines.
- Analog:Transistor-based solid-state relays with fixed characteristic curves. Limited to specialized marine and mining applications requiring intrinsic safety certification.
Electromechanical systems anchor the installed base. The steepest expansion trajectory belongs to microprocessor platforms with integrated condition monitoring.
End User:
Customer type determines specification stringency, with utilities enforcing IEC 62271-100 certification chains while commercial and renewable segments prioritize compact form factors and rapid delivery.
- Utilities:Transmission and distribution operators specify type-tested breakers with 10,000+ mechanical cycle endurance. China's State Grid and India's state transmission utilities aggregate 500-1,000 unit tenders with decade-long spare parts guarantees.
- Renewable Energy:Wind farm collection circuits and solar inverter substations demand compact 36 kV breakers with wide temperature operating ranges. Concentrates in Texas ERCOT zones and Rajasthan solar parks where interconnection queues pressure installation speed.
- Industrial Sector:Petrochemical, mining, and steel operations specify arc-resistant switchgear with pressure relief channels. Gulf Cooperation Council states drive procurement for 12 kV-24 kV indoor installations in process-critical environments.
- Commercial Buildings:High-rise and data center substations prioritize footprint reduction and low noise operation. Tokyo and Singapore building codes mandate dry air or vacuum alternatives for basement electrical rooms.
Utility procurement commands the established base. The steepest expansion runs through renewable energy interconnection demand.
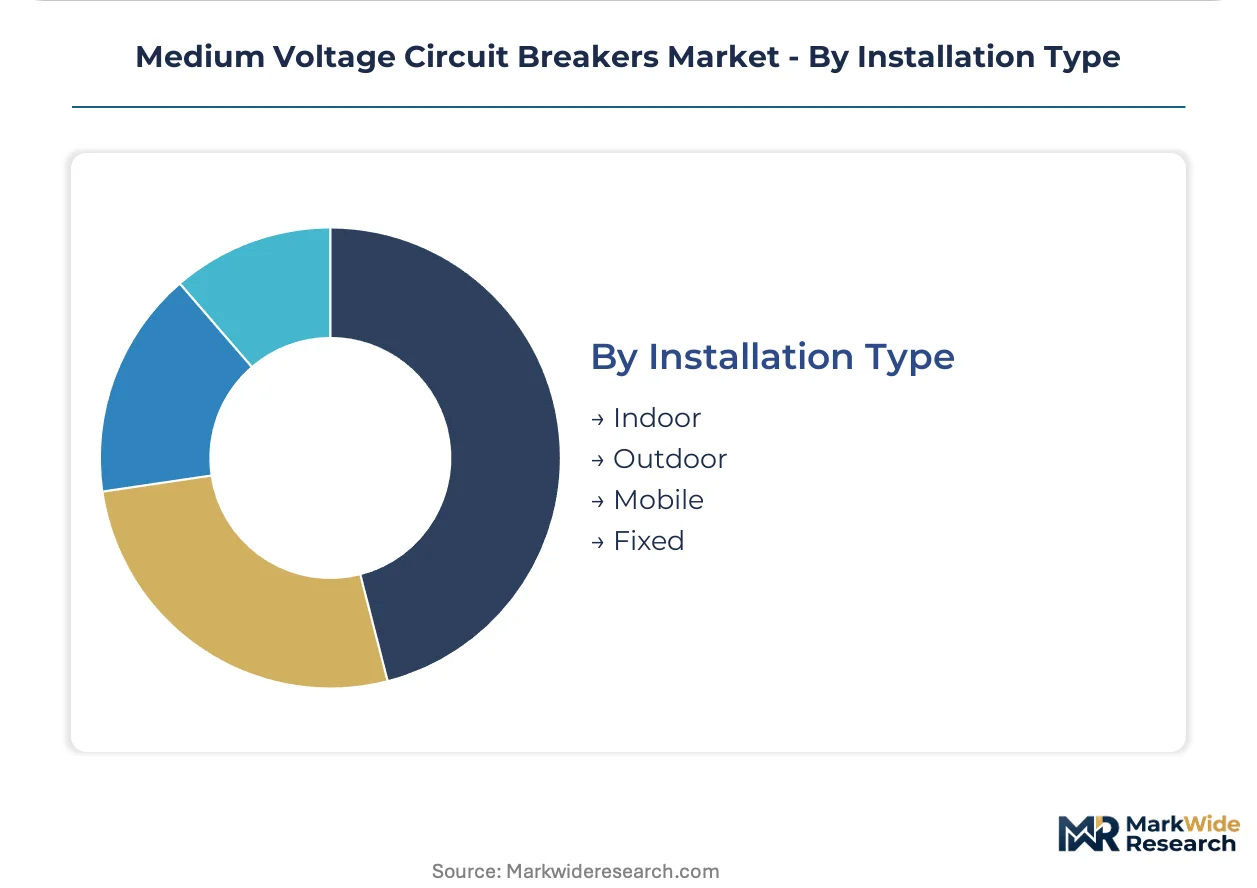
Installation Type:
Physical deployment constraints split manufacturing configurations between standardized indoor cubicles and weather-hardened outdoor enclosures with extended temperature ratings.
- Indoor:Metal-clad switchgear with withdrawable breaker trucks suits climate-controlled substations. Dominates European urban distribution networks where EU building energy performance directives favor enclosed, maintainable architectures.
- Outdoor:Dead-tank or live-tank porcelain bushing designs withstand temperature extremes and pollution. Australian transmission networks and South African Eskom specify these for remote 132 kV/33 kV step-down stations.
- Fixed:Bolted stationary mounting reduces cost for applications without maintenance access requirements. Common in Chinese industrial captive power plants with dedicated maintenance windows.
- Mobile:Skid-mounted or trailer-transportable substations enable rapid deployment for emergency restoration and construction power. US mutual assistance programs and Indian disaster response grids maintain these for cyclone and flood recovery.
Fixed indoor installations command the established base. The steepest expansion runs through mobile configurations for grid resilience programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in medium voltage circuit breakers tilt toward manufacturing concentration in Germany, China, and Japan, while import dependency characterizes India and Brazil where domestic assembly scales up under localization mandates.
China
State Grid Corporation aggregates 500-1,000 unit tenders for 36 kV and 52 kV breakers under grid modernization directives. MIIT dual carbon goals accelerate vacuum interruption adoption while compressing SF6 deployment timelines. Yangtze River Delta manufacturing clusters around Shanghai supply domestic utilities and Southeast Asian export markets.
United States
EPA emissions reporting and mandatory SF6 leak detection programs force utilities to inventory gas-insulated fleets. FERC reliability standards drive microprocessor-based protection relay procurement. ERCOT zones in Texas concentrate renewable interconnection demand for compact 36 kV breakers.
Germany
EU F-Gas Regulation compresses replacement cycles from 25 to 15 years for SF6-dependent installations. Industrial buyers specify IEC 62271-100 certified vacuum breakers with digital monitoring integration. Bavaria and Baden-Württemberg host manufacturing facilities serving Central European utility tenders.
India
Central Electricity Authority mandates digital protection relays for new 36 kV substations under grid modernization programs. PLI scheme incentives attract domestic assembly capacity for 12 kV-36 kV breaker production. Rajasthan solar parks and Maharashtra state transmission utilities drive procurement volume.
Japan
METI building energy performance directives favor enclosed switchgear architectures for urban distribution networks. Tokyo underground substations retain gas-insulated priority where footprint reduction justifies capital premiums. Kansai region manufacturers supply vacuum breakers to domestic utilities and Southeast Asian markets.
Medium Voltage Circuit Breakers Market Competitive Landscape
Listed leaders compete with private specialists across certification-grade portfolio breadth. The vendor base concentrates around manufacturers with in-house IEC 62271-100 type-test facilities and multi-year delivery capacity. Three archetypes dominate: European industrial conglomerates with integrated protection relay portfolios, Asian electrical equipment specialists with vacuum interruption scale, and regional fabricators serving cost-sensitive tenders. Competitive moves center on geographic expansion into PLI-incentivized manufacturing zones and technology licensing for dry air arc-quenching alternatives.
Among European-based conglomerates, Schneider Electric and Siemens occupy positions bundling breaker hardware with microprocessor-based protection systems. ABB anchors the vacuum interruption archetype with digital monitoring integration. These three exemplify the certification-grade tier where type-test documentation and decade-long spare parts guarantees filter tender participation.
| Leading Market Players |
|---|
| Eaton |
| General Electric |
| Schneider Electric |
| CG Power |
| Fuji Electric |
| ABB |
| Mitsubishi Electric |
| Tavrida Electric |
| Siemens |
| Others |
Supply & Pricing Matrix
Fourteen-to-eighteen-month IEC 62271-100 type-test cycles concentrate supply capacity among manufacturers with captive high-voltage laboratories, compressing pricing power for smaller fabricators and amplifying premiums for certified-tier hardware.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in medium voltage circuit breakers. Certification grade and volume scale drive price differentiation, with IEC 62271-100 type-tested units commanding substantial premiums over uncertified alternatives. Cost compression in the economy tier is intensifying because Indian PLI scheme incentives are attracting domestic assembly capacity for 12 kV-36 kV breakers. Distribution cooperatives in Brazil and Southeast Asia exhibit highest price sensitivity, while German utilities under EU F-Gas Regulation deadlines show least sensitivity to secure vacuum interruption compliance.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are extending inbound logistics costs for ceramic vacuum interrupters sourced from Yangtze River Delta clusters. Manufacturing concentrates in China, Germany, and Japan, with vacuum interrupter production drawing from silver-copper contact alloys, ceramic metallized bellows, and epoxy resin housings. Single-source vulnerability sits with Japanese suppliers of high-purity alumina ceramics for vacuum envelopes. Distribution runs through direct utility tender channels in China and India, while European and North American markets layer authorized distributors for aftermarket service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grid digitization mandates from regulators in Germany, India, and China are transforming breaker procurement into a platform-economics inflection, where hardware margins collapse into software-enabled predictive maintenance subscriptions and IEC 61850 interoperability becomes the lock-in mechanism.
For Market Incumbents: Consolidate certification-grade testing capacity and captive contact material production to defend against emerging Asian specialists with PLI-subsidized cost positions. Acquire or license dry air arc-quenching IP to hedge SF6 phase-out acceleration under EPA and EU F-Gas Regulation timelines. Deepen backward integration into silver-copper contact manufacturing to offset precious metal volatility compressing gross margins. For New Entrants and Emerging Players: Commissioning engineer scarcity for IEC 61850-compliant microprocessor systems creates a service-layer gap where incumbents under-serve. Target India's state transmission utilities with digital protection relay programming services bundled with breaker hardware, exploiting 18-24 month lead times for qualified field engineers. Pursue white-label manufacturing partnerships with Yangtze River Delta fabricators to bypass type-test capital requirements. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because grid modernization mandates across China, India, and the United States create decade-long replacement cycles with embedded spare parts revenue. Acquisition targets should exhibit in-house IEC 62271-100 type-test facilities and established utility tender board relationships. Monitor EPA SF6 emissions reporting enforcement intensity as the inflection signal for vacuum interruption technology substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contact Materials | Captive silver-copper production insulates margins from LME volatility affecting competitors. |
| IEC 62271-100 Type-Test Facility Expansion | In-house certification capability accelerates product launches and filters tender participation. |
| Dry Air Arc-Quenching Technology Licensing | SF6 alternatives future-proof portfolios against EPA and EU F-Gas Regulation phase-out mandates. |
| Digital Protection Relay Service Subscriptions | Predictive maintenance revenue streams extend customer lifetime value beyond hardware sales. |
| PLI-Scheme Manufacturing Localization | India's production-linked incentives reduce landed cost for 12 kV-36 kV breaker assembly. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across utility procurement departments, OEM engineering teams, and aftermarket service providers. Primary interviews with transmission planning officers, protection relay commissioning engineers, and breaker manufacturing plant managers were cross-validated against secondary sources including IEC standard committee documentation, EPA emissions reporting filings, FERC reliability compliance records, and customs trade data for vacuum interrupter imports. Bottom-up unit shipment estimates were triangulated with top-down utility capital expenditure projections.
Across the analysis window, forecasts were constructed using a segmented analytical framework spanning arc-quenching medium, protection technology architecture, end-user vertical, and installation type. CAGRs were derived from regression analysis of historical tender award volumes against grid modernization budget allocations. Industry-specific inputs included State Grid Corporation procurement aggregation patterns, EU F-Gas Regulation replacement cycle compression effects, and PLI scheme capacity addition timelines in India.
Underlying assumptions cover sustained utility capital expenditure commitment, stable precious metal pricing for contact assemblies, and regulatory enforcement continuity for SF6 emissions reporting, with deviation risk concentrated in tariff exposure for ceramic component imports and certification timeline delays from laboratory capacity constraints. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
US Industrial Ceiling Fan Market
Electrical Equipment
Europe High Voltage Switchgear Market
Electrical Equipment
Axial Fans Market
Electrical Equipment
Pad-Mounted Transformer Market
Electrical Equipment
Hermetic Reciprocating Refrigerator Compressor Market
Electrical Equipment
Global Capacitor Bank Controllers Market
Electrical Equipment
High Voltage Electric Insulators Market
Electrical Equipment
Electrical Measuring Instrument Market
Electrical Equipment
North America Commercial Lighting Control Market
Electrical Equipment
Rotary and RF Rotary Joints Market
Electrical Equipment
Busbar Systems Market
Electrical Equipment
Vacuum Contactor Market
Electrical Equipment
Smart Heater Market
Electrical Equipment
Europe Electrical Bushing Market
Electrical Equipment
Vacuum Interrupter Market
Electrical Equipment
Electric Enclosure Market