
 Electrical Fuses Market | 2026-2036
Electrical Fuses Market Size, Share, and Industry Trends Forecast 2026-2036
Electrical Fuses Market Analysis
Preventive maintenance contracts and software-defined thermal monitoring is hardening into a discrete revenue layer for fuse suppliers. Littelfuse leverages its sensor-integrated fuse portfolio to capture recurring service value. Schneider Electric anchors its position through integrated power-distribution platforms that bundle fuse protection with digital diagnostics. Mersen specializes in high-speed semiconductor protection fuses for renewable energy inverters.
Electrical fuses are sacrificial overcurrent protection devices containing a metal wire or strip that melts when excessive current flows, thereby interrupting the circuit and preventing equipment damage or fire. They operate on thermal principles with precise melting characteristics defined by alloy composition, element geometry, and fill material such as silica sand for arc quenching. The rating dimension structures the competitive landscape, with low-voltage fuses dominating volume in residential and commercial installations while medium-voltage segments command stronger margins in utility-scale applications. PCB mount installation types are gaining traction in electronics and electric vehicle subsystems where space constraints and automated assembly dictate form factor selection.
IEC 60269, UL 248, and the EU F-Gas Regulation shape product design and market access across major economies, with IEC standards governing breaking capacity and time-current characteristics in Europe and Asia while UL certification remains mandatory for North American electrical infrastructure. India's BIS compulsory registration scheme now requires fuse testing to IS/IEC standards before import clearance. Stakeholders must monitor evolving arc-flash protection mandates and silicon carbide inverter proliferation, as faster fault-clearing requirements will redefine fuse speed-class specifications.
Market Dynamics
Silicon carbide inverter proliferation is compressing fault-clearing timeframes across renewable energy and electric vehicle powertrains, forcing fuse manufacturers to recalibrate speed-class specifications and thermal performance thresholds.
Growth Catalysts
- Data center power density:Hyperscale facilities in Northern Virginia, Frankfurt, and Singapore are deploying medium-voltage fuse banks to protect multi-megawatt UPS architectures and busbar distribution systems.
- EU F-Gas Regulation:Phase-down of sulfur hexafluoride in medium-voltage switchgear is redirecting investment toward vacuum interruption and fuse-protected alternatives that eliminate greenhouse gas insulation.
- India's BIS compulsory registration:Import clearance requirements for fuse testing to IS/IEC standards are formalizing quality tiers and advantaging certified suppliers in industrial electrification projects.
Market Restraints
- Silver price volatility:Fuse element alloys containing silver face input cost pressure from precious metal speculation, compressing margins on precision melting-grade products.
- Supply concentration in silica sand:Arc-quenching fill material sourcing clusters in specific river basin deposits, creating geographic vulnerability for fuse manufacturers dependent on high-purity grades.
- Circuit breaker substitution:Resettable electronic protection in low-voltage residential panels is capturing share in new construction where maintenance access permits active reset devices.
Strategic Opportunities
- Software-defined thermal monitoring:Sensor-integrated fuse portfolios enable recurring service revenue through predictive replacement scheduling and arc-flash incident prevention analytics.
- Electric vehicle powertrain integration:Battery pack and DC-DC converter protection requirements in Germany, China, and California are creating specification windows for compact PCB-mount fuse families.
- India PLI scheme for manufacturing:Production-linked incentives for electrical equipment are attracting fuse assembly investment to serve domestic industrial demand and regional export.
Industry Challenges
- IEC 60269-4 certification timelines:Semiconductor protection fuse approval for high-speed clearing applications requires extensive breaking-capacity testing that extends product launch cycles.
- Legacy power infrastructure integration:Fuse coordination with existing molded-case circuit breakers in retrofit installations demands engineering validation that slows specification velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrical Fuses Market |
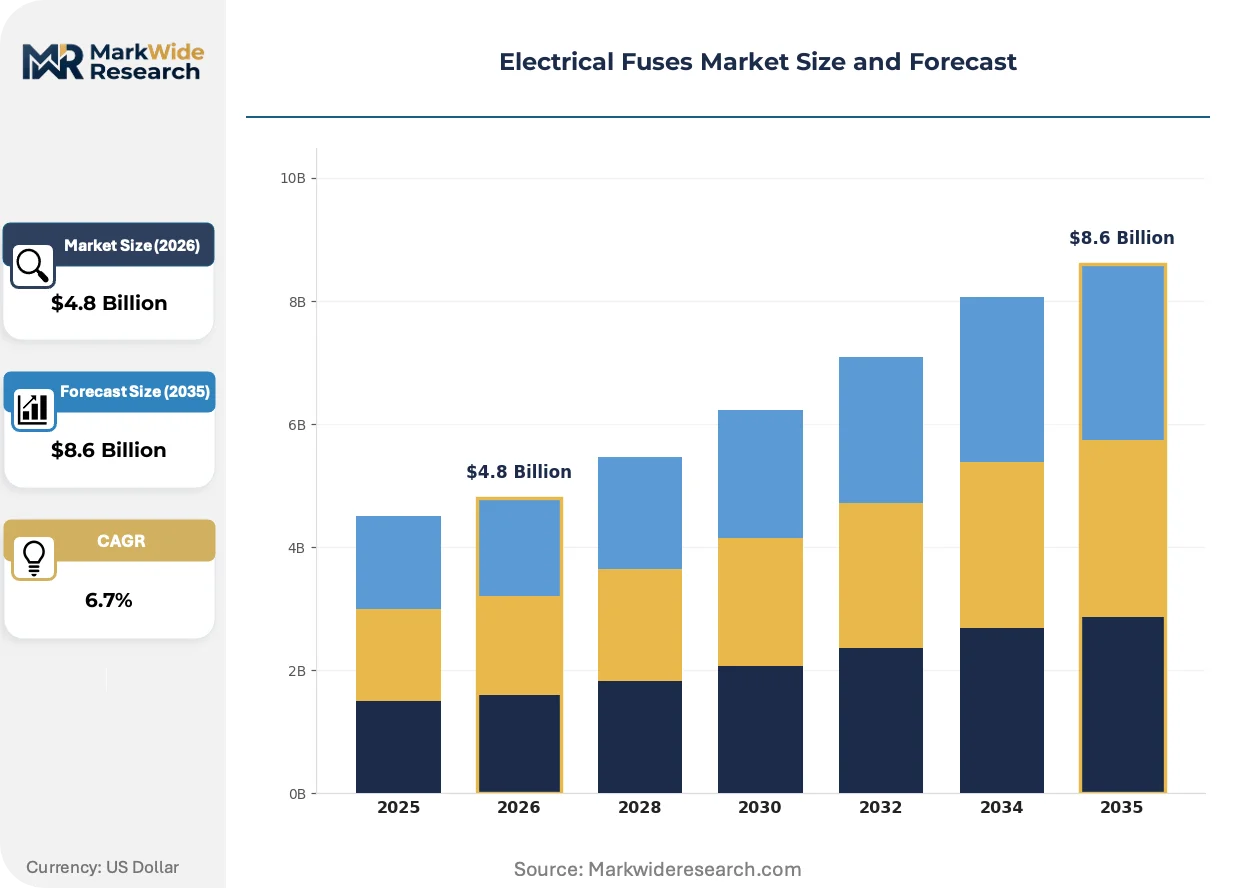
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cylindrical, Blade, Cartridge, Miniature Application: Power Distribution, Automotive, Electronics, Industrial Equipment Rating: Low Voltage, Medium Voltage, High Voltage, Ultra High Voltage Installation Type: Panel Mount, PCB Mount, Inline, Plug-in |
| Companies Covered | Siemens, Littelfuse, ABB, Legrand, Bel Fuse, Schneider Electric, Mersen, Emerson, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrical Fuses Market Emerging Trajectories
Active material science and embedded intelligence are redefining fuse architecture from passive protection toward condition-aware safety systems that communicate degradation states before failure.
Gallium nitride power semiconductors is overtaking silicon MOSFETs in high-frequency DC-DC conversion applications. Electric vehicle onboard chargers and server power supplies are adopting GaN topologies at accelerating pace. This transition is overtaking conventional fuse speed ratings and forcing development of sub-microsecond clearing products that protect against faster fault energy release.
EU F-Gas Regulation phase-down mandates are eliminating sulfur hexafluoride insulation from new medium-voltage switchgear installations. Vacuum interruption technology combined with current-limiting fuses is capturing substation retrofit contracts. Renewable energy inverter OEMs in Germany, Spain, and Denmark are redesigning DC input protection around SF6-free fuse-switch combinations to maintain grid connection permits.
After-sales service unbundling is separating fuse replacement from original equipment procurement contracts. Industrial facility operators in Texas, Rotterdam, and Singapore are contracting preventive maintenance separately from hardware supply. Data center operators are driving this shift most visibly, negotiating thermal monitoring subscriptions that convert fuse vendors into recurring service providers rather than component suppliers.
Electrical Fuses Market Segmentation
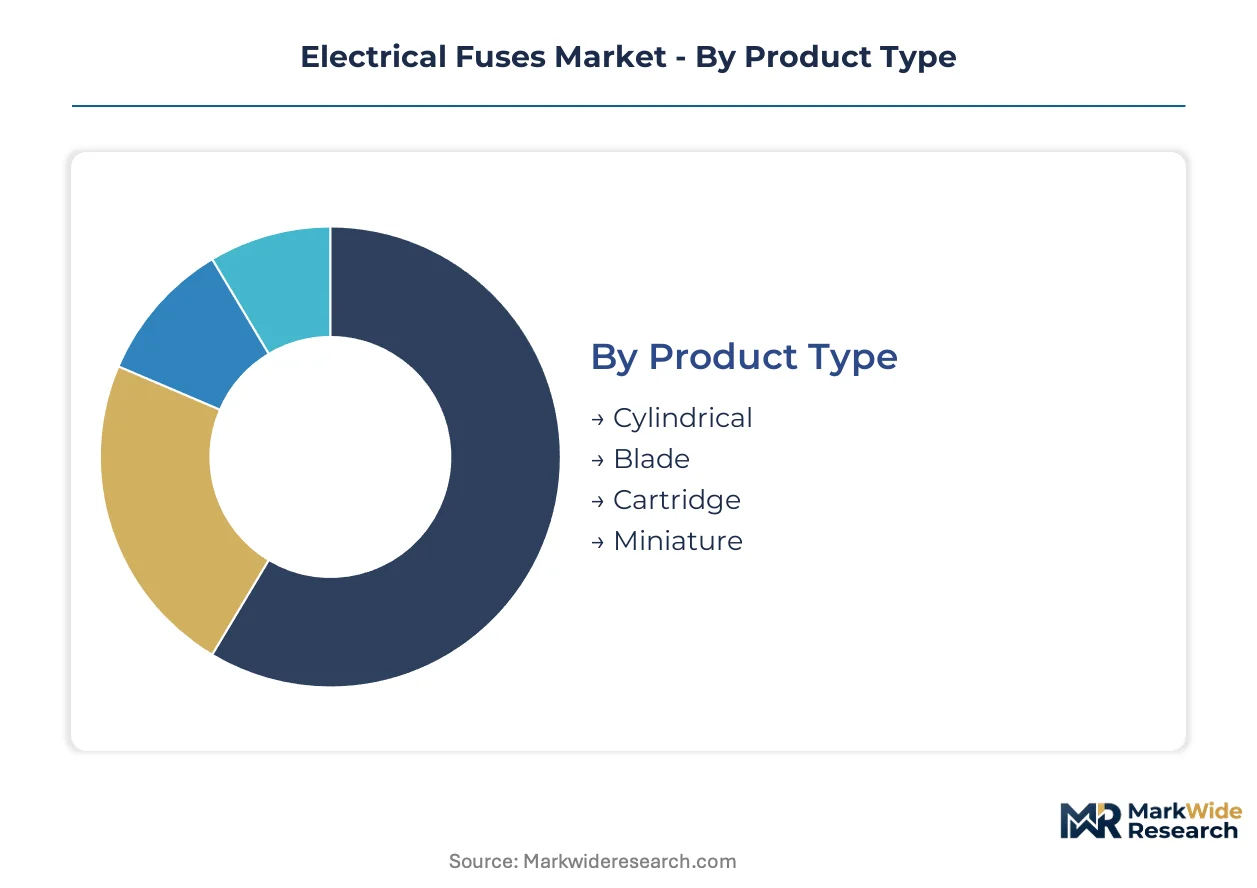
Fuse specification cascades through multiple decision layers—electrical rating determines fundamental suitability, installation geometry dictates form factor compatibility, and end-use application imposes speed-class and environmental resilience requirements. Procurement teams sequence these filters differently across verticals, creating distinct competitive battlegrounds within each dimension.
Product Type:
Buyers prioritize arc-quenching reliability and replacement accessibility when selecting fuse geometries for specific equipment enclosures.
- Cylindrical:Ceramic or glass tube construction with metal end caps provides standardized dimensions across IEC 60269 ratings. Industrial motor control centers in Germany and India specify these for easy field replacement without disassembly. Demand concentrates in legacy manufacturing infrastructure where maintenance crews stock standardized fuse inventories.
- Blade:Flat metal strips embedded in plastic housings enable low-profile integration with automotive fuse boxes and residential load centers. Automotive OEMs in Michigan and Stuttgart specify these for 12V-48V power distribution, with electric vehicle architectures driving demand for higher-current variants in battery management systems.
- Cartridge:Rectangular ceramic bodies with bolted or clip terminals handle medium-voltage industrial applications. Cement mills and steel foundries deploy these for motor branch circuit protection where high breaking capacity is mandatory.
- Miniature:Sub-5mm footprints serve PCB-level overcurrent protection in consumer electronics and telecommunications equipment. Surface-mount variants dominate smartphone and laptop adapter manufacturing in Shenzhen and Taipei.
Volume sits with Cylindrical fuses in established industrial bases; growth tilts toward Blade configurations as automotive electrification accelerates.
Application:
End-use verticals impose divergent certification requirements and replacement cycle economics that reshape supplier margin structures.
- Power Distribution:Utility-scale substations and commercial building main switchgear demand high breaking capacity with documented coordination studies. Northern Virginia data centers and Frankfurt industrial parks specify these for multi-megawatt protection schemes where selective tripping preserves upstream continuity.
- Automotive:Internal combustion vehicle fuse boxes and electric vehicle high-voltage junction boxes require vibration resistance and temperature cycling endurance. Battery pack OEMs in Shanghai and California mandate PCB-mount variants for DC-DC converter protection.
- Electronics:Consumer device power supplies and telecommunications infrastructure prioritize compact footprints and surface-mount compatibility. Server power supply manufacturers in Taiwan specify sub-microsecond clearing speeds for gallium nitride topology protection.
- Industrial Equipment:Motor starters, variable frequency drives, and welding equipment need current-limiting characteristics that minimize let-through energy. Indian cement plants and German machine tool builders specify these for arc-flash hazard reduction.
Revenue concentrates in Power Distribution for medium-voltage margins; Electronics applications are climbing the fastest as GaN adoption compresses protection response requirements.
Rating:
Voltage classification determines manufacturing complexity, testing regime intensity, and regulatory jurisdiction for market access.
- Low Voltage:Up to 1kV AC or 1.5kV DC covers residential panels, commercial distribution, and automotive 12V-48V systems. Mass-market residential construction in Texas and Florida drives volume through standardized 15A-30A ratings.
- Medium Voltage:1kV-36kV range serves industrial motor protection and renewable energy inverter DC inputs. German solar farm developers specify these for string inverter protection under EU F-Gas Regulation compliance mandates.
- High Voltage:36kV-150kV applications include utility substation transformer protection and generator circuit isolation. Indian transmission utilities deploy these for rural electrification grid extensions.
- Ultra High Voltage:Above 150kV for specialized HVDC transmission and test equipment applications. Limited deployment in research facilities and grid interconnection projects.
Shipment volume clusters in Low Voltage for residential and commercial ubiquity; specification value migrates toward Medium Voltage as renewable energy inverter protection demands intensify.
Installation Type:
Mounting geometry dictates assembly automation compatibility, field service accessibility, and thermal management integration.
- Panel Mount:Screw-terminal or clip-on attachment to electrical enclosures enables field replacement without board-level disassembly. Industrial maintenance departments in Rotterdam and Houston prefer these for minimize downtime.
- PCB Mount:Through-hole or surface-mount solder attachment integrates directly into printed circuit board assemblies. Electric vehicle onboard charger manufacturers in Germany and China specify these for automated production lines.
- Inline:Series integration into cable harnesses protects wiring runs in automotive and marine applications. Battery pack interconnects in California EV manufacturing use these for cell-level isolation.
- Plug-in:Tool-free insertion into fuse holders enables rapid replacement in residential load centers and automotive fuse boxes. Big-box retail channels in the US stock these for consumer self-service.
Unit economics favor Panel Mount in industrial aftermarket replacement; PCB Mount specifications are gaining share fastest as electric vehicle powertrain integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes the largest share of electrical fuses for industrial electrification and data center buildouts, while Germany and the United States concentrate specialized production for medium-voltage and automotive applications. Manufacturing clusters in India and Southeast Asia are expanding assembly capacity to serve regional demand growth.
China
Hyperscale data centers in Beijing and Shanghai deploy medium-voltage fuse banks for multi-megawatt UPS protection, while BYD and CATL battery manufacturing in Shenzhen drives PCB-mount fuse specifications for electric vehicle powertrains. MIIT's GB standards for electrical safety equipment mandate local testing certification before market entry. The Yangtze River Delta manufacturing corridor hosts fuse element foundries supplying both domestic industrial demand and export markets.
Germany
Siemens and ABB industrial automation in Bavaria and Baden-Württemberg specifies high-speed semiconductor protection fuses for variable frequency drives and renewable energy inverters. The EU F-Gas Regulation phase-down of sulfur hexafluoride redirects medium-voltage switchgear investment toward vacuum interruption and fuse-protected alternatives. Frankfurt's data center cluster represents Europe's densest concentration of fuse-protected power distribution infrastructure.
United States
Northern Virginia's hyperscale data center corridor consumes medium-voltage fuse assemblies for 100MW-plus facility power distribution, while Texas oilfield electrification and petrochemical expansion drives industrial fuse replacement cycles. OSHA arc-flash protection mandates tighten coordination requirements between fuses and molded-case circuit breakers in retrofit installations. Michigan automotive OEMs specify blade fuses for 48V mild-hybrid architectures transitioning from 12V systems.
India
Cement plants in Rajasthan and steel foundries in Odisha deploy cartridge fuses for motor branch circuit protection under BIS compulsory registration requirements for IS/IEC standard compliance. The PLI scheme for electrical equipment manufacturing attracts fuse assembly investment to Gujarat and Maharashtra for domestic supply and regional export. Rural electrification grid extensions by Power Grid Corporation specify high-voltage fuses for transformer protection in transmission infrastructure.
Japan
Automotive fuse specifications from Toyota and Honda in Aichi Prefecture emphasize vibration resistance and temperature cycling endurance for hybrid vehicle power distribution. METI's energy efficiency standards for industrial equipment drive demand for current-limiting fuses that minimize let-through energy in motor starter applications. The Kanto region's precision electronics manufacturing cluster sources miniature surface-mount fuses for consumer device power supplies and telecommunications infrastructure.
Electrical Fuses Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the electrical fuses market, with integrated manufacturers maintaining foundry control over fuse element alloys and ceramic body production while specialized designers outsource assembly to contract manufacturers. The vendor base stratifies into three tiers: diversified electrical conglomerates with fuse divisions, pure-play fuse specialists with vertical integration into materials, and regional assemblers serving price-sensitive construction markets. Dominant competitive moves include backward integration into silver and copper alloy supply chains to hedge precious metal volatility, and strategic partnerships with data center developers for preventive maintenance contract bundling.
Among diversified electrical conglomerates, Siemens and ABB exemplify scale-driven positioning through integrated power-distribution platforms that bundle fuse protection with digital diagnostics and switchgear systems. Littelfuse occupies a specialist tier focused on sensor-integrated fuse portfolios that enable recurring service revenue through predictive replacement analytics. These three companies represent contrasting archetypes: the full-platform integrator, the component specialist with embedded intelligence, and the hybrid structure spanning both hardware supply and aftermarket services.
| Leading Market Players |
|---|
| Siemens |
| Littelfuse |
| ABB |
| Legrand |
| Bel Fuse |
| Schneider Electric |
| Mersen |
| Emerson |
| Eaton |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between IEC 60269-compliant precision fuses and commodity residential variants generates divergent margin structures and sourcing strategies across the electrical fuses market. Premium-tier suppliers in Germany and Japan command pricing power through captive silver alloy foundries and documented breaking-capacity test records, while commodity assemblers in India and Southeast Asia compete on volume scale with outsourced ceramic body production.
Pricing Analysis
Margin tightening in medium-voltage renewable energy segments reflects silver price volatility and extended IEC 60269-4 certification timelines that delay product launches. Contract-based long-term offtake agreements dominate utility-scale procurement, with price differentiation anchored in breaking capacity documentation and arc-flash coordination study support. Residential panel mount fuses face acute price sensitivity from big-box retail channels, while data center operators absorb premium pricing for sensor-integrated variants bundled with thermal monitoring subscriptions.
Supply Chain Analysis
Freight cost escalation on silica sand shipments from specific river basin deposits in China and India is compressing margins for arc-quenching fill material sourcing. Fuse element alloy production concentrates in Germany, Japan, and the United States, with silver and copper sourcing drawn from precious metal exchanges in London and Shanghai. Single-source vulnerability in high-purity ceramic body supply from China's Yangtze River Delta creates geographic concentration risk. Distribution runs through electrical wholesale distributors and OEM direct channels, with preventive maintenance contracts emerging as a parallel service revenue stream.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silver alloy foundry capacity constraints and IEC certification backlog are propping pricing power for qualified suppliers across the electrical fuses market. Procurement bottlenecks favor incumbents with in-house materials production.
For Market Incumbents: Acquire captive silver alloy foundry capacity or long-term precious metal supply agreements to hedge input cost volatility from London and Shanghai exchange fluctuations. Expand breaking-capacity testing infrastructure to compress IEC 60269-4 certification timelines that currently delay semiconductor protection fuse launches. Deepen data center developer partnerships to convert hardware supply relationships into recurring thermal monitoring service contracts before circuit breaker substitution accelerates in low-voltage residential segments. For New Entrants and Emerging Players: India's BIS compulsory registration scheme opens a window for certified fuse assembly investment targeting cement and steel industrial electrification projects in Rajasthan and Odisha. Target PCB-mount fuse specifications for electric vehicle onboard charger manufacturers in Germany and China, where GaN topology adoption is forcing sub-microsecond clearing product development. Pursue white-label manufacturing partnerships with established European distributors to bypass direct certification investment requirements. For Investors and Strategic Acquirers: Re-rating potential sits with sensor-integrated fuse specialists given software-defined thermal monitoring subscription attach rates expanding gross margin profiles. Long-term viability favors asset-light designers with backward integration into materials science IP rather than capital-heavy ceramic body foundries. Monitor silicon carbide inverter penetration rates in renewable energy and electric vehicle powertrains as the inflection signal for high-speed clearing fuse demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silver Alloys | Captive foundry capacity hedges London Metal Exchange price volatility for precision melting-grade fuse elements. |
| IEC 60269-4 Certification Investment | Accelerated breaking-capacity testing timelines capture semiconductor protection fuse demand from SiC inverter OEMs. |
| Sensor-Integrated Fuse Portfolio Expansion | Predictive replacement analytics convert component vendors into recurring service providers for data center operators. |
| India PLI Scheme Manufacturing Entry | Production-linked incentives in Gujarat and Maharashtra serve domestic industrial demand and regional Southeast Asian export. |
| SF6-Free Fuse-Switch Combination Development | EU F-Gas Regulation compliance enables grid connection permits for German and Spanish renewable energy inverter OEMs. |
Methodological Framework
SEC 10-K filings, IEC certification registries, and customs trade data formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with fuse product managers at diversified electrical conglomerates, procurement leads at data center developers, and maintenance directors at Indian cement plants provided operating context on replacement cycle economics and specification velocity. Bottom-up unit shipment estimates across voltage rating, installation type, and end-use application segments were triangulated against top-down power infrastructure investment data from utility regulatory filings.
Historical trendline analysis of fuse procurement patterns across data center, automotive, and industrial verticals established baseline growth trajectories. The analytical framework modeled volume and value outputs across product type, voltage rating, installation geometry, and end-use application dimensions. CAGRs were derived from regression analysis of segment-specific demand drivers including GaN semiconductor adoption rates, EU F-Gas Regulation implementation timelines, and India's BIS registration enforcement intensity.
The model assumes a particular technology adoption path for silicon carbide and gallium nitride power semiconductors; alternative pathways for wide-bandgap device penetration would alter the outlook for high-speed clearing fuse specifications. Forecasts reflect assumptions on industrial electrification investment rates, precious metal price stability, and regulatory enforcement consistency that may shift with macroeconomic or policy developments. Stakeholders should weight assumptions against their own operating context and supply chain exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Pad-Mounted Transformer Market
Electrical Equipment
Laminated Busbar Market
Electrical Equipment
Global Circuit Breakers Market
Electrical Equipment
MCB and MCCB Market
Electrical Equipment
United States Busbar Market
Electrical Equipment
Magnetic Contactors Market
Electrical Equipment
Central Vacuum Receivers Market
Electrical Equipment
Global Copper Clad Steel (CCS) Wire Market
Electrical Equipment
Passover Humidifiers Market
Electrical Equipment
Hermetic Reciprocating Refrigerator Compressor Market
Electrical Equipment
High Voltage PTC Heater Market
Electrical Equipment
Middle East and Africa Electric Drives Market
Electrical Equipment
Capacitor Bank Market
Electrical Equipment
France DC Motors Market
Electrical Equipment
Electrical Measuring Instrument Market
Electrical Equipment
Saudi Arabia Industrial Electrical Components Market