
 Europe Circuit Breakers Market | 2026-2036
Europe Circuit Breakers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Circuit Breakers Market Analytics
Utility procurement patterns across European distribution network operators is recalibrating vendor selection criteria toward modular, digitally integrated switchgear. ABB leverages its installed base across Nordic and DACH grid operators to sustain long-term service contracts. Schneider Electric anchors its position through deep channel control in French and Benelux electrical wholesale markets. Siemens competes on R&D intensity in solid-state breaker architectures.
Circuit breakers are electromechanical switching devices engineered to interrupt fault currents automatically when overload or short-circuit conditions exceed rated thermal or magnetic thresholds, typically specified by breaking capacity in kiloamperes and voltage ratings up to 1,000V AC for low-voltage applications. Their primary industrial purpose centers on protecting conductors, motors, and transformers from thermal damage while enabling selective coordination across hierarchical power distribution networks. Miniature circuit breakers dominate residential and light commercial installations where cost sensitivity and DIN-rail mounting standardization create volume-driven margin pools. Air circuit breakers command premium positioning in heavy industrial and infrastructure applications requiring higher interrupting ratings and embedded communications for condition monitoring. Electronic trip units within hybrid technology configurations represent the fastest-growing segment as facilities managers prioritize adjustable protection curves and remote diagnostics over conventional thermal-magnetic mechanisms.
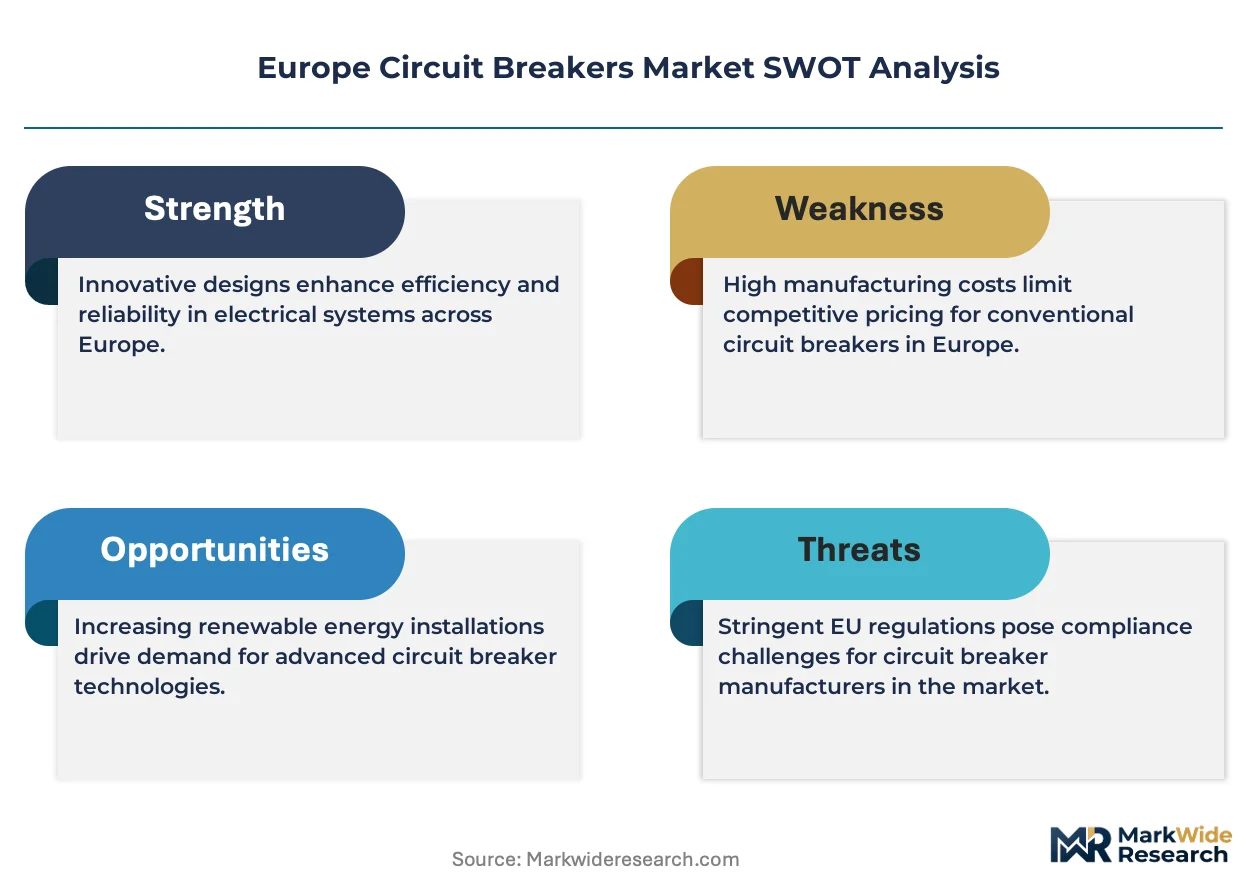
The EU Green Deal, F-Gas Regulation, and CE marking directives under the Low Voltage Directive 2014/35/EU collectively mandate higher energy efficiency standards and restricted substance compliance for electrical distribution equipment sold across member states. ECHA's REACH framework further constrains material choices in arc chutes and housing compounds, pushing manufacturers toward halogen-free thermoset formulations. Stakeholders must monitor how the CSRD disclosure requirements reshape capital allocation toward grid modernization versus incremental equipment replacement cycles.
Market Dynamics
Data center electrification across Germany, France, and the Netherlands is forcing wholesale replacement of thermal-magnetic breakers with solid-state and hybrid architectures capable of sub-millisecond fault isolation. This infrastructure wave concentrates procurement power among hyperscale operators who negotiate multi-year framework agreements directly with manufacturers.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of fluorinated greenhouse gases accelerates retrofit demand for SF6-free medium-voltage switchgear across German and French transmission networks.
- Data center buildouts:Hyperscale facilities in the Netherlands and Ireland require intelligent circuit protection with embedded power quality monitoring and digital twin compatibility.
- CE marking under LVD 2014/35/EU:Harmonized safety standards reduce cross-border certification costs for modular breaker platforms serving pan-European industrial accounts.
Market Restraints
- Copper and silver price volatility:Arc chute contacts and conductor assemblies face input cost swings that compress margin on standardized residential MCB lines.
- SF6 dependency in medium-voltage:European switchgear manufacturers remain tethered to gas-insulated technologies pending viable vacuum interrupter scale-up for 36kV+ ratings.
- REACH substance restrictions:ECHA's evolving candidate list threatens halogenated flame retardants in thermoset housings, forcing reformulation cycles that delay product launches.
Strategic Opportunities
- Polish industrial corridor:Underpenetrated heavy manufacturing zones around Katowice and Łódź present first-mover potential for digitally integrated air circuit breaker portfolios.
- CSRD-aligned disclosure services:Mandatory sustainability reporting creates attach-rate potential for lifecycle carbon tracking and circularity documentation bundled with breaker sales.
- Edge computing microgrids:Convergence of solid-state protection with lithium-ion storage integration opens specification channels outside traditional electrical wholesale.
Industry Challenges
- Power electronics engineering scarcity:Solid-state breaker development requires semiconductor thermal management expertise concentrated among automotive and rail suppliers, not incumbent electromechanical firms.
- Legacy SCADA integration:Brownfield industrial sites in Germany's Ruhr region operate proprietary communication protocols that resist seamless retrofit of IEC 61850-compliant intelligent electronic devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Circuit Breakers Market |
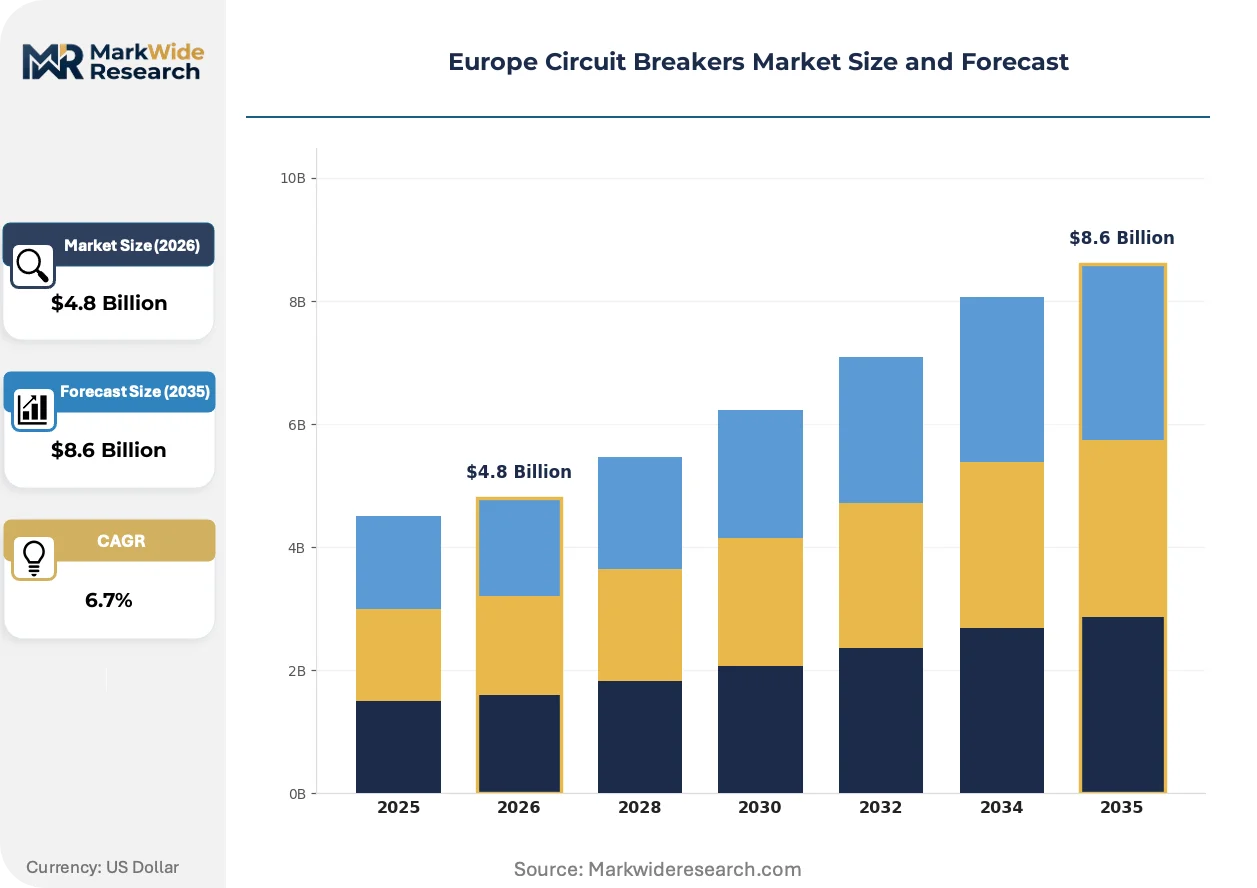
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Miniature Circuit Breakers, Residual Current Circuit Breakers, Air Circuit Breakers, Oil Circuit Breakers End User: Commercial, Industrial, Residential, Infrastructure Technology: Hydraulic Magnetic, Electronic, Hybrid, Thermal Application: Power Distribution, Motor Control, Lighting Systems, Renewable Energy |
| Companies Covered | ABB, Siemens, Schneider Electric, Eaton Corporation, Mitsubishi Electric Corporation, Alstom Holdings, Toshiba Corporation, Furukawa Electric, TE Connectivity, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Circuit Breakers Market Evolving Landscape
Solid-state interruption technologies are compressing the competitive set around semiconductor competence rather than conventional electromechanical craftsmanship. European manufacturers now face a capability pivot that favors power electronics over arc quenching physics.
Hybrid circuit breakers combining electromechanical isolation with electronic current limiting is overtaking pure thermal-magnetic designs in data center and semiconductor fabrication applications. Facility engineers at ASML, Infineon, and major colocation operators specify adjustable protection curves and remote diagnostics as baseline requirements. This specification shift compresses volume for standardized MCB platforms while expanding margin pools for configurable, software-defined protection.
The EU Green Deal's 2030 climate targets and F-Gas Regulation amendments are mandating SF6 phase-out timelines that accelerate vacuum and dry air insulation R&D. Medium-voltage switchgear procurement by TenneT, RTE, and National Grid ESO now explicitly weights global warming potential in technical evaluation criteria. Manufacturers with certified SF6-free portfolios capture disproportionate share in Nordic and Benelux tender processes where environmental procurement scoring carries statutory weight.
Direct manufacturer engagement with asset-owning utilities and hyperscale data center operators is displacing traditional electrical wholesale distribution for specification-grade products. Framework agreements with E.ON, Enel, and Equinix bypass distributor markup and capture lifecycle service revenue. France and Germany exhibit the most pronounced channel compression, where Schneider Electric and ABB field organizations maintain dedicated key account teams for top fifty electrical infrastructure spenders.
Europe Circuit Breakers Market Segmentation
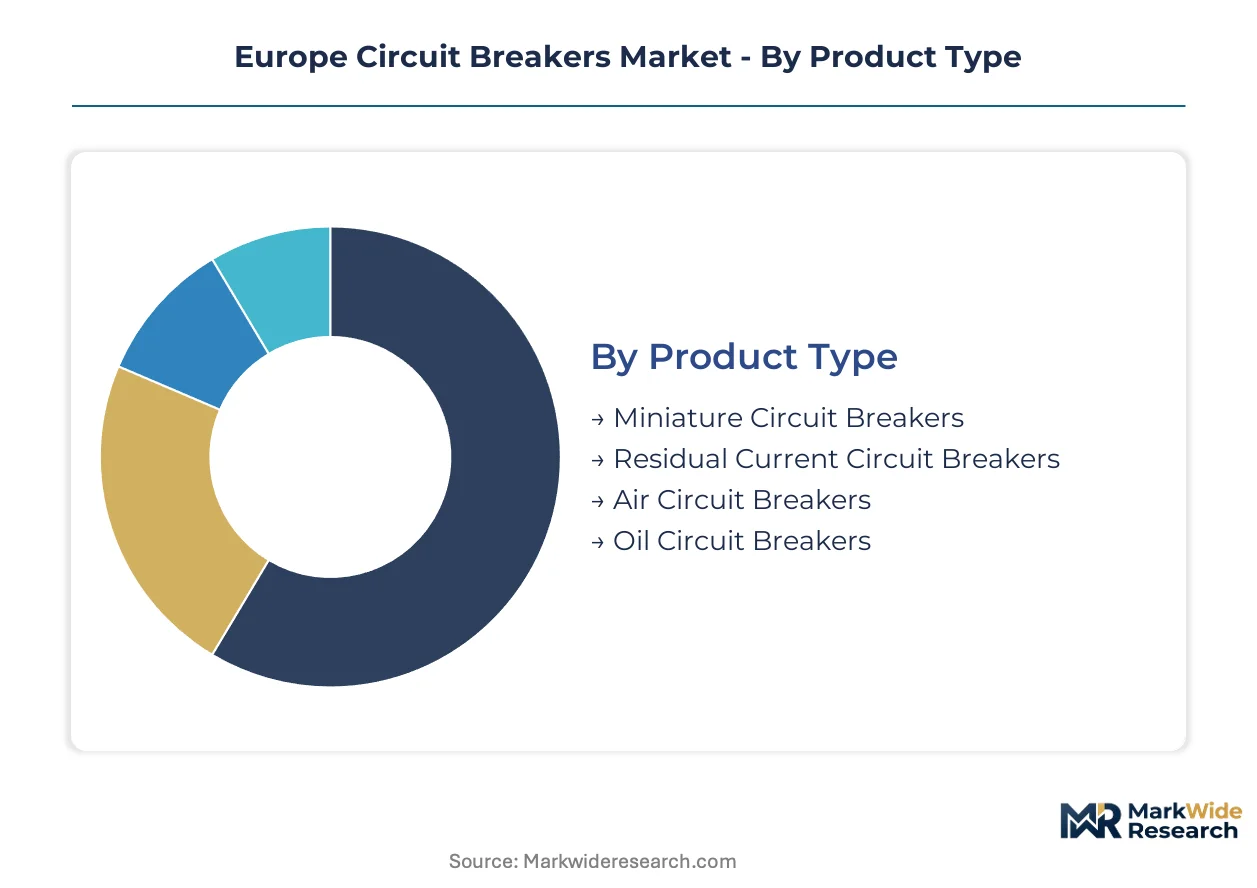
Circuit breaker procurement across Europe fragments along technical specifications, end-use requirements, and regulatory compliance tiers. Each segmentation dimension carries distinct certification burdens under the Low Voltage Directive 2014/35/EU and harmonized EN standards that shape vendor positioning and margin structures.
Product Type:
CE marking requirements vary sharply across breaker architectures, with air circuit breakers facing the most intensive conformity assessment procedures involving notified body intervention for higher interrupting capacities.
- Miniature Circuit Breakers:DIN-rail mounted devices rated up to 125A dominate residential and light commercial installations across Germany and France. Massive volume concentration in housing retrofit programs and new construction in Poland and Spain compresses margins while enforcing strict cost discipline on contact materials and housing compounds.
- Air Circuit Breakers:Draw-out frame designs rated 630A to 6300A protect heavy industrial busbars and infrastructure substations. Demand clusters in Germany's automotive manufacturing corridor and Netherlands data center campuses where adjustable electronic trip units and embedded communications are specification requirements.
- Residual Current Circuit Breakers:Combined overcurrent and earth leakage protection mandated by national wiring regulations in France and Belgium for residential final circuits.
- Oil Circuit Breakers:Legacy medium-voltage designs persisting in Eastern European utility fleets pending SF6-free replacement cycles under F-Gas Regulation timelines.
Miniature circuit breakers sit at the top of the volume ranking, with air circuit breakers climbing the fastest.
End User:
Customer procurement sophistication creates three distinct cost tiers, from price-sensitive residential distributors to lifecycle-focused industrial asset owners negotiating framework agreements.
- Industrial:Heavy manufacturing, chemical processing, and semiconductor fabrication facilities specify intelligent breakers with power quality monitoring and predictive maintenance capabilities. German automotive OEMs and ASML's Dutch lithography operations drive premium tier demand for solid-state and hybrid architectures.
- Infrastructure:Rail electrification, airport terminals, and healthcare facilities require certified selective coordination and high availability. French hospital construction programs and German ICE rail expansion create specification-grade procurement channels with extended warranty requirements.
- Commercial:Office buildings, retail chains, and hospitality properties balance first-cost sensitivity with energy efficiency compliance under national building codes.
- Residential:Single-family and multi-unit housing developments prioritize standardized MCB platforms with minimal differentiation beyond price and availability through electrical wholesale channels.
Industrial applications command the highest revenue per unit, with infrastructure posting the steepest expansion trajectory as EU Green Deal funding accelerates grid and transport electrification.
Technology:
Protection mechanism selection reflects a maturity gradient from established thermal-magnetic designs to emerging solid-state architectures requiring new engineering competencies.
- Hybrid:Electromechanical isolation paired with electronic current limiting dominates data center and semiconductor facility specifications. Netherlands hyperscale operators and Infineon's German fabs require sub-millisecond fault clearing and adjustable protection curves that thermal-magnetic mechanisms cannot deliver.
- Electronic:Microprocessor-based trip units with communication interfaces enable remote diagnostics and digital twin integration. French nuclear maintenance programs and German Industry 4.0 retrofits drive replacement demand for legacy thermal devices.
- Hydraulic Magnetic:Temperature-independent magnetic actuation serves marine, defense, and harsh environment applications with specialized certification requirements.
- Thermal:Bimetallic strip designs persist in cost-constrained residential and commercial segments where functional simplicity outweighs diagnostic capabilities.
Hybrid configurations are gaining share fastest among specification-grade applications, while thermal technology retains volume leadership in standardized residential markets.
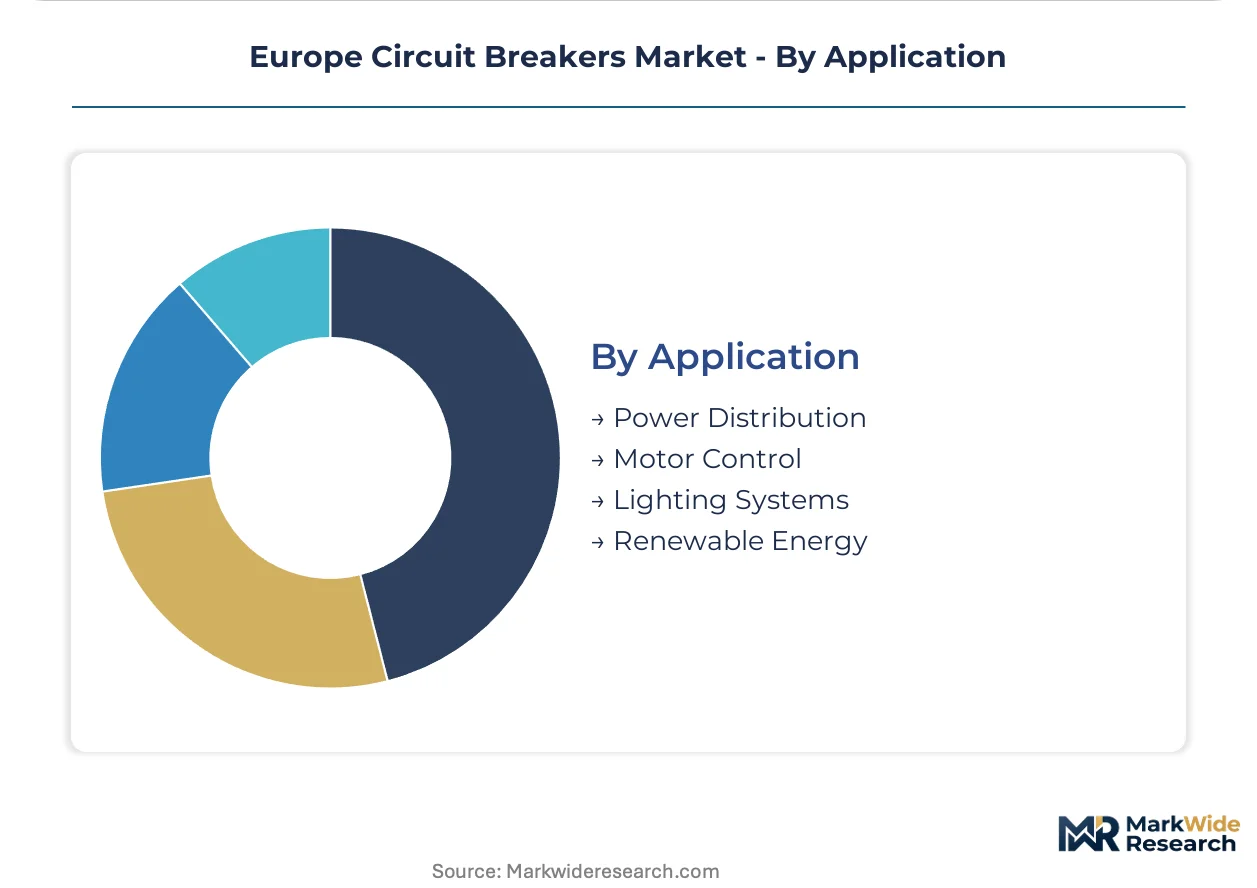
Application:
Functional deployment context determines breaker performance requirements, from routine load switching to fault isolation in generation-connected equipment.
- Power Distribution:Main and feeder protection across low-voltage switchboards and distribution panels. German industrial corridor investments and French grid modernization by RTE concentrate demand for intelligent air circuit breakers with embedded metering.
- Renewable Energy:Solar inverter integration, wind turbine switchgear, and battery storage connection points. Nordic offshore wind buildouts and Spanish solar park deployments require DC-rated and bidirectional protection capabilities.
- Motor Control:Motor protection circuit breakers and combination starters for industrial automation. Polish manufacturing expansion around Katowice drives volume for thermal-magnetic motor circuit protectors.
- Lighting Systems:Final circuit protection for commercial and residential luminaires, typically served by miniature circuit breakers with C-curve tripping characteristics.
Power distribution maintains the largest installed base, with renewable energy applications expanding most quickly as member states accelerate capacity deployment under REPowerEU targets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power electronics engineering talent concentrates in Germany's Ruhr industrial belt and the Netherlands' Brainport Eindhoven corridor, anchoring Europe's circuit breaker innovation base. French electromechanical expertise clusters around Lyon and Grenoble, while Nordic vacuum interrupter competence centers on Swedish and Finnish transmission technology hubs.
Germany
Automotive electrification and data center buildouts drive demand for intelligent air circuit breakers with embedded power quality monitoring. The EU Green Deal's 2030 climate targets accelerate SF6-free medium-voltage switchgear procurement by TenneT and distribution network operators. Industrial clusters in Bavaria and Baden-Württemberg specify hybrid protection architectures for semiconductor fabrication facilities.
France
Nuclear maintenance programs and hospital construction create specification-grade procurement channels for electronic trip units with remote diagnostic capabilities. CE marking under the Low Voltage Directive 2014/35/EU harmonizes safety standards for modular breaker platforms serving pan-European accounts. The Île-de-France region concentrates hyperscale data center investments requiring sub-millisecond fault isolation.
Netherlands
Hyperscale colocation operators negotiate multi-year framework agreements for solid-state and hybrid circuit protection with digital twin compatibility. F-Gas Regulation amendments mandate vacuum and dry air insulation R&D timelines for transmission infrastructure. The Eindhoven-Brainport corridor anchors power electronics engineering scarcity solutions for semiconductor thermal management.
Poland
Heavy manufacturing expansion around Katowice and Łódź presents first-mover potential for digitally integrated air circuit breaker portfolios. REACH substance restrictions constrain halogenated flame retardants in thermoset housings, forcing reformulation cycles. The country's underpenetrated industrial zones attract direct manufacturer engagement bypassing traditional electrical wholesale channels.
Spain
Solar park deployments under REPowerEU targets require DC-rated and bidirectional protection capabilities for renewable energy integration. Copper and silver price volatility compress margins on standardized residential MCB lines serving housing retrofit programs. Andalusian and Catalan industrial zones drive volume for thermal-magnetic motor circuit protectors in manufacturing automation.
Europe Circuit Breakers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across electromechanical and power electronics competence domains. The vendor base organizes around three strategic archetypes: integrated industrial technology groups with long-term utility service contracts, electrical distribution specialists with deep wholesale channel control, and component suppliers pivoting toward semiconductor-based interruption. Dominant competitive moves include direct manufacturer engagement with hyperscale operators and R&D partnerships bridging electromechanical craftsmanship with power electronics engineering.
Among the integrated industrial technology groups, ABB leverages its installed base across Nordic and DACH grid operators, while Siemens occupies a position anchored in solid-state breaker architecture development. Schneider Electric exemplifies the electrical distribution specialist archetype through channel control in French and Benelux wholesale markets. These three represent the competitive anchors around which European procurement patterns recalibrate toward modular, digitally integrated switchgear specifications.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| Schneider Electric |
| Eaton Corporation |
| Mitsubishi Electric Corporation |
| Alstom Holdings |
| Toshiba Corporation |
| Furukawa Electric |
| TE Connectivity |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between SF6-free vacuum interrupters and legacy gas-insulated switchgear manifests in both procurement premiums and supplier qualification timelines across German and French transmission networks. Buyers negotiating framework agreements with TenneT and RTE face extended vendor onboarding for medium-voltage portfolios, while standardized MCB lines compete on spot copper and silver pricing through electrical wholesale channels in Poland and Spain.
Pricing Analysis
Capacity additions in Poland and Spain are reshaping price floors for DIN-rail mounted MCBs serving residential retrofit programs. Three-tier pricing structure across intelligent air circuit breakers, hybrid electronic units, and thermal-magnetic commodity lines differentiates by embedded diagnostic capability and CE marking tier. Cost compression in standardized residential segments intensifies because copper contact material volatility feeds directly into manufacturer margin structures. Data center operators in the Netherlands exhibit the lowest price sensitivity, prioritizing sub-millisecond fault isolation over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for solid-state protection architectures, bypassing traditional electrical wholesale markup. Manufacturing concentration in Germany, France, and the Netherlands feeds from silver contact suppliers in Nordic mining jurisdictions and halogen-free thermoset compounders in Benelux chemical corridors. Single-source vulnerability in semiconductor thermal management components for solid-state breaker development threatens scale-up timelines. Distribution runs through manufacturer field organizations for specification-grade products and regional distributors for commodity MCB volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by data center procurement shifts toward digital twin-compatible protection with embedded power quality monitoring.
For Market Incumbents: To counter power electronics engineering scarcity concentrated in automotive and rail supplier pools, ABB and Siemens should deepen captive semiconductor thermal management capabilities through targeted hiring in Eindhoven-Brainport corridor. Channel control investments in French and Benelux electrical wholesale networks defend service contract attach rates against direct manufacturer engagement trends. For New Entrants and Emerging Players: The price-point gap between premium hybrid architectures and economy thermal-magnetic lines opens specification channels in Poland's underpenetrated Katowice-Łódź industrial corridor. First-mover positioning in digitally integrated air circuit breakers for heavy manufacturing automation bypasses entrenched distributor relationships. Direct sales teams targeting Polish plant engineers with CSRD-aligned lifecycle documentation bundles accelerate reference customer acquisition. For Investors and Strategic Acquirers: Asymmetric upside sits with semiconductor competence acquisitions bridging electromechanical craftsmanship gaps. Long-term viability over the coming decade hinges on vacuum interrupter scale-up for 36kV+ SF6-free ratings. Watch Nordic tender processes where environmental procurement scoring carries statutory weight as the inflection indicator for portfolio premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| SF6-Free Vacuum Interrupter Scale-Up | TenneT and RTE procurement criteria now weight global warming potential in technical evaluation scoring. |
| Power Electronics Engineering Acquisition | Semiconductor thermal management talent concentrated in Brainport Eindhoven anchors solid-state breaker development. |
| CSRD-Aligned Lifecycle Services Bundling | Mandatory sustainability reporting creates attach-rate potential for carbon tracking documentation with breaker sales. |
| Direct Hyperscale Framework Agreements | Equinix and colocation operators negotiate multi-year contracts bypassing distributor markup for intelligent protection. |
| Polish Industrial Corridor Channel Bypass | Direct manufacturer engagement in Katowice-Łódź manufacturing zones displaces traditional wholesale distribution. |
Research Methodology
Coverage spans Germany, France, the Netherlands, Poland, and Spain, with primary inputs from each market cluster combining interviews with utility planning officers, data center infrastructure directors, OEM procurement teams, and aftermarket service heads with secondary validation. Secondary sources include TenneT and RTE procurement disclosures, ECHA REACH substance restriction updates, customs data on copper and silver trade flows, and harmonized EN standard certification records. Bottom-up segment sizing triangulates against top-down macroeconomic anchors across the analysis window.
Rate-of-change decomposition separates volume growth from value mix-shift across product type, end user, technology, and application dimensions. CAGRs derive from modeled segment trajectories incorporating REPowerEU capacity deployment timelines, F-Gas Regulation phase-out schedules, and data center power density projections. Industry-specific forecast inputs include hyperscale operator capex disclosures and Nordic-Benelux environmental procurement scoring weights.
Caveats apply where semiconductor supply constraints or ECHA substance list expansions could materially shift the outlook for solid-state breaker commercialization. Forecasts reflect assumptions about vacuum interrupter manufacturing scale-up and power electronics engineering labor market elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Copper and Copper Alloy Busbars Market
Electrical Equipment
Middle East and Africa Electric Drives Market
Electrical Equipment
Electric Enclosure Market
Electrical Equipment
Portable Fan Market
Electrical Equipment
Porcelain Insulators Market
Electrical Equipment
Global Cooling Fan Market
Electrical Equipment
GCC Ceiling Fan Market
Electrical Equipment
Electric Control Panel Market
Electrical Equipment
High Voltage Electric Capacitor Market
Electrical Equipment
Medium Voltage Circuit Breakers Market
Electrical Equipment
Portable Misting Fans Market
Electrical Equipment
Earth Leakage Circuit Breakers Market
Electrical Equipment
Busbar Systems Market
Electrical Equipment
High Efficiency Low Voltage Aluminum Motors Market
Electrical Equipment
Europe Electric Insulator Market
Electrical Equipment
Motor Control Centers (MMC) Market