
 North America Low Voltage Induction Motors Market | 2026-2036
North America Low Voltage Induction Motors Market Size, Share, and Industry Trends Forecast 2026-2036
North America Low Voltage Induction Motors Market Insights
Multi-source procurement from Asian motor suppliers is shifting toward qualified North American production partners as OEMs seek shorter lead times and tariff resilience. ABB Ltd leverages its regional manufacturing footprint to anchor utility-scale pump applications across the Midwest. Siemens AG competes through integrated drive-motor packages that simplify commissioning for water treatment operators. WEG S.A. differentiates its offering with aggressive channel control in the Mexican industrial belt.
North America low voltage induction motors are asynchronous AC machines typically rated below 1,000 volts, constructed with cast iron or aluminum frames, copper or aluminum rotor bars, and insulation systems rated for Class F or Class H thermal endurance, designed to convert electrical energy into mechanical rotation for continuous-duty industrial processes. Three phase units dominate heavy manufacturing loads where constant torque and high starting current tolerance are required, while variable frequency drive compatibility now determines specification priority over raw efficiency metrics in most retrofit scenarios. HVAC systems represent a mature but volume-stable application segment, whereas compressor duty cycles are pushing demand toward multi speed configurations that reduce mechanical throttling losses.
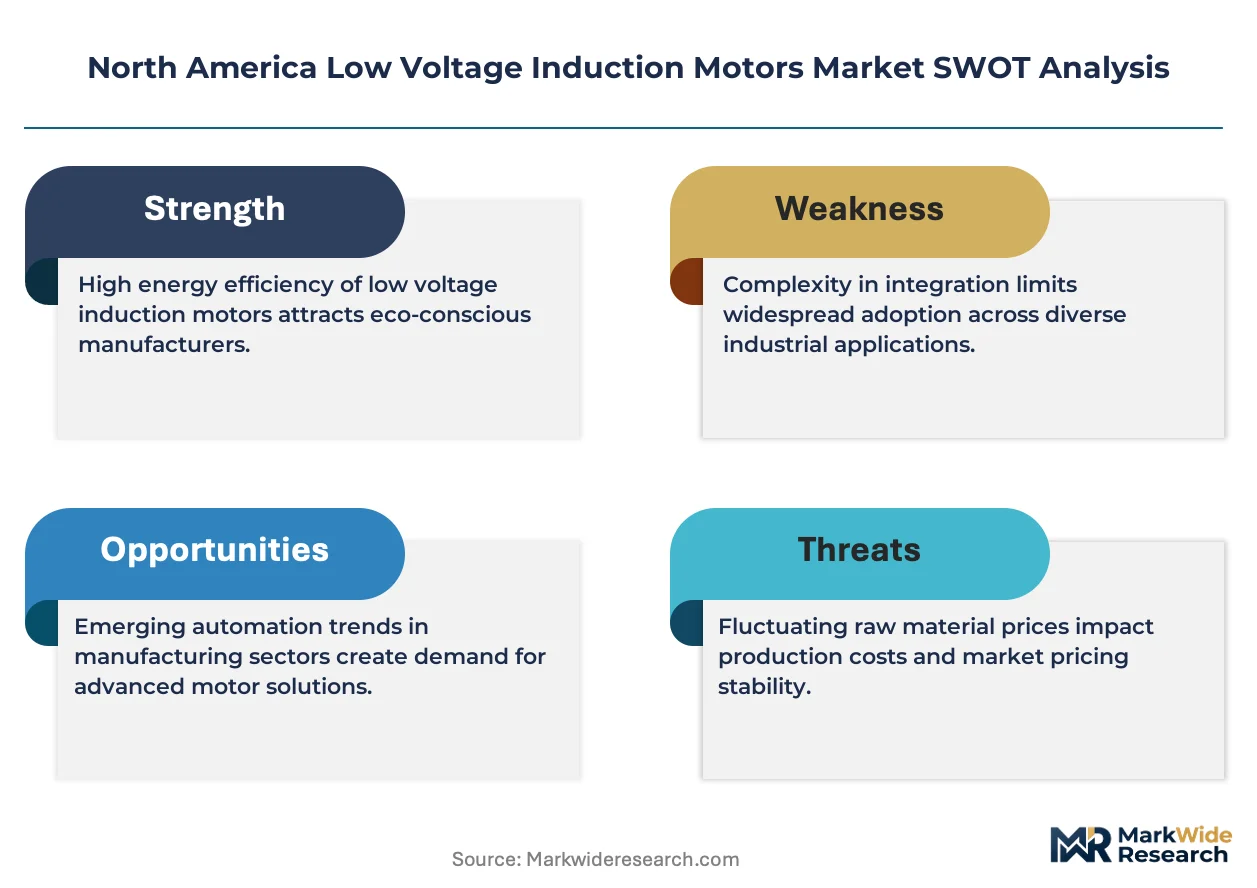
EPA efficiency mandates under the Energy Policy and Conservation Act and NEMA MG 1 standards enforced by the Department of Energy compel manufacturers to redesign core laminations and magnet wire specifications, effectively raising minimum performance floors and disqualifying import models that lack certified test data. CSA Group certification requirements in Canada add a parallel compliance layer that favors suppliers with dual-accredited laboratories in Ontario or Illinois. Stakeholders must monitor how impending Department of Energy rulemakings on integral horsepower motors redefine the boundary between standard and premium efficiency tiers, as this classification will determine which installed bases qualify for utility rebate programs and which face accelerated replacement timelines.
Market Dynamics
Variable frequency drive integration is compressing fixed-speed motor specifications across North American industrial retrofits, forcing manufacturers to redesign thermal management systems and bearing assemblies for inverter-fed duty cycles rather than sinusoidal grid power.
Growth Catalysts
- EPA effluent mandates:Water treatment facilities across the United States are expanding aeration and pumping capacity to meet stricter discharge standards, directly expanding motor fleet procurement timelines.
- Automotive electrification spillover:Battery gigafactory construction in Michigan and Ohio is pulling premium-efficiency motor demand for coating lines and environmental systems.
- Copper rotor bar technology:Die-cast copper rotor designs are penetrating food processing applications where NEMA Premium efficiency thresholds now gate utility rebate eligibility.
Market Restraints
- Aluminum price volatility:Cast aluminum frame production faces input cost instability that compresses margin buffers for standard-efficiency product lines.
- Asian supply concentration:Stator lamination steel and magnet wire supply chains remain concentrated in East Asian rolling mills, exposing North American assemblers to tariff and logistics risk.
- NEMA MG 1 revision friction:Pending Department of Energy rulemakings on integral horsepower classifications create specification uncertainty that freezes capital planning cycles.
Strategic Opportunities
- Mexican industrial belt expansion:Automotive tier suppliers in Querétaro and Guanajuato represent underpenetrated demand for IE3-equivalent motors with CSA dual-certification.
- Heat pump manufacturing surge:Federal IRA production credits for domestic HVAC equipment are accelerating compressor motor demand from Texas and Tennessee assembly plants.
- Digital twin commissioning:Convergence of motor-mounted vibration sensors with cloud-based predictive maintenance platforms opens service revenue streams beyond hardware margins.
Industry Challenges
- Magnet wire winding automation:Shortages of technicians capable of programming robotic coil insertion equipment constrain output scaling at Midwest manufacturing facilities.
- CSA-NEMA dual certification timelines:Parallel laboratory testing requirements in Ontario and Illinois extend product launch cycles by four to six months for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Low Voltage Induction Motors Market |
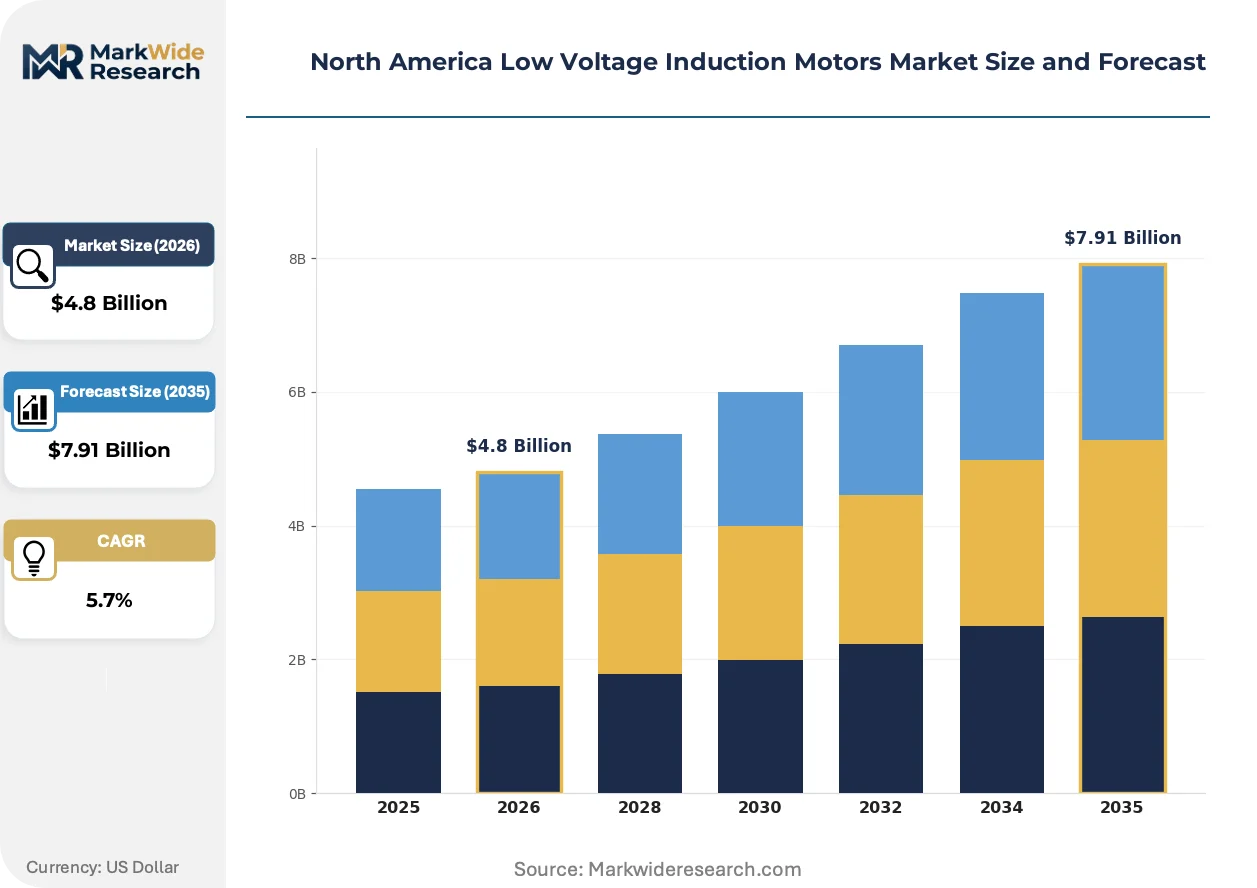
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Phase, Three Phase, Multi Speed, Dual Voltage Application: HVAC Systems, Pumps, Conveyors, Compressors End User: Manufacturing, HVAC, Water Treatment, Mining Technology: Direct On-Line, Variable Frequency Drive, Soft Starter, Servo |
| Companies Covered | Nidec Corporation, ABB Ltd, Siemens AG, Toshiba Industrial Corporation, Regal Rexnord Corporation, Rockwell Automation, Inc., WEG S.A., TECO Electric and Machinery Co Ltd, Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Low Voltage Induction Motors Market Trends and Innovations
Permanent magnet-assisted synchronous reluctance motor designs are penetrating North American industrial specifications, compressing the efficiency gap between induction and servo technologies while preserving inverter compatibility.
Copper rotor die-casting is absorbing thermal losses that previously limited NEMA Premium efficiency achievement in smaller frame sizes. Food processors in Wisconsin and Pennsylvania are specifying copper-bar units for washdown-duty applications. This metallurgical shift is absorbing market share from aluminum-rotor alternatives in continuous-duty process industries.
The Department of Energy's pending integral horsepower motor rulemaking is tightening minimum efficiency thresholds under Energy Policy and Conservation Act authority. Canadian operators face parallel CSA C390 test protocol updates that disqualify uncertified import models. Water treatment utilities in the Great Lakes corridor are front-loading replacement schedules to lock in current rebate qualification windows.
Compressed specification cycles are fragmenting buyer-seller relationships across the Midwest manufacturing belt. Automotive and metals processors are unbundling motor procurement from turnkey drive packages, forcing distributors to stock discrete SKUs with verified VFD compatibility. This pattern is most pronounced in Michigan and Ohio, where plant engineering teams now mandate witnessed dynamometer testing before volume commitments.
North America Low Voltage Induction Motors Market Segmentation
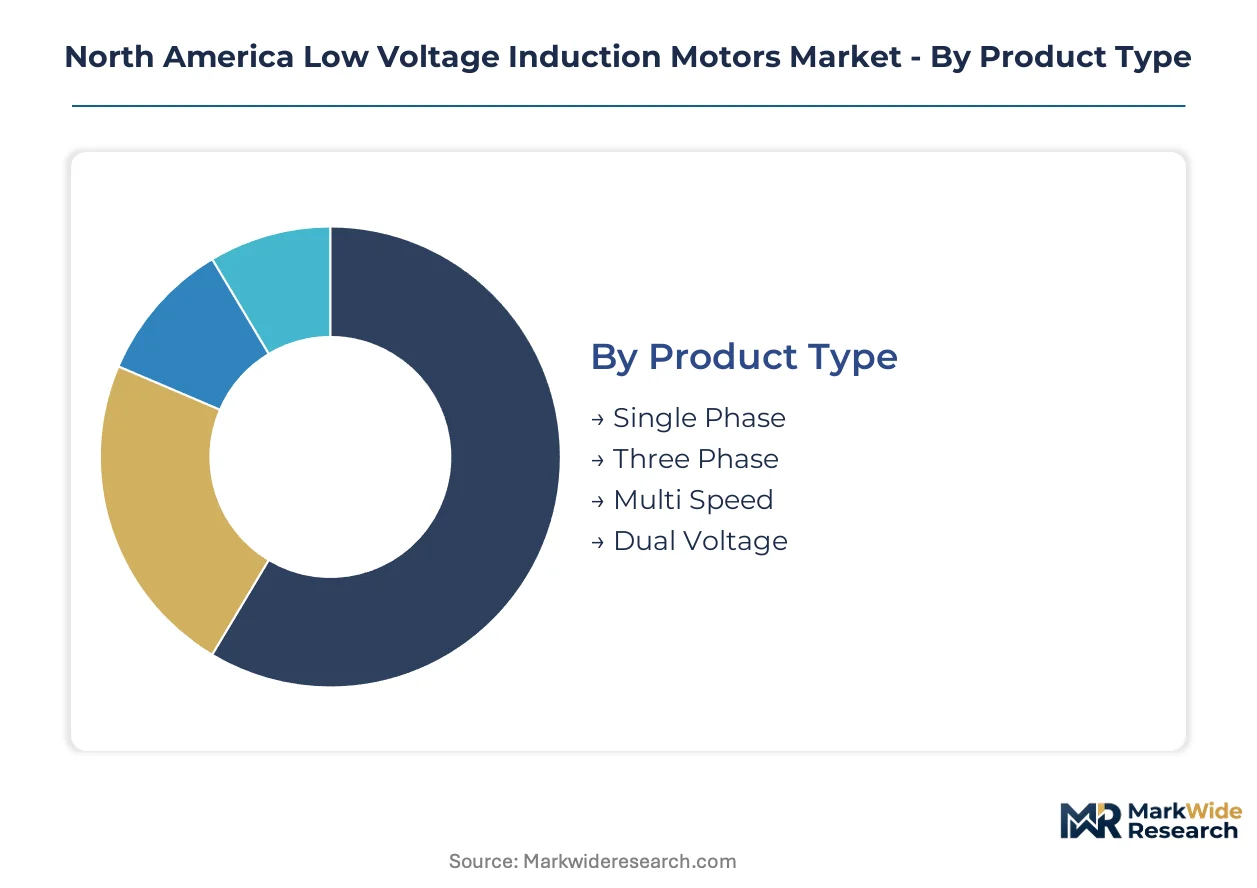
Segmentation in the North America low voltage induction motors market reveals how certification requirements, thermal management specifications, and duty cycle profiles fragment procurement decisions across industrial verticals. Understanding these divides exposes where specification power concentrates and which technology transitions threaten incumbent positions.
Product Type:
NEMA MG 1 compliance burdens fall unevenly across frame constructions, with premium efficiency tiers demanding witnessed dynamometer testing that smaller manufacturers cannot absorb.
- Three Phase:These asynchronous machines handle constant torque loads across 208-600V ranges with copper or aluminum rotor bars and Class F insulation systems. Demand clusters in Michigan and Ohio automotive battery gigafactories where NEMA Premium efficiency gates utility rebate eligibility under Department of Energy mandates.
- Single Phase:Fractional horsepower units rated below 5 HP serve residential and light commercial compressor duty with split-phase or capacitor-start winding configurations. California and Texas HVAC OEMs are specifying these for heat pump production lines qualifying for IRA domestic manufacturing credits.
- Multi Speed:Dahlander or pole-changing configurations reduce mechanical throttling losses in variable air volume systems. Food processors in Wisconsin specify washdown-duty variants.
- Dual Voltage:Reconfigurable stator windings accommodate 230/460V installations without inventory duplication. Midwest distributors stock these for mixed-voltage plant retrofits.
Three Phase sits at the top of the volume ranking, with Multi Speed climbing the fastest.
Application:
Application selection determines bearing assembly specifications, with inverter-fed duty cycles forcing thermal management redesigns across pump and compressor segments.
- Pumps:Centrifugal and positive displacement pump motors face continuous-duty thermal profiles that stress insulation systems in water treatment aeration basins. Great Lakes utilities are expanding fleets to meet EPA effluent discharge standards, pulling IE3-equivalent units with CSA dual-certification.
- HVAC Systems:Fan and blower duty motors operate at reduced load factors that favor VFD compatibility over peak efficiency metrics. Tennessee and Texas assembly plants are scaling output for heat pump manufacturing surge.
- Compressors:Hermetic and semi-hermetic motor-compressor packages demand locked-rotor torque tolerance for refrigerant startup loads. Screw compressor OEMs in Pennsylvania specify copper rotor bars for continuous process duty.
- Conveyors:Material handling motors face frequent start-stop cycles that accelerate bearing wear. Automotive tier suppliers in Querétaro specify ruggedized frame designs.
Pumps dominate procurement volume, while Compressors gain share fastest on refrigeration demand.
End User:
End user concentration shapes channel control patterns, with water treatment utilities unbundling motor procurement from turnkey drive packages.
- Manufacturing:Automotive, metals, and food processing plants across the Great Lakes corridor modernize aging motor infrastructure with witnessed dynamometer testing requirements. Michigan and Ohio battery coating lines pull premium-efficiency demand.
- Water Treatment:Municipal and industrial effluent facilities face EPA discharge mandates that expand aeration and pumping capacity. Canadian operators parallel CSA C390 protocol updates that disqualify uncertified imports.
- HVAC:Commercial building retrofits and residential heat pump installations create stable volume demand. Federal IRA production credits accelerate domestic sourcing requirements.
- Mining:Harsh environment duty with explosion-proof enclosures faces procurement cycles tied to commodity price volatility. Mexican industrial belt expansion lags this segment.
Manufacturing leads absolute volume, with Water Treatment expanding most quickly on regulatory deadlines.
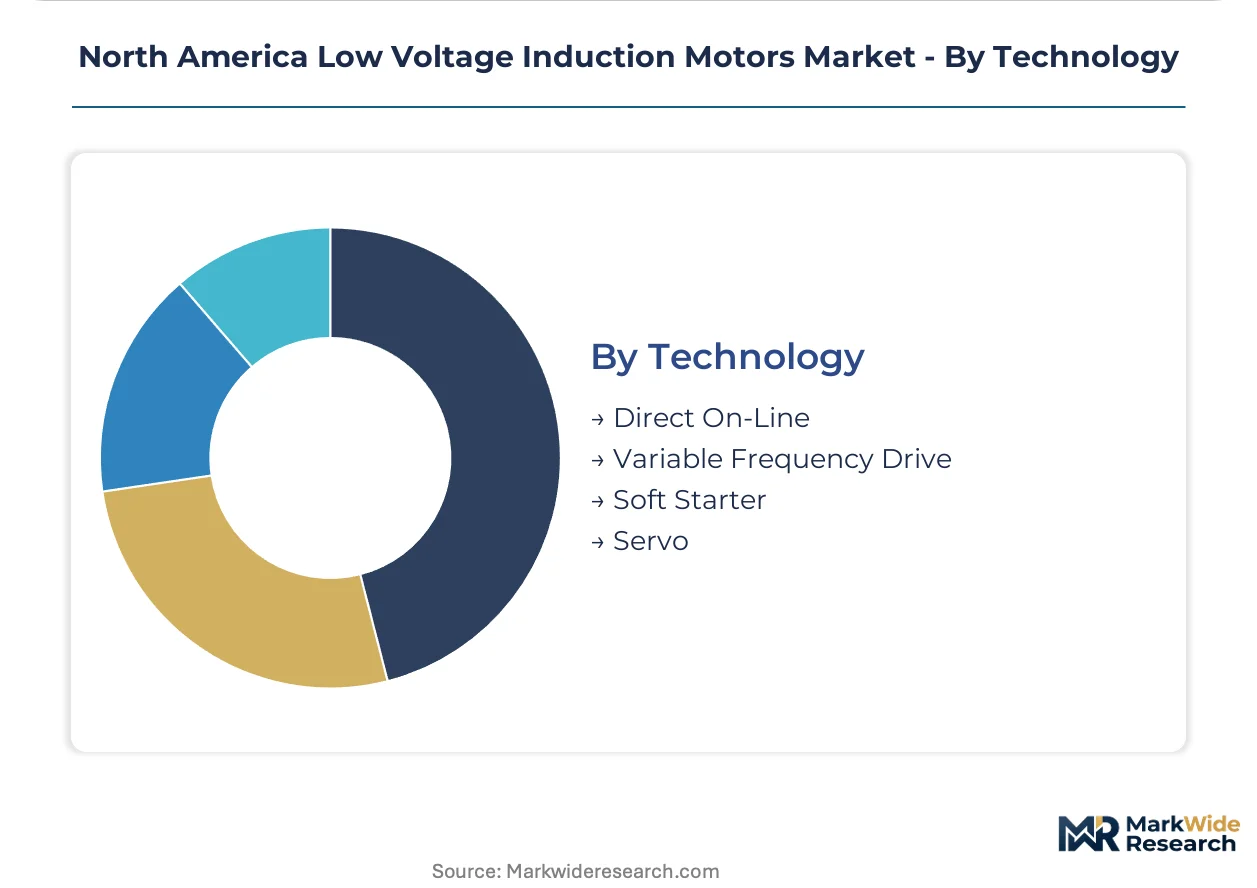
Technology:
Technology selection now determines specification priority, with VFD integration compressing fixed-speed motor designs across North American retrofits.
- Variable Frequency Drive:Inverter-fed motors with reinforced insulation systems and bearing current mitigation handle non-sinusoidal waveforms. HVAC retrofits across the United States displace fixed-speed installations as commissioning teams prioritize integrated drive-motor packages.
- Direct On-Line:Across-the-line starting remains cost-effective for low-duty-cycle applications with minimal speed variation requirements. Standard-efficiency product lines face aluminum price volatility compression.
- Soft Starter:Reduced-voltage starting limits mechanical and electrical stress on conveyor and pump systems. Mining applications specify these for high-inertia loads.
- Servo:Permanent magnet and synchronous reluctance designs penetrate precision positioning applications. Food packaging OEMs in Pennsylvania adopt these for washdown environments.
Variable Frequency Drive commands the largest installed base, with Servo gaining traction fastest in precision applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as motor assemblers migrate toward jurisdictions with aligned NEMA-CSA certification regimes, compressing cross-border compliance costs while EPA and Department of Energy mandates tighten performance floors.
United States
Great Lakes manufacturing corridors in Michigan and Ohio are absorbing premium-efficiency motor demand from battery gigafactory construction. EPA effluent mandates under the Clean Water Act are expanding water treatment aeration capacity across Midwestern utilities. Department of Energy rulemakings on integral horsepower classifications are freezing capital planning cycles pending NEMA MG 1 threshold clarity.
Canada
CSA C390 protocol updates are disqualifying uncertified import models from municipal procurement tenders. Ontario-based water treatment operators are front-loading replacement schedules to lock in current rebate qualification windows. Toronto and Hamilton industrial clusters are specifying dual-certified units for cross-border supply chain resilience.
Mexico
Automotive tier suppliers in Querétaro and Guanajuato are pulling IE3-equivalent motor demand for conveyor and environmental systems. Mexican industrial belt expansion is creating underpenetrated demand for CSA-NEMA dual-certified products. Monterrey manufacturing corridors are modernizing aging motor infrastructure amid nearshoring acceleration.
North America Low Voltage Induction Motors Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue integrated drive-motor packaging and predictive maintenance service layers. The vendor base stratifies across three tiers: multinational electromechanical conglomerates with captive distribution, regional specialists with channel control in specific industrial belts, and Asian-origin suppliers competing on lead time compression. Dominant competitive moves include backward integration into stator lamination steel sourcing and technology licensing partnerships for copper rotor die-casting processes.
Within the multinational tier, ABB Ltd and Siemens AG exemplify divergent strategic positioning. ABB Ltd anchors utility-scale pump applications through regional manufacturing footprint leverage. Siemens AG occupies a position emphasizing integrated drive-motor packages that simplify commissioning protocols. WEG S.A. represents the regional specialist archetype with concentrated channel control in the Mexican industrial belt.
| Leading Market Players |
|---|
| Nidec Corporation |
| ABB Ltd |
| Siemens AG |
| Toshiba Industrial Corporation |
| Regal Rexnord Corporation |
| Rockwell Automation, Inc. |
| WEG S.A. |
| TECO Electric and Machinery Co Ltd |
| Schneider Electric SE |
| Others |
Pricing and Supply Chain Analysis
NEMA Premium versus standard-efficiency certification tiers create divergent margin architectures that reshape both procurement budgets and supplier qualification pathways across the Great Lakes manufacturing corridor. This bifurcation concentrates pricing power with dual-certified manufacturers while compressing margins for import-dependent distributors facing parallel CSA and Department of Energy compliance costs.
Pricing Analysis
Distributor margins absorb the steepest compression as OEM procurement teams unbundle motor specifications from integrated drive packages and demand witnessed dynamometer testing. Three-tier pricing structure across premium, standard, and economy levels aligns with IE3 efficiency thresholds and CSA-NEMA dual certification status. Pricing pressure stems from aluminum frame input cost volatility and tariff exposure on Asian stator lamination steel. Water treatment utilities demonstrate lowest price sensitivity due to locked-in rebate qualification windows, while automotive tier suppliers in Mexico negotiate aggressively on volume scale.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Michigan and Ohio battery gigafactories, while authorized distributors serve fragmented Midwest plant retrofit requirements. Manufacturing concentration spans Mexico for automotive belt proximity, the United States for Department of Energy compliance proximity, and Canada for CSA certification efficiency. Raw material dependencies center on East Asian stator lamination steel, copper magnet wire, and aluminum frame castings. Single-source vulnerability in lamination steel rolling mills exposes North American assemblers to logistics chokepoint risk. Distribution runs through manufacturer-direct relationships for utility-scale projects and regional distributor networks for maintenance-replacement-operations demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America low voltage induction motors market represents a late-cycle quality story as EPA effluent mandates and IRA production credits shift procurement specifications toward premium-efficiency tiers with verified VFD compatibility.
For Market Incumbents: To counter specification unbundling by automotive and metals processors, anchor utility-scale pump relationships through witnessed testing protocols and backward integration into copper rotor die-casting capacity. Deepen channel control in the Mexican industrial belt via CSA-NEMA dual-certified inventory positioning ahead of nearshoring acceleration. For New Entrants and Emerging Players: Launch via digital twin commissioning service layers that attach predictive maintenance subscriptions to hardware sales, bypassing capital-intensive manufacturing scale requirements. Target food processing applications in Wisconsin and Pennsylvania where copper rotor washdown-duty specifications remain underpenetrated and utility rebate eligibility gates procurement decisions. For Investors and Strategic Acquirers: Consolidation pressure builds where CSA-NEMA dual certification timelines stretch product launch cycles and fragment mid-tier supplier viability. Long-term positioning favors targets with captive Ontario or Illinois laboratory accreditation and established VFD integration partnerships. Monitor Department of Energy integral horsepower rulemaking clarity as the signal for accelerated replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Copper Rotor Die-Casting Scale-Up | Captures NEMA Premium efficiency thresholds that gate utility rebate eligibility in water treatment applications. |
| CSA-NEMA Dual Certification Investment | Compresses cross-border product launch timelines and disqualifies uncertified import competitors from municipal tenders. |
| VFD Integration Partnership | Aligns with HVAC retrofit specifications that prioritize integrated drive-motor packages over discrete hardware procurement. |
| Predictive Maintenance Platform Development | Opens recurring service revenue streams beyond hardware margins in food processing and automotive verticals. |
| Mexican Industrial Belt Channel Expansion | Positions inventory for automotive tier supplier demand in Querétaro and Guanajuato amid nearshoring acceleration. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with plant engineers, OEM procurement teams, aftermarket service heads, and water treatment utility maintenance directors with secondary validation against Department of Energy rulemaking dockets, EPA effluent discharge databases, CSA C390 certification records, and customs trade data on stator lamination steel imports. Bottom-up motor fleet expansion estimates from Great Lakes utilities and top-down manufacturing capacity analysis triangulated volume projections.
Historical reference periods anchored demand modeling to pre-IRA capital planning cycles and post-EPA mandate compliance windows across the projection horizon. Segmentation dimensions included efficiency tier, frame construction, rotor bar metallurgy, voltage reconfigurability, and VFD compatibility status. CAGRs derived from utility rebate program expiration schedules, battery gigafactory construction pipelines, and heat pump manufacturing capacity announcements. Forecast inputs incorporated aluminum price volatility indices and tariff exposure scenarios on Asian magnet wire supply.
Forecast precision tightens around the base case; tail outcomes carry wider variance under pending Department of Energy integral horsepower reclassification scenarios and abrupt CSA protocol update timing. Motor fleet replacement schedules reflect assumptions about rebate qualification window continuity and NEMA MG 1 threshold clarity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Europe Electric Insulator Market
Electrical Equipment
India Electrical Enclosures Market
Electrical Equipment
Global Sealed DC Contactor Market
Electrical Equipment
North America Electrical Bushing Market
Electrical Equipment
Vacuum Interrupter Market
Electrical Equipment
Low Voltage Circuit Breakers Market
Electrical Equipment
Pad-Mounted Transformer Market
Electrical Equipment
Air Circuit Breaker Market
Electrical Equipment
Vacuum Contactor Market
Electrical Equipment
Global Electric Plugs and Sockets Market
Electrical Equipment
China DC Motor Market
Electrical Equipment
Europe Circuit Breakers Market
Electrical Equipment
Alligator Clips Market
Electrical Equipment
Global Copper Clad Steel (CCS) Wire Market
Electrical Equipment
Motor Protection Devices Market
Electrical Equipment
Electric Enclosure Market