
 High Voltage PTC Heater Market | 2026-2036
High Voltage PTC Heater Market Size, Share, and Industry Trends Forecast 2026-2036
High Voltage PTC Heater Market Foresight
The EU F-Gas Regulation is broadening the cost-of-entry calculus for thermal management suppliers across Europe by restricting fluorinated greenhouse gases in mobile air conditioning and heating systems. MAHLE GmbH leverages its integrated thermal management portfolio to capture value from electrification transitions in passenger and commercial vehicle segments. BorgWarner Inc. anchors its position through in-house production of power electronics and heating modules that pair with high voltage architectures. Eberspächer competes by extending its traditional combustion heater expertise into electric PTC systems for hybrid and battery-electric platforms.
A high voltage PTC heater utilizes positive temperature coefficient ceramic elements—typically barium titanate-based compositions—that self-regulate resistance as temperature rises, enabling safe operation at 400-800V without external control circuitry. These devices convert electrical energy directly into heat for cabin comfort, battery preconditioning, and powertrain thermal stability in electrified vehicles. Liquid PTC heaters command the deepest margin pools due to their critical role in battery thermal management for premium electric vehicles, while air PTC systems dominate unit volumes across mass-market passenger car segments. High power and ultra high power ratings are capturing the fastest growth trajectory as 800V architectures proliferate and cold-climate performance requirements intensify.
The EPA tailpipe emissions framework and NHTSA fuel economy standards in the United States are compressing allowable auxiliary loads from combustion engines, forcing OEMs to source electrified heating solutions. EMA's MDR and REACH compliance in Europe adds material traceability and substance restriction layers that shape ceramic element sourcing and module assembly location decisions. China's GB standards and MIIT new energy vehicle mandates create a dual certification burden for suppliers serving domestic OEMs with export ambitions. Stakeholders must monitor how 800V platform commitments from major automotive groups reshape power rating specifications and supplier qualification timelines across multiple geographies simultaneously.
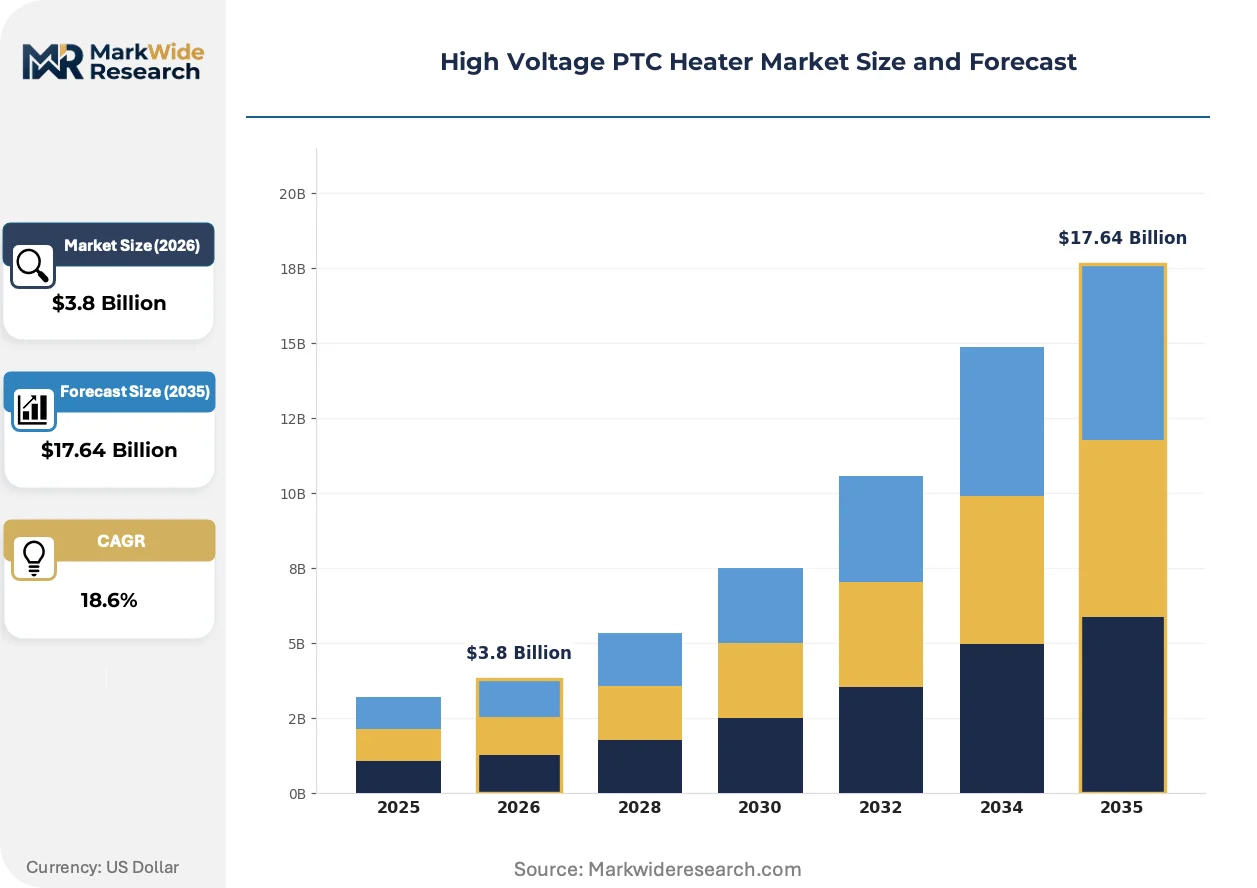
Market Dynamics
The 800V platform transition across premium electric vehicle architectures is compressing supplier qualification timelines and redrawing competitive boundaries in thermal management procurement.
Growth Catalysts
- MIIT new energy vehicle mandates:China's production quotas for battery-electric platforms are pulling high voltage PTC capacity into domestic supply chains at scale.
- Cold-climate battery preconditioning:Nordic and Canadian EV adoption is creating specification pull for ultra-high-power liquid heating modules.
- Barium titanate ceramic maturation:Domestic Chinese material processing advances are reducing element cost curves for 400-800V applications.
Market Restraints
- Raw material concentration:Processed barium titanate supply clusters in East Asian ceramic foundries, exposing buyers to single-region disruption risk.
- EU F-Gas Regulation compliance:Transition costs for fluorinated gas elimination are elevating module certification expenses for European market entry.
- Silicon carbide heat pump convergence:Emerging solid-state heating alternatives threaten PTC share in 2028+ vehicle platforms above 60kWh.
Strategic Opportunities
- Commercial vehicle electrification:European and North American bus and medium-duty truck thermal loads remain underpenetrated by high voltage PTC systems.
- Battery recycling integration:Second-life EV battery preconditioning for stationary storage opens ancillary heating module demand.
- India PLI scheme:Localized component manufacturing incentives are creating qualification pathways for suppliers establishing domestic assembly.
Industry Challenges
- Power electronics integration:Combining PTC modules with 800V inverters demands scarce embedded software and thermal-mechanical engineering talent.
- Dual certification burden:Suppliers serving Chinese OEMs with export ambitions must simultaneously satisfy GB standards and EMA REACH substance traceability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Voltage PTC Heater Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air PTC, Liquid PTC, Molded PTC, Flexible PTC End User: Automotive, Aerospace, Industrial Equipment, Consumer Electronics Application: Heating Systems, Freeze Protection, Temperature Control, Surface Heating Power Rating: Low Power, Medium Power, High Power, Ultra High Power |
| Companies Covered | MAHLE GmbH, Mitsubishi Heavy Industries, Eberspächer, LG Electronics, Woory Corporation, BorgWarner Inc., Webasto Group, Denso Corporation, DBK Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Voltage PTC Heater Market Shifts & Advancements
Platform voltage escalation and ceramic material advances are converging to reshape how thermal management systems are specified, sourced, and integrated across vehicle programs.
Silicon carbide-based power switching is consolidating control architectures for 800V PTC heaters, enabling faster thermal response cycles without discrete relay banks. Tier 1 suppliers are embedding these switches directly into heater modules to capture value from electrification transitions. The structural consequence is compressing the addressable market for standalone power electronics vendors.
REACH substance restrictions under ECHA oversight are forcing reformulation of ceramic dopants and electrode materials in European-bound modules. Manufacturers are qualifying alternative titanate compositions to maintain dielectric performance without restricted heavy metal stabilizers. Battery-electric platforms with export ambitions into the EU are absorbing these compliance costs earliest.
Fleet procurement of thermal management as a service component is fragmenting traditional OEM-direct supplier relationships. Leasing operators and battery-as-a-service providers are negotiating heater module performance guarantees separate from vehicle platform sourcing. This pattern is most visible in German and Chinese commercial vehicle electrification programs where total-cost-of-ownership contracts dominate.
High Voltage PTC Heater Market Segmentation
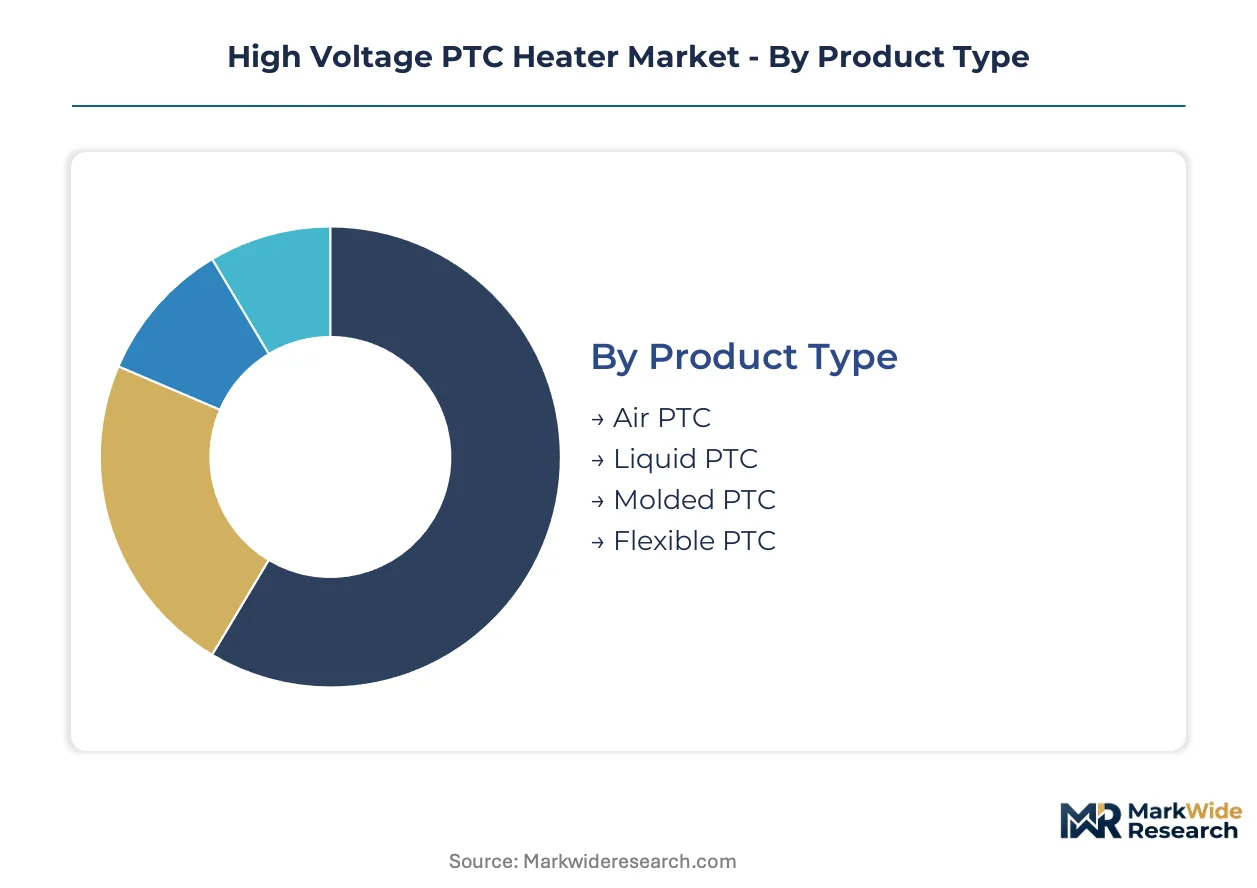
High voltage PTC heater procurement diverges sharply by thermal medium and power architecture, with liquid-cooled battery systems commanding fundamentally different qualification standards than cabin air heating. Understanding where each segment sits within vehicle integration hierarchies reveals which specifications will dominate supplier R&D allocation.
Product Type:
Integration depth separates standalone modules from fully embedded thermal subsystems, reshaping how Tier 1 suppliers structure their heater portfolios.
- Liquid PTC:These heaters circulate coolant through barium titanate elements to manage battery pack temperatures across 400-800V architectures. Premium electric vehicle platforms in Germany and China specify these modules for preconditioning cycles that preserve range in sub-zero conditions.
- Air PTC:Direct cabin heating units dominate unit volumes across mass-market passenger segments, with self-regulating ceramic elements eliminating external control complexity. Chinese domestic brands source these aggressively for cost-optimized battery-electric platforms serving temperate climate zones.
- Molded PTC:Encapsulated ceramic elements suit space-constrained applications with integrated thermal-mechanical packaging.
- Flexible PTC:Thin-film configurations conform to irregular surfaces for specialized surface heating requirements.
Volume placements concentrate in Air PTC; the faster expansion belongs to Liquid PTC.
End User:
Cost tier stratification across end-use categories determines whether suppliers pursue module standardization or platform-custom engineering.
- Automotive:Passenger and commercial vehicle electrification absorbs the overwhelming majority of high voltage PTC capacity, with OEMs specifying separate thermal systems for cabin comfort, battery conditioning, and powertrain stability. MIIT production quotas in China and EPA tailpipe frameworks in the United States are compressing procurement timelines simultaneously.
- Aerospace:Aircraft thermal management for electric propulsion prototypes demands ultra-lightweight ceramic configurations with redundant safety architectures.
- Industrial Equipment:Heavy machinery electrification programs in Germany and Japan are adopting adapted automotive modules for cold-start hydraulic warming.
- Consumer Electronics:Niche applications in high-performance computing thermal management specify low-voltage derivatives of automotive ceramic formulations.
Automotive captures the dominant revenue share; aerospace exhibits the steepest expansion trajectory as electric aviation prototypes advance.
Application:
Customer type differentiation separates OEM-integrated specifications from aftermarket and service-contract procurement patterns.
- Heating Systems:Cabin and battery thermal management constitute the core specification pull, with liquid-cooled variants for traction batteries commanding premium positioning. Nordic markets and Canadian provinces are driving cold-climate performance requirements that elevate power density specifications.
- Freeze Protection:Critical for battery preconditioning and powertrain fluid warming in sub-zero operating environments, particularly for fleet operators in northern China and Scandinavia.
- Temperature Control:Precision thermal regulation for power electronics and charging infrastructure.
- Surface Heating:Specialized applications including steering wheel and seat warming modules.
Heating Systems anchor current procurement volumes; freeze protection specifications are climbing the fastest as cold-climate EV adoption accelerates.
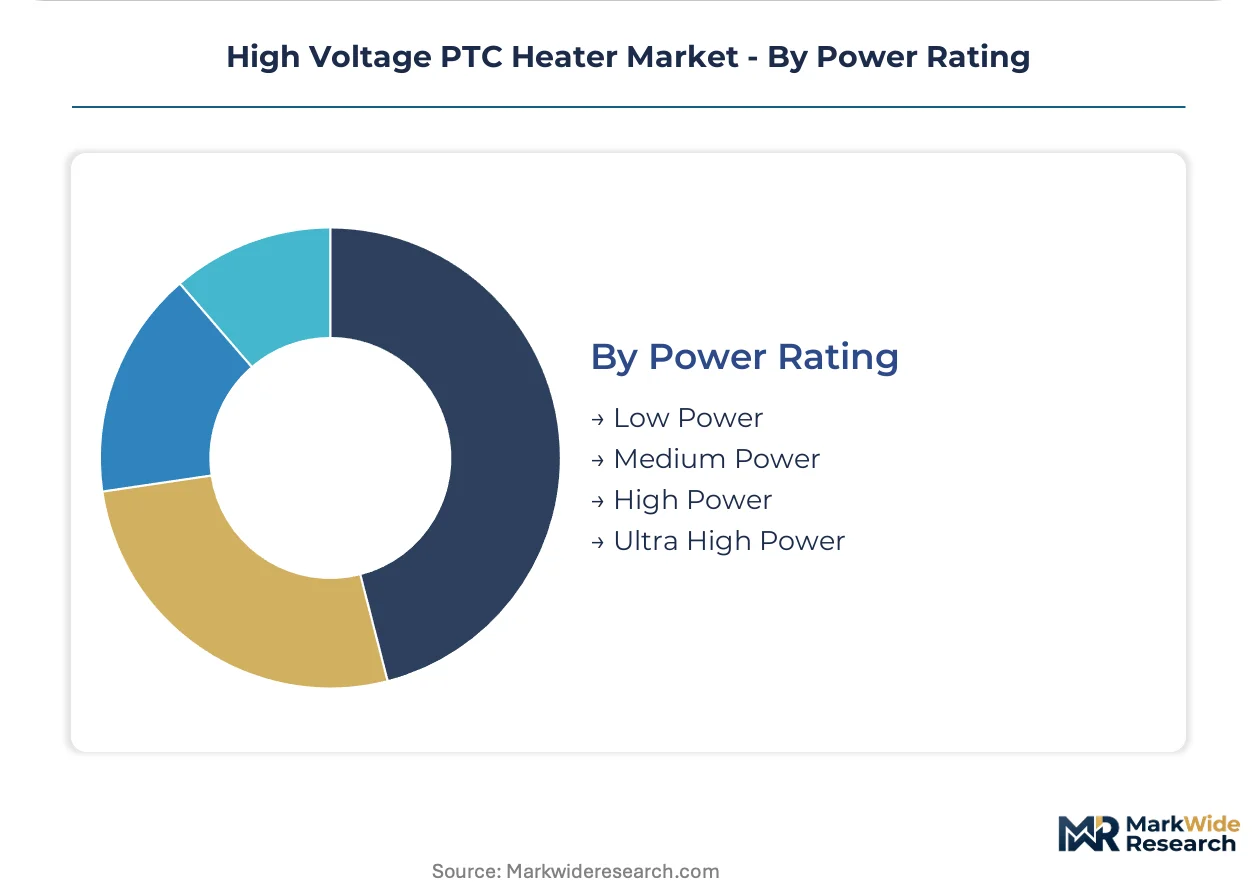
Power Rating:
Maturity gradients separate established low-voltage architectures from emerging ultra-high-power configurations demanded by 800V platforms.
- High Power:5-10kW modules serve dual-purpose cabin and battery warming for mid-size electric vehicles, with silicon carbide switching enabling faster thermal response without discrete relay banks. European premium OEMs are consolidating procurement around these ratings for upcoming platform generations.
- Ultra High Power:10kW+ configurations address 800V architectures and commercial vehicle thermal loads, with embedded power electronics integration compressing supplier qualification timelines. Chinese battery-electric bus programs and German premium SUV platforms are specifying these modules earliest.
- Low Power:Sub-3kW modules for auxiliary cabin applications and small-format vehicles.
- Medium Power:3-5kW ratings for compact passenger vehicle segments.
High Power ratings dominate current installation bases; Ultra High Power configurations are gaining share fastest as voltage architectures escalate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT-designated new energy vehicle industrial zones are concentrating high voltage PTC procurement within domestic supply chains. Germany's automotive clusters are absorbing premium-tier liquid heating modules for 800V platform rollouts. United States EPA tailpipe frameworks are compressing electrified thermal solution adoption timelines across multiple states.
China
MIIT production quotas for battery-electric platforms are pulling capacity toward Yangtze River Delta manufacturing hubs. GB standards compliance creates dual certification requirements for suppliers serving export-oriented OEMs. Shanghai and Suzhou industrial corridors host concentrated ceramic processing facilities for barium titanate element production.
Germany
Premium SUV and sedan electrification programs are specifying ultra-high-power liquid PTC modules for cold-climate battery preconditioning. EU F-Gas Regulation compliance is elevating module certification expenses for European market entry. Stuttgart and Munich automotive clusters anchor thermal management R&D for 800V architectures.
United States
EPA tailpipe emissions frameworks and NHTSA fuel economy standards are forcing OEMs to source electrified heating solutions. California's Advanced Clean Cars program is accelerating phase-out of combustion-based auxiliary systems. Detroit-area engineering centers are consolidating power electronics integration with PTC modules for upcoming platform generations.
Japan
METI carbon neutrality roadmaps are redirecting thermal management procurement toward electrified solutions across passenger and commercial segments. JIS standards for automotive electrical safety are shaping heater module qualification protocols. Nagoya and Tokyo industrial corridors maintain ceramic material research capabilities for next-generation titanate compositions.
South Korea
Domestic battery-electric platform commitments from major automotive groups are reshaping power rating specifications for local suppliers. MFDS-equivalent automotive safety frameworks govern high voltage system approvals. Seoul Capital Area manufacturing complexes are scaling air PTC production for mass-market passenger vehicle segments.
High Voltage PTC Heater Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across fragmented procurement hierarchies. Tier 1 automotive suppliers anchor the premium segment through integrated thermal management portfolios, while mid-scale ceramic specialists capture value from commoditized air heating applications. Two dominant competitive moves are reshaping positioning: backward integration into barium titanate ceramic processing, and strategic partnerships with 800V platform architects for early qualification access.
Among Germany-based diversified automotive suppliers, MAHLE GmbH and Eberspächer exemplify archetypes competing for electrification transition value. BorgWarner Inc. represents the North American tier with power electronics integration capabilities. Mitsubishi Heavy Industries and Denso Corporation anchor Japanese industrial conglomerate participation. LG Electronics and Woory Corporation occupy positions within Korean diversified manufacturing portfolios.
| Leading Market Players |
|---|
| MAHLE GmbH |
| Mitsubishi Heavy Industries |
| Eberspächer |
| LG Electronics |
| Woory Corporation |
| BorgWarner Inc. |
| Webasto Group |
| Denso Corporation |
| DBK Group |
| Others |
Supply & Pricing Matrix
Silicon carbide switching integration into 800V PTC heater modules is compressing cost curves while simultaneously redrawing supplier power dynamics. Barium titanate ceramic processing advances in Chinese foundries are enabling tiered sourcing strategies that separate premium liquid-cooled battery systems from commoditized air heating units.
Pricing Analysis
Lead-time premiums dominate procurement negotiations, with OEMs paying substantial markups for sub-12-week delivery windows versus standard 20-week schedules. Three-tier pricing structure across premium liquid-cooled, standard air-heated, and economy auxiliary modules reflects certification grade and power density specifications. Cost compression in air PTC segments is intensifying because domestic Chinese brands are absorbing margin to secure volume commitments. Fleet operators and battery-as-a-service providers exhibit the lowest price sensitivity, while mass-market passenger OEMs in temperate climate zones drive the hardest unit-cost negotiations.
Supply Chain Analysis
Workforce availability constraints in Yangtze River Delta ceramic foundries and Stuttgart-area engineering centers are elevating labor costs for specialized thermal-mechanical talent. Barium titanate element production concentrates in China, Japan, and Germany, with power electronics assembly drawing from South Korean and Taiwanese semiconductor packaging capabilities. Single-source vulnerability in processed ceramic dopants creates exposure to ECHA REACH substance restriction enforcement. Distribution runs through Tier 1 automotive suppliers holding platform-level integration contracts, with direct OEM procurement emerging only for ultra-high-power 800V configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over barium titanate ceramic processing determines margin capture. Suppliers are pursuing upstream leverage through in-house element production and downstream leverage through embedded power electronics integration.
For Market Incumbents: Deploy embedded software engineering capacity to consolidate 800V inverter-heater module combinations before standalone power electronics vendors capture platform slots. Secure long-term barium titanate supply agreements with Yangtze River Delta foundries to preempt raw material disruption. Silicon carbide heat pump convergence threatens PTC share in premium segments above 60kWh battery capacities. For New Entrants and Emerging Players: Battery-as-a-service providers represent the most penetrable channel partner type for aftermarket thermal management service contracts. Target European commercial vehicle electrification programs where total-cost-of-ownership procurement models fragment traditional OEM-direct relationships. Qualify under alternative titanate compositions compliant with ECHA REACH substance restrictions to bypass incumbent certification moats. For Investors and Strategic Acquirers: Re-rating potential sits with ceramic processing specialists possessing EMA MDR and REACH traceability infrastructure given EU F-Gas Regulation compliance cost escalation. Long-term viability hinges on positioning for 800V platform standardization across premium automotive segments. Watch silicon carbide heat pump adoption curves in Nordic and Canadian cold-climate markets as the critical inflection signal for PTC displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barium Titanate Processing | Captures margin pools from ceramic element production while securing supply continuity against ECHA REACH restrictions. |
| 800V Platform Partnership with OEM Architects | Compresses qualification timelines for ultra-high-power liquid heating modules in German and Chinese premium segments. |
| Silicon Carbide Switching Module Development | Enables faster thermal response cycles that displace discrete relay banks and consolidate control architectures. |
| Dual Certification Infrastructure Investment | Simultaneous GB standards and EMA REACH compliance unlocks Chinese OEM export procurement channels. |
| Battery-as-a-Service Thermal Contracting | Captures recurring revenue from fleet operators and leasing providers outside traditional vehicle platform sourcing. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, ceramic processing plant managers, and thermal management R&D directors combined with bottom-up production database triangulation. Secondary sources included MIIT new energy vehicle production statistics, EPA tailpipe compliance filings, ECHA REACH substance restriction updates, and vehicle registration databases. Top-down market sizing cross-validated against component bill-of-materials estimates from teardown analyses.
Data-stream reconciliation across the projection horizon employed vehicle production forecasts, battery-electric platform rollout schedules, and regional thermal specification requirements. Segmentation modeling incorporated product type, power rating tier, end-use category, and regional regulatory cluster dimensions. CAGRs derived from fitted growth curves against historical adoption patterns and platform voltage escalation timelines. Cold-climate battery preconditioning intensity and 800V architecture penetration served as primary forecast sensitivity inputs.
Caveats apply where silicon carbide heat pump technology maturation, ECHA substance restriction expansion, or Chinese domestic supply chain consolidation could materially shift the outlook. Forecasts reflect assumptions about platform voltage standardization trajectories and barium titanate ceramic cost curves. Material deviation in heat pump cost-performance ratios or REACH regulatory scope warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Terminal Block Market
Electrical Equipment
Wire Splicing Kits Market
Electrical Equipment
Middle East and Africa Electric Drives Market
Electrical Equipment
Electrical Resistor Market
Electrical Equipment
India Electrical Enclosures Market
Electrical Equipment
High-Speed Busbar Transfer Devices Market
Electrical Equipment
Lighting Contactor Market
Electrical Equipment
Air Circuit Breaker Market
Electrical Equipment
Electric Wall Heaters Market
Electrical Equipment
High Voltage Electric Heater Market
Electrical Equipment
North America Commercial Lighting Control Market
Electrical Equipment
Electrical Fuses Market
Electrical Equipment
United States Frequency Converter Market
Electrical Equipment
Electrical Steel Coatings Market
Electrical Equipment
Electrical Isolator Market
Electrical Equipment
Global Panelboards Market