
 Transient Protection Device Market | 2026-2036
Transient Protection Device Market Size, Share, and Industry Trends Forecast 2026-2036
Transient Protection Device Market Analytics
Data center operators and electric vehicle charging network builders are bifurcating demand away from traditional industrial maintenance buyers. Littelfuse specializes in automotive-grade transient voltage suppression for EV charging infrastructure. Schneider Electric SE leverages its energy management portfolio to bundle surge protection with power distribution systems. ABB Ltd anchors its position through high-voltage lightning arrester dominance in utility-scale installations.
A transient protection device limits voltage spikes by diverting excess energy to ground or absorbing it through nonlinear components such as metal oxide varistors with clamping voltages typically between 150V and 600V. Surge protectors command the largest revenue pool among product types due to universal deployment across residential and commercial electrical panels. Transient voltage suppressor technology is gaining share in telecommunications and consumer electronics where picosecond response times protect sensitive integrated circuits. Gas discharge tubes retain utility in outdoor power utility installations where high surge current capacity exceeds solid-state alternatives.
The US market responds to UL 1449 fourth edition requirements for surge protective device safety and performance verification. Europe enforces IEC 61643 series standards for low-voltage surge protective devices alongside CE marking obligations under the Low Voltage Directive. China's GB/T 18802 standards and compulsory certification by the country's national standardization authority shape product entry for domestic grid modernization programs. Stakeholders must track evolving clamping voltage thresholds and regional certification reciprocity as procurement specifications tighten across telecommunications and renewable energy interconnection projects.
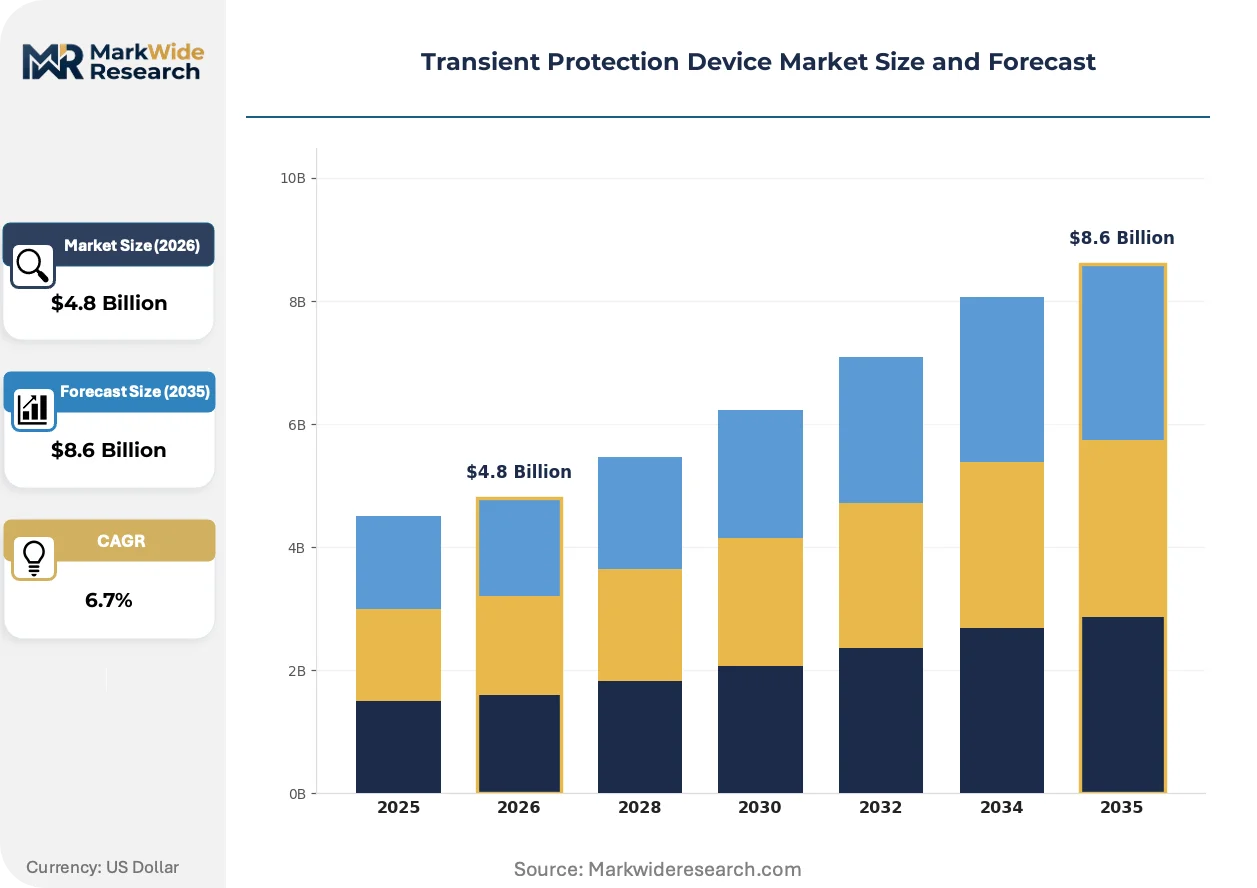
Market Dynamics
Server rack densities above 30 kW per cabinet are forcing hyperscale operators to redesign surge protection architectures, shifting procurement from panel-mounted to distributed point-of-load suppression systems.
Growth Catalysts
- IEC 61643-11 compliance mandates:European grid operators must upgrade substation protection to meet tightened clamping voltage thresholds, triggering replacement cycles across distribution networks.
- Silicon carbide traction inverters:EV manufacturers require faster-responding transient suppression for 800V architectures, pulling automotive-grade TVS diodes into volume production.
- India's telecom infrastructure belt:Tower companies are deploying outdoor surge protection at 400,000+ cell sites to stabilize power quality across rural grid connections.
Market Restraints
- Zinc oxide price volatility:Metal oxide varistor production faces input cost pressure from concentrated Chinese refining capacity, squeezing margin for mid-tier manufacturers.
- Technical ceiling in response speed:Gas discharge tubes cannot achieve sub-nanosecond clamping required for 5G millimeter-wave baseband processors, limiting addressable share.
- UL 1449 fourth edition testing burden:North American certification requires 6,000-cycle endurance validation, extending product launch timelines by 8-14 months.
Strategic Opportunities
- Indonesia's data center construction wave:Batam and Jakarta corridor projects lack mature surge protection supply chains, creating first-mover positioning for certified suppliers.
- Renewable interconnection standards:IEEE 1547-2018 compliance for solar inverters mandates DC-side surge protection, opening utility-scale installation contracts.
- Silicon TVS and polymer PTC convergence:Integrated protection modules combine overvoltage and overcurrent functions, reducing BOM count for consumer electronics OEMs.
Industry Challenges
- EMC testing engineer scarcity:Certification labs face 4-6 month backlog for surge immunity validation per IEC 61000-4-5, throttling product release velocity.
- Legacy 480V industrial infrastructure:Retrofitting motor control centers with modern SPDs requires breaker coordination analysis that most facility teams cannot execute in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transient Protection Device Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surge Protectors, Voltage Suppressors, Power Filters, Lightning Arresters Technology: Varistor, Gas Discharge Tube, Transient Voltage Suppressor, MOV End User: Telecommunications, Consumer Electronics, Industrial Equipment, Power Utilities Installation: Panel Mounted, Inline, Modular, Rack Mounted |
| Companies Covered | Littelfuse, Siemens AG, Schneider Electric SE, Emerson Electric Co., Legrand S.A., Eaton Corporation, General Electric Company, CG Power and Industrial Solutions, ABB Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transient Protection Device Market Evolving Landscape
Transient protection is fragmenting into application-specific architectures, with material science and system integration advancing faster than standalone component improvement. Three forces dominate this evolution.
Silicon avalanche TVS arrays are displacing discrete zener diodes in smartphone USB-C ports and automotive CAN bus lines. Tier-1 electronics assemblers specify multi-channel TVS with sub-picosecond response for 10Gbps signal integrity. This displacement compresses the commodity diode segment while expanding premium integrated protection revenue pools.
China's GB/T 18802.11-2020 revision tightened residual voltage requirements for Class I SPDs deployed in State Grid substations. Domestic manufacturers must retest entire product lines, creating temporary supply tightness. Foreign suppliers with pre-certified platforms are capturing procurement share in 220kV and 500kV grid modernization tenders.
Buying committees at hyperscale data center operators now specify surge protection at the rack PDU level rather than relying solely on facility-level panels. Channel partners with electrical contractor relationships are losing specification influence to direct OEM-engineer engagement. This pattern is most pronounced in Northern Virginia and Frankfurt cloud campus developments.
Transient Protection Device Market Segmentation
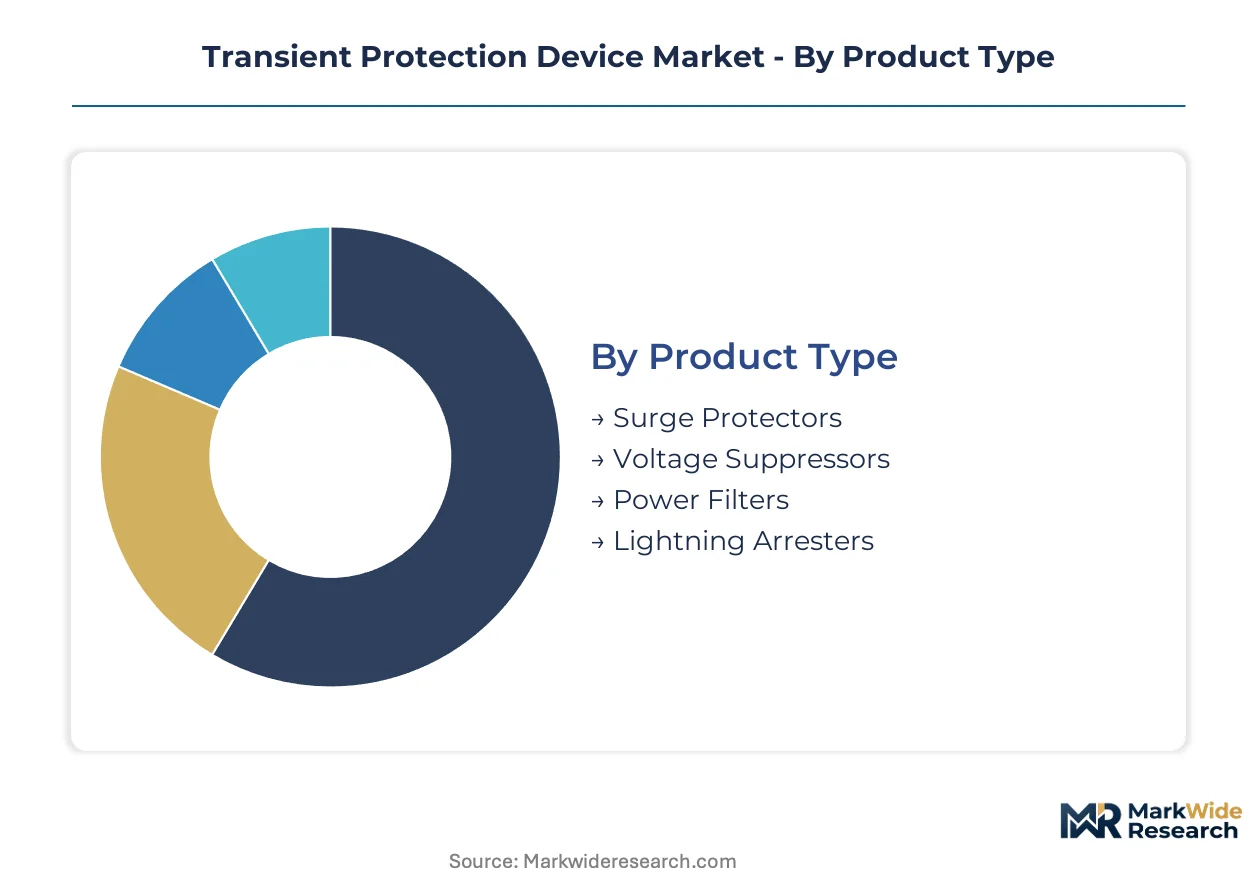
Transient protection architectures fragment across four interlocking dimensions. Product type determines fundamental suppression mechanism. Technology selection locks in response speed and energy handling. End-user verticals impose distinct certification and performance thresholds. Installation format governs whether procurement flows through electrical distributors or direct OEM channels.
Product Type:
Channel mix splits sharply: surge protectors and power filters move predominantly through electrical wholesale distributors serving contractor markets, while voltage suppressors and lightning arresters route through direct specification to OEM engineering teams and utility procurement offices.
- Surge Protectors:Metal oxide varistor-based units with clamping voltages between 150V and 600V dominate residential and commercial electrical panel deployment. Demand concentrates in data center construction corridors across Northern Virginia and Frankfurt, where hyperscale operators specify rack-level redundancy alongside facility-grade protection.
- Voltage Suppressors:Silicon avalanche and zener diode arrays achieve sub-nanosecond response for integrated circuit protection. Telecommunications infrastructure in India's rural tower belt and China's 5G base station rollout are pulling automotive-grade TVS diodes into volume production for 800V architectures.
- Power Filters:EMI suppression combined with transient protection serves medical imaging and industrial motor drive applications. IEC 60601-1 compliance requirements shape hospital procurement specifications.
- Lightning Arresters:Gas discharge tube and spark gap technologies handle utility-scale surge currents exceeding 100kA. State Grid substation modernization in China and European TSO replacement cycles sustain demand.
Surge protectors dominate installed base. Voltage suppressors are where expansion concentrates.
Technology:
Cost tier stratification separates mature commodity platforms from premium solid-state alternatives. Varistor and MOV technologies occupy economy positioning. TVS and advanced GDT formulations command premium pricing.
- Varistor:Zinc oxide disc construction provides nonlinear voltage-current characteristics for general-purpose suppression. Zinc oxide price volatility from concentrated Chinese refining capacity squeezes mid-tier manufacturer margins.
- Gas Discharge Tube:Ceramic-metal seal architecture achieves 10kA+ surge current capacity. Outdoor power utility installations in Germany and Brazil retain GDT preference where response speed requirements remain below 5G millimeter-wave thresholds.
- Transient Voltage Suppressor:Silicon avalanche technology achieves picosecond response for USB-C ports and automotive CAN bus protection. 10Gbps signal integrity requirements at consumer electronics OEMs are displacing discrete zener diodes.
- MOV:Metal oxide varistor arrays dominate surge protective device manufacturing. UL 1449 fourth edition 6,000-cycle endurance validation extends product launch timelines by 8-14 months for North American certification.
MOV technology anchors volume production. TVS platforms are climbing the fastest.
End User:
Customer type dictates specification authority and sales cycle length. Telecommunications and consumer electronics favor direct OEM engagement. Industrial equipment and power utilities route through channel partners with long-term service relationships.
- Telecommunications:Tower companies deploy outdoor surge protection at 400,000+ cell sites across India's infrastructure belt to stabilize power quality. TRAI mandates on network uptime are tightening procurement specifications.
- Consumer Electronics:Smartphone and laptop manufacturers specify multi-channel TVS arrays for 10Gbps signal integrity. USB-C port protection requirements are compressing commodity diode segments.
- Industrial Equipment:Motor control center retrofitting requires breaker coordination analysis that most facility teams cannot execute in-house. Schneider Electric and ABB leverage energy management portfolios to bundle surge protection with power distribution systems.
- Power Utilities:Grid operators must upgrade substation protection to meet tightened IEC 61643-11 clamping voltage thresholds. European TSO replacement cycles and China's State Grid 220kV and 500kV modernization tenders sustain demand.
Industrial equipment dominates current procurement volume. Telecommunications infrastructure is gaining share fastest.
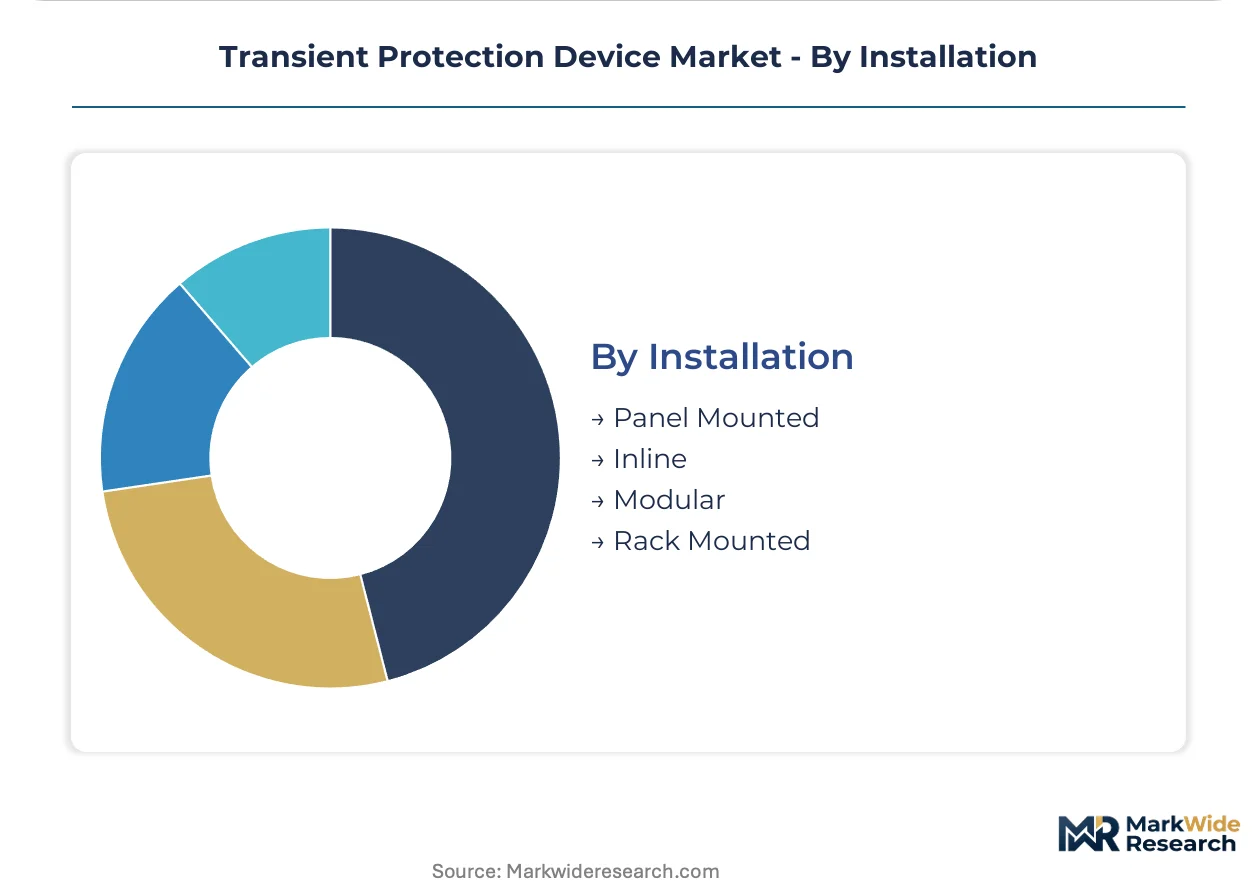
Installation:
Supply concentration varies by mounting format. Panel-mounted and inline products flow through established electrical distribution. Modular and rack-mounted formats require direct manufacturer-engineer collaboration.
- Panel Mounted:DIN-rail and enclosure-integrated units serve facility-level electrical distribution. Traditional industrial maintenance buyers favor this format for established replacement cycles.
- Inline:Cable-integrated suppression protects specific equipment runs without panel modification. Renewable energy interconnection projects specify IEEE 1547-2018 compliant DC-side inline protection.
- Modular:Hot-swappable cartridge designs reduce maintenance downtime for critical infrastructure. Data center operators in Indonesia's Batam and Jakarta corridor specify modular formats where mature surge protection supply chains remain underdeveloped.
- Rack Mounted:PDU-integrated suppression serves server densities above 30 kW per cabinet. Hyperscale operators in Northern Virginia and Frankfurt now specify protection at rack level rather than relying solely on facility panels.
Panel-mounted units retain the largest installed base. Rack-mounted configurations are where specification influence is shifting most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers export transient protection components to data center builders in Northern Virginia and Frankfurt, establishing the primary trade-flow corridor for surge protective devices. Grid modernization tenders in multiple jurisdictions are tightening certification requirements. Procurement committees now prioritize pre-certified platforms over unverified alternatives.
United States
Hyperscale operators in Northern Virginia specify rack-level surge protection for densities exceeding 30 kW per cabinet. UL 1449 fourth edition mandates 6,000-cycle endurance validation, extending certification timelines. Dallas-Fort Worth corridor projects are absorbing modular SPD supply as Batam-serving distributors establish regional stocking positions.
China
State Grid Corporation tenders for 220kV and 500kV substation modernization require GB/T 18802.11-2020 compliance. The national standardization authority enforces compulsory certification for Class I SPDs. Yangtze River Delta fabricators are retesting entire product lines, creating temporary supply tightness that foreign pre-certified suppliers exploit.
Germany
European TSO replacement cycles drive demand for high-voltage lightning arresters in utility-scale installations. IEC 61643-11 tightened clamping voltage thresholds trigger substation protection upgrades. Rhine-Ruhr industrial belt facilities are retrofitting motor control centers with coordinated SPD architectures.
India
Tower companies deploy outdoor surge protection across 400,000+ rural cell sites to stabilize power quality. TRAI mandates on network uptime tighten procurement specifications. Telecom infrastructure belt projects in Gujarat and Maharashtra specify automotive-grade TVS diodes for 800V charging architectures.
Indonesia
Batam and Jakarta data center construction lacks mature surge protection supply chains, creating first-mover positioning. The country's national standardization authority is developing SPD certification reciprocity with IEC frameworks. Channel partners with electrical contractor relationships are losing specification influence to direct OEM-engineer engagement.
Transient Protection Device Market Competitive Landscape
Player mix skews toward diversified electrical conglomerates with energy management portfolios. Market structure concentrates around three to five integrated suppliers controlling utility-scale and automotive-grade segments. Strategic archetypes include component specialists with deep varistor or TVS expertise, diversified industrial electrification providers bundling protection with distribution systems, and high-voltage apparatus manufacturers anchoring transmission network positions. Dominant competitive moves involve certification platform expansion across multiple jurisdictions and direct engagement with hyperscale data center engineering teams.
Among diversified electrical conglomerates, Schneider Electric SE and ABB Ltd exemplify portfolio-integrated positioning, while Littelfuse occupies a specialist anchor role. These three entities represent distinct competitive vectors: bundled energy management systems, high-voltage transmission apparatus, and automotive-grade semiconductor protection. Each sits within a tier where specification authority flows through direct OEM relationships rather than traditional distribution channels. Their collective presence shapes procurement committee expectations for certification breadth and application engineering support.
| Leading Market Players |
|---|
| Littelfuse |
| Siemens AG |
| Schneider Electric SE |
| Emerson Electric Co. |
| Legrand S.A. |
| Eaton Corporation |
| General Electric Company |
| CG Power and Industrial Solutions |
| ABB Ltd |
| Others |
Value Network & Pricing Analysis
Eighteen-month certification backlogs for UL 1449 fourth edition testing concentrate pricing power with pre-certified suppliers while squeezing margin for mid-tier manufacturers awaiting validation. This lead-time asymmetry rewards inventory positions in zinc oxide varistor feedstock and accelerates procurement committee preference for certified platforms.
Pricing Analysis
TVS-to-MOV pricing gaps separate three performance tiers: silicon avalanche arrays command premium positioning for sub-picosecond response in automotive CAN bus and 10Gbps consumer electronics, while metal oxide varistor platforms occupy standard tiers for facility-grade surge protection, and commodity zinc oxide discs anchor economy positioning for residential panels. Price differentiation rests on IEC 61643-11 certification tier and clamping voltage specification granularity. Cost compression in varistor manufacturing is intensifying because concentrated Chinese zinc oxide refining capacity exposes mid-tier producers to input volatility. Industrial equipment buyers exhibit highest price sensitivity due to legacy 480V infrastructure retrofit constraints, while hyperscale data center operators demonstrate lowest sensitivity as rack-level protection specifications override unit cost considerations.
Supply Chain Analysis
Yangtze River Delta ceramic-metal seal fabrication concentrates gas discharge tube output for utility-scale lightning arrester deployment. Zinc oxide disc production draws from Chinese refining clusters, silicon wafer supply rests on Taiwan and South Korea foundry capacity, and polymer PTC compound manufacturing centers on Japan and Germany specialty chemical producers. Single-source vulnerability concentrates in IEC 61000-4-5 EMC testing laboratory capacity, where four-to-six month validation backlogs throttle product release velocity. Distribution runs through electrical wholesale distributors for panel-mounted surge protectors and power filters, while voltage suppressors and lightning arresters route through direct OEM specification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from certification compliance consulting and breaker coordination analysis for legacy motor control center retrofits is expanding faster than hardware unit sales, creating recurring-revenue architecture for protection device vendors.
For Market Incumbents: Fortify certification platform breadth across UL 1449, IEC 61643-11, and GB/T 18802.11-2020 jurisdictions to capture State Grid and European TSO replacement cycles. Deepen backward integration into zinc oxide feedstock to defend margin position against Chinese refining concentration. Channel control through direct hyperscale data center engineering relationships neutralizes electrical distributor disintermediation.
For New Entrants and Emerging Players: Anchor in Indonesia's Batam and Jakarta data center corridor where mature surge protection supply chains remain underdeveloped and first-mover positioning in modular rack-mounted formats escapes incumbent specification lock-in. Target telecom tower companies across India's rural infrastructure belt with automotive-grade TVS diode solutions for 800V charging architecture convergence. Pursue OEM-direct specification authority rather than distributor channel dependence.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with undermonetized transient protection portfolios buried within energy management divisions. Long-term viability hinges on certification asset durability and application engineering headcount depth. Watch IEC 61643-11 clamping voltage threshold revisions as inflection indicator for replacement cycle acceleration across European distribution networks.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Platform Expansion | Multi-jurisdiction UL/IEC/GB compliance unlocks State Grid and European TSO procurement committees. |
| Backward Integration into Zinc Oxide | Captive feedstock supply neutralizes Chinese refining concentration and input cost volatility. |
| Direct OEM-Engineer Engagement | Bypassing electrical distributors captures hyperscale data center specification authority in Northern Virginia. |
| Modular Rack-Mounted Format Development | Hot-swappable cartridge designs penetrate Indonesia's underdeveloped data center supply chains. |
| Automotive-Grade TVS Volume Scale-Up | 800V EV architecture demand pulls semiconductor protection into charging infrastructure tenders. |
Research Methodology
Cross-validation between primary interviews with EMC testing laboratory directors, surge protection product managers at electrical conglomerates, and hyperscale data center facility engineers anchors the qualitative findings. Secondary validation draws from UL certification databases, IEC standard revision documentation, State Grid Corporation tender announcements, and SEC filings of listed electrical equipment manufacturers. Bottom-up demand modeling from installation format and end-user verticals triangulates against top-down market sizing from component shipment value chains.
Sensitivity analysis around zinc oxide price volatility and certification timeline compression shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology platform, end-user vertical, and installation format alongside regional regulatory cluster differentiation. CAGRs derive from replacement cycle analysis of IEC 61643-11 compliance mandates and EV charging infrastructure deployment trajectories. Industry-specific forecast inputs incorporate 30 kW-plus server rack density specifications and IEEE 1547-2018 renewable interconnection standards.
Material uncertainties — IEC standard revision timing, EMC testing laboratory capacity expansion, and zinc oxide supply concentration shifts — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as GB/T 18802 reciprocity negotiations and Indonesia national standardization authority certification framework evolution reshape procurement specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Electrical Sub Panels Market
Electrical Equipment
HID Ballast Market
Electrical Equipment
Low Voltage Electric Motor Market
Electrical Equipment
Global Medium Voltage Surge Arresters Market
Electrical Equipment
Electric Control Panel Market
Electrical Equipment
Portable Misting Fans Market
Electrical Equipment
Global Copper Clad Steel (CCS) Wire Market
Electrical Equipment
France DC Motors Market
Electrical Equipment
Waveguide Market
Electrical Equipment
Electrical Isolator Market
Electrical Equipment
GCC Ceiling Fan Market
Electrical Equipment
Medium Voltage Transformer Market
Electrical Equipment
Electric Wall Heaters Market
Electrical Equipment
Middle East and Africa Electric Drives Market
Electrical Equipment
Europe Electric Insulator Market
Electrical Equipment
Rotary and RF Rotary Joints Market