

Copper and Aluminum Terminal Blocks Market Size, Share, and Industry Trends Forecast 2026-2036
Copper and Aluminum Terminal Blocks Market Insights
The EU Green Deal is shifting procurement criteria toward low-carbon copper and recycled aluminum content in electrical components. Phoenix Contact leverages its captive supply of precision-machined copper alloys to meet tightening material traceability rules. WAGO sustains competitive positioning through spring-clamp technology leadership that reduces installation labor in control panel applications. Weidmüller anchors European demand with localized production networks serving German automotive and machinery OEMs.
Copper and aluminum terminal blocks are electromechanical connection devices engineered to terminate, join, and distribute electrical conductors in industrial and commercial installations, typically rated for currents from 10 A to over 300 A depending on cross-section and material conductivity. Copper variants deliver superior electrical conductivity and oxidation resistance in high-temperature power distribution environments, while aluminum alternatives reduce weight and raw material cost in large-scale renewable energy and shipbuilding applications. Screw terminal blocks retain dominant share in heavy-current power distribution due to established installer familiarity and mechanical reliability under vibration. Spring-clamp terminal blocks represent the fastest-growing product category as panel builders and OEMs prioritize tool-free wiring speed and maintenance access in control panel and switchgear production. Feed-through terminal blocks concentrate margin pools in railway and shipbuilding segments where marine-grade plating and shock-resistant housings command specification premiums.
FDA standards for electrical safety in medical device manufacturing, EPA rules on industrial emissions from metal plating operations, and IEC 60947 terminal block specifications collectively shape product design, testing protocols, and market access conditions. CE marking under the EU Low Voltage Directive and RoHS material restrictions further constrain supplier qualification for European electrical equipment manufacturers. Stakeholders must monitor evolving national building codes and electrification subsidies that will determine replacement-cycle timing across industrial and infrastructure end uses.
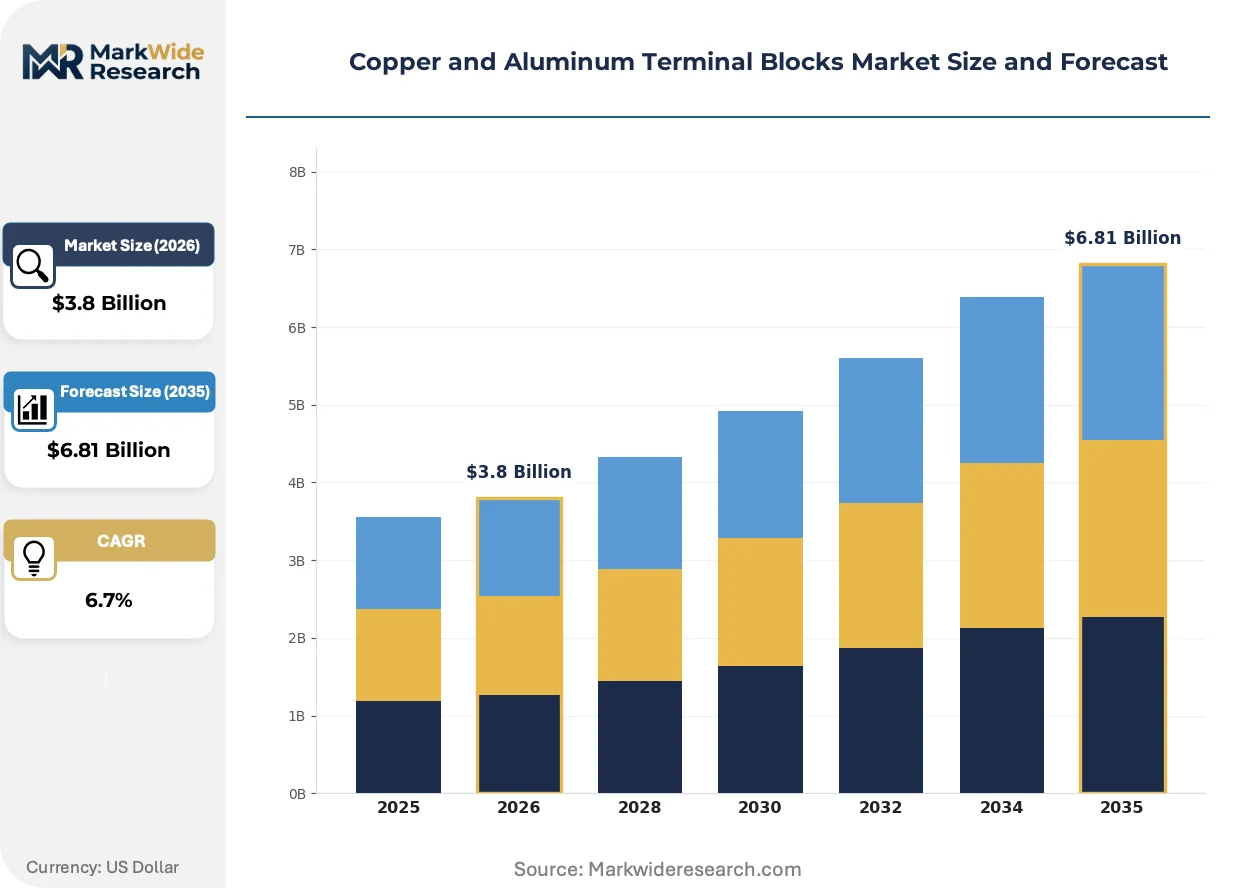
Market Dynamics
Utility-scale solar and wind farm electrification is compressing terminal block specification cycles, forcing suppliers to recertify products for higher current densities and marine-grade corrosion resistance within tighter procurement windows.
Growth Catalysts
- EU Green Deal material mandates:Electrification infrastructure projects across Germany, France, and Italy now require documented recycled aluminum content and low-carbon copper sourcing, accelerating replacement demand in grid modernization programs.
- Spring-clamp technology penetration:Tool-free wiring speed is displacing screw terminals in control panel production, with panel builders prioritizing maintenance access and labor reduction in switchgear assembly.
- Railway electrification density:Feed-through terminal blocks with shock-resistant housings and marine-grade plating are capturing specification premiums in rolling stock and trackside power distribution systems.
Market Restraints
- Copper price volatility:LME copper futures fluctuations above fifteen percent annually compress margin predictability for alloy-dependent product lines and force hedging costs onto smaller fabricators.
- RoHS compliance friction:Cadmium-free plating alternatives for high-temperature power distribution applications impose longer qualification timelines and reject rates in surface treatment operations.
- Aluminum oxidation sensitivity:Galvanic corrosion risk at copper-aluminum junctions limits direct substitution in salt-air marine environments without specialized bimetallic transition hardware.
Strategic Opportunities
- CE marking acceleration:The EU Low Voltage Directive's tightened conformity assessment routes create first-mover advantage for suppliers with pre-positioned notified body relationships and modular certification portfolios.
- Renewable energy OEM integration:Direct specification partnerships with wind turbine and solar inverter manufacturers bypass traditional distribution markups and lock in volume commitments across project pipelines.
- Digital twin convergence:Integration of terminal block digital product passports with building information modeling systems enables predictive maintenance contracts and recurring software-service revenue streams.
Industry Challenges
- IEC 60947 testing backlog:Third-party laboratory capacity constraints extend type-test completion from twelve to twenty-four months, delaying product launches and contract eligibility.
- Precision machining talent scarcity:Shortages of CNC operators capable of maintaining tight tolerances on copper alloy terminal bodies constrain capacity expansion at mid-tier fabricators.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper and Aluminum Terminal Blocks Market Trends and Innovations
Terminal block architecture is fragmenting into application-optimized subsystems, with material science advances and digital integration requirements forcing simultaneous evolution across mechanical, electrical, and data-connection functions.
Push-in connection technology is modularizing panel wiring workflows by eliminating torque tools and reducing installation time in high-density control cabinets. Automotive tier-one suppliers and machinery OEMs in Germany are specifying these interfaces for production line switchgear. The technology is modularizing supplier-customer relationships around plug-and-play subsystem procurement rather than component-level sourcing.
REACH substance restrictions on nickel compounds and chromium trioxide in plating operations are forcing conversion to tin-zinc and silver-based surface finishes. Surface treatment shops face capital equipment replacement costs exceeding two million euros per line. Railway signaling and offshore wind applications are absorbing premium pricing for compliant marine-grade coatings.
Buyer concentration among European energy infrastructure contractors is compressing payment terms and demanding vendor-managed inventory arrangements. Traditional electrical distributors are losing specification influence as EPC firms consolidate procurement through direct manufacturer frameworks. German grid operators and French nuclear maintenance providers are piloting consignment stock models with real-time consumption tracking.
Copper and Aluminum Terminal Blocks Market Segmentation
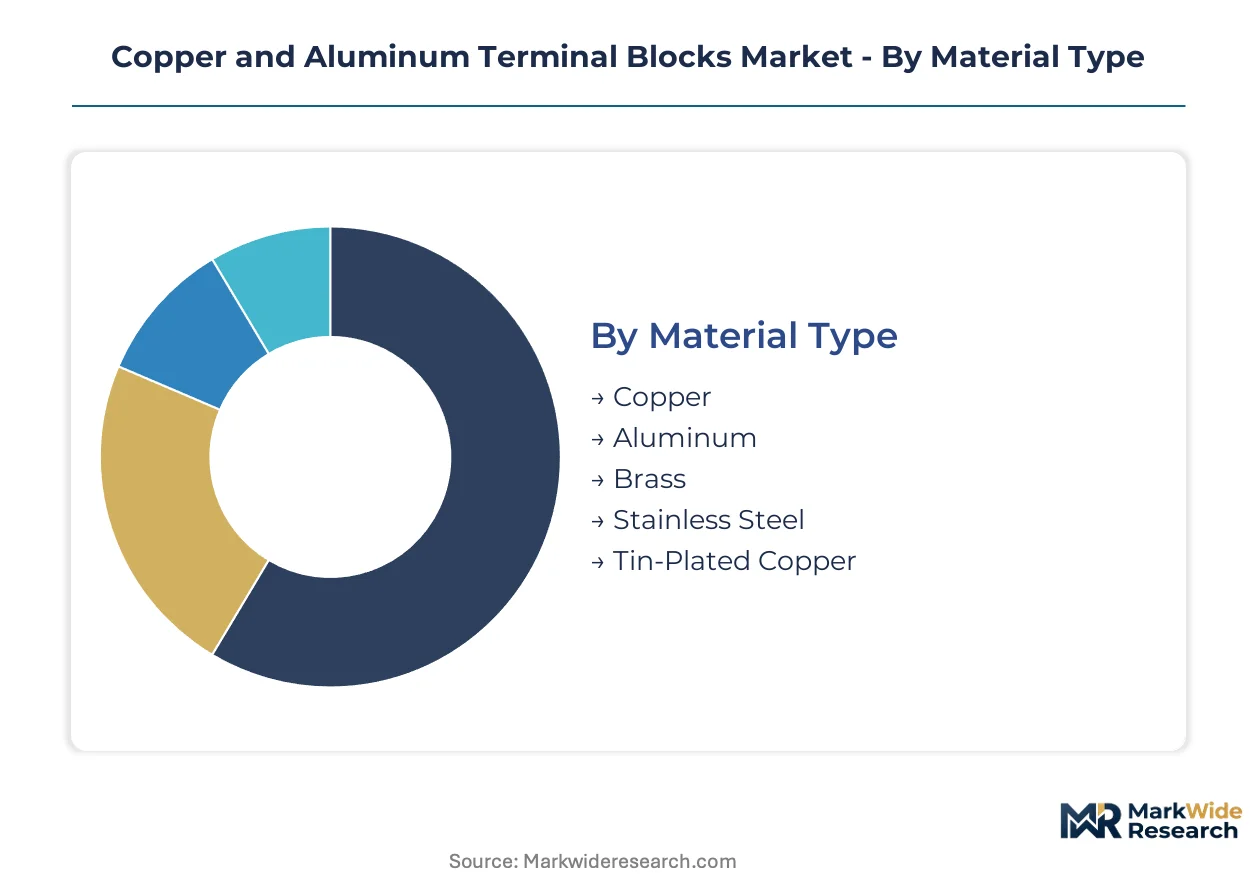
Terminal block procurement decisions diverge sharply across material grades and connection technologies, with certification requirements from IEC 60947 and marine classification societies creating distinct qualification barriers for each segment. Specification engineers weight conductivity performance against installation labor costs, producing tiered sourcing patterns that reshape supplier competitiveness.
Material Type:
IEC 60947-7-1 compliance mandates separate testing protocols for copper alloys versus aluminum conductors, with marine-grade plating specifications adding REACH substance restrictions for offshore applications.
- Copper:High-conductivity electrolytic grades deliver superior current-carrying capacity in power distribution environments above 150 A. German grid operators and French nuclear maintenance providers specify oxygen-free variants for substation infrastructure replacement cycles.
- Aluminum:Lightweight extrusions reduce conductor weight by sixty percent versus copper equivalents in wind turbine nacelle wiring. Italian solar farm EPCs are absorbing bimetallic transition hardware costs to exploit raw material savings at utility scale.
- Brass:Lead-free machinable alloys satisfy RoHS restrictions for control panel terminal bodies in machinery OEM supply chains.
- Stainless Steel:Marine-grade 316L substrates withstand salt-air corrosion in offshore wind and shipbuilding applications without additional surface plating.
- Tin-Plated Copper:Solder-compatible finishes enable printed circuit board integration in power electronics modules for solar inverter manufacturers.
Leading the category by volume: Copper. Growing fastest: Aluminum.
Product Type:
Connection mechanism selection determines labor cost profiles and maintenance accessibility, with tool-free technologies commanding fifteen to twenty-five percent price premiums in high-density panel applications.
- Screw Terminal Blocks:Torque-calibrated clamping systems retain specification dominance in heavy-current power distribution above 100 A. Vibration resistance under railway rolling stock shock loads sustains demand despite slower installation speeds.
- Spring Clamp Terminal Blocks:Constant-force cage-clamp designs eliminate retightening maintenance in building automation systems. German automotive tier-one suppliers are specifying these interfaces for production line switchgear standardization.
- Barrier Terminal Blocks:Raised partition structures prevent accidental contact in high-voltage industrial motor control centers.
- Feed-Through Terminal Blocks:Double-deck configurations maximize panel density in shipbuilding switchboards where space constraints dominate design priorities.
- Pluggable Terminal Blocks:Modular mating interfaces enable field-replaceable subassemblies in wind turbine pitch control systems.
Highest volume share: Screw Terminal Blocks. Steepest expansion trajectory: Spring Clamp Terminal Blocks.
Application:
End-use environment dictates housing material, plating chemistry, and shock resistance specifications, with marine and railway applications absorbing premium pricing for certified subsystems.
- Power Distribution:Busbar-mounted blocks handling 300 A plus currents in utility substations require silver-plated contact surfaces to minimize oxidation resistance.
- Control Panels:High-density DIN rail mounting in machinery OEM production lines prioritizes push-in connection speed over raw conductivity performance.
- Renewable Energy:Solar combiner boxes and wind converter cabinets demand UV-resistant housings and wide temperature cycling tolerance.
- Railways:EN 50155 shock and vibration certification filters supplier qualification to a handful of European specialists with notified body relationships.
- Shipbuilding:Lloyd's Register and DNV marine type approvals impose flame-retardant housing specifications and salt spray testing protocols.
Dominant demand source: Power Distribution. Climbing the fastest: Renewable Energy.
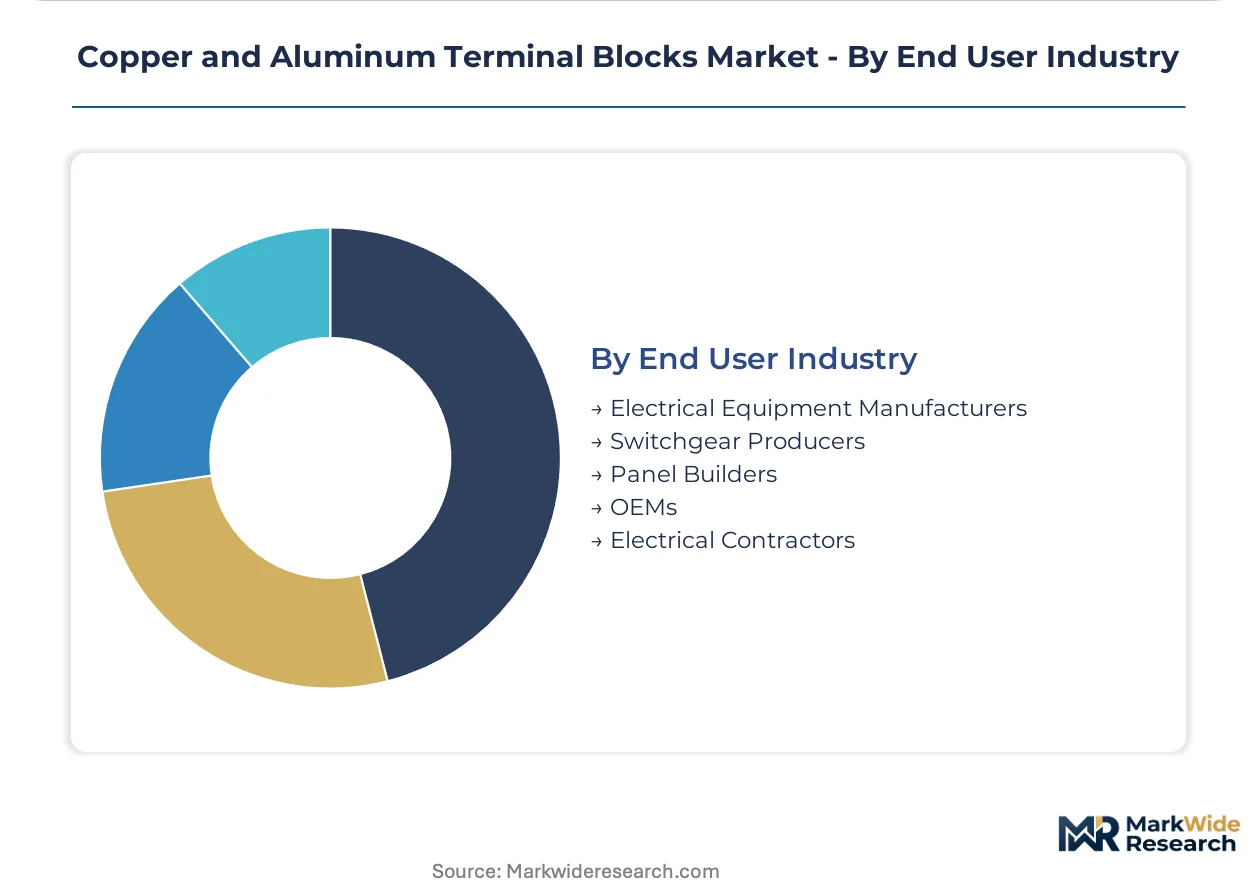
End User Industry:
Procurement sophistication varies from commodity purchasing by electrical contractors to collaborative specification development with switchgear producers requiring vendor-managed inventory arrangements.
- Electrical Equipment Manufacturers:Integrated producers of distribution transformers and switchgear assemblies source terminal blocks through approved vendor lists with two-year qualification cycles.
- Switchgear Producers:German and French medium-voltage specialists are consolidating procurement through direct manufacturer frameworks, bypassing traditional electrical distributors.
- Panel Builders:Control cabinet assemblers in Italian industrial automation clusters prioritize component interoperability and DIN rail compatibility across supplier portfolios.
- OEMs:Wind turbine and solar inverter manufacturers specify terminal blocks at the subsystem design phase, locking in volume commitments across project pipelines.
- Electrical Contractors:Installation firms serving building automation and infrastructure projects rely on distributor stock availability and same-day fulfillment.
Largest procurement volume: Electrical Equipment Manufacturers. Gaining share fastest: OEMs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial corridor anchors European terminal block procurement, with German grid operators and automotive OEMs driving specification cycles for high-current connection systems.
Germany
Industrial automation upgrades in Bavaria and North Rhine-Westphalia are accelerating replacement demand for DIN rail-mounted terminal blocks. The EU Green Deal mandates documented recycled aluminum content in electrification infrastructure, tightening material traceability rules for suppliers serving Stuttgart's machinery clusters.
France
Nuclear maintenance providers and railway electrification projects in Île-de-France specify shock-resistant feed-through terminal blocks for rolling stock applications. ECHA REACH restrictions on nickel compounds in plating operations are forcing conversion to tin-zinc surface finishes at Lyon-area surface treatment shops.
Italy
Solar farm EPCs in Lombardy and Emilia-Romagna absorb bimetallic transition hardware costs to exploit aluminum weight savings in utility-scale photovoltaic installations. National electrification subsidies under the EU Recovery Fund are compressing procurement windows for grid connection components.
United States
Utility-scale wind deployments in Texas and solar converter manufacturing in California are driving demand for UV-resistant terminal block housings with wide temperature cycling tolerance. EPA rules on industrial emissions from metal plating operations constrain surface treatment capacity for marine-grade coatings serving offshore wind projects.
China
Wind turbine nacelle assembly in Jiangsu and solar inverter production in Zhejiang prioritize lightweight aluminum terminal blocks to reduce conductor weight in renewable energy systems. GB standards for electrical connection components and MIIT dual carbon goals are reshaping material sourcing requirements for domestic OEMs.
Copper and Aluminum Terminal Blocks Market Competitive Landscape
The competitive structure tilts toward precision-machining specialists with captive alloy supply chains. German and Swiss electrical component fabricators dominate premium-tier specification through established notified body relationships and modular certification portfolios. Three archetypes occupy distinct competitive terrain: integrated connection technology conglomerates with broad industrial portfolios; mid-scale specialists focused on spring-clamp or push-in connection patents; and Asian-scale manufacturers competing on aluminum extrusion cost structures. Capacity expansion and direct OEM framework agreements represent the dominant competitive moves, bypassing traditional electrical distribution channels.
Among German-based specialists, Phoenix Contact GmbH & Co. KG, WAGO Kontakttechnik GmbH & Co. KG, and Weidmüller Interface GmbH & Co. KG exemplify the precision-machining archetype with strong positions in control panel and switchgear specification. These entities anchor European demand through localized production networks and direct relationships with automotive tier-one suppliers. Chinese fabricators including Degson Electronics Co., Ltd. occupy positions on the scale-driven end of the cost-structure spectrum, serving volume procurement from renewable energy OEMs. The competitive terrain rewards first-movers on CE marking acceleration under tightened EU Low Voltage Directive conformity assessment routes.
| Leading Market Players |
|---|
| Phoenix Contact |
| WAGO |
| Weidmüller |
| TE Connectivity |
| Siemens |
| Eaton |
| Schneider Electric |
| Wieland Electric |
| Degson Electronics |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal mandates for documented recycled aluminum content and low-carbon copper sourcing are forcing suppliers to absorb certification and traceability costs, compressing margins at mid-tier fabricators while concentrating pricing power with integrated producers holding captive alloy supply chains.
Pricing Analysis
Certification-grade performance anchors terminal block pricing tiers, with marine-grade plating and IEC 60947-7-1 compliance commanding substantial premiums over standard industrial grades. Price differentiation separates shock-resistant railway specifications from economy-tier building automation products, with volume scale and after-sales service bundling as secondary drivers. Pricing pressure stems from buyer consolidation among German EPC firms demanding vendor-managed inventory arrangements. Electrical contractors exhibit highest price sensitivity, while nuclear maintenance providers and railway OEMs prioritize specification compliance over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale procurement from wind turbine and solar inverter manufacturers, bypassing traditional electrical distributors. Manufacturing concentrates in Germany, China, and Switzerland, with precision-machining operations anchored in the Ruhr corridor and spring-clamp technology specialists maintaining production in Minden. Raw material flows draw from Chilean copper cathode, Chinese aluminum extrusions, and European recycled content streams. Single-source vulnerability in precision-machined copper alloy terminal bodies constrains capacity expansion. Distribution runs through direct manufacturer frameworks consolidated by French and German switchgear producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Terminal block supply is tightening around precision-machining capacity constraints, with CNC operator scarcity propping pricing for certified products and rewarding first-movers on CE marking acceleration.
For Market Incumbents: Anchor market position through backward integration into precision-machined copper alloy production and modular certification portfolios pre-positioned for tightened EU Low Voltage Directive conformity assessment routes. Defend against Asian-scale aluminum extrusion competitors by locking direct OEM framework agreements with renewable energy manufacturers. Prioritize captive supply chains to meet tightening material traceability rules. For New Entrants and Emerging Players: The gap between premium marine-grade specifications and economy-tier building automation products opens white-space targeting at the mid-market spring-clamp segment serving Italian panel builders. Focus penetration on utility-scale solar EPCs in Lombardy absorbing bimetallic transition hardware costs for aluminum weight savings. Pursue go-to-market partnerships with DIN rail component distributors serving industrial automation clusters. For Investors and Strategic Acquirers: Re-rating potential sits with precision-machining specialists holding notified body relationships given CE marking acceleration under tightened conformity assessment routes. Long-term viability favors integrated producers with captive alloy supply and direct OEM channel control. Watch IEC 60947 testing backlog resolution as inflection indicator for product launch velocity and contract eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Alloys | Captive copper supply secures material traceability compliance for EU Green Deal mandates. |
| CE Marking Acceleration | Pre-positioned notified body relationships capture first-mover advantage in German grid modernization. |
| Direct OEM Framework Agreements | Bypassed distributor markups lock volume commitments with wind turbine manufacturers. |
| Spring-Clamp Technology Expansion | Tool-free wiring speed addresses labor reduction priorities in automotive tier-one supply chains. |
| Digital Twin Integration | Product passport convergence with building information modeling enables predictive maintenance contracts. |
Research Methodology
Trade association filings, customs databases, and IEC certification registries formed the secondary backbone, cross-referenced against primary interviews with switchgear procurement managers, panel builder operations heads, railway specification engineers, and surface treatment shop technical directors. Bottom-up and top-down triangulation validated segment-level volume estimates across material grades and connection technologies.
Bottom-up modeling anchored forecasts on installation labor cost differentials and replacement cycle timing, while top-down cross-checks incorporated renewable energy deployment pipelines and grid modernization program budgets. Segmentation dimensions included material conductivity grade, connection mechanism type, application environment, and end-user procurement sophistication. CAGRs derived from fitted growth curves against electrification infrastructure investment trajectories, with aluminum substitution elasticity and spring-clamp penetration rates as industry-specific sensitivity inputs.
Inputs from notified body certification databases and EPC contractor procurement systems were available through the study window; gaps in real-time inventory tracking data introduce uncertainty bands around short-term demand volatility estimates. Forecasts reflect assumptions on EU electrification subsidy continuity and REACH substance restriction implementation timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.