
 Americas Optoelectronics Market | 2026-2036
Americas Optoelectronics Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Optoelectronics Market Insights
Modular sensor packaging is repositioning procurement patterns across the Americas optoelectronics supply chain. Panasonic Corporation leverages vertical integration in solid-state lighting modules to control cost structures from wafer to fixture. Samsung Electronics anchors display-grade LED supply for North American consumer electronics brands. II-VI Incorporated specializes in engineered materials for high-power laser diodes serving industrial automation end users.
Americas optoelectronics encompasses semiconductor devices that emit, detect, or modulate light across ultraviolet through infrared wavelengths, typically fabricated from III-V compound semiconductors such as gallium arsenide, gallium nitride, and indium phosphide using metal-organic chemical vapor deposition processes. These components enable optical signal conversion in telecommunications infrastructure, precision sensing in medical imaging systems, and solid-state illumination in automotive forward-lighting assemblies. LED product lines retain the largest installed base across consumer and commercial applications, though optical sensors for industrial automation represent the fastest-expanding revenue pool as factories deploy machine-vision quality control systems. Quantum dot technology commands premium positioning in display backlighting applications where color gamut specifications differentiate tier-one television manufacturers from mass-market competitors.
The US Federal Communications Commission governs spectrum allocation for fiber-optic and free-space optical communication equipment, directly shaping product certification requirements for telecommunications end users. Mexico's national standards body coordinates with US OSHA and EPA frameworks to align workplace safety and hazardous substance rules for cross-border electronics manufacturing facilities. Brazil's national telecommunications regulator enforces equipment-homologation protocols that condition market access for imported optoelectronic components. Stakeholders must track evolving domestic-content thresholds in US semiconductor subsidy programs to calibrate regional production footprints against tariff exposure.
Market Dynamics
The US Inflation Reduction Act is redirecting capital flows across the Americas optoelectronics supply chain, compelling manufacturers to reconfigure regional production footprints to capture domestic-content subsidies while maintaining access to Mexico's integrated electronics clusters.
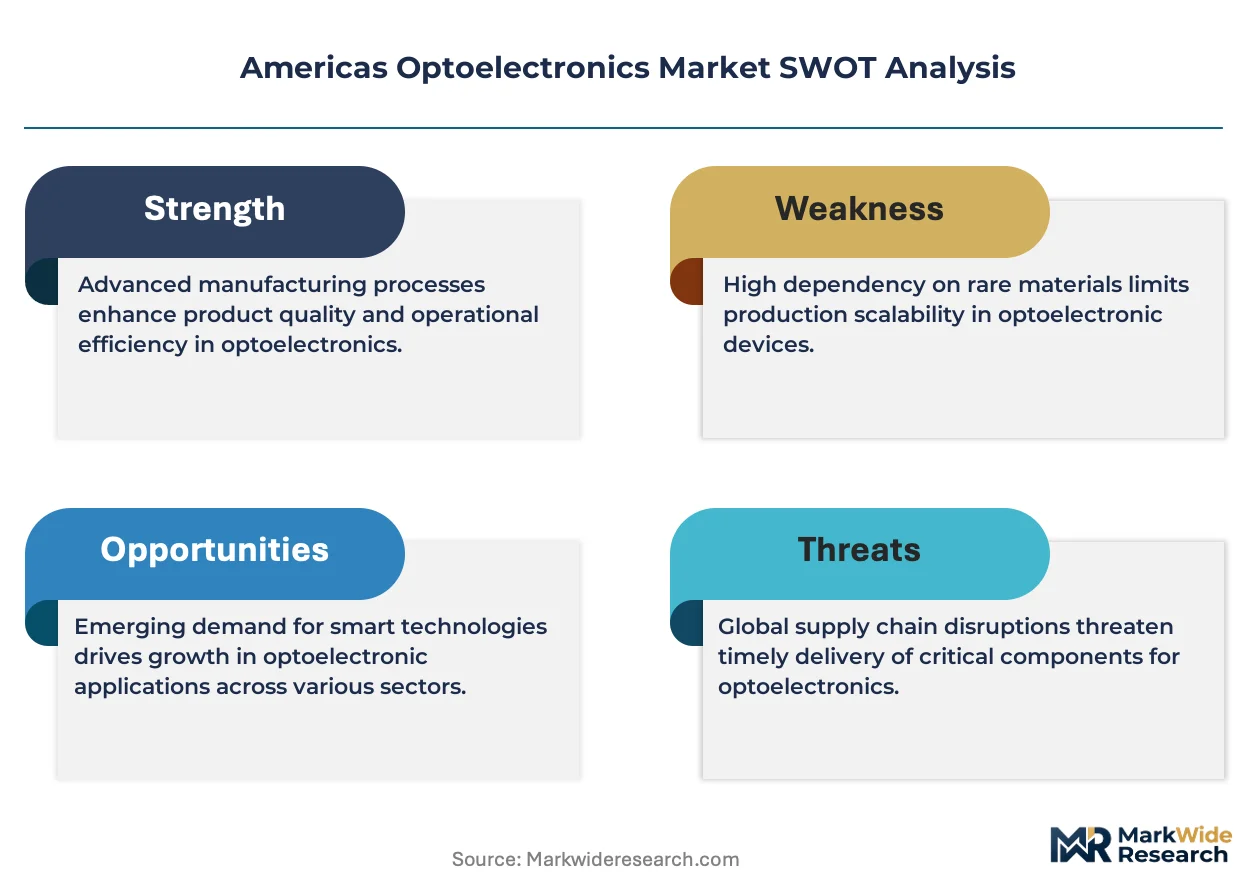
Growth Catalysts
- Automotive LED forward-lighting mandates:NHTSA safety standards and design trends in electric vehicles are accelerating adoption of adaptive matrix LED systems across Detroit Three and transplant OEM assembly plants.
- IRA semiconductor manufacturing incentives:Domestic-content thresholds for federal procurement are pulling wafer fabrication and packaging investments toward Arizona and Texas corridors.
- Machine-vision industrial automation:Factory modernization programs in Mexican border states are expanding demand for high-speed optical sensors in quality-control stations.
Market Restraints
- III-V substrate supply concentration:Gallium arsenide and indium phosphide wafer supply concentrates among a limited set of merchant vendors, exposing buyers to allocation risk during demand surges.
- Metal-organic precursor cost volatility:Trimethylgallium and trimethylindium prices fluctuate with rare earth metal markets, compressing margins for epitaxial foundry operators.
- Homologation friction in Brazil:ANVISA and Anatel certification timelines for imported optoelectronic components extend market entry cycles by six to twelve months versus US or Mexican pathways.
Strategic Opportunities
- Underpenetrated Canadian medical imaging:Provincial health system procurement of optical coherence tomography and endoscopic systems lags US adoption rates by several years, creating white space for component suppliers.
- Quantum dot display convergence:Hybrid integration of cadmium-free quantum dots with mini-LED backlights is opening premium positioning in television and monitor segments.
- Free-space optical communications:FCC spectrum allocation rulings for terrestrial laser links are enabling new last-mile connectivity applications in bandwidth-constrained rural zones.
Industry Challenges
- Compound semiconductor process engineering talent:MOCVD reactor operation and epitaxial growth optimization expertise remains scarce relative to silicon CMOS talent pools, constraining capacity expansion timelines.
- Cross-border customs reconfiguration:USMCA rules-of-origin recertification for optoelectronic subassemblies is forcing inventory repositioning and supplier requalification across Mexican maquiladora networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Optoelectronics Market |
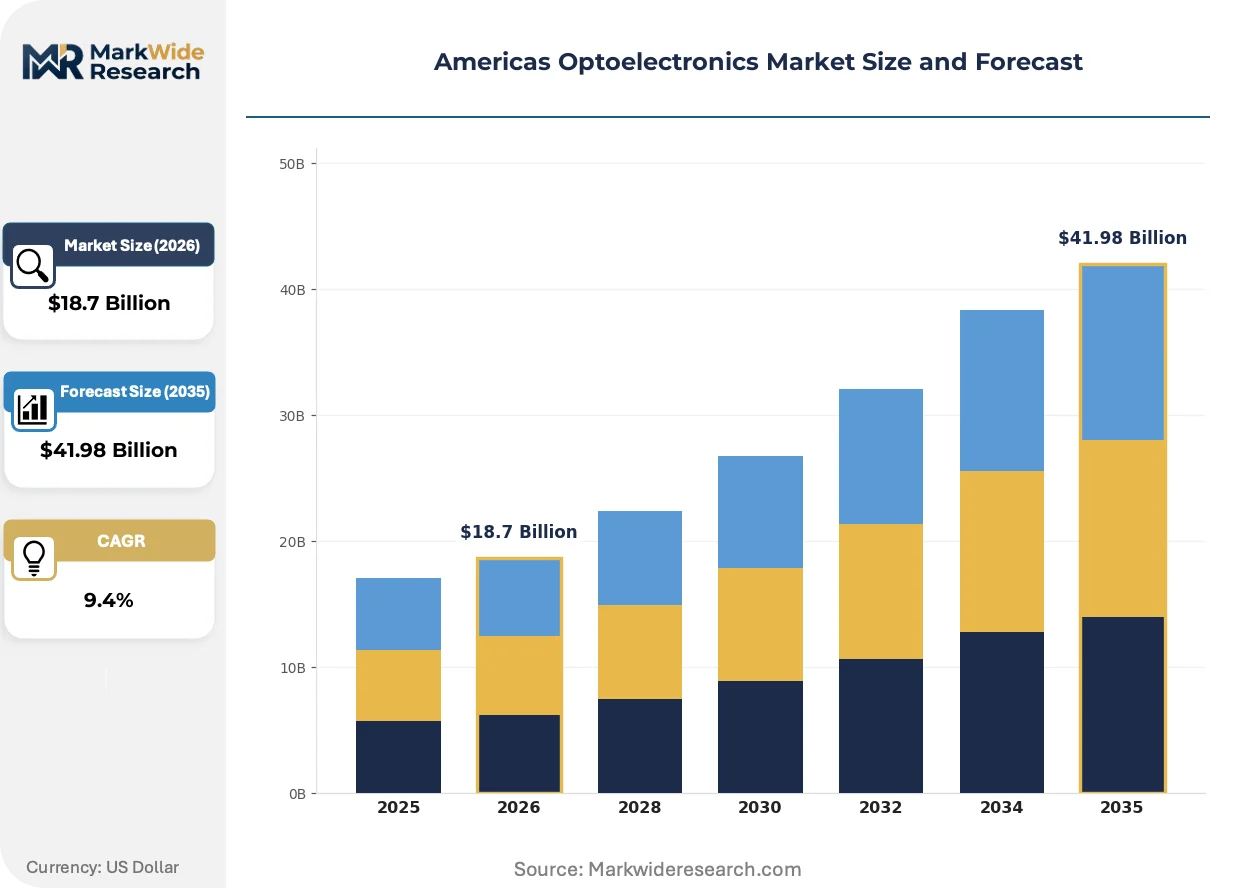
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Laser Diodes, Photodetectors, Optical Sensors Technology: Quantum Dot, Organic Photonics, Fiber Optics, Solid-State Application: Consumer Electronics, Automotive Lighting, Medical Devices, Industrial Automation End User: Retail, Telecommunications, Healthcare, Aerospace |
| Companies Covered | Panasonic Corporation, Samsung Electronics, General Electric Company, Sony Corporation, Omnivision Technologies Inc, II-VI Incorporated, Broadcom Inc, Finisar Corporation, Texas Instruments Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Optoelectronics Market Trends and Innovations
Miniaturization and heterogeneous integration are compressing form factors while expanding functional density across the Americas optoelectronics value chain, with particular momentum in automotive and medical end-use verticals.
Micro-LED display technology is electrifying next-generation visualization architectures. These sub-10-micron emitters enable seamless modular tiling for direct-view displays without backlighting layers. Tier-one consumer electronics brands in the United States are accelerating pilot production lines for augmented-reality near-eye devices and premium television panels. The structural consequence is a compression of the conventional LCD-OLED technology transition timeline, forcing incumbent display manufacturers to accelerate capital redeployment or risk stranded assets.
The US Inflation Reduction Act's domestic-content bonus credits are reshaping sourcing mathematics for federal procurement-eligible optoelectronic systems. Equipment manufacturers must now trace wafer origin through epitaxy, fabrication, and final test to qualify for enhanced tax treatment. Defense and telecommunications infrastructure segments are most affected, with prime contractors demanding certified supply chain documentation from sub-tier photonics vendors previously exempt from such scrutiny.
Consolidated buying by North American automotive OEMs is compressing supplier negotiation cycles and unbundling traditional component-service packages. Tier-one lighting module suppliers now face direct sourcing pressure on discrete LEDs and optical sensors from platform engineering teams, bypassing legacy distribution channels. This pattern is most visible in Detroit and Silicon Valley electric vehicle development centers, where vertical integration into semiconductor procurement is becoming a competitive requirement for program awards.
Americas Optoelectronics Market Segmentation
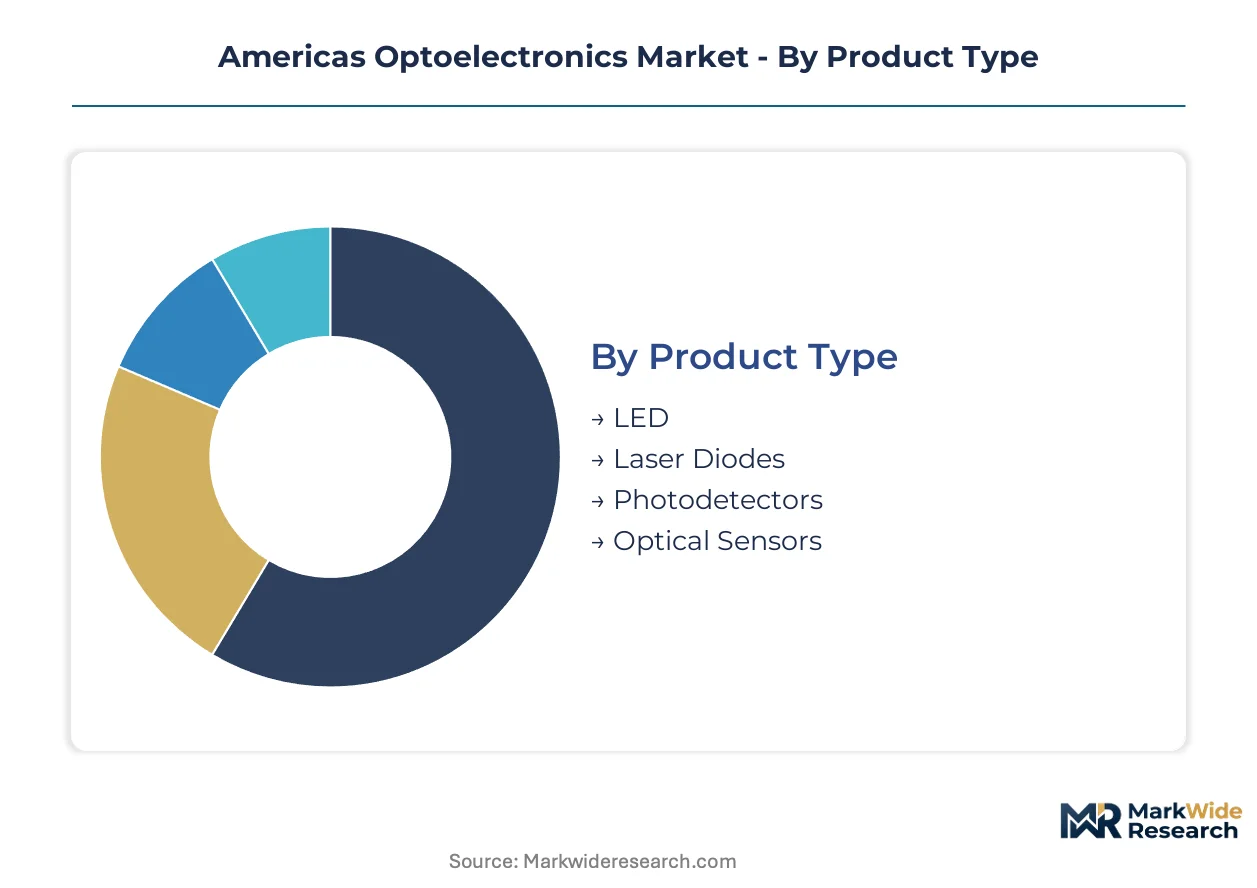
Optoelectronics components serve both standalone illumination roles and deeply embedded sensing architectures across the Americas. Segmentation reveals where value concentrates in discrete packaged devices versus integrated subsystem modules.
Product Type:
Integration depth varies sharply: LEDs and photodetectors frequently operate as discrete surface-mount components, while optical sensors and laser diodes embed into complex multi-chip assemblies.
- LED:Solid-state emitters fabricated on sapphire or silicon carbide substrates dominate forward-lighting and display backlighting volumes. NHTSA headlamp regulations and Detroit Three electric vehicle platforms are pulling specification upgrades toward adaptive matrix configurations in Michigan and Ohio assembly corridors.
- Optical Sensors:Photodiode and image sensor arrays integrate signal conditioning electronics at die level. Mexican border state factories are deploying these for machine-vision quality control in automotive parts inspection lines, with demand scaling alongside USMCA-certified supplier requalification programs.
- Laser Diodes:Edge-emitting and vertical-cavity surface-emitting structures enable precision ranging and fiber-optic transmission.
- Photodetectors:PIN and avalanche photodiodes convert optical signals to electrical current in telecommunications receivers.
LED leads volumes today; optical sensors are gaining share fastest.
Technology:
Cost tiers separate mature epitaxial processes from emerging material systems still scaling manufacturing economics.
- Solid-State:Gallium nitride and gallium arsenide epitaxy on native or engineered substrates commands the largest installed base. Arizona and Texas wafer fabrication corridors are expanding MOCVD reactor capacity to capture IRA domestic-content incentives for federal procurement eligibility.
- Quantum Dot:Colloidal semiconductor nanocrystals enable narrow emission linewidths for display color enhancement. Cadmium-free formulations are qualifying with California Proposition 65 requirements while penetrating premium television backlighting segments.
- Fiber Optics:Doped silica waveguides and erbium-doped fiber amplifiers underpin long-haul telecommunications infrastructure.
- Organic Photonics:Solution-processed organic light-emitting diodes and photovoltaics target flexible form factors.
Solid-state dominates manufacturing throughput; quantum dot shows the steepest expansion trajectory.
Application:
Customer maturity cycles determine whether procurement emphasizes performance specifications or total cost optimization.
- Automotive Lighting:Headlamp and interior illumination modules integrate thermal management, optics, and driver electronics. US transplant OEMs in Tennessee and South Carolina are consolidating supplier bases around vertically integrated module providers capable of traceable semiconductor sourcing.
- Industrial Automation:Machine-vision systems and LiDAR ranging modules demand high-speed photodetection with minimal latency. Mexican electronics manufacturing clusters in Baja California and Chihuahua are expanding optical sensor integration for North American automotive supply chain quality assurance.
- Consumer Electronics:Smartphone camera modules and display backlights drive high-volume packaging requirements.
- Medical Devices:Optical coherence tomography and endoscopic imaging systems require precision wavelength control.
Automotive lighting leads application revenues; industrial automation is climbing the fastest.
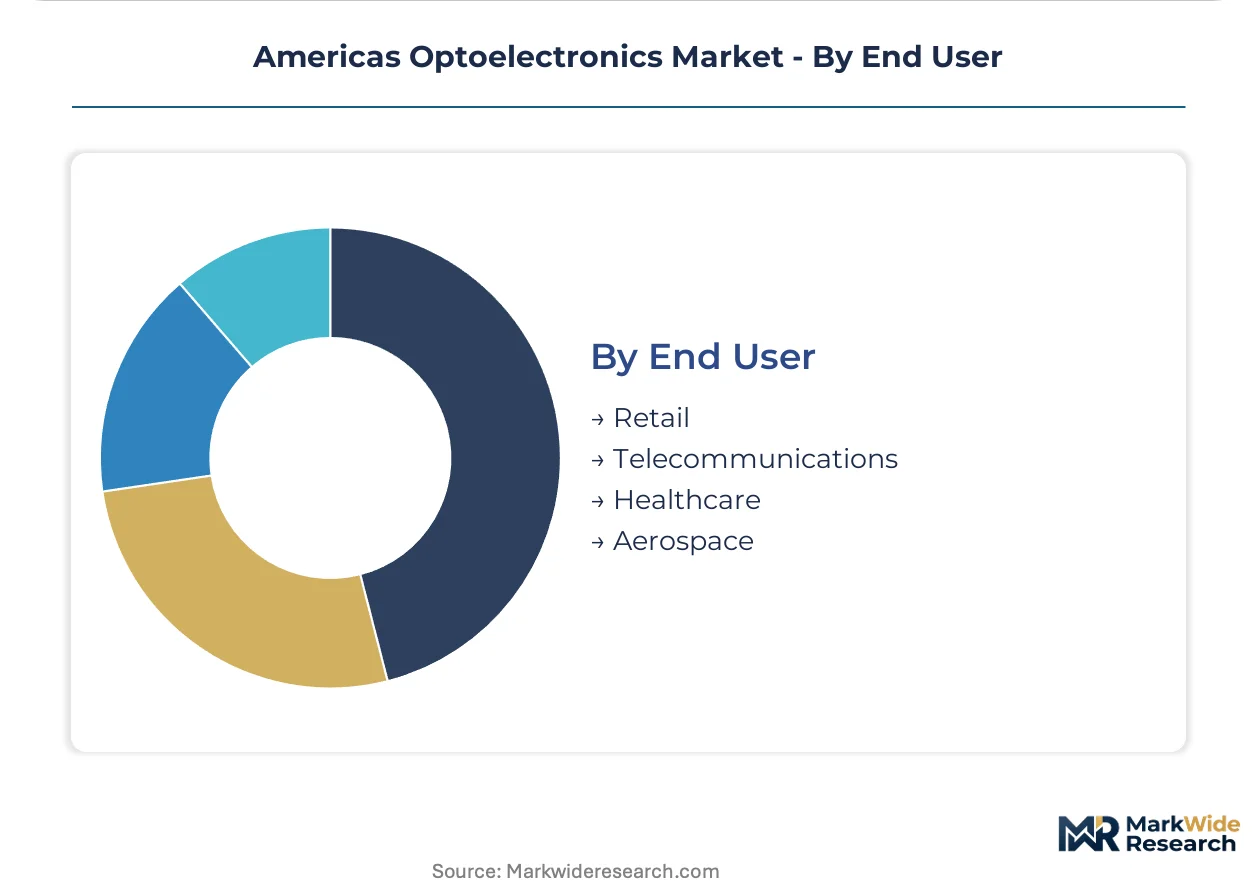
End User:
Volume concentration versus margin potential shapes supplier engagement models across buyer categories.
- Telecommunications:Fiber-optic network equipment and free-space optical links demand high-reliability laser diodes and photodetectors. FCC spectrum allocation rulings for terrestrial laser communications are enabling new last-mile deployment models in bandwidth-constrained rural US zones.
- Healthcare:Diagnostic imaging and surgical visualization systems require certified optical subassemblies. Canadian provincial health system procurement cycles lag US adoption timelines, creating white space for component suppliers targeting Ontario and Quebec hospital network tenders.
- Retail:Digital signage and point-of-sale display systems drive standardized LED module demand.
- Aerospace:Satellite optical communications and avionics sensing require radiation-hardened component qualifications.
Telecommunications anchors procurement scale; healthcare is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optoelectronics manufacturing in the Americas traces its commercial scale to the 1970s semiconductor boom across California and Texas, where early LED and laser diode fabrication established the region's foundational expertise in III-V compound semiconductor processing.
United States
Arizona and Texas wafer fabrication corridors are expanding MOCVD reactor capacity to capture IRA domestic-content incentives for federal procurement eligibility. The FCC governs spectrum allocation for fiber-optic and free-space optical communication equipment, directly shaping product certification requirements. Detroit Three electric vehicle platforms in Michigan and Ohio are pulling specification upgrades toward adaptive matrix LED headlamp configurations.
Mexico
Electronics manufacturing clusters in Baja California and Chihuahua are expanding optical sensor integration for North American automotive supply chain quality assurance. Mexico's national standards body coordinates with US OSHA and EPA frameworks to align workplace safety and hazardous substance rules for cross-border facilities. The maquiladora networks in border states are repositioning inventory and requalifying suppliers under revised USMCA rules-of-origin protocols.
Canada
Provincial health system procurement of optical coherence tomography and endoscopic systems lags US adoption rates, creating white space for component suppliers targeting Ontario and Quebec hospital network tenders. Health Canada and PMRA frameworks govern medical device certification timelines. The Pacific Northwest corridor maintains specialized photonics research concentrations with limited commercial-scale fabrication.
Brazil
ANVISA and Anatel certification timelines for imported optoelectronic components extend market entry cycles by six to twelve months versus US or Mexican pathways. The national telecommunications regulator enforces equipment-homologation protocols that condition market access. São Paulo-based industrial automation distributors serve as gatekeepers for machine-vision component penetration into Latin American manufacturing operations.
Americas Optoelectronics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology specialization and vertical integration depth, with compound semiconductor epitaxy expertise commanding pricing power over standard packaged LED assemblers. The vendor base spans integrated conglomerates with captive wafer fabrication, specialized engineered materials suppliers, and fabless design houses outsourcing production to merchant foundries. Three archetypes dominate: vertically integrated lighting module providers, engineered substrate specialists, and diversified electronics conglomerates with optoelectronic divisions. Capacity expansion in Arizona and Texas corridors and strategic partnerships for quantum dot display integration represent the dominant competitive moves.
Among Asia-Pacific-based conglomerates with Americas market presence, Panasonic Corporation and Samsung Electronics exemplify the vertically integrated archetype with solid-state lighting and display-grade LED capabilities. II-VI Incorporated represents the engineered materials specialization archetype, with its corporate identity signaling focus on compound semiconductor substrates and precision optical components. These three anchors demonstrate how geographic origin and naming conventions signal strategic positioning within the optoelectronics value chain.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Samsung Electronics |
| General Electric Company |
| Sony Corporation |
| Omnivision Technologies Inc |
| II-VI Incorporated |
| Broadcom Inc |
| Finisar Corporation |
| Texas Instruments Inc |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between federal procurement-eligible and commercial-grade optoelectronic components creates parallel pricing architectures that reshape both margin structures and sourcing footprints across the Americas. IRA domestic-content thresholds for enhanced tax treatment force manufacturers to trace wafer provenance through epitaxy and final test, compressing margins on non-compliant tiers while inflating premiums for documented supply chains.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs component transactions, with premium tiers commanding substantial markups for NHTSA-certified automotive modules and FCC-homologated telecommunications gear. Price differentiation rests on traceability documentation depth and thermal performance specifications, not merely brand positioning. Cost compression in economy-grade LED packages is intensifying because Mexican maquiladora networks are absorbing tariff exposure through inventory repositioning. Automotive OEM platform engineering teams exhibit lowest price sensitivity due to liability and warranty requirements, while retail signage buyers negotiate aggressively on volume.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific wafer sources is accelerating regionalization investments across Arizona and Texas MOCVD corridors. Supply concentrates in Japan, Taiwan, and the United States for gallium arsenide and indium phosphide substrates, while trimethylgallium precursors draw from Chinese rare earth processing. Single-source vulnerability in III-V substrate supply exposes buyers to allocation risk during demand surges. Distribution runs through tier-one lighting module suppliers in Detroit and Silicon Valley EV development centers, bypassing legacy distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Americas optoelectronics market compounds steadily as automotive electrification mandates and IRA manufacturing incentives create durable demand tailwinds for compound semiconductor components.
For Market Incumbents: Acquire MOCVD reactor operation expertise through targeted hiring in Arizona and Texas fabrication corridors. Consolidate supplier qualification documentation to defend federal procurement eligibility against emerging foundry competitors. Expand backward integration into engineered substrates to mitigate gallium arsenide allocation risk from Japanese merchant vendors.
For New Entrants and Emerging Players: Distributors serving São Paulo industrial automation clusters represent the most accessible channel for machine-vision component penetration into Latin American manufacturing. Target Canadian provincial health system procurement cycles for optical coherence tomography systems, where adoption lags US timelines by several years. Lead with cadmium-free quantum dot formulations to satisfy California Proposition 65 requirements in premium display backlighting segments.
For Investors and Strategic Acquirers: Consolidation pressure builds where compound semiconductor process engineering talent scarcity constrains capacity expansion timelines. The sector offers viable long-term compounding exposure through vertically integrated module providers capable of traceable semiconductor sourcing. Monitor FCC spectrum allocation rulings for terrestrial laser communications as an inflection indicator for free-space optical component demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Domestic Corridors | Arizona and Texas MOCVD investments capture IRA domestic-content incentives for federal eligibility. |
| Quantum Dot Display Integration | Cadmium-free formulations penetrate premium television segments under California Proposition 65 compliance. |
| Automotive Lighting Module Consolidation | Vertically integrated suppliers secure Detroit Three EV platform awards through traceable LED sourcing. |
| Machine-Vision Sensor Partnerships | Mexican border state factories deploy optical sensors for USMCA-certified automotive quality assurance. |
| Free-Space Optical Communications Development | FCC spectrum rulings enable last-mile connectivity in bandwidth-constrained rural US zones. |
Research Methodology
Coverage spans the United States, Mexico, Canada, and Brazil, with primary inputs from each market informing demand-side validation. The research combines structured interviews with MOCVD reactor operators, tier-one automotive lighting procurement managers, FCC regulatory affairs specialists, and Mexican maquiladora supply chain directors with secondary triangulation across SEC 10-K filings, USMCA customs documentation, FCC equipment authorization databases, and hospital procurement records. Bottom-up component demand modeling and top-down manufacturing capacity assessments were cross-referenced.
Segmentation granularity extends to product type, technology platform, application vertical, and end-user category across the analysis window. CAGRs were derived from installed base evolution and replacement cycle dynamics in automotive forward-lighting, machine-vision industrial automation, and telecommunications infrastructure. Forecast inputs incorporate IRA domestic-content threshold compliance rates and NHTSA adaptive matrix LED adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to III-V substrate supply concentration and rare earth precursor cost volatility. Forecasts reflect documented assumptions about regulatory continuity and trade framework stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Smart Compact Projectors Market
Optoelectronics
Cadmium Telluride Photovoltaic Market
Optoelectronics
Vertical Cavity Surface Emitting Laser (Vcsels) Market
Optoelectronics
Japan Optoelectronics Market
Optoelectronics
Photoluminescent Film Market
Optoelectronics
Laser Projector Market
Optoelectronics
Green Laser Diode Market
Optoelectronics
Gaas Photodiode Market
Optoelectronics
Optoelectronics Market
Optoelectronics
Global Indium Phosphide (Inp) Wafers Market
Optoelectronics
Optoelectronic Transducers Market
Optoelectronics
Quantum Cascade Lasers Market
Optoelectronics
Laser Projection Market
Optoelectronics
Ingaas Avalanche Photodiode Market
Optoelectronics
South Korea Optoelectronics Market
Optoelectronics
China Optoelectronics Market