
 LED Chip Market | 2026-2036
LED Chip Market Size, Share, and Industry Trends Forecast 2026-2036
LED Chip Market Intelligence
China's gallium nitride capacity build-out is rewriting the cost structure for epitaxial wafer supply. Samsung Electronics leverages captive semiconductor fabrication to secure substrate access. Epistar Corporation anchors Taiwan's foundry ecosystem through dedicated LED chip foundry services. San'an Optoelectronics dominates domestic China demand with vertical integration from sapphire ingots to packaged devices.
An LED chip is a semiconductor light source fabricated from gallium nitride or gallium arsenide phosphide on sapphire or silicon carbide substrates, emitting photons through electroluminescence when electrical current passes through a p-n junction, with wavelengths spanning ultraviolet to infrared depending on bandgap engineering. The device serves as the core luminant element in solid-state lighting systems, display backlights, and automotive forward-lighting modules. Mid-power LED chips occupy the volume center of general lighting applications where lumen-per-dollar optimization drives procurement decisions. Micro LED technology leads investment intensity as panel makers pursue self-emissive display architectures for consumer electronics. Flip-chip form factors capture premium margin pools in high-density automotive headlamp arrays where thermal management and beam precision command price premiums.
China's MIIT enforces GB standards for luminous efficacy and rare-earth content in phosphor-converted white LEDs, directly shaping import eligibility for foreign chip suppliers. South Korea's MFDS coordinates with METI-aligned JIS standards to harmonize automotive LED reliability testing protocols across regional supply chains. The EU Ecodesign Directive and F-Gas Regulation constrain mercury-free lighting transitions, accelerating LED retrofit demand in European commercial building stock. Stakeholders must monitor gallium substrate price volatility and regional subsidy shifts as determinants of capacity allocation and sourcing geography.
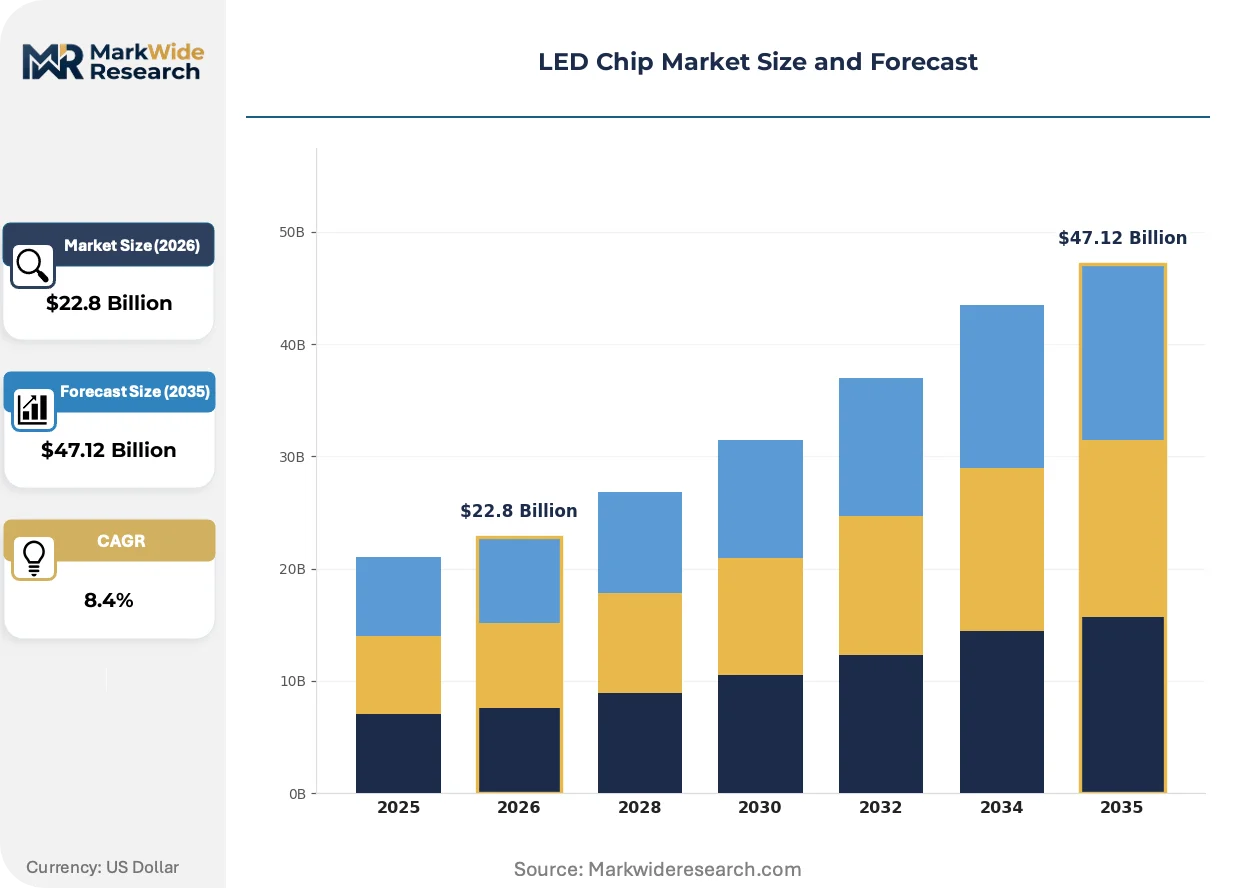
Market Dynamics
China's MIIT efficiency mandates are compressing lumen-per-watt thresholds for domestic procurement eligibility, forcing foreign suppliers to recalibrate epitaxial wafer specifications or exit volume contracts.
Growth Catalysts
- Automotive matrix LED mandates:NHTSA beam-precision standards in the United States and KBA homologation requirements in Germany are compelling OEMs to source high-density flip-chip arrays for adaptive headlamp systems.
- EU F-Gas Regulation:Mercury-free lighting transitions in commercial building retrofit programs are accelerating LED module replacement cycles across European facility management procurement.
- Gallium nitride substrate advances:Epitaxial growth on 8-inch silicon wafers is reducing die-cost structures for mid-power general lighting applications.
Market Restraints
- Rare-earth phosphor dependency:Neodymium and cerium price volatility in Chinese concentrate exports creates input cost instability for warm-white LED chip fabrication.
- Substrate supply concentration:Sapphire ingot production clusters in East Asian manufacturing zones expose downstream fabricators to single-source disruption risk.
- Micro LED yield limitations:Mass transfer defect rates above threshold levels constrain commercial viability for consumer display panel applications.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for semiconductor packaging are attracting LED chip assembly investments targeting domestic lighting and automotive demand.
- LiDAR convergence:Integration of VCSEL arrays with autonomous vehicle sensor suites opens adjacent revenue pools for gallium arsenide epitaxial suppliers.
- Smart city infrastructure:Municipal procurement frameworks for connected streetlight networks in Brazil and Mexico favor suppliers with IoT-ready module architectures.
Industry Challenges
- MOCVD technician scarcity:Metal-organic chemical vapor deposition operation and maintenance expertise concentrates in legacy semiconductor fabrication hubs, constraining greenfield capacity expansion.
- Automotive reliability certification timelines:AEC-Q102 qualification cycles extend months beyond commercial lighting standards, delaying revenue recognition for headlamp chip suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Chip Market |
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $47.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Power LED, Mid-Power LED, Low-Power LED, Chip-on-Board LED Application: General Lighting, Automotive Lighting, Backlighting, Display Lighting Form Factor: Surface-Mounted Device, Through-Hole, Flip-Chip, Package Technology: Quantum Dot, Organic LED, Micro LED, Traditional LED |
| Companies Covered | Samsung Electronics Co., Ltd., Epistar Corporation, Nichia Corporation, San’an Optoelectronics Co., Ltd., Bridgelux, Inc., OSRAM Opto Semiconductors GmbH, Lumileds Holding B.V., Seoul Semiconductor, Cree LED, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Chip Market Strategic Shifts & Innovations
Silicon-based substrate alternatives and regulatory pressure on mercury-containing legacy lighting are compressing technology substitution cycles across multiple end-use verticals simultaneously.
Flip-chip architectures with solder-bump interconnects are rendering obsolete wire-bonded die configurations in automotive forward-lighting modules. Tier-1 headlamp suppliers in Germany and Japan are converting production lines to accommodate thermal management requirements of high-current density arrays. The shift is compressing margin structures for legacy wire-bond equipment suppliers while elevating precision substrate-bonder demand.
China's MIIT enforcement of updated GB standards for luminous efficacy and rare-earth content is disqualifying import shipments that fail wafer-level documentation requirements. Foreign chip suppliers must maintain dual inventory streams—one qualified for domestic Chinese procurement, one for export markets with less stringent phosphor traceability. The regulatory friction most impacts mid-power general lighting suppliers serving multinational fixture manufacturers with unified global product lines.
Consolidated procurement by multinational lighting OEMs is compressing distributor margins and favoring direct foundry relationships with captive substrate access. Procurement teams at major fixture manufacturers are bypassing traditional component distributors to negotiate wafer-level contracts with Taiwan and China-based fabricators. The disintermediation is most advanced in North American commercial building retrofit programs where specification-grade procurement teams possess technical depth for direct supplier qualification.
LED Chip Market Segmentation
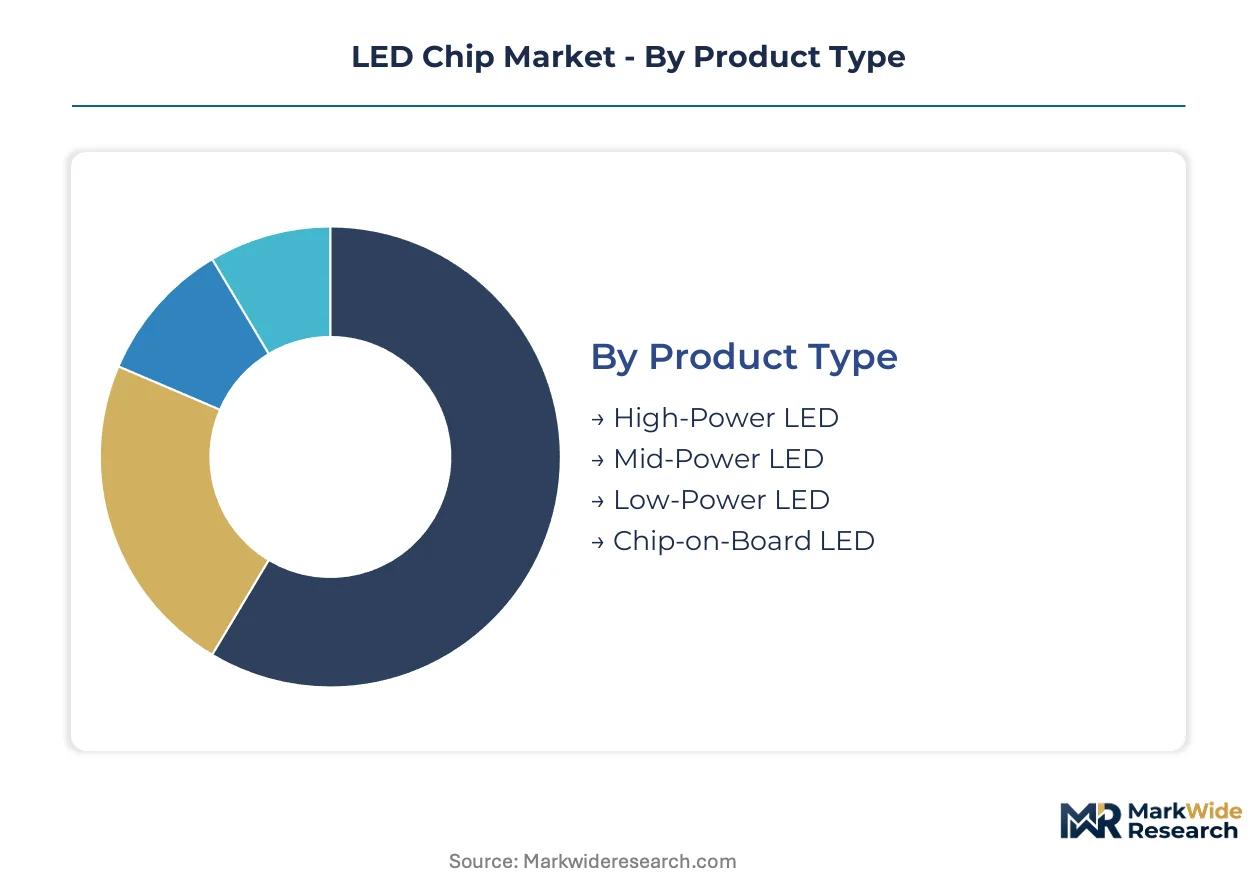
LED chip segmentation reveals divergent margin structures across power classes and form factors. Procurement patterns in automotive and display verticals are fragmenting traditional volume hierarchies established by general lighting demand.
Product Type:
Mature high-power architectures coexist with emerging chip-on-board configurations that challenge conventional packaging economics.
- High-Power LED:Single-die emitters exceeding 1 watt output dominate streetlight and stadium illumination where thermal management systems justify premium die costs. China's municipal procurement in Guangdong and Jiangsu provinces concentrates demand for efficacy-certified modules.
- Mid-Power LED:The volume center of commercial building retrofit programs, these 0.1-0.5 watt devices optimize lumen-per-dollar metrics for troffer and downlight OEMs. Efficiency mandates from China's MIIT are compressing qualified supplier lists for domestic fixture manufacturers.
- Low-Power LED:Indicator and signal applications in consumer electronics and appliance interfaces.
- Chip-on-Board LED:Multi-die arrays directly mounted to metal-core substrates, displacing discrete packaged LEDs in high-bay industrial and horticultural lighting.
Mid-power LED retains volume leadership; chip-on-board LED holds the steepest expansion curve.
Application:
Cost tier stratification separates specification-grade automotive procurement from price-sensitive general lighting contracts.
- General Lighting:Residential, commercial, and industrial fixture demand represents the installed base anchor, with European commercial building retrofits accelerating module replacement cycles under EU F-Gas Regulation compliance deadlines.
- Automotive Lighting:Forward-lighting and interior applications command 3-5x die price premiums over commercial equivalents. NHTSA beam-precision standards and KBA homologation requirements in Germany are mandating matrix LED architectures with flip-chip interconnects.
- Backlighting:LCD panel edge-lighting for televisions and monitors, facing displacement by mini-LED and micro-LED alternatives.
- Display Lighting:Direct-view and signage applications including transparent and flexible form factors.
General lighting retains volume leadership; automotive lighting holds the steepest expansion curve.
Form Factor:
Customer type differentiation separates high-volume surface-mount contracts from precision flip-chip qualifications.
- Surface-Mounted Device:Standardized packages for pick-and-place assembly dominate general lighting and consumer electronics manufacturing. Procurement concentrates with multinational fixture OEMs negotiating direct foundry relationships in Taiwan and China.
- Flip-Chip:Solder-bump interconnects enable high-current density arrays with superior thermal dissipation for automotive headlamp modules. Tier-1 suppliers in Germany and Japan are converting production lines to accommodate these thermal management requirements.
- Through-Hole:Legacy axial and radial leaded configurations for replacement lamp markets and industrial equipment.
- Package:Ceramic and plastic encapsulated discrete devices for standardized socket compatibility.
Surface-mounted device retains volume leadership; flip-chip holds the steepest expansion curve.
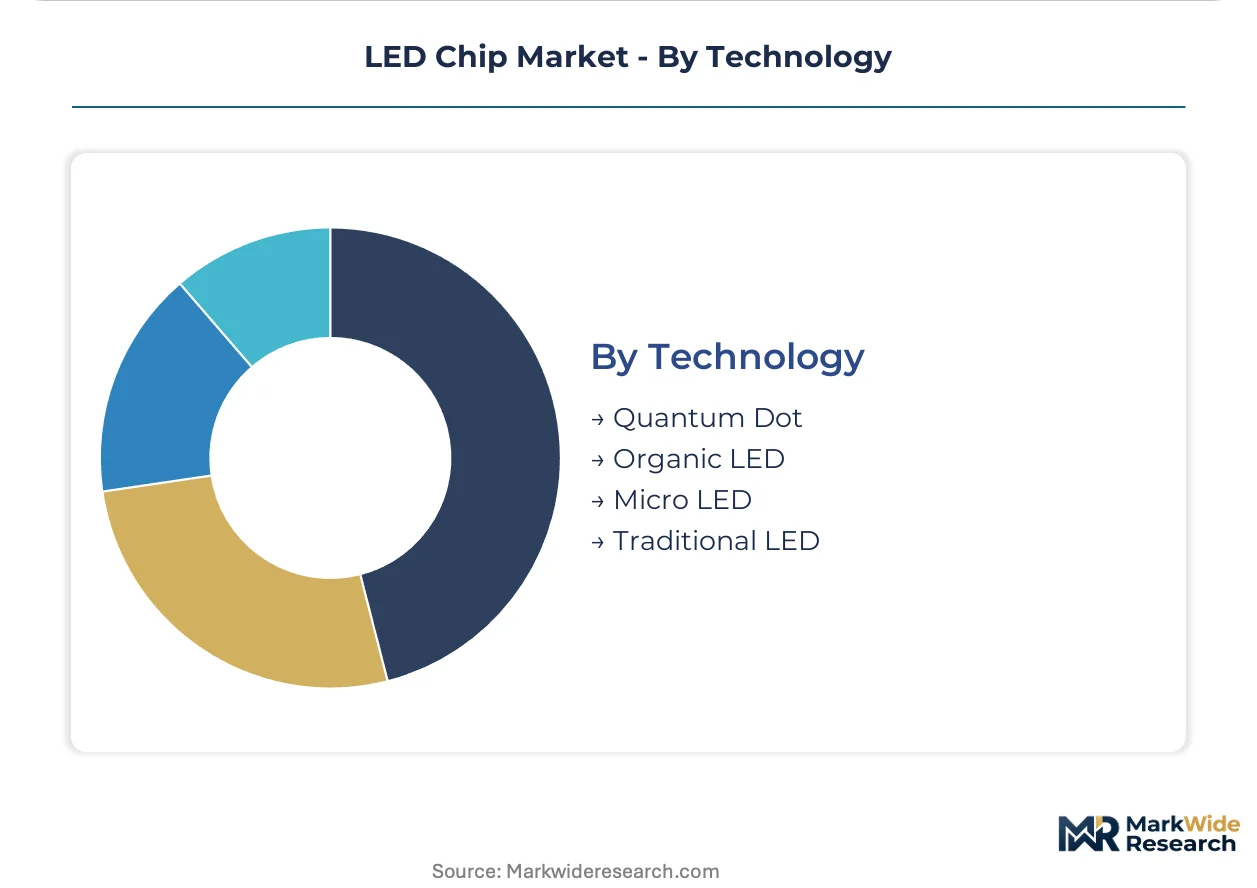
Technology:
Supply concentration in gallium nitride epitaxy favors traditional architectures while micro-LED development strains capital allocation.
- Traditional LED:Gallium nitride and gallium arsenide phosphide p-n junctions on sapphire or silicon carbide substrates anchor current production. San'an Optoelectronics and Epistar Corporation have secured captive substrate access for cost positioning.
- Micro LED:Self-emissive micron-scale emitters for direct-view displays, constrained by mass transfer yield limitations above threshold defect rates. Samsung Electronics and panel makers in South Korea and Taiwan lead investment intensity.
- Quantum Dot:Nanocrystal phosphor conversion for enhanced color gamut in display and lighting applications.
- Organic LED:Small-molecule and polymer electroluminescent devices for flexible and transparent form factors.
Traditional LED retains volume leadership; micro LED holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Epitaxial wafer fabrication concentrates in East Asian manufacturing corridors where gallium nitride substrate capacity and MOCVD technician expertise overlap. China's efficiency mandates, South Korea's display investments, and Japan's automotive certifications are reshaping sourcing geography for multinational fixture manufacturers.
China
Municipal procurement in Guangdong and Jiangsu provinces drives demand for efficacy-certified high-power modules in streetlight infrastructure. MIIT enforces updated GB standards for luminous efficacy and rare-earth phosphor traceability that disqualify import shipments lacking wafer-level documentation. San'an Optoelectronics anchors domestic supply through backward integration from sapphire ingots to packaged devices.
South Korea
Samsung Electronics leverages captive semiconductor fabrication to secure gallium nitride substrate access for display and lighting verticals. MFDS coordinates with METI-aligned JIS standards to harmonize automotive LED reliability testing protocols across regional supply chains. Panel makers in Seoul and Suwon lead investment intensity for micro-LED self-emissive display architectures.
Japan
Nichia Corporation and automotive Tier-1 suppliers concentrate precision flip-chip production for matrix headlamp arrays serving German and US OEM homologation requirements. METI-aligned certification protocols extend AEC-Q102 qualification timelines beyond commercial lighting standards. Nagoya and Osaka industrial corridors host legacy MOCVD expertise constraining greenfield capacity expansion elsewhere.
Germany
KBA homologation requirements mandate adaptive beam-precision standards compelling sourcing of high-density flip-chip interconnects from East Asian fabricators. EU F-Gas Regulation compliance deadlines accelerate LED retrofit cycles in commercial building stock across Bavaria and North Rhine-Westphalia. OSRAM Opto Semiconductors maintains system-tier positioning through automotive forward-lighting module integration.
United States
NHTSA beam-precision standards drive procurement of matrix LED architectures for domestic OEM adaptive headlamp programs. Bridgelux and Cree LED anchor mid-power general lighting supply for commercial building retrofit channels. California and Texas municipal procurement frameworks favor suppliers with IoT-ready connected streetlight module architectures.
LED Chip Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream controlling epitaxial wafer supply and substrate access. The vendor base separates into three strategic archetypes: captive semiconductor fabricators with in-house gallium nitride capacity, dedicated LED chip foundries serving fabless lighting OEMs, and vertical specialists integrating sapphire ingot production through packaged device output. Dominant competitive moves include direct foundry relationships bypassing traditional distributors and capacity expansion targeting 8-inch silicon wafer epitaxy for cost reduction.
Among East Asian fabricators, Samsung Electronics Co., Ltd. and Epistar Corporation exemplify divergent strategic positioning—Samsung leveraging captive semiconductor infrastructure for substrate security, Epistar anchoring Taiwan's foundry ecosystem through dedicated LED chip services. San'an Optoelectronics Co., Ltd. occupies a position within China's domestic supply tier through upstream control over sapphire ingot production. These three entities represent the concentration of gallium nitride epitaxial capacity shaping procurement geography for multinational fixture manufacturers.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| Epistar Corporation |
| Nichia Corporation |
| San'an Optoelectronics Co., Ltd. |
| Bridgelux, Inc. |
| OSRAM Opto Semiconductors GmbH |
| Lumileds Holding B.V. |
| Seoul Semiconductor |
| Cree LED |
| Others |
Cost & Logistics Intelligence
China's gallium nitride substrate concentration anchors margin capture at the epitaxial wafer tier, forcing downstream LED chip fabricators to absorb cost volatility or cede pricing power to captive suppliers. This upstream chokepoint stratifies procurement economics across automotive, display, and general lighting verticals.
Pricing Analysis
China's MIIT efficiency mandates dictate the pricing tier structure across domestic procurement eligibility, separating efficacy-certified premium tiers from non-compliant economy shipments. Three-tier pricing structure across AEC-Q102 automotive, MIIT-certified commercial, and uncertified economy levels reflects certification investment and thermal performance differentiation. Cost compression in mid-power general lighting intensifies because multinational fixture OEMs negotiate direct foundry contracts bypassing distributor markups. Commercial building retrofit programs exhibit highest price sensitivity due to lumen-per-dollar procurement metrics, while automotive forward-lighting modules command lowest sensitivity given homologation-driven specification requirements.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk assessment for gallium nitride epitaxial wafer procurement. Substrate fabrication concentrates in China, South Korea, and Japan where MOCVD equipment clusters overlap with rare-earth phosphor processing capabilities. Raw material dependencies draw from sapphire ingot production, gallium metal refining, and cerium-doped phosphor concentrates. Single-source vulnerability persists for 8-inch silicon wafer epitaxy equipment constrained by technician scarcity in legacy fabrication hubs. Distribution runs through direct foundry relationships with Taiwan and China-based fabricators, displacing traditional component distributors in specification-grade procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
LED chip demand sits at early-cycle expansion as automotive matrix LED mandates penetrate mid-tier vehicle platforms and micro-LED development accelerates display vertical substitution.
For Market Incumbents: Insulate substrate access through captive gallium nitride capacity or long-term wafer supply agreements with East Asian foundries, as China's MIIT documentation requirements threaten import eligibility for non-integrated suppliers. Prioritize AEC-Q102 certification investment to defend automotive margin pools against emerging flip-chip specialists. Deepen backward integration into sapphire ingot production to offset rare-earth phosphor price volatility. For New Entrants and Emerging Players: India's PLI scheme for semiconductor packaging offers the most penetrable white-space target, with domestic lighting and automotive demand outpacing local assembly capacity. Municipal procurement frameworks in Brazil and Mexico for IoT-ready connected streetlight networks present secondary entry points with lower qualification barriers than automotive tiers. Pursue partnership-based go-to-market models with established fixture OEMs rather than direct foundry competition. For Investors and Strategic Acquirers: Capital is best deployed toward captive semiconductor fabricators with in-house gallium nitride substrate access and established MIIT qualification pathways. Long-term viability over the coming decade hinges on positioning for micro-LED mass transfer yield breakthroughs and automotive LiDAR convergence with VCSEL array integration. Monitor MOCVD technician training pipeline expansion as the inflection signal for greenfield capacity feasibility outside legacy East Asian hubs.| Strategic Initiative | Industry Significance |
|---|---|
| 8-inch Silicon Wafer Epitaxy Scale-Up | Reduces die-cost structures for mid-power general lighting procurement in China. |
| AEC-Q102 Certification Investment | Unlocks automotive headlamp module supply contracts with German and US OEMs. |
| Direct Foundry Relationship Establishment | Bypasses distributor margins for multinational fixture manufacturer procurement teams. |
| Micro-LED Mass Transfer Yield Improvement | Enables commercial viability for Samsung Electronics and Taiwan panel maker display architectures. |
| LiDAR VCSEL Array Integration | Opens adjacent revenue pools for gallium arsenide epitaxial suppliers in autonomous vehicle sensor suites. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC filings, customs and trade data, and regulatory submission databases including FDA, EMA, and NMPA records. Interviews with MOCVD equipment engineers, automotive Tier-1 procurement leads, lighting fixture OEM specification teams, and gallium substrate supply specialists informed demand-side validation. Secondary sources encompass MIIT GB standard documentation, EU Ecodesign Directive compliance filings, and IEA energy efficiency program data. Bottom-up wafer fabrication capacity modeling triangulates against top-down end-use demand aggregation across automotive, display, and general lighting verticals.
Forecast inputs span power class segmentation, form factor adoption curves, and technology substitution rates across the projection horizon. Analytical framework models general lighting, automotive lighting, backlighting, and display lighting applications alongside high-power, mid-power, low-power, and chip-on-board product tiers. CAGRs derive from regression analysis of historical capacity utilization against regulatory mandate implementation timelines. Gallium nitride substrate price trajectories and MOCVD equipment deployment schedules constitute industry-specific forecast inputs.
Practitioners should monitor rare-earth phosphor export restrictions, MIIT GB standard revision cycles, and micro-LED mass transfer yield breakthroughs for early signals requiring forecast adjustment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Europe LED Lighting Market
LED
LED Encapsulation Market
LED
Surface Mount PLCC Leds Market
LED
China Outdoor LED Lighting Market
LED
France LED Lighting Market
LED
Bluetooth LED Bulb Market
LED
China Indoor LED Lighting Market
LED
Monochrome Outdoor LED Display Market
LED
LED Lamp Market
LED
LED Display Control Card Market
LED
Brazil LED Market
LED
Germany Outdoor LED Lighting Market
LED
UK LED Lighting Market
LED
Global Chip Scale Package (CSP) LED Market
LED
China LED Market
LED
Mini LED Display Market