
 China LED Market | 2026-2036
China LED Market Size, Share, and Industry Trends Forecast 2026-2036
China LED Market Intelligence
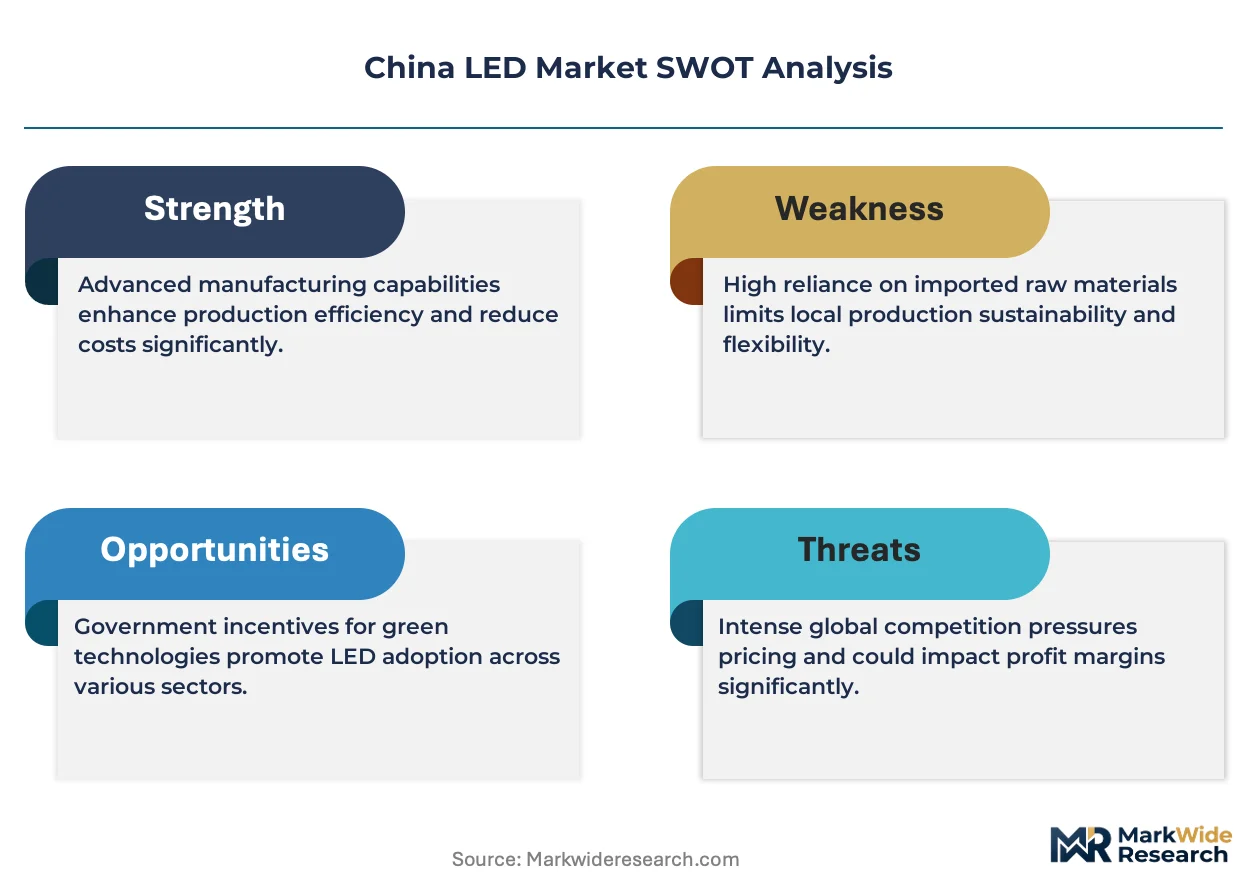
Guangdong province's LED chip foundry capacity is decoupling from downstream packaging operations as manufacturers pursue geographic specialization. MLS Co., Ltd leverages full vertical integration from sapphire substrate growth to finished module assembly, sustaining cost advantages across high-volume orders. NVC Lighting anchors its position through extensive distributor networks in tier-two and tier-three cities, while Opple Lighting differentiates via premium residential fixture design and smart home interoperability.
China LED refers to solid-state semiconductor devices that emit visible, infrared, or ultraviolet light when electrical current flows through a p-n junction, typically fabricated on gallium nitride or indium gallium nitride epitaxial layers on sapphire or silicon carbide substrates, with luminous efficacy ratings now routinely exceeding 150 lumens per watt in commercial products. These devices serve as energy-efficient replacements for incandescent and fluorescent sources across general illumination, display backlighting, and automotive signaling applications. LED Panels command the largest revenue share among product types due to their ubiquity in commercial ceiling retrofits, while Micro LED represents the fastest-expanding technology segment as domestic fabs race to solve mass transfer yield challenges for consumer display applications. Outdoor Lighting applications generate the highest average selling prices per fixture, creating concentrated margin pools for contractors and OEMs serving municipal infrastructure bids.
China's Ministry of Industry and Information Technology sets mandatory energy efficiency grades under GB 30255 for LED products, while the Ministry of Ecology and Environment enforces dual carbon targets that phase out mercury-containing legacy lighting and accelerate LED substitution timelines. SAMR market surveillance audits enforce compliance with these standards at retail and import checkpoints, creating non-tariff barriers for non-compliant products. Stakeholders must monitor whether Beijing extends carbon intensity benchmarks from power generation into manufacturing processes, as this would reshape supplier qualification criteria for state-backed infrastructure tenders.
Market Dynamics
China's LED sector faces a structural squeeze between MIIT's tightening GB 30255 efficacy mandates and the capital intensity required for Micro LED mass transfer commercialization, forcing manufacturers to prioritize either compliance-driven volume or frontier technology bets.
Growth Catalysts
- Dual carbon targets:MEE enforcement accelerates mercury lamp phase-outs and creates replacement demand across municipal streetlight networks. Provincial procurement offices now weight lifecycle carbon metrics in tender scoring.
- Smart city infrastructure:Guangdong, Jiangsu, and Zhejiang province governments bundle LED retrofits with IoT sensor deployment, expanding fixture specifications to include power-over-Ethernet and dimming compatibility.
- GaN-on-silicon epitaxy:Domestic equipment makers are scaling 200mm silicon substrate capacity, reducing sapphire-dependent supply chains and cutting chip fabrication costs for mid-power applications.
Market Restraints
- Sapphire substrate concentration:Four domestic suppliers control high-purity alumina refining, creating input cost volatility when Australian bauxite export quotas tighten.
- Micro LED yield barriers:Mass transfer defect rates above 0.1% prevent consumer display economics from matching OLED alternatives in television panels.
- GB standard compliance friction:SAMR market surveillance audits impose retrofit costs on legacy packaging lines unable to meet luminous efficacy tier-1 thresholds without chip architecture redesign.
Strategic Opportunities
- Agricultural horticulture lighting:Sunless vertical farming installations in Sichuan and Shandong provinces seek tunable spectrum fixtures, creating premium demand outside commoditized general illumination.
- Automotive headlamp modules:Domestic EV manufacturers specify adaptive driving beam systems, opening tier-1 supplier qualification for LED module houses with AEC-Q102 certification capability.
- Health and circadian lighting:Hospital renovation budgets in tier-one cities now specify melanopic lux metrics, requiring fixture vendors to integrate tunable white control systems.
Industry Challenges
- Compound semiconductor process engineering:Epitaxial growth technicians with MOCVD reactor experience command compensation premiums that strain mid-tier foundry operating margins.
- Legacy fluorescent fixture interoperability:Retrofit projects in aging commercial buildings encounter ballast compatibility failures that extend installation timelines and trigger contractor penalty clauses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China LED Market |
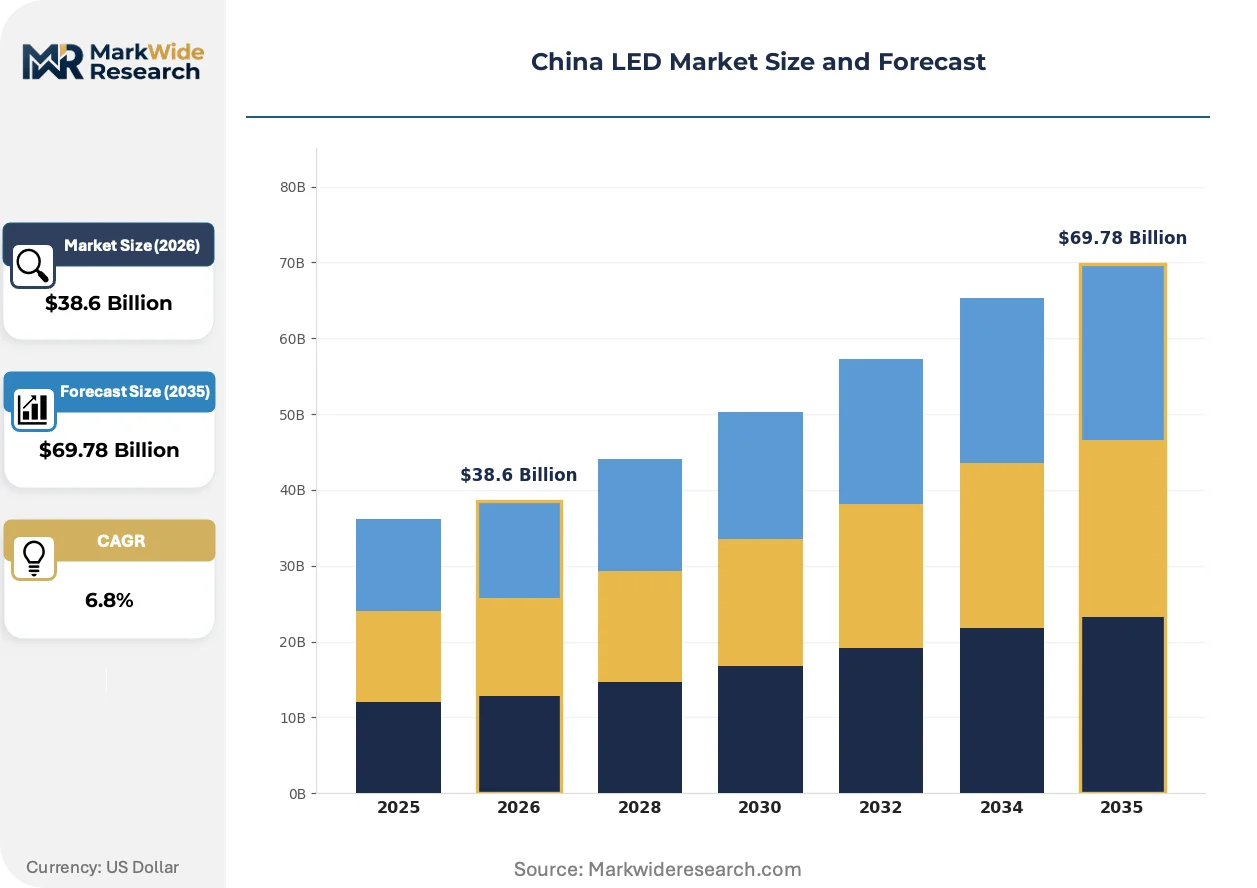
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Bulbs, LED Panels, LED Strips, LED Downlights Application: Residential Lighting, Commercial Lighting, Industrial Lighting, Outdoor Lighting Technology: OLED, QLED, Mini LED, Micro LED End User: Retailers, OEMs, Contractors, Architects |
| Companies Covered | MLS Co., Ltd, Leedarson, NVC Lighting, TCL Lighting, Kingsun Optoelectronic, Opple Lighting, Yankon Group, Huayi Lighting, FSL Lighting, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China LED Market Strategic Shifts & Innovations
Active matrix driving schemes and miniaturized optical engines are compressing form factors while expanding addressable applications beyond traditional illumination into spatial computing and precision agriculture.
Mini LED backlighting is integrating quantum dot color conversion layers to achieve DCI-P3 gamut coverage exceeding 95% in professional monitor panels. Television OEMs in Guangdong province are adopting this architecture at 65-inch and larger diagonal sizes to differentiate against OLED price erosion. The technology is integrating local dimming zones numbering in the thousands, enabling contrast ratios that satisfy broadcast colorist workstation specifications.
MIIT's revised GB 30255-2024 standard tightens minimum luminous efficacy thresholds for general illumination products by 15% versus the 2019 revision. Manufacturers serving state-backed infrastructure tenders must redesign thermal management systems to maintain lumen maintenance at elevated operating temperatures. Outdoor luminaire suppliers in Shenzhen's industrial cluster are responding by migrating from aluminum die-cast housings to graphene-enhanced polymer composites.
Hospital procurement offices in Beijing and Shanghai are unbundling fixture supply from installation and commissioning services, creating direct relationships with LED module houses that bypass traditional distributor markups. This disintermediation compresses project margins for full-service contractors while rewarding manufacturers with in-house application engineering teams. The shift is most visible in healthcare verticals where clinical lighting specifications require photometric validation reports that distributors cannot generate internally.
China LED Market Segmentation
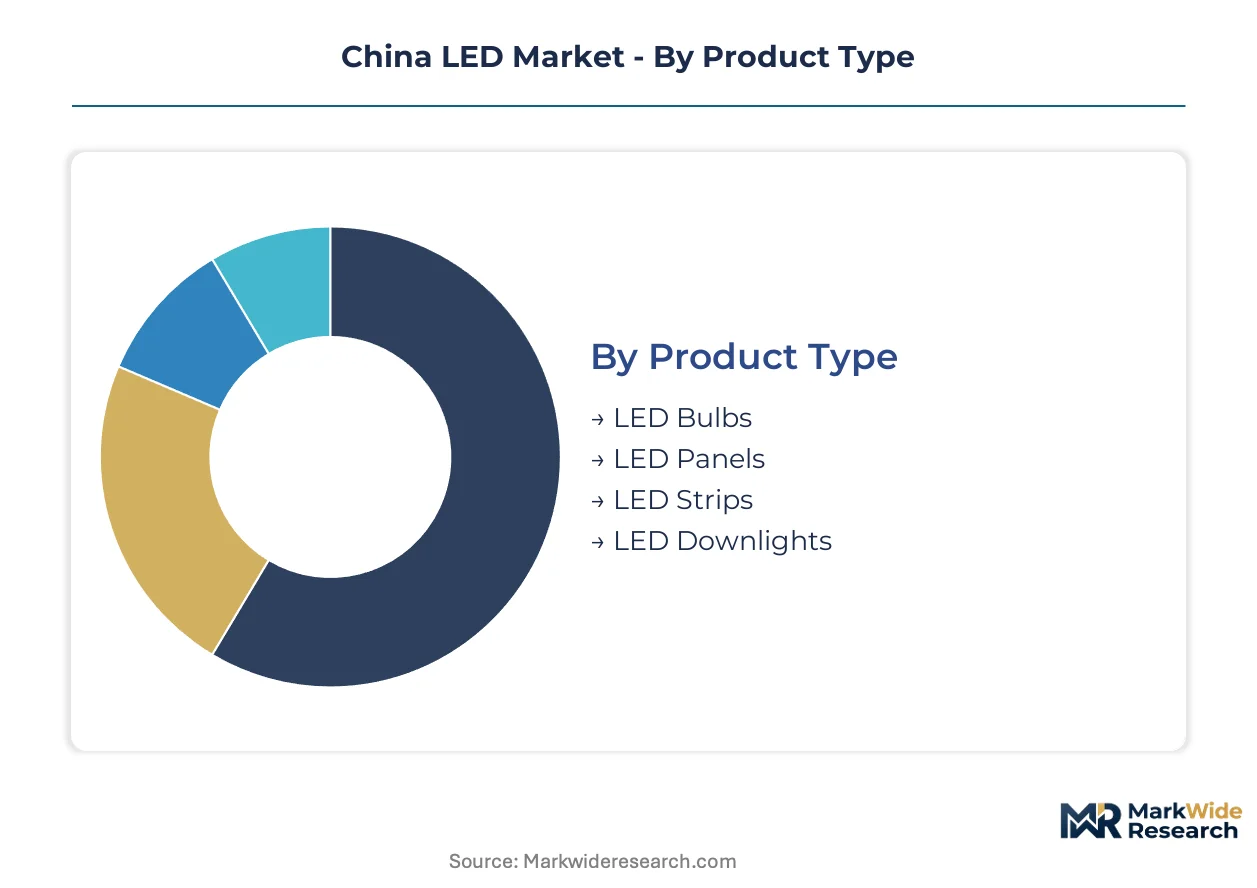
Segmentation in China's LED market determines which manufacturers qualify for state-backed tenders versus commercial retail channels. MIIT's GB 30255 efficacy grades and MEE carbon intensity benchmarks create divergent compliance burdens across product categories, reshaping competitive positioning.
Product Type:
LED Bulbs and LED Panels carry mandatory GB 30255 tier-1 certification for municipal procurement eligibility, while LED Strips and LED Downlights face lighter surveillance audit frequency from SAMR.
- LED Bulbs:Standardized A19 and PAR form factors with screw-base or bayonet interfaces, typically delivering 800-1600 lumens from mid-power chip-on-board arrays. Demand concentrates in Jiangsu province's tier-three city retrofit programs, where provincial procurement offices mandate lumen maintenance above 90% at 25,000 hours.
- LED Panels:Rectangular surface-mount fixtures integrating edge-lit or direct-lit optical architectures, dominating commercial ceiling retrofits in Guangdong province's aging office stock. Shenzhen's industrial cluster supplies 600x600mm and 1200x600mm standards with power-over-Ethernet compatibility for smart building integration.
- LED Strips:Flexible printed circuit boards populated with low-power 2835 or 5050 packages, serving architectural accent and cove lighting applications.
- LED Downlights:Recessed ceiling fixtures with integrated thermal management, penetrating premium residential developments in Zhejiang province.
Leading the category by volume: LED Panels. Growing fastest: LED Bulbs.
Application:
Cost tier stratification separates Outdoor Lighting's premium fixture economics from Residential Lighting's commoditized replacement cycles.
- Residential Lighting:Replacement-driven demand for bulbs and decorative fixtures in urban apartment renovations, with Opple Lighting and NVC Lighting competing through distributor networks in tier-two cities.
- Commercial Lighting:Office and retail retrofit specifications requiring DALI dimming compatibility and unified glare ratings below 19, concentrated in Beijing and Shanghai central business district renovations.
- Industrial Lighting:High-bay fixtures for manufacturing floors and warehouses, where IP65 ingress protection and 50,000-hour lumen maintenance justify premium pricing over fluorescent alternatives.
- Outdoor Lighting:Street and area luminaires with adaptive control systems, generating the highest average selling prices per fixture through Guangdong, Jiangsu, and Zhejiang smart city infrastructure bundles.
Highest margin pool: Outdoor Lighting. Steepest expansion trajectory: Commercial Lighting.
Technology:
Volume concentration sits with mature packaged LED architectures, while frontier display technologies command development-stage capital allocation.
- OLED:Organic electroluminescent panels for premium residential ambient lighting and automotive interior applications, limited by shorter operational lifespans versus inorganic alternatives.
- QLED:Quantum dot-enhanced liquid crystal displays with LED edge backlighting, penetrating Guangdong television OEM portfolios at 65-inch and larger diagonals.
- Mini LED:Thousands of local dimming zones integrated with quantum dot color conversion layers, achieving DCI-P3 gamut coverage exceeding 95% in professional monitor panels.
- Micro LED:Chip-scale devices requiring mass transfer assembly with defect rates above 0.1% currently preventing consumer television economics from matching OLED alternatives.
Dominant by shipment volume: Mini LED. Gaining share fastest: Micro LED.
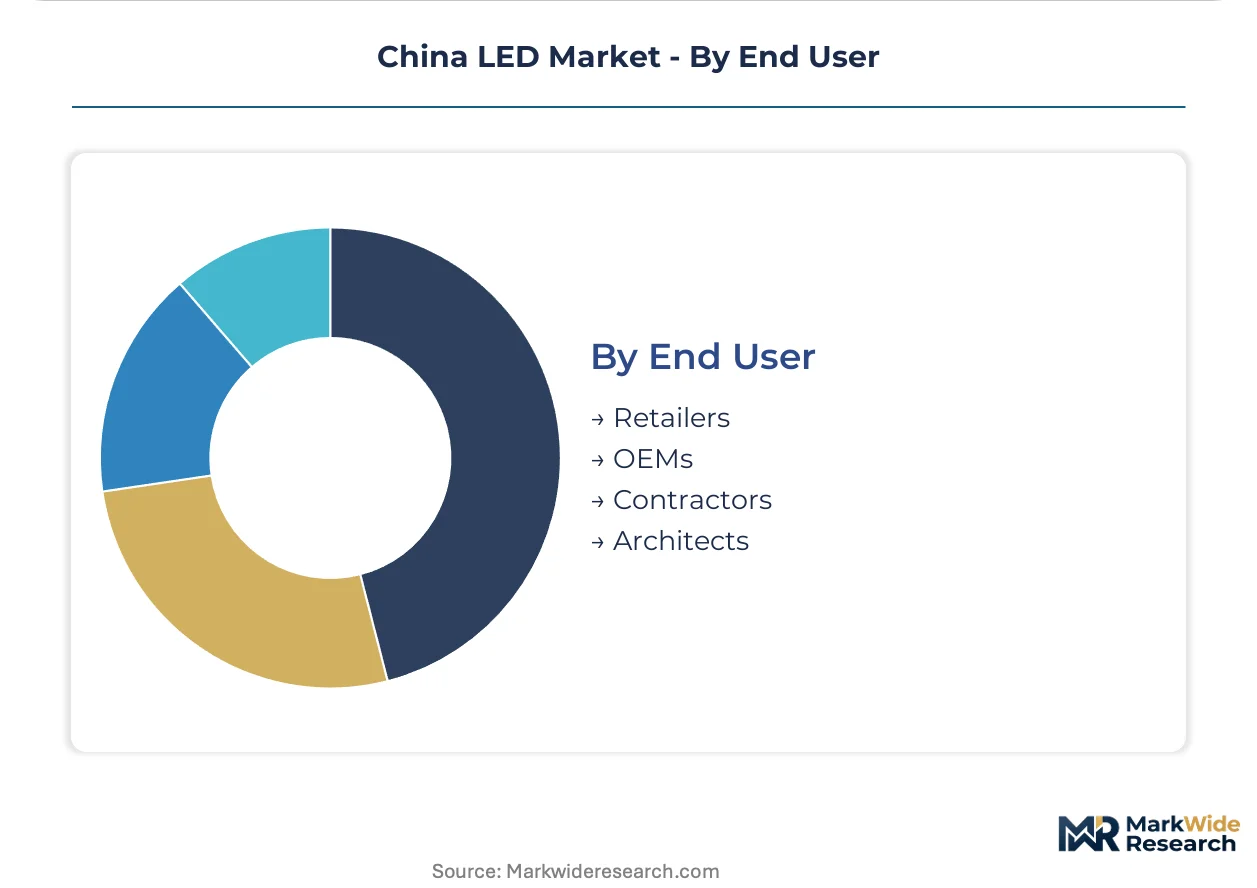
End User:
Customer type determines specification authority and procurement route, with Contractors controlling infrastructure project award decisions while Architects influence premium commercial specifications.
- Retailers:Consumer-facing channels including e-commerce platforms and home improvement chains, stocking GB 30255 tier-2 and tier-3 products for price-sensitive replacement demand.
- OEMs:Original equipment manufacturers integrating LED modules into finished luminaires, televisions, and automotive systems, requiring AEC-Q102 certification for automotive tier-1 qualification.
- Contractors:Installation and project management firms bidding municipal streetlight and commercial retrofit contracts, where lifecycle carbon metrics now weight tender scoring in provincial procurement offices.
- Architects:Design professionals specifying melanopic lux and circadian metrics for healthcare and educational renovations in Beijing and Shanghai, creating direct relationships with module houses that bypass distributor markups.
Largest transaction size: Contractors. Expanding most quickly: Architects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian bauxite export quotas anchor sapphire substrate supply chains for Guangdong epitaxial foundries. Provincial procurement offices across eastern China weight lifecycle carbon metrics in tender scoring. Shenzhen's industrial cluster dominates vertical integration from substrate growth through fixture assembly.
Guangdong Province
Shenzhen's LED industrial cluster concentrates sapphire substrate refining and chip-on-board packaging operations. MIIT's GB 30255-2024 efficacy mandates force thermal management redesigns for outdoor luminaire suppliers. Dongguan manufacturers migrate from aluminum die-cast housings to graphene-enhanced polymer composites for state-backed infrastructure tenders.
Jiangsu Province
Tier-three city retrofit programs drive standardized A19 and PAR bulb demand with 25,000-hour lumen maintenance requirements. Provincial procurement offices bundle LED retrofits with IoT sensor deployment for smart city infrastructure. Suzhou packaging houses face SAMR audit pressure to meet tier-1 luminous efficacy thresholds without chip architecture overhaul.
Zhejiang Province
Premium residential developments specify recessed downlights with integrated thermal management for urban apartment renovations. Ningbo distributors serve tier-two city replacement cycles through extensive retail networks. Hangzhou fixture vendors integrate tunable white control systems for melanopic lux specifications in healthcare renovations.
Sichuan Province
Sunless vertical farming installations seek tunable spectrum fixtures for agricultural horticulture lighting applications. Chengdu module houses develop photometric validation capabilities to bypass traditional distributor markups. Local MEE enforcement accelerates mercury lamp phase-outs across municipal greenhouse networks.
Shandong Province
Industrial high-bay fixture demand concentrates in Qingdao manufacturing floors requiring IP65 ingress protection. Provincial carbon intensity benchmarks reshape supplier qualification criteria for state-backed infrastructure tenders. Jinan packaging lines invest in MOCVD reactor capacity to address compound semiconductor technician scarcity.
China LED Market Key Industry Players
Global majors compete with regional champions across cost structure and compliance certification dimensions. The vendor base stratifies between full-stack integrators and specialized module houses. Three archetypes dominate: vertically integrated foundries controlling substrate-to-assembly workflows, distributor-anchored brands serving tier-two city retail networks, and premium fixture designers targeting smart home interoperability. Capacity expansion and portfolio diversification constitute the dominant competitive moves as manufacturers balance GB 30255 compliance against Micro LED development bets.
Among vertically integrated specialists, MLS Co., Ltd occupies a position exemplifying captive supply chain control from sapphire growth through finished module assembly. NVC Lighting and Opple Lighting represent contrasting archetypes within the branded luminaire tier, with the former anchoring extensive distributor penetration in secondary urban markets and the latter sitting within the premium residential segment emphasizing design differentiation. These three entities illustrate the strategic divergence between cost-driven volume positioning and specification-driven margin capture.
| Leading Market Players |
|---|
| MLS Co., Ltd |
| Leedarson |
| NVC Lighting |
| TCL Lighting |
| Kingsun Optoelectronic |
| Opple Lighting |
| Yankon Group |
| Huayi Lighting |
| FSL Lighting |
| Others |
Cost & Logistics Intelligence
Captive sapphire substrate production from Australian bauxite refining anchors Guangdong foundries' cost position and insulates tier-1 suppliers from alumina price volatility when export quotas tighten. This backward integration into high-purity alumina refining concentrates pricing power among four domestic suppliers while forcing mid-tier packaging houses to absorb input cost swings or surrender municipal tender eligibility.
Pricing Analysis
Warranty and commissioning service bundling separates full-service contractors from module-only suppliers in hospital and infrastructure verticals. Three-tier pricing structure across premium, standard, and economy levels tracks GB 30255 certification grades, with tier-1 efficacy thresholds commanding 15-20% premiums in provincial procurement scoring. Price differentiation stems from lumen maintenance guarantees and smart city IoT compatibility. Cost compression in mid-power general illumination is intensifying because GaN-on-silicon epitaxy is displacing sapphire-dependent architectures. Tier-three city retrofit programs exhibit highest price sensitivity; healthcare circadian lighting specifications show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from television manufacturers in Guangdong, while distributor networks serve tier-two city replacement cycles through NVC Lighting and Opple Lighting retail footprints. Geographic supply concentration centers on China for epitaxial wafer fabrication, Australia for bauxite refining, and Taiwan for MOCVD equipment. Raw material dependencies include high-purity alumina, gallium metal, and silicon carbide substrates. Single-source vulnerability sits with Australian bauxite export quotas. Distribution runs through Shenzhen's vertically integrated industrial cluster for state-backed tenders and Ningbo distributor hubs for residential replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Epitaxial foundry capacity for Micro LED mass transfer is constraining frontier technology supply and propping pricing for qualified tier-1 suppliers in state-backed infrastructure tenders.
For Market Incumbents: Anticipate MIIT's extension of carbon intensity benchmarks into manufacturing processes by securing graphene-enhanced polymer composite supply agreements before qualification criteria shift. Defensive consolidation moves include captive MOCVD technician training programs to offset compensation premiums and direct hospital procurement relationships that bypass distributor markups. The threat of OLED price erosion in consumer displays demands accelerated Mini LED backlighting penetration in professional monitor panels. For New Entrants and Emerging Players: Distributor partnerships in Sichuan and Shandong agricultural horticulture lighting offer the most penetrable white-space target, as sunless vertical farming specifications remain unconsolidated. Agricultural tunable spectrum fixtures and automotive AEC-Q102-certified headlamp modules represent adjacent expansion corridors. Go-to-market execution should anchor on photometric validation capabilities that satisfy hospital procurement office unbundling trends. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by vertically integrated foundries seeking module house capabilities. Long-term viability across the analysis window favors entities with in-house epitaxial growth and GB 30255 tier-1 certification infrastructure. The acquisition target archetype is specialized module houses with healthcare or automotive qualification pipelines. Watch GaN-on-silicon yield improvements at domestic equipment makers as the inflection signal for mid-power chip cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sapphire Substrate Refining | Captive alumina supply insulates against Australian export quota volatility and secures municipal tender eligibility. |
| GB 30255 Tier-1 Certification Investment | MIIT efficacy mandates weight procurement scoring toward certified suppliers in Guangdong infrastructure bundles. |
| Healthcare Direct Procurement Relationships | Beijing and Shanghai hospital unbundling of fixture supply from installation services compresses distributor margins. |
| GaN-on-Silicon Epitaxy Scale-Up | Domestic 200mm silicon substrate capacity reduces sapphire dependency and cuts chip fabrication costs. |
| Automotive AEC-Q102 Qualification | Domestic EV adaptive driving beam specifications open tier-1 supplier positioning for module houses. |
Research Approach
Independent corroboration across MOCVD equipment manufacturers, provincial procurement officers, and hospital biomedical engineering directors underwrites the qualitative findings. Primary interviews with epitaxial growth technicians, distributor network managers, and SAMR compliance auditors combined with secondary validation from MIIT GB standard filings, MEE dual carbon policy documents, and customs trade data. Bottom-up triangulation across Shenzhen industrial cluster production records and top-down reconciliation against provincial infrastructure budget disclosures anchored volume estimates.
Rate-of-change decomposition across the analysis window separates volume growth from price mix effects in segment-level CAGRs. The analytical framework models product type, application, technology, and end user dimensions alongside provincial regulatory cluster differentiation. CAGRs derive from logistic adoption curves for Micro LED commercialization and replacement cycle dynamics for general illumination. Industry-specific forecast inputs include MEE mercury lamp phase-out timelines and smart city IoT sensor deployment bundling rates.
Caveats apply where Australian bauxite export quota tightening or Micro LED mass transfer yield breakthroughs could materially shift the outlook. Forecasts reflect assumptions regarding MIIT efficacy mandate enforcement consistency and provincial procurement office carbon metric weighting stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Vietnam LED Lighting Market
LED
Chip on Board LED Market
LED
France LED Lighting Market
LED
High Power LED Market
LED
Xenon Market
LED
Japan Indoor LED Lighting Market
LED
LED High Bay Drivers Market
LED
Egypt LED Lighting Market
LED
North America Indoor LED Lighting Market
LED
East Africa LED Lighting Market
LED
LED and OLED Display Market
LED
LED Lighting Market
LED
LED Power Supplies Market
LED
Organic Light Emitting Diode (OLED) Market
LED
Global Chip Scale Package (CSP) LED Market
LED
China LED Lighting Market