
 LED Display Control Card Market | 2026-2036
LED Display Control Card Market Size, Share, and Industry Trends Forecast 2026-2036
LED Display Control Card Market Analytics
Live events and sports entertainment is expanding as the dominant demand vertical for LED display control cards, displacing traditional static advertising installations. NovaStar leverages its integrated software-hardware ecosystem to dominate large-venue deployments across Asia. Brompton Technology specializes in high-refresh-rate processing for broadcast and cinema applications, sustaining premium positioning in European markets. Colorlight LED competes aggressively on cost-optimized full-color solutions for commercial retail signage.
An LED display control card is an embedded electronics module that processes video input signals, manages pixel mapping, and synchronizes refresh rates across LED arrays, typically handling data throughput from 1 Gbps to 10 Gbps depending on resolution and panel density. These cards translate compressed video streams into precise timing signals that drive individual LED clusters, enabling seamless visual output for digital billboards, stage backdrops, and command-center video walls. Full-color control cards command the widest margin pools as they integrate complex gamma correction and color calibration algorithms that single-color units omit. Cloud-controlled technology represents the fastest-expanding segment, as venue operators seek remote monitoring and over-the-air firmware management across distributed screen networks. Wired deployments remain the mature baseline in transportation and fixed infrastructure where latency tolerance is minimal.
FCC certification requirements in the United States constrain radio-frequency emissions from wireless control card architectures, pushing vendors toward pre-certified module designs. China's MIIT enforces GB standards for electromagnetic compatibility that filter out non-compliant imports, creating a protected domestic supply base around Shenzhen. The EU's RoHS and REACH frameworks restrict hazardous substances in printed circuit board assemblies, elevating compliance costs for control card manufacturers serving European event and retail clients. Stakeholders must monitor how evolving energy-efficiency mandates reshape hardware architectures and determine whether cloud-managed or edge-processing topologies deliver superior total-cost outcomes across their installed base.
Market Dynamics
Cloud-managed control card architectures are compressing refresh cycles across venue networks, forcing vendors to restructure firmware delivery from discrete releases to continuous over-the-air pipelines that synchronize with LED module calibration schedules.
Growth Catalysts
- Live Event Infrastructure:Sports stadium operators and concert venue owners are replacing static ribbon boards with full-color LED backdrops that demand synchronized multi-panel control systems.
- China's GB Standards:MIIT electromagnetic compatibility certification creates domestic preference for Shenzhen-Dongguan corridor manufacturers, insulating local supply from import competition.
- Edge Processing Architectures:On-card FPGA modules now handle gamma correction locally, reducing latency for broadcast and cinema applications that require sub-frame synchronization.
Market Restraints
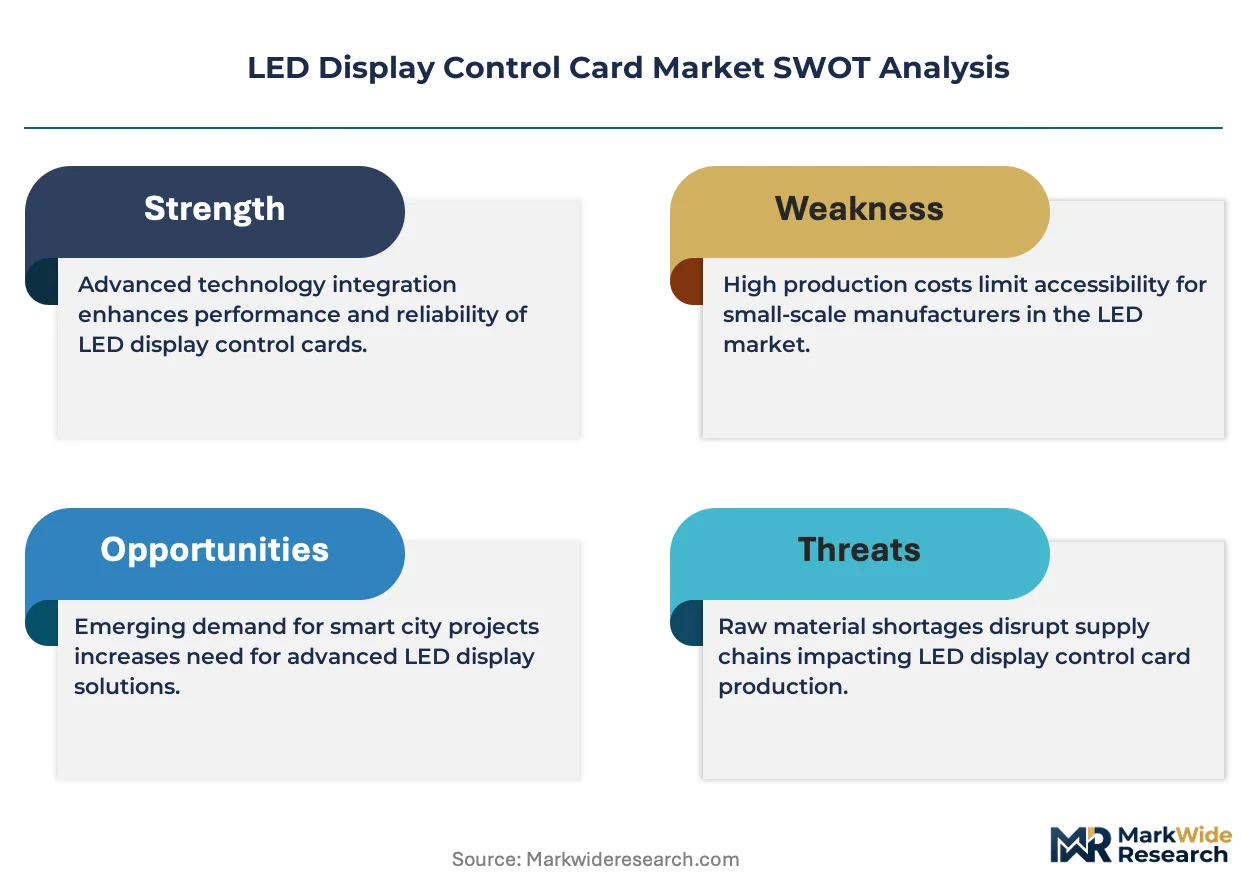
- Silicon Wafer Cost Volatility:FPGA and ASIC fabrication inputs fluctuate with foundry capacity allocation, squeezing margin on high-throughput control cards.
- Shenzhen Supply Concentration:Seventy percent of PCB assembly capacity sits within Guangdong Province, exposing buyers to single-region disruption risk from power rationing or logistics congestion.
- Wireless Latency Floors:FCC emission limits constrain radio-frequency control architectures, preserving wired dominance in transportation and command-center installations where timing tolerance approaches zero.
Strategic Opportunities
- India Commercial Retail:Shopping mall digitization and DOOH expansion in Mumbai and Delhi create first-mover advantage for cost-optimized full-color control card vendors.
- EU Energy Efficiency Mandates:Ecodesign requirements for digital signage hardware incentivize low-power control card architectures with adaptive brightness algorithms.
- 5G-Edge Convergence:Network slicing enables remote real-time monitoring of distributed screen networks, opening subscription-based firmware management revenue streams.
Industry Challenges
- Firmware Integration Complexity:Venue operators struggle to synchronize control card updates across heterogeneous LED panel generations from multiple module suppliers.
- EMC Certification Timelines:GB and FCC testing cycles extend product launch windows by four to six months, compressing effective selling seasons for seasonal event technology procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Display Control Card Market |
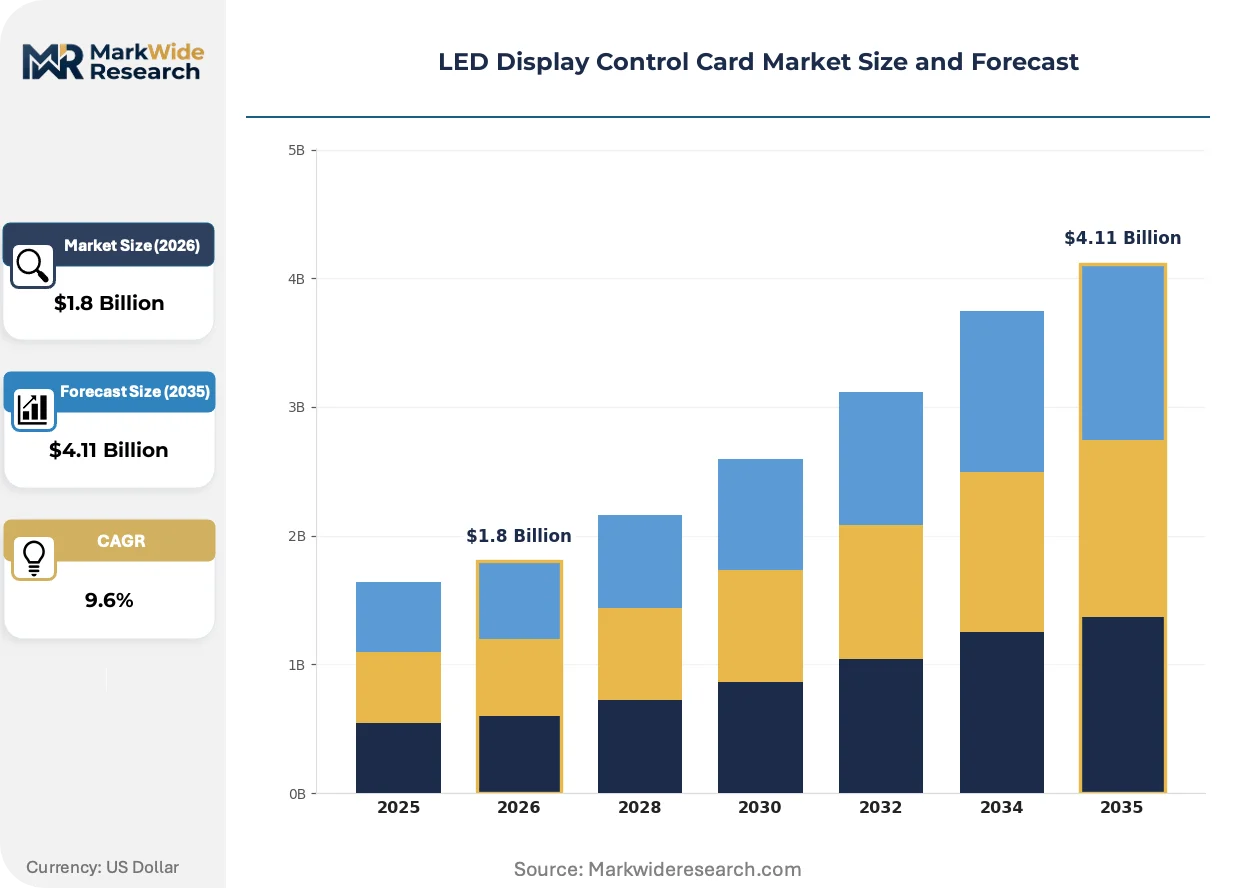
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.11 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Color, RGB, RGBW, Full-Color End User: Advertising, Retail, Events, Transportation Technology: Wireless, Wired, Hybrid, Cloud-Controlled Size: Small, Medium, Large, Custom |
| Companies Covered | Brompton Technology, Huidu Technology, NovaStar, Mooncell Electronics, Magnimage, Colorlight LED, KYSTAR Technology, Sysolution, Linsn Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Display Control Card Market Evolving Landscape
Control card functionality is migrating from fixed-function hardware to software-defined pipelines, enabling post-deployment feature activation and collapsing the traditional boundary between device sale and ongoing service engagement.
FPGA-based processing engines are absorbing gamma correction and color calibration tasks previously executed on host computers. Broadcast studios and virtual production stages are adopting these cards to eliminate frame-buffer latency. This compression of the signal chain is absorbing margin from external processor vendors and consolidating value capture within the control card layer.
REACH substance restrictions and RoHS hazardous material limits are forcing PCB assembly redesigns across European-bound production lines. Manufacturers serving event and retail clients must reformulate solder alloys and substrate laminates to maintain market access. High-density multilayer boards for 10 Gbps throughput applications face the steepest compliance cost escalation.
Venue operators now specify cloud-managed control cards with API-accessible diagnostics, unbundling after-sales service from hardware purchase. Systems integrators in Germany and the United Kingdom are replacing perpetual-license software with metered firmware subscriptions. This reconfiguration of buyer-seller relationships is most visible in sports entertainment, where distributed stadium networks require centralized uptime monitoring.
LED Display Control Card Market Segmentation
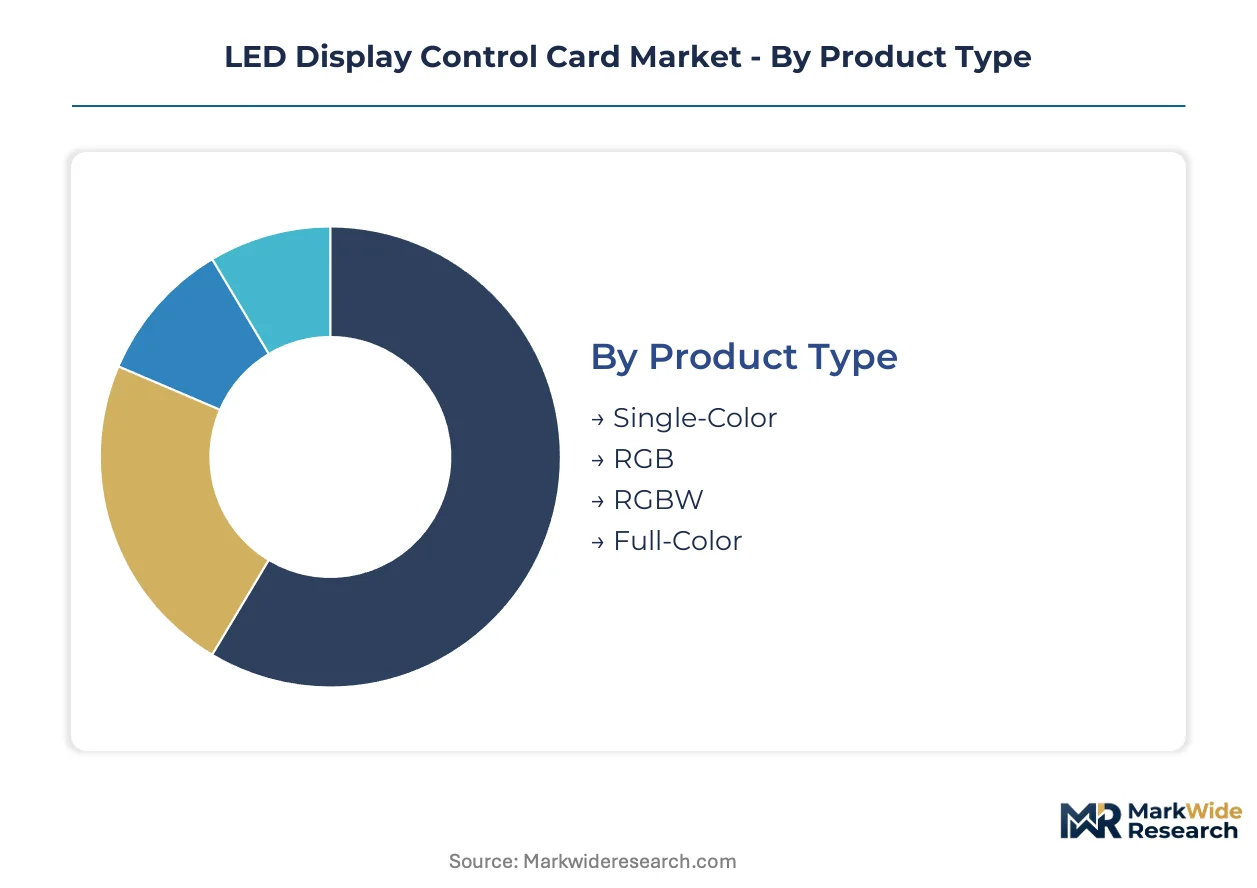
LED display control cards fragment across four axes that determine procurement priorities. Product type governs margin pools through color calibration complexity. End-user verticals dictate latency tolerance and durability specifications. Technology choice locks buyers into connectivity topologies with divergent upgrade paths. Size classifications align with manufacturing batch economics and installation logistics.
Product Type:
Color depth defines the processing load placed on gamma correction engines and FPGA resources.
- Full-Color:These cards integrate 16-bit color depth processing with per-panel calibration tables for cinema-grade output. Sports stadium operators in Guangdong Province specify these systems for perimeter ribbon boards requiring broadcast synchronization.
- RGB:Three-channel processing architectures dominate commercial retail signage where cost-performance balance matters. Shopping mall operators in Mumbai and Delhi prioritize these units for facade digitization projects.
- Single-Color:Monochrome controllers with minimal processing overhead serve transportation ticker displays and basic wayfinding installations.
- RGBW:Four-channel designs add dedicated white LED driving for enhanced luminance in daylight-viewable outdoor applications.
Mature deployment sits with Single-Color systems in fixed infrastructure. Newer deployment is concentrated in Full-Color units for live entertainment venues.
End User:
Vertical-specific durability and synchronization requirements reshape control card specification sheets.
- Events:Temporary installations demand rapid configuration profiles and rental-friendly form factors. Concert touring companies in Germany specify hot-swappable cards with standardized mounting patterns for rapid stage turnaround.
- Advertising:DOOH networks require remote monitoring APIs and adaptive brightness algorithms for 24/7 operation. Media owners in the United Kingdom meter firmware subscriptions through cloud-managed architectures.
- Retail:In-store digital signage prioritizes compact thermal envelopes and silent operation for customer-facing environments.
- Transportation:Command centers and transit hubs specify wired-only configurations with sub-millisecond latency guarantees and MIL-STD shock resistance.
Volume leadership belongs to Advertising networks scaling screen counts. Fastest value expansion tracks Events verticals replacing static backdrops with LED canvases.
Technology:
Connectivity topology determines firmware delivery mechanisms and network architecture complexity.
- Cloud-Controlled:API-accessible diagnostics and over-the-air update pipelines enable centralized management of distributed screen estates. Venue operators across sports entertainment networks specify these for uptime monitoring.
- Wired:Ethernet and fiber-based control maintains zero-latency dominance in transportation and broadcast applications where frame synchronization is non-negotiable.
- Wireless:Radio-frequency architectures face FCC emission constraints that limit refresh rates in the United States, constraining adoption to secondary monitoring roles.
- Hybrid:Dual-path redundancy combines wired primary control with wireless backup for mission-critical installations requiring failover guarantees.
Established base runs on Wired architectures. Cloud-Controlled configurations are climbing the fastest as venue operators unbundle hardware purchase from ongoing service engagement.
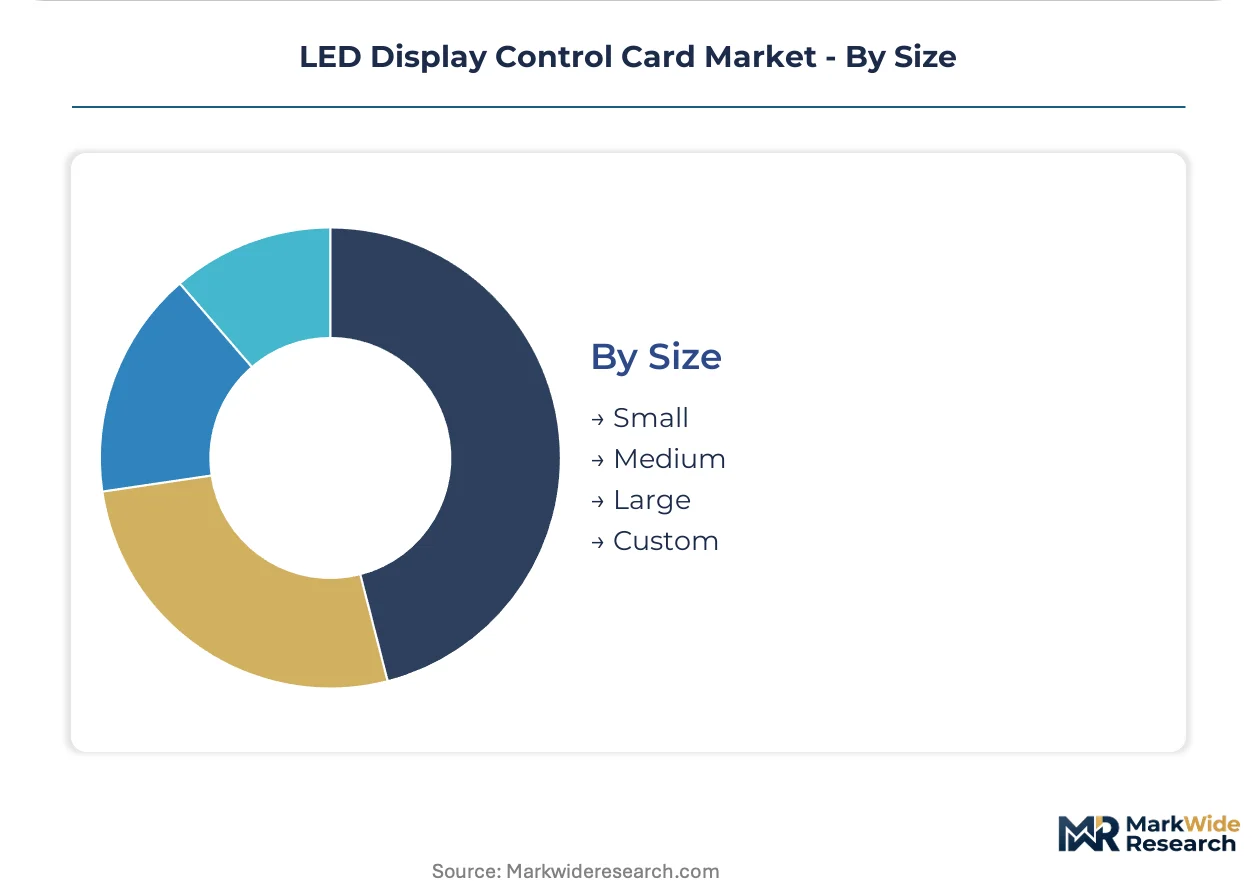
Size:
Physical form factor scales with panel density and thermal dissipation requirements.
- Large:Rack-mount chassis with redundant power supplies serve video walls exceeding 4K resolution in command centers and broadcast facilities.
- Custom:Non-standard dimensions accommodate architectural LED installations with irregular aspect ratios and curved geometries.
- Medium:DIN-rail compatible units balance processing density with installation flexibility for standard commercial displays.
- Small:Compact modules with integrated heat sinks target space-constrained retail fixtures and portable event equipment.
Production scale favors Medium formats for inventory efficiency. Custom specifications are expanding most quickly as architectural integration demands proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in China's Guangdong Province while consumption spreads across live entertainment venues and digital signage networks worldwide. Shenzhen-Dongguan corridor manufacturers supply seventy percent of global control card assembly capacity. Buyers in North America, Europe, and Asia-Pacific import these modules for stadium retrofitting and retail digitization projects.
China
MIIT electromagnetic compatibility certification under GB standards filters import competition and protects Shenzhen-based manufacturers. Guangdong Province's Pearl River Delta cluster hosts NovaStar, Colorlight LED, and Linsn Technology production facilities alongside LED module fabricators. The Shenzhen-Dongguan corridor achieves vertical integration from PCB assembly through finished control card testing.
United States
Sports stadium operators in Texas and California procure full-color control systems for perimeter ribbon board replacements. FCC emission limits constrain wireless control card architectures and preserve wired dominance in transportation hubs. Los Angeles and Las Vegas entertainment venues drive demand for high-refresh-rate processing in broadcast-synchronized installations.
Germany
Concert touring companies specify hot-swappable control cards with standardized mounting patterns for rapid stage turnaround. ECHA REACH substance restrictions and RoHS hazardous material limits force PCB assembly redesigns for European-bound production lines. Berlin and Munich broadcast studios adopt FPGA-based processing engines to eliminate frame-buffer latency in virtual production stages.
India
Shopping mall operators in Mumbai and Delhi pursue facade digitization projects requiring cost-optimized RGB control solutions. BIS certification requirements for electronic imports create compliance timelines that favor established suppliers with testing relationships. Maharashtra and Gujarat commercial retail corridors represent first-mover opportunities for cloud-managed control card architectures.
United Kingdom
Media owners meter firmware subscriptions through cloud-managed architectures replacing perpetual-license software models. EU Ecodesign requirements for digital signage hardware incentivize low-power control card procurement with adaptive brightness algorithms. London and Manchester DOOH networks specify API-accessible diagnostics for centralized uptime monitoring across distributed screen estates.
LED Display Control Card Market Competitive Landscape
Top-tier vendors anchor integrated software-hardware ecosystems, while mid-tier specialists compete on cost-optimized full-color solutions. The vendor base stratifies across premium broadcast-cinema positioning, standard commercial retail targeting, and economy-tier monochrome controllers. Three archetypes dominate: ecosystem integrators with proprietary calibration software, FPGA processing specialists serving latency-sensitive applications, and volume manufacturers exploiting Guangdong supply chain density. Competitive moves center on geographic expansion into India's retail digitization corridor and technology licensing partnerships for cloud-managed firmware platforms.
Within the ecosystem integrator tier, NovaStar and Colorlight LED exemplify divergent strategic positions. NovaStar occupies a position aligned with large-venue deployments across Asian markets, leveraging proximity to Shenzhen manufacturing clusters. Colorlight LED sits within the cost-optimization archetype, competing aggressively on full-color solutions for commercial retail signage where price-performance ratios determine procurement outcomes. Brompton Technology represents the specialized broadcast-cinema segment, sustaining premium positioning in European markets through high-refresh-rate processing capabilities. These three anchors illustrate how competitive positioning fragments across integration depth, geographic focus, and application-specific performance requirements.
| Leading Market Players |
|---|
| Brompton Technology |
| Huidu Technology |
| NovaStar |
| Mooncell Electronics |
| Magnimage |
| Colorlight LED |
| KYSTAR Technology |
| Sysolution |
| Linsn Technology |
| Others |
Value Network & Pricing Analysis
Silicon wafer spot indices and FPGA foundry pricing cascade through Guangdong Province's assembly corridors into three distinct procurement tiers for LED display control cards. Sports stadium operators absorb premium positioning for broadcast-synchronized full-color systems, while commercial retail buyers in Mumbai and Delhi drive cost-down pressure on RGB controllers through volume consolidation.
Pricing Analysis
Margin tightening in mid-tier RGB controllers reflects foundry capacity reallocation toward automotive semiconductor demand. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling, with FCC and GB compliance tiers commanding substantial premiums. Cost compression accelerates in single-color transportation applications as Shenzhen manufacturers compete on bare-bones hardware specifications. Shopping mall operators in India exhibit highest price sensitivity, while German broadcast studios prioritize latency performance over unit economics.
Supply Chain Analysis
Engineering talent availability in Shenzhen-Dongguan and Dongguan-Huizhou manufacturing corridors anchors PCB assembly density for control card production. Supply draws from Taiwan for high-layer-count substrates, South Korea for advanced FPGA packaging, and domestic China for passive component integration. Single-region concentration in Guangdong Province creates vulnerability to power rationing and logistics congestion. Distribution runs through systems integrators in Germany and the United Kingdom, with direct OEM relationships dominating North American stadium procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-managed firmware architectures are displacing perpetual-license software models across sports entertainment networks, compressing refresh cycles and restructuring vendor-customer relationships throughout the LED display control card value chain.
For Market Incumbents: Deepen FPGA processing capabilities in edge-control cards to defend against broadcast-cinema specialists encroaching on latency-sensitive applications. Consolidate calibration software ecosystems to lock venue operators into recurring firmware subscription revenue. Prioritize MIIT GB certification maintenance to preserve Shenzhen manufacturing advantages against import competition.
For New Entrants and Emerging Players: Begin with cost-optimized RGB controllers targeting India's commercial retail digitization corridor in Maharashtra and Gujarat, where BIS certification timelines favor established testing relationships. Pursue white-label partnerships with Guangdong module manufacturers to bypass captive distribution channels. Emphasize API-accessible cloud management as differentiation against legacy wired-only incumbents.
For Investors and Strategic Acquirers: Distressed-cycle entries favor FPGA processing specialists with broadcast-studio relationships in Germany and the United Kingdom, where REACH compliance costs squeeze mid-tier competitors. Long-term viability hinges on software-defined pipeline migration and recurring revenue attachment rates. Monitor 5G network slicing deployment timelines as inflection indicator for remote monitoring subscription scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Firmware Platform Integration | Enables metered subscription revenue from German and UK sports venue operators. |
| GB Certification Investment | Secures MIIT electromagnetic compatibility approval for Shenzhen-Dongguan manufacturing. |
| India Distribution Partnership | Accelerates BIS compliance navigation for Mumbai and Delhi retail digitization projects. |
| FPGA Processing Engine Acquisition | Absorbs gamma correction latency critical for Berlin broadcast studio virtual production. |
| REACH-Compliant PCB Redesign | Maintains European market access under ECHA substance restriction mandates. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this LED display control card market assessment. Primary interviews with control card hardware engineers, stadium technology procurement directors, broadcast systems integrators, and cloud platform product managers combined with MIIT certification databases, FCC equipment authorization registries, and Guangdong customs export statistics. Bottom-up module shipment analysis and top-down venue installation tracking provided triangulation across value chain layers.
Granularity-level modeling captured product type, end-user vertical, connectivity technology, and physical form factor dimensions across the projection horizon. CAGRs derived from panel density evolution curves and refresh rate specification trends in sports entertainment and broadcast applications. FPGA throughput requirements and cloud-management API adoption rates served as industry-specific forecast inputs alongside foundry capacity allocation assumptions.
Silicon wafer price volatility, GB certification timeline extensions, and 5G network slicing deployment delays are the dominant revision risks for forecast trajectories. Material deviation in foundry pricing or MIIT regulatory enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Linear LED Strip Fixture Market
LED
Japan Indoor LED Lighting Market
LED
Global LED Phosphor Market
LED
Architectural LED Products Market
LED
High Power LED Market
LED
UK Indoor LED Lighting Market
LED
LED Phosphor Materials Market
LED
LED Lamp Market
LED
China LED Lighting Market
LED
East Africa LED Lighting Market
LED
Dot-Matrix LED Displays Market
LED
Dual-Digit 7 Segment LED Displays Market
LED
OLED Blue Emitter Market
LED
Philippines LED Market
LED
Europe Indoor LED Lighting Market
LED
US and Europe LED Lighting Market