
 LED Lamp Market | 2026-2036
LED Lamp Market Size, Share, and Industry Trends Forecast 2026-2036
LED Lamp Market Analysis
E-commerce and direct-contractor platforms are reshaping how LED lamps reach end users. Signify Holding leverages integrated smart lighting ecosystems to sustain premium positioning across European and North American project channels. Acuity Brands anchors its competitive stance through deep specification relationships with electrical distributors and architectural lighting designers. ams OSRAM competes at the component level, supplying high-efficacy chips that power downstream fixture brands.
An LED lamp converts electrical energy into visible light through a semiconductor diode, typically achieving luminous efficacy exceeding 120 lumens per watt in premium designs through phosphor-coated blue emitters. The device serves commercial and residential illumination by replacing legacy incandescent and fluorescent sources with directional, dimmable output. Bulbs and tubes retain volume leadership in replacement cycles across mature building stock, while fixtures capture expanding margin pools as integrated smart systems penetrate new construction. COB and SMD technologies dominate manufacturing throughput, though RGB configurations are gaining traction in architectural and horticultural applications where spectral control commands price premiums.
EU Green Deal directives and REACH substance restrictions are tightening material compliance requirements for LED phosphors and driver electronics across European member states. The US Department of Energy maintains efficacy benchmarks through ENERGY STAR and federal minimum standards that filter low-performance imports from distribution channels. China's GB standards and MIIT efficiency regulations enforce domestic manufacturing quality while shaping export competitiveness. Stakeholders must monitor regulatory divergence between efficiency mandates and circular-economy recycling obligations as these frameworks mature.
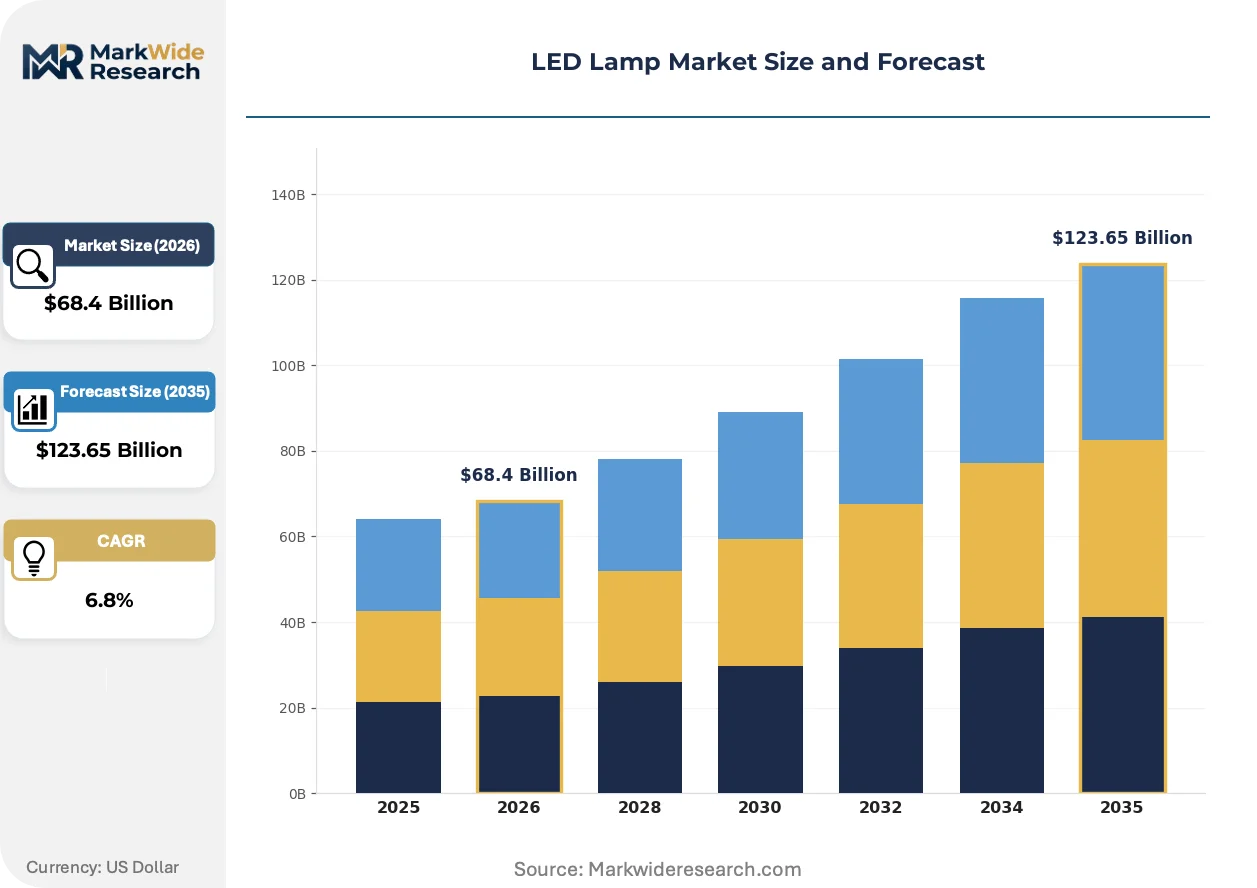
Market Dynamics
EU Green Deal directives are forcing accelerated phase-outs of legacy fluorescent and halogen technologies while retrofit mandates across commercial building stock in Germany, France, and Italy pull volume toward high-efficacy LED systems. This regulatory compression is restructuring procurement priorities across European electrical distributors and facility managers.
Growth Catalysts
- EU Ecodesign Regulations:Mandatory minimum efficacy thresholds for light sources sold in European member states are eliminating low-performance imports and clearing shelf space for premium LED products.
- Commercial Building Retrofits:Deep energy renovation programs across Germany and France are replacing T8 fluorescent troffers with integrated LED panels in office and retail environments.
- Connected Luminaire Systems:DALI-2 and wireless mesh protocols are embedding sensors and controls directly into fixtures, enabling daylight harvesting and occupancy-based dimming in new construction.
Market Restraints
- Phosphor Cost Volatility:Rare-earth elements including cerium and yttrium used in warm-white LED phosphors face concentrated supply from Chinese processors, creating input price instability.
- Technical Degradation Limits:Lumen maintenance below 70% after 50,000 hours in high-temperature operating environments constrains warranty terms for industrial high-bay applications.
- Regulatory Friction from REACH:Substance restrictions on lead-containing solder and certain flame retardants in driver electronics are forcing redesign cycles that delay product launches in European markets.
Strategic Opportunities
- Horticultural Spectral Control:Tunable RGB and far-red LED configurations for vertical farming and greenhouse operations command price premiums based on photosynthetic photon flux density optimization.
- Direct-Contractor Platforms:E-commerce channels serving electrical contractors are bypassing traditional distributor markups and capturing specification influence in North American commercial projects.
- China Dual Carbon Goals:National efficiency mandates and building decarbonization targets are accelerating LED adoption in municipal street lighting and industrial facilities across Chinese provinces.
Industry Challenges
- EMC Certification Complexity:Divergent electromagnetic compatibility testing requirements between EN standards in Europe and FCC Part 15 in the United States extend product validation timelines.
- Legacy Control Integration:Retrofit installations must interface with existing 0-10V dimming infrastructure and phase-cut wall switches, complicating driver design and commissioning protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Lamp Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulbs, Fixtures, Tubes, Strips Technology: COB, SMD, RGB, Hybrids Application: Residential, Commercial, Industrial, Outdoor End User: Consumers, Businesses, Contractors, Government |
| Companies Covered | Signify Holding, Acuity Brands, ams OSRAM, Cree Lighting, LG Electronics, Panasonic Corporation, Hubbell, Zumtobel Group, Dialight, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Lamp Market Emerging Trajectories
Miniaturization of driver electronics and convergence of lighting with building automation systems are compressing traditional product boundaries. Manufacturers are racing to embed intelligence while maintaining thermal performance in shrinking form factors.
Chip-on-board LED arrays are collapsing the distinction between discrete packaged emitters and integrated light engines. Horticultural operators in the Netherlands and pharmaceutical-grade cleanroom facilities in Switzerland are adopting COB modules at accelerated replacement cycles. This integration is collapsing the addressable market for standalone driver and optical component suppliers.
REACH substance restrictions and RoHS recast directives are tightening material compliance for LED phosphors and printed circuit board substrates across European member states. Manufacturers are reformulating solder alloys and seeking halogen-free flame retardants to maintain market access. German industrial lighting brands are responding fastest, leveraging existing chemical management systems to accelerate recertification.
Facility managers are consolidating supplier relationships around full-system providers capable of delivering luminaires, controls, and energy performance contracting in single-source agreements. Electrical distributors in the United States are losing specification influence to manufacturer-direct sales engineers. This concentration is most visible in California Title 24 compliance projects where integrated daylighting and dimming mandates favor bundled procurement.
LED Lamp Market Segmentation
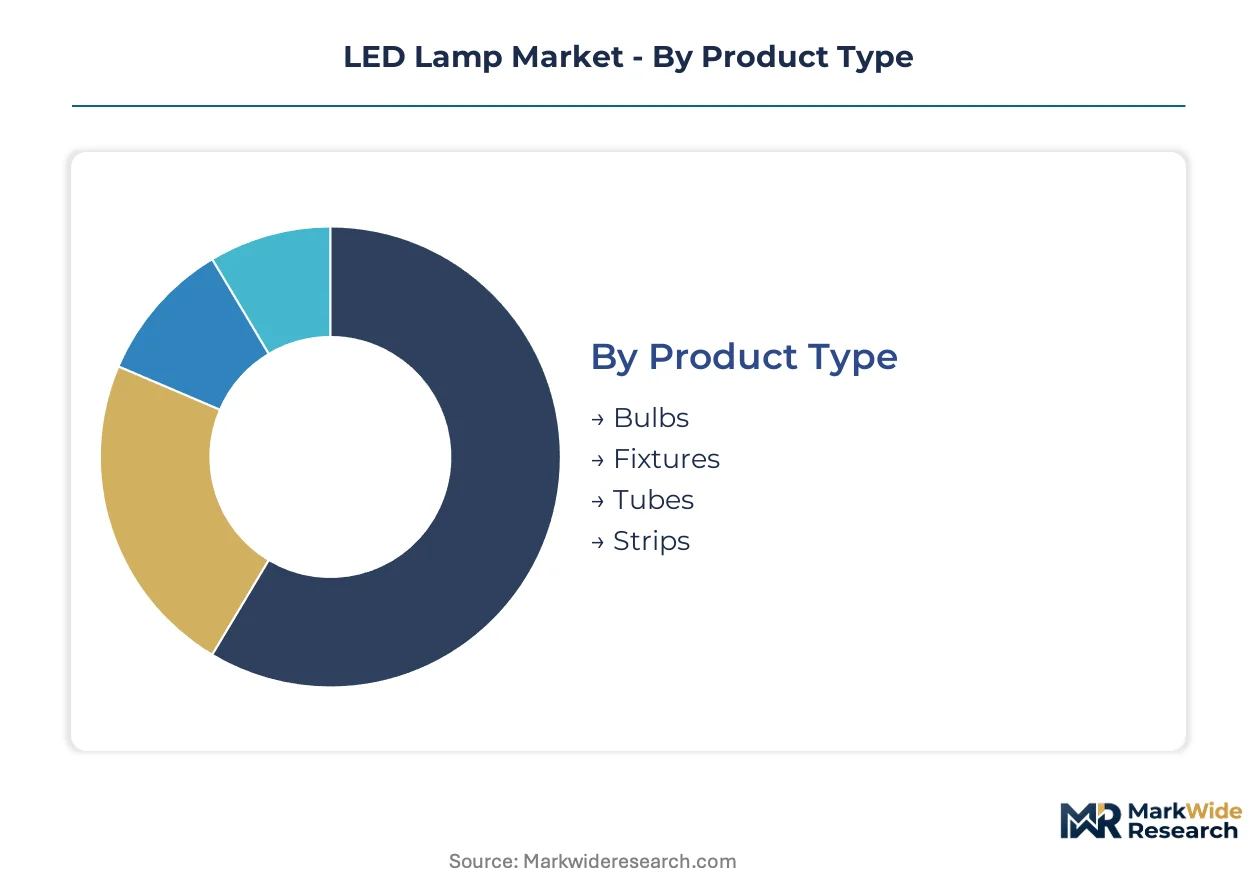
LED lamp segmentation reveals divergent margin profiles across product architectures and procurement channels. Service intensity varies sharply between replacement bulb transactions and integrated fixture installations requiring commissioning support.
Product Type:
After-sales service obligations differ fundamentally across product form factors, with integrated systems demanding ongoing technical support while replacement lamps operate as transactional consumables.
- Bulbs:Standardized screw-base and pin-base configurations dominate residential replacement cycles and facility maintenance inventories. Procurement concentrates through electrical distributors and e-commerce platforms serving price-sensitive retrofit demand across Germany, France, and the United States.
- Fixtures:Integrated luminaire systems embed drivers, optics, and heat sinks as unified assemblies requiring specification engineering and commissioning protocols. Demand clusters in new commercial construction across Chinese provinces and EU Green Deal retrofit mandates where connected controls justify premium positioning.
- Tubes:Linear LED retrofits for T8 and T5 fluorescent housings serve office and retail renovation waves. These products carry moderate technical support requirements for ballast bypass decisions and driver compatibility verification.
- Strips:Flexible printed circuit board assemblies with adhesive mounting serve architectural accent and cove lighting applications. Demand concentrates through specification channels serving hospitality and retail environments.
Bulbs hold the largest share; momentum sits with fixtures.
Technology:
Manufacturing cost tiers separate mature packaging formats from emerging spectral configurations commanding premium pricing in specialized applications.
- COB:Chip-on-board arrays deposit multiple LED dies directly onto thermally conductive substrates, collapsing optical complexity into compact light engines. Horticultural operators in the Netherlands and pharmaceutical cleanroom facilities in Switzerland are adopting COB modules at accelerated replacement cycles.
- SMD:Surface-mount device packages dominate high-volume manufacturing through automated pick-and-place assembly. Chinese producers leverage SMD economies to supply downstream fixture brands across price-sensitive commercial segments.
- RGB:Discrete red-green-blue emitter combinations enable tunable spectral output for entertainment, architectural, and agricultural applications. Vertical farming operators pay premiums based on photosynthetic photon flux density optimization.
- Hybrids:Mixed-technology architectures combine COB central arrays with SMD perimeter emitters for adjustable beam control. These configurations serve museum and gallery applications requiring precise CRI maintenance.
SMD holds the largest share; RGB configurations are climbing the fastest.
Application:
Regulatory pressure intensity varies across installation environments, with commercial and industrial segments facing mandatory efficiency thresholds that residential retrofits escape.
- Residential:Consumer-driven replacement of legacy incandescent and CFL sources through retail and e-commerce channels. ENERGY STAR certification filters product availability in the United States while EU Ecodesign mandates accelerate phase-outs.
- Commercial:Office, retail, and hospitality installations drive integrated panel and downlight specifications. Deep energy renovation programs across German and French building stock pull volume toward high-efficacy systems with embedded controls.
- Industrial:High-bay and hazardous-location fixtures serve manufacturing, warehousing, and extraction environments. Lumen maintenance requirements above 50,000 hours constrain warranty terms and supplier qualification.
- Outdoor:Street, area, and flood lighting applications face municipal procurement cycles and dark-sky compliance requirements. China's dual carbon goals accelerate LED adoption in provincial street lighting infrastructure.
Commercial holds the largest share; outdoor applications are gaining share fastest.
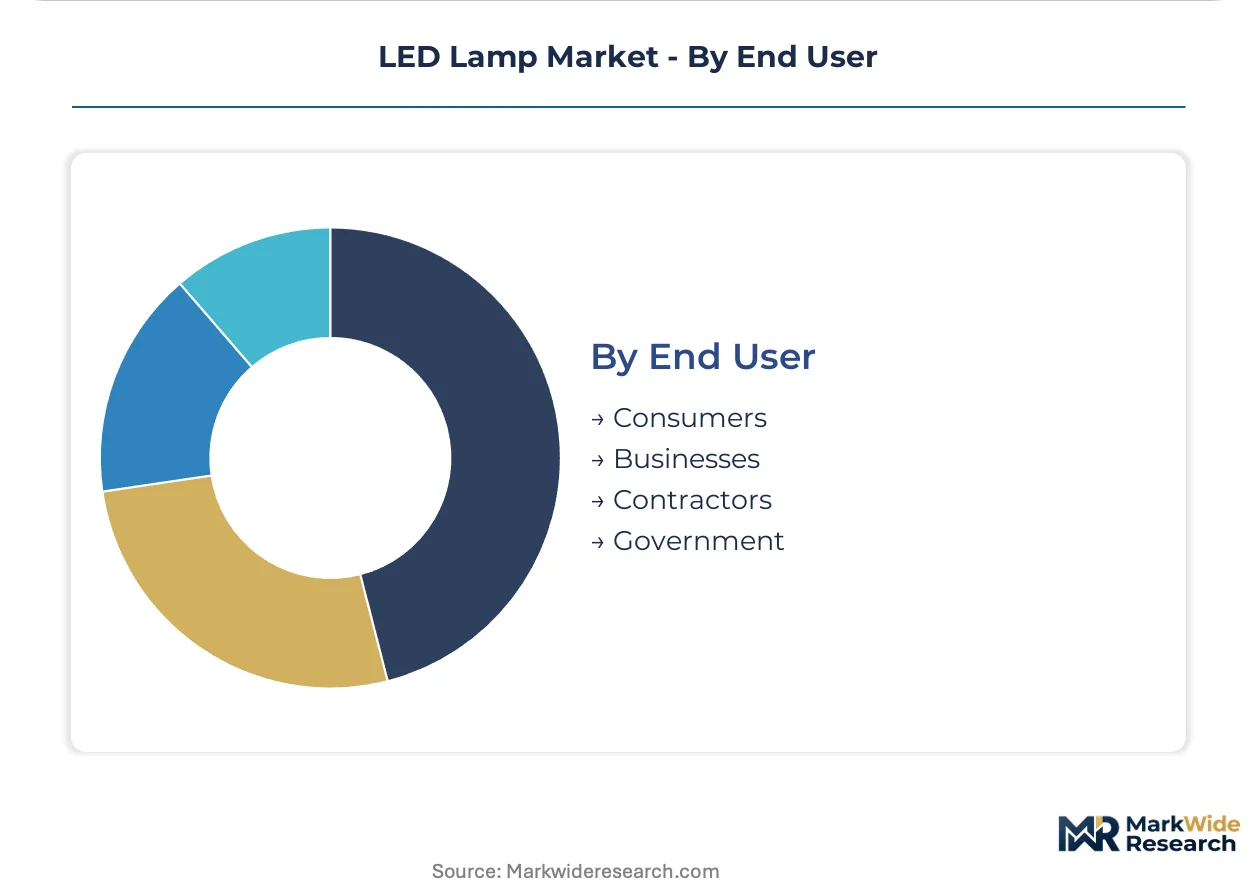
End User:
Procurement sophistication and specification influence separate fragmented consumer demand from concentrated contractor and government purchasing power.
- Consumers:Individual household purchases through retail and online channels prioritize first-cost economics over lifecycle value. Brand recognition and packaging claims drive selection in low-involvement transactions.
- Businesses:Corporate facility managers and sustainability officers consolidate supplier relationships around full-system providers. Energy performance contracting agreements bundle luminaires, controls, and guaranteed savings.
- Contractors:Electrical installation professionals influence specification through direct-manufacturer relationships and e-commerce platforms. These channels are bypassing traditional distributor markups in North American commercial projects.
- Government:Municipal, federal, and military procurement operates through formal bidding processes with domestic content and Buy America requirements. Efficiency mandates and decarbonization targets reshape specification criteria.
Businesses hold the largest share; contractor channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium fixture pricing in Switzerland commands multiples over mass-market bulb transactions in Vietnam, reflecting divergent regulatory enforcement and procurement sophistication across geographies.
United States
Commercial building retrofits and federal efficiency mandates drive specification demand. The Department of Energy enforces ENERGY STAR benchmarks and federal minimum standards that filter low-performance imports. California's Title 24 compliance projects concentrate integrated daylighting procurement in the Los Angeles-San Diego corridor.
Germany
Deep energy renovation programs and industrial facility upgrades pull volume toward connected luminaire systems. EU Ecodesign regulations and REACH substance restrictions tighten material compliance for phosphors and driver electronics. The Ruhr industrial cluster and Bavarian manufacturing belt anchor fixture specification activity.
China
Municipal street lighting infrastructure and industrial facility modernization accelerate adoption of high-lumen fixtures. MIIT efficiency regulations and dual carbon goals enforce domestic manufacturing quality while shaping export competitiveness. The Yangtze River Delta and Pearl River Delta concentrate SMD packaging capacity and downstream fixture assembly.
Netherlands
Horticultural operators and greenhouse facilities drive demand for tunable RGB spectral configurations. EU Green Deal directives phase out legacy fluorescent technologies across commercial building stock. The Westland greenhouse cluster and Eindhoven lighting technology corridor anchor COB module adoption at accelerated replacement cycles.
Japan
Pharmaceutical-grade cleanroom facilities and precision manufacturing environments specify high-efficacy chip-on-board arrays. METI efficiency standards and JIS certification requirements maintain quality thresholds for domestic and export markets. The Kansai industrial belt and Nagoya manufacturing corridor concentrate premium fixture specification.
LED Lamp Market Vendor Landscape
Full-system providers and component-level specialists split the market along the value chain integration axis. The vendor base concentrates around three strategic archetypes: integrated smart lighting ecosystem builders, specification-engineering fixture houses, and high-efficacy semiconductor suppliers. Competitive moves center on backward integration into driver electronics and geographic expansion through direct-contractor e-commerce channels.
Within the integrated ecosystem tier, Signify Holding and Acuity Brands exemplify divergent route-to-market strategies. Signify anchors premium positioning across European and North American project channels. Acuity Brands occupies a position anchored through electrical distributor and architectural lighting designer relationships. At the component level, ams OSRAM represents the semiconductor supply archetype, supplying downstream fixture brands without direct luminaire market participation.
| Leading Market Players |
|---|
| Signify Holding |
| Acuity Brands |
| ams OSRAM |
| Cree Lighting |
| LG Electronics |
| Panasonic Corporation |
| Hubbell |
| Zumtobel Group |
| Dialight |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese SMD packaging facilities is compressing component pricing while forcing suppliers toward extended payment terms and supply-chain finance facilities to maintain liquidity. This utilization dynamic creates divergent pricing power between integrated fixture houses and standalone component vendors across European and North American procurement channels.
Pricing Analysis
Configured-to-order pricing for integrated luminaire systems commands substantial premiums over standard bulb transactions through distributor channels. Three-tier pricing structure across premium, standard, and economy levels separates ENERGY STAR-certified connected fixtures from basic retrofit tubes and unbranded residential bulbs. Cost compression in the SMD component tier is intensifying because Chinese packaging capacity expansion outpaces fixture demand growth. Residential consumers exhibit highest price sensitivity, selecting on first-cost economics, while corporate facility managers prioritize lifecycle value and energy performance contracting bundles.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become critical working capital tools for fixture assemblers sourcing from concentrated upstream suppliers. Manufacturing gravity centers on China for SMD packaging and driver electronics, Germany for precision optics and thermal management components, and Taiwan for high-efficacy LED epitaxy. Rare-earth phosphor materials including cerium and yttrium draw from Chinese processors, creating single-source vulnerability for warm-white emitter formulations. Distribution runs through electrical distributors in mature markets and direct-contractor e-commerce platforms in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LED lamp market functions as a service-attach opportunity where commissioning protocols and energy performance contracting expand faster than hardware transactions. Connected controls and ongoing technical support layers capture recurring revenue streams that hardware margins alone cannot sustain.
For Market Incumbents: Build switching-cost moats through embedded DALI-2 and wireless mesh protocol integration that locks facility managers into ecosystem upgrades. Defensive consolidation moves center on backward integration into driver electronics to capture margin pools from component suppliers, plus certification investment in EU REACH and US ENERGY STAR tiers to filter low-cost imports. The emerging threat of direct-contractor e-commerce platforms bypassing traditional distributors demands channel control through manufacturer-direct sales engineering teams.
For New Entrants and Emerging Players: Build out specification influence in horticultural spectral control applications where tunable RGB and far-red configurations command price premiums based on photosynthetic photon flux density optimization. White-space targets include vertical farming operators in the Netherlands and greenhouse facilities seeking yield optimization, plus municipal street lighting infrastructure across Chinese provinces under dual carbon mandates. A direct-manufacturer e-commerce angle serving electrical contractors bypasses distributor markups and captures procurement influence.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across SMD packaging sub-segments as automated pick-and-place assembly achieves scale economies. Long-term viability over the coming decade favors full-system providers capable of bundling luminaires, controls, and energy performance contracting in single-source agreements. Acquisition targets should concentrate on connected lighting software platforms and thermal management specialists. The signal to monitor is consolidation of electrical distributor relationships around integrated ecosystem vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Driver Electronics | Captures margin pools from standalone component suppliers while accelerating REACH compliance cycles. |
| Horticultural Spectral Platform Launch | Commands price premiums from Dutch greenhouse operators optimizing photosynthetic photon flux density. |
| Direct-Contractor E-Commerce Channel | Bypasses distributor markups and captures specification influence in North American commercial projects. |
| Energy Performance Contracting Bundle | Locks facility managers into recurring revenue streams through guaranteed savings agreements. |
| Dual Carbon Compliance Certification | Secures municipal procurement preference across Chinese provincial street lighting infrastructure. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with electrical distributors, facility managers, lighting specification engineers, and component procurement leads. Secondary validation drew from US Department of Energy ENERGY STAR databases, EU Ecodesign directive filings, Chinese MIIT efficiency standard publications, and customs trade data tracking rare-earth phosphor movements. Bottom-up volume triangulation across product architectures converged with top-down value estimates derived from regional procurement patterns.
Calibration against historical adoption curves and regulatory phase-out timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product form factor, packaging technology, application environment, and procurement channel sophistication. CAGRs were derived from slope analysis of replacement cycle acceleration and new construction penetration rates. Industry-specific forecast inputs incorporated EU Green Deal retrofit mandate enforcement schedules and Chinese dual carbon building decarbonization targets.
Stress conditions across rare-earth supply disruption, REACH substance restriction expansion, and EMC certification timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology substitution elasticity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
LED Digital Scoreboard Market
LED
Middle East LED Lights Market
LED
Microled Market
LED
Smart LED Indoor Signage Market
LED
Organic Light Emitting Diode (OLED) Market
LED
US LED Downlight Market
LED
LED Power Supplies Market
LED
South America Indoor LED Lighting Market
LED
LED Tester Market
LED
High Power LED Market
LED
LED Mask Market
LED
Monochrome Outdoor LED Display Market
LED
7 Segment LED Displays Market
LED
Middle East and Africa Indoor LED Lighting Market
LED
LED High Bay Drivers Market
LED
Dot-Matrix LED Displays Market