
 France LED Lighting Market | 2026-2036
France LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
France LED Lighting Market Insights
Commercial real estate is consolidating its share of LED procurement in France, outpacing residential retrofit cycles. Signify France leverages its Philips brand equity and connected lighting platforms to dominate large-scale office and retail rollouts. Lucibel SA specializes in human-centric lighting systems for healthcare and education facilities, differentiating through tunable white technology. Schneider Electric SE extends its building automation integration capabilities, anchoring its position in smart building projects where lighting converges with energy management systems.
France LED lighting comprises solid-state luminaires utilizing semiconductor diodes that convert electrical current into visible light with luminous efficacy typically exceeding 100 lumens per watt, primarily serving energy reduction mandates and extended operational lifespan requirements in built environments. The technology dimension shows smart LED systems capturing premium margin pools as building operators prioritize networked controls and occupancy-responsive dimming, while tunable white applications gain traction in healthcare and workplace wellness programs. Fixture form factors lead hardware value generation, though tape and linear installations expand in architectural accent and cove lighting applications where design flexibility commands specification loyalty.
France's LED market operates under the EU Ecodesign Directive and RE2020 thermal regulation, which together mandate minimum efficacy thresholds and phase out inefficient technologies in new construction and major renovations. ANSM and the national standardization body enforce CE marking compliance and photobiological safety standards under IEC 62471, shaping product certification requirements for domestic and imported luminaires. Stakeholders must monitor the trajectory of France's decarbonization roadmap for buildings, where tightening operational energy limits will determine which LED technologies qualify for public procurement and green financing eligibility.
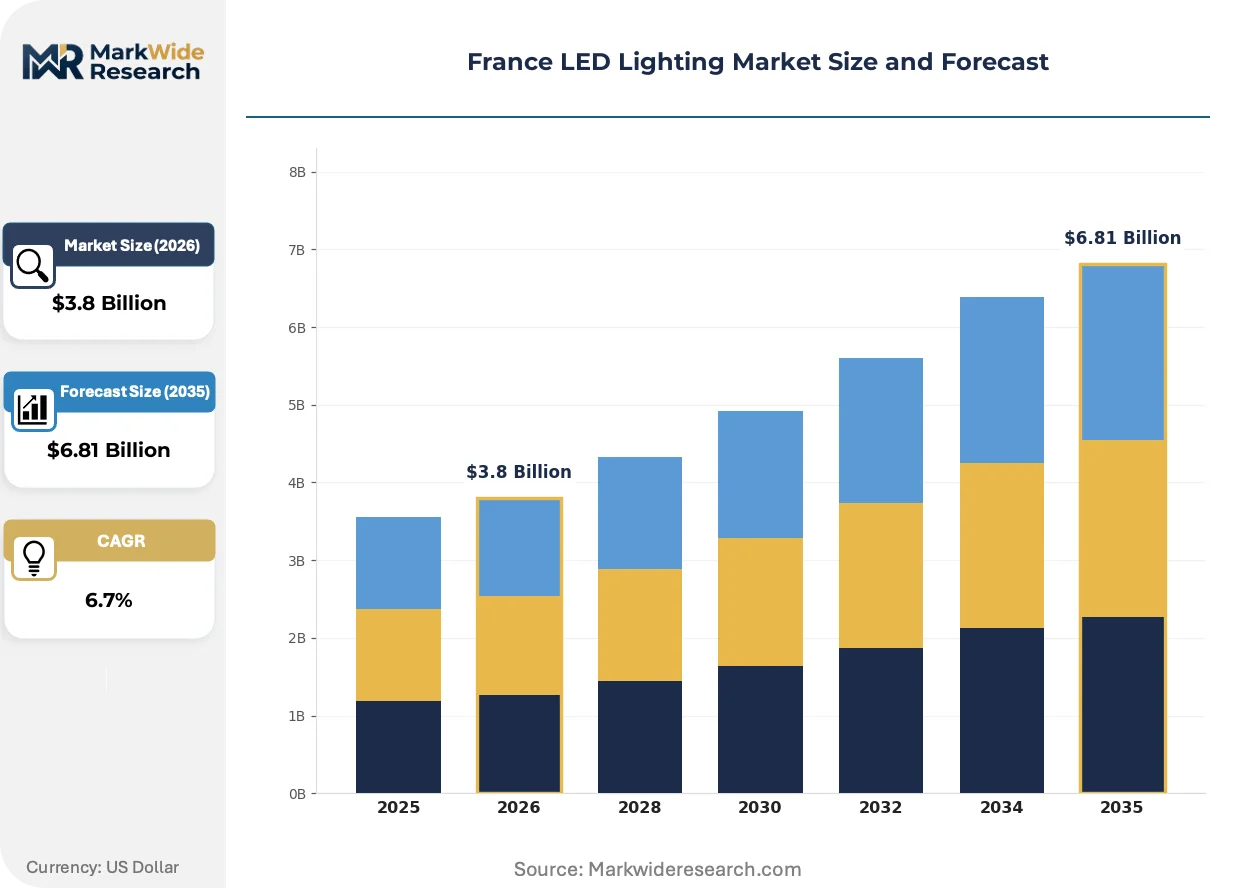
Market Dynamics
France's LED lighting sector is undergoing structural compression as RE2020 thermal regulations and municipal decarbonization contracts force simultaneous hardware replacement and control-system upgrades. The regulatory stack now mandates networked luminaires for new construction, collapsing the traditional separation between fixture procurement and building automation.
Growth Catalysts
- RE2020 Building Regulations:France's thermal regulation mandates minimum efficacy thresholds for new construction and major renovations, accelerating fixture replacement cycles in commercial and residential buildings.
- Municipal Streetlight Modernization:French metropolitan areas are executing large-scale LED retrofits under energy performance contracts, concentrating procurement volumes in urban infrastructure.
- Human-Centric Lighting:Tunable white systems are penetrating healthcare and education facilities as circadian lighting research validates wellness outcomes, expanding specification opportunities beyond pure energy savings.
Market Restraints
- Semiconductor Supply Concentration:LED chip fabrication concentrates in East Asian foundries, exposing French luminaire assemblers to input volatility and extended lead times for high-efficacy diodes.
- Copper and Aluminum Input Costs:Thermal management components and driver housings depend on base metals whose price swings compress assembler margins on fixed-price municipal contracts.
- Legacy HID Infrastructure Inertia:Existing high-pressure sodium installations in industrial zones and peripheral municipalities resist replacement due to capital budget constraints and maintenance staff familiarity.
Strategic Opportunities
- Grand Paris Infrastructure Works:The metropolitan expansion program sustains fixture replacement volumes across transportation hubs, commercial cores, and public spaces through 2035.
- LiFi Technology Convergence:Integration of LED illumination with visible light communication protocols opens data transmission applications in electromagnetic-sensitive environments.
- Circular Economy Incentives:France's extended producer responsibility framework for lighting equipment creates competitive differentiation for manufacturers with closed-loop recycling capabilities and modular repairable designs.
Industry Challenges
- Building Automation Integration Complexity:Facility managers face skill gaps in commissioning networked lighting controls with BACnet and KNX protocols, delaying smart system deployments.
- CE Marking and Photobiological Certification Timelines:ANSM enforcement of IEC 62471 safety standards extends product validation cycles, compressing launch windows for seasonal specification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France LED Lighting Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulbs, Fixtures, Tapes, Panels Application: Residential, Commercial, Industrial, Outdoor Technology: Smart LED, Tunable White, RGB, Linear End User: Homeowners, Businesses, Contractors, Designers |
| Companies Covered | Lucibel SA, CisLED, Signify France, Delphi LED, Eclatec, Legrand SA, Osram GmbH, Planlicht France, Schneider Electric SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France LED Lighting Market Trends and Innovations
Connected lighting platforms are compressing the traditional separation between illumination hardware and building management software. Three developments are restructuring competitive positioning and procurement patterns.
Sensor-embedded luminaires is automating occupancy detection and daylight harvesting in French office portfolios. Large facility managers are specifying fixture-integrated microwave and PIR sensors as standard, eliminating standalone control hardware. This convergence is compressing supplier lists toward vendors with native software stacks.
France's transposition of the EU Ecodesign Directive is tightening minimum efficacy thresholds and phasing out non-directional halogen sources ahead of broader European timelines. Domestic manufacturers are accelerating R&D spending on mid-power LED packages to maintain compliance margin. The commercial retrofit segment faces the steepest product obsolescence risk.
Energy service companies are capturing specification authority from traditional electrical distributors. Municipal and commercial buyers are consolidating procurement under performance-contracting arrangements where lighting upgrades are bundled with guaranteed savings verification. This channel shift concentrates volume with vendors capable of financing and measurement-and-verification reporting.
France LED Lighting Market Segmentation
LED lighting segmentation in France reflects divergent procurement logics across construction verticals. RE2020 compliance deadlines and municipal energy performance contracts create distinct specification requirements that fragment demand patterns across product categories.
Product Type:
Customization intensity varies sharply across hardware formats, from mass-produced replacement lamps to architect-specified integrated systems.
- Fixtures:Integrated luminaires with thermal management housings and optical assemblies dominate commercial new-build specifications. Ile-de-France office developments and Grand Paris transit infrastructure sustain specification volumes for recessed, surface-mounted, and suspended variants under RE2020 efficacy mandates.
- Bulbs:Retrofit lamps with Edison and bayonet bases serve residential replacement cycles and legacy socket compatibility requirements. Demand concentrates in mass retail channels as consumers respond to Ecodesign Directive phase-outs of halogen sources.
- Tapes:Flexible linear arrays with adhesive backing enable architectural accent and cove lighting applications. Design flexibility commands specification loyalty in hospitality and retail fit-outs.
- Panels:Edge-lit and back-lit flat luminaires deliver uniform illumination for suspended ceiling grids. Healthcare and education facilities prioritize glare control and cleanability in procurement decisions.
Leading the category by volume: Fixtures. Expanding most quickly: Tapes.
Application:
Cost tier stratification separates premium-specified commercial systems from price-sensitive residential retrofits.
- Commercial:Office, retail, and hospitality installations prioritize networked controls and daylight harvesting integration. Parisian renovation cycles and corporate sustainability commitments concentrate procurement authority with facility managers and energy service companies.
- Outdoor:Street, area, and landscape luminaires serve municipal decarbonization contracts and transportation infrastructure. French metropolitan areas execute large-scale retrofits under energy performance contracting arrangements with guaranteed savings verification.
- Residential:Single-family and multi-unit dwelling installations respond to consumer price sensitivity and DIY installation preferences. Big-box retailers and electrical distributors compete on replacement lamp pricing.
- Industrial:High-bay and hazardous-location fixtures serve manufacturing and logistics facilities. Legacy high-pressure sodium infrastructure resists replacement due to capital budget constraints in peripheral zones.
Climbing the fastest: Commercial. Dominating procurement volumes: Outdoor.
Technology:
Margin pools concentrate where semiconductor and software capabilities converge.
- Smart LED:Networked luminaires with embedded sensors and wireless connectivity enable occupancy detection and remote commissioning. Building automation integration requirements under RE2020 collapse the separation between fixture procurement and control-system specification.
- Tunable White:Variable correlated color temperature systems support circadian lighting protocols in healthcare and workplace wellness programs. ANSM photobiological safety standards under IEC 62471 shape product validation cycles for human-centric applications.
- RGB:Multi-channel color-mixing arrays serve architectural accent and entertainment lighting. Hospitality and retail environments prioritize brand-aligned ambient color programming.
- Linear:Continuous run systems with uniform illumination distribution serve cove, under-cabinet, and display applications. Architectural specification favors slim profiles and seamless jointing capabilities.
Steepest expansion trajectory: Smart LED. Commanding premium positioning: Tunable White.
End User:
Customer sophistication determines specification authority and channel access.
- Businesses:Corporate facility managers and sustainability officers control large-scale rollout decisions. Energy service companies capture specification authority through performance-contracting arrangements bundling installation with guaranteed savings.
- Contractors:Electrical installation firms influence product selection through procurement relationships and installation familiarity. Municipal streetlight modernization concentrates volume with contractors capable of financing and measurement-and-verification reporting.
- Homeowners:Individual consumers respond to retail pricing and replacement convenience. Mass-market channels dominate as Ecodesign Directive phase-outs drive halogen-to-LED substitution.
- Designers:Lighting designers and architects specify aesthetic and performance characteristics in premium commercial and residential projects. Specification loyalty depends on optical quality and control integration capabilities.
Highest value concentration: Businesses. Gaining procurement influence: Designers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Île-de-France's Qualité de Vie au Travail tax incentives concentrate LED specification authority in Parisian commercial retrofits. The region's Grand Paris infrastructure timeline sustains fixture procurement through 2035.
Île-de-France
Parisian office renovation cycles and Grand Paris transit expansion drive specification volumes for networked luminaires. RE2020 thermal regulations mandate minimum efficacy thresholds for new construction in the capital region. La Défense business district and Roissy-Charles de Gaulle airport zone anchor commercial retrofit demand.
Auvergne-Rhône-Alpes
Lyon's healthcare and education facilities prioritize tunable white systems for circadian lighting applications. The regional council's building decarbonization contracts accelerate municipal LED retrofits. Grenoble's clean-tech cluster incubates sensor-embedded luminaire startups targeting alpine microgrid installations.
Provence-Alpes-Côte d'Azur
Marseille port modernization and Nice Côte d'Azur Airport expansion sustain outdoor fixture procurement. The region's tourism-dependent hospitality sector drives architectural accent lighting specifications in Cannes and Monaco. Aix-Marseille-Provence Metropolis executes streetlight energy performance contracts under EU cohesion funding.
Hauts-de-France
Lille's Euralille business district and Calais port infrastructure concentrate commercial lighting demand. The region's industrial legacy sites face RE2020 compliance deadlines for major renovation works. Dunkirk's steel and chemical complexes resist LED conversion due to hazardous-location certification costs.
Nouvelle-Aquitaine
Bordeaux Métropole's municipal decarbonization program funds streetlight modernization across 28 communes. The region's wine tourism and hospitality sector drives decorative fixture specifications. Poitiers and Limoges university hospitals pilot human-centric lighting installations for patient recovery protocols.
France LED Lighting Market Competitive Landscape
Top-tier vendors anchor premium commercial specifications, while mid-tier assemblers compete on municipal contract pricing. The vendor base stratifies across three tiers: multinational lighting groups with software platforms, national specialists with sector expertise, and regional fabricators serving retrofit replacement cycles. Two strategic archetypes dominate: building automation integrators collapsing lighting into energy management systems, and human-centric lighting specialists capturing healthcare premiums. Competitive moves concentrate on strategic partnerships with energy service companies and portfolio diversification into LiFi data transmission.
Within the building automation tier, Schneider Electric SE and Legrand SA occupy positions where electrical infrastructure and lighting controls converge. Signify France exemplifies the multinational platform archetype with its Philips brand equity and connected lighting deployments. Lucibel SA represents the specialization vector through its tunable white focus on healthcare and education facilities.
| Leading Market Players |
|---|
| Lucibel SA |
| CisLED |
| Signify France |
| Delphi LED |
| Eclatec |
| Legrand SA |
| Osram GmbH |
| Planlicht France |
| Schneider Electric SE |
| Others |
Pricing and Supply Chain Analysis
Municipal energy performance contractors concentrate procurement authority across French metropolitan areas, enforcing project-based pricing with fixed-cost guarantees that compress assembler margins on multi-year streetlight modernization contracts. This buyer archetype dominance forces luminaire vendors to absorb raw material volatility within contract terms, collapsing traditional spot-market pricing flexibility.
Pricing Analysis
Short lead-time premiums command pricing power from municipal contractors facing RE2020 compliance deadlines, while spot inventory discounts attract residential retrofit channels. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and smart control integration. Price differentiation hinges on CE marking tier and after-sales service bundling. Cost compression in standard-tier fixtures is intensifying because copper and aluminum input volatility outpaces contract escalation clauses. Residential homeowners exhibit highest price sensitivity; Grand Paris infrastructure contractors show least.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Signify France and Schneider Electric SE, while electrical distributors serve contractor retrofit cycles. LED chip fabrication concentrates in China, Taiwan, and South Korea, exposing French assemblers to single-source vulnerability for high-efficacy diodes. Thermal management components draw from aluminum smelters in Norway and Russia, with driver electronics sourcing from German and Austrian semiconductor packaging facilities. Distribution runs through energy service companies capturing specification authority under performance-contracting arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's LED market operates as a supply-constrained environment where East Asian foundry capacity limits for automotive-grade LED chips prop pricing premiums in the smart luminaire tier.
For Market Incumbents: Cement dominance in Grand Paris infrastructure by securing exclusive supplier status with energy service companies financing measurement-and-verification reporting. Deepen backward integration into thermal management component production to offset aluminum price volatility threatening fixed-price municipal contracts. For New Entrants and Emerging Players: The mid-tier price-point gap between Signify France's premium connected platforms and mass-market retrofit lamps offers white-space entry. Target Auvergne-Rhône-Alpes healthcare facilities with tunable white specialization, leveraging Grenoble's clean-tech cluster for sensor-embedded product development partnerships. For Investors and Strategic Acquirers: The window for entry favors modular repairable design specialists with closed-loop recycling capabilities under France's extended producer responsibility framework. Watch ANSM enforcement timelines for IEC 62471 photobiological certification as inflection indicator for human-centric lighting premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| LiFi Technology Integration | Visible light communication protocols open electromagnetic-sensitive environments to data transmission applications. |
| Circular Economy Certification | Modular repairable designs qualify for green financing eligibility under France's decarbonization roadmap. |
| Energy Service Partnership | Performance-contracting arrangements bundle installation with guaranteed savings verification. |
| Smart Building Convergence | Building automation integration collapses fixture procurement into energy management system specifications. |
| Tunable White Specialization | Circadian lighting protocols in healthcare facilities command premium positioning beyond pure energy savings. |
Research Methodology
Multi-period observation of municipal procurement volumes, RE2020 compliance timelines, and semiconductor input lead times anchored the trend analysis, supplemented by interviews with facility managers at La Défense commercial properties, energy service company procurement directors, lighting designers specifying Grand Paris transit infrastructure, and ANSM regulatory affairs specialists. Secondary validation drew from EU Ecodesign Directive transposition documents, French thermal regulation decrees, IEC 62471 safety standard publications, and customs data on LED chip imports. Bottom-up luminaire shipment tracking triangulated against top-down building construction permit analysis.
Input-output matrices modeled fixture demand against RE2020 implementation phases, municipal energy performance contract award cycles, and semiconductor foundry capacity allocation across the analysis window. Segmentation dimensions spanned product type, application vertical, technology tier, and end-user sophistication. CAGRs derived from regression analysis of historic replacement cycles projected against regulatory mandate deadlines. Industry-specific forecast inputs included Grand Paris infrastructure spend profiles and ANSM certification queue lengths.
Inputs from facility manager interviews and regulatory filing databases were available through the study window; gaps in real-time semiconductor inventory data introduce uncertainty bands around smart LED adoption trajectories. Forecasts reflect assumptions on RE2020 enforcement consistency and municipal budget continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Single-Digit 7 Segment LED Displays Market
LED
China LED Lighting Market
LED
Japan Indoor LED Lighting Market
LED
LED Light Bar Market
LED
Indonesia LED Market
LED
Germany LED Lighting Market
LED
Europe LED Packaging Market
LED
France Indoor LED Lighting Market
LED
Bi-Color LED Ring Light Market
LED
Pixel Pitch LED Market
LED
Egypt LED Lighting Market
LED
France Outdoor LED Lighting Market
LED
Japan LED Market
LED
Global Chip on Board (COB) Light Emitting Diode Market
LED
US LED Downlight Market
LED
Micro LED Display Market