
 Germany Outdoor LED Lighting Market | 2026-2036
Germany Outdoor LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Outdoor LED Lighting Market Insights
Municipal procurement consolidation across German cities is repositioning supplier relationships toward framework-contract specialists. LEDVANCE GmbH leverages its broad distribution network to serve aggregated public tenders. TRILUX GmbH & Co KG anchors its position through deep vertical integration in luminaire manufacturing. ams-OSRAM AG dominates upstream LED component supply, controlling critical chip architectures that downstream assemblers depend upon.
Germany outdoor LED lighting encompasses solid-state luminaires engineered with efficacy ratings exceeding 130 lumens per watt, typically housed in IP65-rated or higher enclosures for weather resilience, and deployed to illuminate roadways, public squares, and commercial exteriors while minimizing energy draw and maintenance cycles. Street lights occupy the largest installed base among product types, though smart lighting technology commands premium positioning as municipalities prioritize remote dimming and fault detection capabilities. Solar lighting competes most aggressively in off-grid perimeter applications where trenching costs outweigh battery storage premiums.
The EU Green Deal's building renovation mandates and Germany's national efficiency standards under the Federal Immission Control Act shape replacement timelines and minimum performance thresholds for outdoor installations. KBA guidelines for tunnel and roadway illumination, alongside DIN EN 13201 street lighting standards, define photometric compliance that manufacturers must satisfy for market access. Stakeholders should monitor how forthcoming EU Ecodesign revisions tighten minimum efficacy requirements and whether German municipalities accelerate smart-city infrastructure budgets beyond current replacement schedules.
Market Dynamics
Municipal procurement consolidation across German cities is compressing supplier margins while favoring framework-contract specialists capable of serving aggregated tenders. This structural force is repositioning competitive advantage toward scale logistics and compliance bundling rather than standalone product differentiation.
Growth Catalysts
- F-Gas Regulation tightening:The EU's phasedown of hydrofluorocarbon refrigerants accelerates luminaire replacement cycles in legacy outdoor installations, forcing municipalities toward solid-state LED alternatives.
- North Rhine-Westphalia urban corridor:Concentrated infrastructure investment across Düsseldorf, Cologne, and Essen generates sustained demand for street and tunnel lighting upgrades.
- LiDAR-integrated smart poles:Sensor fusion technology enables traffic monitoring and pedestrian safety applications, expanding addressable use cases beyond illumination.
Market Restraints
- Upstream chip concentration:German downstream assemblers depend on captive LED component supply from a concentrated Asian upstream base, creating vulnerability to allocation shocks.
- Copper and aluminum volatility:Heat sink and housing materials face commodity price swings that compress margin predictability for fixture manufacturers.
- DIN EN 13201 compliance costs:Photometric testing and certification requirements impose fixed cost barriers that disadvantage smaller regional suppliers.
Strategic Opportunities
- Bavaria smart-city lag:Munich and Nuremberg municipalities trail North Rhine-Westphalia in connected infrastructure deployment, presenting whitespace for system integrators.
- EU Ecodesign revisions:Forthcoming minimum efficacy thresholds will disqualify sub-150 lumens-per-watt products, creating replacement demand ahead of mandate deadlines.
- Solar-plus-storage perimeter lighting:Off-grid applications in rural Baden-Württemberg and Saxony circumvent trenching costs through photovoltaic-battery hybrids.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development for mesh-networked controls outpaces qualified talent supply in German technical universities.
- Legacy HPS retrofit complexity:Existing sodium vapor infrastructure requires electrical and mechanical adaptation that extends installation timelines and labor costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Outdoor LED Lighting Market |
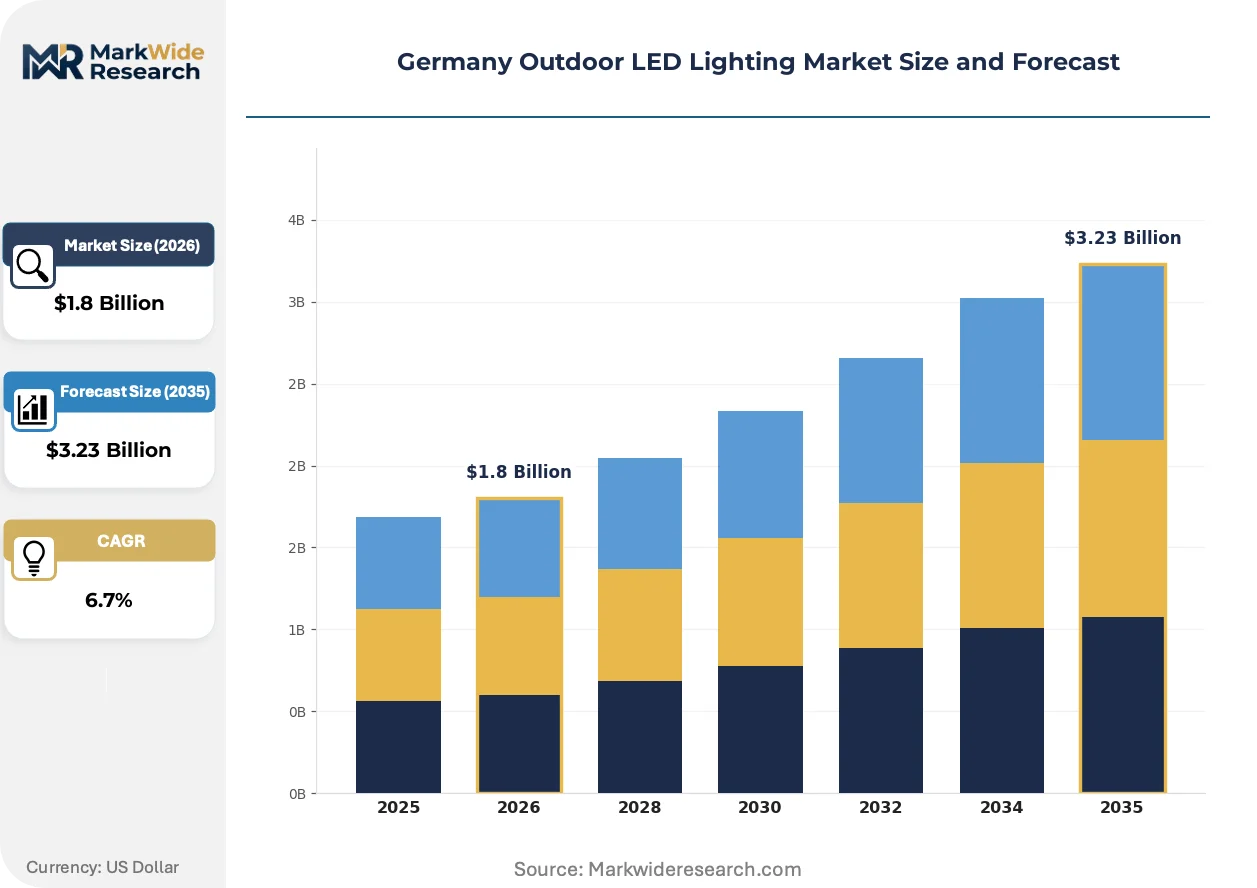
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Street Lights, Garden Lights, Flood Lights, Signage Lights Technology: Smart Lighting, Solar Lighting, Conventional Lighting, Motion Sensor Lighting Application: Public Spaces, Outdoor Advertising, Sports Facilities, Residential Areas End User: Municipalities, Commercial Establishments, Homeowners, Event Organizers |
| Companies Covered | Zumtobel Group AG, LEDVANCE GmbH, Signify Holding, ROBERS-LEUCHTEN GmbH & Co KG, Siteco GmbH, ams-OSRAM AG, Thorn Lighting Ltd, Dialight PLC, TRILUX GmbH & Co KG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Outdoor LED Lighting Market Trends and Innovations
Connected infrastructure architectures are displacing passive luminaire deployment as the default municipal specification. German cities now prioritize remote operability and data extraction over standalone efficiency metrics.
Adaptive dimming algorithms paired with occupancy sensing are integrating motion-responsive controls into standard street lighting specifications. Municipal operators in Hamburg and Frankfurt deploy these systems to reduce off-peak energy draw. The technology is integrating fault-detection telemetry that compresses maintenance dispatch cycles from weeks to hours.
The EU Green Deal's building renovation mandates extend to outdoor infrastructure through national transposition under Germany's Federal Immission Control Act. These frameworks impose minimum performance thresholds that filter substandard imports from Eastern European suppliers. Tunnel and roadway segments face the tightest compliance windows under KBA technical guidelines.
Aggregated framework contracting is displacing single-project bidding as the dominant municipal acquisition model. Mid-sized lighting specialists lose access to direct city relationships as procurement centralizes at state or multi-city level. This concentration is most visible in North Rhine-Westphalia, where regional purchasing cooperatives now handle technical specification and vendor qualification collectively.
Germany Outdoor LED Lighting Market Segmentation
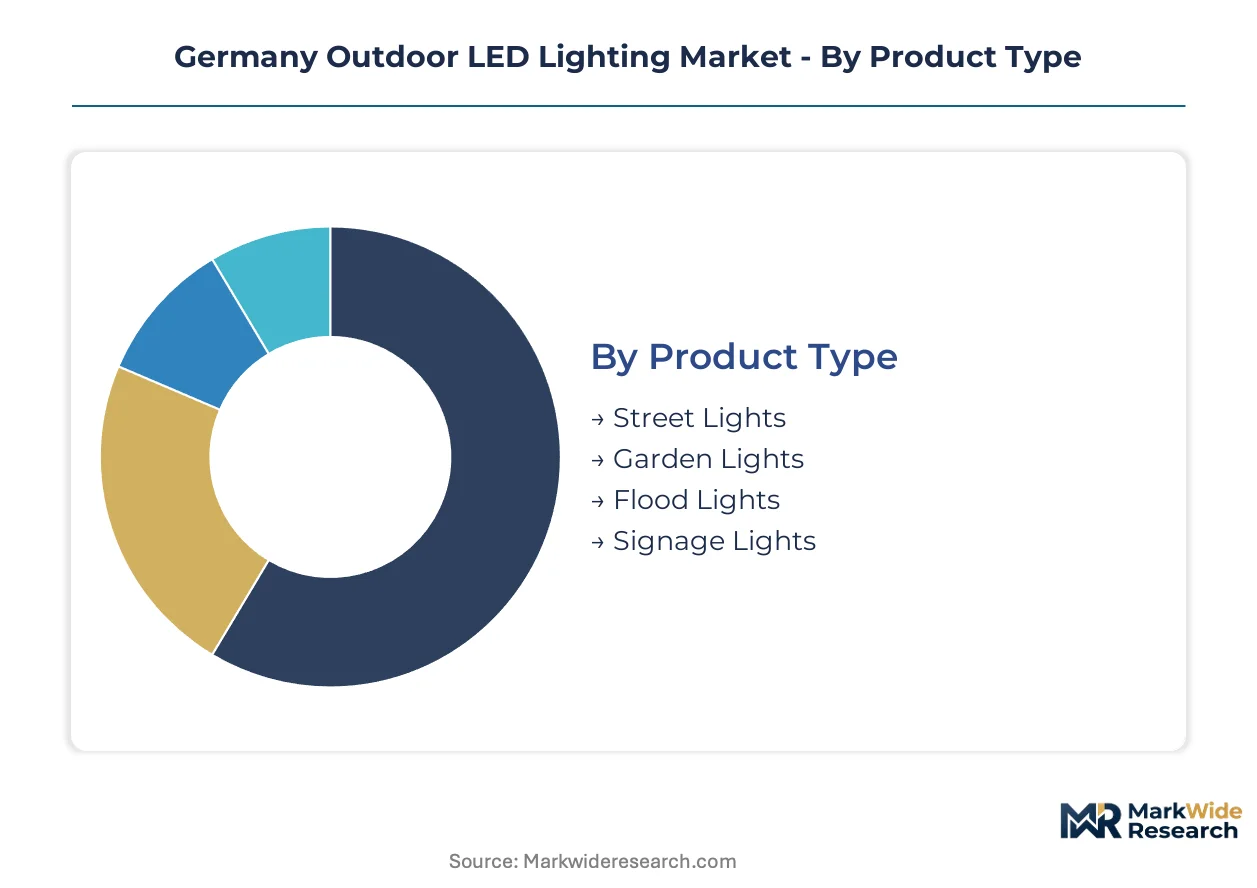
Segmentation in Germany's outdoor LED lighting market reveals how procurement consolidation and regulatory pressure reshape competitive positioning across distinct technology tiers and customer categories. Understanding these boundaries exposes where margin pools concentrate and which integration depths command premium pricing.
Product Type:
Standalone luminaire categories dominate installed volume, while embedded systems with sensor integration capture expanding specification share in North Rhine-Westphalia's consolidated tenders.
- Street Lights:High-output solid-state luminaires engineered for roadway photometric compliance under DIN EN 13201 standards. Demand concentrates across Düsseldorf, Cologne, and Essen where KBA guidelines for tunnel and roadway illumination drive replacement timelines.
- Flood Lights:Directional high-intensity fixtures deployed for perimeter security and commercial facade illumination. Sports facilities in Bavaria and industrial zones in Baden-Württemberg generate concentrated procurement volume for high-efficacy models exceeding 150 lumens per watt.
- Garden Lights:Low-mount decorative luminaires for residential and hospitality landscaping.
- Signage Lights:Edge-lit and backlit modules for commercial branding and wayfinding applications.
Volume placements concentrate in Street Lights; the faster expansion belongs to Flood Lights.
Technology:
Cost tier stratification separates premium connected infrastructure from commodity replacement luminaires, with mid-tier solar hybrids gaining traction in off-grid perimeter applications.
- Smart Lighting:Mesh-networked luminaires with remote dimming, fault telemetry, and sensor fusion capabilities. Hamburg and Frankfurt municipal operators prioritize these systems for adaptive energy management and compressed maintenance dispatch cycles.
- Conventional Lighting:Passive LED retrofits without connectivity or control intelligence. Legacy HPS replacement projects in Saxony and rural municipalities favor this tier where budget constraints outweigh smart-city ambitions.
- Solar Lighting:Photovoltaic-battery hybrid systems eliminating trenching infrastructure. Rural Baden-Württemberg perimeters and Saxon agricultural facilities deploy these where grid connection costs prove prohibitive.
- Motion Sensor Lighting:Occupancy-responsive controls integrated at luminaire or network level.
Conventional Lighting retains dominant volume share; Smart Lighting climbs the fastest on municipal specification shifts.
Application:
Customer type maturity varies sharply, with public sector procurement centralization contrasting fragmented residential decision-making.
- Public Spaces:Street, square, and park illumination under municipal or state ownership. North Rhine-Westphalia's regional purchasing cooperatives aggregate technical specification and vendor qualification for this segment.
- Sports Facilities:Stadium and arena lighting meeting broadcast and player safety standards. Compliance windows under KBA technical guidelines and DIN standards create concentrated replacement demand.
- Outdoor Advertising:Billboard and digital display illumination for commercial messaging.
- Residential Areas:Private driveway, garden, and security lighting for homeowners and housing associations.
Public Spaces anchor procurement volume; Sports Facilities show steepest expansion trajectory on renovation mandates.
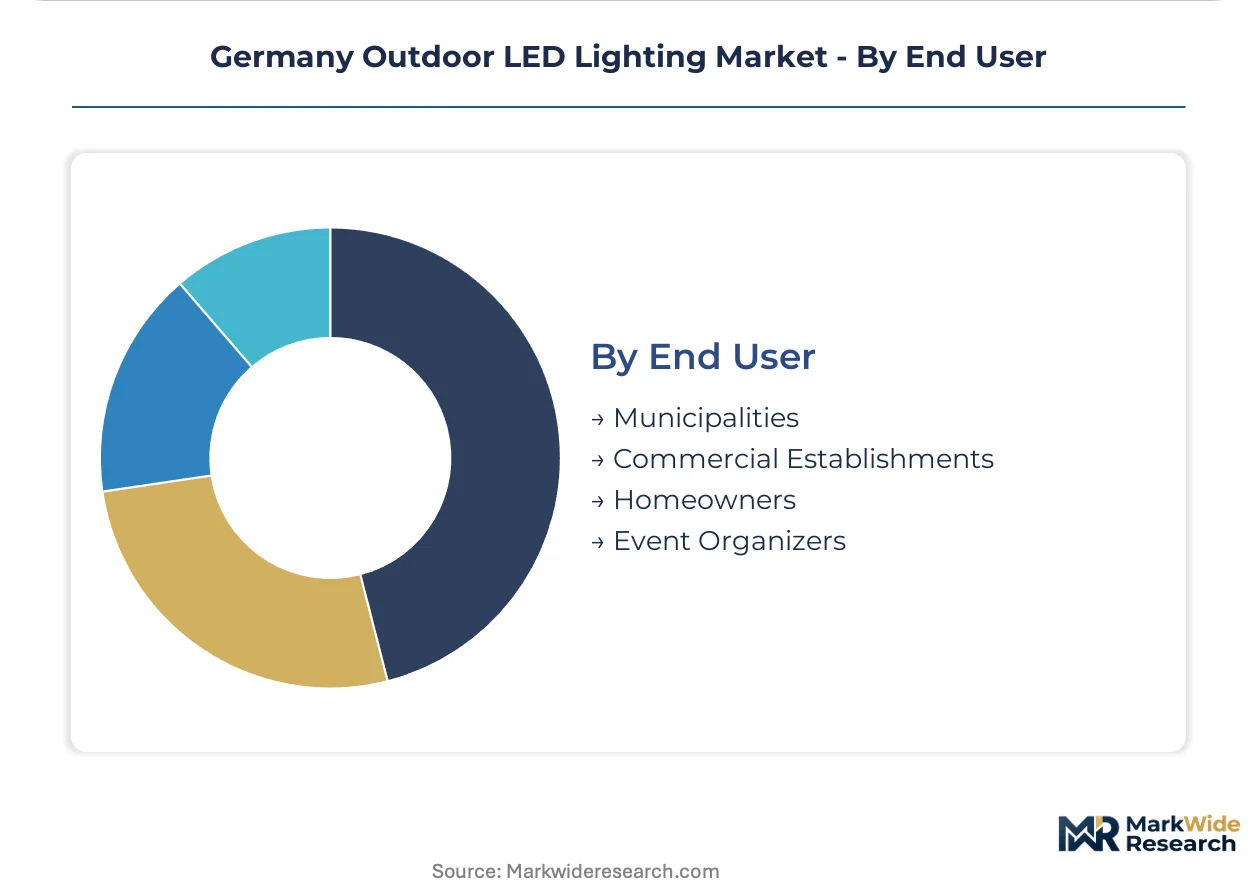
End User:
Supply concentration aligns with customer scale, where framework-contract specialists serve aggregated tenders while regional distributors fragment across small commercial and residential accounts.
- Municipalities:City, state, and federal agencies procuring through centralized frameworks. Procurement consolidation across German cities compresses supplier margins while favoring logistics-scale specialists.
- Commercial Establishments:Retail, hospitality, and industrial operators specifying exterior illumination. Energy efficiency standards under the Federal Immission Control Act shape minimum performance thresholds for this segment.
- Homeowners:Individual residential purchasers selecting decorative and security luminaires.
- Event Organizers:Temporary installation operators for festivals and construction sites.
Municipalities dominate absolute volume placements; Commercial Establishments gain share fastest on Ecodesign compliance deadlines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Rhine-Westphalia concentrates the strongest demand pull for outdoor LED infrastructure, with municipal procurement cooperatives aggregating specification authority across Düsseldorf, Cologne, and Essen. Federal efficiency mandates under the EU Green Deal accelerate replacement timelines nationwide.
North Rhine-Westphalia
Düsseldorf, Cologne, and Essen drive concentrated street and tunnel lighting upgrades through regional purchasing cooperatives. KBA technical guidelines for roadway illumination compress compliance windows. The Rhine-Ruhr metropolitan corridor anchors Germany's densest smart-city infrastructure deployment.
Bavaria
Munich and Nuremberg municipalities lag neighboring states in connected infrastructure adoption. Federal Immission Control Act efficiency standards shape minimum performance thresholds for commercial exterior installations. Bavarian sports facilities generate specialized demand for high-output flood lighting.
Baden-Württemberg
Stuttgart's industrial zones and rural perimeter applications split demand between grid-connected and solar-plus-storage configurations. DIN EN 13201 photometric compliance requirements filter substandard imports. Agricultural facilities in Saxony deploy off-grid photovoltaic-battery hybrids where trenching costs prove prohibitive.
Hamburg
Municipal operators prioritize adaptive dimming algorithms paired with occupancy sensing for off-peak energy reduction. Fault-detection telemetry compresses maintenance dispatch cycles from weeks to hours. Hamburg's port infrastructure generates specialized marine-grade luminaire demand.
Berlin-Brandenburg
The capital region aggregates federal procurement for public square and monument illumination. EU Ecodesign revisions tighten minimum efficacy thresholds ahead of mandate deadlines. Berlin's smart-city pilot programs test LiDAR-integrated sensor fusion for traffic monitoring applications.
Germany Outdoor LED Lighting Market Competitive Landscape
German producers anchor the premium luminaire tier; Asian component specialists hold upstream supply control. Municipal procurement consolidation compresses margins for mid-scale fabricators while favoring framework-contract logistics operators. Three archetypes dominate: vertically integrated luminaire manufacturers, distribution-network aggregators, and captive LED chip suppliers. Competitive moves concentrate on compliance bundling and smart-system integration partnerships.
Within the integrated manufacturing tier, TRILUX GmbH & Co KG and LEDVANCE GmbH exemplify divergent scale strategies—one through in-house production depth, the other through broad distribution reach. ams-OSRAM AG occupies a position as the dominant upstream component anchor, supplying critical chip architectures that downstream assemblers depend upon. These three entities represent the structural fault lines between captive supply control, manufacturing integration, and logistics-scale aggregation.
| Leading Market Players |
|---|
| Zumtobel Group AG |
| LEDVANCE GmbH |
| Signify Holding |
| ROBERS-LEUCHTEN GmbH & Co KG |
| Siteco GmbH |
| ams-OSRAM AG |
| Thorn Lighting Ltd |
| Dialight PLC |
| TRILUX GmbH & Co KG |
| Others |
Pricing and Supply Chain Analysis
The EU Green Deal's building renovation mandates gate qualified supply and premium-tier pricing access, compressing margins for non-compliant luminaire assemblers while rewarding framework-contract specialists who bundle certification and logistics at scale.
Pricing Analysis
Volume placements concentrate in conventional LED retrofits where municipal budget constraints dominate, while smart lighting with mesh-networked controls captures margin premiums through remote operability and fault telemetry. Price differentiation separates DIN EN 13201-certified fixtures from uncertified imports, with KBA guideline compliance adding further tier separation for tunnel and roadway applications. Pricing pressure stems from aggregated framework contracting across North Rhine-Westphalia's regional purchasing cooperatives, which compresses supplier margins through volume concentration. Municipalities exhibit highest price sensitivity in legacy HPS replacement projects, while commercial establishments in Hamburg and Frankfurt accept premiums for adaptive dimming and occupancy-responsive systems.
Supply Chain Analysis
Single-source vulnerability sits with Asian upstream LED component suppliers, where German downstream assemblers draw critical chip architectures from concentrated manufacturing bases in China, Taiwan, and South Korea. Raw material dependencies center on copper and aluminum for heat sinks and housings, alongside rare-earth phosphors for color rendering and silicon substrates for driver electronics. Supply chain risk manifests in commodity price volatility for these metals, which compresses margin predictability for fixture manufacturers when alloy markets fluctuate. Distribution runs through vertically integrated luminaire producers like TRILUX and broad-network aggregators like LEDVANCE, with regional distributors fragmenting across small commercial and residential accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Germany outdoor LED lighting market sits in a technology-transition phase where connected infrastructure architectures displace passive luminaire deployment as the default municipal specification, with solid-state LED systems replacing legacy high-pressure sodium vapor installations.
For Market Incumbents: Extend framework-contract relationships with North Rhine-Westphalia's regional purchasing cooperatives to defend against margin compression from procurement consolidation. Deepen in-house production of LED drivers and optical systems to reduce captive dependence on Asian chip suppliers. Invest in firmware development capabilities for mesh-networked controls, as embedded systems engineering scarcity in German technical universities threatens smart-system integration timelines. For New Entrants and Emerging Players: Bavarian municipalities in Munich and Nuremberg present underserved buyer archetypes trailing neighboring states in connected infrastructure adoption. Solar-plus-storage perimeter lighting in rural Baden-Württemberg and Saxony offers whitespace where trenching costs deter incumbent grid-connected offerings. A go-to-market angle through agricultural facility cooperatives bypasses consolidated municipal procurement channels entirely. For Investors and Strategic Acquirers: EU Ecodesign revisions tightening minimum efficacy thresholds to 150 lumens per watt are the leading indicator that replacement demand will accelerate ahead of mandate deadlines. Long-term viability favors vertically integrated luminaire manufacturers with captive optical design and driver electronics capabilities over pure-play distributors. Acquisition targets should demonstrate DIN EN 13201 certification infrastructure and existing relationships with KBA guideline compliance programs for tunnel and roadway segments.| Strategic Initiative | Industry Significance |
|---|---|
| Smart-System Integration Partnership | Mesh-networked controls with LiDAR sensor fusion expand addressable use cases beyond illumination for Hamburg and Frankfurt operators. |
| Framework-Contract Logistics Scale-Up | Aggregated tender serving capability positions suppliers for North Rhine-Westphalia's consolidated municipal procurement. |
| Backward Integration into Driver Electronics | In-house LED driver production reduces vulnerability to Asian upstream allocation shocks and commodity volatility. |
| Solar-Plus-Storage Product Line Expansion | Photovoltaic-battery hybrids capture off-grid perimeter demand in rural Baden-Württemberg where trenching costs dominate. |
| Firmware Development Talent Acquisition | Embedded systems engineering capabilities accelerate smart-city deployment timelines constrained by German university output. |
Research Methodology
Trade association filings, customs and import records, and KBA technical guideline documentation formed the secondary backbone of this analysis. Primary interviews with municipal procurement officers, luminaire manufacturing executives, embedded systems engineers, and regional distribution channel partners validated demand assumptions and replacement timeline estimates. Bottom-up unit shipment modeling across street, flood, garden, and signage luminaire categories triangulated against top-down value estimates derived from framework-contract award values.
Historical trendline analysis of municipal LED adoption rates, HPS retrofit completion patterns, and smart-city infrastructure budgets informed the projection framework. Segmentation dimensions modeled include product type, technology tier, application vertical, and end-user category, with regional regulatory cluster variations for North Rhine-Westphalia, Bavaria, Baden-Württemberg, Hamburg, and Berlin-Brandenburg. CAGRs were derived from replacement cycle acceleration under F-Gas Regulation tightening and EU Green Deal mandate transposition, incorporating efficacy threshold escalation and procurement consolidation velocity as industry-specific inputs.
Revisions become necessary when F-Gas Regulation phaseout timelines shift, EU Ecodesign efficacy thresholds are modified, or municipal procurement centralization extends beyond current state-level aggregation. Forecasts reflect documented assumptions regarding technology cost curves and regulatory compliance windows. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Saudi Arabia LED Lights Market
LED
GCC LED Lighting Market
LED
North America LED Packaging Market
LED
Global LED Phosphor Market
LED
LED Mask Market
LED
UV LED Market
LED
France Indoor LED Lighting Market
LED
Surface Mount PLCC Leds Market
LED
LED Encapsulation Market
LED
Xenon Market
LED
LED Lighting Solution Market
LED
Europe LED Lighting Market
LED
LED Display Market
LED
LED and OLED Display Market
LED
France Outdoor LED Lighting Market
LED
Europe LED Packaging Market