
 United States Optoelectronics Market | 2026-2036
United States Optoelectronics Market Size, Share, and Industry Trends Forecast 2026-2036
United States Optoelectronics Market Insights
Modular packaging of laser subassemblies is decoupling sourcing decisions from full-system procurement, letting buyers mix photonic engines with third-party thermal management. Broadcom Inc. leverages vertical integration across gallium arsenide epitaxy and silicon photonics to control wafer supply. Lumentum Holdings Inc. anchors its position through specialized pump lasers for optical amplifiers. Texas Instruments Inc. competes by extending analog-to-digital converter integration into optoelectronic sensor modules.
Optoelectronics encompasses devices that emit, detect, or modulate light across ultraviolet through infrared wavelengths, typically fabricated from III-V compound semiconductors such as indium phosphide and gallium nitride with bandgap engineering precise to within nanometers for target emission spectra. These components serve as the transduction layer in systems converting between optical signals and electrical currents for communications, imaging, and illumination. Image sensors and laser diodes command the deepest margin pools where automotive lidar and medical endoscopy drive specification escalation. LED modules for general illumination represent a mature volume base with price compression offset by energy harvesting applications in building-integrated photovoltaics. Organic Light Emitting Diode displays sustain premium positioning in consumer electronics where foldable form factors require flexible emitter substrates.
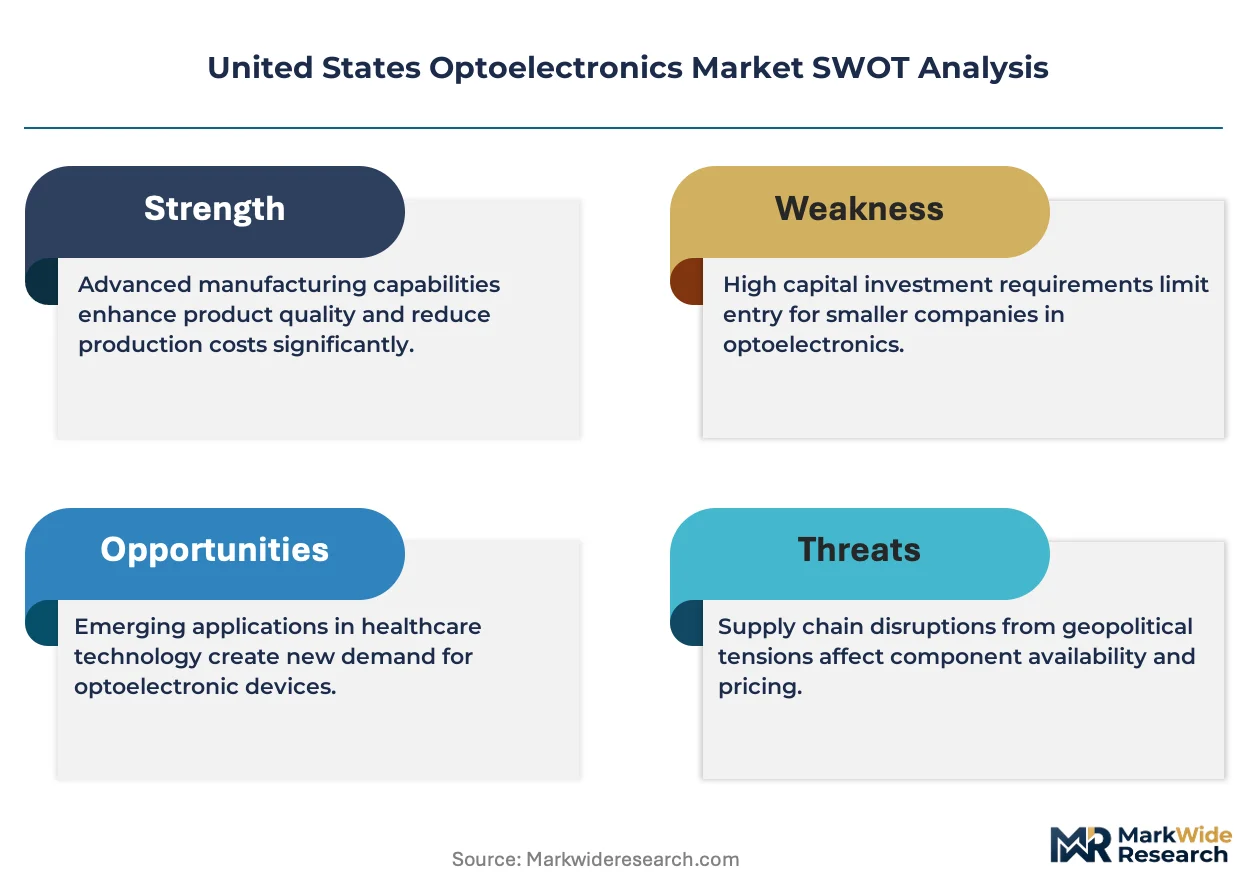
FDA device classification rules shape clinical adoption pathways for optoelectronic diagnostic equipment, while FCC spectrum allocations directly determine permissible wavelengths for free-space optical communications. The CHIPS and Science Act funding criteria from the Department of Commerce are redirecting capital toward domestic compound semiconductor foundries. NHTSA automated vehicle guidance is mandating minimum performance thresholds for lidar and camera systems that cascade back to emitter and detector specifications. Stakeholders must track how BIS export control refinements on epitaxial growth equipment affect equipment availability and foundry expansion timelines.
Market Dynamics
Defense procurement of infrared sensing modules is restructuring supply relationships as prime contractors decouple photonic engine sourcing from full-system integration. The CHIPS and Science Act is redirecting capital toward domestic compound semiconductor foundries in Arizona and Texas, reshaping wafer supply geography.
Growth Catalysts
- CHIPS and Science Act funding:Department of Commerce criteria accelerate domestic gallium arsenide and indium phosphide wafer fabrication capacity, concentrating investment near packaging clusters in the Southwest.
- NHTSA automated vehicle guidance:Mandatory minimum performance thresholds for lidar and camera systems cascade back to emitter and detector specifications, pulling demand for high-precision components.
- Medical endoscopy specification escalation:FDA device classification rules for optoelectronic diagnostic equipment create structured adoption pathways that reward advanced imaging capabilities.
Market Restraints
- Epitaxial growth equipment access:BIS export control refinements on metal-organic chemical vapor deposition systems constrain equipment availability and extend foundry expansion timelines.
- Compound semiconductor feedstock concentration:High-purity gallium and indium refining capacity concentrates in limited overseas suppliers, exposing wafer fabs to input volatility.
- Silicon photonics substitution threat:CMOS-compatible optical interconnects displace III-V devices in data center applications below 100 Gbps, compressing addressable market for traditional laser diodes.
Strategic Opportunities
- Building-integrated photovoltaics:LED module manufacturers extend into energy harvesting applications where transparent photovoltaic glass creates dual-use building envelopes.
- Texas and Arizona cluster proximity:Foundry investments near packaging and test facilities enable co-design of photonic engines with thermal management subsystems, shortening development cycles.
- FCC spectrum allocations for free-space optical:Permissible wavelength expansions for unlicensed optical communications open terrestrial backhaul applications for infrared laser modules.
Industry Challenges
- Compound semiconductor process engineering talent:Wafer fabrication expansion outpaces domestic training pipelines for epitaxial growth and bandgap engineering specialists.
- Multi-material integration complexity:Packaging houses face yield challenges bonding gallium nitride emitters to silicon readout circuits with mismatched thermal expansion coefficients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Optoelectronics Market |
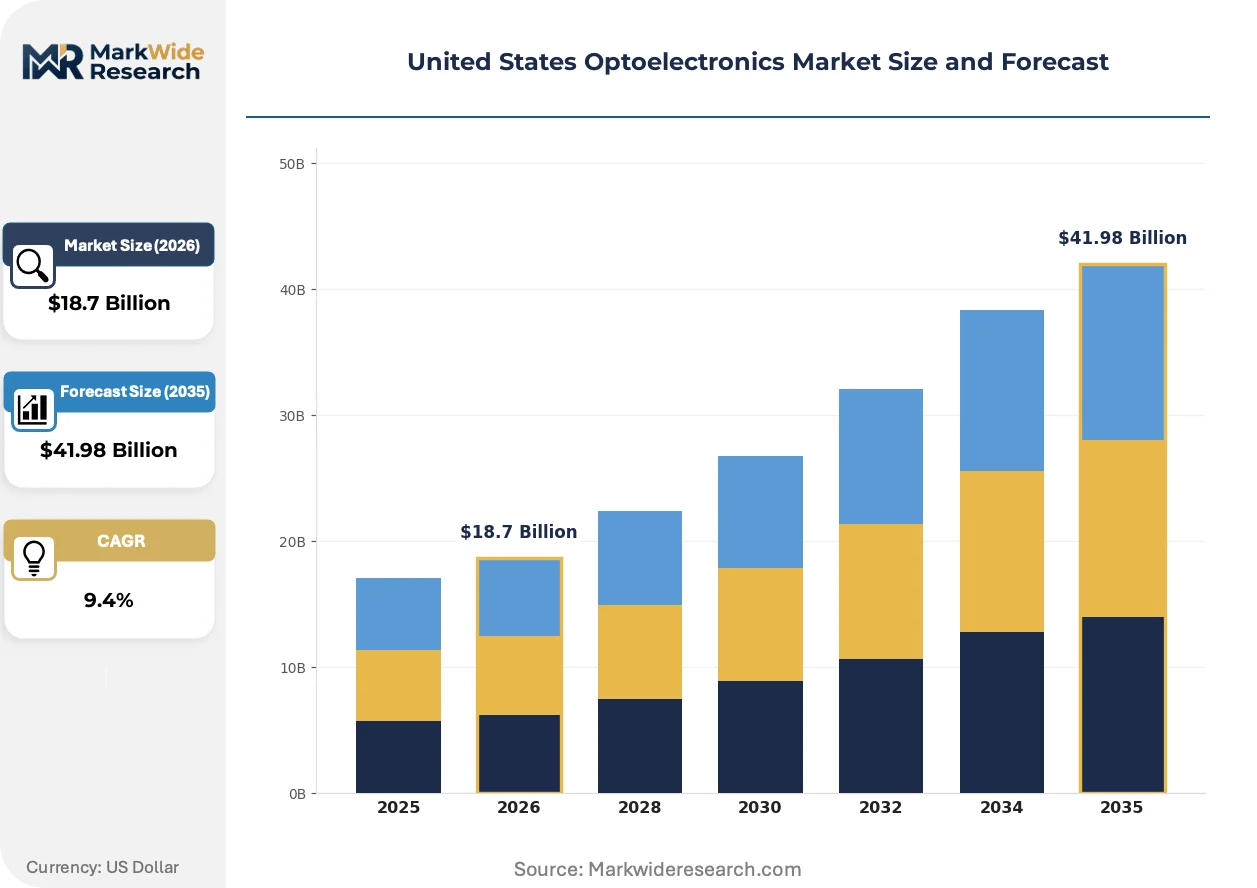
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Laser Diode, Photodiode, Image Sensor Technology: Quantum Dot, Organic Light Emitting Diode, LCD, OLED End User: Telecommunications, Consumer Electronics, Automotive, Healthcare Application: Lighting, Display, Sensing, Energy Harvesting |
| Companies Covered | Broadcom Inc., II-VI Incorporated, Lumentum Holdings Inc., Omnivision Technologies Inc., Finisar Corporation, Texas Instruments Inc., Sony Corporation, Samsung Electronics, General Electric Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Optoelectronics Market Trends and Innovations
Photonic system architecture is fragmenting into interchangeable subassemblies, enabling buyers to source laser engines, thermal management, and optical conditioning from separate suppliers rather than single-system vendors.
Silicon photonics with integrated germanium photodetectors is modularizing transceiver design for data center interconnects. Cloud infrastructure operators now specify optical engines independently from switch ASICs. This decoupling compresses supplier margins on complete modules while expanding addressable market for specialized photonic component vendors.
The CHIPS and Science Act funding criteria from the Department of Commerce require domestic wafer fabrication for qualified investments, forcing foreign-owned foundries to accelerate US greenfield construction. Compound semiconductor facilities in Arizona and Texas must demonstrate supply chain security plans to access subsidies. Defense contractors are restructuring qualification programs to prioritize components from these domestic sources.
Prime contractors in aerospace and automotive are unbundling photonic subsystem procurement from full-platform awards, creating direct purchasing relationships with laser diode and detector manufacturers. Tier-one suppliers that previously captured this margin now face disintermediation. This pattern is most visible in Detroit and Dallas-Fort Worth automotive clusters where lidar module makers sell directly to vehicle OEMs.
United States Optoelectronics Market Segmentation
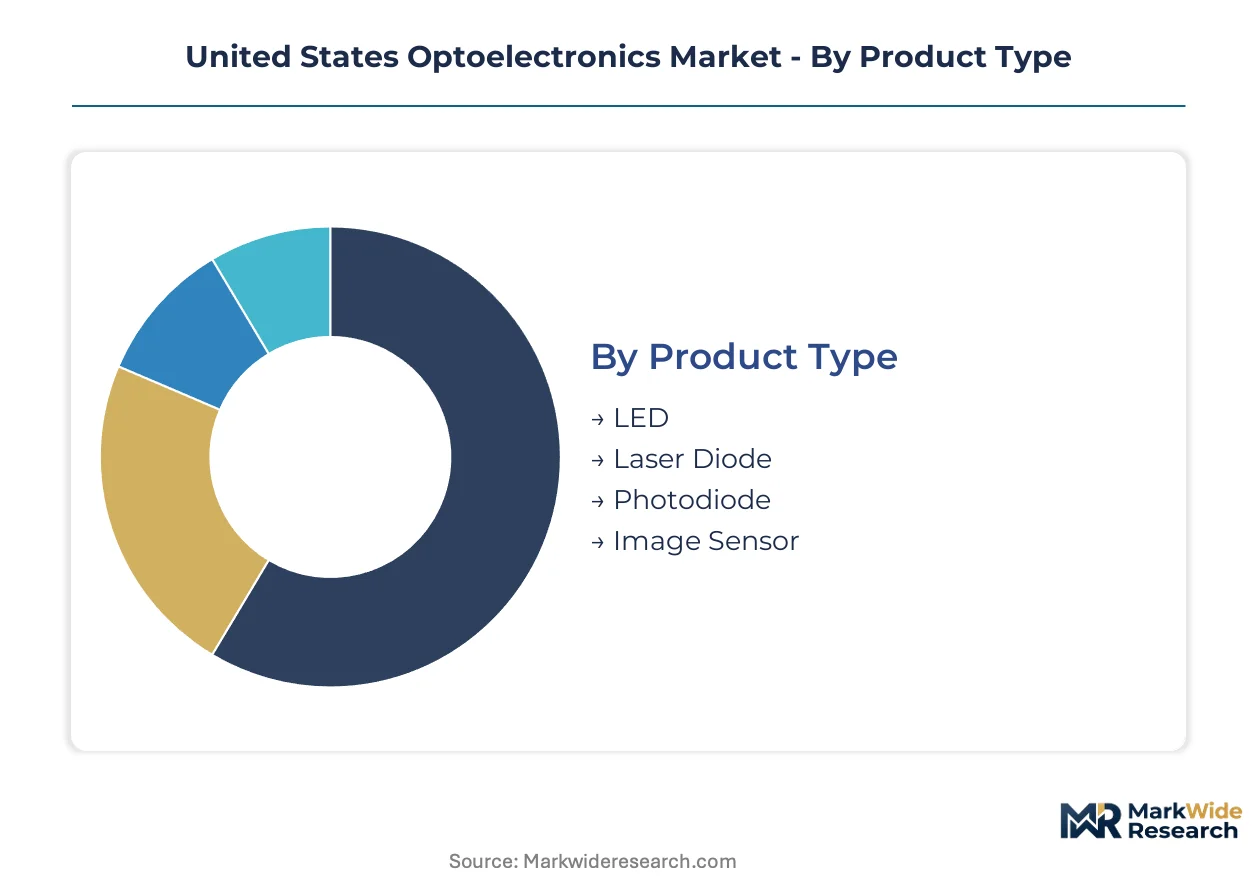
Optoelectronics procurement splits between standalone devices and deeply embedded photonic engines. Component selection cascades through system architecture decisions that lock in thermal budgets, optical coupling efficiency, and regulatory compliance pathways.
Product Type:
Integration depth varies sharply across this category, with some segments shipping as discrete devices while others embed directly into multi-chip modules.
- LED:Solid-state emitters fabricated from gallium nitride epilayers on sapphire or silicon carbide substrates dominate general illumination retrofits. Building-integrated photovoltaic installations in Arizona and Texas drive demand for transparent conductive oxide variants.
- Laser Diode:Edge-emitting and vertical-cavity surface-emitting structures convert electrical current to coherent light with nanometer-scale wavelength precision. Automotive lidar specifications from NHTSA pull demand for 905 nm and 1550 nm emitters toward Detroit-area qualification programs.
- Photodiode:PIN and avalanche structures detect optical signals across ultraviolet through infrared bands.
- Image Sensor:CMOS and CCD arrays capture photon flux for machine vision and medical imaging.
Volume placements concentrate in LED retrofits; the faster expansion belongs to laser diodes.
Technology:
Cost tiers separate mature volume production from emerging deposition processes with yield learning curves still steep.
- Quantum Dot:Nanocrystal emitters with size-tunable bandgaps enable narrow-linewidth displays and biological labeling applications. QD-OLED panels command premium positioning in consumer electronics where Samsung Display and TCL CSOT compete on color gamut coverage.
- Organic Light Emitting Diode:Thin-film organic semiconductor stacks emit light without backlighting, enabling foldable and rollable form factors. LG Display's investment in Gen 8.6 IT OLED lines in Korea pressures domestic manufacturers to accelerate phosphorescent emitter development.
- LCD:Liquid crystal modulators with LED backlighting retain cost advantage in large-format displays.
- OLED:Small-molecule and polymer variants compete on lifetime and power efficiency metrics.
LCD retains the largest installed base; quantum dot displays are climbing the fastest.
End User:
Customer type determines specification rigor, with automotive and healthcare imposing qualification barriers that consumer electronics bypass.
- Telecommunications:Datacenter interconnect and 5G fronthaul consume coherent transceivers and pump lasers for erbium-doped fiber amplifiers. Hyperscale operators in Ashburn and Dallas specify optical engines independently from switch ASICs.
- Consumer Electronics:Smartphone displays, camera modules, and facial recognition systems drive high-volume, short-lifecycle procurement. Apple and Samsung camera specification escalation pulls demand toward larger optical format sensors.
- Automotive:Lidar, interior lighting, and driver monitoring systems impose AEC-Q100 and ISO 26262 compliance requirements.
- Healthcare:Endoscopic imaging and pulse oximetry face FDA 510(k) clearance pathways.
Consumer electronics generates the highest unit volumes; automotive applications show the steepest expansion trajectory.
Application:
Maturity gradients separate established illumination markets from sensing and energy harvesting segments still defining performance benchmarks.
- Lighting:General illumination and horticultural applications exploit LED efficacy improvements and spectral tunability. Commercial retrofits in California and New York prioritize DLC Premium qualification for utility rebate capture.
- Display:Television, monitor, and smartphone panels account for the largest revenue concentration in optoelectronics. MicroLED transfer yield challenges delay mass production timelines despite LuxVue and PlayNitride development efforts.
- Sensing:Proximity detection, gesture recognition, and environmental monitoring expand addressable market for photodiode arrays.
- Energy Harvesting:Transparent photovoltaic glass and thermophotovoltaic emitters create dual-use building envelopes.
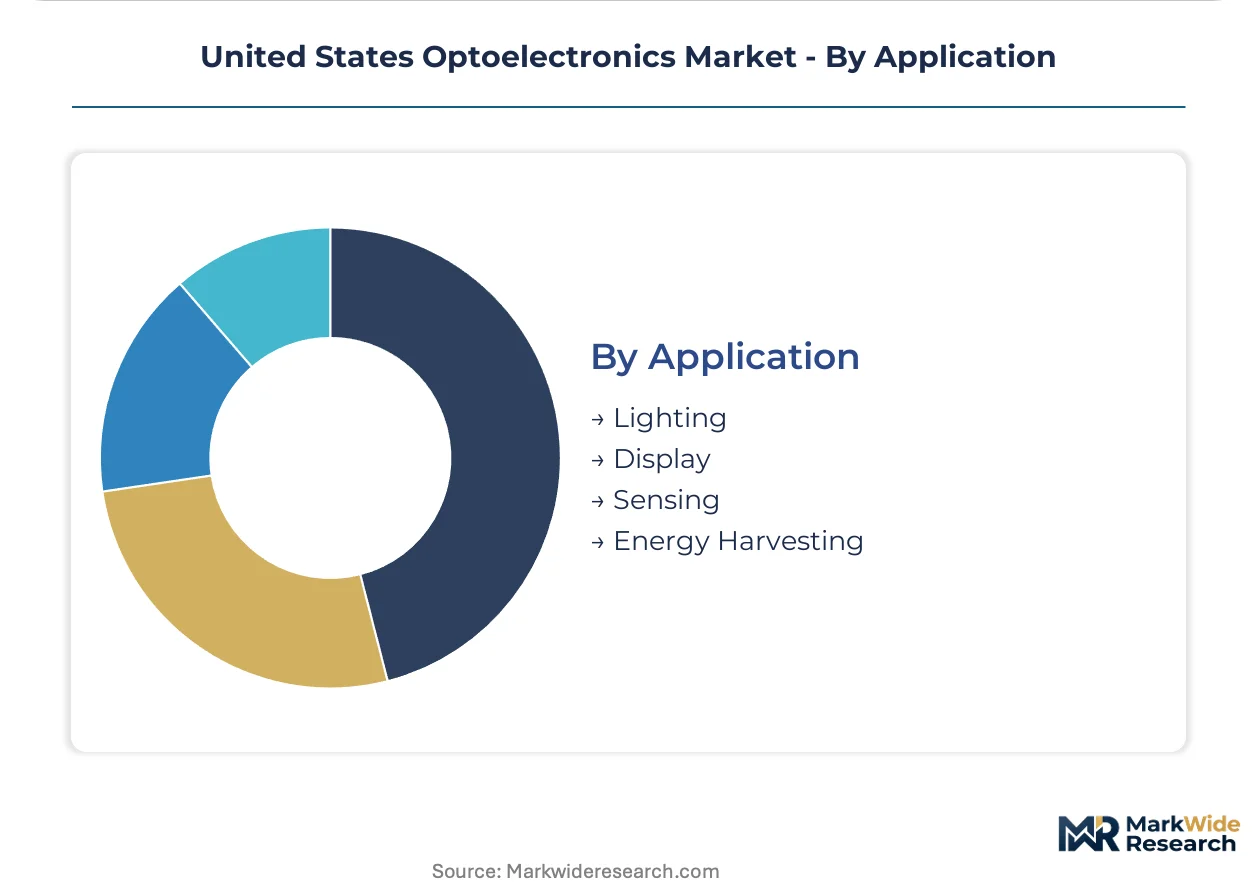
Display applications capture the deepest margin pools; energy harvesting is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic wafer fabrication capacity lags consumption demand, forcing reliance on imported compound semiconductor substrates while CHIPS Act investments rebuild southwestern production clusters.
Arizona
TSMC's Phoenix fab complex and Intel's expansion in Chandler concentrate leading-edge logic and photonics manufacturing. Department of Commerce CHIPS Act funding criteria prioritize domestic compound semiconductor fabrication, accelerating gallium arsenide and indium phosphide capacity builds near packaging facilities. The Phoenix-Tucson corridor hosts emerging foundry-packing-test integration hubs.
Texas
Samsung's Taylor fab and Texas Instruments' Sherman expansion anchor the state's semiconductor manufacturing resurgence. NHTSA automated vehicle guidance mandating lidar performance thresholds pulls automotive photonics qualification programs toward Dallas-Fort Worth. Austin-San Antonio corridor firms specialize in photonic engine-thermal management co-design.
California
Silicon Valley retains design leadership for optical interconnects and sensing algorithms despite manufacturing migration. FDA device classification rules for optoelectronic diagnostic equipment shape clinical adoption pathways emanating from San Diego medical device clusters. Bay Area hyperscale operators specify optical engines independently from switch ASICs.
Michigan
Detroit-area automotive OEMs source lidar modules directly from photonic component manufacturers, bypassing traditional tier-one suppliers. NHTSA performance thresholds cascade to emitter and detector specifications, concentrating qualification relationships in Ann Arbor-Detroit corridor. Automotive lidar specification escalation drives 905 nm and 1550 nm emitter demand.
Massachusetts
Greater Boston's defense contractors modernize infrared sensing modules for targeting systems, restructuring supply relationships toward domestic photonic engine sourcing. DOD procurement prioritizes components from CHIPS Act-qualified domestic foundries, benefiting Massachusetts-based prime contractors. Route 128 corridor firms specialize in military-grade optoelectronic subsystem integration.
United States Optoelectronics Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct capability tiers. The vendor base organizes around three strategic archetypes: vertically integrated compound semiconductor fabricators controlling epitaxy through packaging, modular photonic engine suppliers selling standardized subassemblies, and analog-centric semiconductor firms extending converter integration into sensor modules. Dominant competitive moves include foundry capacity expansion in Arizona and Texas, plus direct procurement relationships between component makers and automotive OEMs that disintermediate tier-one system integrators.
Within the vertically integrated tier, Broadcom Inc. and Lumentum Holdings Inc. exemplify contrasting approaches to supply chain control, while Texas Instruments Inc. anchors the analog-integration archetype. Broadcom's position reflects backward integration across gallium arsenide epitaxy and silicon photonics. Lumentum occupies a specialized position through pump laser manufacturing for optical amplification systems. Texas Instruments represents the extension of analog-to-digital converter technology into optoelectronic sensor module integration.
| Leading Market Players |
|---|
| Broadcom Inc. |
| II-VI Incorporated |
| Lumentum Holdings Inc. |
| Omnivision Technologies Inc. |
| Finisar Corporation |
| Texas Instruments Inc. |
| Sony Corporation |
| Samsung Electronics |
| General Electric Company |
| Others |
Pricing and Supply Chain Analysis
Defense prime contractors and automotive OEMs concentrate procurement leverage, driving contract-based long-term offtake pricing for photonic engines while spot-market volatility persists for commodity LED modules. NHTSA-mandated lidar specifications and FDA device classification tiers create quality-grade price differentiation that insulates certified suppliers from raw material cost swings.
Pricing Analysis
Margin tightening in laser diode tiers reflects silicon photonics substitution below 100 Gbps data center interconnects. Three-tier pricing structure across automotive-grade AEC-Q100, industrial-temperature, and commercial-off-the-shelf levels separates qualification investment from volume scale. Pricing pressure intensifies in general illumination LED modules as building-integrated photovoltaic applications absorb margin. Automotive OEMs exhibit lowest price sensitivity due to liability exposure; consumer electronics buyers drive hardest cost-down negotiations.
Supply Chain Analysis
Freight cost escalation from high-purity gallium and indium refining centers in China and Germany compounds input volatility for Arizona and Texas wafer fabs. Domestic compound semiconductor manufacturing draws from Taiwan and South Korea for epitaxial growth equipment, while metal-organic chemical vapor deposition systems face BIS export control restrictions. Single-source vulnerability concentrates in overseas feedstock refining. Distribution runs through direct procurement relationships between photonic engine makers and automotive OEMs, bypassing traditional tier-one system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Optoelectronics Market operates as a cost-of-compliance story where CHIPS Act domestic content requirements erect barrier-to-entry moats for qualified foundries. FDA 510(k) pathways and NHTSA automated vehicle guidance cascade specification rigor that rewards pre-certified component suppliers.
For Market Incumbents: Cement backward integration into gallium arsenide epitaxy to secure wafer supply against foreign-owned foundry expansion. Lock in direct procurement relationships with Detroit-area automotive OEMs before tier-one suppliers reassert intermediary control. Prioritize Arizona and Texas packaging co-location to satisfy Department of Commerce supply chain security plan requirements for subsidy access.
For New Entrants and Emerging Players: Digital channel partnerships with cloud infrastructure operators bypass entrenched switch ASIC vendor relationships for optical engine sales. Target building-integrated photovoltaic applications where transparent conductive oxide LED variants face limited incumbent specialization. Pursue FCC spectrum allocation expansions for free-space optical communications as regulatory-driven demand catalyst.
For Investors and Strategic Acquirers: The window for entry favors compound semiconductor process engineering specialists with captive epitaxial growth capability. Long-term viability hinges on qualification relationships with defense prime contractors restructuring toward domestic sourcing. Monitor BIS export control refinement announcements as inflection signal for equipment availability and foundry expansion timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Foundry Capacity Expansion | CHIPS Act subsidies accelerate gallium arsenide and indium phosphide wafer fabrication in Arizona and Texas clusters. |
| Photonic Engine-Thermal Management Co-Design | Austin-San Antonio corridor firms shorten development cycles through packaging proximity to foundry investments. |
| Direct OEM Procurement Relationships | Lidar module makers in Dallas-Fort Worth bypass tier-one suppliers to capture margin from automotive qualification programs. |
| Silicon Photonics Platform Integration | Cloud operators in Ashburn specify optical engines independently from switch ASICs, modularizing transceiver procurement. |
| Defense Subsystem Qualification Restructuring | Massachusetts prime contractors prioritize components from CHIPS Act-qualified domestic foundries for infrared sensing modules. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with compound semiconductor fabrication executives, defense procurement officers, automotive platform engineers, and photonic packaging specialists combined with bottom-up and top-down triangulation. Secondary validation drew from Department of Commerce CHIPS Act funding announcements, FDA 510(k) device classification databases, NHTSA automated vehicle guidance documents, and SEC filings from optoelectronics component suppliers.
Data-stream reconciliation across shipment volumes, foundry capacity announcements, and end-use qualification timelines informed the analytical framework. Segmentation dimensions modeled include product type integration depth, technology cost tier, end-user specification rigor, and application maturity gradient. CAGRs derived from regression analysis against capital expenditure cycles and regulatory implementation schedules. Industry-specific forecast inputs encompassed epitaxial growth equipment lead times and automotive lidar specification escalation curves.
The model holds under sustained CHIPS Act funding disbursement and stable export control enforcement; deviation in BIS equipment licensing timelines or feedstock supply disruptions would shift capacity expansion trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Electro-Optical/Infrared (EO/IR) Systems Market
Optoelectronics
Light Projector Market
Optoelectronics
Automotive Optoelectronics Market
Optoelectronics
Optoelectronic Development Tools Market
Optoelectronics
Heterojunction Solar Cell Market
Optoelectronics
Cadmium Telluride Photovoltaic Market
Optoelectronics
Gallium Arsenide Gaas Wafer Market
Optoelectronics
Gunn Diode Market
Optoelectronics
Thermophotovoltaics Market
Optoelectronics
2-Ethyl-3,4-Ethylenedioxythiophene Market
Optoelectronics
Smart Compact Projectors Market
Optoelectronics
Ingaas Avalanche Photodiode Market
Optoelectronics
South Korea Optoelectronics Market
Optoelectronics
Quantum Dots Market
Optoelectronics
Gaas Epiwafer Market
Optoelectronics
Global Infrared Optoelectronics Market