
 Monochrome Outdoor LED Display Market | 2026-2036
Monochrome Outdoor LED Display Market Size, Share, and Industry Trends Forecast 2026-2036
Monochrome Outdoor LED Display Market Foresight
EU F-Gas Regulation phase-down targets for fluorinated greenhouse gases is restructuring procurement criteria for outdoor display cooling systems across European municipal buyers. Daktronics leverages its vertical integration in LED module fabrication to sustain margin stability amid component volatility. Unilumin anchors its competitive position through deep manufacturing scale in Shenzhen, while Absen competes on channel control across European sports venue installations.
A monochrome outdoor LED display comprises a single-color light-emitting diode matrix, typically employing aluminum-indium-gallium-phosphide or gallium-arsenide-phosphide die compositions, packaged in through-hole DIP or surface-mount SMD configurations with pixel pitches ranging from 10mm to 20mm for viewing distances beyond 30 meters. The technology serves commercial messaging, wayfinding, and scoreboard applications where full-color reproduction is unnecessary and power minimization is prioritized. Text displays dominate volume shipments for transit wayfinding, while digital billboards command premium positioning in retail storefront applications despite monochrome constraints. Wall-mounted installations lead the installation type matrix due to lower structural engineering requirements, though portable configurations are gaining traction in event venue deployments.
FCC Part 15 emissions standards in the United States and CE marking under EU electromagnetic compatibility directives shape product certification pathways for cross-border shipment. China's SAMR enforces GB energy efficiency labeling that filters non-compliant modules from government procurement tenders. Stakeholders must monitor evolving municipal sustainability mandates that increasingly embed embodied carbon thresholds into display procurement specifications.
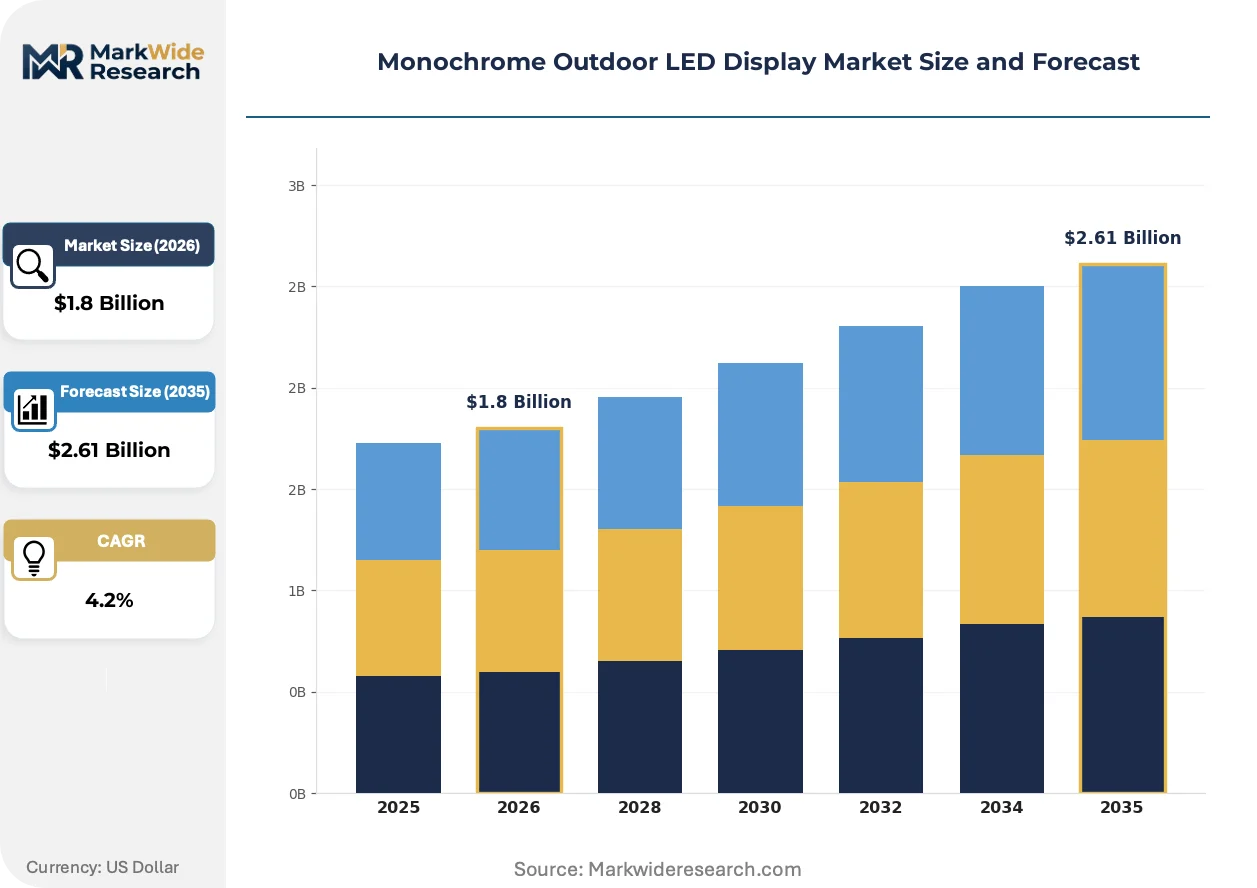
Market Dynamics
China's GB energy efficiency standards are compressing module certification timelines and forcing upstream die suppliers to requalify phosphor compositions, while municipal transit authorities in Asia accelerate digital signage replacement cycles.
Growth Catalysts
- Transit Digitalization Mandates:Municipal authorities in Seoul, Tokyo, and Singapore are expanding real-time passenger information deployments. Procurement specifications now mandate LED-based displays for all new station construction.
- F-Gas Phase-Down:The EU F-Gas Regulation is restructuring cooling system procurement criteria across European municipal buyers. Display vendors must now certify low-global-warming-potential refrigerants in outdoor enclosures.
- Aluminum-Indium-Gallium-Phosphide Die Improvements:Epitaxial growth advances are extending monochrome LED luminous efficacy. Module manufacturers in Shenzhen's Pearl River Delta cluster are integrating these dies into standard product lines.
Market Restraints
- Phosphor and Epitaxial Wafer Concentration:High-purity gallium and indium refining capacity concentrates in Chinese state-controlled smelters. Price volatility in these inputs compresses module margins unpredictably.
- Full-Color LCD Cost Compression:Narrow-pixel-pitch LCD alternatives are penetrating price-sensitive retail signage applications below 10mm equivalent viewing distances. Monochrome LED loses share in storefront digital billboards.
- CE Marking Electromagnetic Compatibility Complexity:EU electromagnetic compatibility directive testing for outdoor enclosures now requires radiated emission validation across expanded frequency bands. Certification timelines extend by 8-12 weeks.
Strategic Opportunities
- Indian Smart City Infrastructure:Municipal corporations in Mumbai, Delhi, and Bangalore are tendering for transit wayfinding under the Smart Cities Mission. Monochrome LED meets cost constraints for high-volume bus stop deployments.
- Solar-Integrated Display Systems:Photovoltaic module convergence with low-power monochrome matrices is enabling off-grid installations. African and Southeast Asian rural transit operators are piloting these configurations.
- Outcome-Based Maintenance Contracts:Municipal buyers in Germany and France are unbundling hardware purchase from 10-year availability guarantees. Service revenue streams are displacing pure equipment margins.
Industry Challenges
- Surface-Mount SMD Rework Skill Scarcity:Field repair of 10mm pitch outdoor modules requires precision hot-air rework capability. Technician certification programs lag deployment scale in emerging markets.
- Legacy RS-485 Control Protocol Integration:Transit authority SCADA systems in older metro networks use proprietary serial interfaces. Display controllers must maintain backward compatibility while adding IP connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monochrome Outdoor LED Display Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Text Displays, Graphics Displays, Scoreboards, Digital Billboards Installation Type: Wall-Mounted, Freestanding, Portable, Under-Canopy End User: Retail Stores, Stadiums, Transportation Hubs, Event Venues Technology: SMD, DIP, RGD, Monochrome |
| Companies Covered | Absen, HTT LED, Daktronics, Samsung Electronics, AOTO, Unilumin, Liantronics, LINSN LED, Leyard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monochrome Outdoor LED Display Market Shifts & Advancements
Module packaging architectures and control electronics are converging to reduce power density and extend maintenance intervals, while regulatory pressure on embodied carbon reshapes material selection across the supply base.
Flip-chip LED die attachment is expanding into outdoor monochrome modules by eliminating wire bonds and improving thermal dissipation. Transit operators in northern European climates are specifying these packages for frost-heave resistance. The technology is expanding into premium-tier municipal contracts previously dominated by conventional wire-bonded DIP configurations.
China's SAMR enforcement of GB energy efficiency labeling is filtering non-compliant modules from government procurement tenders. Manufacturers must submit third-party test reports for luminous efficacy and standby power. The certification burden falls heaviest on smaller Shenzhen assembly houses serving provincial transit authorities.
Buyers are consolidating vendor relationships around integrated hardware-service offerings rather than transactional equipment purchases. German municipal utilities now contract 15-year availability for display networks rather than capitalizing individual units. This preference shift concentrates procurement among vendors with captive service infrastructure.
Monochrome Outdoor LED Display Market Segmentation
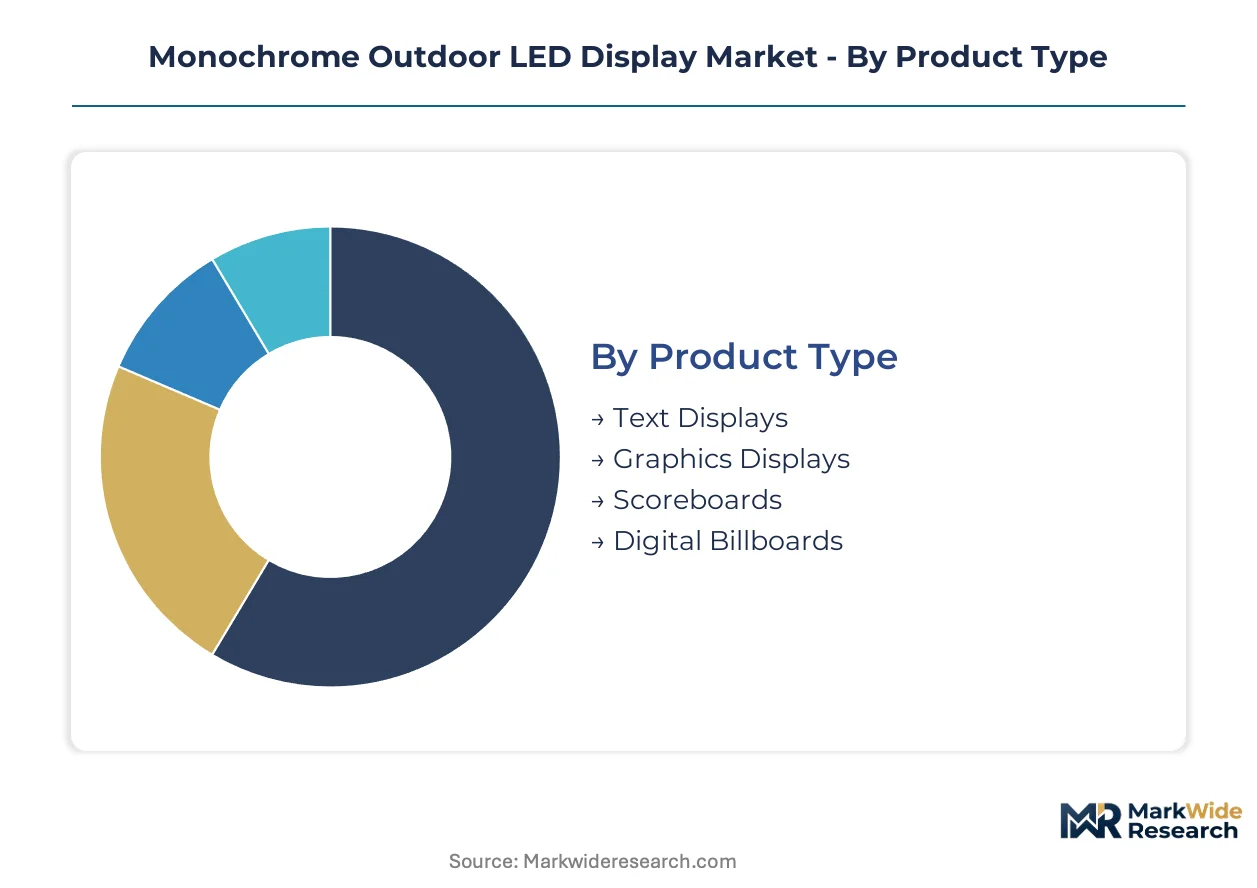
Product architecture in monochrome outdoor LED displays varies sharply by duty cycle, viewing distance, and content complexity. Procurement patterns diverge across transit authorities, retail operators, and sports venue managers who prioritize different performance thresholds. Understanding these segment boundaries clarifies where module suppliers can defend margin versus where price competition dominates.
Product Type:
Buyers in this category separate by content refresh frequency and information density requirements. Transit authorities prioritize legibility at speed and extreme viewing angles. Retail operators balance message flexibility against power draw constraints.
- Text Displays:Single-line or multi-line character matrices using 10mm-16mm pixel pitch with limited font rendering capability. Seoul Metropolitan Subway and Singapore LRT networks specify these for platform arrival boards where alphanumeric clarity outweighs graphical flexibility. GB energy efficiency labeling from China's SAMR filters supplier pools for these high-volume tenders.
- Graphics Displays:Bitmap-capable matrices supporting simple icons, arrows, and pictograms beyond raw text. Transportation hubs in Tokyo and Delhi deploy these for wayfinding at intersection points where multilingual symbol sets reduce cognitive load. Module margins compress here as provincial Chinese assembly houses compete on unit cost.
- Scoreboards:Purpose-built configurations with integrated timing interfaces and stat feed compatibility. Stadium operators in Germany and France specify these for secondary venue tiers where full-color reproduction is unnecessary.
- Digital Billboards:Large-format installations for commercial messaging despite monochrome constraint. Retail storefront applications in India's urban corridors use these where ambient light conditions defeat LCD alternatives.
Volume sits with Text Displays; growth tilts toward Graphics Displays.
Installation Type:
Structural engineering cost and site permanence drive buyer selection here. Municipal procurement teams evaluate foundation requirements, wind load certification, and relocation flexibility against operational lifespan assumptions.
- Wall-Mounted:Direct building attachment eliminating independent structural support. Transit authorities in Mumbai and Bangalore favor these for bus stop retrofits where sidewalk footprint is constrained. CE marking under EU electromagnetic compatibility directives shapes enclosure design for European deployments.
- Freestanding:Self-supporting pylons or cantilevered structures requiring geotechnical assessment. Stadium parking lots and highway-adjacent retail in the United States use these for 360-degree visibility.
- Portable:Trailer-based or modular configurations with rapid deployment capability. Event venues in Southeast Asia pilot these for temporary festival installations where power and network drop points are unpredictable.
- Under-Canopy:Suspended or soffit-mounted units protected from direct precipitation. Tokyo Metro and Seoul station renovations specify these to preserve platform clearances.
Freestanding captures the steepest expansion trajectory as Indian Smart Cities Mission tenders prioritize high-visibility arterial road placements.
End User:
Contract structure and maintenance responsibility divide this category. Retail buyers favor capital expenditure with limited service terms. Transit authorities increasingly demand availability guarantees spanning hardware lifecycle.
- Transportation Hubs:Rail stations, airports, and bus terminals requiring 24/7 operational continuity. Procurement specifications from Germany's municipal utilities now embed 15-year availability contracts rather than transactional purchase.
- Retail Stores:Single-unit or small-network deployments for promotional messaging. Narrow-pixel-pitch LCD encroachment is displacing monochrome LED in premium storefront positions below 10mm equivalent viewing distances.
- Stadiums:Professional and amateur sports venues with scoreboard and perimeter display requirements. European sports venue installations demand F-Gas Regulation compliance for outdoor enclosure cooling systems.
- Event Venues:Convention centers, exhibition halls, and temporary event infrastructure. Portable configuration demand concentrates here as rental fleet operators expand monochrome inventory for cost-sensitive clients.
Transportation Hubs dominate current procurement volume; Event Venues are climbing the fastest as post-pandemic gathering frequency normalizes.
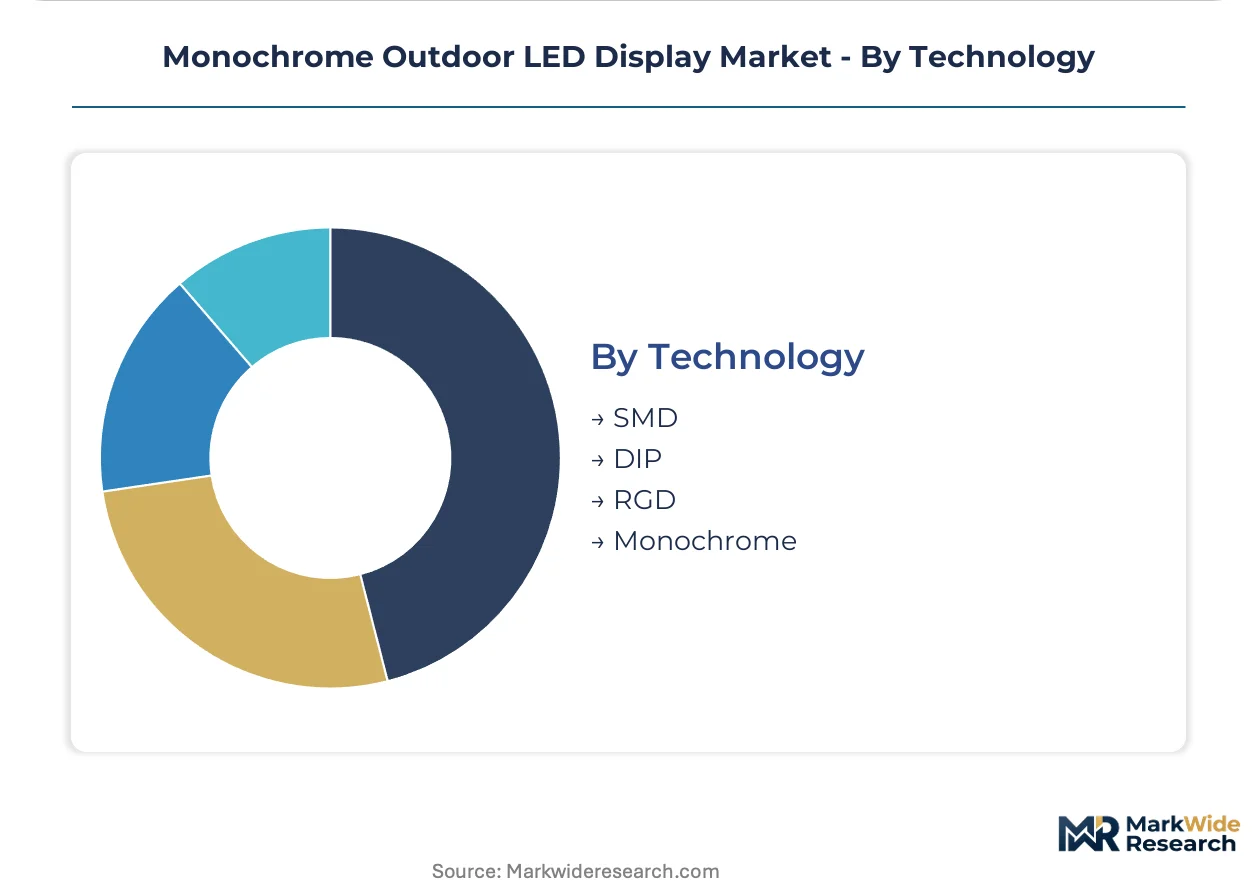
Technology:
Die attachment method and packaging density determine thermal performance, field serviceability, and luminous efficacy. Buyers with extreme climate exposure or limited maintenance access prioritize package reliability over initial unit cost.
- DIP:Dual in-line package through-hole mounting with wire-bonded die attachment. Legacy transit authority specifications in older metro networks still mandate these for RS-485 control protocol compatibility.
- SMD:Surface-mount device packaging enabling higher pixel density and automated assembly. Shenzhen's Pearl River Delta cluster has standardized SMD lines for export volume production.
- RGD:Reduced grain display configurations optimizing for specific viewing distance bands. Niche applications in Japanese rail signage where platform geometry creates predictable sightline constraints.
- Monochrome:Single-color die composition without phosphor conversion, maximizing efficacy for text-dominant content. Solar-integrated display pilots in African and Southeast Asian rural transit rely on these for minimal power draw.
DIP retains installed base dominance; SMD is gaining share fastest as flip-chip thermal improvements penetrate standard product lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's Pearl River Delta manufacturing cluster anchors module production and downstream assembly for monochrome outdoor LED displays, with procurement patterns diverging sharply across municipal transit authorities, retail operators, and sports venue managers on three continents.
China
GB energy efficiency standards from SAMR are compressing module certification timelines and forcing upstream die suppliers to requalify phosphor compositions. The Pearl River Delta cluster integrates LED module production with downstream assembly, serving both domestic tenders and export volume. Provincial transit authorities in Guangdong and Jiangsu are accelerating digital signage replacement cycles under smart city mandates.
United States
FCC Part 15 emissions standards shape product certification pathways for cross-border shipment, while stadium parking lots and highway-adjacent retail deploy freestanding pylons for 360-degree visibility. Municipal procurement teams evaluate wind load certification and foundation requirements against operational lifespan assumptions. Daktronics leverages captive LED module fabrication to sustain margin stability amid component volatility.
Germany
EU F-Gas Regulation phase-down targets are restructuring procurement criteria for outdoor display cooling systems across municipal buyers. German municipal utilities now contract 15-year availability for display networks rather than capitalizing individual units. This preference shift concentrates procurement among vendors with captive service infrastructure.
India
Municipal corporations in Mumbai, Delhi, and Bangalore are tendering for transit wayfinding under the Smart Cities Mission. Monochrome LED meets cost constraints for high-volume bus stop deployments. Wall-mounted installations dominate retrofits where sidewalk footprint is constrained.
Japan
Transportation hubs in Tokyo deploy graphics-capable matrices for multilingual wayfinding at intersection points. Platform geometry in Japanese rail stations creates predictable sightline constraints that favor reduced grain display configurations. METI standards influence procurement specifications for extreme viewing angles and legibility at speed.
Monochrome Outdoor LED Display Market Competitive Landscape
The competitive structure tilts toward vertically integrated module fabricators with captive die sourcing and in-house controller design. Shenzhen-based assembly houses compete on unit cost for provincial transit tenders, while European sports venue specialists defend premium positioning through F-Gas-compliant cooling system integration. Two strategic archetypes dominate: scale-driven Pearl River Delta manufacturers and service-integrated Western vendors. M&A activity concentrates on controller firmware capabilities, while capacity expansion targets Indian and Southeast Asian assembly lines.
Among China-based fabricators, Unilumin anchors its position through manufacturing scale in Shenzhen, while Absen competes on channel control across European sports venue installations. Daktronics occupies a position within the North American vendor tier, representing the service-integrated archetype through vertical control over LED module production. These three companies exemplify how geographic concentration and downstream integration separate premium-tier positioning from commodity module supply.
| Leading Market Players |
|---|
| Absen |
| HTT LED |
| Daktronics |
| Samsung Electronics |
| AOTO |
| Unilumin |
| Liantronics |
| LINSN LED |
| Leyard |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap assemblers in Shenzhen's Pearl River Delta cluster anchor module production, constraining pricing discipline through fragmented capacity allocation while municipal transit authorities in Asia extract volume discounts from competing suppliers. Their limited balance-sheet capacity prevents forward-contracting of gallium and indium inputs, amplifying margin volatility that ripples into spot-market module pricing.
Pricing Analysis
Value-based pricing anchored on 15-year availability guarantees separates German municipal utility contracts from transactional Asian tenders. Three-tier pricing structure across premium flip-chip configurations, standard SMD modules, and economy DIP lines tracks certification grade and thermal performance tier. Pricing pressure stems from narrow-pixel-pitch LCD encroachment in retail storefront applications below 10mm equivalent viewing distances. Provincial Chinese transit authorities exhibit highest price sensitivity; European stadium operators with F-Gas compliance mandates show lowest.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Hong Kong, and Rotterdam orchestrate hub-and-spoke patterns for module fulfillment. Manufacturing concentrates in China, South Korea, and Taiwan, with epitaxial wafer fabrication tethered to Chinese state-controlled gallium refineries. High-purity indium and aluminum-indium-gallium-phosphide die compositions constitute critical input dependencies. Single-source vulnerability in rare-earth refining capacity poses structural risk. Distribution runs through direct OEM relationships for large transit tenders and tiered distributor networks for retail volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained, with Chinese state-controlled smelter capacity for high-purity gallium and indium propping module pricing against downstream cost pressure.
For Market Incumbents: Extend captive die-sourcing arrangements through backward integration into phosphor composition requalification pipelines. Secure GB energy efficiency pre-certification with China's SAMR ahead of provincial transit tender waves. Narrow-pixel-pitch LCD substitution in retail signage threatens share; defend through F-Gas-compliant cooling system bundling for European municipal buyers. For New Entrants and Emerging Players: Municipal engineering contractors in India's Smart Cities Mission represent the most penetrable channel partner type for pilot deployments. Target solar-integrated off-grid configurations for African and Southeast Asian rural transit operators where incumbent service infrastructure is sparse. Lead with 10-year maintenance contract bundling to offset capital expenditure sensitivity. For Investors and Strategic Acquirers: Distressed-cycle entries favor controller firmware specialists in Germany and France where municipal buyers demand RS-485 legacy protocol integration. Long-term viability hinges on service revenue displacement of pure equipment margins. Watch Indian Smart Cities Mission tender acceleration as inflection indicator for volume-scale manufacturing returns.| Strategic Initiative | Industry Significance |
|---|---|
| Flip-Chip Thermal Package Integration | Seoul and Tokyo transit authorities specify frost-heave-resistant modules for premium-tier contracts. |
| GB Energy Efficiency Pre-Certification | China's SAMR filtering creates compliance moat against smaller Shenzhen assembly houses. |
| 15-Year Availability Contract Structuring | German municipal utilities unbundle hardware purchase from lifecycle service guarantees. |
| Solar-Photovoltaic Module Convergence | African rural transit operators pilot off-grid installations with minimal power draw. |
| Controller Firmware Capability Acquisition | Legacy RS-485 protocol integration secures replacement cycles in older metro networks. |
Research Methodology
Multi-period observation of municipal tender award patterns, module shipment volumes, and certification timeline compression anchored the trend analysis, supplemented by interviews with transit authority procurement directors, LED module fabrication plant managers, controller firmware engineers, and municipal engineering contractors. Secondary validation drew from China's SAMR certification databases, EU F-Gas Regulation implementation reports, SEC filings of listed display vendors, and Indian Smart Cities Mission tender documentation. Bottom-up unit economics triangulated against top-down addressable market sizing.
Input-output matrices mapped die attachment technology, pixel pitch tier, and installation type against end-use segment demand across the projection horizon. Segmentation dimensions modeled include product architecture, installation configuration, buyer contract structure, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to replacement cycle data and smart city infrastructure deployment schedules. Forecast inputs incorporated GB standard evolution timelines and F-Gas phase-down compliance cost trajectories.
Caveats apply where Chinese rare-earth export restrictions, LCD cost compression acceleration, or municipal budget austerity could materially shift the outlook. Forecasts embed assumptions on certification timeline stability and transit authority procurement continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Bi-Color LED Ring Light Market
LED
LED Lighting Market
LED
Mini LED Market
LED
Asia Pacific Outdoor LED Lighting Market
LED
High-Brightness Light-Emitting Diodes (LED) Headlamps Market
LED
LED Lamp Market
LED
Germany Outdoor LED Lighting Market
LED
LED Flip Chip Market
LED
Pixel Pitch LED Market
LED
LED Display Control Card Market
LED
Biometrics Infrared LED Market
LED
Global Waterproof LED Module Market
LED
LED Light Bar Market
LED
LED Work Light Market
LED
France LED Lighting Market
LED
Xenon Market