
 IC Socket Market | 2026-2036
IC Socket Market Size, Share, and Industry Trends Forecast 2026-2036
IC Socket Market Outlook
The migration toward heterogeneous integration and chiplet-based architectures is rewriting procurement criteria for IC sockets across the semiconductor test ecosystem. TE Connectivity leverages its vertical integration into precision metal stamping and plating to sustain cost leadership in high-pin-count BGA sockets. Yamaichi Electronics anchors Asia-Pacific supply chains with proprietary contact geometries designed for 0.35 mm pitch devices. Enplas Corporation differentiates through ceramic-filled polymer compounds that withstand repeated thermal cycling in burn-in applications.
An IC socket is a mechanical interconnect device that temporarily houses an integrated circuit for testing, programming, or system validation, typically specifying contact resistance below 30 milliohms and insertion force rated per JEDEC standards. Its primary commercial purpose is to protect valuable semiconductors from solder damage during electrical characterization and reliability screening. BGA sockets command premium positioning due to alignment complexity with high-I/O processors in server and AI accelerator cards. Surface-mount technology variants represent the fastest-growing technology category as contract manufacturers eliminate through-hole processes from high-volume consumer electronics lines. Zero insertion force mechanisms retain stable margin pools in aerospace and defense applications where gold-plated beryllium copper contacts must survive thousands of mate-demate cycles.
FCC equipment authorization rules shape electromagnetic compatibility requirements for sockets used in telecommunications infrastructure testing, while RoHS and REACH restrict cadmium and lead content in contact plating across European-bound products. Japan's METI promotes domestic semiconductor equipment supply chains through funding tied to JIS standard compliance for test socket reliability. Stakeholders must monitor how EPA per- and polyfluoroalkyl substance restrictions affect fluoropolymer insulator formulations before committing to multi-year socket platform designs.
Market Dynamics
Heterogeneous integration and chiplet architectures are compressing socket design cycles as test engineers confront multi-die packages with non-uniform thermal profiles and mixed pitch requirements.
Growth Catalysts
- Automotive burn-in specifications:Semiconductor test engineers at automotive OEMs now mandate sockets rated for wider temperature ranges to validate power electronics under thermal stress conditions.
- Domestic substitution mandates:China's MIIT enforces procurement quotas favoring indigenous test equipment suppliers, redirecting socket demand toward local manufacturers.
- Advanced packaging clusters:Taiwan's Hsinchu Science Park concentrates foundry investment, generating concentrated demand for precision BGA and LGA sockets in volume procurement.
Market Restraints
- Gold and palladium price volatility:Contact plating materials face commodity price swings that compress margin predictability for socket manufacturers.
- Precise machining concentration:High-aspect-ratio micro-milling capacity clusters in Japanese and German machine tool ecosystems, creating single-source dependencies.
- RoHS and REACH compliance friction:European chemical restrictions on cadmium and lead content force reformulation of legacy plating chemistries.
Strategic Opportunities
- India semiconductor test infrastructure:PLI scheme incentives for domestic chip assembly and test facilities create virgin demand for burn-in and final test sockets.
- Zero insertion force aerospace applications:Defense contractors seek gold-plated beryllium copper contact systems rated for thousands of mate-demate cycles.
- Fluoropolymer insulator innovation:EPA per- and polyfluoroalkyl substance restrictions force development of alternative high-temperature polymer formulations.
Industry Challenges
- Micro-machining talent scarcity:Precision metal stamping and sub-0.4 mm pitch contact forming require specialized tool-and-die skills in short supply.
- Multi-year platform certification timelines:JEDEC standard compliance and automotive AEC-Q100 qualification extend product development cycles.
- Legacy socket inventory stranding:Rapid pitch migration from 1.0 mm to 0.35 mm geometries obsoletes existing socket populations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IC Socket Market |
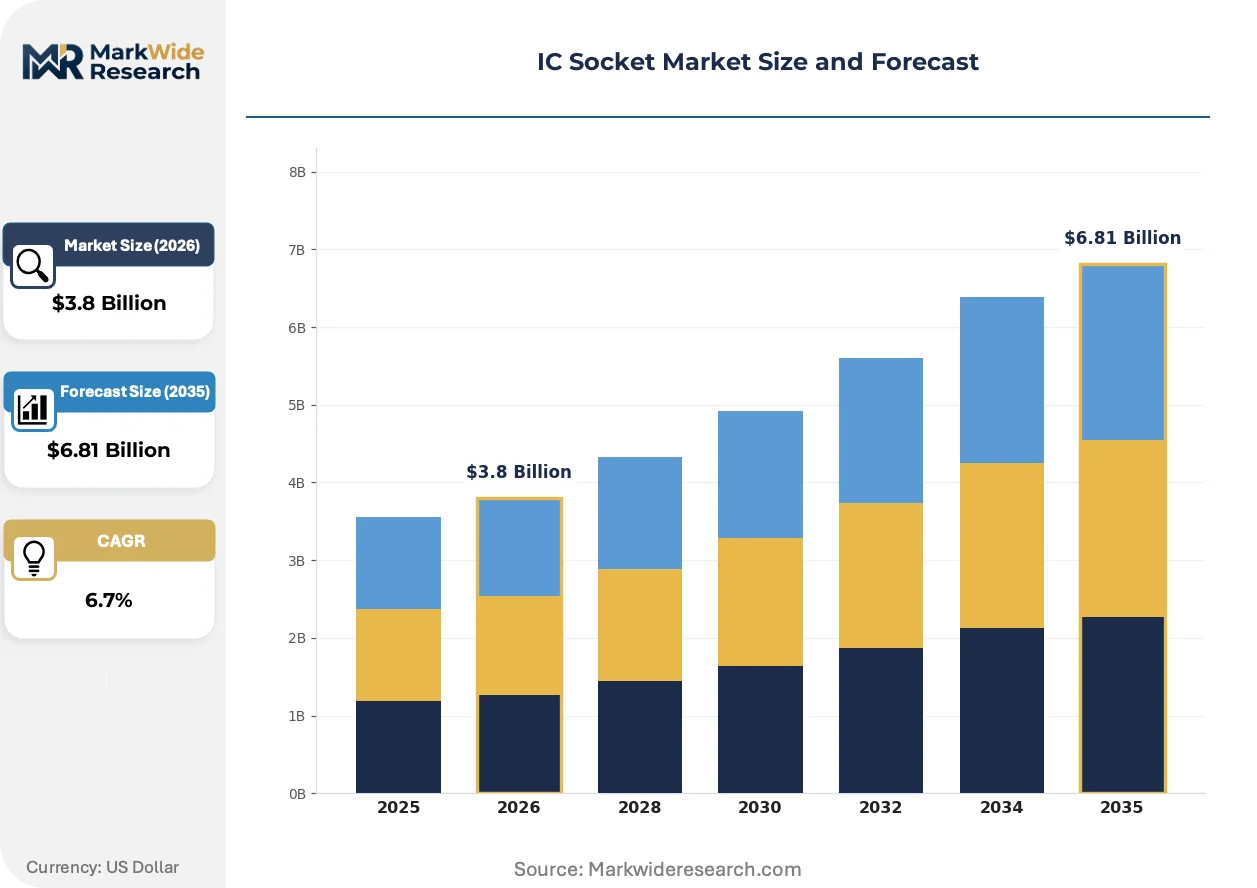
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DIP, PGA, BGA, LGA Application: Consumer Electronics, Automotive, Industrial Equipment, Telecommunications End User: Contract Manufacturers, OEMs, System Integrators, Research Institutions Technology: Through-Hole, Surface-Mount, Zero Insertion Force, Socket Adapters |
| Companies Covered | Enplas Corporation, Mill-Max Mfg., TE Connectivity, Aries Electronics, Sensata Technologies, Smiths Interconnect, Yamaichi Electronics Co., Ltd, Leeno Industrial Inc, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IC Socket Market Strategic Shifts
Contact geometry miniaturization and materials science advances are compressing the functional boundary between temporary test interconnects and permanent solder alternatives.
Spring probe technology with sub-30 milliohms contact resistance is collapsing the performance gap between sockets and direct solder joints for high-I/O processors. Server and AI accelerator card manufacturers now specify these for pre-production validation. The distinction between test and production interconnects is collapsing as reliability data accumulates.
Japan's METI funding tied to JIS standard compliance for test socket reliability is accelerating domestic equipment supply chain consolidation. Socket manufacturers must demonstrate thermal cycling endurance under standardized protocols. Japanese semiconductor equipment vendors are capturing premium positioning through certified reliability data.
Contract manufacturers in consumer electronics are eliminating through-hole assembly lines entirely. Surface-mount socket variants now dominate high-volume procurement specifications. Taiwan-based EMS providers are driving this specification shift through consolidated component sourcing power.
IC Socket Market Segmentation
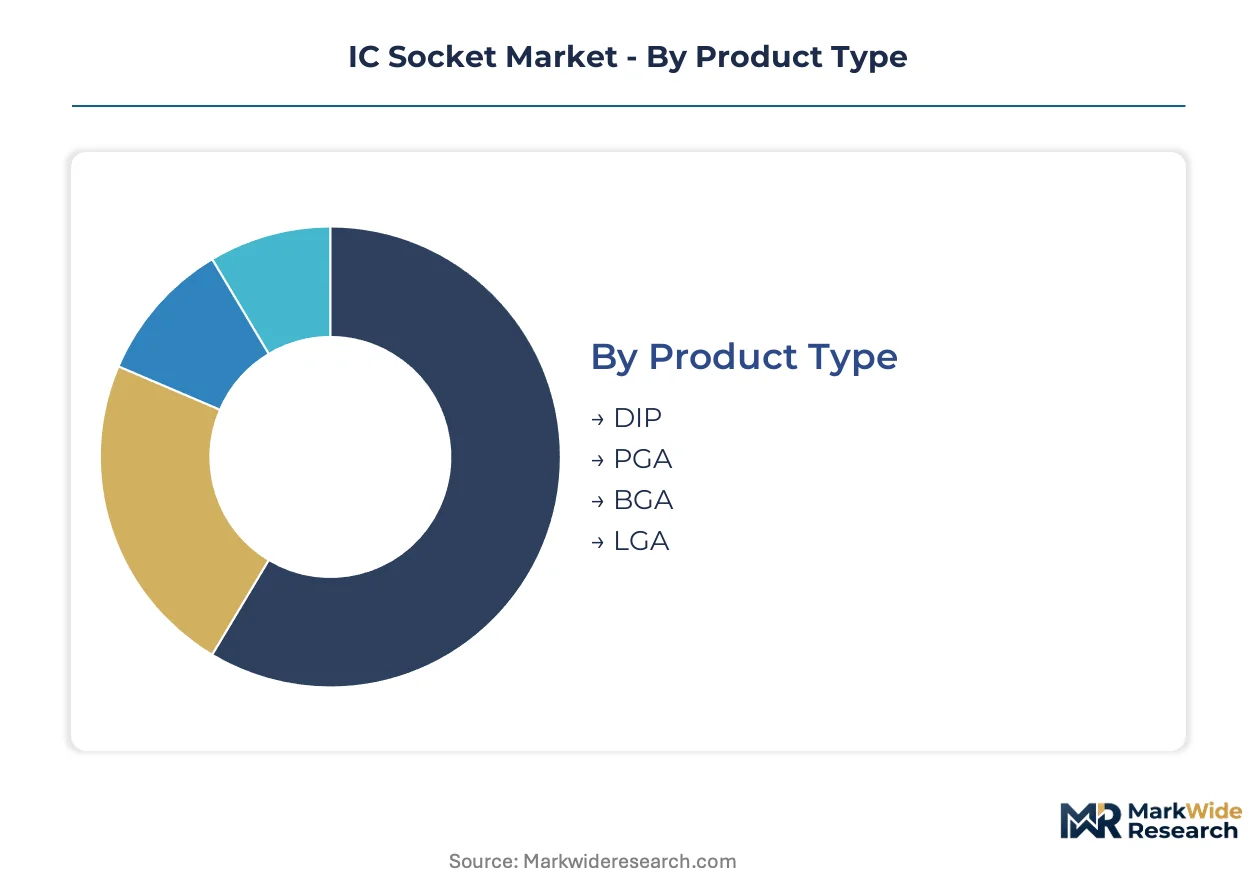
IC socket procurement patterns diverge sharply across product architectures, end-use reliability requirements, and assembly technology roadmaps. Test engineers specify fundamentally different contact geometries, thermal ratings, and insertion mechanisms depending on whether they validate consumer chipsets or automotive power modules.
Product Type:
The use-case spectrum spans legacy through-hole programming sockets to sub-0.4 mm pitch precision interconnects for AI accelerators.
- BGA:Ball grid array sockets employ precision-machined contact springs aligned to solder ball patterns on high-I/O processors. Taiwan's Hsinchu Science Park foundries source these in volume for advanced packaging validation, with procurement concentrated among server and AI accelerator card manufacturers demanding sub-30 milliohms contact resistance.
- LGA:Land grid array variants eliminate solder balls from the package, requiring flat-contact spring probes that withstand higher compressive forces. Intel and AMD processor test lines in Malaysia and Vietnam specify these for burn-in screening, where thermal cycling endurance determines socket replacement intervals.
- PGA:Pin grid array sockets retain niche demand for legacy microcontroller programming and military system retrofits, with procurement concentrated among defense contractors requiring gold-plated beryllium copper contacts rated for thousands of mate-demate cycles.
- DIP:Dual in-line package sockets serve educational institutions and hobbyist electronics markets, with demand concentrated in India and Southeast Asia where through-hole assembly skills remain prevalent in vocational training programs.
The dominant share belongs to BGA, while LGA is closing the gap fastest.
Application:
Cost tier differentiation separates commodity consumer electronics validation from premium automotive reliability screening.
- Automotive:Power electronics test engineers specify burn-in sockets rated for wider temperature ranges to validate IGBT and SiC modules under thermal stress conditions. Germany's KBA and NHTSA safety mandates drive AEC-Q100 qualification requirements that extend socket development cycles and concentrate procurement among certified suppliers.
- Consumer Electronics:High-volume smartphone and wearable test lines prioritize surface-mount socket variants that eliminate through-hole assembly steps. Taiwan-based EMS providers consolidate component sourcing power, driving specification shifts toward 0.35 mm pitch compatibility and automated insertion compatibility.
- Telecommunications:Baseband processor and RF module testing requires FCC equipment authorization compliance for electromagnetic compatibility, with procurement concentrated among 5G infrastructure vendors in South Korea and Finland.
- Industrial Equipment:Programmable logic controller and motor drive manufacturers specify extended-temperature sockets for factory automation validation, with demand concentrated in Germany's industrial automation cluster.
Automotive commands premium pricing, while Consumer Electronics generates the steepest expansion trajectory through volume procurement.
End User:
Customer type determines socket specification authority and replacement cycle economics.
- Contract Manufacturers:Foxconn, Jabil, and Flex consolidate global procurement volumes, driving standardization around surface-mount socket platforms that minimize line changeover time. Their specification power forces socket vendors to demonstrate automated optical inspection compatibility and tape-and-reel packaging.
- OEMs:Apple, Tesla, and Samsung retain direct socket procurement for proprietary chip validation, often co-developing custom contact geometries with Yamaichi Electronics or TE Connectivity for unreleased processor architectures.
- System Integrators:Server and networking equipment assemblers source sockets for final system validation, with procurement concentrated among Supermicro and Quanta Computer test facilities.
- Research Institutions:University cleanrooms and national laboratories purchase low-volume, high-precision sockets for exploratory packaging research, tolerating longer lead times for custom contact configurations.
Contract Manufacturers dominate procurement volume, while OEMs are gaining specification authority fastest through captive semiconductor programs.
Technology:
Maturity gradients separate declining through-hole platforms from emerging zero-insertion-force aerospace applications.
- Surface-Mount:SMT socket variants now dominate high-volume consumer electronics procurement as contract manufacturers eliminate through-hole processes entirely. Taiwan-based EMS providers drive this specification shift through consolidated component sourcing power and automated assembly line investments.
- Zero Insertion Force:ZIF mechanisms retain stable margin pools in aerospace and defense applications where gold-plated beryllium copper contacts must survive thousands of mate-demate cycles for satellite and avionics system maintenance. NASA and ESA qualification protocols extend product development timelines.
- Through-Hole:Legacy DIP and PGA socket formats persist in industrial control systems and educational equipment where soldering skills remain prevalent, though procurement volumes decline annually.
- Socket Adapters:Interposer platforms enable legacy test equipment to accommodate newer package formats, with demand concentrated among semiconductor foundries extending depreciation schedules on existing probe stations.
Surface-Mount holds the installed base advantage, while Zero Insertion Force is expanding most quickly in defense applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan exports precision BGA and LGA sockets to Malaysia and Vietnam, where Intel and AMD operate processor test and burn-in facilities. This trade corridor channels advanced packaging validation equipment from Hsinchu Science Park foundries into Southeast Asian semiconductor assembly hubs.
United States
Defense contractors in California and Texas specify zero-insertion-force sockets with gold-plated beryllium copper contacts for satellite avionics maintenance cycles. NASA and FAA qualification protocols extend product development timelines for aerospace-grade interconnects. The Southwest cluster around Phoenix and Austin concentrates burn-in socket demand from captive semiconductor programs at Tesla and Apple.
Germany
Automotive power electronics test engineers at Bosch and Infineon mandate burn-in sockets rated for extended temperature ranges to validate IGBT and SiC modules. KBA safety mandates enforce AEC-Q100 qualification requirements that concentrate procurement among certified suppliers. Bavaria's industrial automation corridor around Munich and Nuremberg drives demand for extended-temperature sockets in programmable logic controller validation.
Japan
Domestic equipment vendors capture premium positioning through METI funding tied to JIS standard compliance for test socket reliability. Socket manufacturers must demonstrate standardized thermal cycling endurance protocols. The Chubu region around Nagoya anchors precision metal stamping and sub-0.4 mm pitch contact forming capacity for high-pin-count applications.
China
MIIT procurement quotas redirect socket demand toward indigenous test equipment suppliers as domestic substitution mandates tighten. Yangtze River Delta foundries in Shanghai and Suzhou source precision sockets for advanced packaging validation. The central government's dual carbon goals pressure manufacturers to reformulate plating chemistries away from restricted substances.
South Korea
5G infrastructure vendors Samsung and LG specify FCC-aligned electromagnetic compatibility requirements for baseband processor and RF module testing sockets. MFDS equipment authorization rules shape telecommunications testing procurement. The Seoul Capital Area concentrates EMS provider consolidation that drives surface-mount socket standardization.
IC Socket Market Competitive Environment
Channel-controlling players compete with product-specialist players across three distinct tiers. Consolidated procurement power at Foxconn, Jabil, and Flex forces socket vendors to demonstrate automated optical inspection compatibility and tape-and-reel packaging compliance. The market structures around diversified interconnect conglomerates, precision contact geometry specialists, and regional fabrication houses. Dominant competitive moves include backward integration into captive plating and stamping capacity, plus co-development partnerships with unreleased processor architectures.
Within the diversified conglomerate tier, TE Connectivity and 3M Company occupy positions spanning multiple interconnect categories beyond test sockets. Yamaichi Electronics Co., Ltd anchors the precision contact geometry specialist archetype with proprietary designs for sub-0.35 mm pitch devices. Enplas Corporation exemplifies the materials-science-driven segment through ceramic-filled polymer formulations. These three named entities represent the strategic positioning spectrum: scale-driven diversification, precision engineering specialization, and compound material differentiation.
| Leading Market Players |
|---|
| Enplas Corporation |
| Mill-Max Mfg. |
| TE Connectivity |
| Aries Electronics |
| Sensata Technologies |
| Smiths Interconnect |
| Yamaichi Electronics Co., Ltd |
| Leeno Industrial Inc |
| 3M Company |
| Others |
Value Chain & Pricing Dynamics
Hsinchu Science Park foundries concentrate precision BGA and LGA socket capacity, translating their volume procurement power into aggressive price negotiation leverage with contact geometry specialists. This geographic clustering compresses margins for vendors serving Taiwan's advanced packaging ecosystem while sustaining premium positioning for aerospace-grade zero-insertion-force variants.
Pricing Analysis
Current-generation 0.35 mm pitch sockets command substantial premiums over legacy 1.0 mm geometries, while next-generation sub-0.3 mm prototypes remain pre-commercial. Three-tier pricing structure across AEC-Q100 certified automotive, JEDEC standard industrial, and unqualified economy tiers separates procurement categories. Cost compression in consumer electronics SMT variants is intensifying because Taiwan-based EMS providers consolidate component sourcing power. Contract manufacturers exhibit highest price sensitivity through automated optical inspection compatibility demands, whereas defense contractors tolerate extended lead times for NASA-qualified aerospace interconnects.
Supply Chain Analysis
Extended payment terms from Foxconn and Jabil force socket vendors to access supply-chain finance facilities, elevating working capital requirements for precision metal stamping operations. Manufacturing concentrates in Taiwan, Japan, and Germany, with high-aspect-ratio micro-milling capacity anchored in Nagoya and Stuttgart industrial clusters. Raw material dependencies center on gold-plated beryllium copper, ceramic-filled polymer compounds, and fluoropolymer insulators. Single-source vulnerability in Japanese machine tool ecosystems threatens contact forming precision. Distribution runs through consolidated EMS procurement hubs rather than fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spring probe technology with sub-30 milliohms contact resistance is collapsing the distinction between temporary test sockets and permanent solder joints, forcing incumbent vendors to defend against interconnect substitution in pre-production validation workflows.
For Market Incumbents: Pre-empt spring probe substitution by co-developing custom contact geometries with Apple and Tesla for unreleased processor architectures. Secure captive plating capacity to insulate margin pools from gold and palladium commodity volatility. METI funding tied to JIS standard compliance creates defensive certification moats against regional fabrication houses. For New Entrants and Emerging Players: Pursue India's PLI scheme incentives for domestic chip assembly and test facilities, where virgin burn-in socket demand outstrips local supply capacity. Target fluoropolymer insulator innovation as EPA restrictions on per- and polyfluoroalkyl substances force formulation transitions. Position through co-development partnerships with Yangtze River Delta foundries seeking indigenous equipment alternatives. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision contact geometry specialists with demonstrated sub-0.4 mm pitch forming capability over diversified interconnect conglomerates. Long-term viability hinges on heterogeneous integration roadmaps extending socket replacement cycles in automotive power electronics. Monitor MIIT domestic substitution mandate enforcement intensity as inflection indicator for China market access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Plating | Insulates TE Connectivity and Yamaichi Electronics from gold price volatility compressing margins. |
| Co-Development Partnership | Enables socket vendors to secure volume commitments from Tesla and Apple before processor launch. |
| JIS Standard Certification Investment | Unlocks METI funding streams and accelerates supply chain consolidation among Japanese equipment vendors. |
| Fluoropolymer Formulation Transition | Positions Enplas Corporation to capture EPA-driven replacement demand for restricted insulator chemistries. |
| India Manufacturing Footprint Establishment | Aligns socket production capacity with PLI scheme incentives for domestic semiconductor test infrastructure. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with semiconductor test engineers, socket procurement managers at EMS providers, and precision metal stamping operations directors; and secondary validation through JEDEC standard documentation, EPA chemical restriction filings, and MIIT domestic substitution policy releases. Bottom-up triangulation against top-down trade flow estimates anchored Taiwan-to-Southeast Asia socket export volumes.
Forecast inputs span product type segmentation across BGA, LGA, PGA, and DIP architectures; application tier differentiation between automotive AEC-Q100 and consumer electronics SMT variants; and technology generation transitions from through-hole to zero-insertion-force platforms. CAGRs were derived through geometric progression modeling of replacement cycle economics and foundry capacity expansion trajectories. Pitch migration timelines and burn-in temperature specification tightening shaped demand elasticity assumptions across the projection horizon.
Sensitivities concentrate around gold and palladium price volatility, MIIT enforcement intensity for domestic procurement quotas, and EPA per- and polyfluoroalkyl substance restriction implementation timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Circular Waterproof Connector Market
Connectors
Middle East Connector Market
Connectors
Telecom Mounting Hardware Market
Connectors
Space Grade Connectors Market
Connectors
Connector Kits Market
Connectors
Relay Sockets Market
Connectors
Underwater Mate Connectors Market
Connectors
Hybrid Fiber Optic Connectors Market
Connectors
Circular Connectors Market
Connectors
Filtered Connectors Market
Connectors
Power Connector Market
Connectors
Automotive Data Connectors Market
Connectors
Connector Market
Connectors
5G Connector Market
Connectors
Asia-Pacific Connector Market
Connectors
Middle East and Africa Hazardous Location Connectors Market