
 Chip on Board LED Market | 2026-2036
Chip on Board LED Market Size, Share, and Industry Trends Forecast 2026-2036
Chip on Board LED Market Analysis
Subscription-based lumen-maintenance contracts is consolidating how lighting vendors monetize COB LED deployments over product lifecycles. Lumileds Holding B.V. leverages its phosphor-conversion expertise to anchor premium indoor horticulture contracts. EPISTAR Corporation sustains wafer-level chip-scale packaging scale across Taiwanese fabrication facilities. Samsung Electronics Co., Ltd. dominates backlighting supply chains for premium display panels through captive semiconductor integration.
A chip on board LED mounts multiple LED dies directly onto a thermally conductive substrate, eliminating individual device packages and enabling luminous efficacy exceeding 150 lumens per watt in high-density configurations. This architecture serves applications demanding compact emission surfaces with uniform intensity distribution, from surgical luminaires to cinematic display backlights. High-power COB modules capture the dominant share of industrial and street-lighting procurement budgets where thermal management determines operational longevity. Wire bond technology retains cost advantages in mid-power general illumination, though flip chip architectures are displacing conventional interconnects in automotive forward-lighting programs where vibration resistance and beam precision carry regulatory weight.
China's SAMR enforces GB standards that mandate luminous efficacy minimums and restrict hazardous substance content in COB LED products sold domestically. The EU Ecodesign Directive and RoHS compliance frameworks shape import requirements for Asian manufacturers serving European commercial lighting channels. South Korea's MFDS certification protocols govern photobiological safety classifications for consumer-facing applications. Stakeholders must monitor how substrate material transitions from aluminum to copper-composite architectures affect both thermal performance metrics and compliance testing costs across these divergent regulatory regimes.
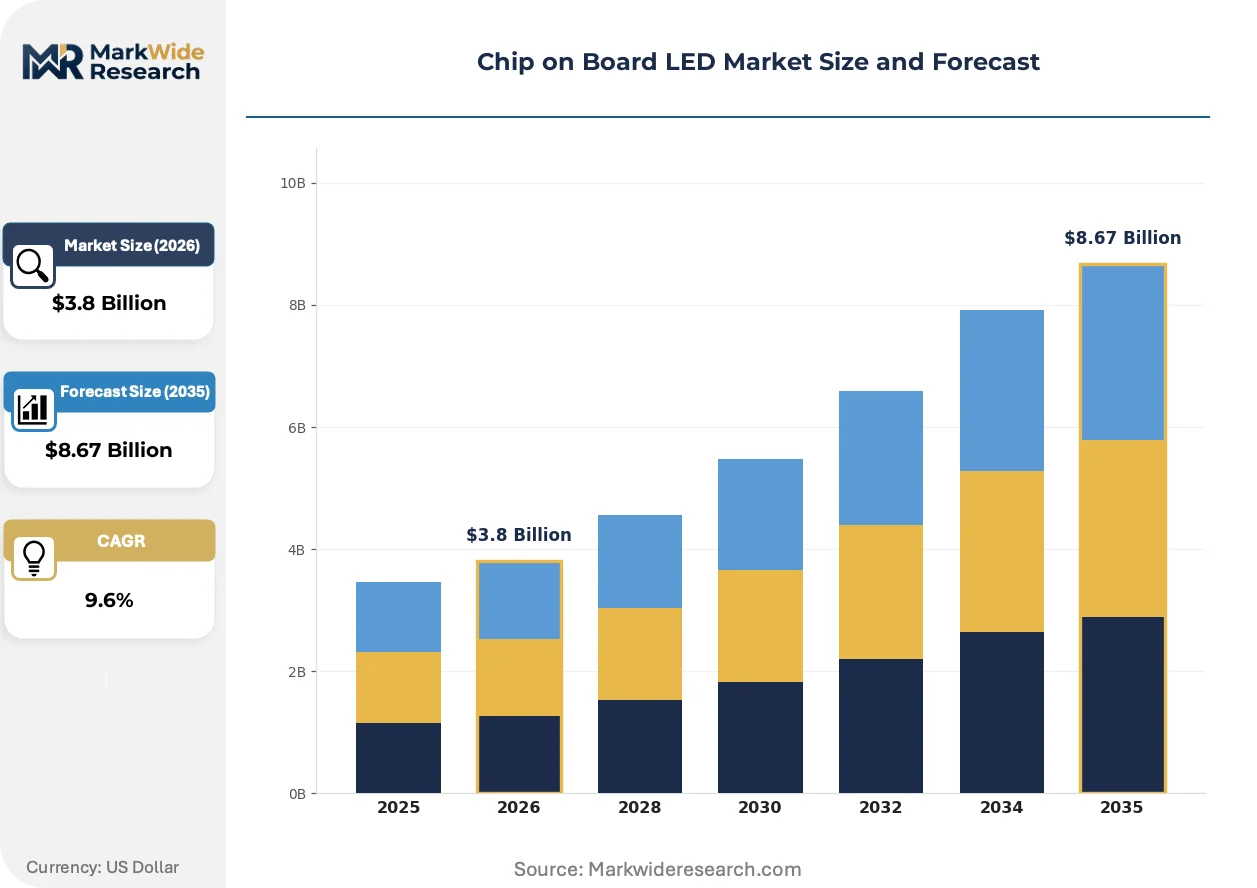
Market Dynamics
Substrate material transitions from aluminum to copper-composite architectures are compressing thermal resistance coefficients while elevating compliance testing costs across divergent regulatory regimes. This materials shift is redistributing competitive advantage toward metallurgical specialists with captive plating capacity.
Growth Catalysts
- GB standards tightening:China's SAMR mandates luminous efficacy minimums and hazardous substance restrictions, forcing domestic COB LED manufacturers to upgrade phosphor-conversion efficiency and substrate thermal conductivity.
- Commercial infrastructure retrofit cycles:General lighting installations in office towers, retail complexes, and logistics facilities are accelerating high-power COB module procurement where operational longevity determines total cost of ownership.
- Flip chip interconnect migration:Automotive forward-lighting programs are displacing wire bond technology with flip chip architectures that deliver superior vibration resistance and beam precision under NHTSA photometric requirements.
Market Restraints
- Copper-composite substrate cost volatility:Raw material exposure to copper futures and specialized ceramic filler supply concentrates pricing power with Japanese metallurgical suppliers.
- East Asian fabrication concentration:Wafer-level chip-scale packaging capacity clusters in Taiwanese and South Korean facilities, creating geographic single-point vulnerability for module integrators.
- Organic LED substitution in display backlights:Premium panel manufacturers are evaluating micro-LED and OLED alternatives for cinematic and medical imaging applications where emission uniformity is paramount.
Strategic Opportunities
- Indoor horticulture spectral tuning:Phosphor-engineered COB arrays enabling tunable full-spectrum output are penetrating controlled-environment agriculture facilities in the Netherlands and Canada.
- EU Ecodesign Directive alignment:Asian manufacturers serving European commercial lighting channels can capture premium channel positioning by front-running RoHS hazardous substance restrictions and circularity disclosure requirements.
- Subscription lumen-maintenance contracting:Lighting vendors are unbundling hardware sales from performance-guaranteed service agreements, creating recurring revenue streams tied to measured photometric degradation curves.
Industry Challenges
- Photobiological safety certification complexity:South Korea's MFDS classification protocols and EU blue-light hazard assessments impose divergent testing timelines that fragment product launch synchronization.
- Thermal simulation talent scarcity:Computational fluid dynamics expertise for high-density COB configurations remains concentrated among semiconductor packaging veterans, constraining module design cycle velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chip on Board LED Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.67 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Power, Mid-Power, Low-Power, Ultra-High-Power Application: Lighting, Displays, Automotive, Backlighting Technology: Flip Chip, Wire Bond, Plastic Package, Ceramic Package End User: Consumer Electronics, Commercial, Industrial, Others |
| Companies Covered | Lumileds Holding B.V., EPISTAR Corporation, EVERLIGHT ELECTRONICS CO., LTD., NICHIA CORPORATION, Bridgelux, Inc., Samsung Electronics Co., Ltd., Seoul Semiconductor Co., Ltd., WOLFSPEED, INC., Lextar Electronics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chip on Board LED Market Emerging Trajectories
Silicon carbide and gallium nitride substrate integration is reshaping thermal management architectures while phosphor-conversion chemistry advances enable spectral precision previously unattainable with conventional ceramic-metal composites.
Flip chip COB architectures are converging with ceramic substrate metallization techniques originally developed for power electronics. Automotive tier-one suppliers are adopting these configurations for adaptive driving beam modules where thermal cycling resistance and optical precision carry regulatory weight. The structural consequence is compressing qualification timelines for conventional wire bond suppliers while elevating captive plating capabilities to tier-one competitive status.
China's MIIT is accelerating GB standard revision cycles for solid-state lighting efficiency, mandating luminous efficacy floors that obsolete first-generation aluminum-substrate COB products. Domestic certification bodies are expanding laboratory capacity to manage throughput. Manufacturers serving export channels are dual-tracking compliance against both GB standards and EU Ecodesign Directive requirements, fragmenting SKU rationalization strategies.
Specification engineers in municipal street-lighting procurement are unbundling luminaire performance from manufacturer brand equity, shifting evaluation criteria toward measured lumen-maintenance curves and third-party thermal testing documentation. This behavioral pivot is elevating component-level substrate and phosphor suppliers to direct specification influence. The pattern is most visible in Chinese provincial infrastructure tenders and German municipal energy-efficiency retrofit programs where total-cost-of-life modeling dominates capital allocation decisions.
Chip on Board LED Market Segmentation
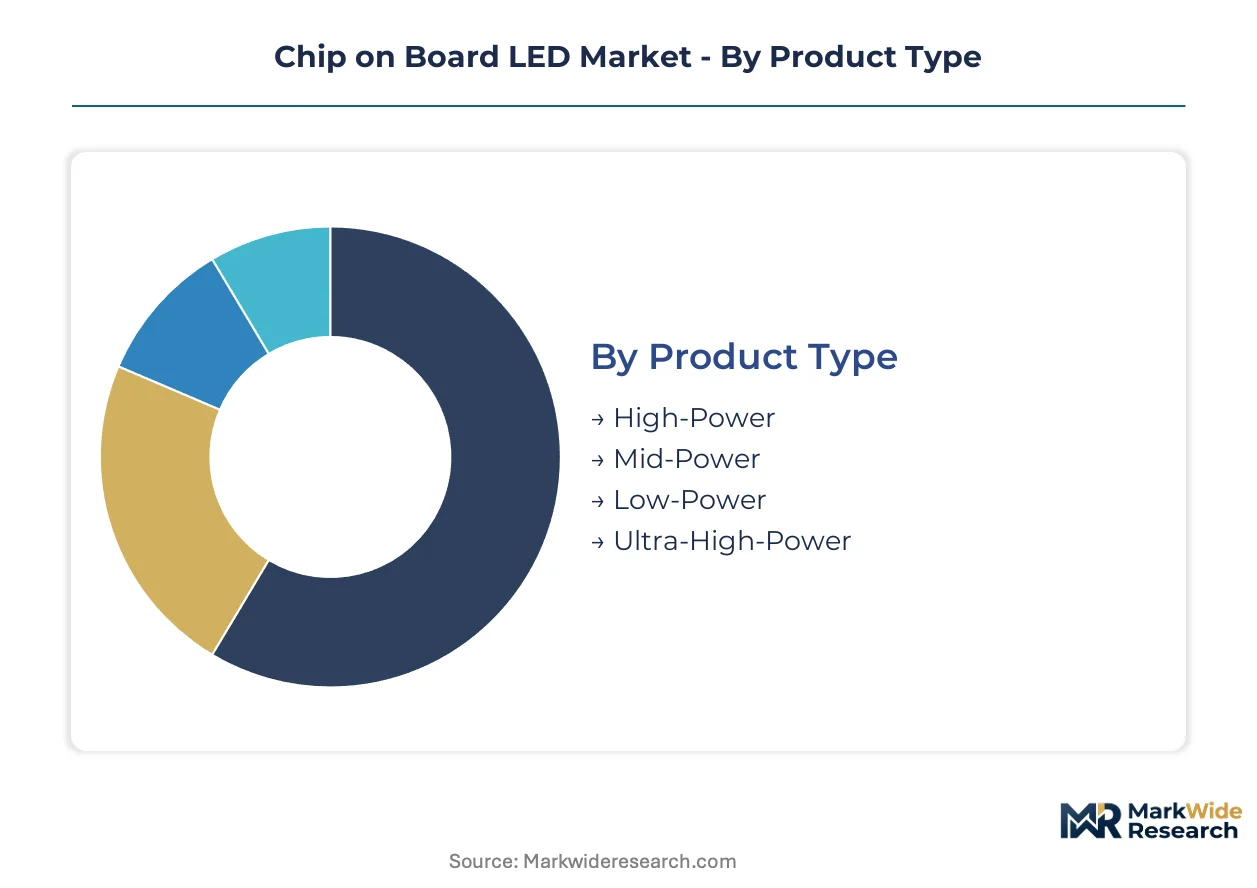
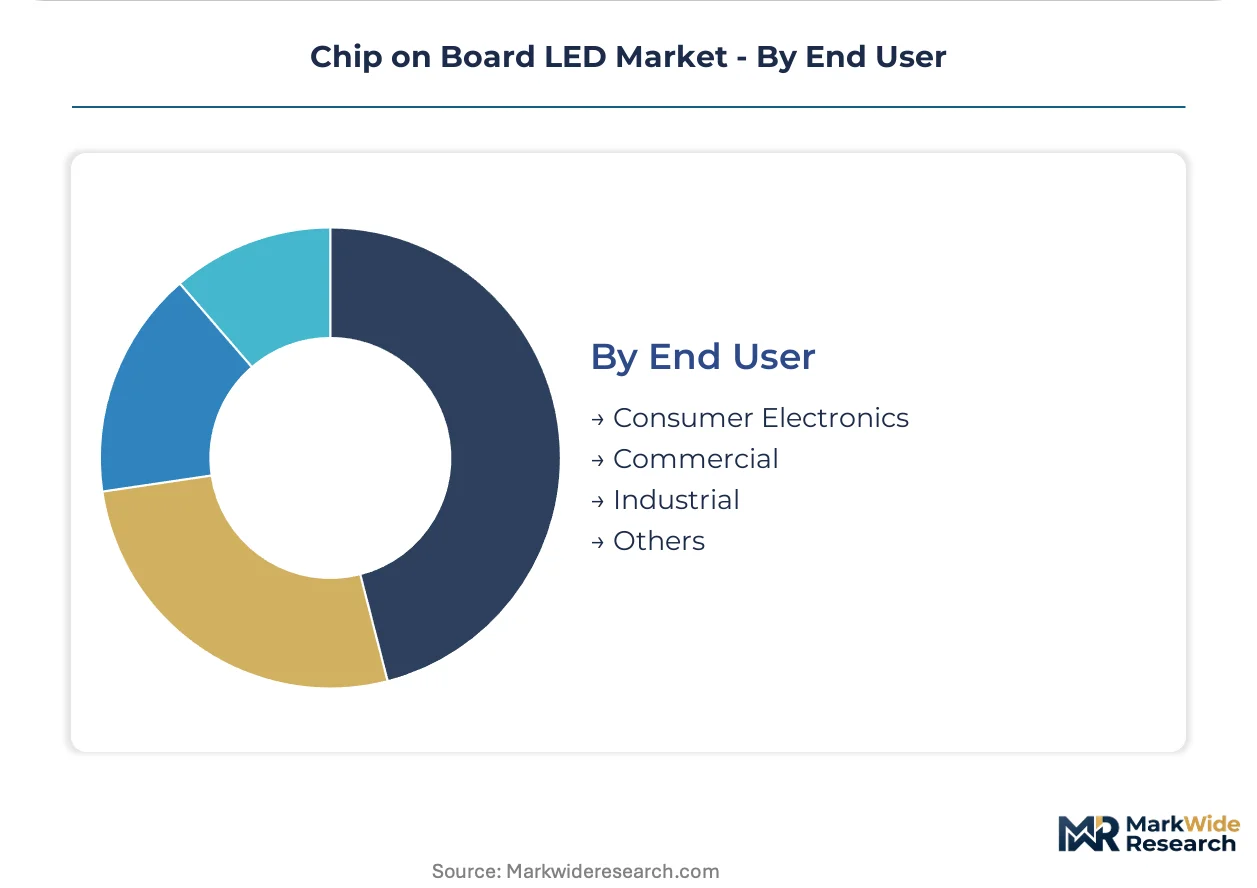
COB LED segmentation reveals how thermal architecture, interconnect technology, and end-use photometric requirements fragment procurement specifications across substrate materials and packaging hierarchies. Module integrators must align product roadmaps with divergent efficacy mandates and reliability testing protocols governing each tier.
Product Type:
Customization intensity varies from standardized mid-power platforms to engineered ultra-high-power assemblies requiring application-specific thermal simulation.
- High-Power:Dense die arrays on copper-composite substrates deliver luminous efficacy exceeding 150 lumens per watt for industrial and street-lighting procurement. Municipal infrastructure tenders in Germany and Chinese provincial energy-efficiency programs specify these modules for total-cost-of-life dominance.
- Mid-Power:Aluminum-substrate configurations retain cost advantages in general commercial illumination where wire bond interconnects suffice. Office tower retrofit cycles in the United States and logistics facility upgrades across the Netherlands concentrate procurement volume here.
- Low-Power:Compact form factors serve portable electronics and decorative accent lighting with minimal thermal management overhead.
- Ultra-High-Power:Surgical luminaires and cinematic display backlights demand customized phosphor-conversion spectra and captive plating metallization.
Most installed capacity flows through Mid-Power. Expansion is steepest in Ultra-High-Power.
Application:
End-use differentiation separates commodity replacement markets from specification-driven verticals where photometric documentation carries procurement weight.
- Lighting:General illumination spans commercial infrastructure retrofits and municipal street-lighting where lumen-maintenance curves determine vendor selection. China's GB standards and EU Ecodesign Directive compliance reshape product qualification requirements.
- Displays:Premium panel backlights for medical imaging and broadcast monitors require emission uniformity that phosphor-engineered COB arrays deliver. Samsung Electronics Co., Ltd. anchors supply chains through captive semiconductor integration.
- Automotive:NHTSA photometric requirements and vibration resistance specifications favor flip chip architectures over conventional wire bonds.
- Backlighting:LCD panel manufacturers evaluate micro-LED alternatives for premium tiers, compressing COB positioning in high-uniformity segments.
Lighting commands the dominant procurement volume. Display applications are climbing the fastest as spectral precision requirements tighten.
Technology:
Interconnect and substrate choices redistribute competitive advantage between metallurgical specialists and legacy packaging houses.
- Flip Chip:Direct die attachment eliminates wire bonds, delivering superior thermal cycling resistance for automotive adaptive driving beam modules. Ceramic substrate metallization techniques from power electronics converge here.
- Wire Bond:Gold and aluminum interconnects retain mid-power cost structures though vibration susceptibility limits automotive penetration.
- Plastic Package:Molded compound substrates serve cost-constrained consumer applications with moderate thermal dissipation requirements.
- Ceramic Package:High thermal conductivity alumina and aluminum nitride substrates anchor ultra-high-power medical and industrial specifications.
Wire Bond retains the largest installed base. Flip Chip is gaining share fastest as automotive qualification timelines compress.
End User:
Customer sophistication spans from price-sensitive consumer electronics to industrial buyers unbundling luminaire performance from manufacturer brand equity.
- Consumer Electronics:Smartphone flash modules and portable lighting drive volume through standardized low-power specifications.
- Commercial:Office, retail, and hospitality procurement emphasizes measured photometric degradation curves over nominal efficacy claims. Third-party thermal testing documentation carries specification weight in German municipal programs.
- Industrial:Manufacturing facilities and warehouse operations prioritize operational longevity where high-power COB modules dominate capital allocation.
- Others:Horticulture and aerospace applications require spectral tuning and radiation hardness outside standard product portfolios.
Commercial channels absorb the most module volume. Industrial procurement is expanding most quickly as facility retrofit cycles accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the dominant manufacturing footprint while Germany anchors European specification engineering, creating divergent competitive dynamics across procurement channels.
China
Municipal street-lighting tenders and industrial facility retrofits drive module demand across coastal provinces. SAMR enforces GB standards that mandate luminous efficacy minimums and hazardous substance restrictions, compressing qualification timelines for domestic manufacturers. Yangtze River Delta fabrication clusters spanning Suzhou and Hangzhou concentrate wafer-level packaging capacity serving both domestic and export channels.
Germany
Municipal energy-efficiency programs and commercial infrastructure retrofits prioritize total-cost-of-life modeling over nominal efficacy claims. EU Ecodesign Directive and RoHS compliance frameworks shape procurement specifications for imported modules. Bavarian industrial zones and North Rhine-Westphalia lighting engineering centers anchor specification influence for high-power COB applications.
United States
Office tower retrofit cycles and logistics facility upgrades concentrate procurement volume in mid-power general illumination segments. NHTSA photometric requirements govern automotive forward-lighting qualification timelines favoring vibration-resistant architectures. Texas and Arizona distribution hubs channel Asian-manufactured modules into North American commercial channels.
South Korea
Premium display panel manufacturing and automotive adaptive driving beam programs drive specification-engineered demand. MFDS certification protocols govern photobiological safety classifications for consumer-facing applications. Seoul Capital Area and Busan-Ulsan fabrication corridors anchor captive semiconductor integration for backlighting supply chains.
Japan
Medical imaging equipment and cinematic display applications demand emission uniformity that phosphor-engineered arrays deliver. METI efficiency standards and JIS certification protocols shape domestic product qualification requirements. Kanto and Kansai industrial belts concentrate metallurgical specialists with captive plating capacity for copper-composite substrate production.
Chip on Board LED Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium specification tiers consolidating around phosphor-conversion expertise while cost-optimized volumes fragment across Asian fabrication networks. Three archetypes dominate: captive semiconductor integrators serving display backlights, metallurgical specialists controlling substrate material transitions, and horticulture-focused spectral engineers. Competitive moves concentrate on backward integration into substrate plating capacity and technology licensing for flip chip architectures.
Among Netherlands-based and Taiwanese specialists, Lumileds Holding B.V. and EPISTAR Corporation exemplify divergent strategic positioning—one anchoring premium indoor horticulture through phosphor expertise, the other sustaining wafer-level chip-scale packaging scale across fabrication facilities. Samsung Electronics Co., Ltd. occupies a position representing captive semiconductor integration for display backlighting supply chains.
| Leading Market Players |
|---|
| Lumileds Holding B.V. |
| EPISTAR Corporation |
| EVERLIGHT ELECTRONICS CO., LTD. |
| NICHIA CORPORATION |
| Bridgelux, Inc. |
| Samsung Electronics Co., Ltd. |
| Seoul Semiconductor Co., Ltd. |
| WOLFSPEED, INC. |
| Lextar Electronics Corporation |
| Others |
Supply Flow & Price Mechanics
Flip chip interconnect migration simultaneously compresses assembly costs and concentrates procurement leverage among automotive tier-one suppliers with captive metallization capacity. China's MIIT-mandated GB standard revisions are forcing aluminum-substrate obsolescence, redistributing cost structures toward copper-composite architectures and elevating Japanese plating specialists to pricing power positions.
Pricing Analysis
Capacity additions in Taiwanese wafer-level packaging facilities are reshaping price floors for mid-power COB modules while premium ultra-high-power tiers retain project-based quoting. Three-tier pricing structure across premium phosphor-engineered, standard ceramic-substrate, and economy aluminum-platform levels differentiates by thermal performance certification and captive plating depth. Cost compression in mid-power general illumination intensifies because Chinese domestic manufacturers absorb GB compliance overhead to defend municipal tender participation. Commercial infrastructure buyers exhibit highest price sensitivity, whereas surgical luminaire and cinematic display procurement prioritizes spectral documentation over unit economics.
Supply Chain Analysis
EU Ecodesign Directive and RoHS qualification gating fragments SKU portfolios for Asian manufacturers serving European commercial channels. Supply concentrates in China, Taiwan, and South Korea, with Yangtze River Delta and Seoul Capital Area anchoring wafer-level chip-scale packaging capacity. Raw material dependencies center on copper-composite substrates, specialized ceramic fillers, and phosphor-conversion chemistries. Single-source vulnerability concentrates with Japanese metallurgical suppliers controlling captive plating capacity for thermal management architectures. Distribution runs through Texas and Arizona distribution hubs channeling Asian-manufactured modules into North American commercial retrofit programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Copper-composite substrate transitions unlock margin expansion for metallurgical specialists capturing thermal performance premiums, while flip chip qualification timelines compress pricing power for legacy wire bond suppliers.
For Market Incumbents: Cement specification influence by backward integration into substrate plating capacity and phosphor-conversion chemistry, defending against OLED substitution in medical imaging backlights and micro-LED encroachment in premium display tiers. Prioritize GB standard pre-certification to lock Chinese provincial infrastructure tender participation before compliance timelines compress. For New Entrants and Emerging Players: EU Ecodesign Directive alignment opens a window for premium channel positioning in German municipal energy-efficiency retrofit programs where third-party thermal testing documentation carries procurement weight. Target indoor horticulture spectral tuning in Netherlands and Canadian controlled-environment agriculture facilities, leveraging phosphor-engineered COB arrays as entry wedge against established general illumination vendors. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-power aluminum-substrate specialists facing GB standard obsolescence pressure, presenting distressed turnaround or capability-stripping opportunities. Long-term viability hinges on substrate material transition execution and automotive flip chip qualification timelines. Watch NHTSA photometric requirement revisions as inflection indicator for vibration-resistant architecture demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Plating | Captive copper-composite metallization capacity secures thermal performance tier positioning against Japanese supplier concentration. |
| Phosphor-Conversion Chemistry Licensing | Spectral precision IP unlocks indoor horticulture and medical imaging premium pricing outside commodity general illumination. |
| GB Standard Pre-Certification Investment | Early SAMR compliance clearance captures Chinese provincial infrastructure tender volume before efficacy mandates tighten. |
| Flip Chip Architecture Qualification | NHTSA-aligned vibration resistance opens automotive adaptive driving beam procurement previously closed to wire bond suppliers. |
| Subscription Lumen-Maintenance Contracting | Recurring revenue streams tied to measured photometric degradation unbundle hardware sales from performance guarantees in commercial retrofits. |
Methodological Framework
Multiple input streams — primary interviews with substrate metallurgists and phosphor chemists, secondary validation through SAMR certification databases and EU Ecodesign Directive filings, and trade data reconciliation — were synthesized across bottom-up module shipment tallies and top-down lighting fixture demand estimates. Conversations with municipal procurement officers in Germany and Chinese provincial infrastructure planners, alongside thermal testing laboratory directors and automotive tier-one supplier engineers, informed qualification timeline and specification weight assumptions. SEC filings from captive semiconductor integrators, Japanese METI efficiency standard disclosures, and customs records for copper-composite substrate trade flows provided secondary anchor points.
Data-stream reconciliation applied segmentation dimensions spanning power tier, interconnect technology, substrate material, and end-use vertical across the projection horizon. CAGRs derived from installed base turnover modeling and retrofit cycle phasing, with automotive flip chip penetration curves and horticulture spectral tuning adoption rates as industry-specific demand drivers. Cross-validation against phosphor-conversion chemistry patent filings and municipal tender award databases tested forecast sensitivity.
Revisions become necessary when GB standard revision cycles accelerate beyond modeled timelines or copper futures volatility disrupts substrate cost assumptions. Forecasts reflect documented assumptions on regulatory compliance cost absorption and thermal simulation talent scarcity constraints. A model refresh is warranted upon material change in NHTSA photometric requirements or EU RoHS hazardous substance restriction scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
LED Mask Market
LED
Micro LED Display Market
LED
Architectural LED Products Market
LED
LED Display Control Card Market
LED
LED Digital Scoreboard Market
LED
Mini LED Display Market
LED
Middle East LED Lights Market
LED
Russia LED Market
LED
North America Indoor LED Lighting Market
LED
Germany Outdoor LED Lighting Market
LED
France Outdoor LED Lighting Market
LED
Egypt LED Lighting Market
LED
North America LED Lighting Market
LED
GCC LED Lighting Market
LED
South America Indoor LED Lighting Market
LED
Gan Substrate Market