
 Concrete Waterproofing with Crystalline Technology Market | 2026-2036
Concrete Waterproofing with Crystalline Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Waterproofing with Crystalline Technology Market Analysis
Portland cement substitution with supplementary cementitious materials is realigning crystalline admixture formulations and cost structures. Sika AG leverages its European construction chemicals infrastructure to sustain specification relationships with infrastructure developers. Kryton International Inc anchors its position through specialized hydrophilic crystal growth technology for deep basement applications. BASF SE competes by extending its construction materials portfolio into reactive crystalline systems for tunnel linings.
Concrete waterproofing with crystalline technology refers to cementitious systems containing proprietary active chemicals that react with moisture and free lime to form insoluble crystalline structures within concrete capillaries, typically achieving water permeability reductions exceeding 85% under hydrostatic pressure conditions. Crystalline admixtures command the dominant volume position due to their integration during batching, while self-healing variants represent the fastest-expanding technology segment driven by autonomous crack-sealing capabilities in critical infrastructure. Surface coatings retain mature margin pools in retrofit markets, and tunnel applications concentrate premium pricing where hydrostatic pressures demand performance-guaranteed specifications.
REACH compliance and CE marking requirements under the EU Construction Products Regulation shape product formulation standards and market access across European member states. The US EPA's stormwater management mandates and state-level building codes in California and New York influence specification thresholds for below-grade waterproofing in commercial construction. China's GB standards and dual carbon goals are tightening embodied-carbon limits on construction materials, creating compliance complexity for imported crystalline systems. Stakeholders must monitor regulatory divergence between performance-based and prescriptive standards when allocating R&D resources across regional product portfolios.
Market Dynamics
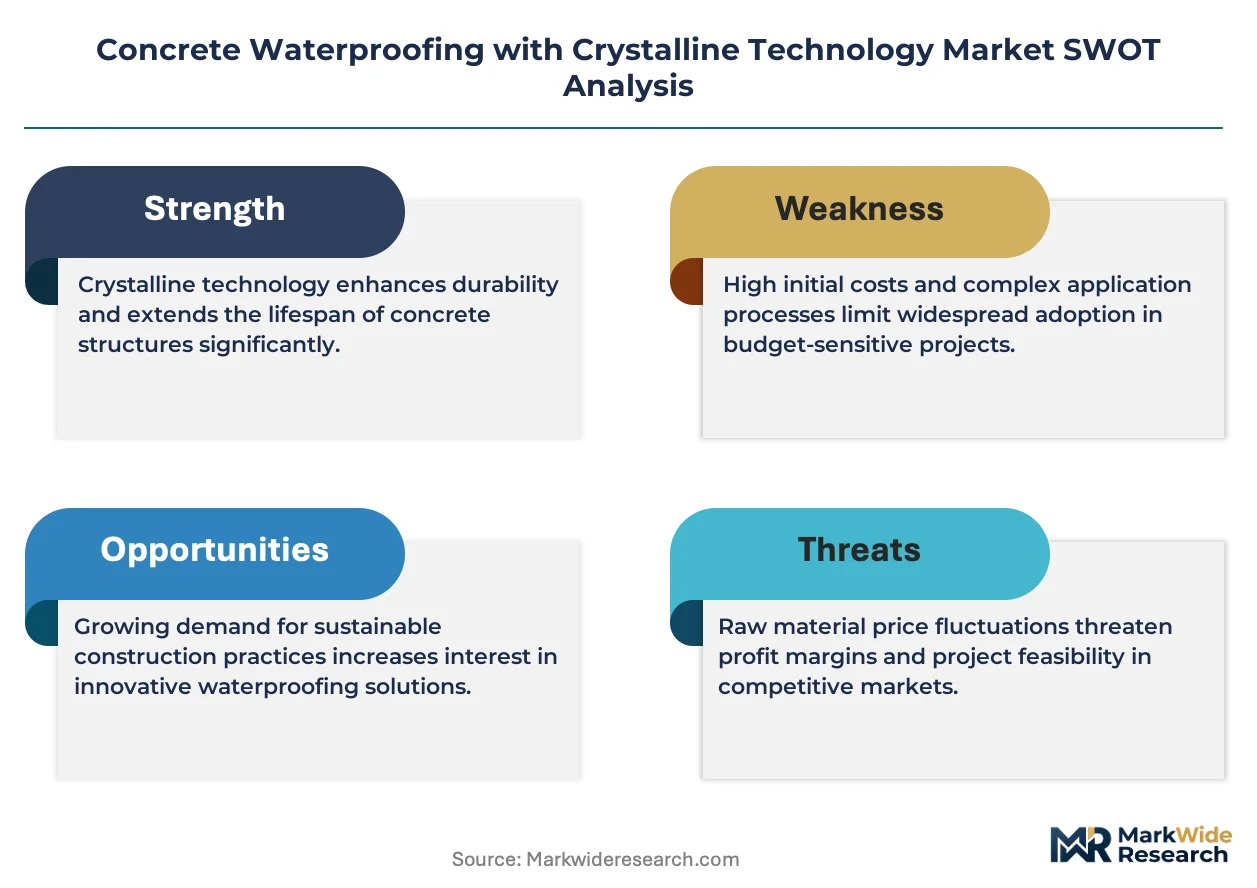
Portland cement substitution with supplementary cementitious materials is fundamentally restructuring crystalline admixture formulations and cost structures across construction chemicals supply chains.
Growth Catalysts
- EU Green Deal embodied-carbon thresholds:Construction material specifications in Germany's Rhine-Ruhr corridor are redirecting toward cementitious systems with lower lifecycle footprints, accelerating crystalline waterproofing adoption in tunnel refurbishment and water-tank construction.
- Metropolitan transit authority underground infrastructure:Expanding crystalline waterproofing specifications in subway and metro projects are creating sustained specification pull for hydrostatic pressure-resistant systems.
- Self-healing crystalline technology:Autonomous crack-sealing capabilities in critical infrastructure are driving fastest-expanding segment growth as asset owners prioritize reduced maintenance liability.
Market Restraints
- Supplementary cementitious material cost volatility:Fly ash and slag supply fluctuations are compressing admixture margin structures and complicating batch-to-batch consistency guarantees.
- REACH compliance formulation costs:ECHA chemical registration requirements and CE marking under EU Construction Products Regulation are elevating R&D expenditure barriers for market access.
- Sheet membrane substitution in retrofit:Pre-applied bituminous systems retain contractor familiarity in below-grade remediation, limiting crystalline surface coating penetration in mature building stock.
Strategic Opportunities
- China GB standards compliance:Dual carbon goals and tightening embodied-carbon limits on construction materials are creating first-mover positioning for crystalline systems meeting domestic certification.
- Deep basement hydrophilic crystal growth:Specialized formulations for high-hydrostatic-pressure environments represent underserved premium specification territory in dense urban cores.
- Performance-guaranteed tunnel lining contracts:Risk-transfer procurement models in infrastructure megaprojects are opening specification pathways for crystalline systems with documented permeability reduction credentials.
Industry Challenges
- Batching integration technician training:Precise crystalline admixture dosing during concrete production requires specialized quality control protocols that ready-mix operators often lack.
- Multi-jurisdiction certification timelines:Divergence between performance-based and prescriptive standards across EU member states, US states, and Chinese provinces fragments product portfolio development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Waterproofing with Crystalline Technology Market |
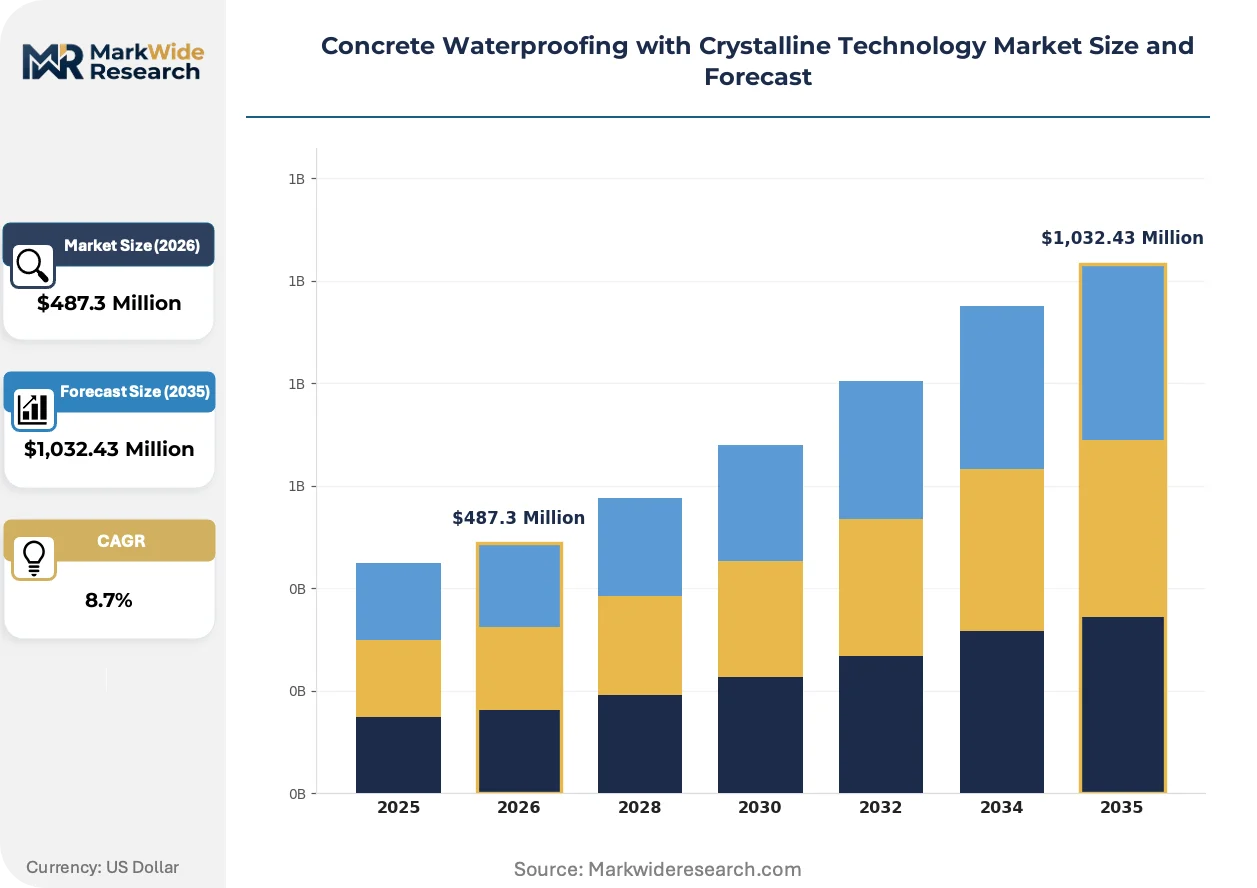
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystalline Admixtures, Surface Coatings, Membranes, Sealers Application: Basements, Water Tanks, Swimming Pools, Tunnels End User: Construction Companies, Infrastructure Developers, Residential Builders, Contractors Technology: Hydrophilic, Hydrophobic, Self-Healing, Reactive |
| Companies Covered | Xypex Chemical Corporation, Kryton International Inc, BASF SE, Sika AG, Saint-Gobain, Penetron, Fosroc International Limited, Hycrete Inc, Cemix Products Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Waterproofing with Crystalline Technology Market Emerging Trajectories
Active chemical reaction engineering is reshaping how crystalline waterproofing systems achieve permeability reduction, with formulation science advancing faster than application methodology standardization.
Self-healing crystalline admixtures are consolidating specification authority in critical infrastructure segments. These systems trigger autonomous crystal growth upon crack formation, sealing capillary pathways without external intervention. Metropolitan transit authorities and nuclear facility operators are adopting them for reduced lifecycle maintenance liability. The technology is consolidating premium pricing power away from conventional surface-applied membranes in hydrostatic pressure applications.
REACH and CE marking requirements under the EU Construction Products Regulation are elevating formulation transparency mandates. Chemical substance registration dossiers now demand extensive toxicological data, compressing product development timelines for new crystalline actives. German and French infrastructure specifications are most affected, with contractors increasingly requiring third-party certification documentation before bid submission.
Asset owner procurement departments are unbundling material supply from installation warranties, forcing crystalline admixture suppliers to document standalone performance credentials. Engineering firms are replacing bundled contractor packages with direct material specification in design-build contracts. This pattern concentrates most visibly in California and New York state-level building codes for below-grade commercial construction.
Concrete Waterproofing with Crystalline Technology Market Segmentation
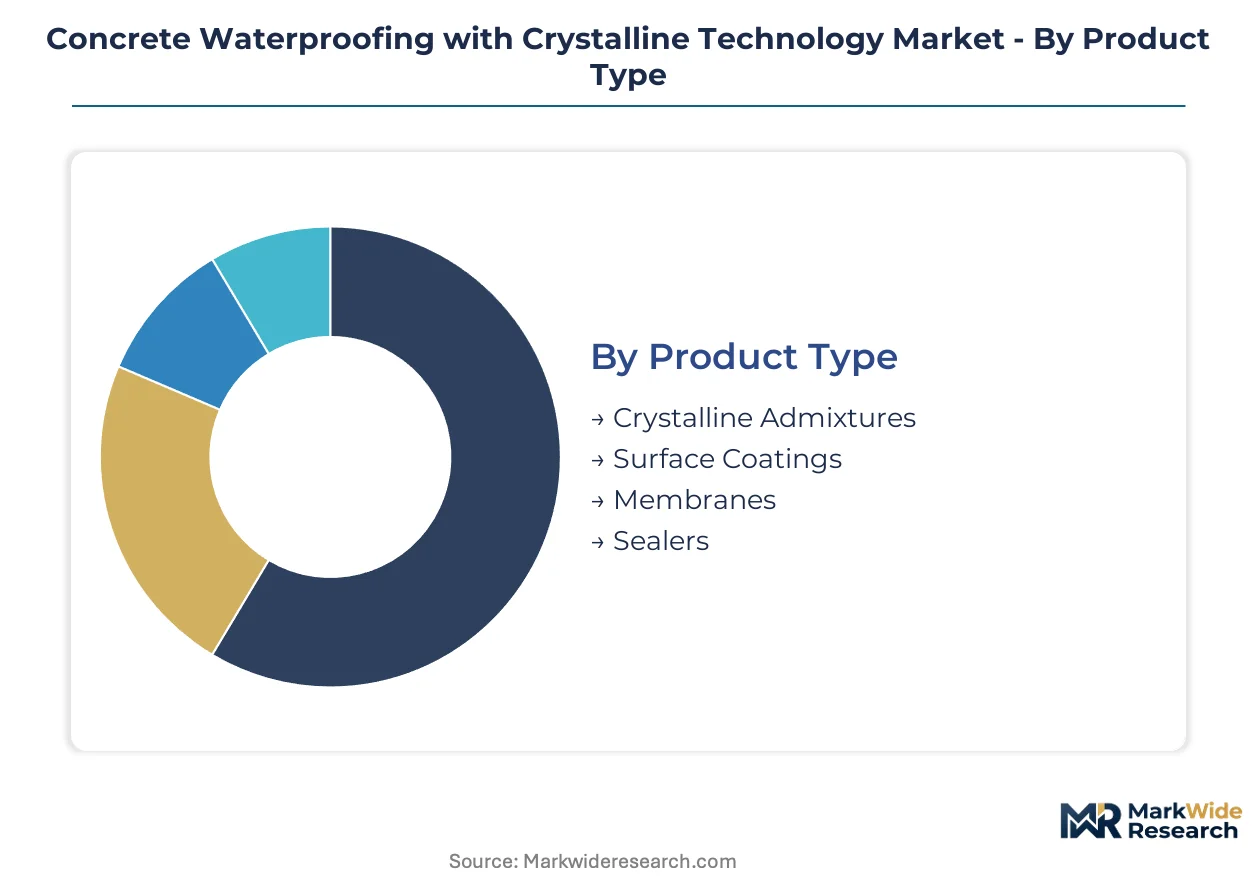
Crystalline waterproofing procurement diverges sharply between infrastructure-scale specifications and commercial building retrofits. Segment boundaries reflect technical performance thresholds, installation methodology constraints, and lifecycle cost accountability structures that reshape competitive positioning across construction chemicals channels.
Product Type:
Volume concentration sits with batch-integrated formulations, while premium margin pools attach to surface-applied systems requiring specialized labor certification.
- Crystalline Admixtures:Proprietary active chemicals blend directly into concrete during batching, reacting with moisture and free lime to form insoluble crystalline structures within capillaries. Demand concentrates in Germany's Rhine-Ruhr corridor tunnel refurbishment programs, where hydrostatic pressure specifications mandate batch-integrated permeability reduction exceeding 85%. EU Green Deal embodied-carbon thresholds redirect specification decisions toward these cementitious systems with lower lifecycle footprints.
- Surface Coatings:Post-cure cementitious slurries containing crystalline actives penetrate concrete substrates to seal capillary networks. Retrofit markets in California and New York state-level building codes for below-grade commercial construction sustain mature margin pools, though contractor familiarity with pre-applied bituminous systems limits penetration in remediation projects.
- Membranes:Sheet-based crystalline composite barriers deliver standardized thickness control for critical infrastructure.
- Sealers:Low-viscosity liquid formulations provide capillary-blocking protection for non-structural applications.
Mature deployment sits with Surface Coatings in building stock remediation. Newer deployment is concentrated in Crystalline Admixtures for infrastructure megaprojects.
Application:
Performance-guaranteed specifications cluster where hydrostatic pressure liability transfers to material suppliers, while cost-driven segments tolerate higher permeability variance.
- Tunnels:Lining systems face sustained hydrostatic pressure from groundwater infiltration, demanding documented permeability reduction credentials under risk-transfer procurement models. Metropolitan transit authority underground infrastructure projects in dense urban cores concentrate premium pricing power, with specifications expanding across EU member states and China's GB standards compliance frameworks.
- Water Tanks:Potable water containment requires NSF/ANSI 61 certification or equivalent drinking water contact approvals, constraining formulation chemistry options. Germany's accelerating water-tank construction programs in the Rhine-Ruhr corridor exemplify demand concentration where lifecycle maintenance liability drives crystalline specification over epoxy alternatives.
- Basements:Below-grade residential and commercial foundations represent volume deployment with variable performance requirements.
- Swimming Pools:Chlorine-resistant crystalline formulations address recreational water containment with aesthetic finish constraints.
Specification authority concentrates in Tunnels for autonomous infrastructure agencies. Volume scaling is accelerating fastest in Water Tanks as municipal asset owners prioritize reduced maintenance liability.
End User:
Procurement unbundling separates material specification from installation, reshaping supplier relationships across contractor tiers.
- Infrastructure Developers:Public-sector transit authorities and water utility operators specify crystalline systems directly in design-build contracts, bypassing bundled contractor packages. Engineering firms in California and New York state-level codes increasingly mandate standalone material credentials with third-party certification documentation before bid submission.
- Construction Companies:Tier-1 general contractors integrate crystalline admixtures into concrete supply agreements for large-scale commercial foundations, negotiating volume pricing against sheet membrane alternatives.
- Contractors:Specialty waterproofing applicators retain influence in surface coating and membrane installation markets.
- Residential Builders:Cost-sensitive single-family and multi-family developers prioritize first-cost minimization over lifecycle performance.
Direct specification authority rests with Infrastructure Developers. Commercial volume flows through Construction Companies.
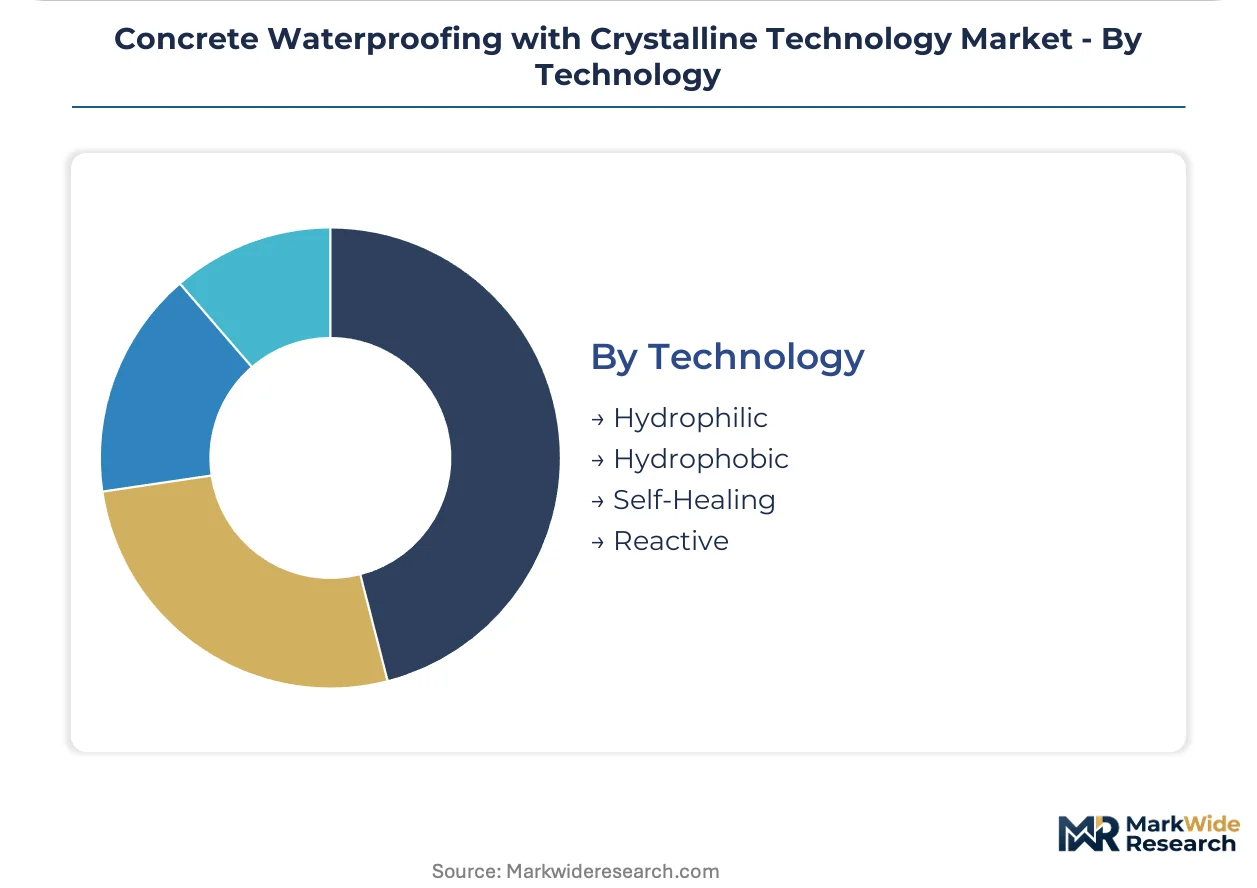
Technology:
Reaction mechanism engineering differentiates autonomous performance capabilities from passive barrier functions.
- Self-Healing:Triggered crystalline growth upon crack formation seals capillary pathways without external intervention, consolidating premium specification authority in critical infrastructure. Metropolitan transit authorities and nuclear facility operators adopt these systems for reduced lifecycle maintenance liability, with the technology expanding most quickly as asset owners prioritize autonomous performance.
- Hydrophilic:Specialized crystal growth chemistry attracts and binds water molecules to form insoluble structures, anchoring positions in deep basement applications facing high hydrostatic pressure.
- Reactive:Conventional cementitious systems depend on ongoing moisture presence to sustain crystalline development.
- Hydrophobic:Water-repellent formulations suit above-grade and non-pressurized applications with lower performance thresholds.
Proven deployment dominates Reactive formulations. Steepest expansion trajectory attaches to Self-Healing in critical infrastructure procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Ruhr corridor concentrates specification authority for crystalline waterproofing in tunnel refurbishment and water-tank construction programs. Metropolitan transit authorities across dense urban cores are expanding hydrostatic pressure-resistant system requirements.
Germany
The Rhine-Ruhr corridor drives tunnel refurbishment and municipal water-tank construction with strict embodied-carbon specifications. EU Green Deal thresholds redirect material decisions toward cementitious systems with lower lifecycle footprints. Düsseldorf and Essen anchor specification clusters where infrastructure agencies mandate batch-integrated crystalline admixtures.
United States
California and New York state-level building codes enforce below-grade waterproofing thresholds for commercial foundations. The US EPA's stormwater management mandates influence specification decisions in dense urban construction. Metropolitan transit authorities in New York City and Los Angeles expand crystalline system requirements for subway infrastructure.
China
Dual carbon goals and tightening GB standards on construction materials reshape compliance frameworks for imported crystalline systems. The country's national construction material regulator enforces embodied-carbon limits that favor domestic certification pathways. Yangtze River Delta infrastructure megaprojects concentrate demand for performance-guaranteed tunnel lining specifications.
France
CE marking requirements under the EU Construction Products Regulation elevate formulation transparency mandates for crystalline actives. ANSM and CNIL oversight extends to chemical substance registration dossiers demanding toxicological data. Paris and Lyon infrastructure specifications increasingly require third-party certification documentation before contractor bid submission.
Canada
Health Canada and PMRA standards govern chemical admixture approval timelines for crystalline waterproofing systems. Provincial building codes in Ontario and British Columbia align with performance-based specification trends in below-grade commercial construction. Toronto's underground transit expansion programs create sustained demand for hydrostatic pressure-resistant crystalline applications.
Concrete Waterproofing with Crystalline Technology Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with batch-integrated admixture suppliers commanding specification relationships while surface coating applicators compete on installation speed. The vendor base organizes around three archetypes: European construction chemicals conglomerates with infrastructure developer ties, North American technology specialists focused on hydrophilic crystal growth, and regional cementitious materials suppliers serving cost-sensitive retrofit markets. Dominant competitive moves include backward integration into supplementary cementitious material supply chains and technology licensing partnerships for self-healing formulation access.
Within the branded specialist tier, Sika AG and BASF SE exemplify European construction chemicals infrastructure leveraged for specification authority. Kryton International Inc occupies a position among technology-focused specialists emphasizing proprietary hydrophilic systems. These three anchors represent distinct strategic postures: scale-driven portfolio breadth, reactive crystalline systems for tunnel applications, and specialized deep basement performance credentials.
| Leading Market Players |
|---|
| Xypex Chemical Corporation |
| Kryton International Inc |
| BASF SE |
| Sika AG |
| Saint-Gobain |
| Penetron |
| Fosroc International Limited |
| Hycrete Inc |
| Cemix Products Ltd |
| Others |
Supply Flow & Price Mechanics
Performance-certification divergence between self-healing admixtures and conventional surface coatings manifests in both margin structures and raw material sourcing patterns. Premium formulations commanding specification authority in tunnel linings draw from specialized hydrophilic crystal growth chemistry, while commodity surface coatings compete on installer labor efficiency and regional cementitious material availability.
Pricing Analysis
Volume-margin splits sharply across application tiers. Crystalline admixtures integrated during batching capture scale-driven project pricing, while surface coatings retain installer-margin pools in retrofit markets. Price differentiation hinges on CE marking tier and hydrostatic pressure certification grade. Cost compression in standard-grade formulations stems from fly ash supply volatility. Residential builders exhibit highest price sensitivity; infrastructure developers prioritize performance guarantees over unit economics.
Supply Chain Analysis
China's domestic-content mandates under GB standards compliance frameworks are reshaping crystalline active chemical sourcing for Yangtze River Delta infrastructure megaprojects. Manufacturing concentrates in Germany, China, and the United States. Proprietary active chemical blends draw from specialized silicate and aluminosilicate feedstocks. Single-source vulnerability attaches to hydrophilic crystal growth chemistry patents held by technology specialists. Distribution runs through construction chemicals distributors and direct specification channels with infrastructure developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Self-healing crystalline technology is displacing conventional surface-applied membranes in critical infrastructure procurement, creating a technology-transition window where formulation capabilities determine competitive survival.
For Market Incumbents: Anticipate margin compression in standard-grade admixtures as supplementary cementitious material cost volatility intensifies. Defensive consolidation should prioritize backward integration into regional fly ash and slag supply chains. Certification investment in China's GB standards compliance represents the priority lever for Yangtze River Delta positioning. For New Entrants and Emerging Players: Direct-to-specifier digital channels bypass entrenched construction chemicals distribution networks in infrastructure procurement. White-space targets include deep basement hydrophilic formulations in dense urban cores and performance-guaranteed tunnel lining contracts under risk-transfer procurement models. Technical documentation platforms targeting engineering firms enable specification capture before contractor bidding. For Investors and Strategic Acquirers: Re-rating potential sits with self-healing formulation specialists given metropolitan transit authority procurement unbundling trends. Long-term viability favors technology-focused players with proprietary crystal growth chemistry and documented permeability reduction credentials. The signal to watch is direct material specification clauses in California and New York state-level design-build contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Supplementary Cementitious Materials | Captive slag and fly ash supply secures batch-to-batch consistency guarantees for admixture producers. |
| Self-Healing Formulation Patent Licensing | Technology access agreements accelerate market entry for regional cementitious materials suppliers. |
| CE Marking and REACH Compliance Investment | ECHA dossier completion unlocks German and French infrastructure specification pathways. |
| Direct Specification Platform Development | Engineering firm engagement tools bypass bundled contractor packages in procurement unbundling. |
| China GB Standards Certification Program | Domestic certification enables participation in dual carbon goal infrastructure megaprojects. |
Methodological Framework
Trade association publications, customs and trade flow databases, and construction chemicals industry reports formed the secondary backbone. Primary interviews with ready-mix plant managers, infrastructure procurement officers at metropolitan transit authorities, waterproofing specialty contractors, and technical R&D directors at construction chemicals suppliers validated demand patterns. SEC filings and EU Construction Products Regulation documentation provided supplier-side financial and compliance data. Bottom-up and top-down triangulation reconciled project-level specification data with national construction output statistics.
Bottom-up modeling anchored volume estimates in tunnel refurbishment program announcements and water-tank construction pipelines across Germany's Rhine-Ruhr corridor, California, and the Yangtze River Delta. Top-down cross-checks applied construction chemicals intensity ratios to national cement consumption forecasts. Segmentation dimensions included product type, application, technology mechanism, and end-user procurement structure. CAGRs were derived from trend extrapolation of specification adoption rates and embodied-carbon regulatory trajectory.
The model holds under continued EU Green Deal threshold enforcement and China dual carbon goal implementation; deviation in supplementary cementitious material supply disruptions or REACH registration timeline extensions would shift volume trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Acoustic Panel Market
Building & Construction Materials
Roofing Underlayment Market
Building & Construction Materials
Electrically Dimmable Exterior Window Systems for Premium Cabins Market
Building & Construction Materials
Global Awning Market
Building & Construction Materials
Artificial Wood Beams Market
Building & Construction Materials
Outside Door Handle Market
Building & Construction Materials
Door Canopy Market
Building & Construction Materials
Finishing Lines Market
Building & Construction Materials
Building and Construction Plastic Fasteners Market
Building & Construction Materials
Europe Building Materials Market
Building & Construction Materials
North America Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Asia-Pacific Particle Board Market
Building & Construction Materials
Global Fire-Rated Medium Density Fiberboard Market
Building & Construction Materials
Global Screw Piles Market
Building & Construction Materials
Italy Ceramic Tiles Market
Building & Construction Materials
Precast Concrete Pile Market