
 France Prefab Wood Building Market | 2026-2036
France Prefab Wood Building Market Size, Share, and Industry Trends Forecast 2026-2036
France Prefab Wood Building Market Foresight
Modular panel bundling with factory-installed insulation and utility rough-ins is rebalancing buyer choice toward turnkey prefabricated solutions. Maisons Pierre leverages its national retail network to anchor volume in standard residential configurations. Bouygues Construction competes through industrialized manufacturing scale at dedicated offsite facilities. LCC Maisons Bois specializes in bespoke timber frames for premium alpine and rural deployments.
France prefab wood building denotes structurally engineered timber assemblies produced in controlled factory conditions, typically featuring moisture content below 20 percent and precision-cut joinery for on-site crane installation, serving residential and commercial construction with accelerated build schedules and reduced on-site waste. Cross-laminated timber dominates structural applications for mid-rise commercial and educational facilities where fire-rated performance and dimensional stability command premium positioning. Modular panels sustain faster growth in residential housing as developers optimize labor costs and weather-independent production cycles. Factory assembled units capture concentrated demand from hospitality structures requiring rapid deployment in seasonal tourism corridors.
France's RE2020 regulation, administered by the Ministry of Ecological Transition, mandates declining carbon thresholds for new buildings and directly elevates wood-based prefabrication over concrete-intensive methods. CE marking under the EU Construction Products Regulation governs structural timber performance declarations, while ECHA oversight of wood preservative biocides shapes material specification protocols for exterior applications. Stakeholders must monitor evolving carbon accounting methodologies and local zoning permissiveness for timber height limits when committing manufacturing capacity to specific construction type segments.
Market Dynamics
France's RE2020 environmental regulation is compressing carbon intensity thresholds for new construction, forcing residential and commercial developers to abandon concrete-intensive methods in favor of factory-assembled timber systems with verified lifecycle emissions data.
Growth Catalysts
- Alpine Tourism Corridors:Seasonal hospitality developers in Auvergne-Rhône-Alpes prioritize rapid-deployment prefabricated units to capture compressed booking windows. Factory production cycles bypass weather-dependent on-site concrete curing.
- RE2020 Carbon Thresholds:The Ministry of Ecological Transition's declining biogenic carbon limits elevate structural timber over steel and concrete for mid-rise residential and educational facilities.
- Cross-Laminated Timber Fire Engineering:Advanced char-layer modeling enables five-story commercial buildings with exposed timber structures, unlocking urban infill sites previously restricted to non-combustible construction.
Market Restraints
- Nordic Spruce Supply Concentration:Structural-grade laminated timber production depends on Swedish and Finnish sawmill capacity, exposing French builders to Baltic Sea shipping disruptions and currency volatility.
- Height Limit Zoning Variance:Municipal plans d'urbanisme in dense departments maintain timber height restrictions below concrete allowances, fragmenting addressable project pipelines.
- Steel-Frame Substitution in Seismic Zones:Parts of the French Alps subject to moderate seismic classification see engineered steel retain preference for lateral load resistance despite timber's carbon advantages.
Strategic Opportunities
- Brittany Coastal Hospitality:Underdeveloped prefabricated eco-lodge supply in Côtes-d'Armor and Finistère offers first-mover positioning for modular timber operators targeting sustainable tourism certification.
- MaPrimeRénov' Deep Retrofit Integration:The national renovation subsidy scheme's extension to structural extensions creates a channel for prefabricated timber additions atop existing concrete housing stock.
- Building Information Modeling-Factory Control System Convergence:Direct data pipelines from architectural models to CNC cutting tables compress design-to-delivery timelines and reduce dimensional tolerance waste.
Industry Challenges
- Charpentier Traditionnel Skill Scarcity:Factory precision cutting and on-site crane assembly require hybrid competencies absent from conventional carpentry apprenticeship pipelines, constraining workforce scaling.
- CE Marking Documentation Burden:Structural timber performance declarations under the EU Construction Products Regulation demand third-party testing protocols that extend product launch timelines by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Prefab Wood Building Market |
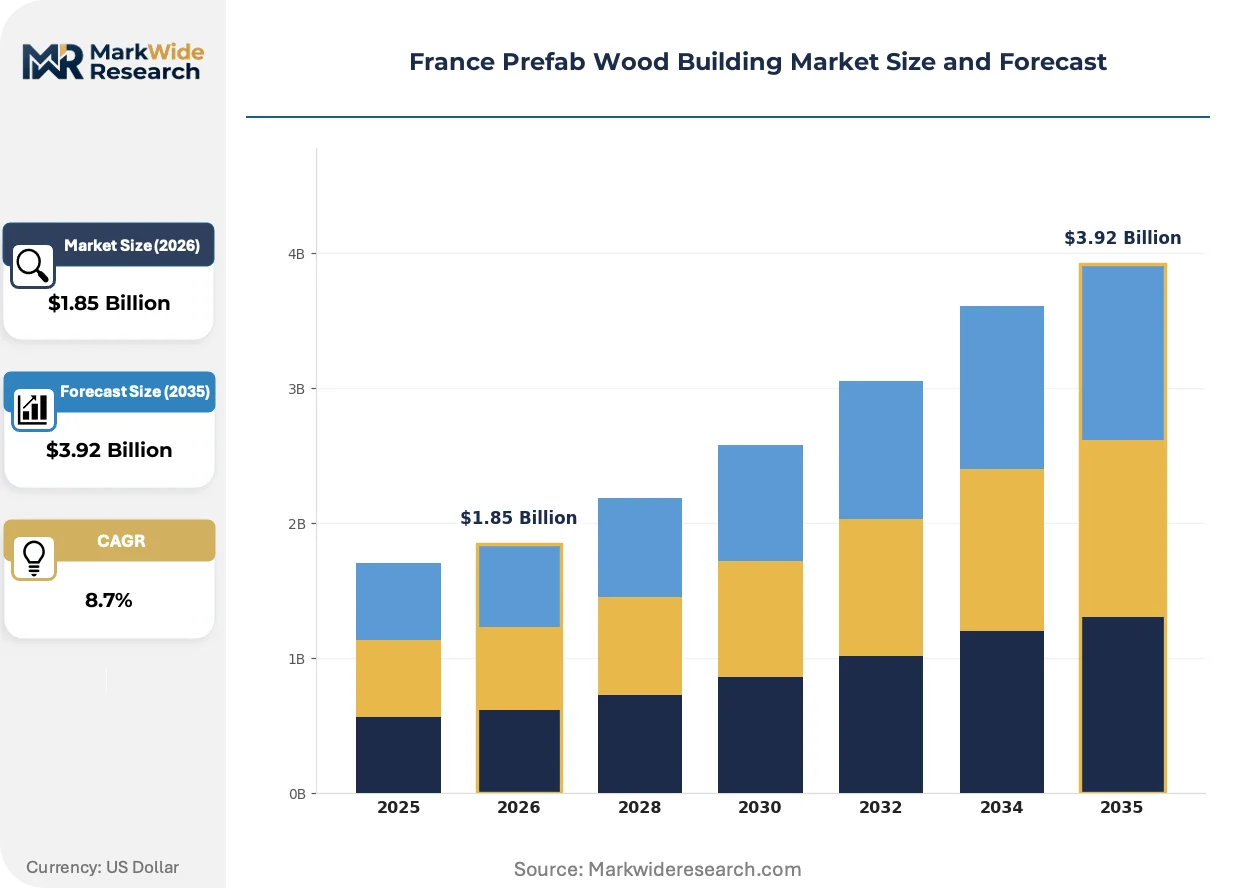
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Panels, Structural Insulated Panels, Timber Frames, Cross-Laminated Timber, Glue-Laminated Timber Construction Type: Residential Housing, Commercial Complexes, Educational Facilities, Hospitality Structures, Office Buildings End User: Property Developers, Architectural Firms, Construction Contractors, Engineering Consultants, Government Agencies Installation Method: On-Site Assembly, Factory Assembled Units, Hybrid Installation, Prefabricated Modules, Panelized Systems |
| Companies Covered | Batipin, Macoretz Scop, Maisons Pierre, Bouygues Construction, Legoupil Industrie, LCC Maisons Bois, Martin Calais, Chalets Bayrou, Les Maisons de Manon, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Prefab Wood Building Market Shifts & Advancements
Digital fabrication and regulatory carbon accounting are converging to transform how French developers specify structural systems, compressing the gap between architectural intent and factory-delivered performance.
Cross-laminated timber is consolidating its position as the dominant engineered wood product for mid-rise commercial and educational structures in France. Institutional buyers including regional hospital authorities and university estate departments specify CLT for its dimensional stability and exposed aesthetic. The technology is consolidating market share previously fragmented between steel-frame and in-situ concrete alternatives, particularly in projects targeting RE2020 carbon compliance.
The Ministry of Ecological Transition's enforcement of lifecycle carbon declarations under RE2020 is reshaping material specification protocols. Developers must now document embodied carbon from extraction through end-of-life, penalizing high-emission construction methods. Educational and healthcare procurement bodies in Île-de-France and Occitanie have responded by mandating timber structural systems for new public buildings exceeding 1,000 square meters.
Design-build procurement is displacing traditional general-contractor bidding for prefabricated timber projects in France. Single-source responsibility for factory production and on-site assembly reduces interface risk for developers facing compressed construction schedules. This pattern concentrates in Auvergne-Rhône-Alpes hospitality developments and Paris-region social housing, where early contractor involvement enables utility rough-in optimization during panel fabrication.
France Prefab Wood Building Market Segmentation
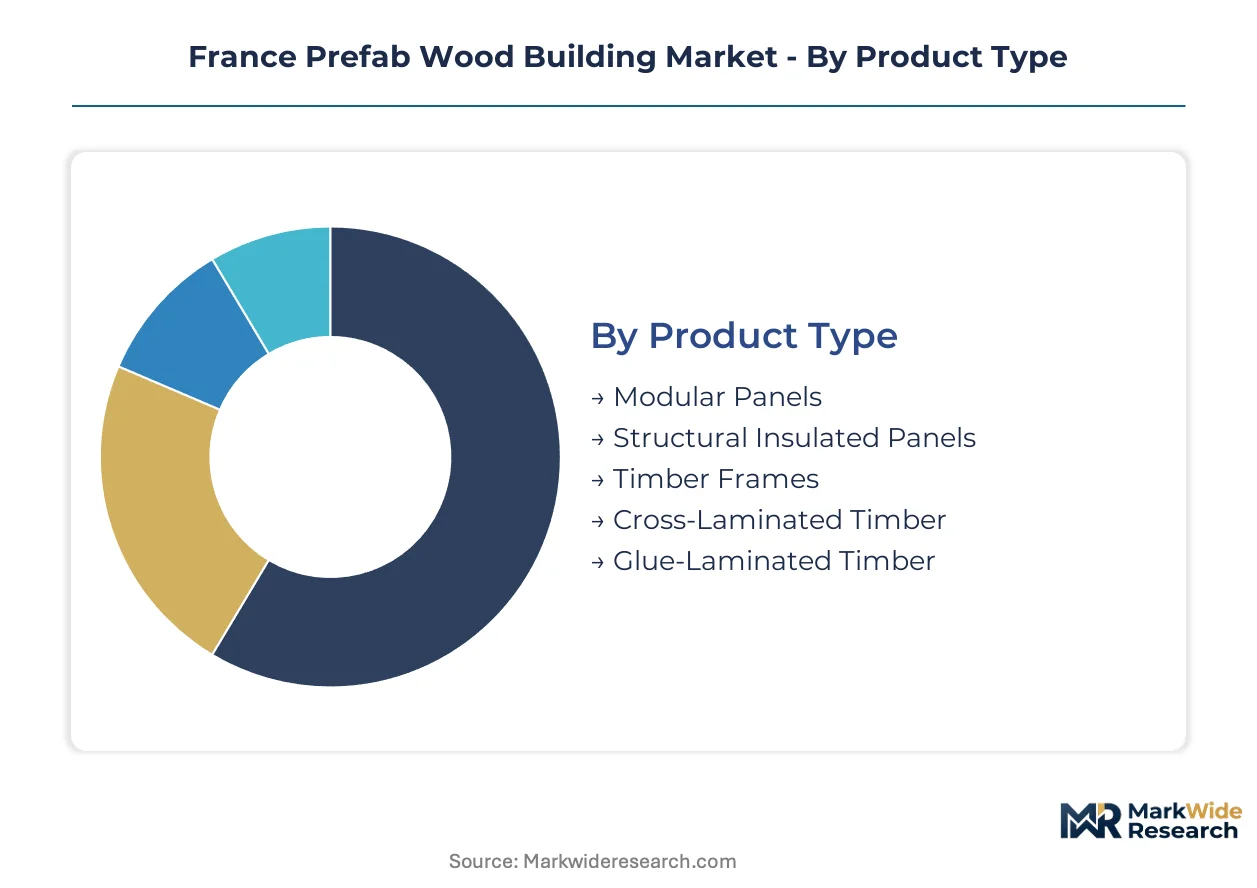
Segmentation in the France prefab wood building market reveals how capital deployment, regulatory compliance, and installation logistics intersect to determine competitive positioning. Manufacturers align production capacity with specific product geometries and construction workflows to capture distinct buyer budgets and project timelines.
Product Type:
Capital intensity varies sharply across engineered wood formats, with automated CLT presses requiring the heaviest upfront investment while timber frame operations sustain lower fixed-asset thresholds.
- Cross-Laminated Timber:Orthogonally bonded lumber layers create monolithic structural slabs rated for five-story commercial spans. Regional hospital authorities in Île-de-France specify CLT for exposed ceiling aesthetics combined with RE2020 carbon compliance.
- Modular Panels:Factory-integrated insulation and utility channels accelerate on-site closure for residential developers facing compressed construction seasons. Demand concentrates in Auvergne-Rhône-Alpes where alpine tourism operators require weather-independent installation.
- Structural Insulated Panels:Rigid foam cores laminated between oriented strand board skins deliver thermal performance for low-rise rural housing.
- Timber Frames:Post-and-beam configurations serve bespoke alpine chalet markets with traditional joinery aesthetics.
- Glue-Laminated Timber:Curved and straight laminated members span long commercial roof profiles in Occitanie educational facilities.
Most installed capacity flows through modular panels. Expansion is steepest in cross-laminated timber as mid-rise urban infill projects multiply.
Construction Type:
Project scale and regulatory scrutiny create divergent margin profiles, with hospitality structures commanding premium pricing for rapid deployment while residential housing sustains volume throughput.
- Residential Housing:Single-family and multi-family configurations dominate unit volume as RE2020 thresholds eliminate concrete alternatives. Social housing developers in the Paris region specify prefabricated timber for cost-certain delivery schedules.
- Hospitality Structures:Seasonal eco-lodges and alpine hotels require factory-finished modules deployable within compressed booking windows. Brittany coastal corridors present underdeveloped supply for sustainable tourism certification schemes.
- Commercial Complexes:Retail and mixed-use developments in urban cores adopt CLT for exposed structural expression.
- Educational Facilities:Regional university estate departments mandate timber systems for new buildings exceeding 1,000 square meters under public procurement directives.
- Office Buildings:Corporate headquarters in Lyon and Grenoble specify engineered wood for employee wellness branding and carbon accounting disclosures.
Residential housing absorbs the majority of production volume. Hospitality structures are gaining share fastest as seasonal tourism investment accelerates.
End User:
Procurement sophistication determines specification authority, with property developers consolidating material choice while contractors retain installation methodology control.
- Property Developers:Balance-sheet investors in social and market-rate housing drive standardized panel specifications to minimize variation cost. Design-build contracting concentrates decision authority with this segment.
- Construction Contractors:Crane-equipped assembly specialists influence panel dimensioning for transport and lifting logistics. Alpine contractors in Haute-Savoie coordinate factory production cycles with mountain access windows.
- Architectural Firms:Specify exposed timber aesthetics and lifecycle carbon performance for institutional clients.
- Engineering Consultants:Perform structural verification and fire engineering for complex CLT spans.
- Government Agencies:Regional hospital authorities and university estate departments mandate timber procurement thresholds.
Property developers channel the largest contract values. Construction contractors are expanding their specification influence through design-build procurement adoption.
Installation Method:
Site labor requirements and weather exposure dictate method selection, with factory completion minimizing on-site crew size while hybrid approaches retain local subcontractor relationships.
- Factory Assembled Units:Volumetric modules with finished interiors deploy to hospitality sites with minimal site preparation. Auvergne-Rhône-Alpes seasonal operators favor this method for opening-date certainty.
- Panelized Systems:Flat-packed wall and floor components enable crane-assisted assembly for mid-rise residential infill. Urban sites in dense Paris departments benefit from reduced laydown area requirements.
- On-Site Assembly:Traditional timber frame raising persists in rural custom home markets with established charpentier networks.
- Hybrid Installation:Combines factory structural panels with site-finished interiors for cost optimization.
- Prefabricated Modules:Bathroom and kitchen pods integrate MEP systems prior to crane placement.
Panelized systems account for the greatest installed square footage. Factory assembled units are climbing the fastest as hospitality investment intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's prefab wood building industry traces its modern lineage to post-war reconstruction programs that established factory-based timber housing as a scalable alternative to masonry construction. Regional specialization now clusters around distinct demand drivers, from alpine tourism infrastructure to metropolitan infill housing.
Auvergne-Rhône-Alpes
Seasonal hospitality developers and urban infill projects converge in this alpine corridor. The region's municipal planning authorities have relaxed timber height restrictions in resort zones, enabling five-story CLT structures. Grenoble-based engineering consultancies coordinate factory production cycles with mountain access windows for crane-dependent assembly.
Île-de-France
Social housing developers in the Paris metropolitan area specify prefabricated timber for cost-certain delivery schedules on compressed urban sites. The Ministry of Ecological Transition's RE2020 carbon thresholds eliminate concrete alternatives for public buildings exceeding 1,000 square meters. Saint-Denis and Montreuil host emerging panel fabrication facilities serving the capital's peripheral communes.
Brittany
Sustainable tourism certification schemes drive demand for modular eco-lodges along the Côtes-d'Armor and Finistère coastlines. MaPrimeRénov' subsidies extend to structural timber extensions atop existing housing stock. Quimper and Brest harbor underdeveloped supply capacity relative to incoming hospitality investment.
Occitanie
Regional university estate departments mandate timber structural systems for new educational facilities under public procurement directives. Toulouse and Montpellier concentrate design-build contractors specializing in exposed CLT aesthetics. The region's moderate seismic classification permits engineered timber lateral load resistance in most zones.
Provence-Alpes-Côte d'Azur
Corporate wellness branding and carbon accounting disclosures elevate engineered wood specifications for headquarters in Lyon and Grenoble satellite offices. The region's planning authorities maintain stricter timber height limits in dense coastal departments, fragmenting addressable commercial pipelines. Nice and Marseille see limited hospitality prefabrication relative to alpine corridors.
France Prefab Wood Building Market Competitive Landscape
Premium-margin players sit above commodity-margin players across customization depth and factory automation intensity. The vendor base clusters into three tiers: national retail networks anchoring standardized residential volume, industrialized construction groups operating dedicated offsite facilities, and bespoke timber frame specialists serving premium alpine deployments. Consolidation pressure runs through design-build procurement adoption, which concentrates contract authority with fewer developer-facing entities. Capacity expansion and backward integration into Nordic spruce supply chains represent the dominant competitive moves.
Among French-based fabricators, Maisons Pierre exemplifies the national retail network archetype through standardized residential configurations. Bouygues Construction occupies the industrialized manufacturing tier with dedicated offsite production scale. LCC Maisons Bois represents the bespoke specialist position, anchoring premium timber frame supply for alpine and rural deployments where traditional joinery aesthetics command price premiums.
| Leading Market Players |
|---|
| Batipin |
| Macoretz Scop |
| Maisons Pierre |
| Bouygues Construction |
| Legoupil Industrie |
| LCC Maisons Bois |
| Martin Calais |
| Chalets Bayrou |
| Les Maisons de Manon |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap timber frame specialists anchor France's prefab wood building supply base, linking generational sawmill relationships to disciplined project pricing that resists commodity volatility. Their concentrated ownership structures reinforce long-term Nordic spruce supply contracts, insulating delivered costs from Baltic Sea shipping disruptions while maintaining margin stability across RE2020-compliant product tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the France prefab wood building market by certification grade and customization depth. Premium tier commands valuation for exposed CLT aesthetics and RE2020 lifecycle carbon documentation, while standard residential panels compete on volume throughput to social housing developers. Price erosion runs through the economy tier as commoditized timber frames face substitution pressure from light-gauge steel in seismic zones. Property developers exhibit highest price sensitivity, whereas alpine hospitality operators absorb premiums for rapid-deployment factory assembled units.
Supply Chain Analysis
Structural-grade laminated timber supply rests on Swedish and Finnish sawmill capacity, with French fabricators drawing from Baltic Sea ports for Nordic spruce feedstock. Cross-laminated timber production hinges on specialized adhesive formulations and automated press equipment concentrated in Central European manufacturing clusters. Single-source vulnerability persists in exterior-grade biocide treatments governed by ECHA oversight, creating regulatory chokepoints for facade applications. Distribution runs through design-build contractors who coordinate factory production cycles with crane-equipped assembly teams across Auvergne-Rhône-Alpes and Île-de-France project sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's prefab wood building market functions as a geographic-arbitrage play between Nordic raw material costs and domestic RE2020 regulatory premiums, capturing margin spreads unavailable to pure import-dependent competitors.
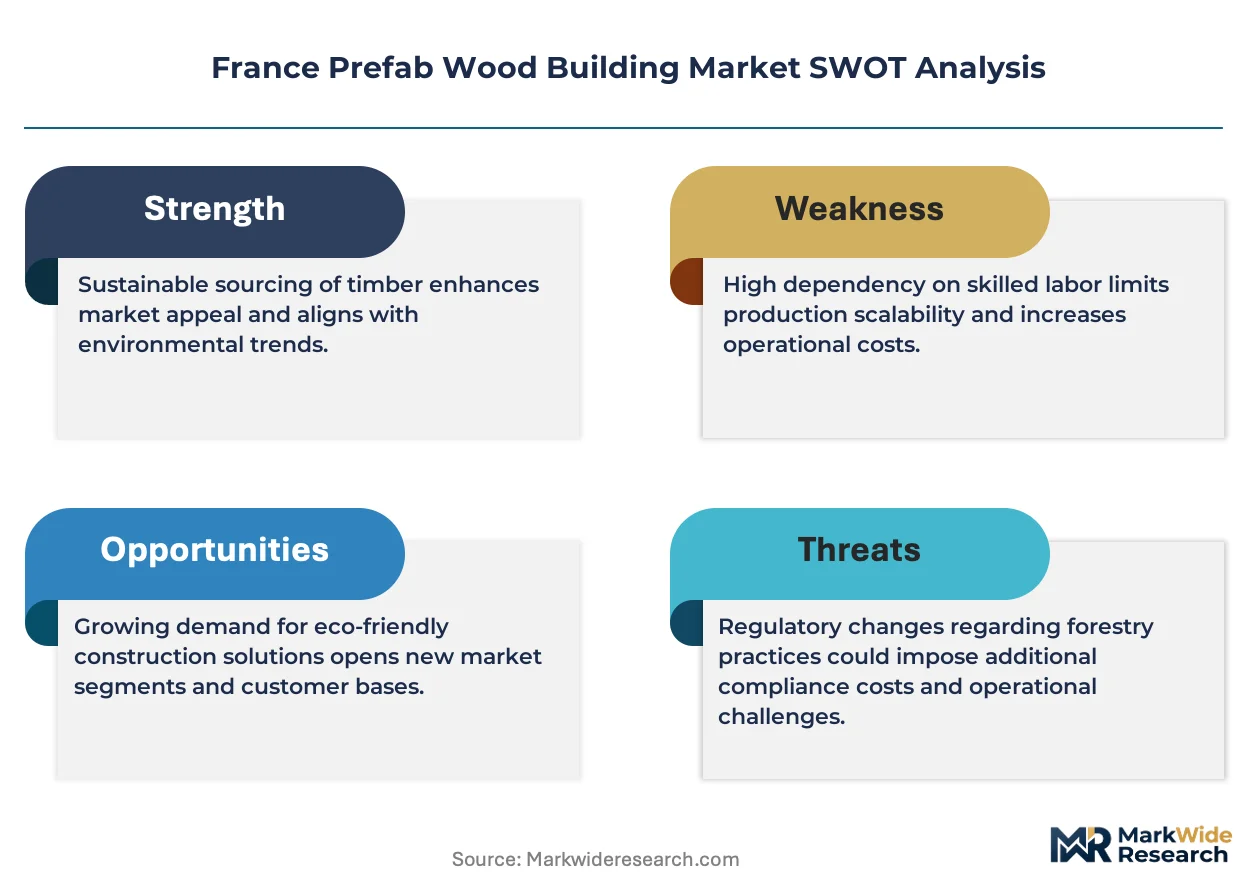
For Market Incumbents: Lock in backward integration into Nordic spruce supply chains through long-term offtake agreements with Swedish and Finnish sawmill cooperatives, defending against Baltic Sea logistics disruptions that threaten production continuity. Anchor capacity expansion in Saint-Denis and Montreuil panel fabrication facilities to capture Île-de-France social housing procurement concentration, while investing in BIM-to-CNC data pipeline certification to differentiate on design-to-delivery compression. For New Entrants and Emerging Players: Direct-to-developer digital platforms offer lowest-friction entry into underpenetrated Brittany coastal hospitality corridors, bypassing established distributor relationships that dominate alpine markets. Target Côtes-d'Armor and Finistère eco-lodge developers seeking MaPrimeRénov'-eligible structural timber extensions, leveraging factory-finished modular units to compress installation timelines against conventional on-site construction. For Investors and Strategic Acquirers: Valuations sit cheapest among regional panel fabricators lacking CLT press capacity but possessing established municipal planning relationships in timber-height-permissive zones. Five-to-ten year viability hinges on RE2020 carbon threshold enforcement durability and Nordic spruce supply contract renewal cycles. Monitor municipal plans d'urbanisme amendments in dense departments as the critical inflection signal for addressable commercial pipeline expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nordic Spruce Supply | Long-term offtake agreements with Swedish and Finnish sawmill cooperatives secure structural-grade feedstock against Baltic shipping volatility. |
| BIM-to-CNC Data Pipeline Deployment | Direct architectural model-to-cutting table integration compresses design-to-delivery timelines for RE2020-compliant projects. |
| Design-Build Procurement Specialization | Single-source factory production and on-site assembly responsibility reduces interface risk for compressed hospitality construction schedules. |
| MaPrimeRénov' Channel Development | National renovation subsidy scheme integration unlocks structural timber extension demand atop existing concrete housing stock. |
| Alpine Height Restriction Advocacy | Municipal planning engagement in Auvergne-Rhône-Alpes resort zones expands addressable five-story CLT commercial pipelines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with timber frame fabricators, CLT press operators, design-build contractors, RE2020 compliance consultants, and regional hospital procurement officers with secondary validation. Bottom-up triangulation incorporated French Ministry of Ecological Transition RE2020 regulatory filings, EU Construction Products Regulation CE marking databases, Nordic sawmill export statistics, and municipal plans d'urbanisme documentation across target departments. Top-down cross-checks anchored volume estimates against social housing agency procurement disclosures and alpine tourism investment filings.
Historical reference periods established baseline penetration rates for engineered wood systems against concrete and steel alternatives, with projection horizons extending across the analysis window. Segmentation modeling incorporated product type, construction category, end-user procurement sophistication, and installation methodology dimensions. CAGRs derived from regression analysis of factory capacity expansion announcements, RE2020 threshold compliance cost curves, and seasonal hospitality construction cycle patterns. Industry-specific forecast inputs included Nordic spruce supply contract renewal schedules and municipal timber height limit amendment pipelines.
The model assumes a particular technology adoption path; alternative pathways for cross-laminated timber fire engineering certification would alter the outlook for mid-rise commercial penetration. Forecasts reflect embedded assumptions regarding RE2020 enforcement continuity, Baltic Sea shipping lane stability, and charpentier traditionnel workforce scaling feasibility. ECHA biocide regulatory amendments, Nordic sawmill capacity reallocation, and municipal zoning permissiveness shifts warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Dominican Republic Construction Market
Building Construction
Egypt Construction Market
Building Construction
Latin America Construction Market
Building Construction
Middle East Data Center Construction Market
Building Construction
India Pre-Engineered Buildings Market
Building Construction
Saudi Arabia Construction Market
Building Construction
Germany Prefabricated Buildings Market
Building Construction
GCC Construction Market
Building Construction
Saudi Arabia Infrastructure Sector Market
Building Construction
Bangladesh Construction Market
Building Construction
Spain Prefabricated Buildings Market
Building Construction
Precast Construction Market
Building Construction
France Prefab Homes Market
Building Construction
Europe Modular Construction Market
Building Construction
GCC Cement Market
Building Construction
Vertical Garden Construction Market