
 ASEAN Prefab Wood Buildings Market | 2026-2036
ASEAN Prefab Wood Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Prefab Wood Buildings Market Outlook
Malaysian engineered timber producers is decoupling from conventional sawn lumber supply chains by investing in cross-laminated timber capacity near Johor Bahru. DTH Prefab leverages its vertical integration across design-to-assembly workflows to capture recurring commercial contracts. Tran Duc Homes anchors its position through deep distribution networks in Vietnamese urban corridors. Thaweephan Wood Products Co Ltd differentiates via specialized teak and hardwood prefabrication for premium residential segments.
ASEAN prefab wood buildings are factory-manufactured structural systems using engineered wood products such as cross-laminated timber, glulam, and mass plywood panels, assembled through precision-cut joinery or steel-wood hybrid connections for rapid on-site erection. These systems serve commercial and institutional clients seeking reduced construction duration and lower embodied carbon footprints compared to conventional concrete or steel framing. Panelized systems currently occupy the largest production volume share due to lower capital barriers for regional fabricators, while modular construction commands premium margins in Singapore and Bangkok where labor constraints elevate off-site value. Cross-laminated timber technology leads growth trajectory as fire-rated and seismic-certified CLT gains code acceptance across multiple ASEAN jurisdictions.
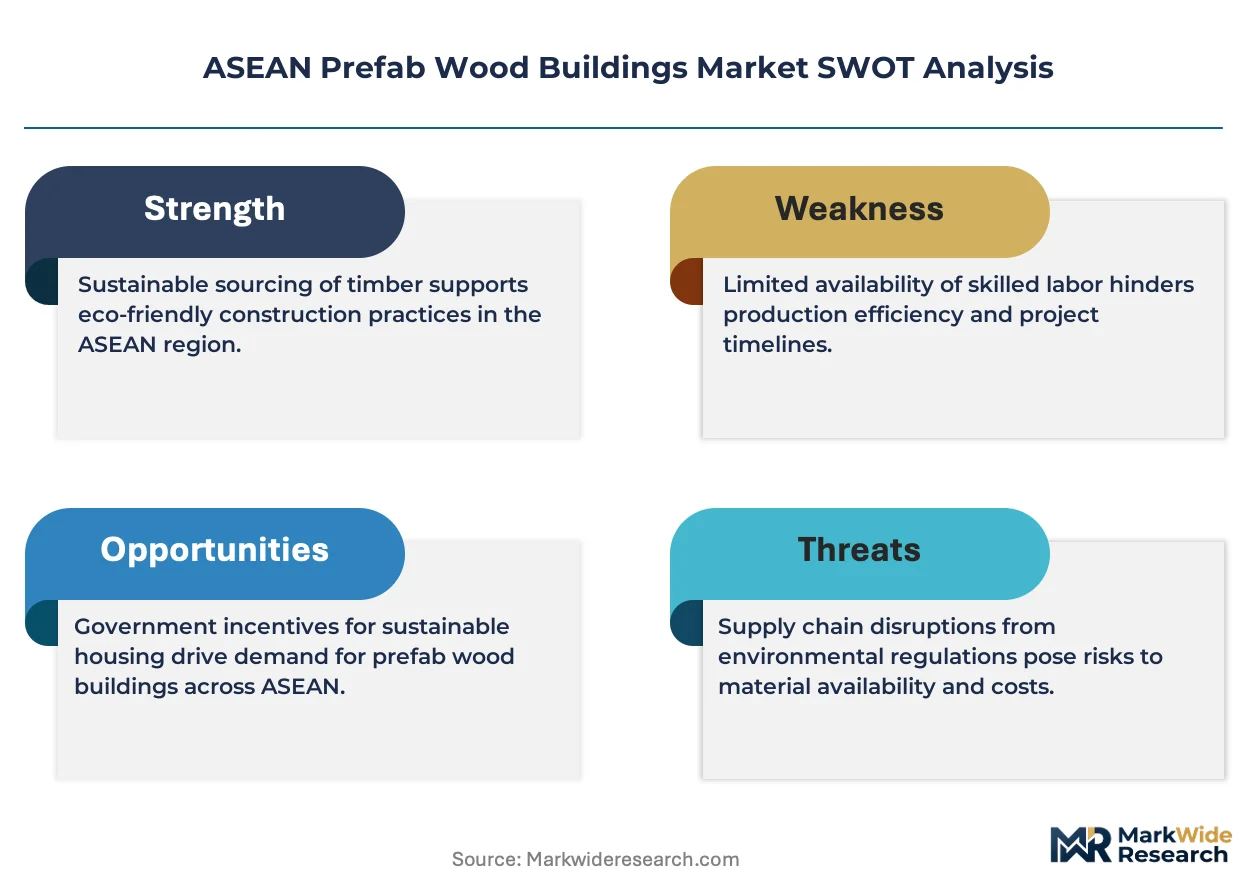
Malaysia's Uniform Building By-Laws, Singapore's Building and Construction Authority Green Mark, and Indonesia's SNI standards for structural timber collectively shape material certification requirements and market access conditions for prefab wood suppliers. Compliance with these frameworks determines eligibility for government tenders and green financing instruments in each national market. Stakeholders must monitor evolving fire safety amendments and mass timber height restrictions as urban density pressures test regulatory boundaries across Southeast Asian capitals.
Market Dynamics
Engineered timber certification and cross-laminated timber fire-rating approvals are compressing project approval timelines across Southeast Asian jurisdictions, reconfiguring developer procurement priorities toward factory-verified structural systems.
Growth Catalysts
- Malaysia's Uniform Building By-Laws:Green certification mandates accelerate engineered timber adoption in commercial construction, creating compliance-driven demand for prefabricated structural systems.
- Hospitality developers:Thailand and Indonesia resort operators expand modular construction to compress project delivery timelines amid tourism infrastructure expansion.
- Cross-laminated timber:Fire-rated and seismic-certified CLT gains code acceptance across multiple ASEAN jurisdictions, unlocking mid-rise commercial applications previously restricted to concrete.
Market Restraints
- Adhesive resin cost volatility:Phenol-formaldehyde and polyurethane binder prices fluctuate with petrochemical feedstock markets, squeezing mass timber panel margins.
- Vietnamese manufacturing concentration:Central coastal provinces dominate regional CLT component supply, creating geographic single-point vulnerability for ASEAN project timelines.
- Mass timber height restrictions:Bangkok and Singapore building codes cap engineered timber structures below steel-concrete hybrid alternatives, limiting addressable high-rise market share.
Strategic Opportunities
- Philippine archipelago logistics:Island geography and port infrastructure constraints favor prefabricated panel systems over bulk concrete supply chains for remote resort and institutional projects.
- Singapore Green Mark incentives:BCA certification tiers reward embodied carbon reduction, positioning mass timber for premium commercial tender eligibility.
- Hybrid steel-timber connections:Convergence of precision CNC joinery with structural steel bracket systems enables taller hybrid structures within existing code frameworks.
Industry Challenges
- Mass timber engineering expertise:Structural designers with CLT-specific fire and seismic modeling capabilities remain concentrated in Singapore and Kuala Lumpur, creating project bottlenecks for regional developers.
- Factory certification timelines:JAS and EN 14080 equivalency testing for ASEAN fabricators extends 12-18 months, delaying export market access for Vietnamese and Indonesian producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Prefab Wood Buildings Market |
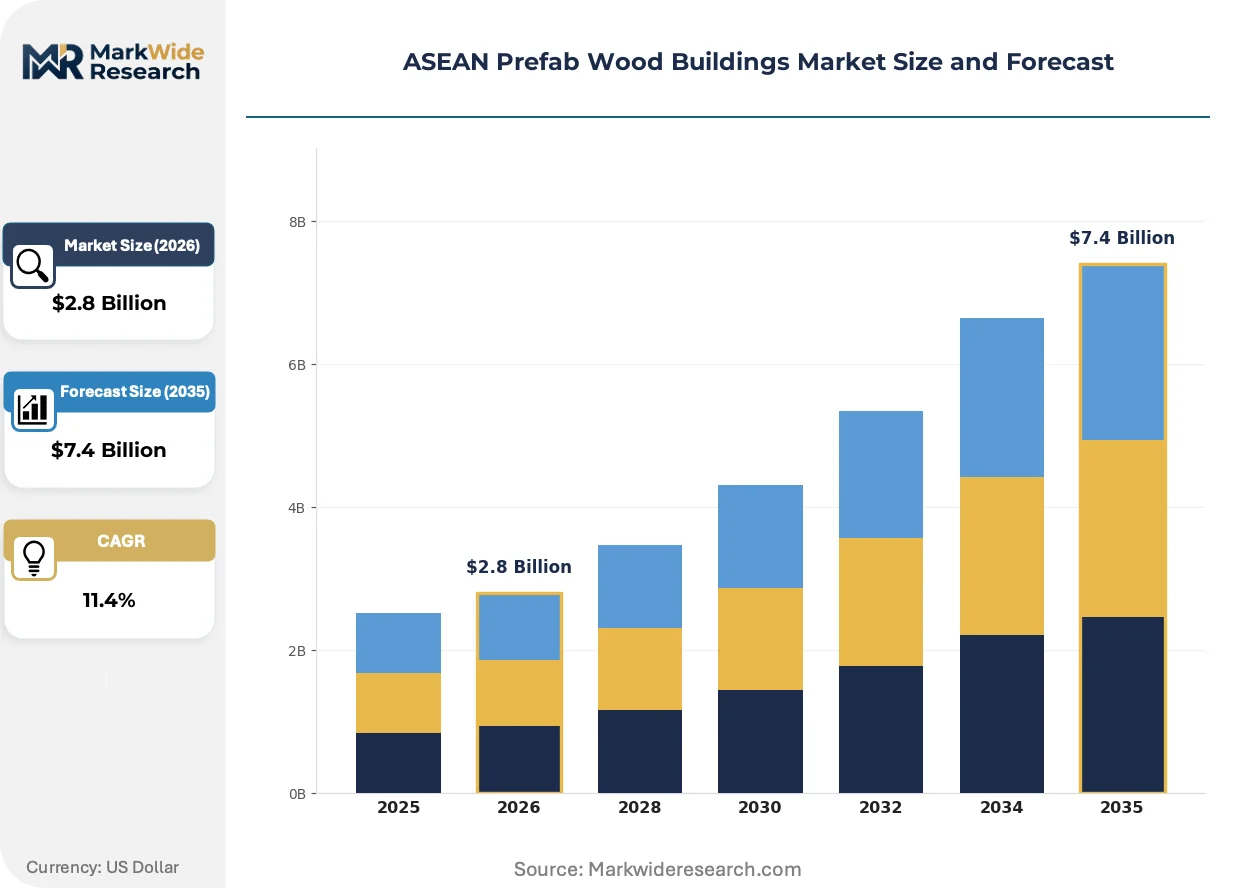
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular, Panelized, Prefabricated, Hybrid End Use: Residential, Commercial, Institutional, Industrial Technology: Green Building, Traditional Frame, Cross-Laminated Timber, Timber Frame Assembly Method: On-Site, Off-Site, Pre-Engineered, Modular Construction |
| Companies Covered | DTH Prefab, AMD Modular, Tran Duc Homes, Karmod Prefabricated Technologies, Laras Bali Prefab, Thaweephan Wood Products Co Ltd, PT Teak Bali, A Fold Houses, Palmatin, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Prefab Wood Buildings Market Strategic Shifts
Digital fabrication workflows and automated CNC cutting are collapsing traditional design-to-assembly lead times, while regulatory harmonization efforts across ASEAN jurisdictions create new standardization pressures for material certification.
Cross-laminated timber is expanding into mid-rise commercial and hospitality verticals as fire-rated panel systems achieve multi-jurisdiction code acceptance. Thai and Indonesian resort developers adopt CLT primary structures to compress foundation-to-enclosure schedules by 40% versus conventional concrete. This technology is expanding into Singapore's commercial office segment, where labor constraints and carbon disclosure mandates elevate off-site fabrication value.
Indonesia's SNI structural timber standards and Malaysia's Uniform Building By-Laws amendments are converging on ISO 16670 testing protocols for engineered wood connections. This regulatory alignment reduces duplicate certification burdens for regional fabricators supplying multi-country project portfolios. Vietnamese CLT producers targeting Thai hospitality contracts now navigate unified performance benchmarks rather than country-specific test regimes.
Developer procurement teams now mandate embodied carbon disclosure and EPD documentation prior to structural system tender participation, displacing price-only evaluation frameworks. This specification shift elevates certified mass timber against conventional concrete in Singapore and Bangkok commercial tenders. Indonesian state-owned hospitality developers have adopted this procurement model for 2026-2028 pipeline projects.
ASEAN Prefab Wood Buildings Market Segmentation
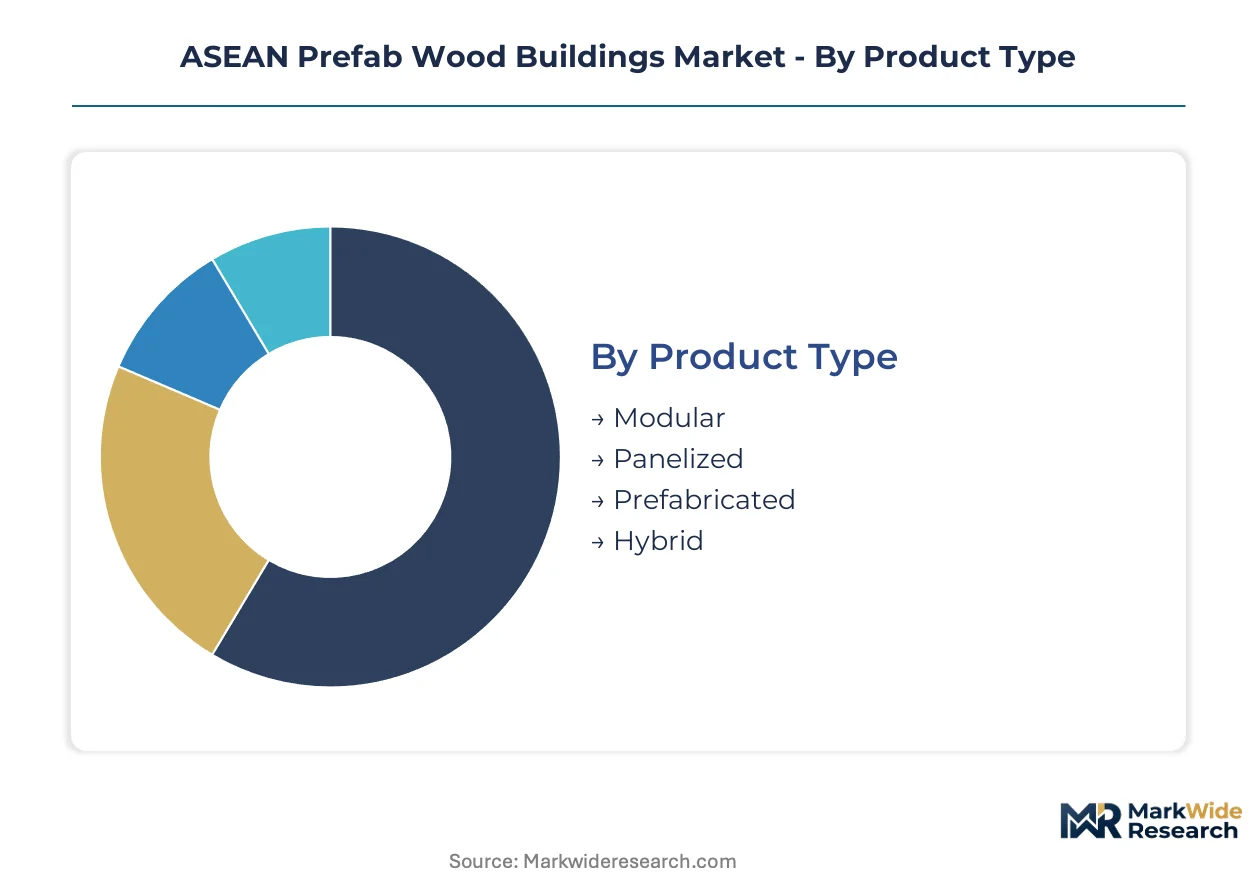
Prefab wood building configurations in Southeast Asia diverge sharply in capital requirements, factory footprints, and labor substitution economics. Understanding these structural differences clarifies why Vietnamese fabricators dominate panelized output while Singaporean developers pay premiums for modular systems.
Product Type:
Capital intensity separates these four structural approaches, with modular systems demanding the heaviest upfront factory investment and panelized methods offering lower barriers to entry for regional fabricators.
- Modular:Complete volumetric units factory-finished with MEP systems installed prior to transport. Singapore and Bangkok developers absorb 30-40% cost premiums to circumvent skilled labor shortages and accelerate enclosure schedules. Most installed capacity flows through Panelized systems. Expansion is steepest in Modular construction.
- Panelized:Flat wall, floor, and roof components shipped for field assembly using precision-cut joinery. Vietnamese central coastal clusters supply cross-laminated timber panels regionally, compressing foundation-to-dry-in timelines by 25% versus conventional framing.
- Prefabricated:Pre-cut dimensional lumber packages with hardware kits for stick-built assembly on site. Indonesian and Philippine resort projects favor this approach for remote island locations where full module transport faces port infrastructure constraints.
- Hybrid:Steel-wood composite systems combining CLT floor plates with steel moment frames. Thai hospitality developers deploy these for mid-rise structures exceeding pure timber height limits while maintaining carbon disclosure advantages.
Panelized systems absorb the majority of regional production volume due to replicable factory economics. Modular construction gains share fastest where labor scarcity and green certification premiums concentrate.
End Use:
Customer procurement sophistication varies dramatically across these four verticals, with institutional buyers demanding ISO-compliant documentation and residential segments prioritizing cost-per-square-meter metrics.
- Residential:Single-family and multi-family housing employing mass timber for primary structure or infill panels. Malaysian green building mandates accelerate engineered timber adoption in Kuala Lumpur and Johor Bahru corridor developments.
- Commercial:Office, retail, and hospitality structures where Singapore Green Mark tiers reward embodied carbon reduction. Bangkok commercial tenders increasingly require EPD documentation prior to structural system evaluation.
- Institutional:Schools, healthcare facilities, and government buildings with extended lifecycle requirements. Indonesian state-owned hospitality developers have adopted carbon-disclosure procurement models for pipeline projects.
- Industrial:Warehousing and light manufacturing facilities prioritizing rapid enclosure and column-free spans. This segment trails others in mass timber penetration due to fire insurance rating complexities.
Commercial applications command the highest certified timber premiums. Institutional procurement is formalizing fastest through government tender standardization.
Technology:
Engineering complexity and code acceptance timelines differentiate these four construction methodologies, with newer mass timber systems facing extended certification periods.
- Green Building:Systems designed for net-zero operational carbon with integrated passive design elements. Singapore BCA certification tiers position these for premium tender eligibility.
- Traditional Frame:Platform and balloon framing using dimensional lumber and plywood sheathing. Philippine and Indonesian rural construction still relies heavily on this lowest-cost approach.
- Cross-Laminated Timber:Orthogonally layered solid wood panels achieving fire-rated and seismic-certified performance. Thai and Indonesian resort developers adopt CLT primary structures to compress foundation-to-enclosure schedules by 40% versus concrete.
- Timber Frame:Post-and-beam systems with infill panels, historically dominant in temperate climates. ASEAN adoption concentrates in premium residential segments seeking aesthetic differentiation.
Traditional frame retains volume leadership across price-sensitive markets. Cross-laminated timber is climbing the fastest as multi-jurisdiction code acceptance expands.
Assembly Method:
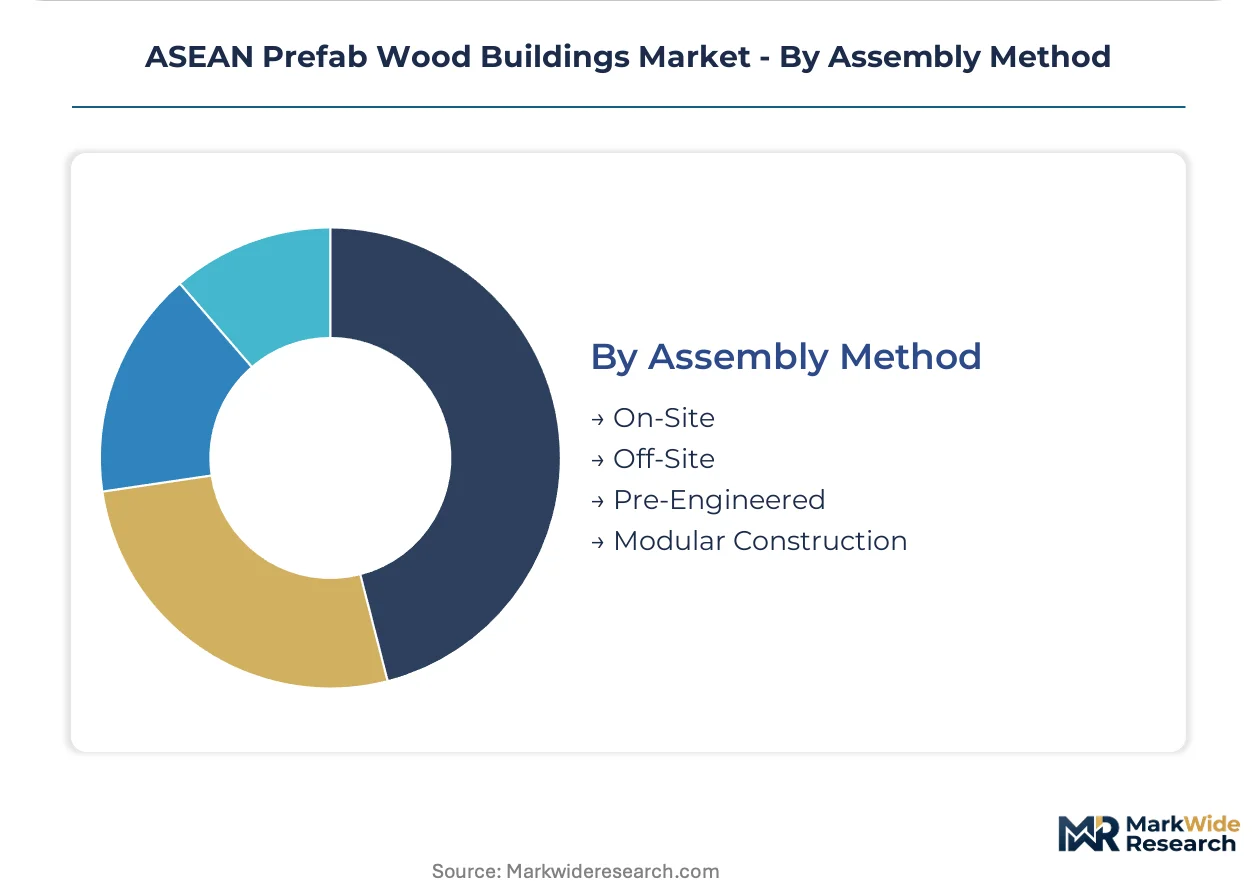
Site labor substitution rates and logistics coordination intensity separate these four delivery models, with fully off-site approaches requiring precise scheduling integration.
- On-Site:Component delivery for field assembly using conventional construction labor. Vietnamese and Indonesian projects in remote provinces default to this method where factory infrastructure is absent.
- Off-Site:Factory-controlled production environments minimizing weather delays and quality variance. Malaysian Uniform Building By-Laws amendments favor these systems through streamlined inspection protocols.
- Pre-Engineered:Design-to-fabrication workflows with CNC-cut connections and embedded hardware. Thai hospitality developers leverage these for compressed project timelines amid tourism infrastructure expansion.
- Modular Construction:Volumetric units complete with finishes, tested and certified prior to transport. Singapore labor constraints elevate off-site fabrication value for commercial office developments.
On-site assembly still dominates regional project counts. Off-site production is gaining share fastest where regulatory harmonization reduces duplicate certification burdens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage drives production migration across ASEAN, with Vietnamese fabricators capturing cost-of-compliance advantages while Malaysian and Singaporean markets absorb premium-certified products. Engineered timber capacity concentrates where fire-rating approval timelines diverge most sharply.
Singapore
Building and Construction Authority Green Mark tiers reward embodied carbon reduction, positioning mass timber for premium commercial tender eligibility. Labor constraints elevate off-site fabrication value for commercial office developments. The city-state's dense urban core hosts specialized engineering consultancies for CLT-specific fire and seismic modeling.
Malaysia
Uniform Building By-Laws amendments accelerate engineered timber adoption in Kuala Lumpur and Johor Bahru corridor developments. Green certification mandates create compliance-driven demand for prefabricated structural systems. Johor Bahru anchors cross-laminated timber capacity investments decoupling from conventional sawn lumber supply chains.
Thailand
Hospitality developers expand modular resort construction to compress project delivery timelines amid tourism infrastructure expansion. Thai resort operators adopt CLT primary structures to reduce foundation-to-enclosure schedules versus conventional concrete. Bangkok building codes cap engineered timber structures below steel-concrete hybrid alternatives.
Indonesia
SNI structural timber standards converge on ISO 16670 testing protocols for engineered wood connections, reducing duplicate certification burdens. State-owned hospitality developers have adopted carbon-disclosure procurement models for pipeline projects. Resort projects in remote island locations favor pre-cut dimensional lumber packages where full module transport faces port infrastructure constraints.
Vietnam
Central coastal provinces dominate regional CLT component supply, creating manufacturing clusters that export cross-laminated timber panels across ASEAN. Factory certification timelines for JAS and EN 14080 equivalency testing extend 12-18 months, delaying export market access. Deep distribution networks in Vietnamese urban corridors anchor domestic market penetration.
ASEAN Prefab Wood Buildings Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialized teak and hardwood prefabrication for premium residential segments. The market structures around three strategic archetypes: vertically integrated design-to-assembly operators, regional panel fabricators leveraging central coastal manufacturing clusters, and specialized hardwood finishers targeting resort hospitality. Capacity expansion and regulatory certification investments constitute the dominant competitive moves as fabricators seek multi-jurisdiction code acceptance.
Among Vietnam-based fabricators, Tran Duc Homes anchors positions through distribution network depth, while DTH Prefab exemplifies vertical integration across design-to-assembly workflows. Thaweephan Wood Products Co Ltd occupies a specialist tier focused on premium hardwood segments. These three represent distinct archetype positions: scale-driven regional supply, integrated service delivery, and material-specialist differentiation.
| Leading Market Players |
|---|
| DTH Prefab |
| AMD Modular |
| Tran Duc Homes |
| Karmod Prefabricated Technologies |
| Laras Bali Prefab |
| Thaweephan Wood Products Co Ltd |
| PT Teak Bali |
| A Fold Houses |
| Palmatin |
| Others |
Value Chain & Pricing Dynamics
Singapore's Building and Construction Authority Green Mark tiers gate qualified supply access and premium-tier pricing eligibility, compressing margins for uncertified fabricators while rewarding code-compliant mass timber producers with tender participation rights and green financing access across ASEAN commercial construction.
Pricing Analysis
Distributor margins in Vietnamese central coastal manufacturing clusters absorb 12-18% of delivered panel costs before regional resale. Pricing stratifies across certified mass timber, factory-verified engineered lumber, and conventional sawn timber tiers. Price differentiation rests on fire-rating certification grade and embodied carbon disclosure completeness. Cost compression in standard-grade panel supply is intensifying because phenol-formaldehyde resin feedstock volatility squeezes mass timber fabricator margins. Institutional buyers in Singapore and Bangkok demonstrate lowest price sensitivity, while Philippine island resort developers exhibit highest cost-per-square-meter scrutiny.
Supply Chain Analysis
Regional distribution centers in Ho Chi Minh City, Johor Bahru, and Bangkok anchor hub-and-spoke patterns for CLT panel delivery across ASEAN hospitality and commercial corridors. Manufacturing gravity centers on Vietnam, Malaysia, and Indonesia for engineered timber component fabrication. Raw material flows draw from tropical hardwood plantations in Indonesia, rubberwood estates in southern Thailand, and imported European spruce for cross-laminated timber core layers. Supply chain risk concentrates in single-source phenol-formaldehyde resin dependence on Northeast Asian petrochemical suppliers. Distribution runs through project-direct bulk shipment contracts for modular units and consolidated container loads for panelized systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASEAN prefab wood buildings constitute a late-cycle quality story as developer procurement shifts toward embodied carbon disclosure and EPD documentation prior to structural system tender participation.
For Market Incumbents: Anchor market position through captive cross-laminated timber capacity additions near Johor Bahru and accelerated JAS equivalency certification for Vietnamese export access. Defensive consolidation should prioritize backward integration into tropical hardwood plantation supply and fire-rating testing laboratory partnerships to neutralize emerging Indonesian SNI-certified competitors. Certification investment represents the critical lever for maintaining tender eligibility as Bangkok and Singapore heighten green procurement mandates. For New Entrants and Emerging Players: The premium-to-economy tier price gap in Philippine archipelago logistics opens white-space targeting for pre-cut dimensional lumber packages serving remote island resort projects. Penetrable segments include Indonesian state-owned hospitality developments adopting carbon-disclosure procurement models and Vietnamese central coastal manufacturing clusters seeking EN 14080 equivalency testing partnerships. A go-to-market angle through precision CNC joinery subcontracting for established panel fabricators accelerates technical credibility without heavy factory capital deployment. For Investors and Strategic Acquirers: Valuations sit cheapest among regional panel fabricators with incomplete multi-jurisdiction certification portfolios yet established distribution networks in Vietnamese urban corridors. Long-term viability across the five-to-ten year window favors vertically integrated design-to-assembly operators with demonstrated CLT fire and seismic modeling capabilities. The acquisition target archetype encompasses Malaysian engineered timber producers decoupling from conventional sawn lumber supply chains. The signal to watch is regulatory harmonization momentum across ASEAN jurisdictions converging on ISO 16670 testing protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Laminated Timber Capacity Expansion | Johor Bahru manufacturing investments capture Malaysian Uniform Building By-Laws compliance-driven demand acceleration. |
| Multi-Jurisdiction Certification Investment | JAS and EN 14080 equivalency testing unlocks export market access for Vietnamese central coastal producers. |
| Backward Integration into Plantation Supply | Indonesian tropical hardwood estate control secures raw material cost stability for premium resort segment positioning. |
| Hybrid Steel-Timber Connection Development | Precision CNC joinery convergence with structural steel brackets enables taller structures within Bangkok height restrictions. |
| Carbon Disclosure Documentation Standardization | EPD certification positions mass timber for Singapore Green Mark premium commercial tender eligibility. |
Study Parameters
Bottom-up commercial and hospitality end-use modeling reconciled against top-down engineered timber capacity tracking forms the analytical core of this study. Primary interviews with hospitality development executives, structural engineering consultants, prefabrication plant managers, and green building certification officers were validated against secondary sources including ASEAN national building code amendments, SNI structural timber standard filings, Malaysian Uniform Building By-Laws documentation, and Singapore BCA Green Mark certification databases. Triangulation between supply-side factory output estimates and demand-side project pipeline aggregation ensures cross-validation of volume assumptions.
Historical trendline analysis of panelized and modular system adoption rates across Thailand, Indonesia, Malaysia, Singapore, Vietnam, and the Philippines established baseline penetration trajectories. The forecast framework segments by product type, end-use vertical, construction technology, and assembly method, with growth trajectories derived from regulatory milestone timing and code acceptance expansion patterns. Industry-specific inputs include fire-rating approval timelines across ASEAN jurisdictions and labor cost compression differentials between on-site and off-site construction.
Caveats apply where adhesive resin cost volatility, mass timber height restriction amendments, or factory certification timeline extensions could materially shift the outlook. Forecasts reflect documented assumptions around regulatory harmonization momentum and green procurement mandate enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
United Kingdom Data Center Construction Market
Building Construction
India Commercial Construction Market
Building Construction
Saudi Arabia Prefabricated Buildings Market
Building Construction
Saudi Arabia Construction Market
Building Construction
Germany Prefab Wood Buildings Market
Building Construction
Eastern Europe Construction Market
Building Construction
India Prefabricated Buildings Market
Building Construction
Indonesia Commercial Construction Market
Building Construction
Germany Prefabricated Buildings Market
Building Construction
Europe 3D Printing Construction Market
Building Construction
UAE Facade Market
Building Construction
GCC Cement Market
Building Construction
UAE Construction Market
Building Construction
Turkey Commercial Construction Market
Building Construction
US Modular Construction Market
Building Construction
Oman Construction Market