
 India Pipe Fabrication Market | 2026-2036
India Pipe Fabrication Market Size, Share, and Industry Trends Forecast 2026-2036
India Pipe Fabrication Market Insights
BIS IS 1239 certification for mild steel tubes is collapsing the vendor pool to qualified fabricators. APL Apollo Tubes Limited leverages its nationwide distribution network to dominate retail and project sales. Jindal SAW Ltd. anchors large-diameter orders through integrated steelmaking and coating capabilities. Ratnamani Metals & Tubes Limited specializes in stainless and alloy deliveries for corrosive service environments.
Pipe fabrication encompasses the cutting, bending, welding, and assembly of metallic and non-metallic tubular products into spools, supports, and fitting assemblies for fluid conveyance systems. Fabricators typically work with carbon steel, alloy grades, and PVC compositions, applying SMAW, GMAW, or automated orbital welding to meet pressure ratings from 150 to 2500 psi. Spool prefabrication leads output volumes due to modular construction trends in refineries and power plants. Carbon steel maintains the widest application footprint across oil and gas transmission networks. Water treatment utilities now specify PVC and corrosion-resistant alloy supports for chemical resistance in coastal installations.
BIS mandates IS 3589 for water and sewage applications, while the CEA enforces material traceability for thermal power piping. The PLI scheme for specialty steel rewards domestic producers who upgrade to API 5L and ASTM-compliant pipe mills. Stakeholders must monitor how BIS harmonization with ISO 3183 affects import competitiveness and domestic capacity allocation across western and southern industrial corridors.
Market Dynamics
BIS certification tightening for steel pipes is consolidating India's vendor pool toward qualified fabricators with testing infrastructure. This regulatory compression is reshaping competitive positioning across Gujarat's petrochemical corridor and Maharashtra's industrial zones.
Growth Catalysts
- PLI Scheme for Specialty Steel:Domestic producers upgrading to API 5L and ASTM-compliant pipe mills receive production-linked incentives, accelerating capacity modernization.
- Western India Pipeline Projects:Oil and gas transmission networks across Gujarat and Rajasthan drive demand for large-diameter carbon steel fabrication.
- Modular Refinery Construction:Spool prefabrication for refineries and power plants is displacing field welding, shortening project timelines.
Market Restraints
- Alloy Input Cost Volatility:Nickel and molybdenum price swings compress margins for stainless and corrosion-resistant alloy pipe fabricators.
- Import Dependency for High-Grade Coils:Domestic mills lack consistent supply of API 5L X70+ grades, forcing reliance on Japanese and Korean suppliers.
- BIS-ISO Harmonization Friction:Transition delays between IS 3589 and ISO 3183 standards create certification backlogs for water and sewage contractors.
Strategic Opportunities
- Southern Industrial Corridor Underpenetration:Tamil Nadu and Andhra Pradesh chemical processing zones lack localized stainless fabrication capacity.
- CEA Thermal Power Material Traceability Mandate:New documentation requirements for high-pressure boiler piping favor domestic fabricators with integrated metallurgical testing.
- Orbital Welding-NDT Convergence:Automated welding paired with real-time radiography is enabling offshore platform spool production for Mumbai High contractors.
Industry Challenges
- Certified Welder Shortage:SMAW and GMAW specialists with pressure vessel qualifications remain scarce across western Indian fabrication yards.
- Coating Facility Capex Burden:FBE and 3LPE anti-corrosion lines require capital outlays that mid-tier fabricators struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Pipe Fabrication Market |
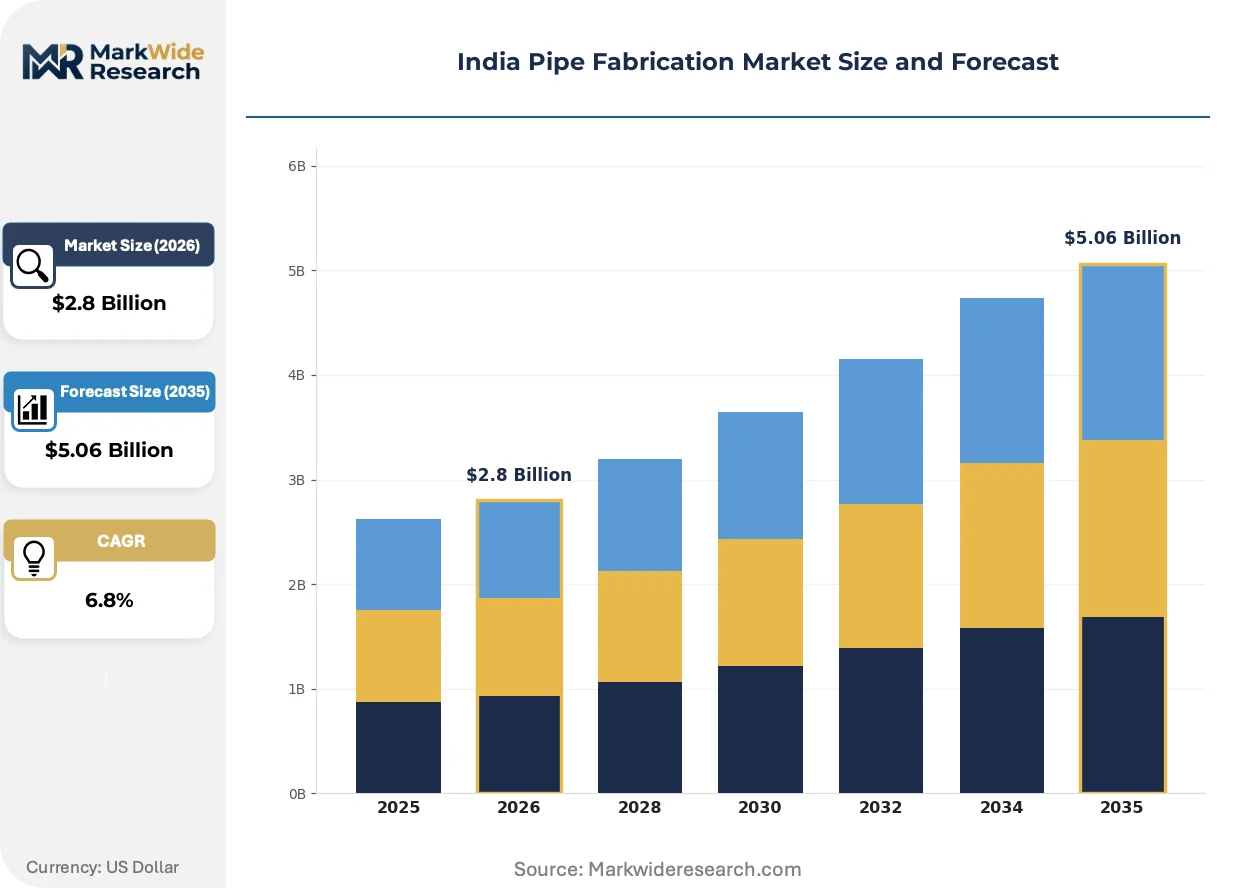
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.06 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spools, Joints, Fittings, Supports Material: Steel, PVC, Carbon Steel, Alloy Application: Oil & Gas, Power Generation, Water Treatment, Construction End User: Construction Firms, Energy Sector, Municipalities, Industrial Plants |
| Companies Covered | APL Apollo Tubes Limited, Jindal SAW Ltd., Ratnamani Metals & Tubes Limited, Finolex Industries Ltd., Tata Steel Limited, Maharashtra Seamless Ltd, Surya Roshni Limited, JSW Steel Limited, Hitech Pipes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Pipe Fabrication Market Trends and Innovations
Digital thread integration across design-to-fabrication workflows is compressing engineering cycles. Automation is displacing manual processes in high-specification segments.
Automated orbital welding systems for high-pressure alloy piping are miniaturizing field deployment footprints. Offshore platform contractors in Mumbai High are adopting portable units for subsea spool repairs. This capability compression is enabling same-day turnaround on critical path interventions that previously required shore-based facilities.
BIS harmonization with ISO 3183 for line pipe standards is tightening import competitiveness rules. Domestic mills must upgrade testing protocols to maintain market access. Water transmission projects in Maharashtra and Gujarat now specify dual-certified material, forcing fabricators to requalify supplier bases.
Engineering-procurement-construction firms are consolidating vendor panels to tier-one certified fabricators. Mid-tier players without BIS IS 1239 or IS 3589 accreditation are losing refinery and power plant access. This concentration is most visible in Hazira and Vadodara industrial clusters, where project owners now mandate third-party inspection witnessing.
India Pipe Fabrication Market Segmentation
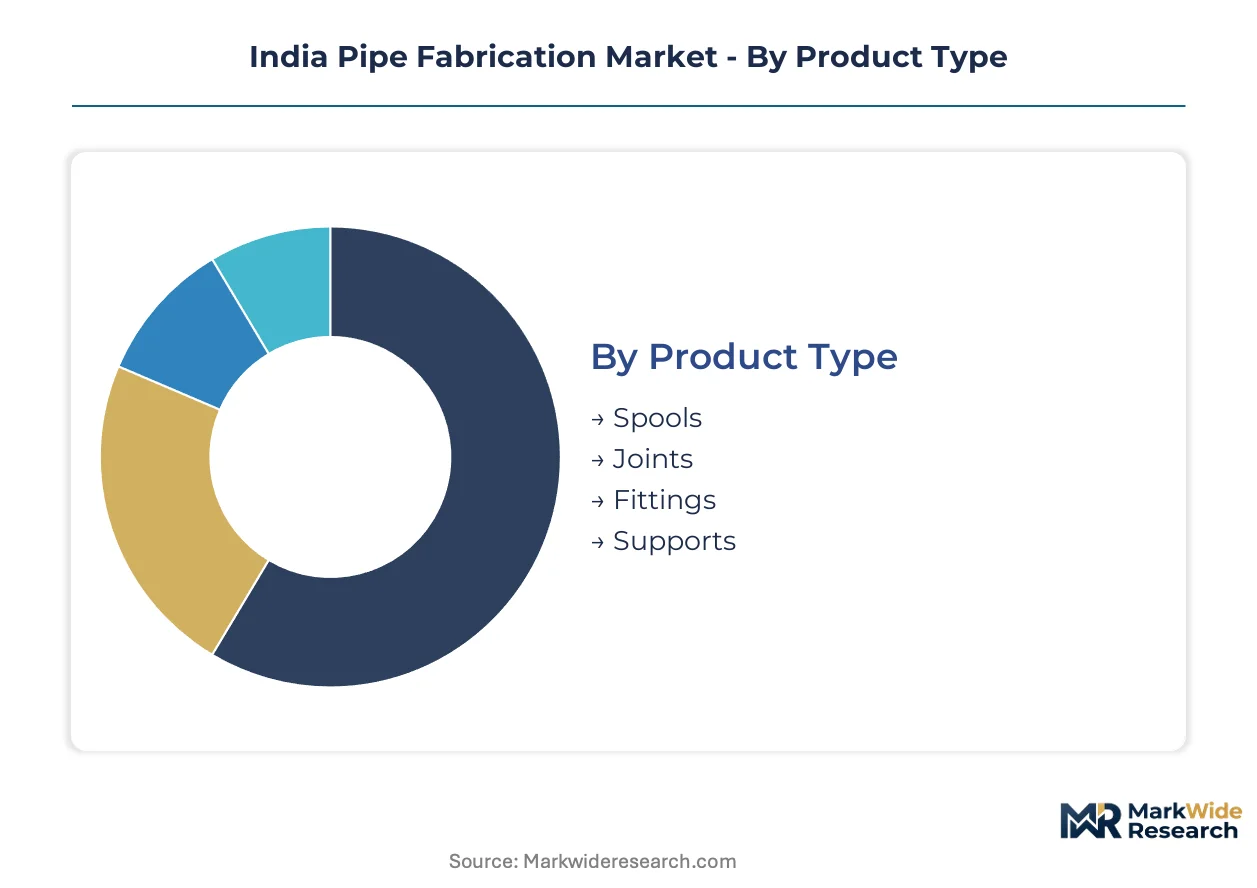
Segmentation in India's pipe fabrication market reveals how fabrication capabilities align with project complexity and regulatory tiers. Material certifications and end-use pressure ratings determine which fabricators capture specific contract categories across western and southern industrial corridors.
Product Type:
Channel distribution varies sharply by product complexity—spools and joints flow through EPC contractor panels, while fittings and supports reach end-users via distributor networks and direct mill relationships.
- Spools:Prefabricated pipe assemblies with welded flanges and valves, produced in 6-12 meter modular sections for refinery and power plant installation. Demand clusters in Gujarat's petrochemical corridor where Reliance Industries and IOCL execute large turnaround projects. PLI scheme incentives for domestic specialty steel production are accelerating spool fabrication capacity upgrades.
- Joints:Connection assemblies including weld neck, slip-on, and blind configurations rated for 150-2500 psi service. Maharashtra's industrial zones drive specification intensity as MIDC-registered chemical processors mandate BIS IS 1239 compliance for all pressure-boundary connections.
- Fittings:Elbows, tees, and reducers in carbon and alloy grades for directional flow control. Stocking distributors in Ahmedabad and Vadodara maintain inventory for maintenance-repair-operations procurement.
- Supports:Structural hangers, guides, and anchors for thermal expansion management. Coastal water treatment utilities in Tamil Nadu specify PVC-coated supports for chemical resistance.
Spools dominate installed base. Joints is where expansion concentrates.
Material:
Cost tier stratification separates commodity carbon grades from premium alloy specifications, with certification requirements acting as the primary price differentiator across project categories.
- Steel:Mild steel tubes under BIS IS 1239 for general structural and low-pressure applications. Construction firms in tier-2 cities source through APL Apollo's retail network for building services plumbing.
- Carbon Steel:API 5L grades for oil and gas transmission with standardized weldability. Western India pipeline projects across Rajasthan and Gujarat absorb the majority of domestic X52-X70 production.
- Alloy:Stainless and nickel-chrome-molybdenum compositions for corrosive service above 400°C. Ratnamani Metals anchors this segment through integrated metallurgical testing for CEA thermal power mandates.
- PVC:Thermoplastic piping for chemical drainage and potable water distribution. Municipalities in coastal Maharashtra specify uPVC for sewerage schemes under AMRUT funding.
Carbon steel captures volume leadership. Alloy commands margin expansion.
Application:
Geographic concentration of end-use industries creates distinct demand pockets—oil and gas in the west, power generation across central coal belts, water treatment in coastal urban agglomerations.
- Oil & Gas:Cross-country pipelines, gathering systems, and refinery process piping requiring 100% radiographic inspection. HPCL's Visakh refinery expansion and Gujarat State Petronet's city gas distribution rollout sustain fabrication demand.
- Power Generation:High-pressure boiler tubing and steam piping under CEA material traceability rules. NTPC's ultra-supercritical projects in Telangana and Madhya Pradesh specify domestic alloy fabrication.
- Water Treatment:Transmission mains and sewage force mains under BIS IS 3589. Maharashtra's Jal Jeevan Mission implementation drives ductile iron and mild steel pipe orders.
- Construction:Building services plumbing and fire suppression systems. Real estate developers in Bangalore and Hyderabad procure ISI-marked GI pipes through organized retail channels.
Oil and gas anchors revenue concentration. Water treatment is climbing the fastest.
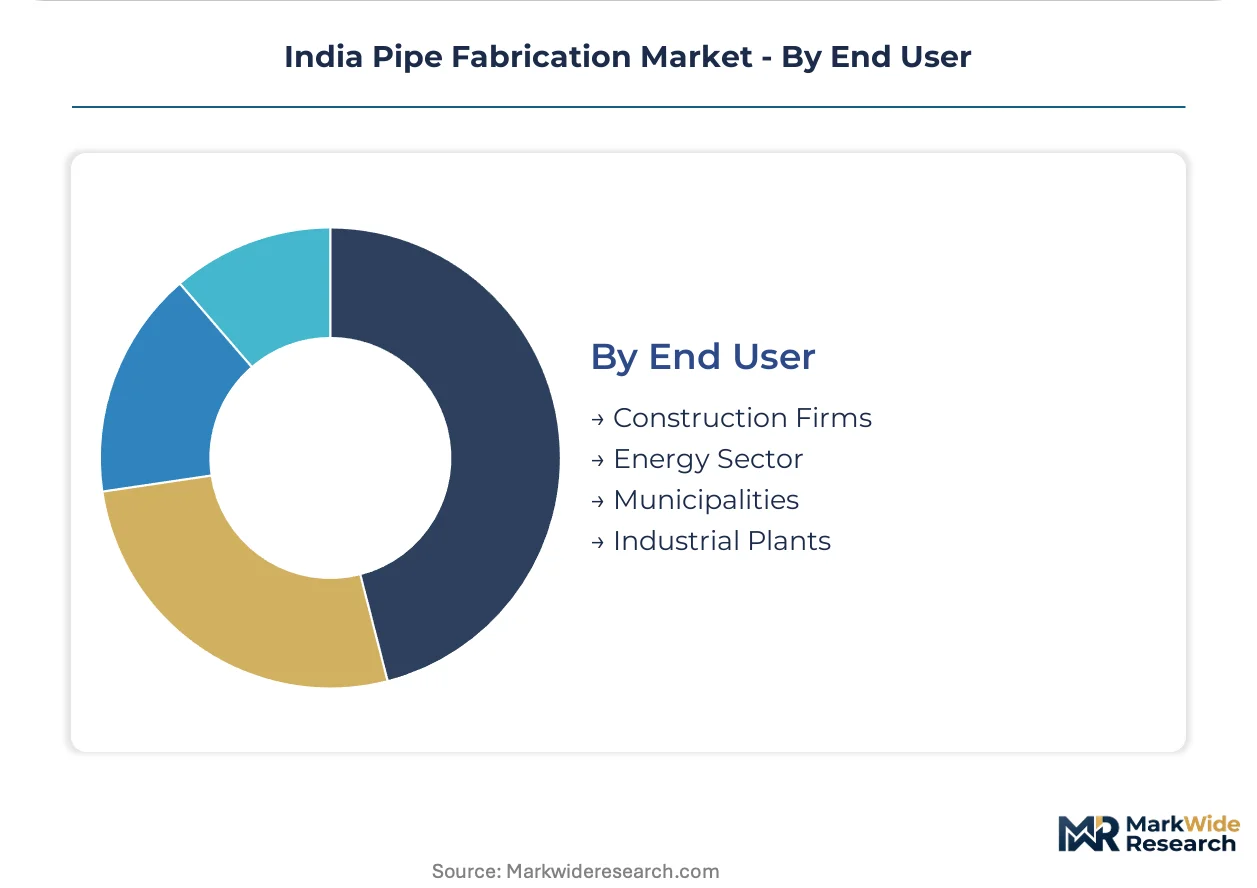
End User:
Procurement sophistication varies by buyer type—energy sector entities mandate integrated testing, while municipalities prioritize lowest-compliant-bid mechanisms that fragment supplier relationships.
- Energy Sector:IOCL, BPCL, ONGC, and private LNG terminal operators with qualification requirements for API Q1 and ISO 9001. Vendor panel consolidation favors tier-one fabricators with in-house NDT capabilities.
- Industrial Plants:Chemical processors and fertilizer manufacturers in Haldia, Paradip, and Hazira. Corrosion-resistant alloy demand concentrates here due to acid service environments.
- Construction Firms:Real estate developers and infrastructure contractors procuring standard grades through distributor networks. Price sensitivity drives spot purchasing behavior.
- Municipalities:Urban local bodies executing water supply and sewerage projects under central government missions. Bidding thresholds often exclude specialized fabricators lacking prior government contract experience.
Energy sector dominates specification intensity. Industrial plants is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Hazira-Vadodara pipeline corridor anchors western India's fabrication concentration. Gujarat State Petronet's cross-country transmission networks and Reliance Industries' refinery expansions sustain demand for large-diameter spool production.
Gujarat
The Dahej petrochemical belt and Hazira industrial cluster absorb the majority of domestic API 5L-grade fabrication. CEA material traceability mandates for thermal power piping favor fabricators with integrated metallurgical testing facilities in Surat and Vadodara. The PLI scheme for specialty steel accelerates capacity upgrades across Bharuch district.
Maharashtra
Mumbai's city gas distribution rollout and MIDC-registered chemical processors in Thane-Pune corridor drive specification intensity. BIS IS 1239 compliance requirements for pressure-boundary connections consolidate procurement toward qualified vendors. Nagpur's emerging steel fabrication zone attracts backward-integrated producers seeking logistics advantages for central India projects.
Tamil Nadu
The Manali-Ennore petrochemical corridor and Chennai's port-linked industrial estates generate stainless steel demand for corrosive service environments. Coastal water treatment utilities specify PVC-coated supports under AMRUT funding guidelines. Fabrication capacity gaps in Tiruchirappalli and Coimbatore create procurement bottlenecks for chemical processors.
Telangana
NTPC's ultra-supercritical power projects in the Godavari belt specify domestic alloy fabrication with full material documentation. The Hyderabad-Warangal industrial corridor attracts EPC contractors seeking localized spool suppliers for refinery maintenance. State infrastructure missions prioritize BIS-certified vendors for water transmission mains.
Rajasthan
HPCL's Barmer refinery expansion and Indradhanush gas grid extensions sustain demand for X70-grade line pipe. Jodhpur-Jaipur industrial clusters host mid-tier fabricators serving oilfield service contractors. BIS-ISO 3183 harmonization delays create certification backlogs for water transmission contractors in Udaipur and Kota districts.
India Pipe Fabrication Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and material grades. The vendor pool compresses toward BIS-accredited fabricators with in-house NDT capabilities, eliminating unqualified competitors from refinery and power plant panels. Three archetypes dominate: integrated steelmakers with captive pipe mills, standalone fabricators with coating infrastructure, and distributors controlling retail channels. Capacity expansion and vendor panel consolidation represent the primary competitive moves.
Among listed entities, APL Apollo Tubes Limited exemplifies the distributor-integrated archetype with nationwide retail penetration. Jindal SAW Ltd. occupies a position within the integrated steelmaker tier, anchoring large-diameter orders through captive production. Ratnamani Metals & Tubes Limited represents the specialty fabricator archetype, concentrating on corrosion-resistant alloys for demanding service environments.
| Leading Market Players |
|---|
| APL Apollo Tubes Limited |
| Jindal SAW Ltd. |
| Ratnamani Metals & Tubes Limited |
| Finolex Industries Ltd. |
| Tata Steel Limited |
| Maharashtra Seamless Ltd |
| Surya Roshni Limited |
| JSW Steel Limited |
| Hitech Pipes |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Gujarat's petrochemical majors and Hazira-based fabricators lock in both API 5L-grade coil supply and price visibility across 12-18 month project cycles. These arrangements insulate tier-one vendors from nickel and molybdenum volatility while compressing spot-market access for mid-tier competitors lacking BIS accreditation.
Pricing Analysis
Certification level creates the primary spread between BIS IS 1239-accredited fabricators and unqualified competitors. Three-tier pricing structure separates API 5L X70+ premium grades from standard X52 carbon steel and economy mild steel tubes. Cost compression in alloy segments is intensifying because Japanese and Korean coil suppliers command dollar-denominated premiums. Municipal procurement under AMRUT funding shows highest price sensitivity, while NTPC ultra-supercritical projects prioritize traceability documentation over unit economics.
Supply Chain Analysis
Port congestion at Mundra and Hazira elevates inbound logistics costs for Korean X70-grade coil shipments, adding 8-12% to landed input costs. Supply concentrates in Japan, South Korea, and domestic integrated mills at Dolvi and Vijayanagar. The fabrication ecosystem rests on nickel-chrome-molybdenum alloys, FBE coating chemicals, and orbital welding consumables. Single-source vulnerability persists for API 5L X80+ grades where only two overseas mills qualify. Distribution runs through EPC contractor panels for refinery spools and APL Apollo's retail network for construction-grade tubing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's pipe fabrication market is entering a cyclical recovery phase. Western India pipeline projects and PLI-scheme capacity upgrades provide the demand floor for this upswing.
For Market Incumbents: Compound BIS certification advantages by acquiring distressed mid-tier fabricators in Bharuch and Vadodara clusters before ISO 3183 harmonization closes. Integrate in-house NDT capabilities to capture CEA thermal power documentation mandates that exclude third-party-reliant competitors. Defend against Ratnamani's stainless alloy dominance through backward integration into specialty steel melting. For New Entrants and Emerging Players: Differentiate on orbital welding-NDT convergence for Mumbai High offshore contractors seeking same-day turnaround capability. Target Tamil Nadu's underpenetrated chemical processing corridor where Tiruchirappalli and Coimbatore capacity gaps force procurement from distant Gujarat vendors. Lead with portable automated welding units as a service model rather than capital-heavy yard investments. For Investors and Strategic Acquirers: BIS-accredited fabricators with captive coating infrastructure represent the most defensible acquisition archetype as vendor panel consolidation accelerates. Long-term viability hinges on exposure to central government infrastructure missions rather than spot construction demand. Watch HPCL's Barmer refinery expansion timeline as the inflection signal for X70-grade capacity utilization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Steel Melting | Captures PLI scheme incentives while securing alloy supply for CEA-mandated thermal power projects. |
| Orbital Welding-NDT Service Model | Enables Mumbai High contractors to execute subsea repairs without shore-based facility dependency. |
| BIS-ISO 3183 Dual Certification Investment | Preserves market access as Maharashtra water transmission projects specify harmonized standards. |
| Coastal Capacity Expansion in Tamil Nadu | Addresses chemical processor procurement bottlenecks in Manali-Ennore petrochemical corridor. |
| Long-term Supply Agreement with NTPC | Locks in ultra-supercritical boiler piping demand with full material traceability documentation. |
Research Methodology
Cross-validation between EPC contractor procurement data and BIS certification registries anchors the qualitative findings in documented vendor panel compositions. Primary interviews with fabrication yard managers, NTPC project engineers, and Maharashtra municipal procurement officers combined with secondary validation from DGFT import records, CEA thermal power advisories, and PLI scheme disbursement filings. Bottom-up spool production estimates and top-down steel consumption data triangulate market sizing across western and southern industrial corridors.
Sensitivity analysis on nickel price trajectories and BIS-ISO harmonization timelines frames the projection uncertainty. The analytical framework models product type, material grade, application intensity, and end-user procurement sophistication across the analysis window. CAGRs derive from segmented volume builds calibrated to announced refinery expansions, pipeline kilometerage targets, and power plant commissioning schedules. Alloy input cost pass-through assumptions and municipal budget execution rates constitute key industry-specific forecast inputs.
Forecasts assume regulatory continuity in BIS certification regimes and CEA material traceability mandates; material policy shifts would require re-modeling. Alloy price volatility beyond historical bands or PLI scheme suspension would compress margin assumptions for stainless and corrosion-resistant segments. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Europe Industrial Flooring Market
Building & Construction Materials
US Commercial Windows Market
Building & Construction Materials
China Concrete Superplasticizer Market
Building & Construction Materials
Glass Railing System Market
Building & Construction Materials
Global Formwork Market
Building & Construction Materials
India Particle Board Market
Building & Construction Materials
Moisture Resistant Gypsum Board Market
Building & Construction Materials
Global Drywall Textures Market
Building & Construction Materials
Education Building Design Market
Building & Construction Materials
Hollow Concrete Block Market
Building & Construction Materials
China Marble Market
Building & Construction Materials
North America Gutter Guards Market
Building & Construction Materials
Sectional Door Market
Building & Construction Materials
Drywall Compound and Drywall Mud Market
Building & Construction Materials
United States I-Joist Market
Building & Construction Materials
Asphalt Market