
 Infrastructure Sector in Asia Pacific Market | 2026-2036
Infrastructure Sector in Asia Pacific Market Size, Share, and Industry Trends Forecast 2026-2036
Infrastructure Sector in Asia Pacific Market Foresight
Project finance through asset-light concession models is reconfiguring competitive entry barriers across Asia Pacific infrastructure. Samsung C&T leverages its integrated engineering-procurement-construction capability to anchor large-scale transport projects in Southeast Asia. Larsen & Toubro sustains dominance in India's heavy civil segment through captive manufacturing of construction equipment. Hyundai E&C differentiates via specialized nuclear and thermal power plant expertise that commands premium contract terms.
The infrastructure sector in Asia Pacific encompasses the physical systems and facilities enabling economic activity, including transport networks with design lifespans of 50-100 years, utility distribution grids, and social infrastructure requiring seismic resilience ratings of 8.0+ in tectonically active zones. Its primary purpose is reducing logistics costs and connecting population centers to industrial production. Roads and railways absorb the majority of public capital allocation, with railways representing the fastest-growing product type as high-speed corridors proliferate from Indonesia to Vietnam. BIM and smart grid technologies concentrate margin pools by enabling lifecycle cost reductions that traditional construction cannot match.
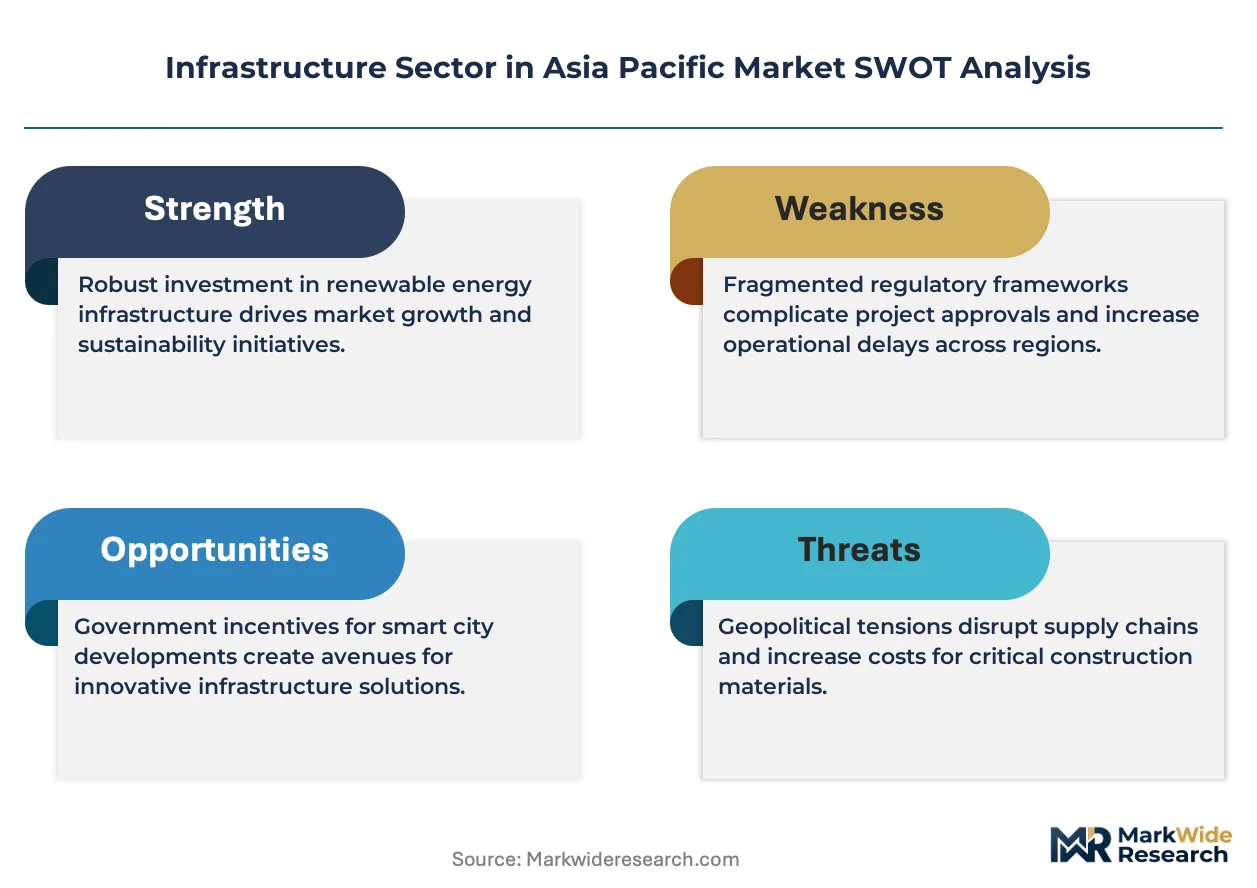
India's CEA mandates grid-code compliance for all new power infrastructure, while China's MEE enforces dual carbon emission benchmarks that reshape material procurement across projects. Japan's METI building energy standards and Australia's Infrastructure Australia assessment frameworks further fragment compliance requirements. Stakeholders must monitor which regulatory jurisdiction's technical standards become the default reference for cross-border project financing.
Market Dynamics
China's dual carbon goals and India's PLI scheme for infrastructure equipment are redirecting capital flows toward green construction technologies, fundamentally reconfiguring procurement priorities across transport and power projects.
Growth Catalysts
- Smart city mandates:Government-led programs across Southeast Asia are accelerating demand for integrated transport networks with embedded sensor infrastructure.
- CEA grid-code compliance:India's Central Electricity Authority mandates are forcing upgrades to power distribution infrastructure, opening equipment replacement cycles.
- Industrial corridor development:Maharashtra and Gujarat are absorbing record steel and cement volumes as western India becomes the continent's densest construction zone.
Market Restraints
- Steel price volatility:Input cost swings of 30-40% within single quarters are compressing EPC margins on fixed-price contracts.
- Seismic rating requirements:Japan's 8.0+ resilience mandates add 15-25% to structural steel tonnage for social infrastructure in tectonically active zones.
- Cement supply concentration:Clinker production clusters in China's coastal provinces create freight cost vulnerability for Southeast Asian projects.
Strategic Opportunities
- Vietnam's high-speed rail gap:The 1,500km north-south corridor remains underpenetrated by foreign EPC consortia despite feasibility completion.
- BIM-lifecycle integration:Building Information Modeling convergence with IoT sensor networks is opening margin pools through predictive maintenance contracts.
- Australia's Infrastructure Australia framework:Mandatory cost-benefit transparency is creating first-mover advantage for contractors with documented asset-performance databases.
Industry Challenges
- BIM technician scarcity:Shortage of certified modelers is delaying design handoffs and inflating pre-construction timelines by 20-30%.
- Legacy grid interoperability:Smart grid deployments face integration friction with 1960s-era switchgear still serving 40% of India's distribution network.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infrastructure Sector in Asia Pacific Market |
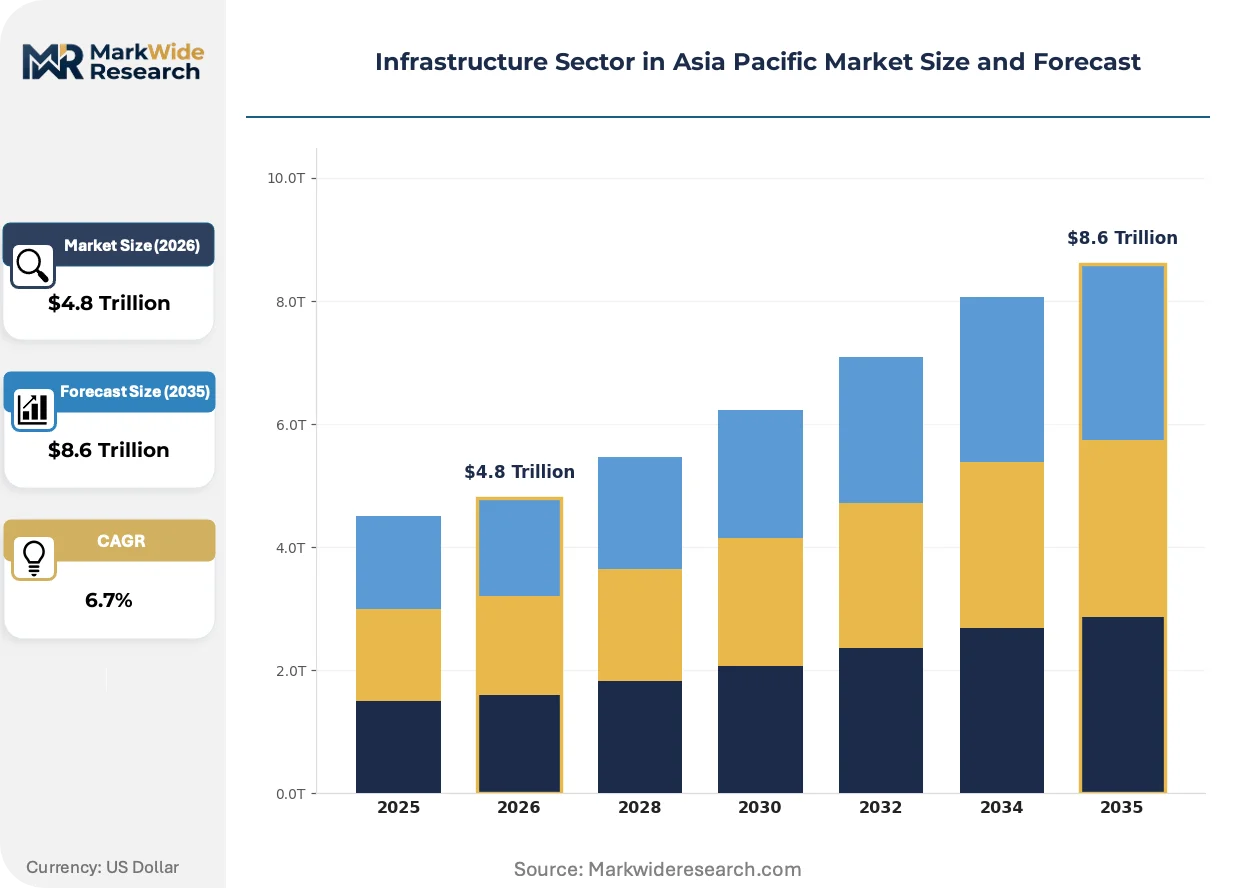
| Market Size in 2026 | $4.8 Trillion |
| Market Size in 2035 | $8.6 Trillion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roads, Bridges, Railways, Airports Service Type: Construction, Maintenance, Consulting, Project Management Technology: BIM, IoT, Drones, Smart Grids End User: Government, Private Sector, NGOs, Utilities |
| Companies Covered | China State Construction Engineering (CSCEC), China Communications Construction Company (CCCC), Power Construction Corporation of China (PowerChina), Samsung C&T, Obayashi Corporation, Hyundai E&C, Larsen & Toubro (L&T), China Railway Group (CREC), China Railway Construction Corporation (CRCC), Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infrastructure Sector in Asia Pacific Market Shifts & Advancements
Digital twin technology and modular construction methods are compressing project delivery timelines while regulatory pressure on embodied carbon is forcing material substitution across the Asia Pacific infrastructure value chain.
Digital twin platforms integrating real-time structural health monitoring with predictive maintenance algorithms are rendering obsolete traditional 5-year fixed-interval inspection regimes for bridges and tunnels. State transport authorities in Japan and South Korea are mandating continuous sensor deployment on new mega-projects. The shift is compressing lifecycle cost models and transferring margin from construction-phase contractors to data-analytics service providers.
China's Ministry of Ecology and Environment enforces dual carbon emission benchmarks that reshape steel and cement procurement across Belt and Road projects. The policy requires embodied carbon disclosure for all imported construction materials on state-financed infrastructure. Contractors are responding by sourcing from electric-arc-furnace steel producers and alternative binder concrete mixes, particularly on Indonesia's new capital city projects.
Asset-light concession models are displacing traditional EPC-own-operate structures as pension funds and infrastructure REITs seek yield without construction risk. Australian and Singaporean institutional investors now dominate toll road and port financing, stripping operational assets from engineering groups. The pattern concentrates most visibly in India's western corridor, where Canadian and Middle Eastern capital funds 60% of greenfield expressway development.
Infrastructure Sector in Asia Pacific Market Segmentation
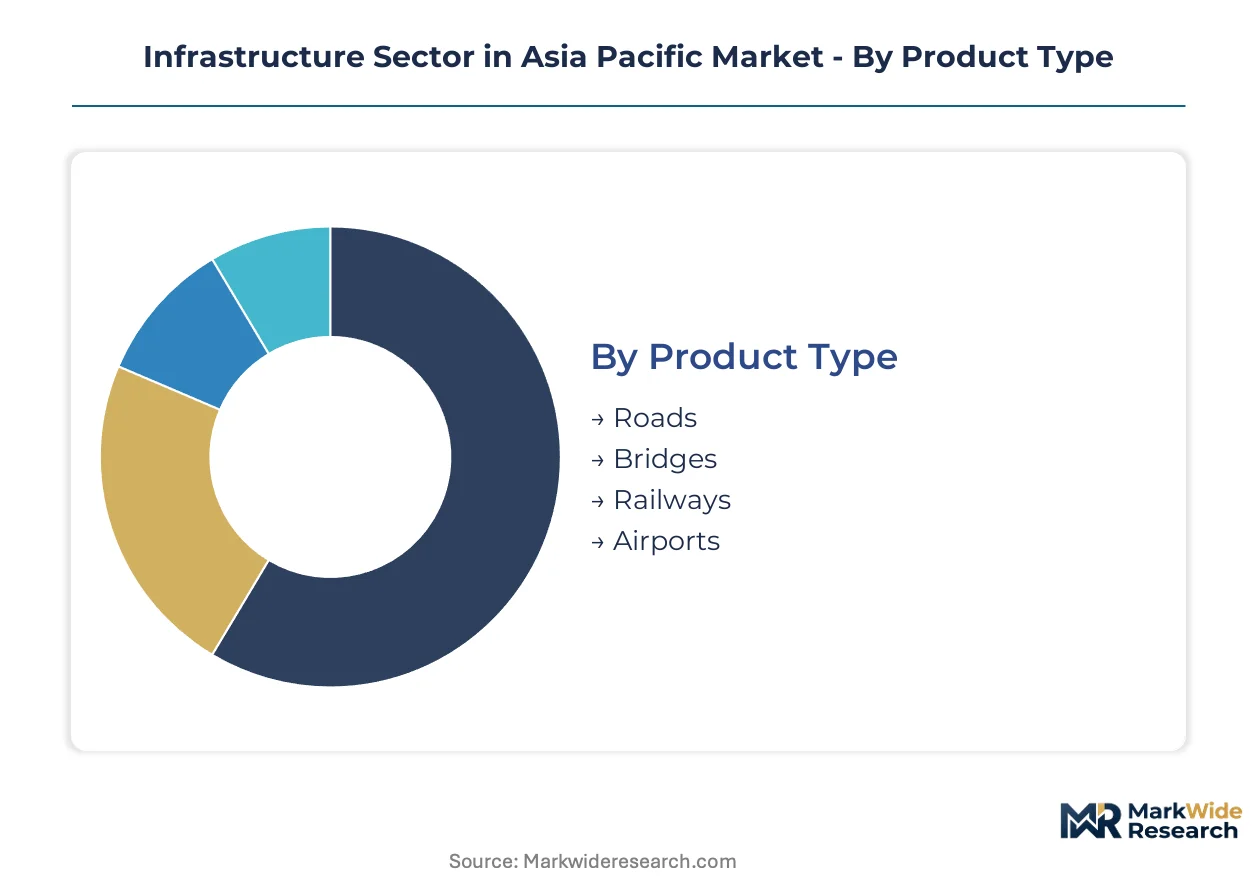
Segmentation in Asia Pacific infrastructure reveals how capital allocation, regulatory pressure, and technological readiness diverge across project types and delivery models. Understanding these fault lines enables stakeholders to match capability investments with where margin pools are forming.
Product Type:
Mature transport assets with 50-100 year design lifespans dominate procurement volumes, while emerging corridor formats are capturing policy attention and pilot funding.
- Roads:Paved surface networks with flexible or rigid pavement designs rated for 20-40 tonne axle loads. Maharashtra and Gujarat's industrial corridors are absorbing record asphalt and concrete volumes as western India becomes the continent's densest construction zone, though land acquisition delays are stretching project timelines.
- Railways:Steel-wheel-on-rail systems including conventional, metro, and high-speed configurations with 1435mm standard gauge or 1676mm broad gauge standards. Vietnam's 1,500km north-south high-speed corridor remains underpenetrated by foreign EPC consortia despite feasibility completion, creating first-mover openings for integrated engineering groups.
- Bridges:Span structures exceeding 20m in length requiring seismic resilience ratings of 8.0+ in Japan and Indonesia's tectonically active zones.
- Airports:Aviation infrastructure with runway pavement classifications from PCN 30 to PCN 90, concentrated in Southeast Asia's tourism-dependent economies and India's secondary city expansion programs.
Roads handle the majority of throughput; railways are expanding most quickly on share as high-speed corridors proliferate from Indonesia to Vietnam.
Service Type:
Contract structures are splitting along risk allocation lines, with asset-heavy construction giving way to lifecycle service models that transfer operational exposure to specialized operators.
- Construction:Greenfield and brownfield physical asset delivery encompassing earthworks, structural erection, and systems integration. Fixed-price contracts are compressing EPC margins as steel price volatility of 30-40% within single quarters exposes contractors to input cost risk.
- Maintenance:Lifecycle asset preservation including predictive, preventive, and corrective interventions. Digital twin platforms integrating real-time structural health monitoring are rendering obsolete traditional 5-year fixed-interval inspection regimes for bridges and tunnels in Japan and South Korea.
- Consulting:Front-end engineering design, feasibility studies, and regulatory compliance advisory.
- Project Management:Owner's engineer and construction supervision services coordinating multi-contractor delivery.
Construction commands the dominant revenue share; maintenance is gaining fastest as concession periods extend and performance-based contracts proliferate.
Technology:
Adoption curves are steepening where regulatory mandates force compliance spend, while voluntary deployment lags in markets without procurement incentives tied to digital deliverables.
- BIM:Building Information Modeling platforms enabling 3D-4D-5D design coordination and clash detection. Shortage of certified modelers is delaying design handoffs and inflating pre-construction timelines by 20-30% across major projects.
- IoT:Sensor networks for structural health monitoring, traffic flow optimization, and environmental condition tracking. State transport authorities in Japan and South Korea are mandating continuous sensor deployment on new mega-projects, compressing lifecycle cost models and transferring margin to data-analytics service providers.
- Drones:Unmanned aerial systems for survey, inspection, and progress monitoring applications.
- Smart Grids:Intelligent electricity distribution networks with automated fault detection and demand response capability. India's CEA mandates grid-code compliance for all new power infrastructure, forcing upgrades that face integration friction with 1960s-era switchgear still serving 40% of the distribution network.
BIM anchors current procurement requirements; IoT is climbing the fastest as lifecycle performance contracts spread.
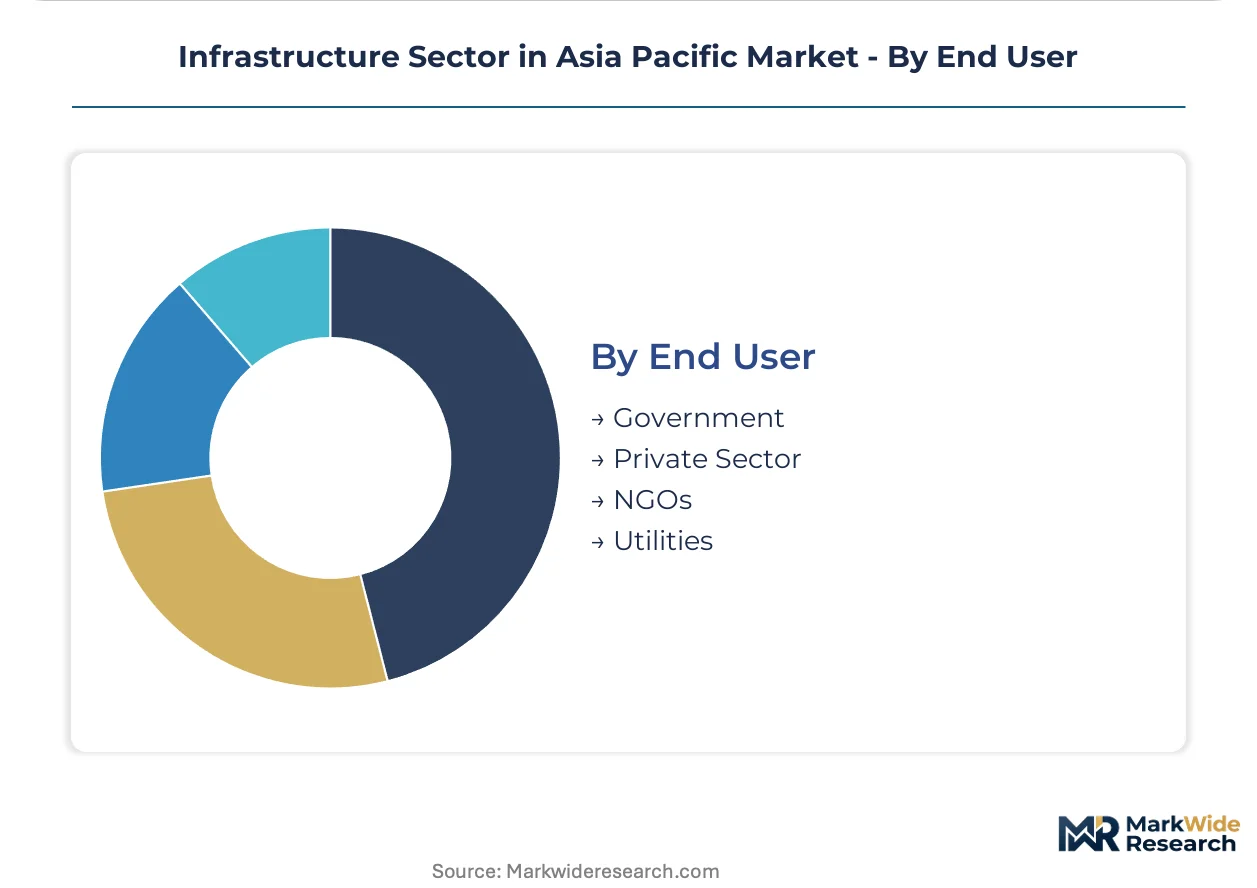
End User:
Capital sources are diversifying beyond traditional government dominance as institutional investors seek yield-bearing infrastructure exposure and private operators assume operational risk.
- Government:Central, state, and municipal agencies funding public goods through budgetary allocation and sovereign borrowing. China's dual carbon goals and India's PLI scheme for infrastructure equipment are redirecting capital toward green construction technologies across transport and power projects.
- Private Sector:Corporate developers, industrial park operators, and logistics firms building captive infrastructure. Asset-light concession models are displacing traditional EPC-own-operate structures as pension funds and infrastructure REITs seek yield without construction risk, with Canadian and Middle Eastern capital funding 60% of greenfield expressway development in India's western corridor.
- NGOs:Multilateral development banks and charitable foundations financing social infrastructure in underserved regions.
- Utilities:Power, water, and telecommunications operators building distribution networks with regulated cost recovery mechanisms.
Government retains the dominant funding role; private sector participation is deepening fastest as institutional capital structures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's coastal provinces extract 15-25% pricing premiums on cement and steel exports to Southeast Asian projects, while Indian states negotiate localized procurement discounts through PLI-linked domestic manufacturing mandates.
China
MEE dual carbon benchmarks force embodied carbon disclosure on all imported construction materials for state-financed Belt and Road projects. Yangtze River Delta clinker producers dominate regional cement supply, exposing Indonesian and Vietnamese projects to freight cost volatility when coastal inventories tighten.
India
CEA grid-code compliance mandates are forcing power distribution infrastructure upgrades across Maharashtra and Gujarat. Western India's industrial corridor development absorbs record steel and cement volumes, with Canadian and Middle Eastern capital funding 60% of greenfield expressway development in these states.
Japan
METI building energy standards and 8.0+ seismic resilience ratings add structural steel tonnage requirements for social infrastructure. Kanto region transport authorities mandate continuous sensor deployment on new mega-projects, compressing lifecycle cost models and transferring margin to data-analytics providers.
Vietnam
The 1,500km north-south high-speed rail corridor remains underpenetrated by foreign EPC consortia despite feasibility completion. Government smart city programs accelerate demand for integrated transport networks with embedded sensor infrastructure, creating first-mover openings for engineering groups with BIM-IoT integration capabilities.
Australia
Infrastructure Australia assessment frameworks mandate cost-benefit transparency for all major project approvals. Sydney and Melbourne metro corridors drive demand for predictive maintenance contracts as digital twin platforms replace traditional 5-year fixed-interval inspection regimes for tunnels and bridges.
Infrastructure Sector in Asia Pacific Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on margin-diluted procurement. The Asia Pacific infrastructure vendor base splits between state-backed engineering conglomerates with captive financing arms and specialized EPC contractors competing on technical certification. Three archetypes dominate: integrated construction-financing platforms, heavy civil specialists with captive equipment manufacturing, and nuclear-power EPCs commanding premium contract terms. Competitive moves concentrate on asset-light concession structures and BIM-lifecycle service integration.
Among Chinese state-backed conglomerates, China State Construction Engineering and China Communications Construction Company exemplify the integrated platform archetype with cross-border project origination capabilities. Samsung C&T and Hyundai E&C represent the Korean EPC tier differentiated by specialized power plant and transport corridor expertise. Larsen & Toubro anchors the Indian heavy civil segment through vertically integrated construction equipment supply.
| Leading Market Players |
|---|
| China State Construction Engineering (CSCEC) |
| China Communications Construction Company (CCCC) |
| Power Construction Corporation of China (PowerChina) |
| Samsung C&T |
| Obayashi Corporation |
| Hyundai E&C |
| Larsen & Toubro (L&T) |
| China Railway Group (CREC) |
| China Railway Construction Corporation (CRCC) |
| Others |
Supply & Pricing Matrix
The Malacca Strait freight corridor's bunker fuel cost swings transmit directly into Southeast Asian cement landed prices, amplifying the pricing power of Yangtze River Delta clinker producers while forcing Indian EPC contractors toward domestic steel sourcing to escape import cost volatility.
Pricing Analysis
Industrial OEM buyers anchor project-based contract structures across Asia Pacific infrastructure, with premium-mid-economy pricing differentiation driven by seismic certification grade and BIM deliverable depth. Cost compression in fixed-price EPC tiers is intensifying because steel price volatility of 30-40% within single quarters exposes contractors to unrecoverable input spikes. State transport authorities exhibit lowest price sensitivity due to budgetary allocation flexibility, while private concession operators face acute margin pressure from yield-hungry institutional capital.
Supply Chain Analysis
Export control regimes on high-grade structural steel and nuclear-certified concrete additives limit technology flows into Vietnam's high-speed rail corridor, concentrating procurement leverage among licensed Japanese and Korean suppliers. Manufacturing gravity centers on China, India, and South Korea for construction equipment and specialty cement. Raw material dependencies include Australian iron ore, Indonesian nickel for stainless reinforcement, and Middle Eastern petrochemicals for advanced admixtures. Single-source vulnerability runs through China's coastal clinker production clusters. Distribution runs through port-tied bulk terminals with captive logistics arms of state-backed engineering conglomerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Infrastructure investment cycles in Asia Pacific are recovering from a three-year trough as India's PLI-linked equipment manufacturing mandates and China's dual carbon procurement rules restart capital deployment.
For Market Incumbents: Build switching-cost moats through captive BIM-lifecycle service platforms that lock state transport authorities into decade-long predictive maintenance contracts. Deepen backward integration into electric-arc-furnace steel production to escape China's embodied carbon disclosure requirements on imported materials. Defend against asset-light concession competitors by anchoring operational data rights in contract structures.
For New Entrants and Emerging Players: Build out specialized seismic engineering capabilities targeting Japan's 8.0+ resilience mandates, where incumbent capacity constraints create 20-30% timeline premiums. Vietnam's 1,500km north-south high-speed corridor remains the most penetrable mega-project for foreign EPC consortia despite feasibility completion. Lead with BIM-IoT integration demonstrations on pilot smart city segments to bypass traditional qualification barriers.
For Investors and Strategic Acquirers: Engineering groups with documented asset-performance databases and Infrastructure Australia framework compliance represent the priority acquisition archetype for yield-bearing infrastructure exposure. Long-term viability hinges on concession period extensions beyond 25 years and performance-based contract proliferation. Watch for CEA grid-code compliance mandate acceleration as the inflection signal for power distribution equipment replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| BIM-Lifecycle Integration | Captures margin pools through predictive maintenance contracts that transfer revenue from construction to data-analytics services. |
| Asset-Light Concession Structuring | Enables pension fund and REIT capital deployment without construction risk exposure, stripping operational assets from engineering groups. |
| Green Steel Sourcing Transition | MEE dual carbon benchmarks force electric-arc-furnace procurement, reshaping material flows on Belt and Road projects. |
| Seismic Engineering Certification | Japan's 8.0+ resilience mandates add structural steel tonnage requirements that command premium contract terms from specialized EPCs. |
| Smart Grid Code Compliance | India's CEA mandates force distribution infrastructure upgrades, opening equipment replacement cycles for grid-code-certified suppliers. |
Research Methodology
A spread of perspectives from EPC contract directors, state transport authority procurement leads, institutional infrastructure fund managers, and BIM platform engineers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against MEE emission filings, CEA grid-code notifications, Infrastructure Australia assessment records, and customs data on steel and cement trade flows. Bottom-up project pipeline aggregation and top-down macroeconomic factor weighting were triangulated to anchor volume estimates.
Demand-supply balance modeling across the projection horizon incorporated segmentation by transport mode, service delivery structure, technology adoption tier, and capital source type. CAGRs were derived from fitted growth curves applied to disclosed contract awards and announced industrial corridor investments. Industry-specific forecast inputs included PLI scheme disbursement trajectories and high-speed rail feasibility study completions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed engineering conglomerates into foreign concession markets would shift outcomes. Cross-checking against Infrastructure Australia cost-benefit transparency benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
South America Data Center Construction Market
Infrastructure Construction
Bahrain Construction Market
Infrastructure Construction
Gas Pipeline Infrastructure Market
Infrastructure Construction
South Korea Infrastructure Market
Infrastructure Construction
US Pipeline Construction Market
Infrastructure Construction
Offshore Pipeline Infrastructure Market
Infrastructure Construction
Philippines Data Center Construction Market
Infrastructure Construction
Pipeline Construction Market
Infrastructure Construction
Rebar Tier Market
Infrastructure Construction
Heavy Movable Bridges Market
Infrastructure Construction
Aerial Cable Car Equipment Market
Infrastructure Construction
Africa Pipeline Construction Market
Infrastructure Construction
Qatar Transportation Infrastructure Construction Market
Infrastructure Construction
France Transportation Infrastructure Construction Market
Infrastructure Construction
APAC Data Center Construction Market
Infrastructure Construction
China Transportation Infrastructure Construction Market