
 France Transportation Infrastructure Construction Market | 2026-2036
France Transportation Infrastructure Construction Market Size, Share, and Industry Trends Forecast 2026-2036
France Transportation Infrastructure Construction Market Foresight
The capability gap between vertically integrated conglomerates and specialized regional contractors is reorganizing competitive tiers in French transportation infrastructure. VINCI Construction leverages its in-house engineering and concession-management arms to dominate complex rail and highway concessions. Bouygues Construction anchors its position through advanced digital construction platforms and precast manufacturing scale. Eiffage differentiates via integrated rail-electrification capabilities and long-term maintenance contracts.
France transportation infrastructure construction encompasses the planning, engineering, and physical assembly of mobility assets including roadways, railways, airports, and ports, typically employing reinforced concrete superstructures, hot-mix asphalt wearing courses, and steel-composite bridge decks designed for 100-year service lives under Eurocode load specifications. Railways command the deepest project pipelines as the Grand Paris Express and intercity TGV extensions absorb multibillion-euro commitments. Roadways retain mature, maintenance-heavy revenue streams where precast concrete and asphalt paving technologies dominate renewal cycles. Public-private partnerships as a funding source concentrate margin pools in concession finance and long-term operations, attracting infrastructure bond investors seeking regulated yield profiles.
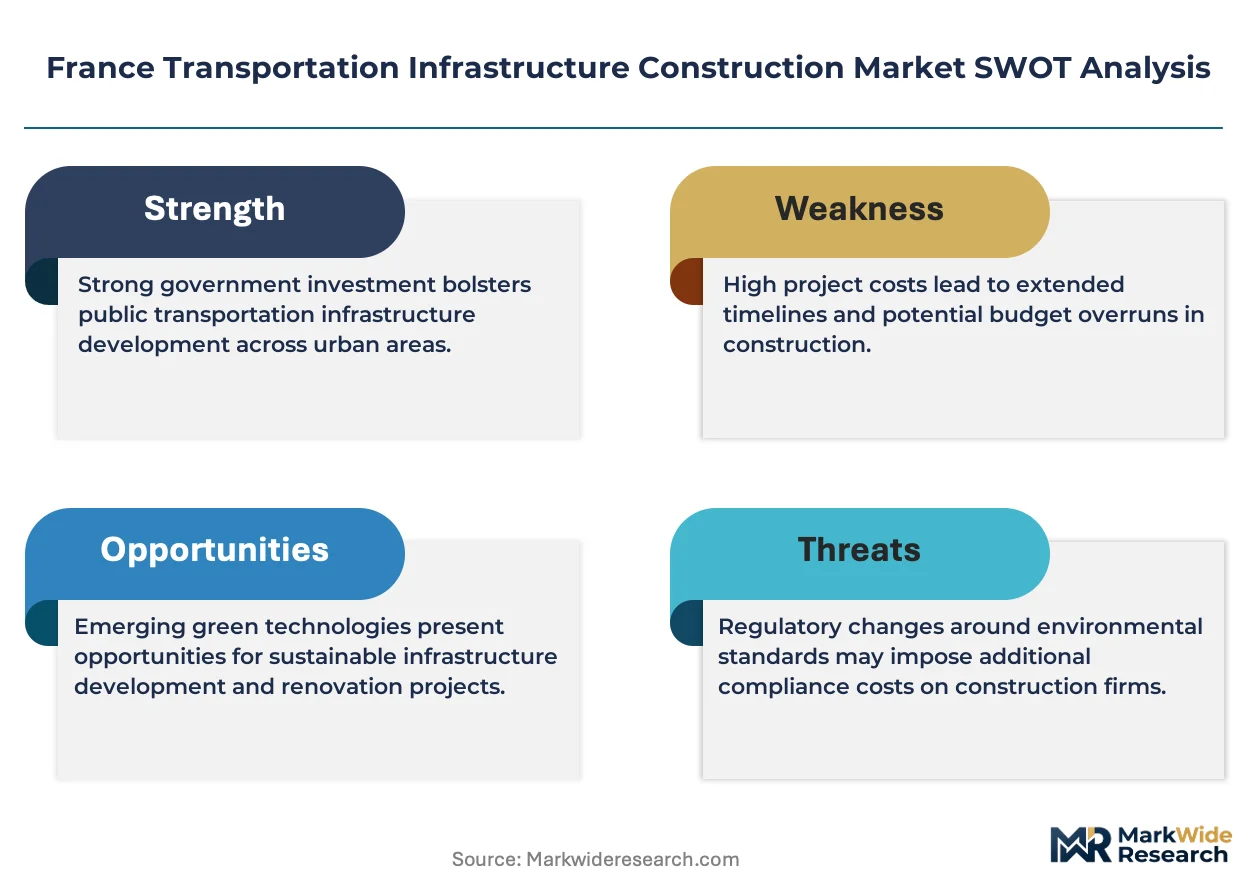
France's infrastructure sector operates under the EU Green Deal's embodied-carbon thresholds, France's national low-carbon strategy enforced by the Ministry of Ecological Transition, and EU taxonomy alignment requirements for sustainable finance eligibility. These frameworks mandate environmental product declarations for construction materials and progressively restrict high-carbon cement and steel in publicly funded projects. Stakeholders must monitor evolving CSRD disclosure obligations and the EU AI Act's eventual application to automated construction equipment and traffic-management systems.
Market Dynamics
France's transportation infrastructure construction sector is reconfiguring around the EU Green Deal's embodied-carbon thresholds, which are redirecting material procurement toward low-carbon concrete and recycled aggregates while compressing contractor margins on legacy high-carbon supply chains.
Growth Catalysts
- Grand Paris Express:The multibillion-euro metro expansion is absorbing steel-composite bridge decks and precast concrete tunnel segments at scale, concentrating demand among specialized rail-electrification contractors.
- EU Green Deal:Carbon-reduction mandates for construction materials are creating regulated procurement pipelines for environmental product declaration-certified suppliers.
- TGV Extensions:Intercity high-speed rail corridors under France's national infrastructure plan are sustaining deep project pipelines for reinforced concrete superstructures and hot-mix asphalt wearing courses.
Market Restraints
- Cement Cost Volatility:Energy-intensive clinker production faces carbon-border adjustment pressure, squeezing margins for concrete-dependent bridge and tunnel contractors.
- Regional Contractor Concentration:Specialized capabilities cluster around Lyon and Marseille logistics hubs, leaving peripheral territories dependent on distant mobilization.
- REACH Compliance Friction:Chemical registration requirements for asphalt additives and concrete admixtures extend procurement timelines by 12-18 months.
Strategic Opportunities
- Occitanie Logistics Corridors:Underpenetrated multimodal freight hubs around Montpellier and Toulouse offer first-mover positioning for integrated concession operators.
- Digital Twin Convergence:BIM platforms fused with IoT sensor networks are enabling predictive maintenance contracts that capture 30-year revenue streams.
- CSRD-Aligned Green Bonds:EU taxonomy eligibility for sustainable finance is opening institutional capital pools for low-carbon infrastructure concessions.
Industry Challenges
- Rail-Electrification Skill Scarcity:Specialized technicians for 25kV overhead line equipment are concentrated among aging workforces, constraining TGV and metro expansion timelines.
- Legacy System Integration:New digital construction platforms must interface with France's fragmented regional rail signaling standards, multiplying commissioning complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Transportation Infrastructure Construction Market |
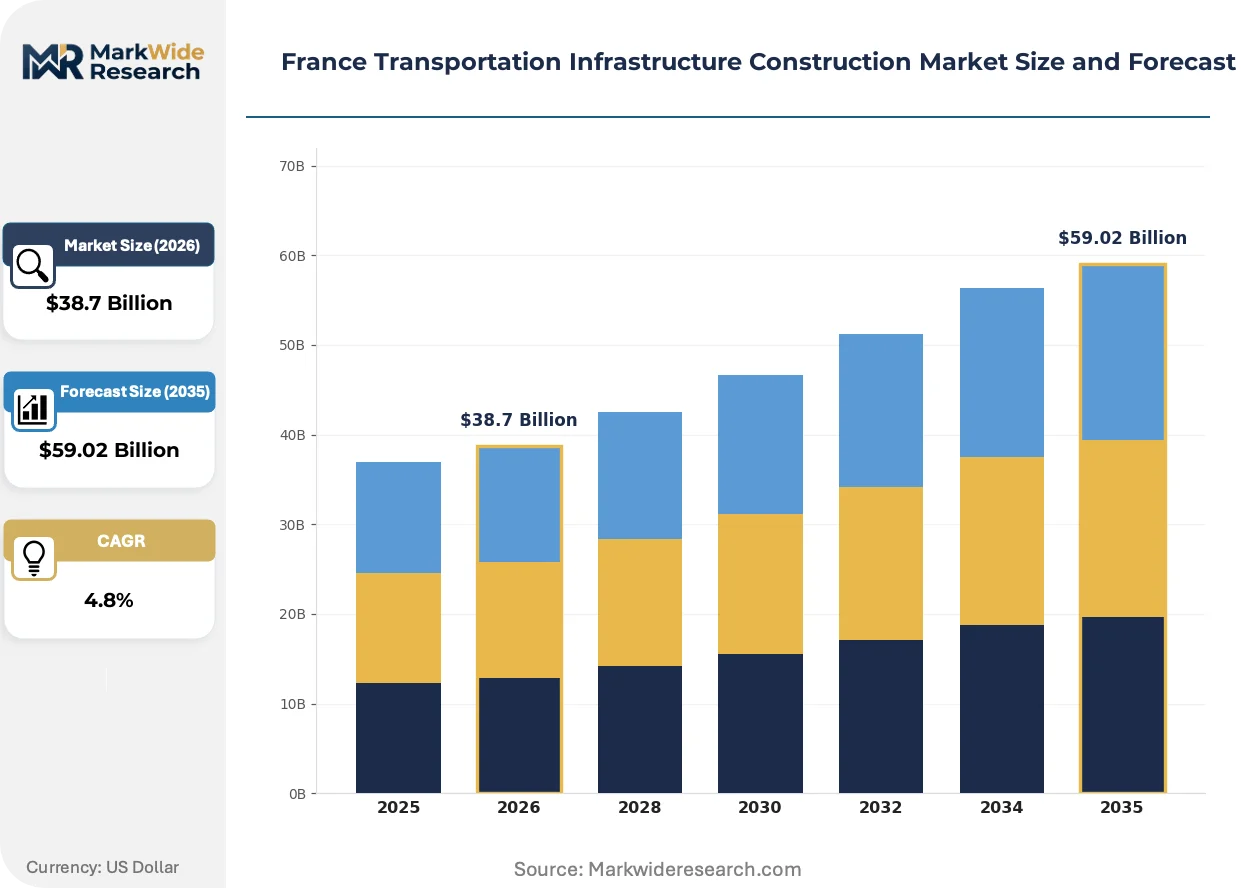
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Roadways, Railways, Airports, Ports Construction Technology: Precast Concrete, Geo-synthetics, Asphalt Paving, Steel Structures, Reinforced Earth End User: Government Agencies, Private Contractors, Public Transport Operators, Logistics Companies Funding Source: Public Funding, Private Investments, Public-Private Partnerships, Infrastructure Bonds |
| Companies Covered | Bouygues Construction, NGE, VINCI Construction, SYSTRA, Egis, Colas, Spie Batignolles, SETEC, Eiffage, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Transportation Infrastructure Construction Market Shifts & Advancements
Material science breakthroughs and regulatory digitization are compressing design-to-construction cycles while elevating lifecycle performance metrics above first-cost bidding.
Geopolymer concrete formulations are replacing Portland cement in bridge deck applications, cutting embodied carbon by 40-60 percent. VINCI Construction and Bouygues Construction are piloting these mixes on Grand Paris Express segments. The technology is miniaturizing quality-control protocols, enabling real-time compressive strength monitoring via embedded wireless sensors rather than laboratory batch testing.
France's Ministry of Ecological Transition is enforcing environmental product declarations through the national low-carbon strategy, progressively restricting high-carbon cement and steel in publicly funded projects. Contractors must now submit verified lifecycle assessments to qualify for state procurement frameworks. Rail and highway concessions face the steepest compliance curves, with Grand Paris Express segments already mandating EPD-certified materials.
Public authorities are unbundling design-build-maintain contracts into separate lots, fragmenting risk allocation and compressing contractor margins on pure construction work. Regional prefectures in Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur are pioneering this disaggregation. Specialized maintenance contractors are capturing 15-25 year operations contracts that were historically bundled with initial construction awards.
France Transportation Infrastructure Construction Market Segmentation
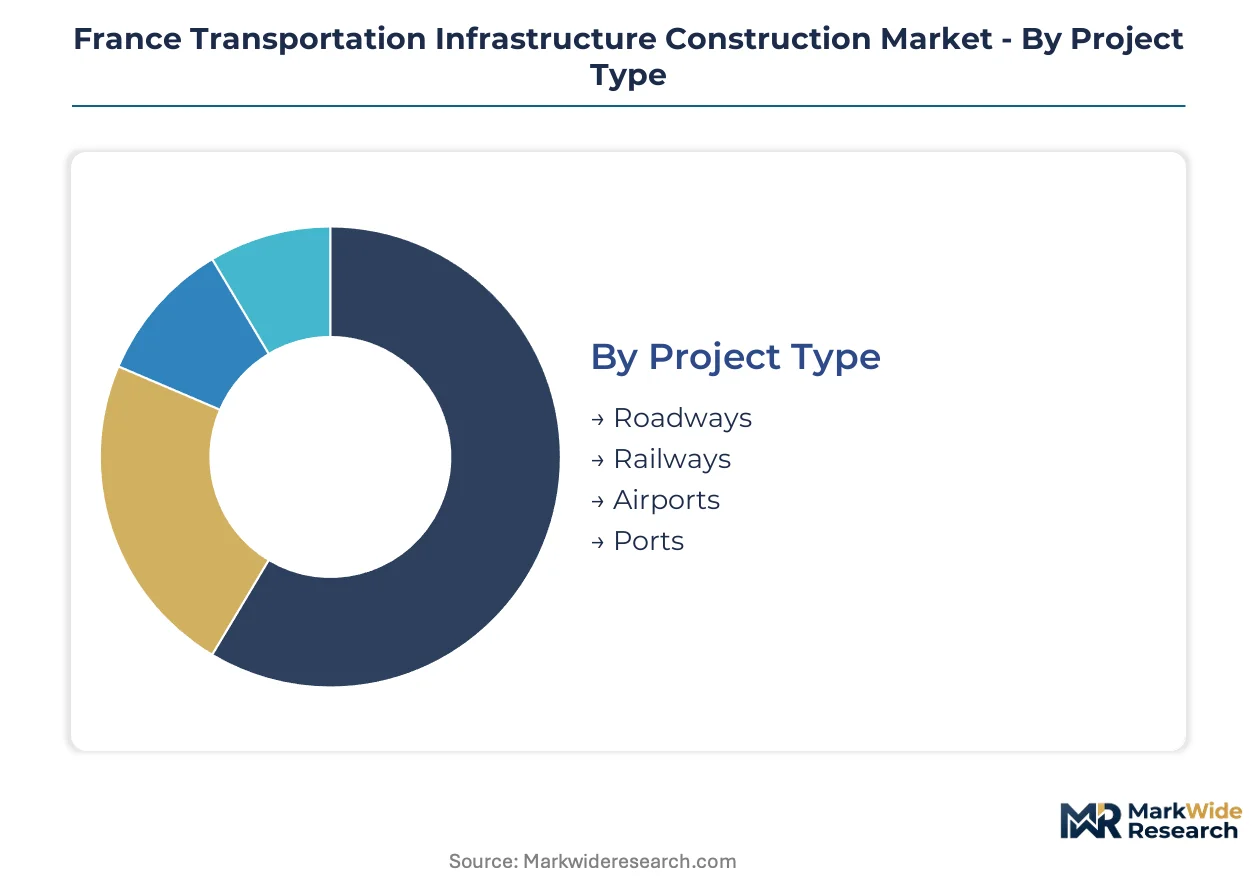
Segmentation in French transportation infrastructure construction reveals how capital allocation, regulatory compliance, and procurement complexity fragment across project types and stakeholder groups. Each dimension carries distinct margin structures and technical capability requirements.
Project Type:
Railways command the deepest margin pools due to multi-decade concession terms and specialized electrification requirements, while roadways operate on compressed bidding cycles with maintenance-heavy revenue profiles.
- Railways:High-speed TGV corridors and metro extensions absorb reinforced concrete superstructures and 25kV overhead line equipment at scale. Grand Paris Express segments concentrate demand in Île-de-France, where EU Green Deal carbon thresholds mandate environmental product declaration-certified materials.
- Roadways:Hot-mix asphalt wearing courses and precast concrete renewal cycles dominate mature maintenance pipelines. Auvergne-Rhône-Alpes regional prefectures are unbundling design-build-maintain contracts, fragmenting risk allocation across specialized resurfacing contractors.
- Airports:Runway pavement engineering and terminal steel-composite structures serve Orly and Charles de Gaulle expansion programs under strict noise-abatement regulations.
- Ports:Quay wall rehabilitation and container terminal paving in Marseille-Fos sustain cyclical maritime freight investment tied to EU emissions trading scheme compliance.
The dominant share belongs to Railways, while Roadways retains the broadest contractor base despite thinner margins.
Construction Technology:
Technology selection tracks embodied-carbon compliance costs, with low-carbon material premiums reshaping procurement economics across France's publicly funded frameworks.
- Precast Concrete:Tunnel segments and bridge elements manufactured off-site under controlled curing conditions. Bouygues Construction and VINCI Construction leverage dedicated precast plants to meet Grand Paris Express volume requirements while embedding wireless sensors for real-time quality monitoring.
- Geo-synthetics:Polymeric reinforcement grids and drainage composites stabilize subgrades in Occitanie logistics corridor expansions, where soil conditions demand alternative foundation solutions.
- Asphalt Paving:Hot-mix wearing courses with polymer-modified binders dominate roadway renewal cycles, though REACH compliance friction extends additive procurement timelines.
- Steel Structures:Composite bridge decks and overhead line support masts serve rail electrification programs, facing carbon-border adjustment pressure on energy-intensive production.
- Reinforced Earth:Mechanically stabilized earth walls retain embankments in highway widening projects across Provence-Alpes-Côte d'Azur, where terrain constraints favor modular construction.
Precast Concrete holds the largest installed base, though Geo-synthetics is expanding most quickly in underpenetrated freight hub applications.
End User:
Procurement authority concentration determines contract scale, with state agencies bundling megaprojects while private operators fragment into specialized maintenance lots.
- Government Agencies:Ministry of Ecological Transition frameworks mandate lifecycle assessment submission for state-funded rail and highway concessions, concentrating award decisions in Paris-based procurement bodies.
- Private Contractors:Regional construction firms compete for disaggregated maintenance contracts, capturing 15-25 year operations terms previously bundled with initial construction.
- Public Transport Operators:RATP and SNCF Network specify integrated rail-electrification capabilities, filtering vendor pools to contractors with in-house signaling and traction power expertise.
- Logistics Companies:Multimodal freight operators around Lyon and Marseille drive demand for connected intermodal terminals, though peripheral territories suffer from distant contractor mobilization.
Government Agencies control the deepest project pipelines, while Private Contractors are capturing share fastest through maintenance specialization.
Funding Source:
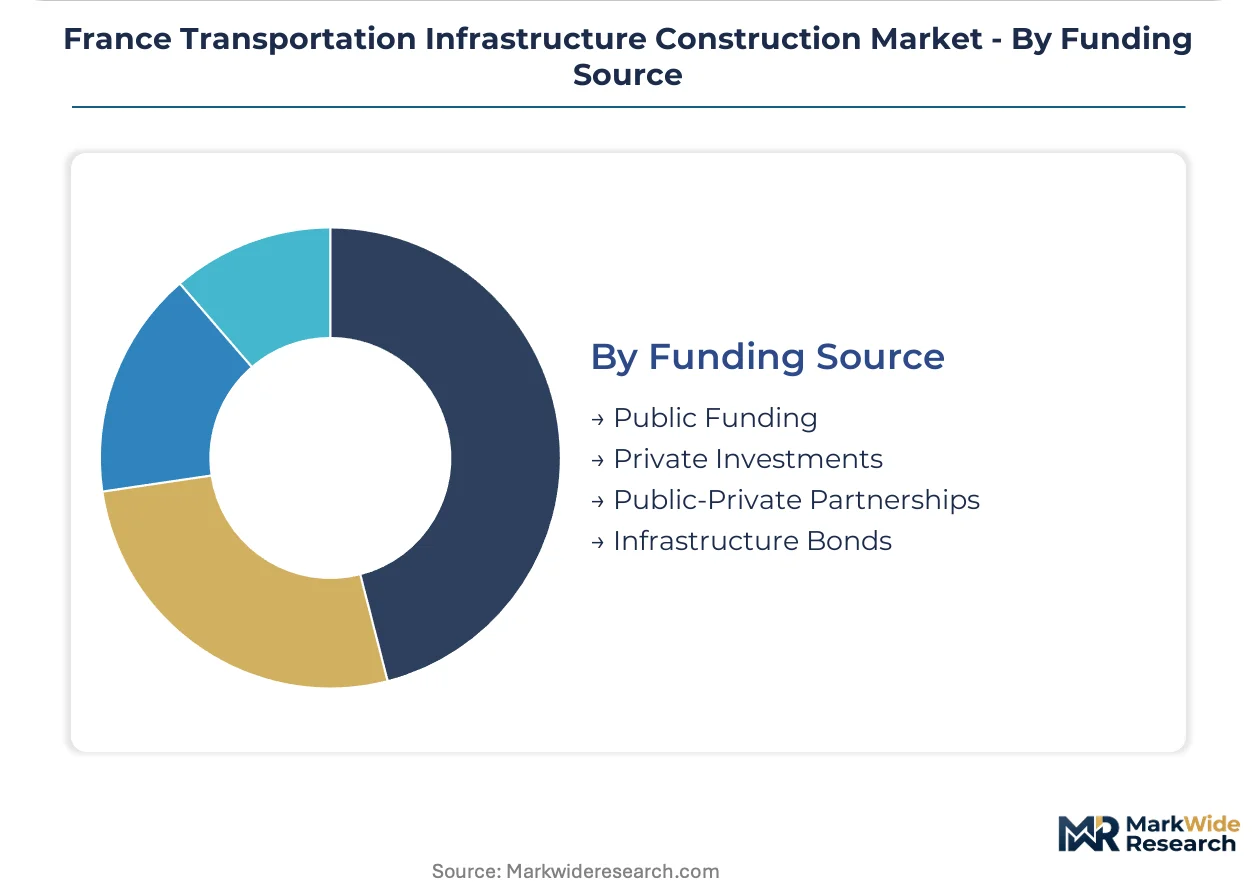
Capital structure complexity separates long-dated institutional investment from annual budget volatility, with concession finance attracting infrastructure bond markets seeking regulated yield profiles.
- Public Funding:State budget allocations through France's national infrastructure plan sustain Grand Paris Express and TGV extension commitments, subject to Ministry of Ecological Transition carbon compliance conditions.
- Private Investments:Pension funds and insurance capital deploy into operational assets, preferring toll road and airport concessions with inflation-linked revenue mechanisms.
- Public-Private Partnerships:Availability payment structures dominate complex rail projects, transferring construction risk to contractors while retaining demand risk with public authorities.
- Infrastructure Bonds:EU taxonomy-aligned green bond issuance opens institutional capital pools for low-carbon concrete and recycled aggregate procurement, with CSRD disclosure obligations enhancing eligibility verification.
Public-Private Partnerships anchor the largest committed capital volumes, while Infrastructure Bonds are climbing the fastest on green finance regulatory alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Île-de-France show lowest price elasticity for complex rail-electrification packages, while peripheral regions squeeze margins on standardized roadway maintenance contracts. Regional procurement fragmentation under France's decentralized infrastructure governance creates divergent competitive dynamics across metropolitan and rural construction markets.
Île-de-France
Grand Paris Express metro expansion absorbs the deepest capital commitments for tunnel segments and station infrastructure. The Ministry of Ecological Transition enforces environmental product declaration mandates on all publicly funded segments. Saint-Denis and Noisy-Champs construction clusters concentrate precast concrete manufacturing and rail-electrification specialist mobilization.
Auvergne-Rhône-Alpes
Lyon-Saint-Exupéry logistics hub expansion and Rhône corridor multimodal terminals sustain demand for reinforced earth structures and geosynthetic stabilization. Regional prefectures unbundle design-build-maintain contracts into separate lots under EU public procurement directives. Vienne and Valence satellite yards serve as staging points for highway widening projects with modular precast elements.
Provence-Alpes-Côte d'Azur
Marseille-Fos port quay rehabilitation and A7 autoroute capacity upgrades drive cyclical investment in marine concrete and asphalt paving renewal. The EU Green Deal's carbon-border adjustment pressure elevates low-carbon cement procurement costs for Mediterranean coastal projects. Toulon and Nice regional offices anchor contractor presence for maintenance-heavy revenue streams.
Occitanie
Montpellier and Toulouse freight corridors remain underpenetrated for multimodal terminal integration, offering positioning opportunities for concession operators. France's national low-carbon strategy restricts high-carbon steel in bridge construction across Garonne watershed projects. Perpignan logistics zones suffer from distant specialist contractor mobilization, compressing bid competitiveness.
Hauts-de-France
Calais-Dunkerque port expansion and Channel Tunnel rail link maintenance sustain demand for steel-composite bridge decks and overhead line equipment. REACH compliance friction extends chemical additive procurement timelines for asphalt resurfacing of A1 and A16 autoroutes. Lille metropolitan construction clusters compete for TGV extension segments with Île-de-France-based rivals.
France Transportation Infrastructure Construction Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with concession-management capabilities separating the uppermost layer from pure construction contractors. The upper tier commands multibillion-euro rail and highway concessions through bundled engineering-procurement-construction offerings. Mid-scale regional contractors capture disaggregated maintenance lots and resurfacing contracts. Dominant competitive moves include backward integration into precast manufacturing and strategic partnerships for digital twin platform deployment.
Within the integrated conglomerate tier, VINCI Construction and Bouygues Construction occupy positions defined by in-house engineering arms and concession-management scale. Eiffage represents the specialized rail-electrification archetype with long-term maintenance contract anchoring. Among mid-scale specialists, Colas and Spie Batignolles exemplify regional contractors capturing share through maintenance specialization and disaggregated lot bidding.
| Leading Market Players |
|---|
| Bouygues Construction |
| NGE |
| VINCI Construction |
| SYSTRA |
| Egis |
| Colas |
| Spie Batignolles |
| SETEC |
| Eiffage |
| Others |
Supply & Pricing Matrix
Geopolymer concrete substitution for Portland cement in Grand Paris Express segments simultaneously concentrates supply geography around dedicated precast plants in Saint-Denis and Noisy-Champs while compressing pricing economics for legacy high-carbon suppliers unable to meet environmental product declaration mandates. This material transition redirects procurement power toward contractors with captive low-carbon formulation capabilities, fragmenting competitive tiers between EPD-certified and conventional supply bases.
Pricing Analysis
Long-term maintenance contracts and 25-year operations terms capture lifetime value pools that exceed initial construction margins by substantial multiples. Project-based bidding for rail electrification and tunnel segments stratifies across premium EPD-certified tiers, standard compliant-mix tiers, and economy conventional-material tiers constrained by carbon-border adjustment exposure. Pricing pressure stems from unbundled design-build-maintain contracts that compress pure construction margins while concentrating award decisions in Paris-based procurement bodies. Regional prefectures in peripheral territories exhibit highest price sensitivity due to distant contractor mobilization costs, while Île-de-France buyers show lowest elasticity for complex rail-electrification packages.
Supply Chain Analysis
Clinker import dependence through Mediterranean port terminals anchors supply vulnerability for conventional cement-dependent contractors. France draws from Spanish and Italian precast manufacturing clusters for specialized tunnel segments, while German and Belgian steel-composite bridge deck suppliers feed rail electrification programs. Raw material dependencies center on low-carbon cement alternatives, recycled aggregate streams, and polymer-modified asphalt binders subject to REACH registration friction. Single-source vulnerability concentrates in 25kV overhead line equipment where specialized technicians cluster among aging workforces. Distribution runs through regional prefabrication yards in Vienne and Valence serving highway widening projects with modular elements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France transportation infrastructure construction functions as a service-attach market where predictive maintenance contracts and digital twin-enabled operations layers expand faster than physical construction revenue, rewarding contractors who bundle lifecycle performance guarantees with initial asset delivery.
For Market Incumbents: Consolidate backward integration into precast manufacturing and rail-electrification specialist capabilities to defend against disaggregated contract structures fragmenting risk allocation. Capture dedicated low-carbon concrete formulation capacity before environmental product declaration mandates harden procurement barriers. Deepen concession-management scale to anchor availability payment structures that transfer construction risk while retaining long-term operations revenue. For New Entrants and Emerging Players: Lead with digital twin platform deployment targeting underpenetrated multimodal freight corridors in Occitanie where Montpellier and Toulouse logistics hubs lack integrated concession operators. Position for 15-25 year maintenance contracts unbundled from initial construction awards in Auvergne-Rhône-Alpes regional prefectures. Pursue geosynthetic stabilization specialization for soil-constrained foundation projects where established contractors lack technical depth. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-scale regional contractors capturing disaggregated maintenance lots through specialized resurfacing and rail-electrification capabilities. Long-term viability over a multi-year horizon hinges on EU taxonomy-aligned green bond eligibility opening institutional capital pools for low-carbon infrastructure concessions. Monitor CSRD disclosure obligation enforcement as the inflection signal separating EPD-compliant asset portfolios from stranded high-carbon exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precast Manufacturing | Bouygues Construction and VINCI Construction leverage dedicated plants to meet Grand Paris Express volume requirements with embedded wireless quality monitoring. |
| Digital Twin Platform Deployment | BIM platforms fused with IoT sensor networks enable predictive maintenance contracts capturing 30-year revenue streams from SNCF Network and RATP. |
| Environmental Product Declaration Certification | Ministry of Ecological Transition mandates progressively restrict high-carbon cement and steel in publicly funded rail and highway concessions. |
| Concession Finance Structuring | Availability payment mechanisms transfer construction risk to contractors while retaining demand risk with public authorities under France's national infrastructure plan. |
| Rail-Electrification Capability Acquisition | Eiffage anchors market position through integrated 25kV overhead line expertise and long-term maintenance contracts with specialized technician workforces. |
Research Methodology
Cross-validation between primary interviews with construction project directors, rail-electrification specialists, regional prefecture procurement officers, and infrastructure bond analysts anchors the qualitative findings against secondary validation from EU public procurement databases, Ministry of Ecological Transition carbon compliance filings, and concession finance disclosure records. Bottom-up project pipeline aggregation triangulates with top-down national infrastructure plan commitments to isolate volume and value estimates. The analysis synthesizes field perspectives on contract unbundling trends with documented award patterns across Île-de-France, Auvergne-Rhône-Alpes, and Provence-Alpes-Côte d'Azur regional markets.
Sensitivity analysis across low-carbon material adoption scenarios, REACH compliance timeline variations, and rail-electrification workforce availability constraints shapes the analytical framework. Segmentation dimensions span project type, construction technology, end-user procurement authority, and funding source structure across the projection horizon. CAGRs derive from modeled investment commitments under France's national infrastructure plan adjusted for carbon-border adjustment implementation pacing and EU Green Deal threshold enforcement curves. Industry-specific inputs include Grand Paris Express segment award schedules, TGV extension corridor prioritization, and regional prefecture disaggregation policy diffusion patterns.
Underlying assumptions cover continued EU taxonomy alignment for green bond eligibility, stable carbon-border adjustment mechanisms, and gradual REACH compliance timeline compression, with deviation risk concentrated in cement cost volatility from energy-intensive clinker production and rail-electrification skill scarcity constraining project delivery. Practitioners should keep alternative scenarios live as CSRD disclosure obligations and EU AI Act construction equipment applications evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Transportation Infrastructure Construction Market
Infrastructure Construction
South Korea Infrastructure Market
Infrastructure Construction
New Zealand Infrastructure Market
Infrastructure Construction
Finland Transportation Infrastructure Construction Market
Infrastructure Construction
Latin America Data Center Construction Market
Infrastructure Construction
Italy Transportation Infrastructure Construction Market
Infrastructure Construction
Docks Market
Infrastructure Construction
Canada Commercial Construction Market
Infrastructure Construction
Russia Transportation Infrastructure Construction Market
Infrastructure Construction
New Zealand Data Center Construction Market
Infrastructure Construction
China Transportation Infrastructure Construction Market
Infrastructure Construction
India Transportation Infrastructure Construction Market
Infrastructure Construction
Brazil Infrastructure Sector Market
Infrastructure Construction
Vietnam Infrastructure Market
Infrastructure Construction
Global Manhole Covers Market
Infrastructure Construction
Conventional Overhead Conductor Market