
 North America Modular Construction Market | 2026-2036
North America Modular Construction Market Size, Share, and Industry Trends Forecast 2026-2036
North America Modular Construction Market Intelligence
Software-defined building management systems are restructuring how modular projects deliver long-term value beyond initial installation. Clayton leverages its captive retail finance network to control customer acquisition costs across manufactured housing markets. Champion Home Builders sustains manufacturing scale through vertically integrated lumber and appliance sourcing. Cavco Industries anchors southwestern production capacity with concentrated plant locations in Arizona and Texas.
Modular construction encompasses factory-built volumetric units assembled off-site and transported for final installation, with structural specifications typically meeting or exceeding local ICC and state modular administrative codes for seismic, wind, and energy performance. Permanent Modules command the largest revenue share as developers pursue multi-story multifamily and hospitality assets with conventional financing eligibility. Relocatable Modules serve fastest-growing demand from school districts and healthcare networks requiring rapid capacity scaling without capital commitment to fixed structures. Wood-framed volume modules dominate single-family and light commercial applications, while steel and concrete systems penetrate mid-rise commercial and institutional segments where fire ratings and span requirements escalate.
The U.S. Department of Housing and Urban Development maintains preemptive federal standards for manufactured housing construction and safety, while individual states including California, Florida, and Texas operate modular administrative programs with supplemental inspection protocols. The EPA enforces lead-safe renovation certification affecting modular retrofit and redevelopment projects across residential end uses. Stakeholders must monitor evolving state-level energy stretch codes and local zoning amendments that determine whether modular assemblies qualify for conventional construction classification or remain subject to restrictive manufactured housing placement rules.
Market Dynamics
Labor scarcity across skilled trades in Texas, Florida, and California is forcing developers toward factory-controlled production environments where quality and schedule certainty offset transportation premiums.
Growth Catalysts
- ICC Modular Administrative Codes:Harmonized state inspection protocols in California, Florida, and Texas reduce regulatory friction for multi-state operators. Factory certification transfers across jurisdictions accelerate project starts.
- Healthcare capacity expansion:Hospital networks deploy patient towers and surgical suites as permanent modular assemblies to compress commissioning timelines. Clinical staff recruitment cycles now dictate construction schedules.
- Steel and concrete volumetric systems:Mid-rise commercial developers adopt fire-rated assemblies exceeding 75-foot height thresholds. Structural performance specifications now match site-built alternatives for insurance and financing purposes.
Market Restraints
- Lumber input volatility:OSB and dimensional lumber price swings compress margins for wood-framed single-family producers. Champion Home Builders mitigates exposure through captive timberland holdings.
- Transportation radius economics:Module width limits on interstate highways constrain plant-to-site distances to roughly 500 miles. Production geography concentrates where demand density justifies dedicated fleet investment.
- EPA Lead-Safe Renovation Rule:Retrofit and redevelopment projects trigger RRP certification requirements for disturbance of pre-1978 housing stock. Compliance overhead deters residential contractors from modular conversion work.
Strategic Opportunities
- Canadian market penetration:Ontario and British Columbia building codes now recognize ICC-compliant modular assemblies. US manufacturers with underutilized northern plant capacity can serve cross-border demand without new capital deployment.
- Grid-interactive building envelopes:Factory integration of battery storage, heat pumps, and solar pre-wiring aligns with California Title 24 electrification mandates. Electrical contractors on site perform final connections rather than full system builds.
- Direct-to-developer channel development:Multifamily REITs and hospitality operators source modules bypassing traditional general contractor markups. Procurement teams embed factory quality managers into project oversight structures.
Industry Challenges
- Seismic engineering certification:California's HCD and OSHPD inspection protocols demand project-specific structural calculations. Factory engineering staffs strain under case-by-case review timelines.
- Site integration coordination:Crane availability and foundation precision tolerances create schedule risk at module delivery. Weather windows in hurricane-season Florida compress acceptable installation periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Modular Construction Market |
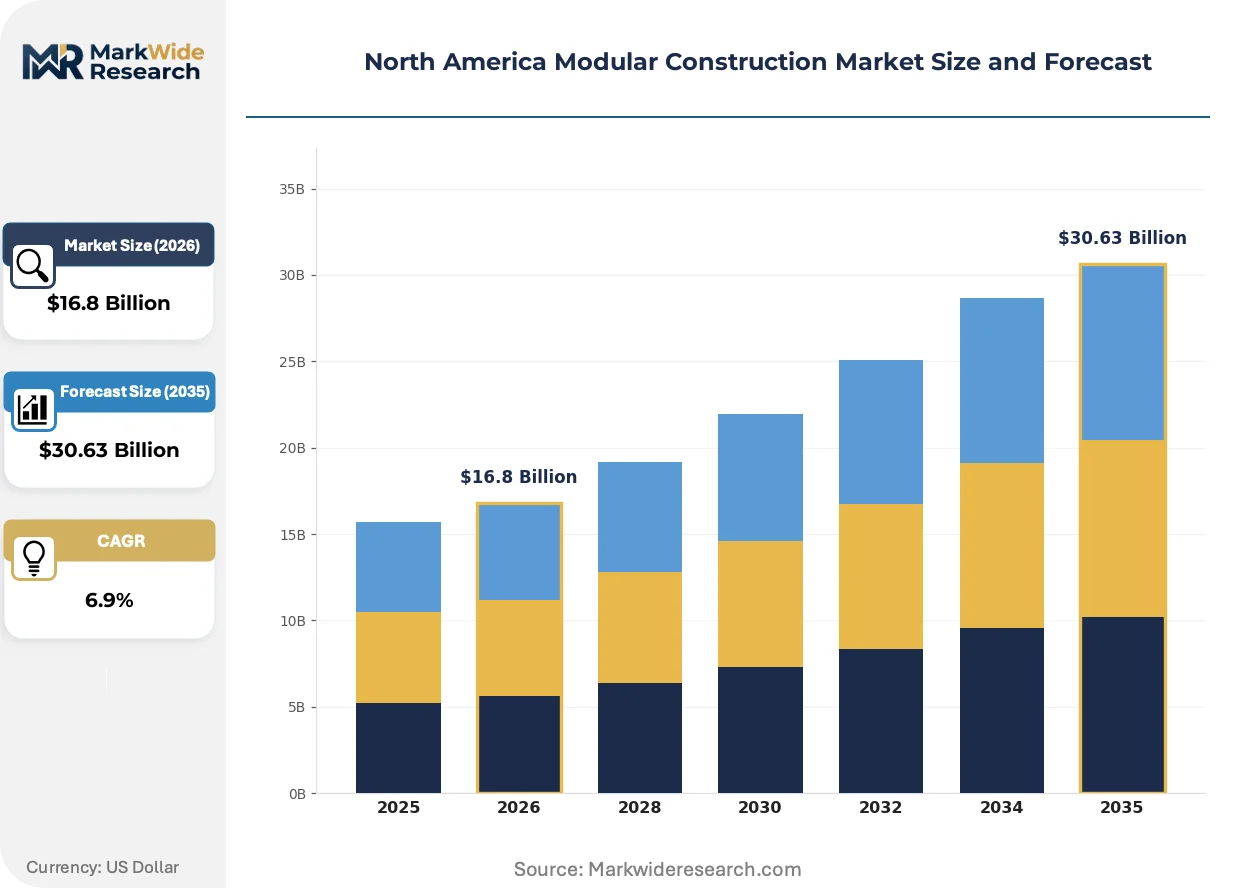
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $30.63 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Permanent Modules, Relocatable Modules, Component-Based Modules, Other Structures End User: Residential Developers, Commercial Builders, Educational Institutions, Healthcare Facilities Construction Method: Panelized Systems, Volume Modules, Hybrid Systems, Prefabricated Elements Material: Wood, Steel, Concrete, Composite Materials |
| Companies Covered | ATCO Ltd., Mobile Modular Management Corporation, Boxx Modular, Clayton, Aries Building Systems, Guerdon, Cavco Industries, Champion Home Builders, Westchester Modular Homes, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Modular Construction Market Strategic Shifts & Innovations
Software-defined building management systems are embedding intelligence into modular assets, transforming static structures into data-generating platforms that command premium valuations in operational real estate portfolios.
Digital twin platforms are rewriting how owners operate modular facilities after handover. Healthcare networks in Texas deploy sensor-rich patient towers with predictive maintenance algorithms. Asset managers now underwrite buildings based on operational data streams rather than replacement cost alone.
California's Title 24 energy stretch codes and the EPA's evolving refrigerant phase-down rules are accelerating electrification of modular HVAC systems. Heat pump water heaters and variable refrigerant flow packages now ship pre-charged from factories. Developers in Florida face parallel pressure from hurricane-resistant wind codes that favor factory-controlled envelope sealing over site-built alternatives.
Institutional procurement teams now bundle module supply with long-term facilities management contracts. University systems in the US Southwest source dormitory blocks with 25-year performance guarantees. This shifts vendor selection criteria from first cost to lifecycle operational expenditure, rewarding factories with captive service networks.
North America Modular Construction Market Segmentation
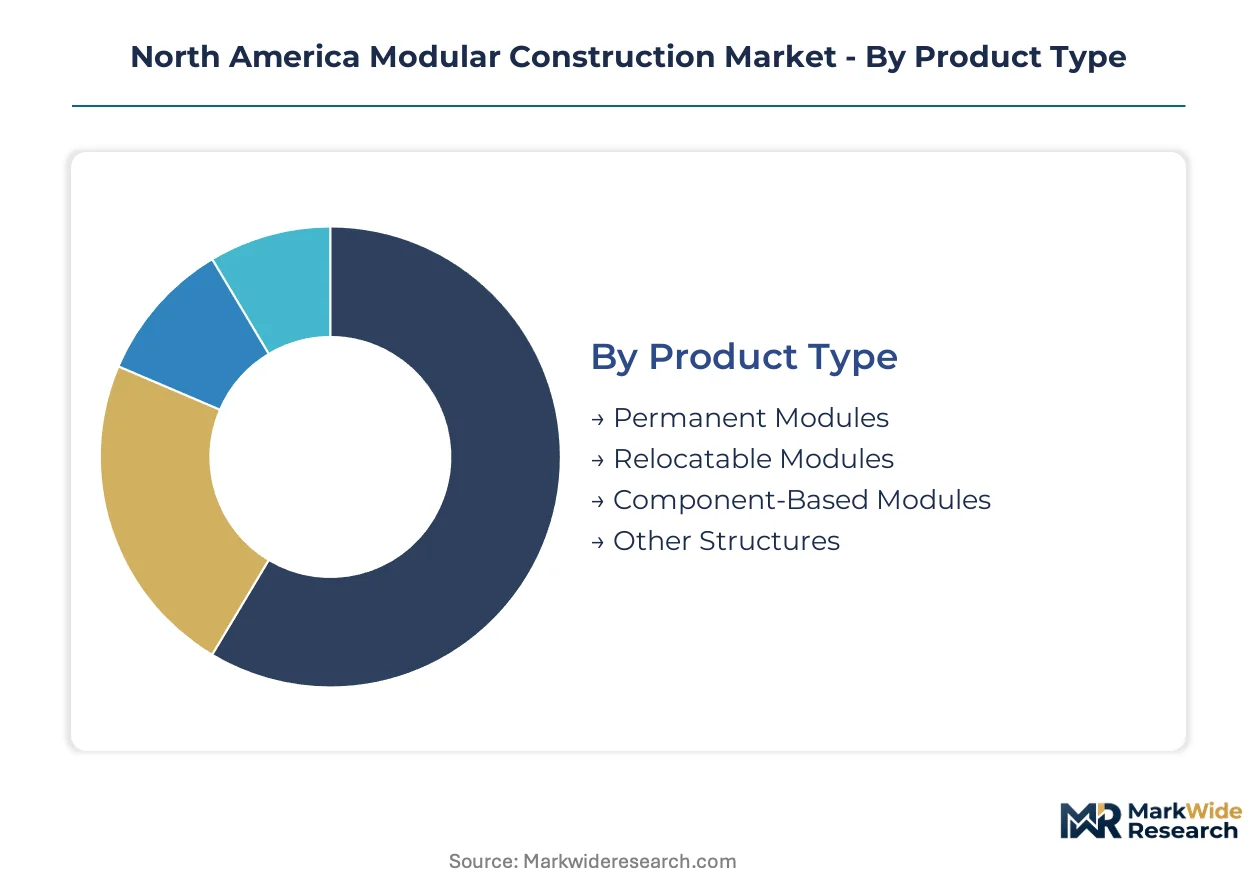
Modular construction segments diverge sharply by capital commitment duration, regulatory pathway, and buyer procurement sophistication. Understanding these divides reveals where factory production economics outperform site-built alternatives.
Product Type:
Buyers in this category separate by financing eligibility and asset permanence intent.
- Permanent Modules:Volumetric units installed on permanent foundations with conventional mortgage and commercial loan eligibility. Demand concentrates in Texas and California multifamily developments where 75-foot height thresholds and seismic ratings match site-built insurance terms.
- Relocatable Modules:Transportable structures designed for repeated deployment without foundation permanence. School districts in Florida and healthcare networks across the Southwest deploy these for rapid capacity scaling without capital commitment to fixed real estate.
- Component-Based Modules:Partial assemblies integrated with site-built elements.
- Other Structures:Specialty configurations including kiosks, guard stations, and emergency response units.
Permanent Modules lead volumes today; Relocatable Modules are gaining share fastest.
End User:
Procurement sophistication and lifecycle cost visibility determine buyer behavior here.
- Residential Developers:Single-family and multifamily builders leveraging HUD-code manufactured housing or state modular programs. Texas and Florida developers exploit labor scarcity to compress construction schedules.
- Commercial Builders:Mid-rise hospitality and office developers requiring fire-rated assemblies. Steel and concrete volumetric systems penetrate this segment where insurance and financing parity with site-built construction is mandatory.
- Educational Institutions:University systems and K-12 districts sourcing dormitory blocks and classroom expansion with long-term performance guarantees.
- Healthcare Facilities:Hospital networks deploying patient towers and surgical suites where clinical staff recruitment cycles dictate compressed commissioning timelines.
Residential Developers anchor current volumes; Healthcare Facilities show the steepest expansion trajectory.
Construction Method:
Transportation economics and crane logistics shape method selection across project sites.
- Volume Modules:Complete three-dimensional units with MEP rough-in performed at factory. Interstate width limits constrain plant-to-site distances to roughly 500 miles, concentrating production geography where demand density justifies dedicated fleet investment.
- Panelized Systems:Flat-packed wall, floor, and roof assemblies offering greater transport efficiency. California multifamily developers favor these for mid-rise projects where site crane availability is limited.
- Hybrid Systems:Combinations of volumetric and panelized elements.
- Prefabricated Elements:Discrete components including precast stairs, bathroom pods, and mechanical racks.
Volume Modules dominate factory throughput; Panelized Systems are climbing the fastest in commercial applications.
Material:
Structural performance requirements and input cost volatility drive material substitution patterns.
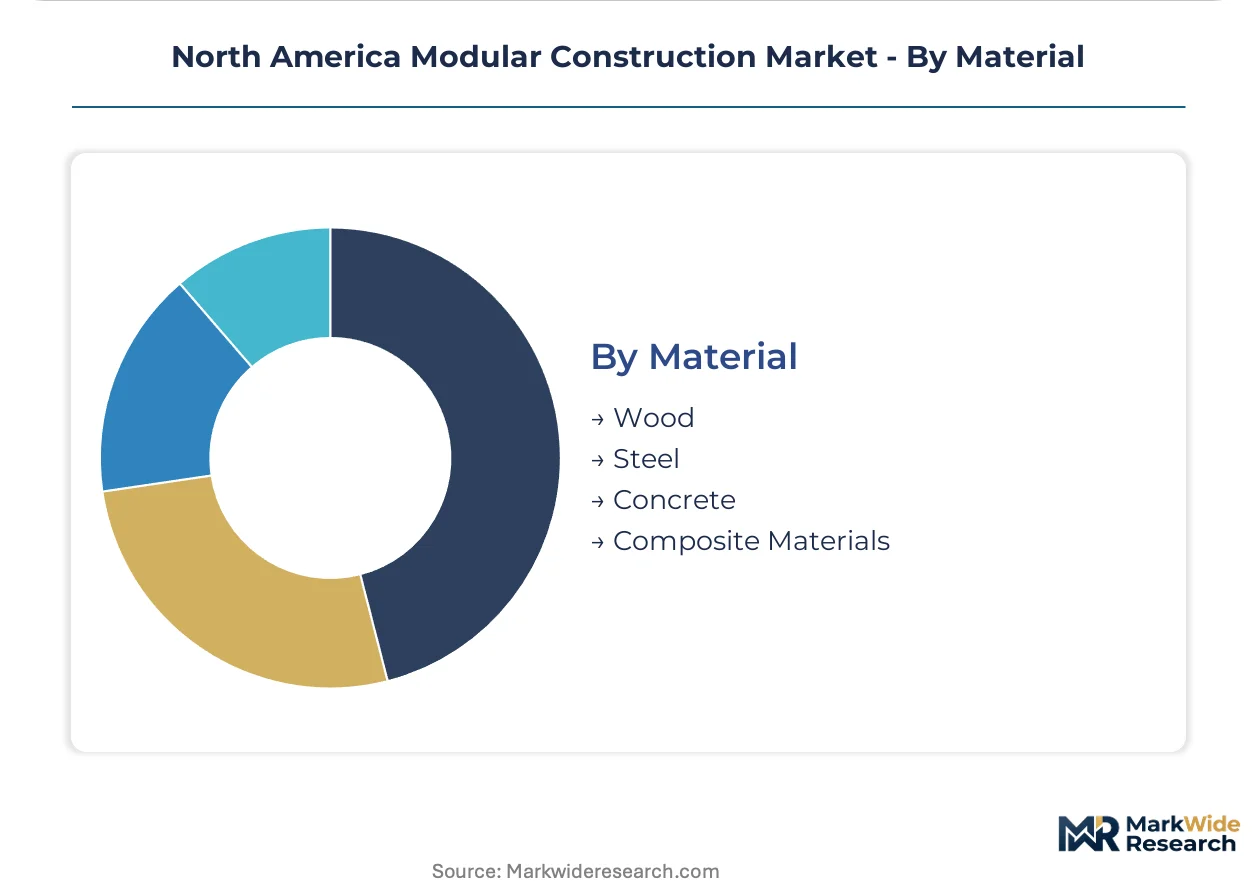
- Wood:Dimensional lumber and engineered wood products dominating single-family and light commercial applications. OSB price swings compress margins, prompting captive timberland strategies among major producers.
- Steel:Cold-formed and structural steel assemblies penetrating mid-rise commercial where fire ratings and 75-foot height thresholds apply. Factory welding certification transfers across California, Florida, and Texas inspection protocols.
- Concrete:Precast and tilt-up concrete systems for institutional and heavy commercial applications.
- Composite Materials:Fiber-reinforced polymers and cross-laminated timber hybrids.
Wood commands current production volumes; Steel is expanding most quickly in commercial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers migrate capacity toward jurisdictions with streamlined factory certification and lower compliance overhead. The cost-of-compliance gap between states and provinces now determines plant location decisions more than raw material proximity.
United States
Texas, Florida, and California concentrate demand as labor scarcity across skilled trades forces developers toward factory-controlled environments. The EPA enforces lead-safe renovation certification affecting modular retrofit projects across residential end uses. Houston and Dallas-Fort Worth anchor southwestern production capacity with concentrated plant locations serving multifamily REIT procurement.
Canada
Ontario and British Columbia building codes now recognize ICC-compliant modular assemblies, opening cross-border supply opportunities. Health Canada maintains national construction standards while provincial programs administer supplemental inspection protocols. Toronto and Vancouver metropolitan areas drive institutional procurement for dormitory blocks with long-term performance guarantees.
Mexico
Nuevo León and the Bajío Region attract nearshoring investment as US developers seek to compress transportation radius economics. The country's national housing commission operates construction standards distinct from ICC protocols, creating dual certification requirements. Monterrey industrial clusters serve border-state demand with assembly operations bridging factory fabrication and site installation.
North America Modular Construction Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated housing producers commanding manufactured home volumes while project-specific fabricators capture commercial and institutional work. The vendor base organizes around three strategic archetypes: captive finance networks controlling customer acquisition costs, timberland-backed producers insulating against input volatility, and regional specialists optimizing transportation radius economics. Dominant competitive moves include backward integration into lumber and appliance sourcing and direct-to-developer channel development bypassing general contractor markups.
Among North American modular fabricators, Clayton, Champion Home Builders, and Cavco Industries occupy distinct positions within the manufactured housing tier. Clayton represents the captive finance network archetype, leveraging retail lending infrastructure to control acquisition economics. Champion Home Builders exemplifies the input-hedging model through upstream control over timberland and appliance supply chains. Cavco Industries anchors southwestern production geography with concentrated plant locations in Arizona and Texas, optimizing for the 500-mile transportation radius that constrains volume module economics.
| Leading Market Players |
|---|
| ATCO Ltd. |
| Mobile Modular Management Corporation |
| Boxx Modular |
| Clayton |
| Aries Building Systems |
| Guerdon |
| Cavco Industries |
| Champion Home Builders |
| Westchester Modular Homes |
| Others |
Cost & Logistics Intelligence
Backward integration into captive timberland and appliance sourcing anchors both supply security and margin control for wood-framed modular producers operating across Texas, Florida, and California. This upstream control insulates Champion Home Builders from OSB volatility while enabling pricing discipline against spot-market competitors.
Pricing Analysis
Direct-to-developer channel development bypasses traditional general contractor markups that historically captured 15-20% of project value. Pricing stratifies across premium steel-concrete systems for mid-rise commercial, standard wood-framed multifamily, and economy HUD-code manufactured housing tiers. Cost compression in economy single-family segments intensifies as lumber input volatility compresses margins for non-integrated producers. School districts and healthcare networks show least price sensitivity, prioritizing speed-to-occupancy over first cost.
Supply Chain Analysis
Single-source vulnerability sits with Canadian softwood lumber suppliers subject to periodic trade remedy disputes. Factory production draws from dimensional lumber mills in British Columbia, OSB plants in the US Southeast, and cold-formed steel mills in Mexico's Monterrey industrial cluster. Tariff exposure on cross-border steel and lumber shipments creates margin unpredictability for border-state assemblers. Distribution runs through dedicated fleet operators serving 500-mile radiuses from concentrated plant locations in Arizona, Texas, and Florida.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American modular construction operates as a late-cycle quality story as healthcare and institutional buyers shift procurement criteria from first cost to 25-year lifecycle performance guarantees.
For Market Incumbents: Deepen captive finance network control to lock in customer acquisition economics against emerging fintech entrants offering modular construction loans. Champion Home Builders should expand Arizona plant capacity to defend southwestern market share as Cavco Industries consolidates regional production geography. Investment in California HCD and OSHPD engineering certification capabilities protects against project-specific review delays that threaten schedule certainty. For New Entrants and Emerging Players: Digital-channel direct procurement platforms offer the lowest-friction entry path for multifamily REITs and hospitality operators seeking to bypass general contractor markups. Ontario and British Columbia represent the most penetrable cross-border geography given ICC code recognition and underutilized northern US plant capacity. Embed factory quality managers into developer procurement teams to replicate incumbent trust relationships. For Investors and Strategic Acquirers: Roll-up economics work for regional specialists with optimized transportation radius coverage because factory-to-site distance constraints prevent national-scale pure-play dominance. Target mid-cap fabricators with captive fleet assets and established state modular administrative program certifications. Watch California Title 24 electrification mandate compliance rates as the signal indicating which factories can capture grid-interactive building envelope premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Timberland Acquisition | Champion Home Builders insulates OSB margin exposure through upstream lumber supply control. |
| Direct-to-Developer Channel Development | Bypassing general contractor markups captures 15-20% value previously lost to intermediaries. |
| Canadian Market Penetration | Ontario and British Columbia ICC code recognition enables cross-border supply without new capital deployment. |
| Grid-Interactive Envelope Integration | California Title 24 compliance differentiates factories shipping pre-wired battery and heat pump systems. |
| Long-Term Facilities Management Bundling | University dormitory contracts with 25-year performance guarantees shift vendor selection to lifecycle cost. |
Research Approach
Direct dialogue with modular factory operations directors, multifamily REIT procurement officers, state modular administrative program inspectors, and healthcare facilities capital planners grounded qualitative findings in operational reality. Secondary validation drew from HUD manufactured housing construction standards, EPA lead-safe renovation rule filings, California HCD inspection protocols, and Texas modular program administrative records. Bottom-up project pipeline tracking across 12 metropolitan areas triangulated against top-down macroeconomic indicators.
Segment-level revenue and volume trajectories across the analysis window reflect modeled interactions between labor scarcity intensity, transportation radius constraints, and state regulatory compliance costs. The analytical framework disaggregates permanent modules from relocatable structures, wood-framed from steel-concrete systems, and residential developer from healthcare facility end-use demand. CAGRs derive from regression-weighted capacity utilization trends and historical project completion velocity by state jurisdiction.
The model assumes a particular technology adoption path; alternative pathways for software-defined building management system integration would alter the outlook for premium asset valuations. Forecasts embed assumptions regarding ICC code harmonization progress and EPA enforcement intensity that regulatory shifts could revise. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
China Construction Market
Building Construction
Precast Construction Market
Building Construction
Swiss Prefabricated Buildings Market
Building Construction
Indonesia Construction Market
Building Construction
Indonesia Prefabricated Buildings Market
Building Construction
Germany Commercial Construction Market
Building Construction
Kuwait Construction Market
Building Construction
Australia Construction Market
Building Construction
GCC Cement Market
Building Construction
Dominican Republic Construction Market
Building Construction
Global Dry Construction Market
Building Construction
South Korea Data Center Construction Market
Building Construction
Poland Construction Market
Building Construction
UAE Prefab Wood Buildings Market
Building Construction
Vertical Garden Construction Market
Building Construction
United States Commercial Construction Market