
 Latin America Artificial Lift System Market | 2026-2036
Latin America Artificial Lift System Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Artificial Lift System Market Foresight
REACH is recalibrating the cost-of-entry calculus for artificial lift suppliers targeting Latin American export channels into Europe, forcing reformulation of elastomer and lubricant chemistries across the supply base. Baker Hughes Company leverages its integrated manufacturing footprint to pre-certify pump components against evolving chemical safety thresholds. Halliburton Company anchors its regional competitiveness through localized service infrastructure in Brazil and Mexico. Schlumberger Limited differentiates via proprietary digital lift optimization platforms that reduce intervention frequency in deepwater pre-salt applications.
Artificial lift systems encompass surface and downhole equipment engineered to augment hydrocarbon flow from reservoirs where natural drive pressure proves inadequate, with electric submersible pumps rated for operating temperatures exceeding 200°C and gas lift valves precision-machined to API 19G tolerances. These systems serve the primary commercial purpose of maximizing recovery rates from mature or low-permeability formations where primary production methods exhaust their economic utility. Rod lift configurations retain dominant share across Mexico's onshore stripper well population where low-volume, high-viscosity crude demands mechanical simplicity and minimal electrical infrastructure. Electric submersible pump demand accelerates fastest in Brazil's pre-salt developments where high bottomhole pressures and corrosive CO2-rich fluids necessitate metallurgically advanced multistage centrifugal designs. Hybrid lift architectures command concentrated margin pools where producers blend gas lift initiation with electric pump conversion to manage slugging and sand production across Venezuela's Orinoco Belt.
ANP, the Brazilian petroleum regulator, enforces escalating local content minimums for subsea and artificial lift equipment, redirecting procurement toward domestic fabrication partnerships and joint ventures. Mexico's ASEA imposes environmental compliance protocols on lift system fluids and surface containment, shaping product specifications for Permian-adjacent operators migrating southward. Colombia's ANH regulates well integrity standards that directly dictate artificial lift installation and workover frequencies. Stakeholders must monitor how regulatory divergence across Mercosur and Pacific Alliance frameworks fragments certification requirements and service standardization.
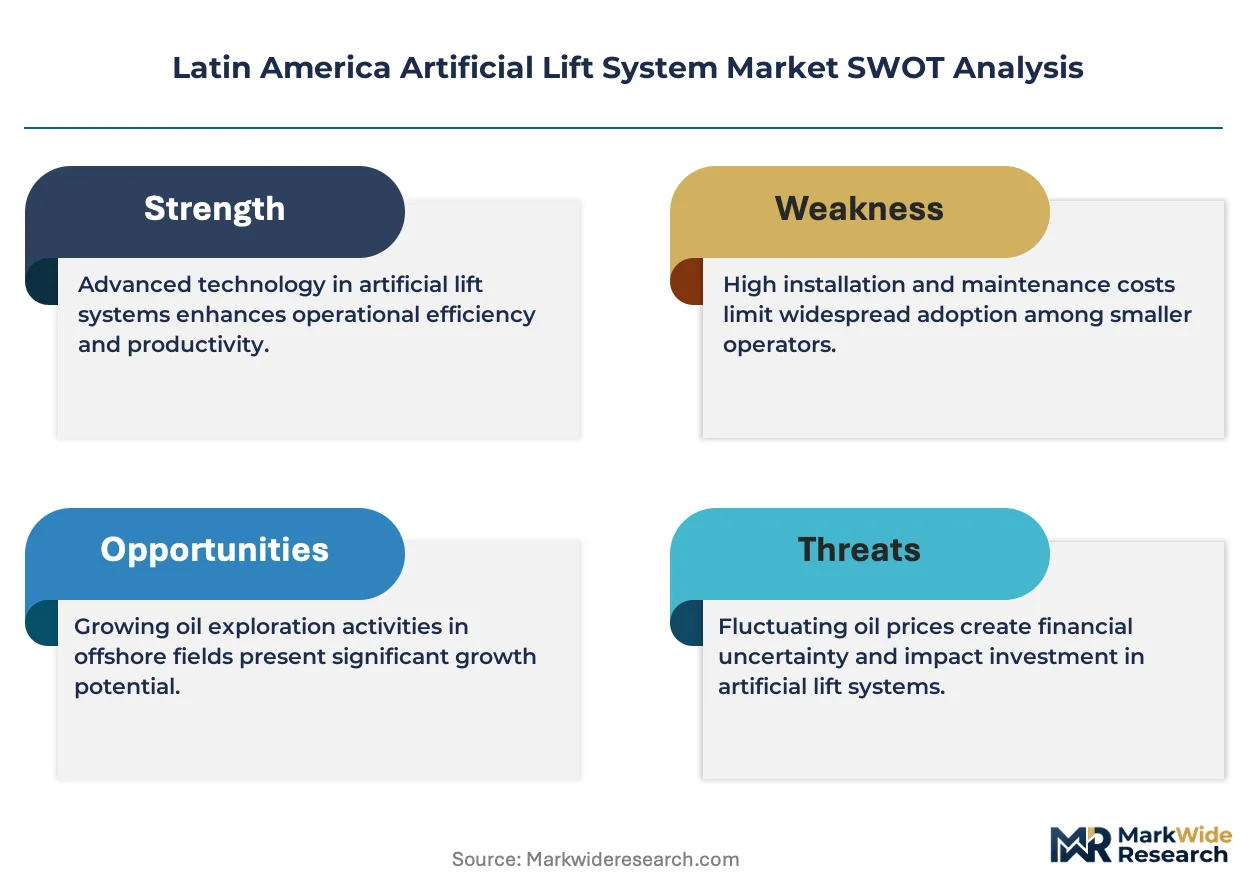
Market Dynamics
Brazil's ANP local content mandates are restructuring artificial lift procurement, forcing international suppliers into domestic fabrication partnerships while accelerating technology transfer requirements for pre-salt equipment.
Growth Catalysts
- Pre-salt reservoir complexity:Brazil's ultra-deepwater fields with bottomhole pressures exceeding 500 bar demand specialized metallurgy and multistage centrifugal designs that command premium service contracts.
- ANP regulatory escalation:Increasing local content minimums for subsea and artificial lift equipment redirect capital toward domestic joint ventures and certified fabrication facilities.
- Maturing onshore basins:Mexico's Cantarell and Ku-Maloob-Zaap fields require artificial lift conversion as natural drive pressure depletes, sustaining replacement demand for rod pump and gas lift systems.
Market Restraints
- Specialized alloy supply concentration:Duplex and super-duplex stainless steel sourcing for corrosive CO2-rich environments concentrates among Scandinavian and Japanese mills, exposing procurement to currency volatility and extended lead times.
- REACH chemical compliance:European export channels now demand reformulated elastomer and lubricant chemistries, raising R&D burdens for suppliers serving dual Latin American and European markets.
- Power infrastructure deficits:Remote Venezuelan and Colombian fields lack grid reliability for electric submersible pump deployment, constraining technology selection to mechanical lift alternatives.
Strategic Opportunities
- Digital lift optimization convergence:Integration of downhole sensors with edge computing platforms enables real-time gas-liquid ratio adjustment, reducing intervention frequency in Brazil's pre-salt cluster.
- Colombia's unconventional pivot:ANH regulatory frameworks for shale and tight sandstone formations create demand for hybrid lift architectures combining plunger lift initiation with progressive cavity pump conversion.
- Argentina's Vaca Muerta scale-up:Neuquén Basin operators seek artificial lift standardization across multi-pad developments, opening channel partnerships for integrated service providers.
Industry Challenges
- Deepwater completion engineering scarcity:Qualified specialists capable of integrating artificial lift with subsea trees and riser systems command compensation premiums that inflate project economics.
- Legacy wellbore compatibility:Pre-salt recompletion campaigns require retrofitting 7-inch production casing with slimhole pump configurations, complicating installation logistics and reliability forecasting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Artificial Lift System Market |
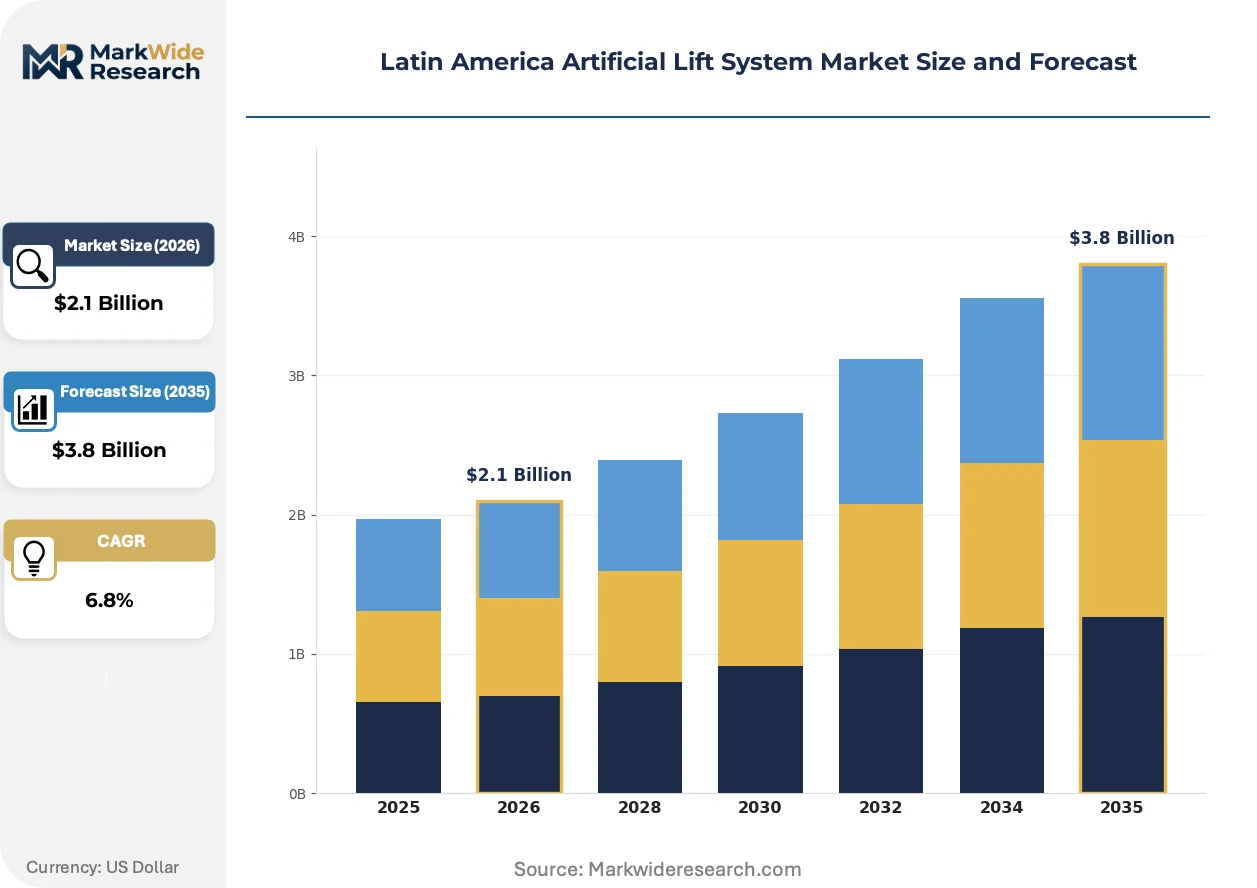
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Rod Pump, Electric Submersible Pump, Gas Lift, Progressive Cavity Pump Industry Vertical: Oil Production, Natural Gas Extraction, Water Management, Mining Technology: Mechanical Lift, Electrical Lift, Hybrid Lift, Pneumatic Lift End User: Independent Producers, National Oil Companies, Service Providers, Utilities |
| Companies Covered | Baker Hughes Company, National-Oilwell Varco, Inc., Halliburton Company, Schlumberger Limited, Novomet Group, Weatherford International Ltd, Borets Company Llc, Dover Artificial Lift, Llc, General Electric Co., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Artificial Lift System Market Shifts & Advancements
Artificial lift technology trajectories center on modularity, chemical compliance, and procurement restructuring as operators seek to compress capital cycles and satisfy evolving regulatory thresholds across Brazilian and Mexican jurisdictions.
Electric submersible pump systems are modularizing into standardized cartridge subassemblies that permit rapid downhole replacement without full workover rig mobilization. Petrobras and its pre-salt partners are piloting these configurations to reduce non-productive time in ultra-deepwater environments. The approach compresses maintenance windows from weeks to days, fundamentally altering service contract economics and supplier liability structures.
ANP's escalating local content framework is forcing technology localization decisions that reshape competitive positioning. Foreign suppliers must now certify domestic fabrication partnerships to qualify for pre-salt procurement rounds, accelerating joint venture formation and knowledge transfer obligations. Equipment categories with the highest local content thresholds—subsea manifolds and high-pressure pumps—experience the most acute supplier restructuring.
Lease-versus-own models for artificial lift equipment are displacing traditional capital purchase arrangements among Mexico's Pemex-adjacent independents. Smaller operators in the Burgos Basin favor rental structures that transfer downhole reliability risk to service companies while preserving balance sheet flexibility. This behavioral shift concentrates in regions where capital access constraints intersect with reservoir uncertainty, particularly Permian-adjacent plays migrating southward.
Latin America Artificial Lift System Market Segmentation
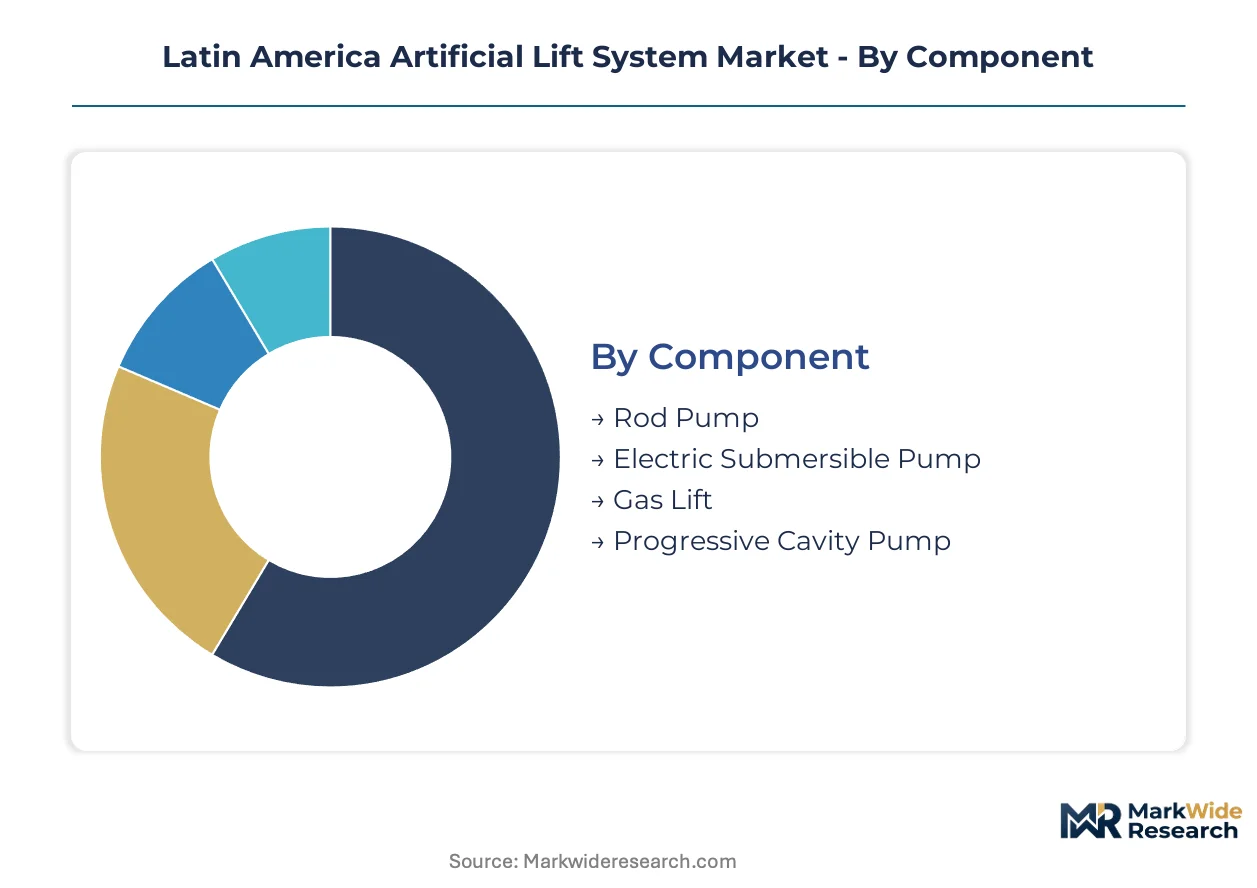
Artificial lift system segmentation in Latin America reflects divergent reservoir conditions across Brazil's pre-salt depths and Mexico's mature onshore fields. Component selection varies sharply between standalone mechanical installations and integrated electrical architectures that demand subsea power infrastructure.
Component:
Rod pump and electric submersible pump systems operate as standalone installations in shallow onshore fields, while gas lift and progressive cavity configurations embed within broader production networks requiring surface compression or downhole drive systems.
- Electric Submersible Pump:Multistage centrifugal assemblies rated for bottomhole pressures exceeding 500 bar handle corrosive CO2-rich fluids in Brazil's pre-salt cluster. Petrobras mandates metallurgically advanced designs with super-duplex stainless steel construction for ultra-deepwater completions where intervention costs dwarf equipment capital.
- Rod Pump:Beam-pump configurations dominate Mexico's Cantarell and Ku-Maloob-Zaap fields where mechanical simplicity offsets declining reservoir pressure. Stripper well operators favor this technology for high-viscosity crude production with minimal electrical infrastructure requirements.
- Gas Lift:Compression-dependent systems suit Venezuelan Orinoco Belt developments where gas availability and surface facility integration drive selection.
- Progressive Cavity Pump:Positive displacement pumps handle heavy oil and sand-laden production in Colombia's Llanos Basin unconventional plays.
Electric submersible pump leads volumes today; progressive cavity pump is gaining share fastest.
Industry Vertical:
Cost tier differentiation separates capital-intensive offshore oil developments from margin-constrained water management applications where equipment standardization dominates procurement.
- Oil Production:Artificial lift constitutes essential production infrastructure for mature fields where natural drive pressure depletes. Brazil's pre-salt developments command premium service contracts with specialized metallurgy and digital monitoring integration.
- Natural Gas Extraction:Liquid loading mitigation in gas wells drives plunger lift and velocity string installations across Argentina's Neuquén Basin tight sandstone formations.
- Water Management:Produced water handling and disposal well applications utilize standardized pump configurations with lower specification thresholds than hydrocarbon service.
- Mining:Dewatering operations in Chilean copper and Peruvian polymetallic deposits deploy robust pump systems for pit and underground mine drainage.
Oil production anchors revenue concentration; natural gas extraction exhibits the steepest expansion trajectory.
Technology:
Application context determines whether lift systems deploy as pure mechanical, electrical, or blended architectures, with hybrid configurations commanding concentrated margin pools in complex reservoir conditions.
- Mechanical Lift:Sucker rod and beam-pump systems serve low-volume, high-viscosity production with minimal operational complexity. Mexico's onshore stripper well population retains dominant mechanical lift share due to infrastructure constraints and crude characteristics.
- Electrical Lift:Submersible motor-pump assemblies integrate with downhole sensors and surface variable speed drives for real-time optimization. Brazil's pre-salt fields require electrical lift for high-pressure, high-temperature conditions inaccessible to mechanical alternatives.
- Hybrid Lift:Gas lift initiation followed by electric pump conversion manages slugging and sand production across Venezuela's heavy oil belt. Operators blend technologies to match evolving reservoir conditions without full workover requirements.
- Pneumatic Lift:Compressed gas and plunger systems address liquid loading in gas wells with intermittent production profiles.
Mechanical lift retains installed base dominance; hybrid lift climbs the fastest as operators seek flexibility.
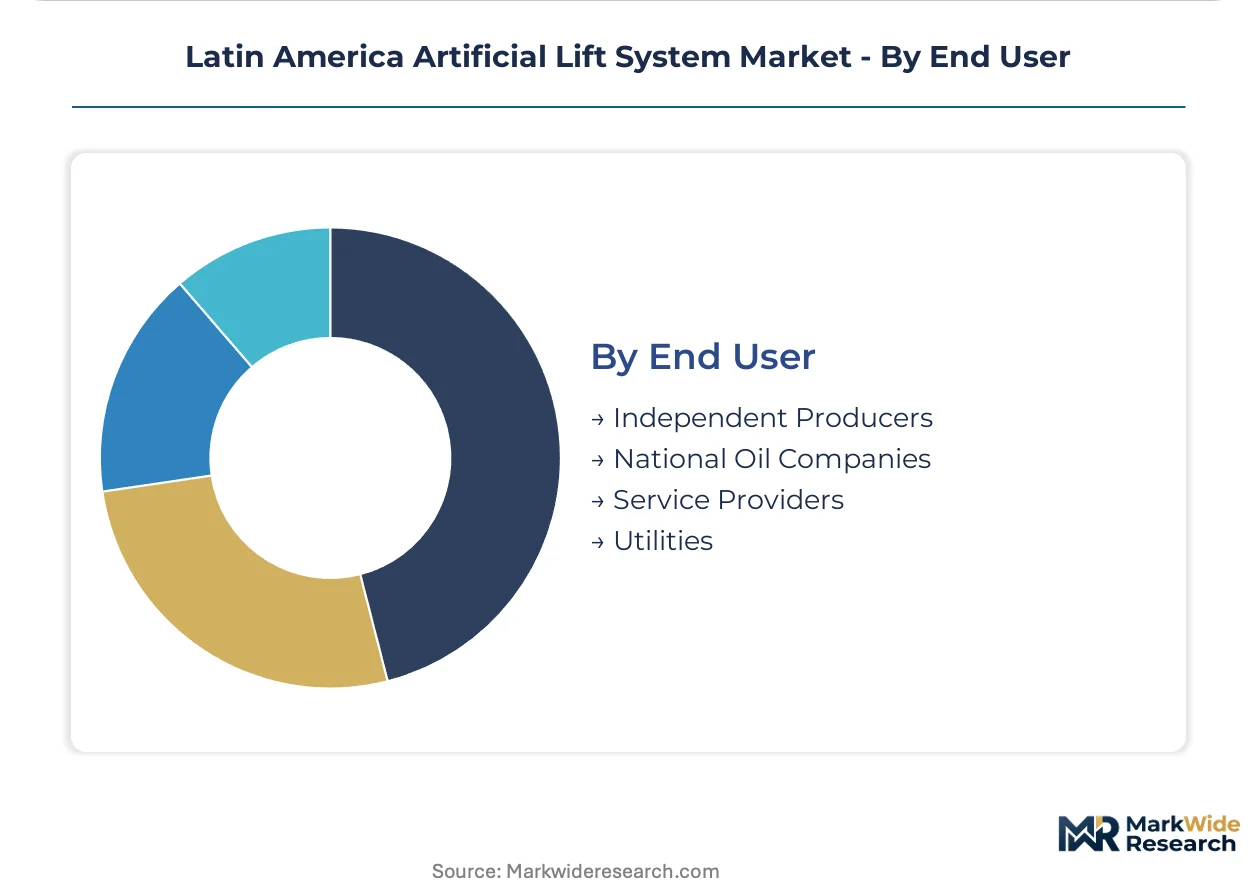
End User:
Customer type segmentation tracks procurement authority concentration, with national oil companies driving specification standards that cascade through independent producer and service provider channels.
- National Oil Companies:Petrobras and Pemex dictate regional technology roadmaps through pre-salt and mature field investment programs. ANP local content mandates force supplier restructuring toward domestic fabrication partnerships.
- Independent Producers:Burgos Basin and Vaca Muerta operators favor lease-versus-own equipment arrangements that transfer downhole reliability risk to service companies. Capital access constraints drive rental model adoption among smaller entrants.
- Service Providers:Integrated oilfield services companies bundle artificial lift within broader production optimization contracts, capturing recurring revenue through maintenance and intervention services.
- Utilities:Power generation and industrial water users deploy lift technology for cooling water and process fluid management outside hydrocarbon extraction.
National oil companies lead capital deployment; independent producers are expanding procurement most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrobras employs over 45,000 engineers and technicians across Brazil, anchoring Latin America's deepest reservoir expertise concentration. This workforce density shapes regional technology diffusion patterns and supplier qualification standards.
Brazil
Pre-salt basin developments drive specialized electric submersible pump demand where bottomhole pressures exceed 500 bar. ANP local content mandates force international suppliers into domestic fabrication joint ventures. Macaé and Rio de Janeiro host the primary equipment certification and assembly clusters serving ultra-deepwater completions.
Mexico
Cantarell and Ku-Maloob-Zaap maturation sustains rod pump and gas lift replacement cycles. ASEA environmental compliance protocols reshape fluid specifications for Permian-adjacent operators. Ciudad del Carmen concentrates service provider infrastructure for southern Gulf of Mexico workover campaigns.
Argentina
Vaca Muerta shale scale-up demands artificial lift standardization across multi-pad developments. Neuquén provincial authorities coordinate with national regulators on well integrity standards. The Neuquén Basin itself clusters drilling and completion service capacity for unconventional production ramp.
Colombia
Llanos Basin heavy oil and unconventional tight sandstone plays expand progressive cavity pump and hybrid lift deployment. ANH well integrity regulations dictate installation frequencies and workover protocols. Villavicencio anchors the primary service logistics hub for eastern piedmont operations.
Venezuela
Orinoco Belt heavy oil production relies on gas lift initiation and electric pump conversion architectures. Power infrastructure deficits constrain electrical lift penetration outside grid-adjacent fields. Puerto La Cruz maintains residual fabrication capacity for downhole pump assembly and repair.
Latin America Artificial Lift System Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Latin America's artificial lift procurement channels. The market structure concentrates around integrated oilfield service providers with pre-certified local content partnerships. Three archetypes dominate: full-service multinationals with manufacturing footprints, regional specialists with ANP-certified fabrication alliances, and equipment-lessors capturing Pemex-adjacent independents. Competitive moves center on domestic joint venture formation and digital platform integration rather than price-led expansion.
Among US-based integrated service providers, Baker Hughes Company, Halliburton Company, and Schlumberger Limited exemplify the full-service archetype. These entities occupy positions defined by pre-existing ANP certification pathways and localized engineering presence. Their competitive posture reflects the premium-tier vector where metallurgical specialization and subsea integration capabilities determine contract eligibility. Russian and European specialists including Novomet Group and Borets Company Llc sit within the focused equipment tier, anchoring regional market segments through technology licensing arrangements rather than direct fabrication investment.
| Leading Market Players |
|---|
| Baker Hughes Company |
| National-Oilwell Varco, Inc. |
| Halliburton Company |
| Schlumberger Limited |
| Novomet Group |
| Weatherford International Ltd |
| Borets Company Llc |
| Dover Artificial Lift, Llc |
| General Electric Co. |
| Others |
Supply & Pricing Matrix
ANP local content mandates in Brazil are forcing international suppliers into domestic fabrication partnerships, compressing procurement timelines while elevating qualification costs that suppliers must recover through premium service contract structures.
Pricing Analysis
The bundled-versus-unbundled service split defines contract economics across Latin American procurement channels. Full-service contracts integrating equipment supply with maintenance and intervention services command premium positioning against standalone equipment sales. Price differentiation rests on metallurgical certification grade and digital monitoring integration depth. Cost compression in standard rod pump configurations is intensifying as Mexican independents migrate toward lease-versus-own rental structures. National oil companies exhibit lowest price sensitivity given pre-salt intervention cost exposure, while Burgos Basin independents prioritize balance sheet flexibility over ownership.
Supply Chain Analysis
ANP certification gating restricts qualified fabrication to Macaé and Rio de Janeiro industrial clusters, concentrating supply chain control among pre-certified joint venture partners. Super-duplex stainless steel draws from Scandinavian and Japanese mill sources, creating raw material dependencies outside regional control. Single-source vulnerability concentrates in specialized alloy procurement for corrosive CO2-rich pre-salt environments. Distribution runs through integrated service provider networks rather than independent equipment distributors, with Baker Hughes and Halliburton controlling primary logistics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ANP escalating local content thresholds continuously restructure supplier economics and procurement access.
For Market Incumbents: Anchor competitive position through ANP-certified domestic fabrication capacity expansion in Macaé and Rio de Janeiro. Deepen backward integration into super-duplex alloy sourcing through long-term offtake agreements with Scandinavian mills. Digital lift optimization platforms represent the critical defensive lever against modular equipment specialists threatening service contract renewal rates. For New Entrants and Emerging Players: ANP local content mandates in Brazil open a window for joint venture formation with established domestic fabricators lacking subsea pump technology licensing. Colombia's ANH unconventional pivot presents the most penetrable white-space target for hybrid lift architecture specialists. Lease-versus-own rental models offer the strongest go-to-market angle for Pemex-adjacent independents in Mexico's Burgos Basin. For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists holding ANP certification pathways and digital platform integration capabilities. Five-to-ten year viability favors equipment providers with captive service revenue streams rather than pure manufacturing plays. Watch Petrobras pre-salt procurement round timing as the critical inflection signal for capacity utilization and pricing power restoration.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Fabrication Joint Venture | ANP certification unlocks pre-salt procurement access for international technology licensors. |
| Digital Lift Platform Integration | Real-time optimization reduces intervention frequency in Brazil's ultra-deepwater pre-salt cluster. |
| Super-Duplex Alloy Supply Agreement | Long-term offtake secures metallurgical inputs for corrosive CO2-rich production environments. |
| Lease-Versus-Own Model Expansion | Rental structures transfer reliability risk and attract capital-constrained Mexican independents. |
| Hybrid Lift Architecture Development | Gas-to-electric conversion systems capture Venezuela Orinoco Belt heavy oil demand. |
Research Methodology
Coverage spans Brazil, Mexico, Argentina, Colombia, and Venezuela, with primary inputs from each market's artificial lift procurement channels. The research combines structured interviews with Petrobras and Pemex engineering directors, ANP certification officers, integrated service provider account managers, and independent producer procurement leads with secondary validation through ANP regulatory filings, SEC 10-K disclosures from listed service providers, and Brazilian trade association equipment shipment data. Bottom-up field-level demand estimates triangulate against top-down national production forecasts.
Granularity-level modeling distinguishes between pre-salt ultra-deepwater, mature onshore, and unconventional shale applications across the projection horizon. Segmentation dimensions include lift technology type, metallurgical specification tier, digital integration depth, and end-user procurement authority concentration. CAGRs derive from production decline curve analysis and replacement cycle modeling. Forecast inputs incorporate ANH well integrity regulation evolution and Vaca Muerta multi-pad development scaling assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged power infrastructure deficits in Venezuela and Colombia or accelerated ANP local content threshold escalation. Forecasts reflect documented assumptions regarding Petrobras capital commitment continuity and super-duplex alloy supply chain stability. A model refresh is warranted upon material change in ANP regulatory enforcement intensity or pre-salt production plateau timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Well Completion Market
Oil & Gas
Rotary Steerable System Market
Oil & Gas
Intelligent Completion Sales Market
Oil & Gas
Digital Drilling Rigs Market
Oil & Gas
Kuwait Oil and Gas Market
Oil & Gas
Sudan Oil and Gas Market
Oil & Gas
Cased Hole Logging Services Market
Oil & Gas
Well Testing Services Market
Oil & Gas
Europe Seismic Survey Market
Oil & Gas
South America Deep Water and Ultra Deep Water Exploration and Production (Eandp) Market
Oil & Gas
India Oil and Gas Market
Oil & Gas
Oil and Gas Data Monetization Market
Oil & Gas
Oil Hose Market
Oil & Gas
Oil and Gas Storage Market
Oil & Gas
Oil Storage Terminal Market
Oil & Gas
Wired Drill Pipe Sales Market