
 North America Artificial Lift Systems Market | 2026-2036
North America Artificial Lift Systems Market Size, Share, and Industry Trends Forecast 2026-2036
North America Artificial Lift Systems Market Analytics
Modular skid-mounted artificial lift packages is hardening as the default procurement format across tight-oil fields. Halliburton Company leverages its integrated well-construction portfolio to bundle artificial lift with completions services. Baker Hughes Company sustains technology leadership through permanent magnet motor designs for electric submersible pumps. ChampionX anchors its position in chemical-enhanced recovery systems tied to rod lift optimization.
Artificial lift systems are mechanical devices that increase reservoir pressure to sustain or boost hydrocarbon flow to surface, typically operating at depths exceeding 10,000 feet with bottom-hole temperatures above 300°F in North American shale plays. Their primary commercial purpose is maximizing recovery rates from mature or low-pressure wells where natural drive energy proves insufficient. Electric submersible pump technology dominates high-volume unconventional applications while rod pumping retains cost advantages in stripper-well portfolios. Gas lift configurations are expanding fastest in deepwater Gulf of Mexico developments where platform space constraints favor minimal surface footprint. Progressive cavity pump demand clusters in heavy-oil thermal recovery projects across Alberta's oil sands regions.
The EPA enforces methane monitoring requirements under NSPS OOOOa that compel operators to specify sealed bearing systems and vapor recovery units on artificial lift installations. The Pipeline and Hazardous Materials Safety Administration governs surface facility pressure integrity, shaping material specifications for wellhead and flowline connections. Alberta Energy Regulator Directive 060 imposes venting limits that drive gas-lift compressor upgrades and pneumatic device replacements across Canadian operations. Stakeholders must weigh the trade-off between capital efficiency in standardized pump designs and the operational flexibility that modular, digitally instrumented systems provide for declining well profiles.
Market Dynamics
The EPA's NSPS OOOOa methane regulations are forcing operators to retire pneumatic-driven lift systems and retrofit sealed bearing architectures across Permian and Bakken well pads. This compliance-driven equipment refresh cycle now dominates capital allocation decisions more than reservoir performance optimization alone.
Growth Catalysts
- Shale decline-curve acceleration:Tight-oil wells in the Permian Basin and Eagle Ford experience 60-70% first-year production drops, mandating earlier artificial lift deployment to maintain plateau rates.
- EPA NSPS OOOOa compliance mandates:Methane monitoring requirements compel operators to specify vapor recovery units and low-emission compressor packages on new installations.
- Digital twin integration:Real-time downhole sensor networks enable predictive failure modeling that extends run-life of electric submersible pumps by 15-25%.
Market Restraints
- Specialized metallurgy cost inflation:Nickel-based alloys and tungsten carbide coatings for high-temperature ESP stages face supply bottlenecks from concentrated superalloy foundries.
- Permian infrastructure saturation:Limited electrical substation capacity constrains ESP power-upgrades in West Texas sub-basins where grid expansion lags drilling activity.
- Rod lift displacement limits:Heavy crude viscosity above 10,000 cP in Cold Lake thermal projects restricts beam-pump applicability regardless of cost advantages.
Strategic Opportunities
- Alberta thermal SAGD expansion:Progressive cavity pump demand clusters around steam-assisted gravity drainage projects where multiphase handling exceeds centrifugal pump capability.
- Modular skid standardization:Pre-engineered plug-and-play lift packages reduce field installation time from weeks to days, opening marginal well economics in North Dakota's declining legacy fields.
- Canadian carbon intensity accounting:Alberta's TIER regulation rewards operators for electrified lift systems that displace gas-engine prime movers with grid or renewable power.
Industry Challenges
- Downhole electronics reliability:Permanent magnet motor drives and sensor arrays fail at rates exceeding 8% annually in 300°F+ thermal environments, requiring redundant telemetry architectures.
- Cross-vendor integration complexity:Operators mixing ESP hardware from Schlumberger with variable frequency drives from ABB encounter communication protocol mismatches that delay commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Artificial Lift Systems Market |
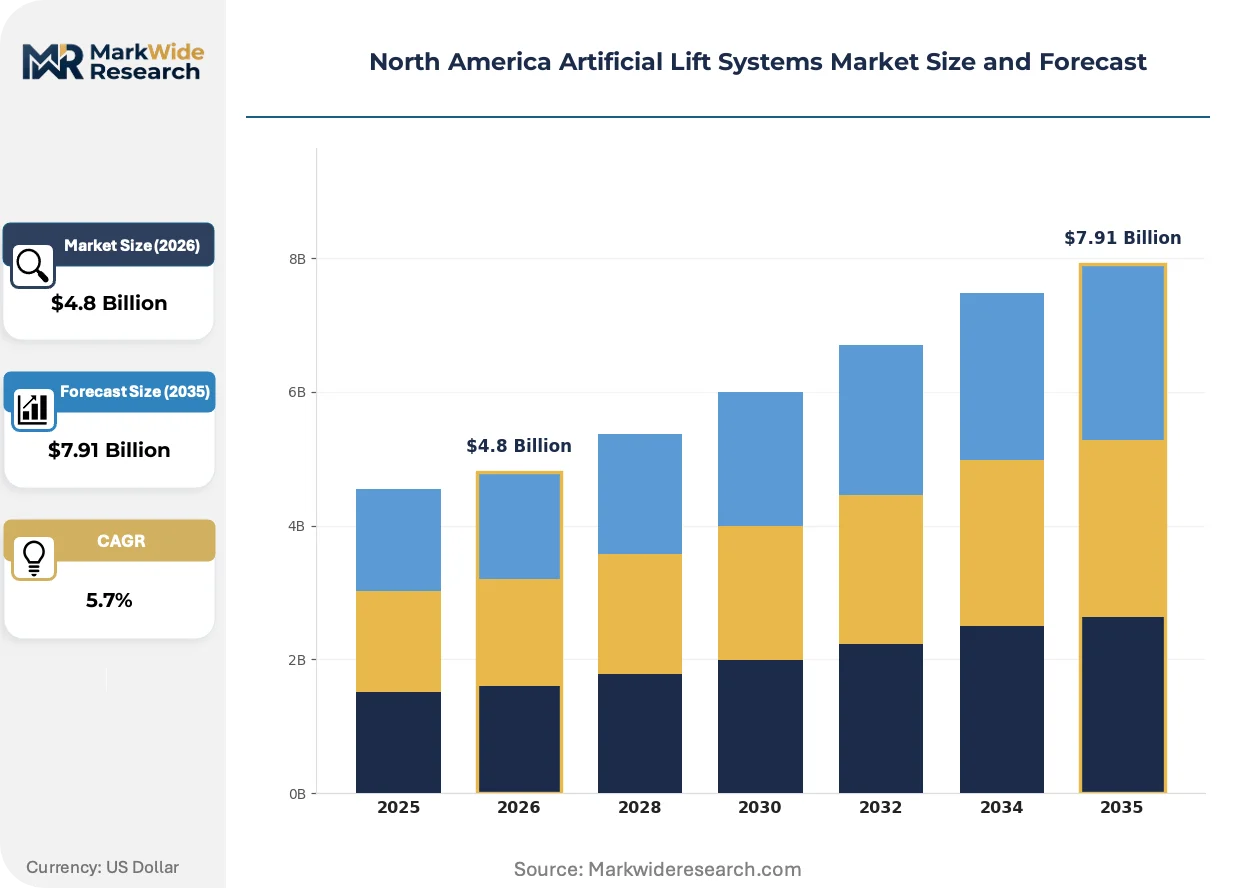
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Rod Pumping, Electric Submersible Pump, Gas Lift, Progressive Cavity Pump Installation Type: Onshore, Offshore, Fixed Platform, Floating Platform End User: Oil & Gas Producers, Water Utilities, Manufacturing Plants, Chemical Industry Application: Oil Recovery, Water Injection, Geothermal Energy, Wastewater Management |
| Companies Covered | Halliburton Company, Schlumberger Limited, Baker Hughes Company, Weatherford International plc, JJ Tech, DistributionNow, NOV, Inc., ChampionX, Dover Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Artificial Lift Systems Market Evolving Landscape
Equipment intelligence and emissions accountability are converging to redefine supplier value propositions. Vendors now compete on integrated lifecycle emissions profiles and predictive uptime guarantees rather than standalone pump efficiency metrics.
Permanent magnet motor technology is unifying power density and thermal tolerance in next-generation electric submersible pumps. Unconventional operators in the Delaware Basin are adopting these systems at 40% faster replacement cycles than conventional induction motors. The technology is unifying previously separate motor and seal sections into single-housing architectures that reduce failure points and enable slimmer wellbore designs.
The EPA's NSPS OOOOa enforcement timeline compresses pneumatic device retirement schedules across Texas and New Mexico oilfields. Operators must install continuous methane monitoring and sealed bearing systems on all new lift installations by specified compliance windows. Gulf of Mexico platform operators face the tightest retrofit deadlines, driving demand for integrated vapor recovery compressor packages from specialized fabricators.
Integrated service contracting now bundles artificial lift hardware with chemical treatment programs and remote diagnostics. Large Permian independents are displacing transactional equipment purchases with performance-based agreements where suppliers guarantee production uptime. This restructuring concentrates procurement authority among fewer integrated vendors and shifts technical risk from operator balance sheets to service company engineering teams.
North America Artificial Lift Systems Market Segmentation
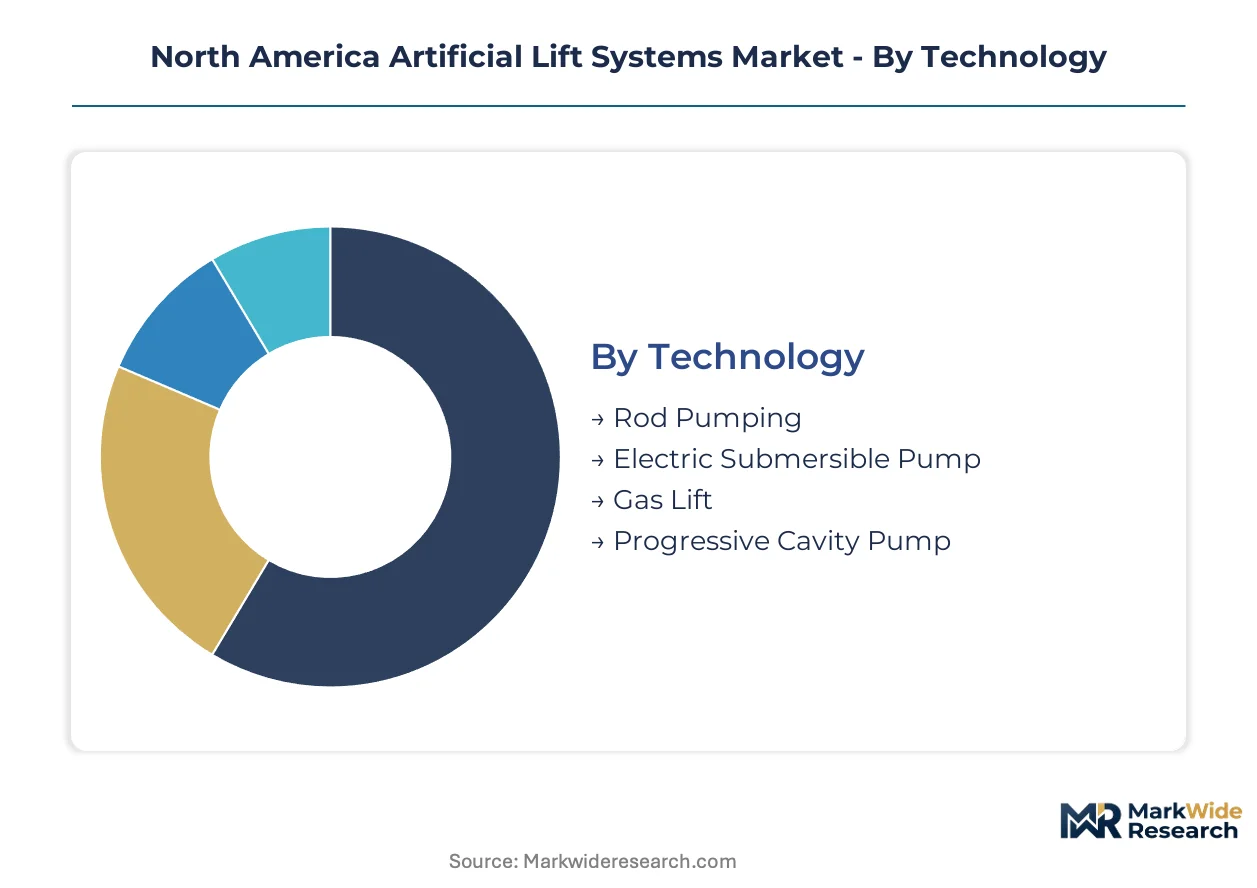
Artificial lift procurement decisions in North America hinge on reservoir characteristics, surface constraints, and regulatory exposure. Operators weight capital intensity against decline-curve steepness and emissions compliance burdens when selecting system architectures.
Technology:
Buyers prioritize flow-rate requirements and bottom-hole temperature tolerance when specifying lift mechanisms.
- Electric Submersible Pump:Centrifugal multistage configurations handle high-volume unconventional wells in the Permian Basin and Eagle Ford. Delaware Basin operators favor permanent magnet motor variants for power density in slim-hole laterals where induction motor bulk restricts deployment.
- Rod Pumping:Beam-pump assemblies dominate stripper-well portfolios across West Texas and North Dakota legacy fields. Low capital cost and field-proven repair infrastructure offset efficiency limitations in sub-100 barrel-per-day applications.
- Gas Lift:Annular injection systems minimize surface footprint on Gulf of Mexico platforms where deck space commands premium valuations. Compressor reliability and methane containment under EPA NSPS OOOOa drive specification decisions.
- Progressive Cavity Pump:Helical rotor-stator pairs manage multiphase flow in Alberta SAGD thermal projects where steam-oil ratios challenge centrifugal pump tolerance. Heavy crude viscosity above 10,000 cP necessitates positive displacement mechanics.
Electric Submersible Pump leads on scale; Progressive Cavity Pump leads on momentum in thermal recovery expansions.
Installation Type:
Surface infrastructure availability and regulatory jurisdiction shape deployment modality selection.
- Onshore:Pad-mounted skid packages predominate across Permian and Bakken tight-oil developments. Grid access constraints in West Texas sub-basins favor modular diesel-electric hybrid configurations pending substation expansion.
- Offshore:Subsea boosting stations extend tieback distances in deepwater Gulf of Mexico fields. High-pressure riser dynamics and platform abandonment liability timelines influence lift system redundancy specifications.
- Fixed Platform:Jacket-supported structures in shallower federal waters accommodate conventional beam-pump and gas-lift compressor arrays. Weight allowances and crane capacity bound equipment swap-out logistics.
- Floating Platform:Tension-leg and spar hulls in ultra-deepwater employ subsea ESP installations with surface variable frequency drives. Vessel motion compensation and dynamic umbilical management add engineering complexity.
Onshore commands deployment volume; Offshore commands capital intensity per installation.
End User:
Production economics and regulatory exposure differentiate buyer priorities across sectors.
- Oil & Gas Producers:Integrated majors and Permian independents specify lift systems under performance-based contracting where suppliers guarantee uptime. Methane intensity metrics under EPA and Alberta TIER regulations now penetrate procurement scorecards.
- Water Utilities:Municipal groundwater extraction operations in the Ogallala and Central Valley aquifers deploy submersible pumps for agricultural supply security. Energy efficiency standards and drawdown permitting constrain equipment selection.
- Manufacturing Plants:Industrial process water and cooling tower recirculation applications favor standardized centrifugal configurations. Reliability-centered maintenance programs prioritize mean-time-between-failures over initial capital cost.
- Chemical Industry:Corrosive fluid handling in Texas Gulf Coast petrochemical complexes demands specialty metallurgy and sealed bearing architectures. Process safety management regulations govern pressure boundary integrity.
Oil & Gas Producers dominate equipment demand; Water Utilities present steadiest replacement-cycle visibility.
Application:
Fluid properties and recovery objectives determine system design specifications.
- Oil Recovery:Primary, secondary, and tertiary production phases each impose distinct lift requirements. Decline-curve management in unconventional shale drives fastest equipment replacement cycles industry-wide.
- Water Injection:Pressure maintenance programs in mature Texas and Oklahoma fields utilize high-pressure centrifugal pumps for reservoir voidage replacement. Corrosion inhibition and solids filtration protect downhole formation integrity.
- Geothermal Energy:Binary cycle and flash steam plants in Nevada and California extract brine at temperatures exceeding 300°F. Scale deposition and non-condensable gas handling challenge conventional pump metallurgy.
- Wastewater Management:Produced water disposal and recycling infrastructure across the Permian employs multistage centrifugal systems for saltwater disposal well injection. Seismicity protocols in Texas Railroad Commission jurisdictions constrain injection pressure limits.
Oil Recovery anchors installed base; Geothermal Energy exhibits steepest expansion trajectory as baseload renewable development accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The artificial lift industry traces its modern scaling to the Permian Basin of West Texas in the 1940s, where beam-pump standardization for stripper-well economics established North American engineering templates later exported worldwide.
United States
Permian Basin operators deploy electric submersible pumps across Delaware and Midland sub-basins to combat 60-70% first-year decline curves in tight-oil laterals. The EPA's NSPS OOOOa methane regulations mandate sealed bearing retrofits and vapor recovery units on all new installations across Texas and New Mexico. West Texas electrical substation saturation constrains ESP power upgrades in Reeves and Culberson counties where grid expansion lags drilling activity.
Canada
Alberta's steam-assisted gravity drainage projects drive progressive cavity pump demand for multiphase handling where steam-oil ratios exceed centrifugal pump tolerance. The Alberta Energy Regulator's Directive 060 imposes venting limits that accelerate gas-lift compressor upgrades and pneumatic device replacements across thermal recovery operations. Cold Lake and Peace River thermal clusters anchor heavy-oil artificial lift procurement, with Fort McMurray SAGD expansions requiring specialized high-viscosity handling systems.
Mexico
Chicontepec Basin mature field rehabilitation programs specify rod-lift conversions for low-pressure carbonate reservoirs where natural drive energy has depleted. The Comisión Nacional de Hidrocarburos regulates upstream equipment standards for foreign-operated blocks under energy reform contracts. Burgos Basin shale pilots in Nuevo León and Tamaulipas test ESP configurations for tight-gas condensate recovery, drawing on Permian engineering templates adapted for Mexican surface infrastructure constraints.
North America Artificial Lift Systems Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth, with bundled service-and-equipment contracts commanding pricing power over standalone hardware transactions. The vendor base concentrates among integrated oilfield service conglomerates and specialized lift technology boutiques, with mid-tier fabricators occupying pressure on both flanks. Three archetypes dominate: full-cycle service integrators bundling lift with completions and intervention; pure-play lift specialists optimizing single-technology depth; and diversified industrial conglomerates leveraging manufacturing scale across adjacent pump markets. Consolidation through asset-level acquisitions and strategic technology licensing agreements represents the dominant competitive dynamic, alongside vertical integration into permanent magnet motor manufacturing and predictive analytics software.
Within the integrated service tier, Halliburton Company and Schlumberger Limited exemplify full-cycle positioning that anchors procurement relationships through bundled well-construction and artificial lift offerings. Baker Hughes Company occupies a technology-leadership position represented by permanent magnet motor architectures for electric submersible pump applications. ChampionX exemplifies the specialized chemical-and-lift convergence archetype, with its positioning in rod-lift optimization systems tied to production chemistry programs.
| Leading Market Players |
|---|
| Halliburton Company |
| Schlumberger Limited |
| Baker Hughes Company |
| Weatherford International plc |
| JJ Tech |
| DistributionNow |
| NOV, Inc. |
| ChampionX |
| Dover Corporation |
| Others |
Value Network & Pricing Analysis
London Metal Exchange nickel price volatility cascades through permanent magnet motor supply chains into three-tier equipment pricing across North American artificial lift markets. Premium ESP systems with sealed bearing architectures command margin separation from standard induction motor configurations as superalloy foundry capacity tightens.
Pricing Analysis
Performance-based contracting structures now dominate procurement relationships across Permian Basin independents. Price differentiation hinges on EPA NSPS OOOOa compliance bundling and predictive uptime guarantees rather than standalone hardware efficiency metrics. Cost compression in standard rod-lift configurations intensifies as commodity fabricators crowd the stripper-well segment. Small-scale operators in North Dakota legacy fields exhibit highest price sensitivity; integrated majors prioritize total cost of ownership over capital expenditure minimization.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare earth processing for neodymium permanent magnet feedstock. Manufacturing concentration spans China for magnet alloys, Germany for precision bearing systems, and domestic Texas fabrication for skid-mounted packages. Raw material dependencies include nickel-based superalloys, tungsten carbide coatings, and high-temperature elastomers. Tariff exposure on Chinese magnet materials threatens cost stability for next-generation ESP motor architectures. Distribution runs through Halliburton and Schlumberger integrated service networks, with independent distributors serving marginal well operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in digitally instrumented lift packages where sensor telemetry and predictive analytics justify premium pricing. Permanent magnet motor standardization and modular skid fabrication drive unit cost reduction across high-volume unconventional deployments.
For Market Incumbents: Deepen captive supply arrangements for rare earth magnet alloys to insulate against Chinese export restriction scenarios. Expand permanent magnet motor manufacturing footprint in Texas to exploit proximity advantages for Permian Basin operators. Reinforce service density in Delaware Basin sub-basins where electrical infrastructure constraints favor integrated power-and-lift bundling. Counter emerging pure-play digital diagnostics specialists through proprietary telemetry platform standardization. For New Entrants and Emerging Players: Begin with geothermal energy lift applications in Nevada and California where conventional oilfield service networks maintain limited presence. Target binary cycle brine extraction projects where scale-tolerant metallurgy requirements exceed standard ESP specifications. Exploit regulatory tailwinds from California geothermal development mandates. Pursue equipment-as-a-service revenue models that transfer performance risk from capital-constrained developers. For Investors and Strategic Acquirers: Consolidation pressure builds where sub-scale fabricators lack backward integration into permanent magnet supply chains. Long-term viability favors vendors with integrated chemical treatment and lift optimization capabilities spanning the full production lifecycle. Acquisition targets include specialized downhole sensor developers with 300°F+ reliability validation. Monitor EPA enforcement intensity around NSPS OOOOa retrofit deadlines as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Motor Manufacturing Scale-Up | Captures power density advantages for slim-hole lateral deployments in Delaware Basin. |
| Integrated Vapor Recovery Compressor Packaging | Addresses EPA NSPS OOOOa compliance mandates across Gulf of Mexico platform retrofits. |
| Predictive Diagnostics Platform Development | Extends ESP run-life through real-time failure modeling for Permian operators. |
| Alberta SAGD Thermal Recovery Specialization | Aligns with steam-assisted gravity drainage expansion in Cold Lake and Peace River clusters. |
| Modular Skid Standardization Program | Reduces field installation time for marginal well economics in declining North Dakota legacy fields. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct bottom-up and top-down market estimates. Primary research engaged artificial lift engineering directors at Permian independents, ESP procurement leads at integrated majors, Alberta thermal project managers, and aftermarket service heads at regional distributors. Secondary validation drew from EPA regulatory filings, EIA drilling productivity reports, Alberta Energy Regulator directives, and SEC 10-K equipment revenue disclosures.
Historical reference periods anchored the projection horizon through trend extrapolation and driver elasticity modeling. Segmentation dimensions included lift technology type, installation modality, end-user sector, and application phase across oil recovery, water injection, and geothermal extraction. CAGRs derived from equipment replacement cycle analysis, regulatory compliance-driven refresh schedules, and unconventional decline-curve steepness parameters. Forecast inputs incorporated electrical grid expansion timelines in West Texas and thermal SAGD project sanctioning rates in Alberta.
Caveats apply where nickel alloy supply disruptions or EPA enforcement timeline accelerations could materially shift the outlook. Forecasts reflect assumptions around methane regulation stringency, permanent magnet cost trajectories, and shale productivity evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Europe Oil and Gas Electric Submersible Pump Market
Oil & Gas
Downhole Drilling Tools Market
Oil & Gas
Drilling Services Market
Oil & Gas
Indonesia Coal Market
Oil & Gas
India Oil and Gas Market
Oil & Gas
United Kingdom LNG Market
Oil & Gas
Russian Federation Oil and Gas Market
Oil & Gas
Drilling and Completion Fluids Market
Oil & Gas
Mexico Oil and Gas Downstream Market
Oil & Gas
Exploration and Drilling Security Market
Oil & Gas
Oil and Gas Gasket Market
Oil & Gas
Subsea Multiphase Flowmeter Market
Oil & Gas
Upstream Services Market
Oil & Gas
Bunker Liners Market
Oil & Gas
Perforating Gun Market
Oil & Gas
Ecuador Oil and Gas Midstream Market