
 Wired Drill Pipe Sales Market | 2026-2036
Wired Drill Pipe Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Wired Drill Pipe Sales Market Insights
Modular telemetry packages bundled with wired drill pipe strings is shifting buyer evaluation criteria from standalone pipe pricing to total cost of data acquisition. Baker Hughes Company leverages integrated sensor manufacturing to control component sourcing for its wired pipe systems. NOV Inc. anchors North American supply through dedicated fabrication facilities in Houston. Schlumberger Limited differentiates through proprietary high-bandwidth telemetry protocols that reduce signal degradation in extended-reach wells.
Wired drill pipe consists of conventional steel drill pipe modified with embedded electrical conductors and signal amplifiers to transmit downhole measurements to surface acquisition systems; wall thickness typically ranges from 0.5 to 1.0 inch with conductor channels machined into upset connections. Standard Pipe occupies the largest volume share due to universal compatibility with conventional rig fleets, while Composite Pipe represents the emerging technology tier where reduced weight enables extended lateral lengths in unconventional shale plays. Smart Sensors within the Technology dimension command the highest attachment margins as operators prioritize pressure-while-drilling and vibration monitoring capabilities.
The US Bureau of Safety and Environmental Enforcement and the EPA jointly enforce well integrity standards that mandate real-time annular pressure monitoring in offshore applications, directly stimulating wired pipe retrofit demand. API Specification 5DP and ISO 11961 govern dimensional and mechanical properties, though neither yet codifies embedded electronics durability testing. Stakeholders must weigh capital allocation between expanding composite pipe R&D and defending conventional steel telemetry market position as rig automation protocols evolve.
Market Dynamics
Real-time downhole telemetry is compressing operator decision cycles from days to hours, forcing rig fleets to retrofit conventional pipe strings with embedded conductor systems or face operational obsolescence in deepwater and extended-reach applications.
Growth Catalysts
- BSEE well integrity mandates:The US Bureau of Safety and Environmental Enforcement requires continuous annular pressure monitoring in offshore drilling, mandating sensor-embedded pipe replacement across Gulf of Mexico rig fleets.
- Extended-reach laterals:Unconventional shale operators in the Permian Basin deploy wired pipe to transmit vibration and pressure-while-drilling data across 15,000-foot laterals where conventional mud-pulse telemetry fails.
- Deepwater rig reactivation:Offshore contractors in Brazil's pre-salt basins are specifying high-bandwidth wired strings for real-time geosteering through complex salt formations.
Market Restraints
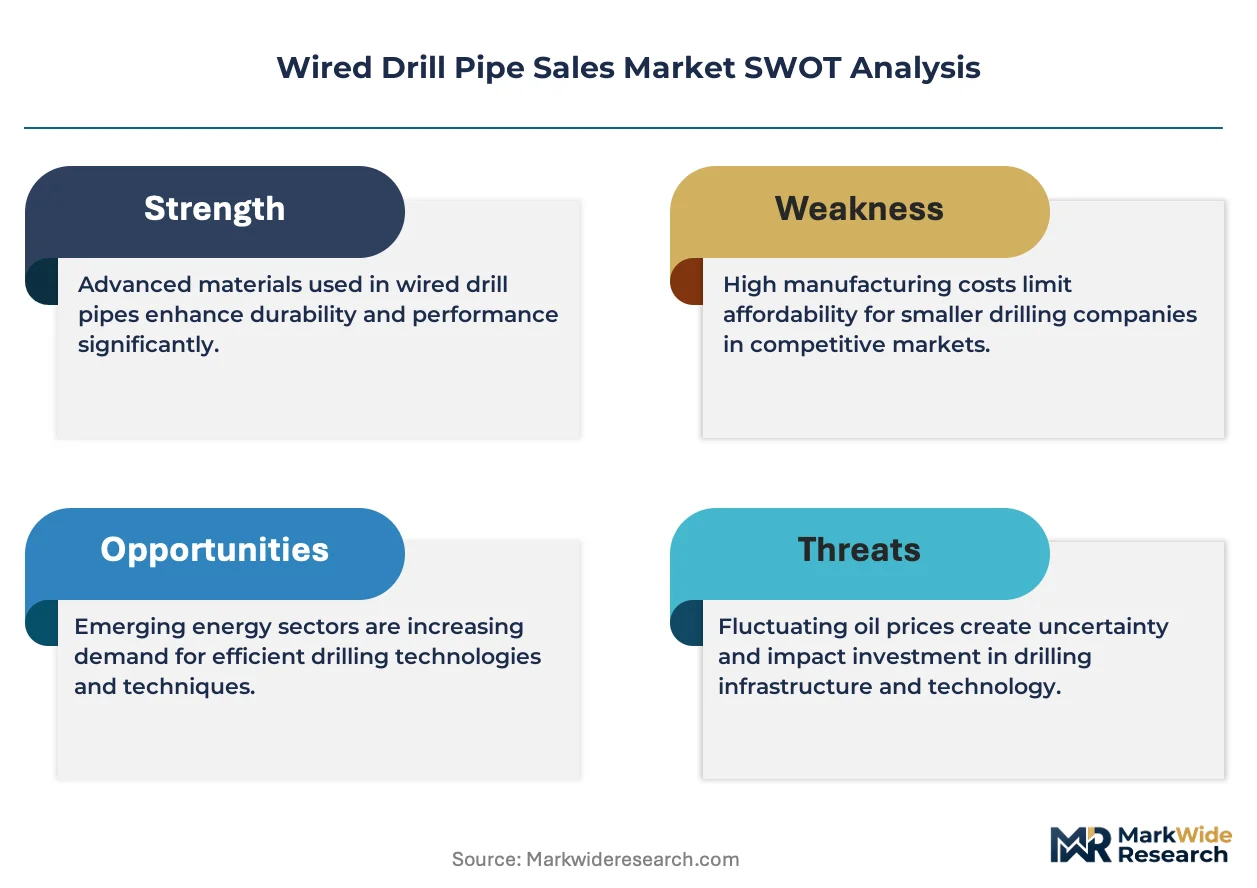
- Alloy steel input volatility:Drill pipe manufacturers face margin compression from fluctuating chrome-molybdenum alloy prices, with conductor channel machining adding 40% processing time per joint.
- Connection standard fragmentation:Proprietary telemetry protocols from major system integrators lock buyers into single-vendor replacement cycles, limiting secondary market liquidity.
- Composite pipe durability gaps:Glass-reinforced epoxy alternatives lack standardized fatigue testing under API 5DP, delaying adoption in high-torque directional drilling.
Strategic Opportunities
- Retrofit telemetry modules:Modular amplifier packages that clamp onto existing premium pipe strings open addressable market among operators with stranded conventional inventory.
- Geothermal energy drilling:High-temperature wired pipe configurations rated above 200°C penetrate hard-rock geothermal projects where standard electronics fail.
- Carbon capture monitoring:EPA Class VI well construction rules for CO2 sequestration mandate continuous pressure verification, creating new demand for annular monitoring pipe in saline formations.
Industry Challenges
- Embedded electronics certification:ISO 11961 covers mechanical pipe properties but omits conductor insulation integrity under cyclic loading, forcing vendors to self-certify durability claims.
- Cross-functional field integration:Rig crews must coordinate between directional drillers, MWD engineers, and pipe handlers during wired string makeup, stretching competency requirements beyond traditional drilling teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wired Drill Pipe Sales Market |
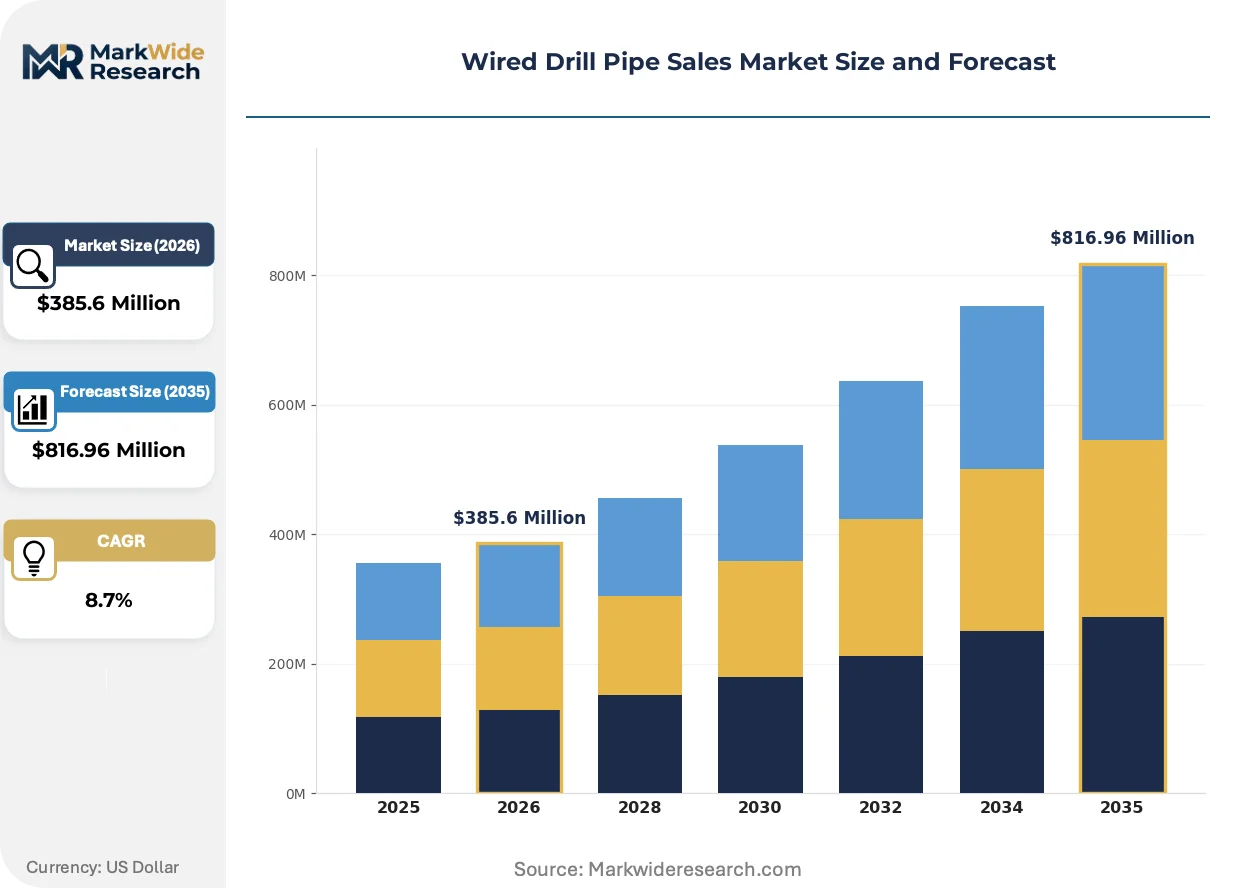
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $816.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Pipe, Coiled Tubing, Heavyweight Drill Pipe, Composite Pipe Application: Exploration, Development, Production, Workover End User: Oil & Gas Companies, Drilling Contractors, Service Providers, Mining Firms Technology: Smart Sensors, Data Transmission, Real-Time Monitoring, Automated Control |
| Companies Covered | Baker Hughes Company, Halliburton Company, Schlumberger Limited, NOV Inc., Weatherford International plc, DP-Master Manufacturing Pte Ltd., Hilong Group of Companies, TMK Group, Hunting Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wired Drill Pipe Sales Market Trends and Innovations
Digital twin integration is pulling downhole measurement resolution requirements upward, forcing wired pipe architectures to handle sensor densities that exceed current amplifier bandwidth limits.
Composite-carbon drill pipe is expanding into unconventional shale plays where reduced weight enables longer laterals from existing mast capacities. Permian Basin operators running 24-hour drilling schedules adopt hybrid steel-composite strings to cut tripping time without upgrading rig hoisting systems. The technology is expanding into marginal well economics by allowing single-pad development of multiple zones previously requiring separate surface locations.
The EPA's methane emissions monitoring framework now covers associated gas venting during drilling operations, compelling operators to deploy pressure-temperature sensors inside wired pipe for early kick detection. This regulatory pressure is compressing procurement timelines for offshore contractors in the Gulf of Mexico, where BSEE inspectors verify real-time data logging capabilities before permitting spud operations. Deepwater rig operators respond by specifying redundant telemetry paths through dual-conductor wired pipe architectures.
Buyer evaluation criteria now weight total data acquisition cost over standalone pipe pricing, unbundling hardware from analytics subscriptions. Offshore drilling contractors in the US Gulf Coast negotiate performance-based contracts where telemetry uptime guarantees determine day-rate premiums. This behavioral shift is most visible among integrated majors operating proprietary rig fleets, who internalize data processing capabilities and demand API-standardized conductor interfaces to avoid vendor lock-in.
Wired Drill Pipe Sales Market Segmentation
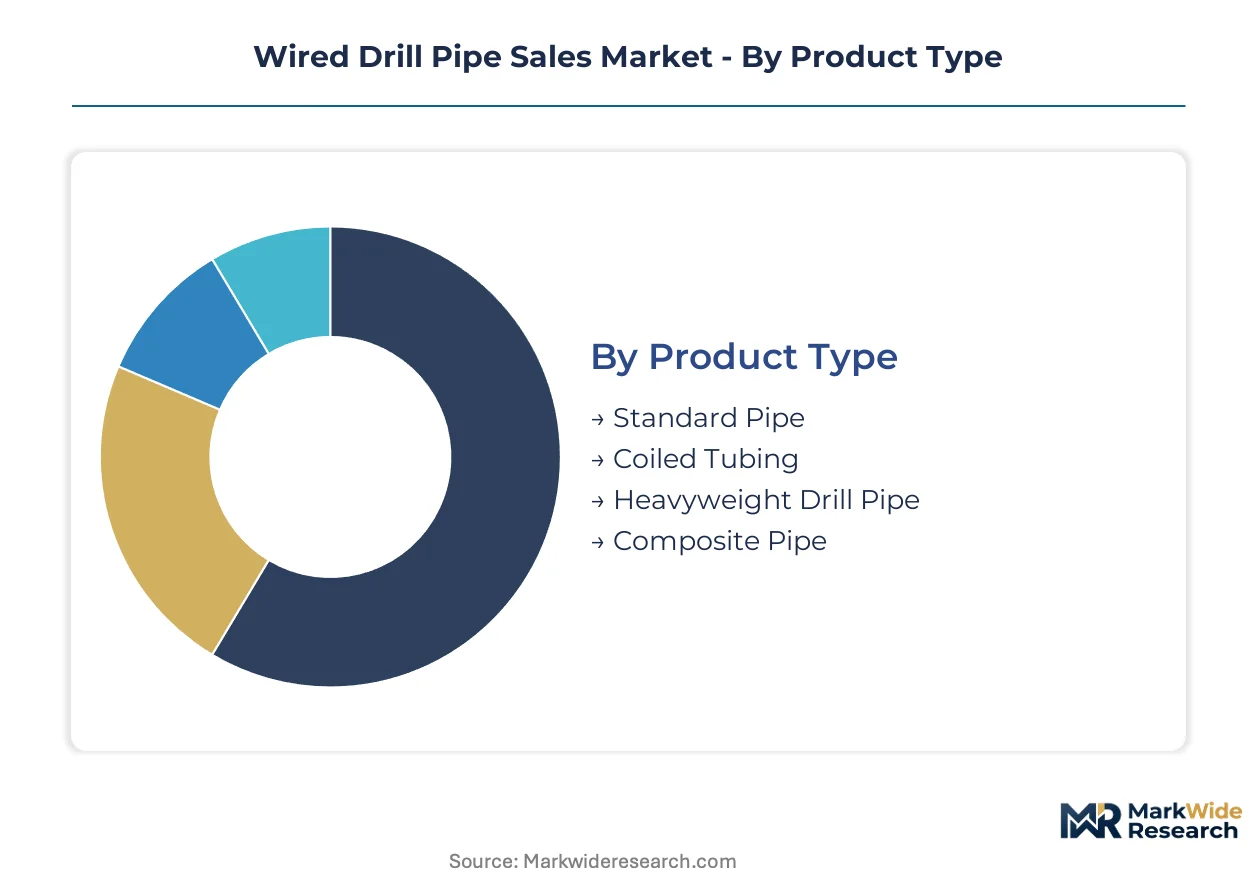
Segmentation in wired drill pipe markets reveals how procurement patterns diverge across rig fleet configurations and regulatory exposure. Buyers prioritize different performance bundles depending on whether they operate in mandated offshore environments or discretionary unconventional plays.
Product Type:
Supply concentration in alloy steel processing shapes availability and lead times across all pipe categories.
- Standard Pipe:Conventional steel drill pipe with machined conductor channels in upset connections, compatible with existing rig fleets without mast modifications. Demand concentrates in the US Gulf Coast where BSEE mandates drive replacement cycles across deepwater contractor inventories.
- Composite Pipe:Glass-reinforced or carbon-fiber epoxy construction reduces weight by 30-50% versus steel equivalents, enabling extended lateral reach from existing hoisting capacity. Operators in the Permian Basin deploy hybrid steel-composite strings to push laterals beyond 15,000 feet without rig upgrades.
- Coiled Tubing:Continuous spooled conduit with embedded conductors for live-well intervention and logging operations.
- Heavyweight Drill Pipe:Thick-walled transition sections with integrated telemetry for high-torque directional drilling.
Today's leader: Standard Pipe. Tomorrow's challenger: Composite Pipe.
Application:
Cost tier separation between capital-intensive offshore drilling and marginal onshore economics drives specification divergence.
- Exploration:Wildcat and appraisal drilling in frontier basins requires maximum telemetry bandwidth for formation evaluation while drilling. Brazil's pre-salt contractors specify redundant dual-conductor architectures to maintain geosteering continuity through salt formations.
- Development:Field construction and infill drilling prioritizes proven reliability over cutting-edge specifications. US unconventional operators favor standardized pipe strings to minimize spare inventory complexity across multi-pad developments.
- Production:Completion and intervention operations in producing wells.
- Workover:Well maintenance, remediation, and recompletion activities.
Development drilling commands current volume. Exploration applications are expanding most quickly as frontier basins reopen.
End User:
Customer type determines whether procurement emphasizes rental flexibility or capital depreciation schedules.
- Oil & Gas Companies:Integrated majors and national oil companies with proprietary rig fleets. Internal data processing capabilities drive demand for API-standardized conductor interfaces to avoid vendor lock-in.
- Drilling Contractors:Independent rig owners supplying equipment and crews under day-rate contracts. Performance-based telemetry uptime guarantees increasingly determine rate premiums in US Gulf Coast negotiations.
- Service Providers:Specialty firms supplying directional drilling, logging, or completion services.
- Mining Firms:Hard-rock extraction operators adapting oilfield telemetry for deep mineral exploration.
Drilling Contractors dominate current procurement. Oil & Gas Companies show the steepest expansion trajectory as majors internalize rig fleets.
Technology:
Margin concentration follows sensor density and signal processing complexity rather than mechanical pipe fabrication.
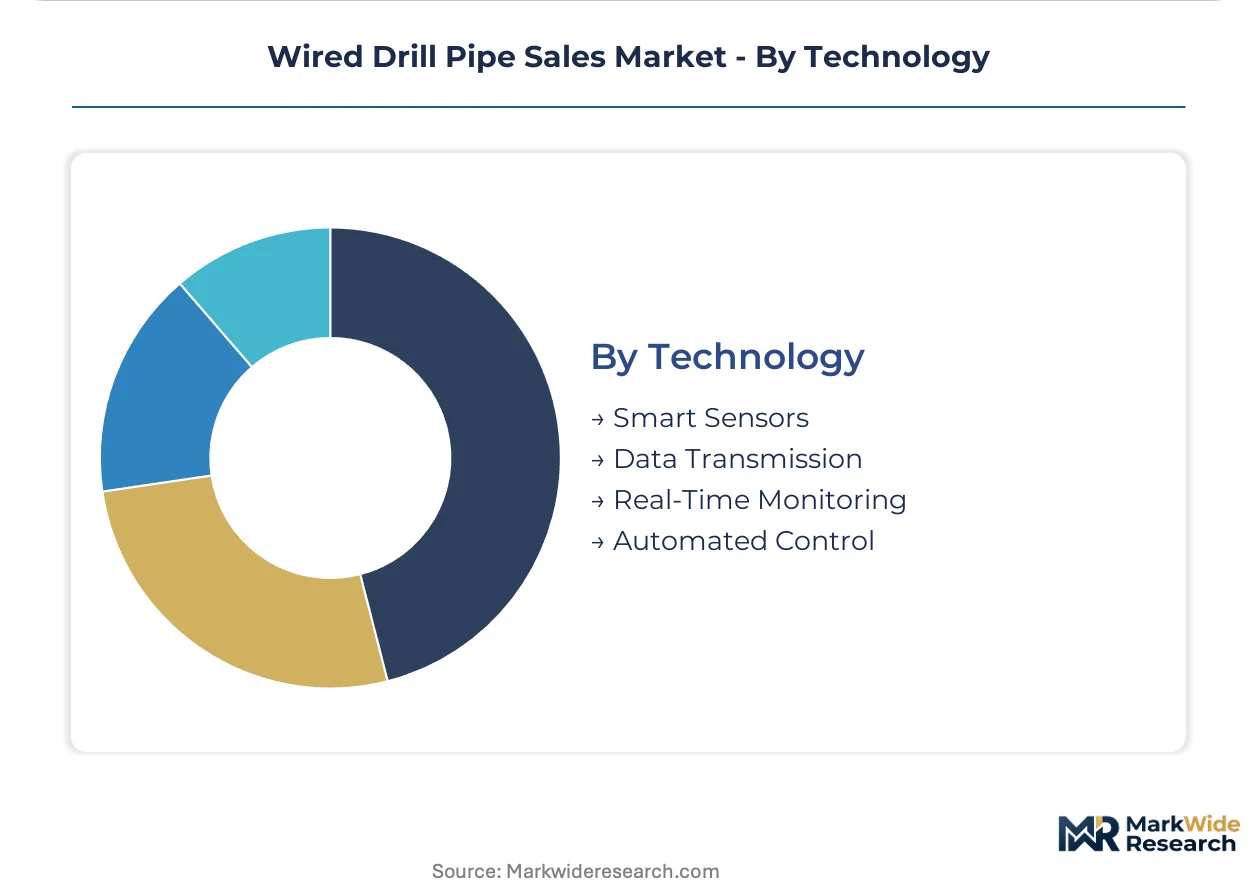
- Smart Sensors:Pressure-while-drilling, vibration monitoring, and temperature measurement packages embedded in pipe wall or connection subs. Attachment margins peak here as operators prioritize kick detection and stick-slip mitigation capabilities.
- Data Transmission:Electrical conductors, signal amplifiers, and repeater stations maintaining telemetry integrity across extended-reach laterals. Bandwidth limitations constrain sensor density in current architectures.
- Real-Time Monitoring:Surface acquisition systems and visualization platforms.
- Automated Control:Closed-loop drilling automation using downhole feedback.
Smart Sensors capture premium pricing today. Data Transmission infrastructure faces the greatest capacity pressure as digital twin integration demands higher resolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The wired drill pipe industry traces its commercial origins to North American offshore drilling operations, where real-time telemetry demands first outpaced conventional mud-pulse technology. Equipment fabrication and system integration capabilities subsequently concentrated in energy corridor clusters across multiple continents.
United States
Deepwater rig contractors in the Gulf of Mexico drive replacement cycles for sensor-embedded pipe strings under BSEE well integrity mandates. The EPA's Class VI well construction rules for carbon sequestration now extend demand into saline formation monitoring applications. Houston anchors domestic fabrication capacity, with dedicated facilities supplying both offshore contractors and Permian Basin shale operators.
Brazil
Pre-salt basin development requires redundant dual-conductor architectures for geosteering through complex salt formations. ANP regulatory frameworks for ultra-deepwater operations mandate continuous downhole pressure verification. Contractors in Rio de Janeiro and Macaé specify high-bandwidth wired strings for real-time formation evaluation while drilling.
Norway
North Sea drilling contractors face Petroleum Safety Authority requirements for enhanced wellbore monitoring in mature field redevelopment. Statoil-operated projects in the Norwegian Continental Shelf prioritize kick detection capabilities through embedded pressure-while-drilling sensors. Stavanger and Bergen host system integration facilities serving Barents Sea frontier exploration.
China
National oil companies accelerate procurement of wired pipe systems for South China Sea deepwater campaigns under MIIT industrial equipment modernization directives. Sinopec and CNOOC specify domestic-compatible telemetry interfaces for rig fleet standardization. Manufacturing clusters in Tianjin and Shanghai supply both indigenous operators and export markets.
Saudi Arabia
Aramco's unconventional gas drilling programs in the Jafurah Basin adopt wired pipe for extended-reach laterals where conventional telemetry fails. The Ministry of Energy's localization mandates drive joint venture fabrication partnerships. Dhahran and Jubail Industrial City concentrate system assembly capacity for Middle East and North Africa deployment.
Wired Drill Pipe Sales Market Competitive Landscape
Premium-margin players sit above commodity-margin players across telemetry integration depth, with those controlling proprietary high-bandwidth protocols capturing superior returns on sensor-embedded strings. The vendor base stratifies into three tiers: integrated oilfield service conglomerates with captive pipe manufacturing, specialized drill pipe fabricators with licensed telemetry partnerships, and regional steel processors supplying commodity conductor-ready blanks. Dominant competitive moves include backward integration into sensor manufacturing and strategic partnerships with directional drilling technology providers.
Within the integrated service tier, Baker Hughes Company, Schlumberger Limited, and NOV Inc. occupy positions that exemplify contrasting strategic postures. Baker Hughes leverages in-house sensor production to control component sourcing for wired pipe systems. Schlumberger differentiates through proprietary telemetry protocols that reduce signal degradation in extended-reach wells. NOV anchors North American supply through dedicated fabrication facilities in Houston, representing the equipment-manufacturing-centric archetype among major competitors.
| Leading Market Players |
|---|
| Baker Hughes Company |
| Halliburton Company |
| Schlumberger Limited |
| NOV Inc. |
| Weatherford International plc |
| DP-Master Manufacturing Pte Ltd. |
| Hilong Group of Companies |
| TMK Group |
| Hunting Plc |
| Others |
Pricing and Supply Chain Analysis
EPA methane emissions monitoring frameworks and BSEE well integrity mandates now gate access to premium-tier wired drill pipe contracts, restricting qualified supply to vendors with certified embedded electronics and forcing price stratification between regulatory-compliant and conventional offerings.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with premium tiers commanding substantial uplifts for dual-conductor architectures and API-standardized telemetry interfaces. Price differentiation rests on certification grade for offshore BSEE compliance and volume scale for Permian Basin development programs. Cost compression in standard steel pipe is intensifying because conductor channel machining adds substantial processing overhead. National oil companies with proprietary rig fleets show least price sensitivity, while independent drilling contractors in marginal shale plays exhibit highest elasticity.
Supply Chain Analysis
Freight costs for chrome-molybdenum alloy inputs from Germany and Japan amplify landed costs for US Gulf Coast fabrication facilities, compressing margins on long-haul procurement. Manufacturing gravity centers on the United States, China, and Saudi Arabia, with Houston, Tianjin, and Dhahran hosting dedicated system assembly capacity. Raw material dependencies draw from specialty steel mills, glass-reinforced epoxy suppliers, and semiconductor foundries producing signal amplifiers. Single-source vulnerability in high-bandwidth telemetry protocols creates lock-in risk. Distribution runs through rig fleet procurement officers and national oil company technical specifications teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through composite pipe R&D cost-down curves and premium-tier shifts toward smart sensor bundles with recurring analytics subscriptions.
For Market Incumbents: Anchor North American supply position through captive sensor manufacturing capacity in Houston while defending against modular retrofit telemetry entrants. Deepen backward integration into alloy steel processing to offset chrome-molybdenum price volatility. Prioritize API certification investment for embedded electronics durability testing to maintain regulatory-compliant tier access. For New Entrants and Emerging Players: Begin with geothermal energy drilling configurations rated above 200°C, where standard electronics failures create addressable white space absent entrenched competition. Target hard-rock mineral exploration operators adapting oilfield telemetry, as mining firms lack established vendor relationships. Pursue joint development partnerships with directional drilling technology providers to bypass proprietary protocol lock-in. For Investors and Strategic Acquirers: Roll-up economics work for specialized drill pipe fabricators with licensed telemetry partnerships because connection standard fragmentation limits secondary market liquidity and creates consolidation value. Five-to-ten year viability favors vendors controlling proprietary high-bandwidth protocols. Watch EPA Class VI well construction rule adoption velocity as inflection indicator for carbon sequestration monitoring demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Baker Hughes controls component sourcing for wired pipe systems through in-house production. |
| Composite Pipe R&D Scale-Up | Reduced weight configurations enable extended lateral lengths in Permian Basin shale plays. |
| API Standardization Advocacy | Operators demand standardized conductor interfaces to avoid Schlumberger protocol lock-in. |
| Geothermal Configuration Development | High-temperature ratings above 200°C penetrate hard-rock projects where standard electronics fail. |
| Modular Retrofit Telemetry Launch | Clamp-on amplifier packages open addressable market among stranded conventional pipe inventories. |
Research Methodology
Multiple input streams — directional drilling contractors, MWD engineers, rig fleet procurement officers, and pipe handling specialists — were reconciled with secondary validation from BSEE enforcement records, EPA regulatory filings, API specification documents, and SEC disclosures from oilfield service conglomerates. Bottom-up equipment shipment tallies and top-down energy capex allocation models were cross-referenced to establish baseline volumes.
Historical rig fleet retrofit patterns were cross-referenced against panel input from offshore contractors and unconventional shale operators to project adoption trajectories across the modeling period. Segmentation dimensions modeled include product type, application, end user, and technology tier, with CAGRs derived from equipment replacement cycle analysis and regulatory mandate compliance timelines. Forecast inputs incorporated deepwater rig reactivation schedules and pre-salt basin development timelines.
Several conditions sit outside the modeled scope, including potential ISO 11961 revisions codifying embedded electronics durability testing and unforeseen alloy steel commodity price spikes. Forecasts reflect assumptions about BSEE enforcement continuity and EPA methane framework expansion. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Processing Seals Market
Oil & Gas
North America Seismic Services Market
Oil & Gas
South America Intelligent Pigging Market
Oil & Gas
Egypt Natural Gas Market
Oil & Gas
Australia Oil and Gas Upstream Market
Oil & Gas
Middle East and Africa Drilling Market
Oil & Gas
Underreamers Market
Oil & Gas
Sudan Oil and Gas Market
Oil & Gas
Oilfield Market
Oil & Gas
United States Oil and Gas Upstream Market
Oil & Gas
Russia Oil and Gas EPC Market
Oil & Gas
Polycrystalline Diamond Compact (PDC) Drill Bit Market
Oil & Gas
Oil and Gas Separation Equipment Market
Oil & Gas
US Oil and Gas Infrastructure Market
Oil & Gas
Turkmenistan Oil and Gas Market
Oil & Gas
Subsea Manifolds Market