
 Rotary Steerable System Market | 2026-2036
Rotary Steerable System Market Size, Share, and Industry Trends Forecast 2026-2036
Rotary Steerable System Market Outlook
National oil companies and integrated majors are bifurcating the buyer landscape as independents retrench on capital discipline. Schlumberger Limited leverages integrated well construction portfolios to anchor premium tool deployments in deepwater frontiers. Baker Hughes Company competes through in-house bit-steering integration that sustains drilling efficiency metrics across unconventional shale plays. Halliburton Company specializes in real-time telemetry architectures that differentiate its offering in high-temperature geothermal applications.
A rotary steerable system is a downhole drilling tool that enables continuous rotation of the drill string while steering the bit along a predetermined trajectory using closed-loop feedback from near-bit sensors. The technology eliminates slide drilling interruptions, improving rate of penetration and wellbore quality in extended-reach and horizontal sections. Smart Systems command expanding share as operators demand autonomous trajectory correction and vibration suppression in complex well architectures. Electrical technology leads the technology dimension due to superior signal fidelity and compatibility with high-data-rate logging-while-drilling packages. Managed Systems remain nascent but attract investment from supermajors pursuing fully automated rig floors.
The US Bureau of Safety and Environmental Enforcement enforces well control and equipment reliability standards that shape RSS certification requirements for Gulf of Mexico operations. API Specification Q2 and ISO 9001 quality management frameworks govern manufacturing traceability and field service documentation across supplier networks. Brazil's national petroleum regulator ANP mandates local content thresholds that condition market access for offshore drilling contractors. Stakeholders must weigh technology refresh cycles against regulatory compliance burdens as automation standards harden and carbon intensity disclosures expand across capital allocation decisions.
Market Dynamics
Closed-loop automation architectures are compressing drilling economics for extended-reach wells while API Specification Q2 and ISO 9001 frameworks harden qualification barriers for new entrants.
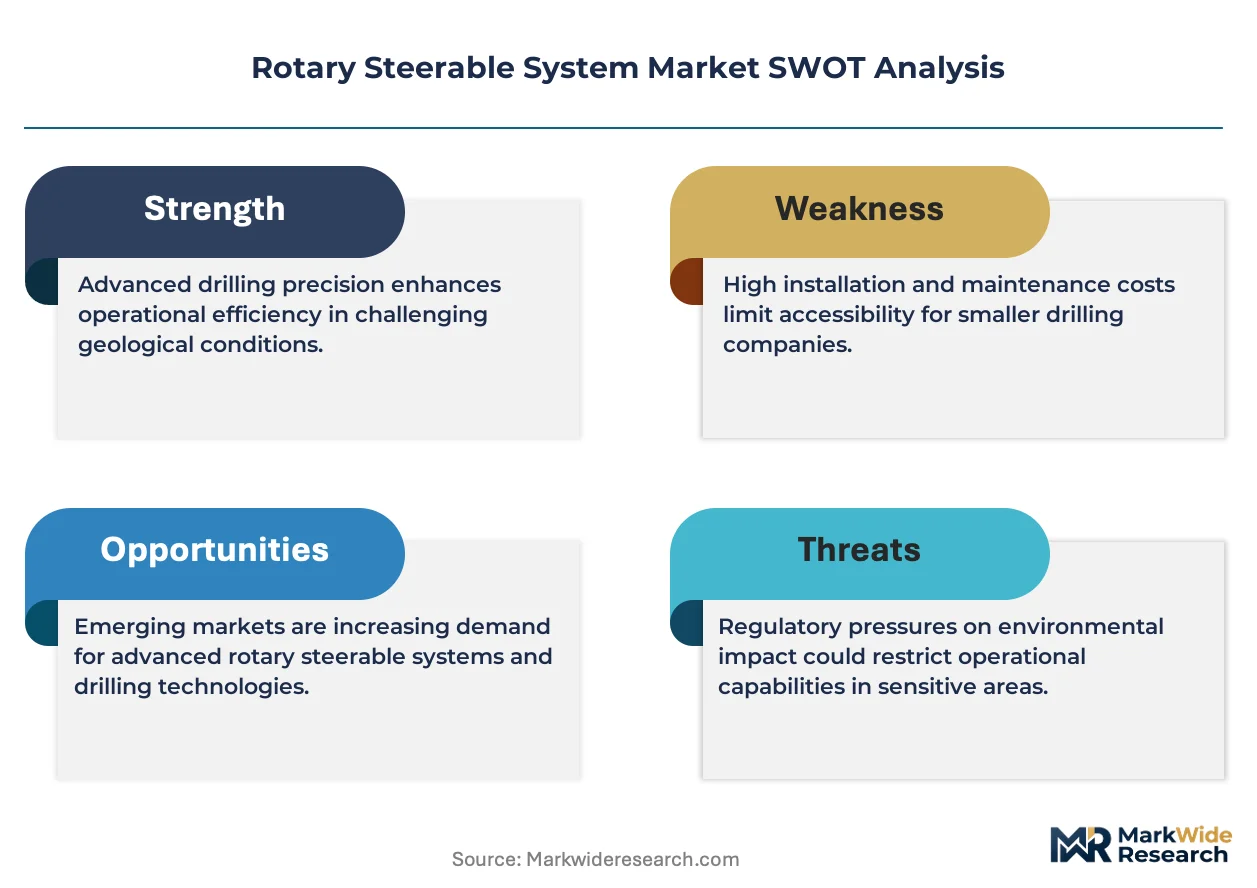
Growth Catalysts
- Deepwater frontier expansion:Brazil's ANP local content mandates are accelerating offshore rig deployments in pre-salt basins, creating concentrated demand for high-specification steering tools.
- API Specification Q2 compliance:Quality management traceability requirements are filtering out low-reliability suppliers and consolidating procurement toward certified service providers.
- Geothermal drilling resurgence:High-temperature formations in Iceland and Indonesia are pulling real-time telemetry architectures into volcanic heat extraction projects.
Market Restraints
- Electronics supply concentration:High-temperature sensor fabrication depends on a narrow supplier base concentrated in Japan and Germany, creating single-source vulnerability.
- Tool qualification timelines:BSEE well control certification for Gulf of Mexico operations extends field validation cycles to 18-24 months before commercial deployment.
- PDC bit substitution pressure:Fixed-cutter directional drilling in homogeneous shale sections limits RSS penetration in certain unconventional basins.
Strategic Opportunities
- West Africa underpenetration:Angola and Nigeria's mature field redevelopment programs lack indigenous RSS service capacity, opening contractor expansion pathways.
- Managed pressure drilling convergence:Integration of closed-loop pressure control with autonomous steering is creating fully automated well construction platforms.
- US Inflation Reduction Act geothermal incentives:Tax credits for clean heat projects are redirecting drilling contractor fleets toward high-temperature sedimentary formations.
Industry Challenges
- Downhole electronics reliability:175°C+ operating environments degrade signal fidelity and accelerate component failure rates in real-time telemetry systems.
- Cross-functional skill scarcity:Mechatronics engineers capable of integrating mechanical steering with digital control systems command premium compensation and limited availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotary Steerable System Market |
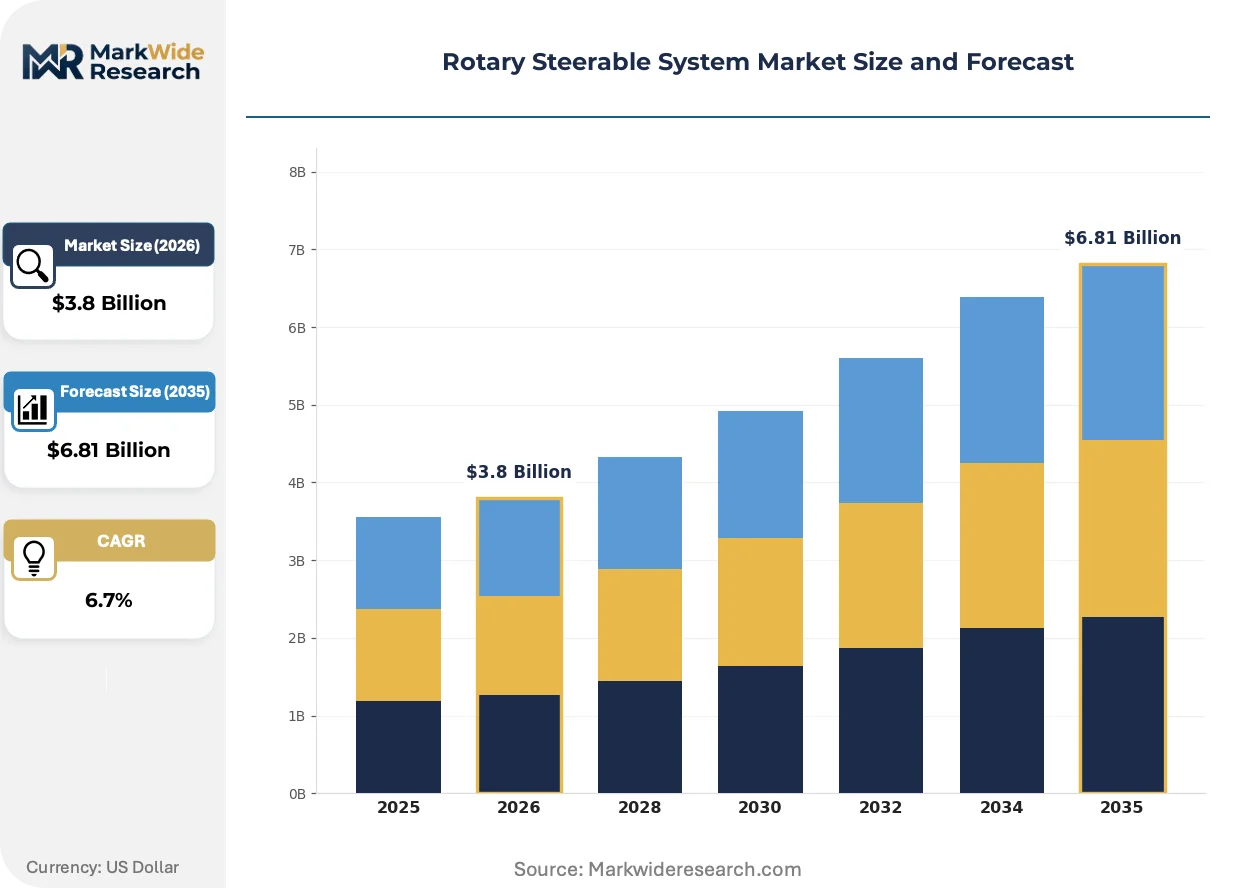
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Systems, Smart Systems, Hybrid Systems, Managed Systems Technology: Mechanical, Electrical, Hydraulic, Pneumatic End User: Oil & Gas Companies, Mining Firms, Geothermal Developers, Contractors Application: Well Drilling, Exploring, Horizontal Drilling, Directional Drilling |
| Companies Covered | Weatherford International, APS Technology, Schlumberger Limited, China Oilfield Services Limited, Gyrodata Incorporated, Baker Hughes Company, NOV Inc, Enteq Technologies, Halliburton Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotary Steerable System Market Strategic Shifts
Digital twin architectures and autonomous trajectory algorithms are compressing the feedback loop between subsurface sensing and surface decision-making, reshaping how operators manage wellbore placement risk.
Electrical RSS architectures are bifurcating the technology landscape. These systems transmit steering commands through wired drill pipe or electromagnetic telemetry, eliminating mud-pulse signal degradation in extended-reach sections. Supermajors operating in Brazil's pre-salt and the US Gulf of Mexico are standardizing on electrical platforms for wells exceeding 10,000 meters measured depth. The shift is compressing market share for conventional hydraulic push-the-bit systems in high-specification applications.
ISO 14001 environmental management integration with API Q2 quality frameworks is tightening supplier documentation requirements. Drillers must now demonstrate carbon intensity tracking across manufacturing and field service operations. European operators under EU Green Deal disclosure mandates are conditioning contract awards on verified lifecycle emissions data, forcing RSS providers to reconfigure supply chain audit protocols.
Performance-based contracting is displacing day-rate structures in deepwater markets. Operators now tie contractor compensation to rate-of-penetration guarantees and tortuosity targets rather than time-on-well. This shift is most visible in Norway's North Sea sector and offshore Australia, where national oil companies have rewritten standard drilling agreements to transfer downhole risk to service providers.
Rotary Steerable System Market Segmentation
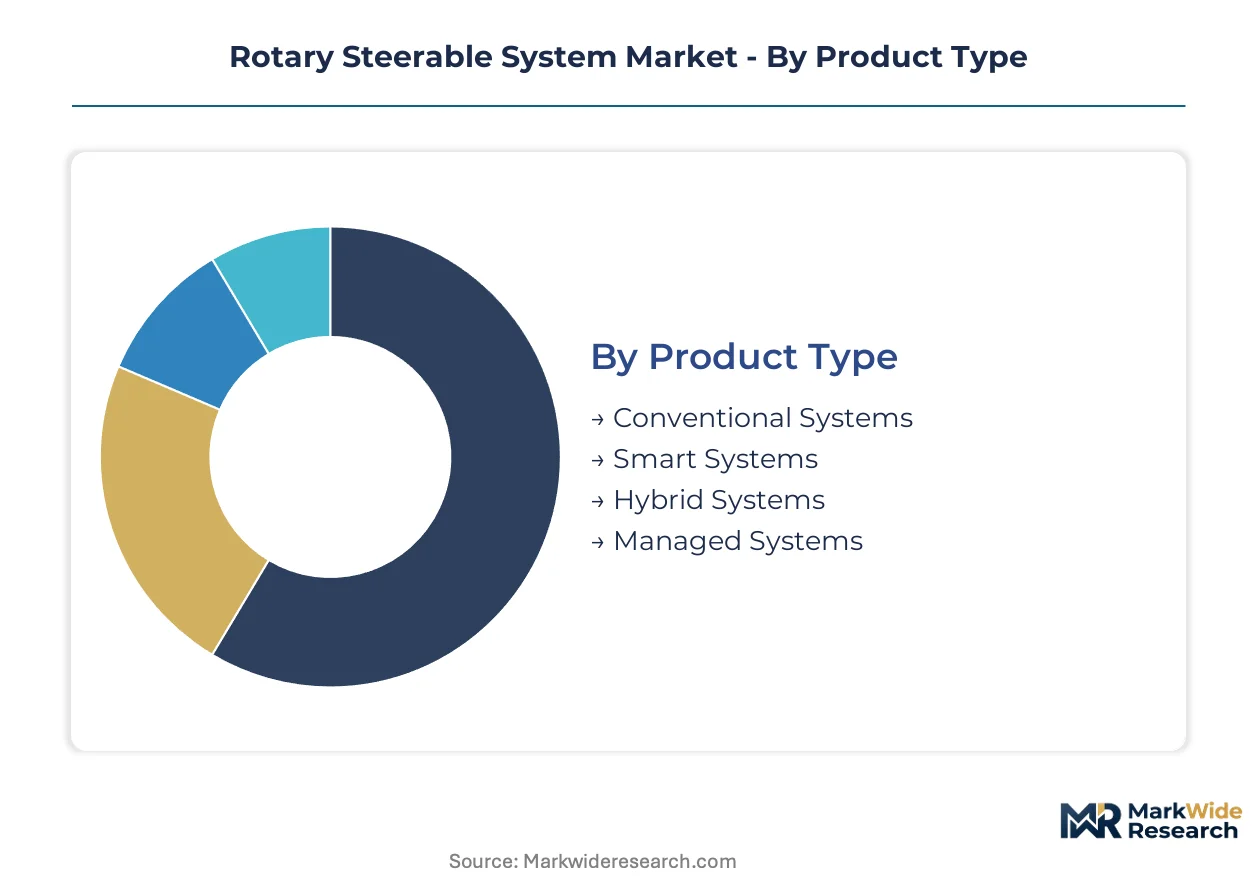
Segmentation in the rotary steerable system market reveals how tool specifications align with distinct operational economics across drilling environments. Channel dynamics vary sharply between high-specification offshore deployments and price-sensitive onshore contracting.
Product Type:
Channel flow splits between direct OEM relationships for premium systems and rental fleets for conventional hardware, with service companies arbitraging asset utilization across rig programs.
- Smart Systems:Autonomous trajectory correction and vibration suppression capabilities integrate near-bit sensors with closed-loop control algorithms. Demand concentrates in Brazil's pre-salt basins and the US Gulf of Mexico, where extended-reach well economics justify premium day rates.
- Conventional Systems:Push-the-bit and point-the-bit architectures dominate rental channel volumes through established drilling contractors. These systems flow through Halliburton and Baker Hughes rental fleets serving North American shale operators.
- Hybrid Systems:Combines mechanical steering with electrical telemetry for intermediate complexity wells.
- Managed Systems:Fully automated rig floor integration remains nascent, attracting supermajor R&D investment.
By volume, Conventional Systems leads. By growth pace, Smart Systems is expanding most quickly.
Technology:
Cost tier stratification separates electrical platforms commanding premium pricing from mechanical and hydraulic alternatives competing on capital efficiency.
- Electrical:Wired drill pipe and electromagnetic telemetry transmit steering commands with signal fidelity that mud-pulse systems cannot match in extended-reach sections. Norway's North Sea operators and Brazil's Petrobras have standardized on electrical architectures for wells exceeding 10,000 meters measured depth.
- Mechanical:Simple push-the-bit linkages serve geothermal developers in Iceland and Indonesia where high-temperature electronics face reliability constraints.
- Hydraulic:Conventional mud-pulse signal transmission retains share in mature onshore basins.
- Pneumatic:Compressed air drilling applications in mining exploration use pneumatic steering for water-sensitive formations.
Electrical platforms capture the steepest expansion trajectory as deepwater operators prioritize data density over capital cost.
End User:
Customer type determines procurement structure, with national oil companies favoring integrated service contracts and independents sourcing through competitive bidding.
- Oil & Gas Companies:Integrated majors and national oil companies anchor demand through multi-year frame agreements. Saudi Aramco and ADNOC specify closed-loop automation requirements in tender documents for complex well profiles.
- Contractors:Drilling contractors build RSS rental fleets as differentiated service offerings. Nabors Industries and Precision Drilling compete on tool availability and technical support density across Permian and Bakken programs.
- Geothermal Developers:High-temperature formations pull specialized telemetry architectures from oilfield service providers.
- Mining Firms:Mineral exploration programs use directional steering for ore body delineation in hard rock environments.
Oil & Gas Companies account for the largest revenue base. Geothermal Developers are gaining share fastest as clean heat incentives redirect drilling capacity.
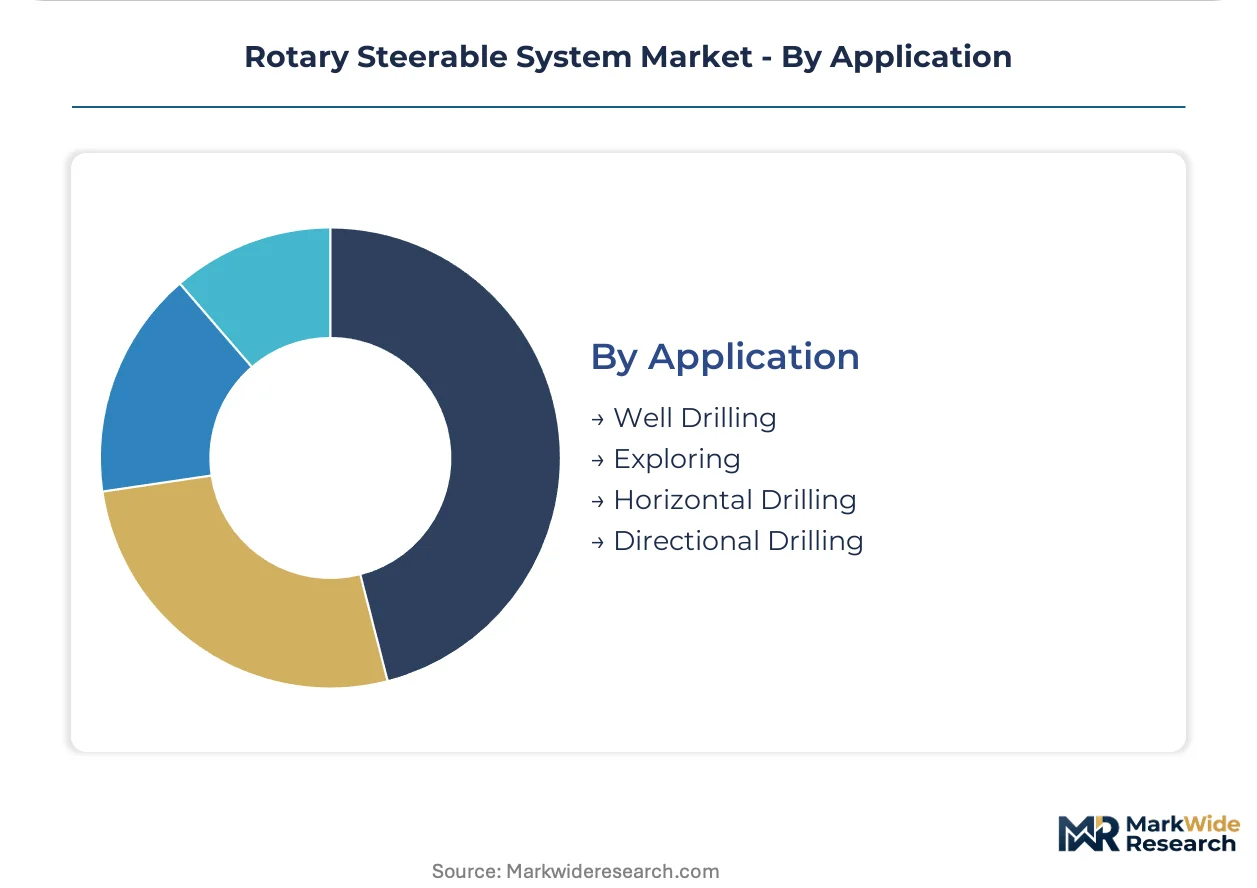
Application:
Application maturity varies, with horizontal drilling representing established practice and directional drilling in mining contexts representing frontier adoption.
- Horizontal Drilling:Extended-reach laterals in unconventional shale basins require continuous rotation to manage torque and drag. Permian Basin operators deploy electrical RSS for laterals exceeding 3,000 meters.
- Well Drilling:Conventional vertical and deviated well construction remains the volume base for rental fleet deployment.
- Exploring:Wildcat and appraisal drilling demands steering flexibility for unknown subsurface conditions.
- Directional Drilling:Sidetracking and re-entry applications in mature fields use RSS to access bypassed pay zones.
Horizontal Drilling dominates capital deployment. Exploring applications show the most volatile demand cyclicality tied to exploration budget cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
National oil companies and integrated majors anchor procurement across concentrated offshore basins, with Brazil, the United States, and Norway commanding premium tool specifications while Middle Eastern NOCs accelerate automation adoption for complex well profiles.
Brazil
Petrobras drives pre-salt basin development with extended-reach wells exceeding 10,000 meters measured depth. ANP local content mandates condition offshore drilling contracts on domestic supplier participation. The Santos Basin cluster near Rio de Janeiro concentrates high-specification RSS deployments for ultra-deepwater carbonate reservoirs.
United States
Permian Basin operators deploy electrical architectures for laterals surpassing 3,000 meters in unconventional shale plays. BSEE enforces well control certification extending field validation cycles to 18-24 months before Gulf of Mexico commercial deployment. Houston anchors service company headquarters and technical support infrastructure for deepwater frontier operations.
Norway
Equinor and Aker BP standardize on electrical platforms for North Sea extended-reach drilling. Performance-based contracting ties contractor compensation to rate-of-penetration guarantees rather than day-rate structures. Stavanger and Bergen host concentrated engineering centers for autonomous trajectory algorithm development.
Saudi Arabia
Saudi Aramco specifies closed-loop automation requirements in tender documents for complex well profiles targeting carbonate and tight gas formations. The country's national petroleum regulator mandates equipment reliability documentation aligned with API Specification Q2 frameworks. Dhahran's industrial corridor concentrates manufacturing partnerships for high-temperature downhole electronics.
China
Sinopec and CNOOC expand offshore drilling in the South China Sea and Bohai Bay basins. GB standards and MIIT regulations govern drilling equipment import qualification and data localization requirements. Shenzhen and Tianjin clusters develop domestic RSS capabilities through state-backed technology programs.
Rotary Steerable System Market Competitive Environment
Player mix skews toward integrated oilfield service conglomerates with full well construction portfolios. Market structure concentrates around three dominant archetypes: technology-integrated majors anchoring premium offshore contracts, specialized steering tool developers serving niche geothermal and mining applications, and national champions capturing domestic content-mandated procurement. Competitive moves center on strategic partnerships for closed-loop automation convergence and portfolio diversification into managed pressure drilling integration.
Among Houston-based service conglomerates, Schlumberger Limited and Baker Hughes Company occupy positions representing integrated technology portfolios, while Halliburton Company exemplifies real-time telemetry specialization. China Oilfield Services Limited anchors the national champion archetype serving Asia-Pacific offshore markets. These three entities represent distinct competitive vectors: premium offshore specification, unconventional shale efficiency, and state-backed frontier expansion.
| Leading Market Players |
|---|
| Weatherford International |
| APS Technology |
| Schlumberger Limited |
| China Oilfield Services Limited |
| Gyrodata Incorporated |
| Baker Hughes Company |
| NOV Inc |
| Enteq Technologies |
| Halliburton Company |
| Others |
Value Chain & Pricing Dynamics
Long-term frame agreements with national oil companies lock in supply access and price visibility across multi-year drilling programs. These contracts bundle RSS deployment with integrated well construction services, insulating premium tool providers from spot-market volatility while embedding cost-plus indexation to raw material and labor inputs.
Pricing Analysis
Cost-plus contracts with steel and electronics indexation dominate procurement structures for high-specification offshore deployments. Three-tier pricing structure across premium smart systems, standard electrical platforms, and economy hydraulic units separates Petrobras-grade specifications from Permian Basin rental fleet deployments. Pricing pressure stems from drilling contractor consolidation in North American shale plays, where Nabors Industries and Precision Drilling squeeze day-rate margins. National oil companies exhibit lowest price sensitivity, while independent shale operators drive aggressive rental rate negotiations.
Supply Chain Analysis
Extended lead times for high-temperature sensor modules strain inventory planning across OEM assembly lines. Manufacturing concentrates in the United States, Germany, and Japan, where specialized foundries fabricate downhole electronics rated for 175°C+ operation. Component sourcing draws from Japanese semiconductor fabricators and German precision machining houses, creating single-source vulnerability for gyroscopic sensors. Tariff exposure on Chinese-sourced rare earth magnets for motor assemblies threatens cost stability. Distribution runs through Houston and Stavanger service hubs that maintain field-ready tool pools for rapid deployment to Brazil and West Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rotary steerable systems are approaching a platform-economics inflection as closed-loop automation architectures demand interoperability between steering tools, wired drill pipe telemetry, and surface rig control systems. This interoperability imperative favors providers with integrated well construction portfolios over point-solution specialists.
For Market Incumbents: Compound defensive moats by embedding RSS offerings within multi-service well construction contracts that bundle directional drilling, logging-while-drilling, and managed pressure drilling. Deepen backward integration into high-temperature sensor fabrication to reduce dependence on Japanese and German single-source suppliers. Prioritize API Specification Q2 certification investments to filter out emerging competitors during procurement pre-qualification.
For New Entrants and Emerging Players: Lead with specialized high-temperature telemetry architectures for geothermal developers in Iceland and Indonesia, where Schlumberger and Baker Hughes maintain limited service density. Target West Africa's mature field redevelopment programs in Angola and Nigeria, where indigenous RSS service capacity remains underdeveloped. Pursue partnership-based go-to-market models with regional drilling contractors lacking capital for owned tool fleets.
For Investors and Strategic Acquirers: Niche steering tool developers with proven 200°C+ electronics capabilities represent priority acquisition targets as geothermal drilling accelerates under US Inflation Reduction Act incentives. Long-term viability hinges on exposure to automation-convergent rig platforms rather than standalone RSS point solutions. Monitor BSEE certification queue lengths as an inflection indicator—extended validation backlogs signal tightening supply and pricing power for qualified incumbents.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Automation Convergence | Integrates RSS with managed pressure drilling to create fully automated well construction platforms for Petrobras pre-salt operations. |
| High-Temperature Electronics Development | Extends reliable operating range beyond 175°C for geothermal expansion in Iceland and Indonesia volcanic formations. |
| Electrical Telemetry Standardization | Wired drill pipe compatibility captures premium pricing in Norway North Sea extended-reach drilling programs. |
| Local Content Partnership Formation | Brazil ANP compliance enables market access for offshore contractors in Santos Basin ultra-deepwater developments. |
| Performance-Based Contracting Transition | Rate-of-penetration guarantees transfer downhole risk from Equinor to service providers in North Sea sector. |
Study Parameters
A standing panel of drilling engineers, directional drilling contractors, procurement managers at national oil companies, and geothermal project developers provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation against API certification databases, BSEE equipment approval records, ANP local content compliance filings, and rig deployment tracking from offshore contracting databases. Bottom-up tool deployment counts triangulated against top-down service company revenue segmentation across product lines.
Consistency checks validated volume and value outputs against external benchmarks including rig fleet utilization reports, capital expenditure disclosures from integrated majors, and national petroleum regulator drilling permit data. The analytical framework modeled demand across technology type, well complexity tier, application maturity, and regional regulatory cluster throughout the projection horizon. CAGRs derived from fitted growth curves adjusted for basin-specific drilling intensity and equipment replacement cycles. Forecast inputs incorporated ANP local content enforcement trajectories and US geothermal tax credit utilization rates.
Forecasts assume regulatory continuity in Brazil ANP local content regimes, US BSEE well control certification protocols, and EU Green Deal carbon disclosure mandates; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Multi-Point Ground Flares (MPGF) Market
Oil & Gas
Iran Oil and Gas Market
Oil & Gas
Netherlands LNG Bunkering Market
Oil & Gas
Saudi Arabia Drilling Rigs Market
Oil & Gas
Sudan Oil and Gas Market
Oil & Gas
Oilfield Chemicals Market
Oil & Gas
Coal Seam Gas Market
Oil & Gas
Global Upstream Petrotechnical Training Services Market
Oil & Gas
Geothermal Drilling Market
Oil & Gas
US Oil and Gas Analytics Market
Oil & Gas
Global Well Logging Equipment Market
Oil & Gas
Kuwait Oil and Gas Market
Oil & Gas
Italy Oil and Gas Market
Oil & Gas
India Oil and Gas Market
Oil & Gas
North Sea Oilfield Equipment Market
Oil & Gas
Central Asia Oil and Gas Market