
 Digital Drilling Rigs Market | 2026-2036
Digital Drilling Rigs Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Drilling Rigs Market Insights
Subscription-based predictive maintenance software is realigning how rig OEMs monetize their installed base. Schlumberger leverages its digital twin platform to anchor long-term service contracts across deepwater fleets. Baker Hughes Company competes through specialized edge-computing modules that sustain uptime guarantees for Arctic deployments.
Digital drilling rigs integrate automated hoisting, closed-loop circulation, and real-time downhole telemetry to optimize rate of penetration and minimize non-productive time. Automated Rigs dominate capital allocation as operators prioritize iron roughneck and pipe-handling automation over semi-manual Smart Rigs. AI-enabled analytics within the Technology dimension commands premium pricing by reducing stuck-pipe incidents through predictive formation evaluation.
The US BSEE enforces subsea equipment reliability standards that shape offshore rig certification requirements, while the EPA methane emissions rules tighten flaring protocols for onshore pad drilling. Norway's Petroleum Safety Authority mandates functional safety documentation for integrated control systems. Stakeholders must weigh regulatory compliance costs against automation-derived efficiency gains when allocating capital across rig upgrade cycles.
Market Dynamics
Automated rig systems are compressing drilling cycles while regulatory pressure from the US Bureau of Safety and Environmental Enforcement forces capital reallocation toward certified blowout preventer architectures.
Growth Catalysts
- Permian Basin Concentration:West Texas and southeastern New Mexico pad drilling density creates economies of scale for autonomous pipe-handling deployments. Operators justify automation spend through multi-well pad repetition.
- BSEE Blowout Preventer Mandates:Stricter subsea equipment testing protocols compel fleet-wide control system upgrades. Compliance-driven replacement cycles accelerate digital rig procurement.
- Predictive Formation Evaluation:AI-enabled downhole telemetry reduces stuck-pipe incidents. Real-time analytics command premium pricing from offshore deepwater operators.
Market Restraints
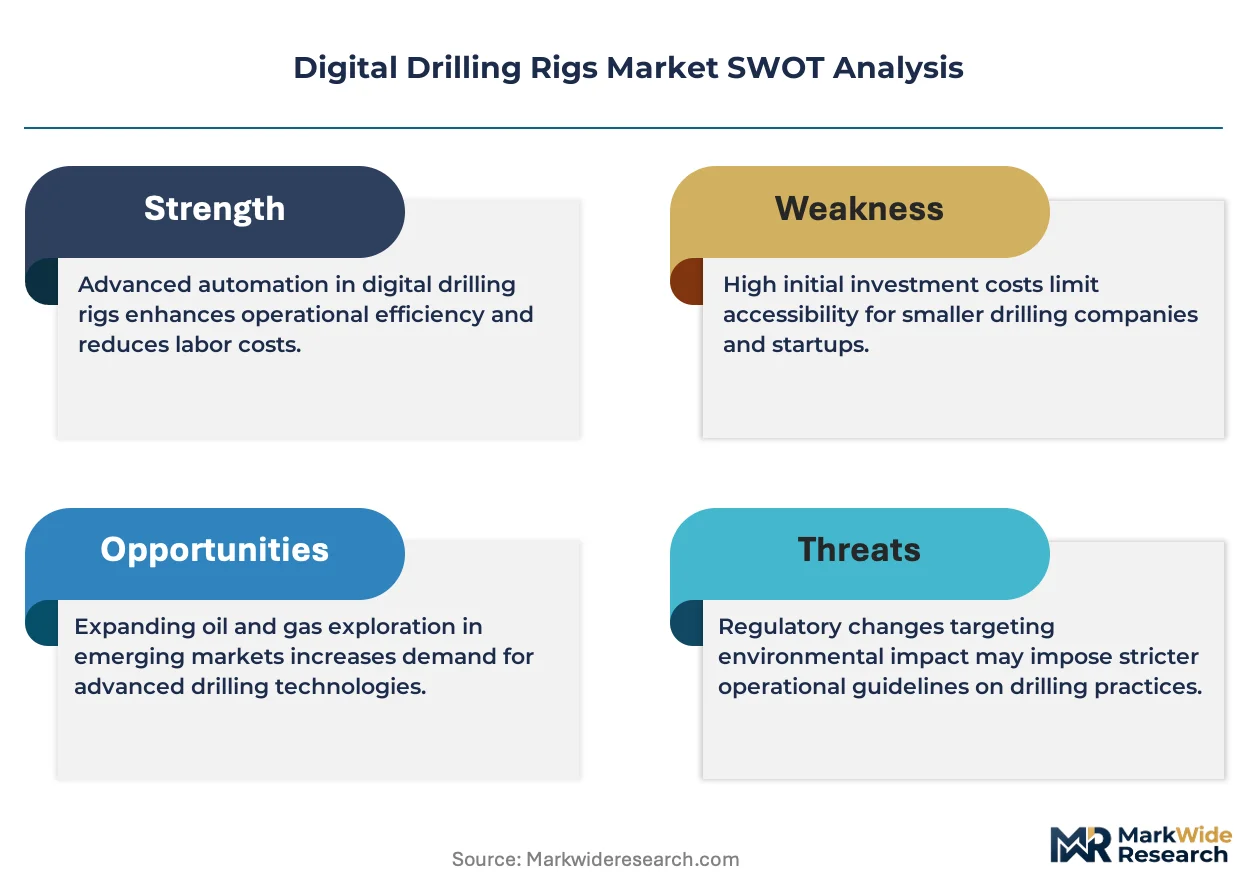
- Arctic Edge Computing Costs:Specialized modules sustaining uptime guarantees in extreme cold climates carry 40-60% hardware premiums over standard deployments.
- Integrated Control System Documentation:Norway's Petroleum Safety Authority mandates exhaustive functional safety paperwork. Certification timelines extend 18-24 months for new platform integrations.
- Legacy Fleet Inertia:Semi-manual Smart Rigs retain residual value in marginal basins. Capital discipline delays full automation conversion for second-tier contractors.
Strategic Opportunities
- EPA Methane Flaring Rules:Tightened emissions protocols for onshore pad drilling create demand for closed-loop circulation systems. Automated rigs capture vented gas for processing.
- Digital Twin Convergence:Physics-based simulation layers merge with live sensor streams. Service contracts anchor long-term revenue through predictive maintenance subscriptions.
- Deepwater Fleet Renewal:Aging floating rigs in the Gulf of Mexico require control system overhaul. Retrofit-ready automation architectures penetrate this installed base.
Industry Challenges
- Automation Technician Scarcity:Iron roughneck programming and robotic pipe-handling maintenance outstrip vocational training pipeline output. Competitors poach certified personnel across basins.
- Multi-Vendor Integration Complexity:Proprietary edge-computing modules from competing OEMs resist interoperability. Operators face vendor lock-in or costly custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Drilling Rigs Market |
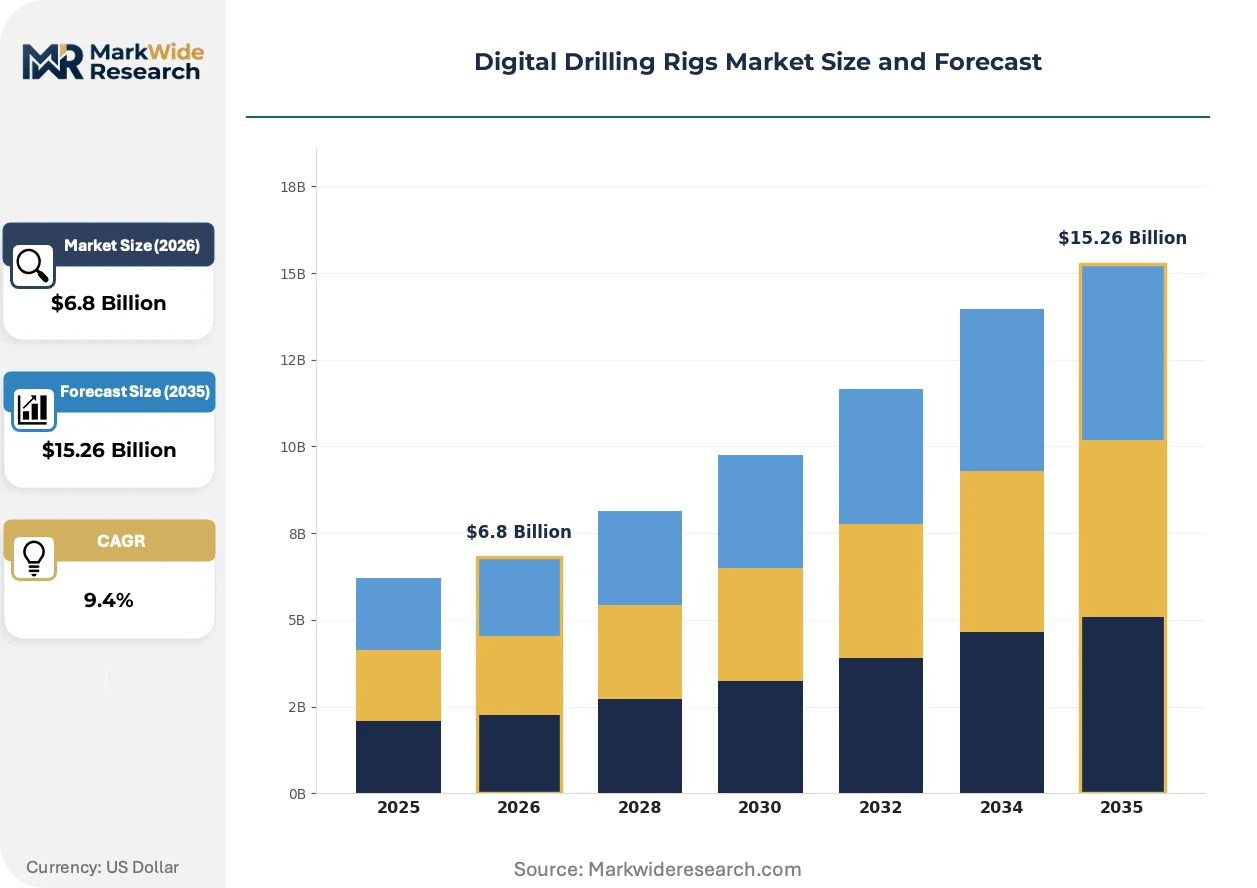
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Rigs, Smart Rigs, Data-Driven Rigs, Hybrid Rigs Technology: IoT, AI, Cloud Computing, Cybersecurity End User: Oil & Gas Companies, Mining Operations, Geothermal Energy, Research Institutions Deployment Model: Onshore, Offshore, Mobile Units, Fixed Installations |
| Companies Covered | Schlumberger, Halliburton Company, Baker Hughes Company, Helmerich & Payne, Inc., Nabors Industries Ltd., NOV Inc., Weatherford, Transocean Ltd., Pason Systems Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Drilling Rigs Market Trends and Innovations
Real-time telemetry architectures are compressing decision cycles from days to hours. Three forces dominate: sensor fusion at the edge, regulatory documentation automation, and procurement model unbundling.
Closed-loop circulation systems are integrating automated pressure management with managed pressure drilling software. Offshore operators in the Gulf of Mexico deploy these configurations to maintain constant bottom-hole pressure across narrow drilling windows. The technology is integrating formerly separate mud pump and choke manifold controls into unified digital threads.
EPA methane emissions rules now require continuous monitoring equipment on all new onshore pad drilling operations. Operators must install optical gas imaging or equivalent detection systems tied to automated shutdown protocols. Shale producers in the Permian Basin respond by specifying rigs with integrated flare gas recovery compression.
Service contract unbundling accelerates as operators separate predictive maintenance software subscriptions from hardware procurement. Digital drilling rig OEMs now face pressure to price analytics modules independently of iron roughneck automation packages. This shift concentrates in North American unconventional basins where capital efficiency scrutiny is most intense.
Digital Drilling Rigs Market Segmentation
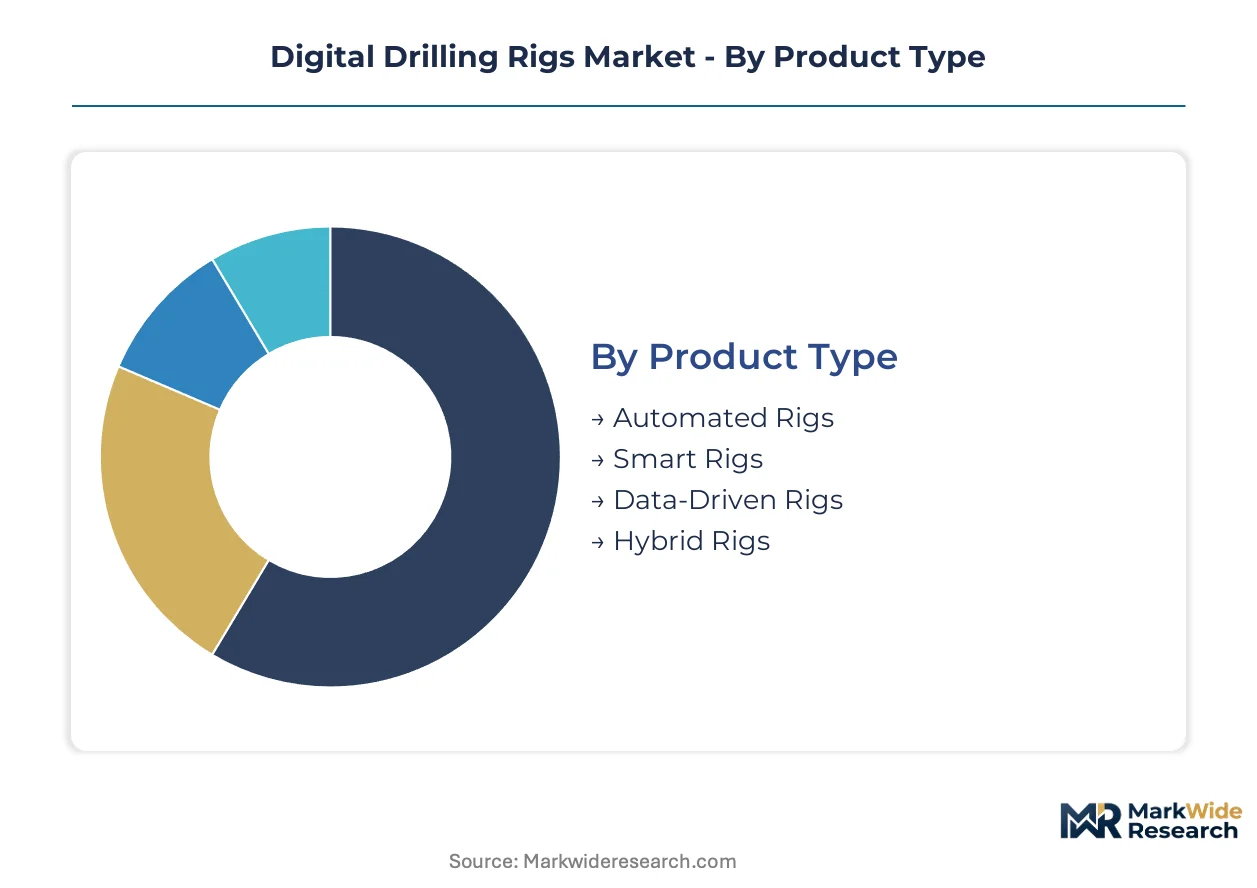
Segmentation reveals how regulatory certification burdens and automation intensity vary across rig architectures. Procurement patterns diverge sharply between offshore fleets facing BSEE mandates and onshore shale operators optimizing pad economics.
Product Type:
Certification requirements from the US Bureau of Safety and Environmental Enforcement and Norway's Petroleum Safety Authority apply unevenly across automation tiers, with fully automated systems demanding exhaustive functional safety documentation.
- Automated Rigs:These systems integrate iron roughneck automation, robotic pipe-handling, and closed-loop circulation under unified control architectures. Demand concentrates in the Permian Basin where multi-well pad drilling justifies capital intensity through repetition cycles. BSEE blowout preventer mandates accelerate fleet replacement toward these configurations.
- Smart Rigs:Semi-manual systems retain human intervention points for critical operations while digitizing monitoring and logging functions. Marginal basins in West Texas and southeastern New Mexico sustain residual demand where capital discipline delays full automation conversion.
- Data-Driven Rigs:Sensor-heavy platforms prioritize real-time telemetry over mechanical automation.
- Hybrid Rigs:Modular architectures allow selective automation upgrades without full platform replacement.
Automated Rigs sits at the top of the volume ranking, with Hybrid Rigs climbing the fastest as retrofit strategies gain traction among second-tier contractors.
Technology:
Cost tiers separate premium AI-enabled analytics from standardized connectivity layers, with pricing spreads reflecting computational intensity and regulatory validation requirements.
- AI:Predictive formation evaluation algorithms reduce stuck-pipe incidents through real-time downhole telemetry interpretation. Deepwater operators in the Gulf of Mexico command premium pricing for these capabilities where non-productive time costs escalate rapidly.
- IoT:Edge sensor networks feed unified data lakes for equipment health monitoring. Arctic deployments from Baker Hughes Company sustain uptime guarantees through specialized cold-climate hardware modules carrying substantial premiums.
- Cloud Computing:Centralized data processing enables fleet-wide benchmarking and remote expert support.
- Cybersecurity:IEC 62443-compliant network segmentation protects integrated control systems from operational technology threats.
IoT commands the largest installed base, while AI expands most quickly as offshore operators quantify stuck-pipe avoidance value.
End User:
Customer type determines procurement sophistication, with supermajors driving integrated platform specifications versus independent operators prioritizing modular, lease-based arrangements.
- Oil & Gas Companies:Integrated majors and large independents specify fully automated rigs with predictive maintenance subscriptions anchored to digital twin platforms. Schlumberger leverages these relationships for long-term service contracts across deepwater fleets.
- Mining Operations:Hard rock extraction applies drilling automation to blasthole and exploration applications with different torque and depth specifications than hydrocarbon targets.
- Geothermal Energy:Directional drilling into hot dry rock formations requires modified bottom-hole assembly cooling and cementing protocols.
- Research Institutions:Scientific drilling programs prioritize precision logging and sampling over rate-of-penetration optimization.
Oil & Gas Companies dominates segment revenue, with Geothermal Energy gaining share fastest as baseload renewable investment accelerates.
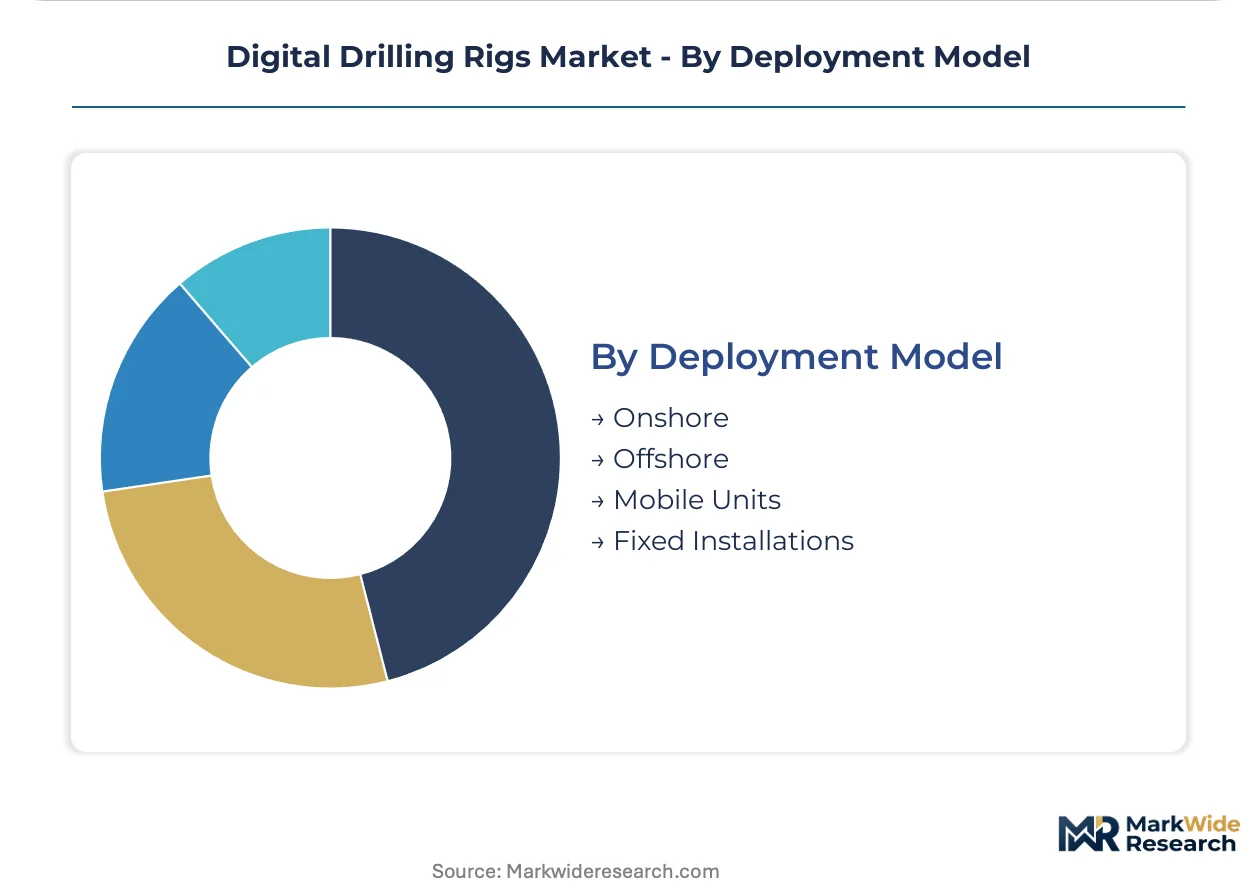
Deployment Model:
Geography and mobility requirements shape supply chain configuration, with offshore fixed installations demanding longest certification timelines and mobile onshore units optimizing logistics flexibility.
- Onshore:Pad drilling density in the Permian Basin creates economies of scale for autonomous pipe-handling deployments. EPA methane flaring rules tighten emissions protocols, driving specification of closed-loop circulation systems with integrated flare gas recovery compression.
- Offshore:Floating and fixed platforms in the Gulf of Mexico require BSEE-certified blowout preventer architectures with subsea equipment reliability documentation. Aging fleet renewal creates retrofit-ready automation opportunities.
- Mobile Units:Skid-mounted and walking systems relocate between well pads without full rig-down sequences.
- Fixed Installations:Platform-mounted rigs on production facilities drill development wells from permanent structures.
Onshore leads deployment volume, with Offshore showing the steepest expansion trajectory as deepwater fleet renewal accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States rig automation investment outpaces Norwegian offshore spending by roughly three-to-one in absolute terms, though Norway's per-rig digitalization intensity remains higher. Canada and China follow as secondary markets with distinct regulatory drivers shaping procurement patterns.
United States
Permian Basin pad drilling density drives autonomous pipe-handling demand across West Texas and southeastern New Mexico. The US Bureau of Safety and Environmental Enforcement enforces stricter blowout preventer testing protocols that accelerate fleet replacement cycles. Gulf of Mexico deepwater operators anchor digital twin service contracts to predictive maintenance platforms.
Norway
North Sea offshore platforms require integrated control system upgrades under functional safety mandates. The country's Petroleum Safety Authority demands exhaustive documentation that extends certification timelines for new automation architectures. Stavanger-based engineering clusters concentrate subsea equipment reliability expertise.
Canada
Arctic and extreme cold climate deployments sustain demand for specialized edge-computing hardware modules. Federal methane emissions regulations align with EPA protocols, driving closed-loop circulation specifications in Alberta's oil sands and British Columbia shale plays. Calgary serves as the primary procurement coordination hub.
China
State-directed unconventional gas development in Sichuan and Xinjiang basins absorbs automated rig imports alongside domestic manufacturing expansion. The Ministry of Ecology and Environment tightens drilling waste discharge standards that favor closed-loop systems. Shanghai-based equipment integrators coordinate technology transfer partnerships.
Brazil
Pre-salt deepwater fields require BSEE-equivalent subsea reliability certification for imported automation systems. The national petroleum regulator ANP coordinates with international standards for floating production platform integrations. Rio de Janeiro anchors engineering procurement for offshore fleet renewal programs.
Digital Drilling Rigs Market Competitive Landscape
Top-tier vendors anchor integrated platform supply, while mid-tier specialists compete on modular retrofit packages. The market structures around three distinct tiers: full-stack automation providers, component subsystem specialists, and regional rig fabricators licensing foreign control systems. Strategic moves concentrate on predictive maintenance subscription anchoring and Arctic-hardened hardware differentiation.
Among US-based energy service conglomerates, Schlumberger, Halliburton Company, and Baker Hughes Company exemplify divergent automation strategies. Schlumberger occupies a position emphasizing digital twin convergence for long-term service anchoring. Halliburton Company represents the integrated project delivery archetype across unconventional basins. Baker Hughes Company exemplifies edge-computing specialization for extreme environment uptime guarantees.
| Leading Market Players |
|---|
| Schlumberger |
| Halliburton Company |
| Baker Hughes Company |
| Helmerich & Payne, Inc. |
| Nabors Industries Ltd. |
| NOV Inc. |
| Weatherford |
| Transocean Ltd. |
| Pason Systems Corp. |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up rig automation specialists anchor supply-side concentration in Houston and Stavanger, translating capital discipline into pricing power for integrated control systems while squeezing margins on modular retrofit packages.
Pricing Analysis
Capacity additions in China's Sichuan and Xinjiang basins are reshaping price floors for standard automated rig configurations. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled predictive maintenance bundles from basic iron roughneck automation. Cost compression in economy-tier hardware is intensifying because domestic Chinese OEMs expand manufacturing scale. Independent shale operators in the Permian Basin exhibit highest price sensitivity, while Gulf of Mexico supermajors accept premium positioning for BSEE-certified subsea architectures.
Supply Chain Analysis
Domestic-content mandates in Brazil's pre-salt sector and China's unconventional gas programs are reshaping sourcing patterns for blowout preventer assemblies and integrated control systems. Manufacturing concentrates in the United States, Norway, and China for advanced automation hardware. Supply chains draw from specialized foundries in Germany for high-pressure valves, Japanese sensor manufacturers for downhole telemetry, and South Korean electronics suppliers for edge-computing modules. Single-source vulnerability around Arctic-hardened semiconductor components poses structural risk. Distribution runs through rig OEM direct sales teams and oilfield service integrators with regional technical support capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where BSEE blowout preventer mandates and EPA methane flaring rules continuously refresh replacement demand across installed fleets.
For Market Incumbents: Hedge against modular retrofit specialists by anchoring long-term predictive maintenance subscriptions to digital twin platforms. Acquire Arctic edge-computing capabilities to defend uptime guarantee positioning against Baker Hughes Company's extreme-environment specialization. Prioritize certification investment for Norway's Petroleum Safety Authority functional safety documentation to extend platform lock-in. For New Entrants and Emerging Players: Enter via geothermal energy drilling automation where directional bottom-hole assembly cooling requirements create specification white space. Target hybrid rig retrofit opportunities among second-tier contractors in West Texas marginal basins where capital discipline delays full automation conversion. Lead with lease-based procurement models to bypass incumbent service contract anchoring. For Investors and Strategic Acquirers: Valuations sit cheapest among semi-manual Smart Rig fabricators with installed base conversion potential. Five-to-ten year viability hinges on regulatory compliance cost absorption rather than pure technology differentiation. Target acquisition archetype: regional rig builders with BSEE pre-certification engineering capabilities. Watch EPA enforcement intensity on methane flaring as inflection signal for closed-loop circulation system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Subscription Anchoring | Schlumberger's digital twin platform locks in multi-year service revenue across deepwater fleets. |
| Arctic-Hardened Hardware Specialization | Baker Hughes Company sustains 40-60% pricing premiums through extreme-cold uptime guarantees. |
| Regulatory Certification Pre-Investment | Early BSEE blowout preventer documentation accelerates fleet replacement procurement cycles. |
| Hybrid Rig Modular Retrofit Packaging | Second-tier contractors in Permian marginal basins justify automation spend through selective upgrade paths. |
| Geothermal Directional Drilling Adaptation | Hot dry rock cementing protocols open baseload renewable investment channels outside hydrocarbon cyclicality. |
Research Methodology
Multiple input streams — rig OEM product managers, offshore drilling contractors, BSEE regulatory compliance officers, and petroleum safety authority documentation specialists — were reconciled against customs data, SEC oilfield service filings, and Norwegian Petroleum Safety Authority certification databases. Bottom-up rig deployment tallies across the Permian Basin and Gulf of Mexico were cross-referenced with top-down oilfield capital expenditure tracking from operator earnings disclosures.
Historical rig automation adoption curves were cross-referenced against panel input from fleet engineering directors to establish projection baselines across the analysis window. Segmentation dimensions modeled include automation tier, technology intensity, end-user sophistication, and deployment geography. CAGRs were derived from equipment procurement cycle analysis and regulatory compliance deadline clustering. Industry-specific forecast inputs incorporated BSEE equipment testing protocol phase-in schedules and EPA methane monitoring mandate implementation timelines.
Inputs from operator maintenance logs and OEM service contract databases were available through the study window; gaps in real-time downhole telemetry performance benchmarking introduce uncertainty bands around AI-enabled analytics penetration assumptions. Forecasts reflect documented regulatory milestone assumptions and commodity price scenario sensitivity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Middle East and Africa Digital Oilfield Market
Oil & Gas
Asia-Pacific Liner Hanger System Market
Oil & Gas
Oil and Gas Processing Seals Market
Oil & Gas
North Sea Oil and Gas Upstream Market
Oil & Gas
Saudi Arabia Drilling Rigs Market
Oil & Gas
Subsea Manifolds Market
Oil & Gas
North America Digital Oilfield Market
Oil & Gas
Distributed Fiber Optic Sensor in Oil & Gas Market
Oil & Gas
Egypt Oil and Gas Market
Oil & Gas
Egypt Natural Gas Market
Oil & Gas
India AI in Oil and Gas Market
Oil & Gas
Asia-Pacific Intelligent Pigging Market
Oil & Gas
United States Wireline Logging Services Market
Oil & Gas
United States Oil and Gas Separation Market
Oil & Gas
Delayed Coker Unit Market
Oil & Gas
Wireline Services Market