
 Latin America Pumps Market | 2026-2036
Latin America Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Pumps Market Foresight
Direct distribution through OEM service networks is fragmenting across Latin America as local distributors and rental-service hybrids capture maintenance-intensive segments. Grundfos leverages its digital monitoring platforms to anchor premium positions in Brazil's municipal water sector. KSB SE & Co. KGaA competes through localized manufacturing in Mexico, sustaining cost advantages for North American export-linked buyers. Ebara Corporation specializes in corrosion-resistant alloys for Chilean mining dewatering, occupying a defensible niche in copper extraction operations.
Pumps are mechanical devices that impart kinetic energy to fluids through impeller rotation, piston displacement, or diaphragm oscillation, with performance calibrated by flow rate, head pressure, and net positive suction head parameters. These machines serve essential functions in process industries, infrastructure systems, and resource extraction where controlled fluid movement determines operational continuity. Centrifugal pumps dominate volume across Latin American oil terminals and desalination plants due to their scalability in high-flow, moderate-head applications. Positive displacement technology captures margin concentration in Mexico's food processing sector, where precise metering of viscous ingredients commands premium positioning. Submersible installations are accelerating in Colombia's underground mining revival, reflecting deeper excavation trends and stricter dewatering requirements.
Brazil's INMETRO certification mandates efficiency labeling for electric motor-driven pumps, reshaping procurement criteria for industrial buyers across São Paulo and Minas Gerais states. Mexico's CONAGUA water authority enforces leakage reduction targets that accelerate diaphragm pump adoption in precision chemical dosing for treatment plants. ANA regulations in Brazil restrict groundwater extraction rates, forcing agricultural pump users toward higher-efficiency hydraulic systems in the Cerrado belt. Stakeholders must monitor how evolving efficiency standards and water scarcity policies across these regulatory frameworks reshape replacement cycles and technology migration paths.
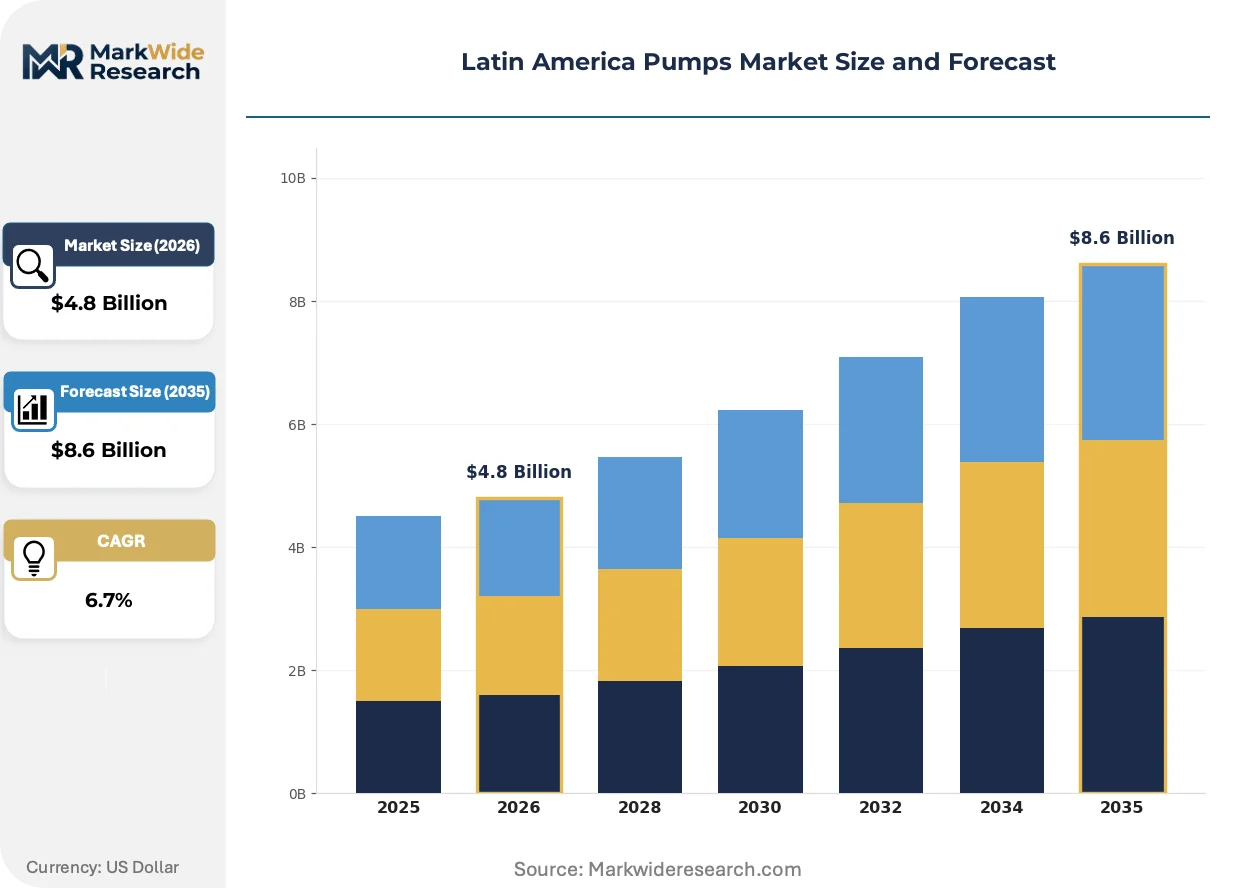
Market Dynamics
Efficiency mandates from Brazil's ANA and INMETRO are compressing replacement cycles across Latin America's pump-installed base, forcing industrial buyers toward higher-specification equipment despite elevated capital requirements. This regulatory pressure layer intersects with water scarcity policies in Mexico and Colombia to reshape procurement criteria toward lifecycle cost optimization rather than upfront acquisition price.
Growth Catalysts
- ANA groundwater extraction limits:Brazil's water agency restrictions on agricultural pumping rates in the Cerrado belt are accelerating demand for variable-frequency drive systems and precision hydraulic controls that maintain output within permitted thresholds.
- Mexico's CONAGUA leakage targets:The national water authority's pressure management mandates are driving diaphragm pump procurement for precision chemical dosing in municipal treatment infrastructure across the Valley of Mexico.
- Copper extraction depth trends:Chilean mining operations are deploying submersible dewatering systems at progressively deeper excavation levels, creating sustained replacement demand for corrosion-resistant alloy pump configurations.
Market Restraints
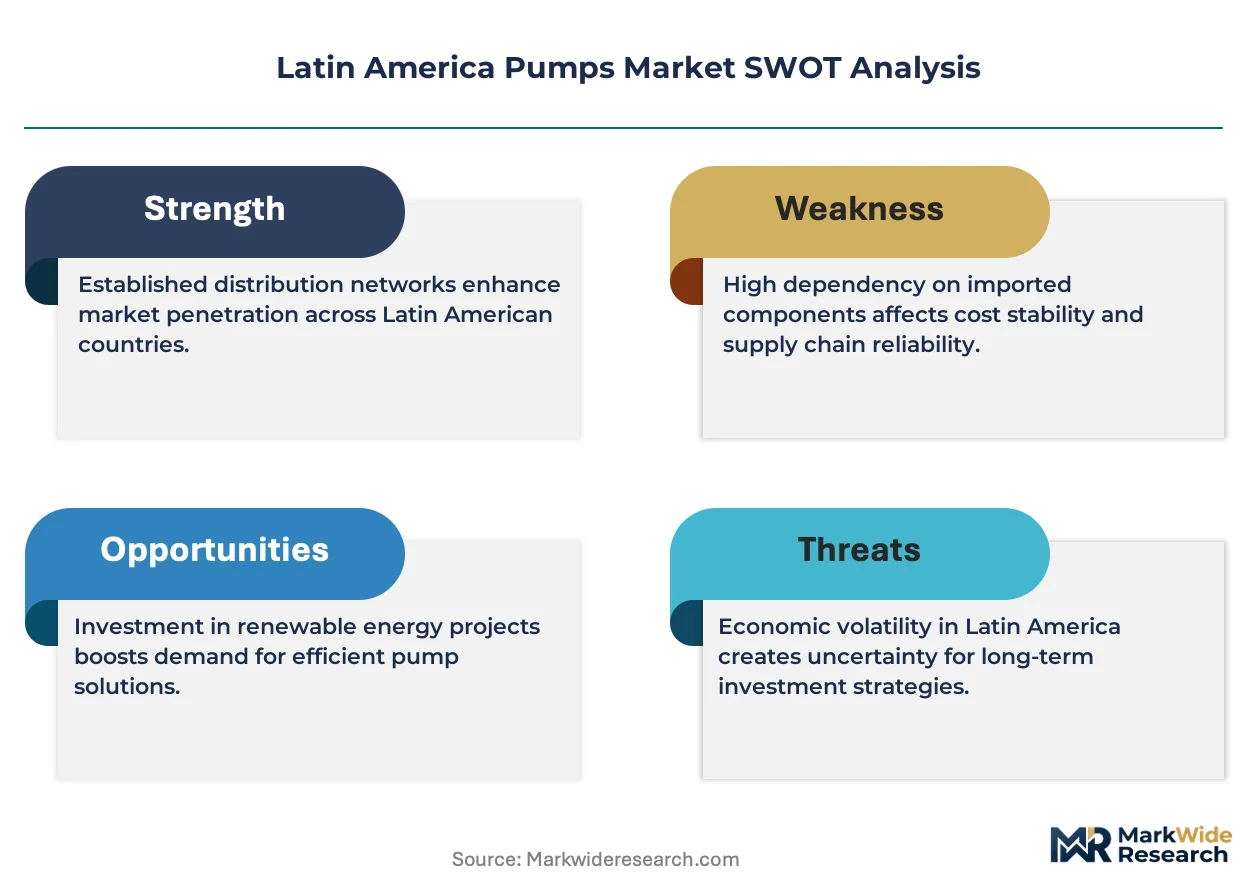
- Specialized alloy cost volatility:Nickel and chromium price swings directly compress margins for corrosion-resistant pump manufacturing destined for Chilean mining and Brazilian petrochemical clusters.
- Import dependency for high-efficiency motors:Localized electric motor production remains concentrated in Mexico and Brazil, leaving Andean markets exposed to currency fluctuation and extended lead times for INMETRO-certified drive systems.
- Technical limitation in abrasive slurry handling:Centrifugal impeller designs face accelerated wear rates in Colombian coal and Brazilian iron ore slurry transport, restricting equipment life below depreciation schedules.
Strategic Opportunities
- Colombia's underground mining revival:Deeper excavation permits in the Boyacá and Antioquia regions are creating unmet demand for submersible dewatering systems with integrated monitoring capabilities.
- Digital monitoring convergence:IoT-enabled vibration and temperature sensing is merging with predictive maintenance platforms to create subscription-based service models for Brazilian municipal water utilities.
- Argentina's Vaca Muerta development:Unconventional oil and gas extraction in Neuquén province requires high-pressure injection pumps for hydraulic fracturing operations, representing a geographically concentrated white space.
Industry Challenges
- Certification timeline compression:INMETRO efficiency labeling requirements and ANA equipment registration processes are extending product approval cycles by four to six months for imported pump systems.
- Fluid dynamics simulation expertise scarcity:Computational modeling capability for custom hydraulic design remains concentrated in São Paulo and Mexico City engineering consultancies, constraining regional OEM development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Pumps Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal, Positive Displacement, Submersible, Diaphragm End Use Industry: Oil & Gas, Water & Wastewater, Chemicals, Food & Beverage Technology: Electric, Pneumatic, Hydraulic, Manual Installation Type: Above Ground, Underground, Portable, Stationary |
| Companies Covered | ITT Inc., KSB SE & Co. KGaA, Grundfos, Ruhrpumpen Group, Weir Group PLC, Sulzer Ltd, Ebara Corporation, Wilo SE, Baker Hughes Company, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Pumps Market Shifts & Advancements
Pump system architecture across Latin America is undergoing fundamental restructuring as efficiency regulations tighten and operational data becomes a competitive differentiator. Equipment suppliers are repositioning around lifecycle service capabilities rather than hardware margins.
Variable-frequency drive integration with cloud-based performance monitoring is digitizing maintenance scheduling for Brazilian municipal water utilities. SABESP and other state operators are adopting these systems to demonstrate compliance with ANA efficiency benchmarks. The technology is digitizing traditional break-fix service relationships into continuous optimization contracts that lock in multi-year vendor relationships.
INMETRO's mandatory efficiency labeling program for electric motor-driven pumps is eliminating substandard equipment from Brazil's industrial procurement channels. The regulation forces São Paulo and Minas Gerais manufacturing facilities to retire legacy fixed-speed installations ahead of scheduled replacement cycles. Petrochemical and sugar-ethanol processors are responding by consolidating vendor relationships with suppliers offering certified retrofit packages.
After-sales service unbundling is fragmenting traditional OEM distribution models across Mexico's food processing sector. Mid-sized dairy and beverage producers are sourcing precision metering pumps through specialized maintenance contractors rather than direct manufacturer relationships. This channel shift concentrates most visibly in Jalisco and Querétaro states where independent service networks have achieved technical certification for diaphragm and peristaltic system overhaul.
Latin America Pumps Market Segmentation
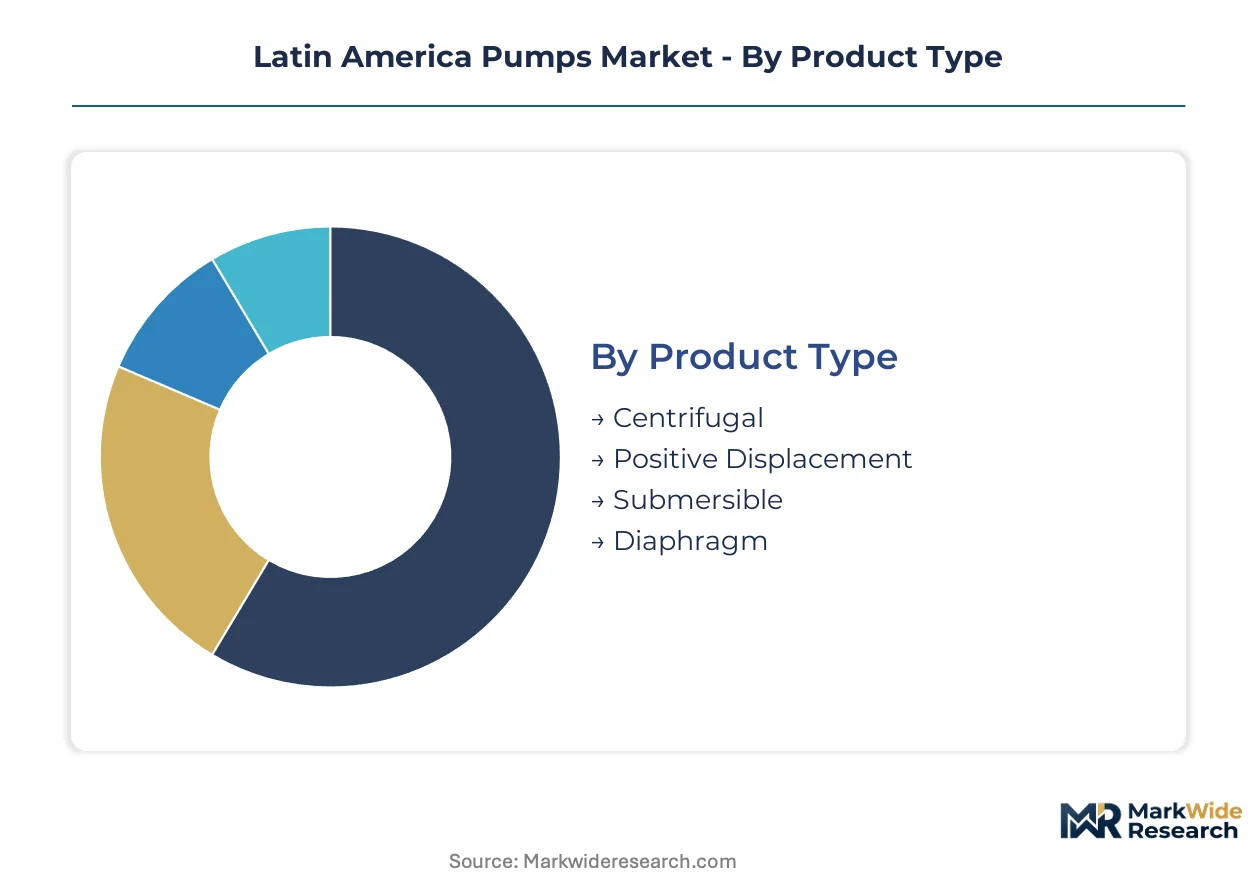
Pump procurement across Latin America fragments along technical specifications, operational environments, and regulatory compliance requirements. Understanding how these dimensions intersect reveals where pricing power concentrates and which technology migrations are accelerating replacement cycles.
Product Type:
Mature hydraulic architectures dominate installed base volumes while emerging designs capture specification upgrades driven by efficiency mandates.
- Centrifugal:Impeller-driven kinetic energy transfer achieves high-flow, moderate-head performance with scalable configurations. Brazilian petrochemical terminals and Chilean desalination facilities concentrate demand as ANA efficiency benchmarks force replacement of fixed-speed legacy installations.
- Positive Displacement:Reciprocating or rotary mechanisms deliver precise volumetric output independent of discharge pressure. Mexico's Jalisco dairy processors and Querétaro beverage manufacturers specify these systems for viscous ingredient metering where flow accuracy determines product consistency.
- Submersible:Motor and pump integrated for submerged operation in boreholes or sumps. Colombian mining operations in Boyacá deploy these for deep excavation dewatering.
- Diaphragm:Flexible membrane isolates fluid from mechanical components. CONAGUA-mandated chemical dosing stations across Valley of Mexico treatment plants drive procurement.
Centrifugal retains volume leadership; diaphragm holds the steepest expansion curve.
End Use Industry:
Application-specific performance requirements create divergent margin structures across Latin America's industrial base.
- Oil & Gas:High-pressure injection and transfer operations demand ruggedized construction for abrasive crude handling. Argentina's Vaca Muerta unconventional development in Neuquén province requires hydraulic fracturing pump systems with pressure ratings exceeding conventional specifications.
- Water & Wastewater:Municipal infrastructure upgrades prioritize lifecycle cost optimization over upfront capital. SABESP and other Brazilian state operators anchor demand as ANA regulations mandate efficiency labeling compliance.
- Chemicals:Corrosive fluid handling necessitates specialized alloy selection. Brazilian São Paulo state petrochemical clusters specify corrosion-resistant configurations.
- Food & Beverage:Hygienic design standards govern equipment selection. Mexico's mid-sized processors increasingly source through independent maintenance contractors rather than OEM direct channels.
Water & Wastewater commands the largest installed base; Oil & Gas is gaining share fastest.
Technology:
Power transmission methods segment by operational precision requirements and energy efficiency compliance thresholds.
- Electric:Motor-driven systems dominate industrial procurement with variable-frequency drive integration enabling ANA-compliant efficiency performance. INMETRO certification mandates reshape Brazilian buyer criteria toward labeled equipment.
- Pneumatic:Compressed air power suits explosive atmosphere applications and precise flow modulation. Mexican food processing facilities specify these for ingredient transfer where electrical ignition risks exist.
- Hydraulic:Fluid power transmission delivers high torque density for heavy-duty mining dewatering. Colombian underground operations in Antioquia deploy these for deep-pit extraction.
- Manual:Human-operated systems serve remote maintenance and emergency backup roles. Small-scale Brazilian agricultural operations in Cerrado belt use these for supplemental irrigation.
Electric dominates procurement volumes; pneumatic is climbing the fastest.
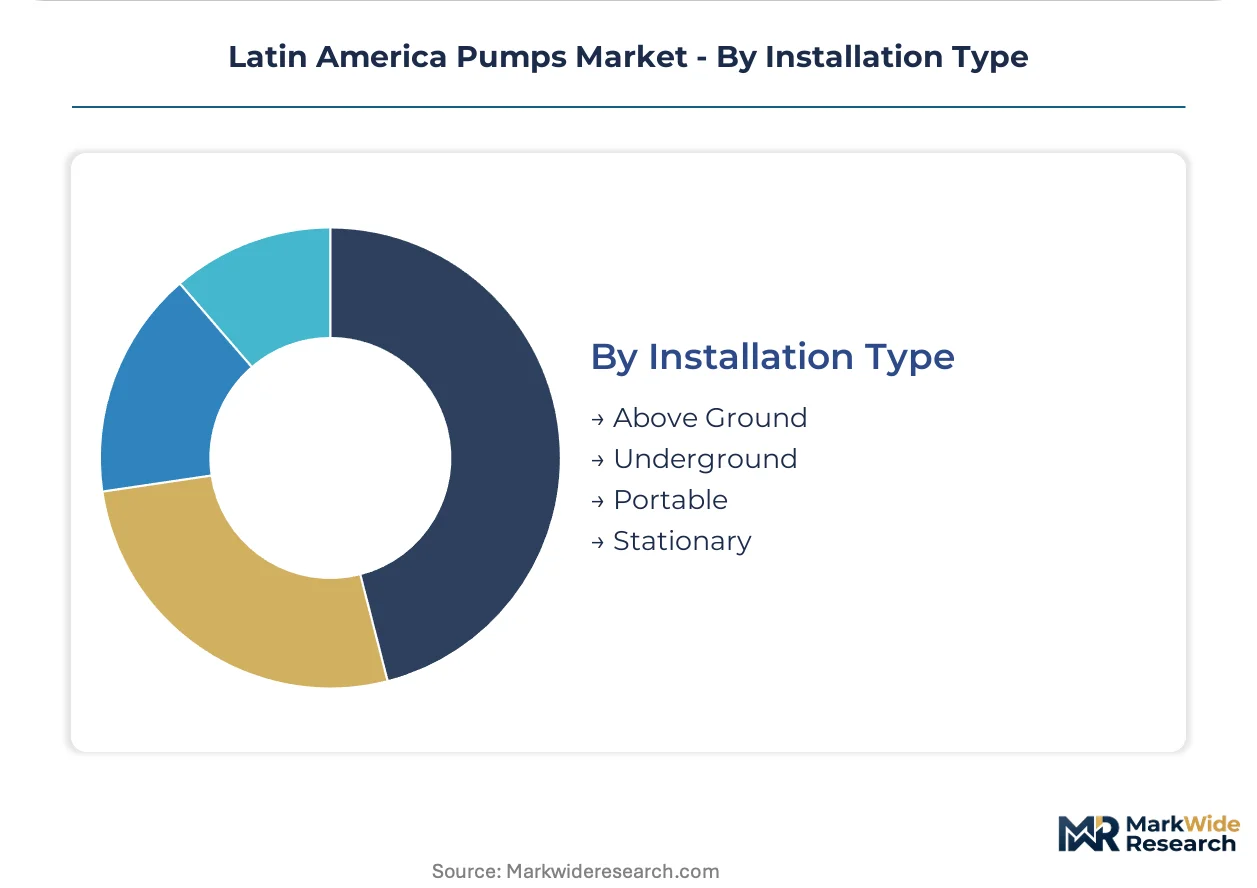
Installation Type:
Physical deployment configurations align with site constraints, mobility requirements, and maintenance access protocols.
- Above Ground:Surface-mounted systems facilitate maintenance access and monitoring integration. Brazilian Southeast industrial corridor facilities prefer these for petrochemical and sugar-ethanol processing where vibration sensing enables predictive maintenance contracts.
- Underground:Subsurface placement reduces noise exposure and environmental footprint. Chilean copper extraction operations at depth specify corrosion-resistant submersible configurations.
- Portable:Mobile mounting supports temporary dewatering and emergency response. Colombian mining contractors deploy these for site-specific groundwater management.
- Stationary:Fixed installations anchor municipal water infrastructure. Mexican Valley of Mexico treatment plants specify these for permanent chemical dosing stations.
Above Ground retains volume leadership; Underground holds the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands pricing premiums through ANA-mandated efficiency standards while Mexican buyers leverage localized manufacturing for cost advantages. This asymmetry concentrates procurement power in São Paulo's industrial corridor against Monterrey's export-linked assembly bases.
Brazil
ANA groundwater extraction limits and INMETRO efficiency labeling compress replacement cycles across São Paulo and Minas Gerais states. The Southeast industrial corridor anchors demand as petrochemical and sugar-ethanol processors consolidate vendor relationships around certified retrofit packages.
Mexico
CONAGUA leakage reduction targets drive diaphragm pump procurement for precision chemical dosing in Valley of Mexico treatment plants. Jalisco and Querétaro food processors increasingly source through independent maintenance contractors rather than OEM direct channels.
Chile
Copper extraction depth trends create sustained replacement demand for corrosion-resistant submersible dewatering systems. Mining operations in Antofagasta and Atacama deploy these configurations at progressively deeper excavation levels.
Colombia
Underground mining revival in Boyacá and Antioquia generates unmet demand for submersible systems with integrated monitoring capabilities. Deeper excavation permits force contractors toward mobile dewatering solutions for site-specific groundwater management.
Argentina
Vaca Muerta unconventional development in Neuquén province requires high-pressure injection pumps for hydraulic fracturing operations. This geographically concentrated white space represents specialized procurement outside established distribution networks.
Latin America Pumps Market Competitive Landscape
Full-service OEMs and regional specialists split the market between premium lifecycle contracts and cost-driven equipment supply. The installed base concentrates around three strategic archetypes: European-headquartered multinationals with digital service platforms, Asian manufacturers with corrosion-resistant alloy specializations, and regional distributors with maintenance-contractor hybrids. Dominant competitive moves include backward integration into localized motor production and technology licensing for INMETRO-certified efficiency systems.
Among European-based OEMs, Grundfos and KSB SE & Co. KGaA exemplify the full-service archetype through digital monitoring platforms and localized manufacturing positions. Ebara Corporation occupies a specialist tier focused on corrosion-resistant configurations. These three anchors demonstrate how geographic origin and company structure correlate with strategic positioning across Latin America's divergent regulatory environments.
| Leading Market Players |
|---|
| ITT Inc. |
| KSB SE & Co. KGaA |
| Grundfos |
| Ruhrpumpen Group |
| Weir Group PLC |
| Sulzer Ltd |
| Ebara Corporation |
| Wilo SE |
| Baker Hughes Company |
| Others |
Supply & Pricing Matrix
Monterrey's export-linked manufacturing corridor concentrates electric motor assembly capacity, feeding downstream pricing power to North American buyers while Brazilian purchasers absorb INMETRO certification premiums. This geographic asymmetry compresses margins for Andean distributors sourcing certified drive systems through extended import channels.
Pricing Analysis
The customization-premium spread spans configured-to-order corrosion-resistant alloys against standard cast-iron configurations. Project-based pricing dominates mining and oil terminal procurement, while municipal water utilities negotiate multi-year lifecycle contracts bundling hardware with predictive maintenance subscriptions. Price differentiation hinges on INMETRO efficiency certification tier and after-sales service bundling depth. Cost compression in standard centrifugal equipment is intensifying as Chinese manufacturers penetrate Brazil's mid-tier industrial segment. Mid-sized Mexican food processors exhibit highest price sensitivity, deferring replacement cycles until regulatory deadlines force compliance expenditure.
Supply Chain Analysis
Upstream nickel and chromium feedstock volatility from Indonesian and South African mining operations transmits directly to corrosion-resistant pump margins. Manufacturing capacity concentrates in Germany, China, and Mexico, with Brazilian assembly plants dependent on imported high-efficiency motor components. Single-source vulnerability persists for INMETRO-certified variable-frequency drive systems sourced from São Paulo and Monterrey facilities. Distribution runs through OEM direct channels for large municipal contracts, while independent maintenance-contractor hybrids capture mid-tier industrial segments across Jalisco and Querétaro.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated municipal water utilities bundling multi-year service contracts, fragmenting traditional OEM pricing leverage. SABESP and comparable state operators now dictate vendor qualification criteria through ANA-mandated efficiency benchmarks.
For Market Incumbents: Pre-empt margin erosion in standard centrifugal equipment by anchoring subscription-based digital monitoring platforms with Brazilian state water operators. Defend position against Chinese mid-tier entrants through backward integration into localized motor production in Minas Gerais. Prioritize certification investment for INMETRO efficiency labeling to maintain procurement channel access. For New Entrants and Emerging Players: Establish a beachhead in Colombia's underground mining dewatering segment where unmet demand for integrated monitoring capabilities exceeds incumbent service capacity. Target portable submersible configurations for Boyacá and Antioquia contractors facing deeper excavation permits. Deploy rental-service hybrid models to bypass entrenched OEM distribution relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors corrosion-resistant alloy specialists with captive mining sector relationships over commodity centrifugal manufacturers. Long-term viability rests on lifecycle service revenue capture rather than hardware shipment volumes. Acquisition target archetype: regional distributors with certified maintenance capabilities in ANA-regulated Brazilian states. Watch for ANA groundwater extraction limit enforcement intensity as inflection indicator for variable-frequency drive demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Manufacturing | Captive supply of INMETRO-certified drive systems secures Brazilian procurement channel access against import dependency. |
| Digital Monitoring Platform Deployment | IoT-enabled predictive maintenance contracts lock in multi-year SABESP relationships beyond hardware replacement cycles. |
| Corrosion-Resistant Alloy Capacity Expansion | Dedicated nickel-chromium fabrication lines capture Chilean copper dewatering specification upgrades at depth. |
| Maintenance-Contractor Hybrid Partnership | Technical certification transfer enables Jalisco dairy processor access without direct OEM sales force investment. |
| Variable-Frequency Drive Retrofit Packaging | Certified efficiency upgrade bundles accelerate ANA compliance-driven replacement cycles in São Paulo petrochemical clusters. |
Research Methodology
Desk research of customs trade databases, INMETRO certification registries, and ANA groundwater extraction permits preceded structured interviews with maintenance directors at Brazilian sugar-ethanol processors, procurement leads at Chilean mining operations, and aftermarket service heads at Mexican food processing facilities. Secondary validation drew from CONAGUA infrastructure investment disclosures, SEC filings of listed pump manufacturers, and regional EPC contractor project databases. Bottom-up equipment shipment analysis triangulated against top-down municipal capital expenditure forecasts.
Assumptions held fixed include ANA regulatory enforcement intensity and nickel-chromium price bands; varied conditions encompassed CONAGUA leakage target acceleration and Colombian mining permit depth extensions. The analytical framework modeled product type, end-use industry, technology, and installation type dimensions across the projection horizon. CAGRs derived from replacement cycle compression rates under efficiency mandate scenarios, incorporating pump life depreciation schedules and municipal budget allocation patterns.
Stress conditions across Brazilian currency fluctuation, Chinese export pricing, and Chilean mining investment cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory timeline adherence and alloy cost stability. Cross-checking against SABESP and CONAGUA published procurement plans is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Air-Operated Double Diaphragm (AODD) Pumps Market
Pumps and Control Devices
Automatic Water Level Controller Market
Pumps and Control Devices
Mixed Flow Pump Market
Pumps and Control Devices
Suction Pump Market
Pumps and Control Devices
Electric Oil Pump Market
Pumps and Control Devices
Fire Pump Test Meters Market
Pumps and Control Devices
Chemical Pump Market
Pumps and Control Devices
Global Positive Displacement (PD) Pumps Market
Pumps and Control Devices
Worm Pumps Market
Pumps and Control Devices
Fluid Power Equipment Market
Pumps and Control Devices
Slurry Pumps Market
Pumps and Control Devices
Industrial Pump Control Panels Market
Pumps and Control Devices
Spiral Classifier Market
Pumps and Control Devices
Global Industrial Submersible Pumps Market
Pumps and Control Devices
Global Lubrication Pumps Market
Pumps and Control Devices
Dewatering Pumps Market