
 Europe Seismic Survey Market | 2026-2036
Europe Seismic Survey Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Seismic Survey Market Foresight
Project finance structures tied to multi-client seismic libraries are reshaping competitive dynamics across the European maritime survey sector. Fugro NV leverages its integrated vessel and sensor fleet to control data collection costs in the North Sea. CGG SA anchors its position through proprietary high-resolution imaging algorithms purpose-built for complex salt formations. Shearwater GeoServices Holding AS competes by extending its fleet of modern streamer vessels into frontier basins west of Ireland and the Barents Sea.
Seismic survey denotes the geophysical method of mapping subsurface structures through controlled energy source propagation and reflected wavefield recording, typically employing air-gun arrays towed at 5-10 meter depths and hydrophone streamers extending 6-12 kilometers behind acquisition vessels. The technique enables hydrocarbon exploration, carbon storage site qualification, and offshore wind foundation assessment across Europe's continental shelf. Data acquisition services command the largest revenue share given vessel day-rate structures and fuel-intensive operations, while 4D seismic technology represents the fastest-expanding segment as operators repeat 3D surveys to track fluid displacement in producing reservoirs. Oil and gas end users retain dominant demand share, though environmental applications for offshore wind site investigation are building new margin pools.
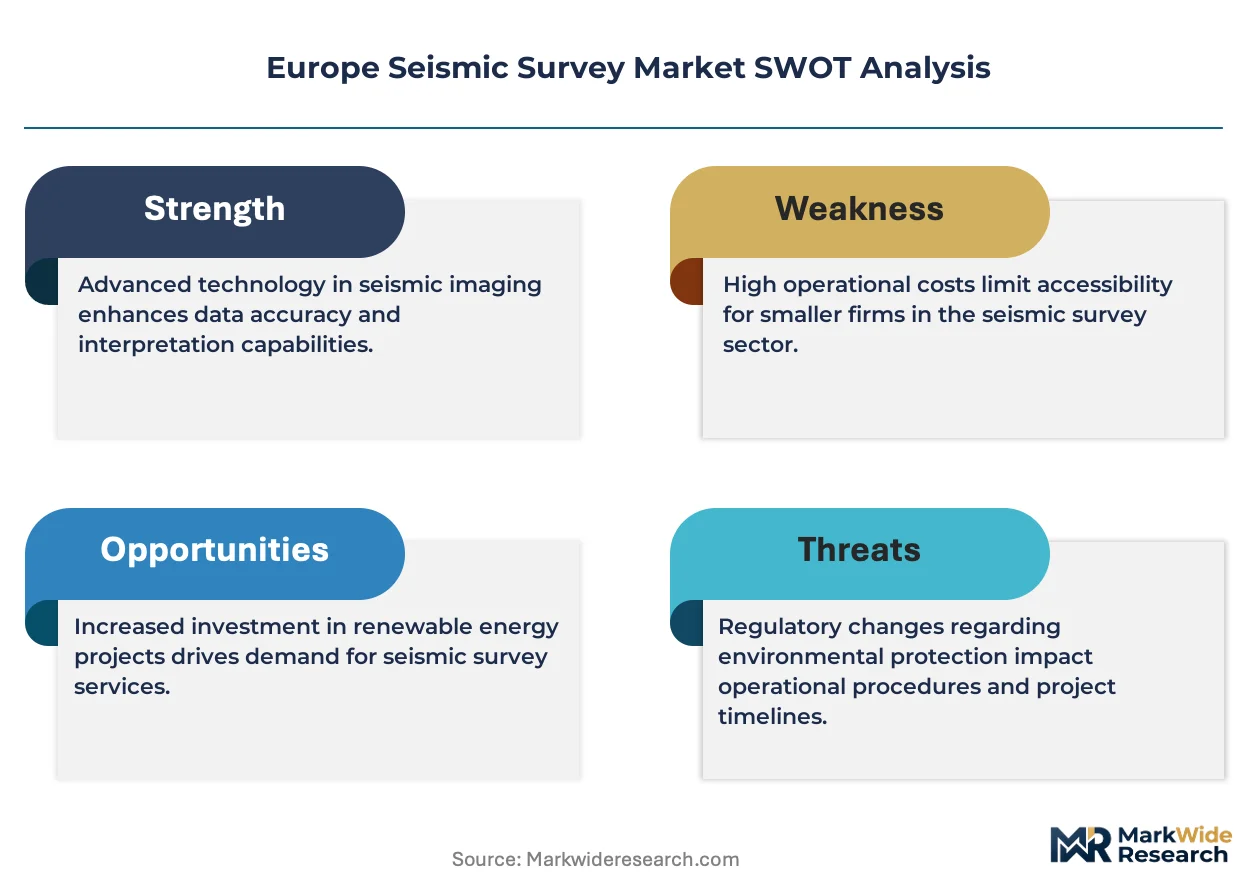
EMA guidelines on offshore noise mitigation and the EU Marine Strategy Framework Directive constrain survey timing and source specifications in sensitive habitats, directly shaping vessel deployment schedules and equipment configurations. REACH compliance for hydraulic fluids and lubricants aboard survey vessels adds material certification costs that filter into service pricing. Norway's Petroleum Safety Authority and the UK's North Sea Transition Authority both mandate seismic data submission as part of field development plan approvals, embedding regulatory compliance into core procurement workflows. Stakeholders must monitor how the EU's expanding offshore wind leasing rounds redirect specialized acquisition capacity from hydrocarbon surveys to seabed characterization contracts.
Market Dynamics
The EU Green Deal's methane emissions reduction mandates are compressing survey timelines and forcing operators to adopt higher-resolution reservoir characterization before field development approvals. This regulatory pressure is redistributing vessel capacity across the North Sea and accelerating technology refresh cycles among acquisition contractors.
Growth Catalysts
- 4D seismic monitoring:North Sea operators are repeating 3D surveys to track fluid displacement in mature reservoirs, extending field life and recovery rates.
- EU Marine Strategy Framework Directive:Environmental baseline requirements for offshore wind leasing are generating new seabed characterization contracts west of Ireland.
- Carbon storage site qualification:Saline aquifer and depleted field assessment for CO2 injection is opening procurement channels outside traditional hydrocarbon budgets.
Market Restraints
- Specialized vessel scarcity:The global fleet of ice-class streamer vessels concentrates among Norwegian and UK operators, limiting spot market availability.
- Fuel cost volatility:Marine gasoil price swings directly compress day-rate margins for multi-client library operators.
- Air-gun source restrictions:EMA guidelines on offshore noise mitigation constrain survey windows in sensitive habitats, reducing effective operating days.
Strategic Opportunities
- Barents Sea frontier basins:Norway's northern licensing rounds are attracting specialized acquisition capacity for harsh-environment operations.
- Offshore wind foundation assessment:Geotechnical surveys for monopile and jacket installations are displacing hydrocarbon work in North Sea vessel scheduling.
- High-resolution imaging algorithms:Convergence of machine learning with seismic processing is compressing interpretation timelines for complex salt formations.
Industry Challenges
- Geophysicist talent pipeline:University programs in seismic interpretation are not replenishing retirement losses at major acquisition houses.
- REACH compliance certification:Hydraulic fluid and lubricant material approvals are extending vessel dry-dock timelines.
- Legacy data integration:Decades of 2D and 3D seismic archives require format standardization before AI-assisted reprocessing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Seismic Survey Market |
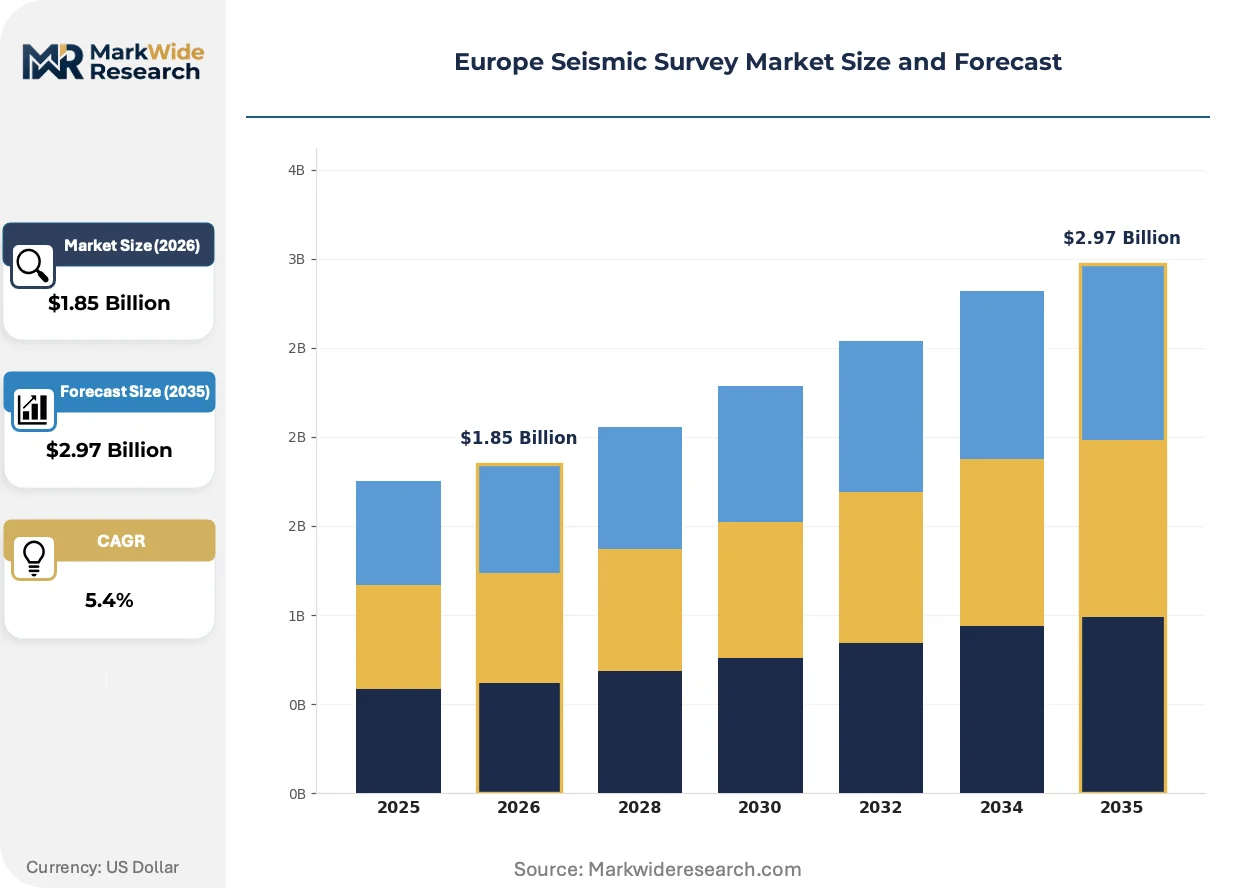
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Acquisition, Data Processing, Interpretation, Consulting Technology: 2D Seismic, 3D Seismic, 4D Seismic, Reflection Seismology End User: Oil & Gas, Mining, Construction, Environmental Application: Hydrocarbon Exploration, Reservoir Characterization, Site Investigation, Subsurface Mapping |
| Companies Covered | Fugro NV, ION Geophysical Corporation, Halliburton Company, PGS, SAExploration Holdings Inc, Schlumberger Ltd, CGG SA, TGS, Shearwater GeoServices Holding AS, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Seismic Survey Market Shifts & Advancements
Seismic acquisition technology is hybridizing across energy sectors, with equipment originally developed for hydrocarbon exploration migrating into carbon storage and offshore wind site investigation. This convergence is compressing development cycles and forcing contractors to reconfigure sensor packages between contract types.
Node-based ocean-bottom seismic technology is hybridizing with traditional towed-streamer acquisition, enabling simultaneous recording of pressure and shear-wave data. North Sea operators are deploying hybrid spreads for 4D reservoir monitoring, reducing repeat survey uncertainty. This convergence is compressing the timeline between acquisition and reservoir model update, tightening feedback loops for production optimization.
REACH compliance for hydraulic fluids and lubricants aboard survey vessels is forcing material requalification across the European fleet. The European Chemicals Agency's substance restrictions are extending procurement lead times for critical vessel components. Norway's Petroleum Safety Authority and the UK's North Sea Transition Authority are both embedding chemical compliance checks into field development plan approvals, affecting vessel deployment schedules.
Multi-client seismic data licensing is displacing proprietary acquisition for frontier basin evaluation, compressing upfront capital requirements for exploration teams. Independent operators are purchasing pre-existing 3D volumes rather than commissioning new shoots, redirecting contractor revenue toward 4D monitoring and carbon storage site work. This shift concentrates most visible in the UK and Netherlands sectors, where mature data libraries cover extensive acreage.
Europe Seismic Survey Market Segmentation
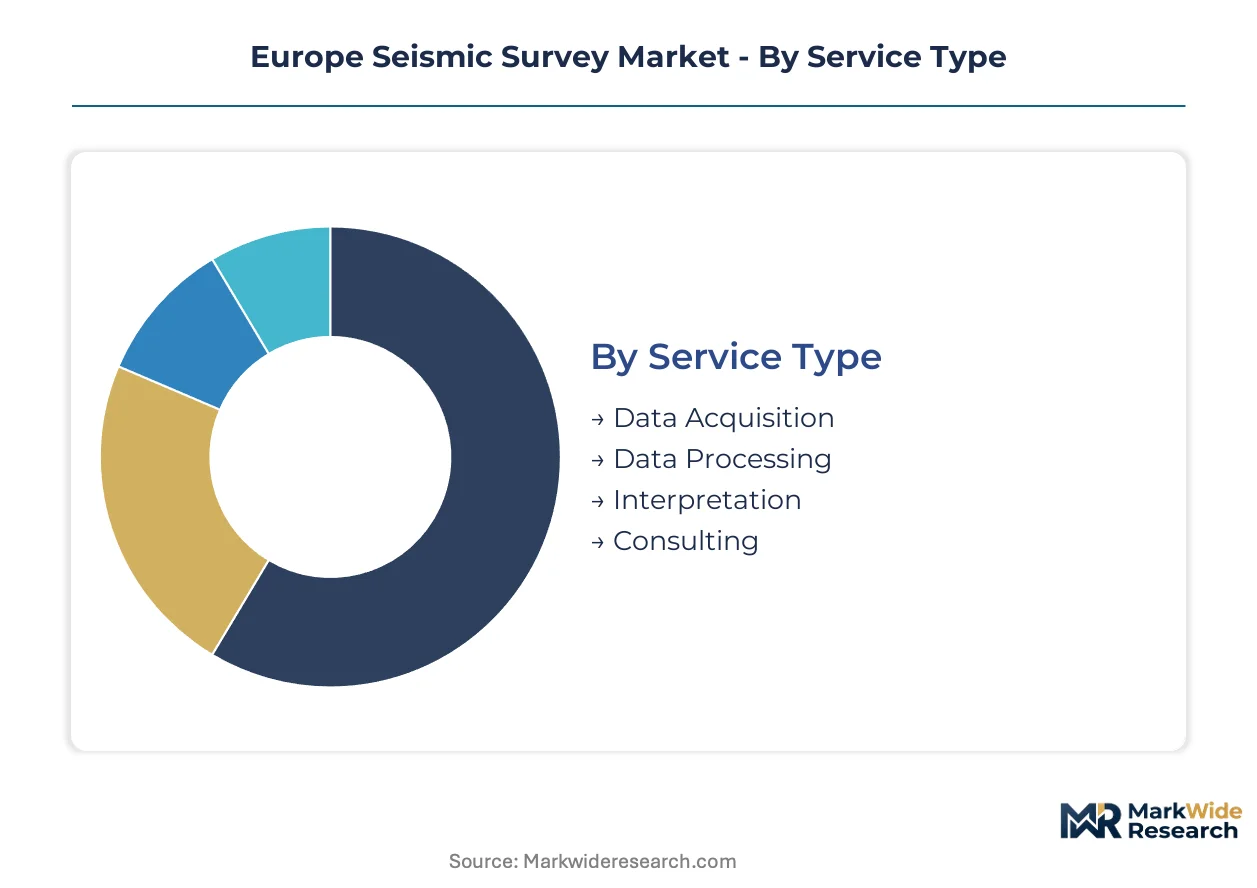
Segmentation in the Europe seismic survey market reveals how vessel capacity, processing algorithms, and regulatory constraints distribute value across distinct service tiers. Procurement patterns differ sharply between hydrocarbon operators seeking 4D reservoir monitoring and offshore wind developers requiring geotechnical site investigation.
Service Type:
Service type segmentation tracks how vessel day rates, computational intensity, and specialist labor allocate revenue across the survey value chain. Cost structures vary from fuel-intensive acquisition through algorithm-heavy processing to premium consulting engagements.
- Data Acquisition:Towed-streamer and ocean-bottom node operations using air-gun arrays and hydrophone spreads deployed from specialized seismic vessels. Norway and the United Kingdom concentrate procurement for North Sea 4D monitoring programs where vessel scarcity compresses availability. The EU Marine Strategy Framework Directive constrains operating windows in sensitive habitats, directly shaping deployment schedules.
- Data Processing:High-performance computing workflows applying velocity model building, depth migration, and noise attenuation to raw seismic volumes. UK and Netherlands operators are expanding procurement for legacy data reprocessing as machine learning algorithms compress interpretation timelines for complex salt formations.
- Interpretation:Geoscientist-led structural and stratigraphic analysis translating processed volumes into drilling recommendations or carbon storage site assessments.
- Consulting:Advisory services spanning survey design optimization, regulatory compliance navigation, and multi-client library valuation.
The dominant share belongs to Data Acquisition, while Data Processing is closing the gap fastest.
Technology:
Technology segmentation maps the evolution from reconnaissance-grade reconnaissance through time-lapse reservoir surveillance, with each tier demanding distinct sensor configurations and vessel specifications.
- 3D Seismic:Multi-azimuth acquisition using overlapping streamer spreads to illuminate subsurface structures with vertical and spatial resolution sufficient for field development planning. Netherlands and UK sectors show concentrated demand for baseline surveys supporting carbon storage site qualification under EU Green Deal methane reduction frameworks.
- 4D Seismic:Repeat 3D surveys acquired at intervals to detect fluid displacement, pressure depletion, and compaction in producing reservoirs. North Sea operators in Norwegian and UK waters are expanding procurement for mature field life extension as baseline 3D libraries enable cost-effective repeat shooting.
- 2D Seismic:Single-profile reconnaissance surveys for frontier basin evaluation and regional structural mapping.
- Reflection Seismology:The foundational physical method underlying all controlled-source seismic techniques, applied across energy transition and traditional hydrocarbon contexts.
3D Seismic retains the largest installed base, though 4D Seismic is expanding most quickly as operators prioritize reservoir optimization over frontier exploration.
End User:
End user segmentation captures diverging procurement patterns between hydrocarbon incumbents with established survey specifications and emerging demand from energy transition sectors with distinct technical requirements.
- Oil & Gas:Integrated and independent operators commissioning surveys for exploration, appraisal, and production optimization across the North Sea and Barents Sea. Norway's Petroleum Safety Authority and the UK's North Sea Transition Authority embed seismic data submission into field development plan approvals, making compliance procurement mandatory.
- Environmental:Offshore wind developers and carbon storage operators requiring seabed characterization and subsurface integrity assessment. Ireland's western coast and the UK North Sea are generating concentrated demand for geotechnical surveys supporting monopile foundation design and saline aquifer CO2 injection qualification.
- Mining:Mineral exploration teams applying seismic methods to deep-target base and precious metal deposits.
- Construction:Infrastructure developers assessing tunneling hazards, aggregate resources, and foundation conditions.
Oil & Gas maintains the dominant procurement volume, while Environmental is gaining share fastest as offshore wind leasing accelerates.
Application:
Application segmentation distinguishes between frontier exploration targeting new hydrocarbon volumes and mature-field activities where seismic data optimizes existing asset performance.
- Reservoir Characterization:Detailed subsurface property estimation including porosity, permeability, and fluid saturation distribution to inform development planning and enhanced recovery design. North Sea operators in UK and Norwegian waters are prioritizing high-resolution acquisition to meet EU Green Deal methane emissions reduction mandates before field development approvals.
- Site Investigation:Geotechnical and geohazard assessment for offshore infrastructure including wind turbine foundations, pipeline routes, and carbon injection wells. The Barents Sea and waters west of Ireland show expanding procurement as frontier leasing rounds and wind farm development displace vessel capacity from traditional hydrocarbon work.
- Hydrocarbon Exploration:Reconnaissance and appraisal surveys targeting undiscovered petroleum resources in frontier and mature basins.
- Subsurface Mapping:Regional structural and stratigraphic framework definition for geological model building across energy and mineral sectors.
Reservoir Characterization holds the leading position, with Site Investigation climbing the fastest as energy transition applications redirect acquisition capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's methane emissions reduction mandates and offshore wind leasing rounds are redistributing seismic survey procurement across the European maritime zone. Norway, the United Kingdom, and the Netherlands concentrate multi-client data acquisition, while frontier basins west of Ireland and in the Barents Sea attract specialized vessel deployment.
Norway
North Sea 4D monitoring programs and Barents Sea frontier licensing drive concentrated demand for ice-class streamer vessels. The Petroleum Safety Authority mandates seismic data submission as part of field development plan approvals, embedding compliance into procurement workflows. Stavanger and Bergen anchor the country's seismic contractor cluster, with acquisition fleets servicing mature field life extension contracts.
United Kingdom
The North Sea Transition Authority's regulatory framework compresses survey timelines for reservoir characterization ahead of development approvals. Multi-client seismic libraries covering extensive UK continental shelf acreage displace proprietary acquisition for exploration teams. Aberdeen maintains its position as the primary service hub, though vessel scheduling increasingly accommodates offshore wind foundation assessments west of Scotland.
Netherlands
Carbon storage site qualification in depleted gas fields and saline aquifers generates procurement outside traditional hydrocarbon budgets. REACH compliance for hydraulic fluids aboard survey vessels extends material certification timelines for Dutch-flagged operations. Rotterdam and Den Helder concentrate processing and interpretation capacity serving North Sea carbon capture and storage projects.
Ireland
Offshore wind leasing rounds along the western coast are redirecting specialized acquisition capacity from hydrocarbon surveys to seabed characterization contracts. The EU Marine Strategy Framework Directive constrains survey windows in sensitive marine habitats, shaping vessel deployment schedules. Cork and Galway harbor emerging clusters of geotechnical survey contractors targeting monopile foundation design work.
Europe Seismic Survey Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure consolidating around integrated vessel-and-sensor fleets and proprietary algorithm developers. The vendor base stratifies into three tiers: full-service acquisition houses with owned marine assets, technology licensors selling processing workflows, and niche consultancies advising on survey design optimization. Dominant competitive moves include fleet modernization cycles responding to fuel cost volatility and strategic partnerships linking hardware providers with offshore wind developers.
Within the integrated acquisition tier, Fugro NV, CGG SA, and Shearwater GeoServices Holding AS exemplify contrasting geographic and technological positioning. Fugro's Netherlands-based corporate structure anchors its North Sea market presence. CGG SA's French origins situate it within the EU regulatory orbit for REACH compliance and EMA noise mitigation guidelines. Shearwater GeoServices Holding AS represents Norwegian maritime specialization, with its corporate designation indicating Nordic capital market access. These three entities collectively illustrate how European seismic contracting concentrates vessel ownership, algorithm development, and frontier basin expertise across distinct national regulatory environments.
| Leading Market Players |
|---|
| Fugro NV |
| ION Geophysical Corporation |
| Halliburton Company |
| PGS |
| SAExploration Holdings Inc |
| Schlumberger Ltd |
| CGG SA |
| TGS |
| Shearwater GeoServices Holding AS |
| Others |
Supply & Pricing Matrix
North Sea marine gasoil corridors linking Rotterdam to Aberdeen and Stavanger transmit fuel cost volatility directly into vessel day-rate structures, concentrating pricing power among Norwegian and UK-flagged operators with captive bunkering arrangements while forcing price differentiation between ice-class and standard acquisition fleets.
Pricing Analysis
Certification level under REACH and EMA noise-mitigation protocols creates the primary spread between premium and standard service tiers. Project-based contracting dominates, with 4D reservoir monitoring commanding substantial premiums over baseline 3D acquisition due to repeat-survey precision requirements. Price differentiation rests on vessel ice-class rating and proprietary algorithm ownership. Margins are tightening in the multi-client library segment as pre-existing 3D volumes displace new shoots. Independent exploration teams show highest price sensitivity, while national oil companies under regulatory mandate exhibit lowest.
Supply Chain Analysis
Export-control restrictions on high-performance streamer sensors and air-gun source arrays limit technology flows into non-EU vessel operators. Manufacturing concentrates in Norway, the United Kingdom, and the Netherlands. Critical inputs include specialized hydrophone cables, compressed air systems, and marine-grade hydraulic fluids. Single-source vulnerability runs through German-engineered streamer winch systems. Distribution runs through integrated acquisition houses with owned vessel fleets rather than third-party charter networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Seismic survey contractors face substitution pressure from satellite-based gravimetry and electromagnetic seabed mapping technologies that promise lower environmental compliance costs for carbon storage site qualification.
For Market Incumbents: Harden market position by securing exclusive vessel dry-dock capacity at Rotterdam and Bergen yards ahead of REACH compliance-driven maintenance surges. Anchor proprietary processing algorithms through patent filings on machine-learning-enhanced salt-formation imaging. Vertical integration into ocean-bottom node manufacturing reduces exposure to German sensor-supplier concentration.
For New Entrants and Emerging Players: Ireland's western offshore wind corridor offers underpenetrated demand for geotechnical site investigation displacing hydrocarbon work. Target carbon storage operators in the Netherlands requiring saline aquifer characterization outside established oil and gas procurement channels. Lead with regulatory compliance advisory bundled into survey design to bypass vessel-ownership barriers.
For Investors and Strategic Acquirers: Carve-out targets emerge from integrated energy majors spinning non-core seismic data libraries. Long-term viability hinges on contractor ability to redirect acquisition capacity from declining North Sea exploration toward offshore wind and carbon storage procurement. Monitor EU offshore wind leasing round announcements as inflection signals for vessel scheduling arbitrage opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Ice-Class Modernization | EMA noise-mitigation compliance and Barents Sea frontier access depend on upgraded hull specifications. |
| Multi-Client Library Expansion | Pre-existing 3D volumes in UK and Netherlands sectors reduce upfront capital for exploration teams. |
| Machine Learning Integration | CGG SA and competitors compress interpretation timelines for complex salt formations through algorithm development. |
| Offshore Wind Pivot | Geotechnical surveys for monopile foundations redirect vessel capacity from hydrocarbon contracts. |
| REACH Compliance Certification | Hydraulic fluid and lubricant material approvals extend dry-dock timelines for Dutch-flagged operations. |
Research Methodology
The analysis maps data acquisition, processing, interpretation, and consulting sub-sectors, each validated through vessel operations managers, geophysicist team leads, offshore wind project developers, and carbon storage site qualification officers. Primary interview findings triangulate against customs records for seismic vessel movements, Norwegian Petroleum Directorate production forecasts, UK North Sea Transition Authority licensing round disclosures, and EU Marine Strategy Framework Directive implementation reports. Bottom-up vessel day-rate modeling and top-down energy transition budget allocation estimates converge on segment sizing.
Assumptions hold marine gasoil price corridors within observed volatility bands and regulatory compliance timelines per current EMA and REACH frameworks. Segmentation dimensions include service type, technology tier, end-user sector, and application purpose across the projection horizon. CAGRs derive from vessel deployment schedules tied to offshore wind leasing rounds and carbon storage site qualification pipelines. Forecast inputs incorporate North Sea field depletion curves and EU Green Deal methane reduction enforcement intensity.
The forecast holds incumbent behavior within observed patterns; aggressive fleet expansion by state-backed contractors or accelerated electromagnetic substitution would shift outcomes. Cross-checking against Norwegian Petroleum Safety Authority field development plan approval volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Perforating Gun Market
Oil & Gas
Middle East and Africa Digital Oilfield Market
Oil & Gas
Coiled Tubing System Market
Oil & Gas
Europe Well Intervention Market
Oil & Gas
Africa Drilling and Completion Fluids Market
Oil & Gas
Workover Rigs Market
Oil & Gas
Romania Oil and Gas Downstream Market
Oil & Gas
Oil and Gas Industry Turbomachinery Market
Oil & Gas
Oil and Gas Fabrication Market
Oil & Gas
Italy Oil and Gas Downstream Market
Oil & Gas
India Oil and Gas Midstream Market
Oil & Gas
Geothermal Drill Bits Market
Oil & Gas
Oil and Gas Pipe Market
Oil & Gas
Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Drones for Oil & Gas Market
Oil & Gas
Global Oil Line Corrosion Inhibitors Market