
 Well Completion Market | 2026-2036
Well Completion Market Size, Share, and Industry Trends Forecast 2026-2036
Well Completion Market Analysis
North American pressure pumping capacity is consolidating after years of oversupply destruction. Schlumberger leverages integrated well construction platforms to bundle completion hardware with digital diagnostics. Halliburton sustains dominance in hydraulic fracturing through manufacturing scale at its in-house proppant and chemical supply chain. Baker Hughes anchors its position in intelligent completion systems with permanent downhole monitoring and remotely actuated flow control.
Well completion encompasses the final phase of well construction where casing, cement, perforations, and production tubulars are installed to establish hydrocarbon flow from reservoir to surface, typically requiring zonal isolation ratings exceeding 10,000 psi and temperature tolerance above 150°C in deep formations. Hydraulic fracturing commands the largest value pool among completion technologies due to stage count inflation in unconventional wells, while coiled tubing intervention grows fastest as operators prioritize re-fracturing and wellbore cleanouts over new drilling. Onshore applications absorb the majority of completion spending, though deepwater margins remain superior given subsea tree integration and high-specification metallurgy requirements.
EPA methane emissions rules and OSHA blowout prevention standards tighten equipment certification and operational training mandates across US well sites. API Specification Q2 and ISO 9001 quality management frameworks govern supplier qualification for critical completion components. Stakeholders must monitor regulatory divergence between state-level permitting timelines and federal environmental compliance to calibrate capital deployment across basins.
Market Dynamics
Horizontal multistage completion intensity in unconventional shale basins is compressing cycle times and multiplying equipment wear rates, forcing service providers to reconfigure asset deployment models around pad drilling economics.
Growth Catalysts
- EPA Methane Regulations:The EPA's updated methane emissions standards mandate continuous monitoring equipment on all new well completions, creating mandatory demand for pneumatic controller retrofits and fugitive detection systems.
- Permian Basin Pad Development:Superpad configurations with 24+ wells per pad multiply fracturing stage counts per location, concentrating service demand and justifying dedicated equipment pools.
- Coiled Tubing Re-fracturing:Mature shale producers increasingly favor recompletion over new drilling, redirecting capital toward intervention services that access bypassed pay zones.
Market Restraints
- Proppant Supply Concentration:Northern White Sand deposits in Wisconsin and Minnesota face rail logistics constraints, while regional brown sand alternatives require higher downhole volumes to achieve equivalent conductivity.
- Pressure Pumping Fleet Oversupply:Excess hydraulic horsepower capacity accumulated during the 2014-2018 buildout continues to suppress dayrate pricing recovery across North American land markets.
- API Q2 Certification Barriers:Smaller equipment fabricators struggle to implement the quality management documentation required for supplier qualification to major integrated operators.
Strategic Opportunities
- Argentina Vaca Muerta:The Neuquén Basin's shale development remains completion-service constrained, with foreign operators seeking technology transfer partnerships to replicate North American multistage techniques.
- Electrified Fracturing Fleets:Natural gas-powered turbine and grid-tied electric pumping units offer path to emissions reduction compliance while reducing diesel logistics costs.
- Remote Actuation Integration:Convergence of downhole fiber optics with surface automation platforms enables real-time fracture diversion decisions without wireline intervention.
Industry Challenges
- Specialized Technician Scarcity:High-pressure pumping operations require certified operators with hazardous materials training; workforce attrition during sector downturns depleted experience pipelines.
- Legacy SCADA Integration:Digital completion systems must interface with decades-old wellhead control architectures, creating cybersecurity vulnerabilities and data protocol mismatches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Well Completion Market |
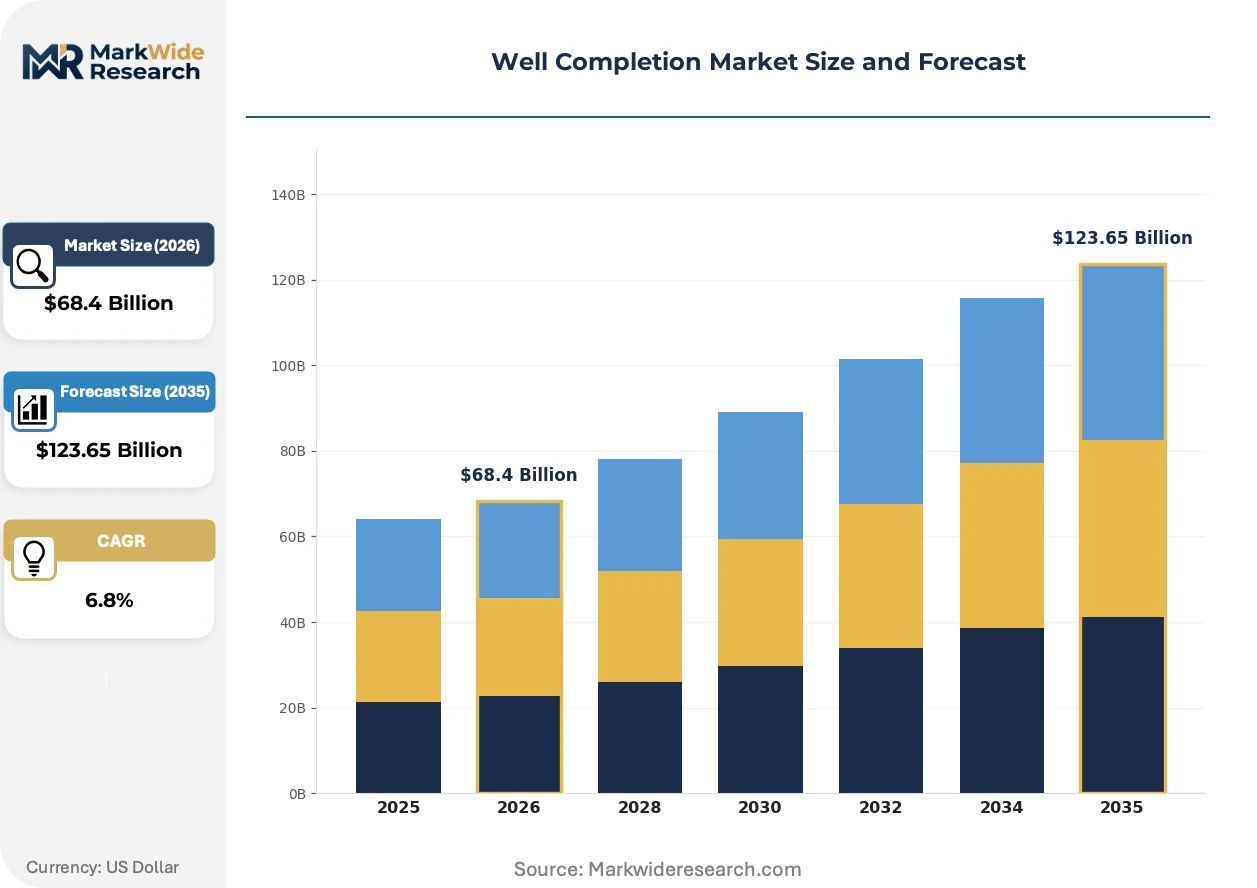
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Hydraulic Fracturing, Cementing, Coiled Tubing, Plug and Abandonment Service Type: Completion Services, Stimulation Services, Workover Services, Intervention Services Application: Onshore, Offshore, Deep Water, Shale Gas End User: Oil Producers, Gas Producers, Independent Operators, Service Companies |
| Companies Covered | Schlumberger, Halliburton, Baker Hughes, Weatherford International, NOV, National Oilwell Varco, Welltec, Superior Energy Services, Packers Plus Energy Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Well Completion Market Emerging Trajectories
Completion hardware is converging with subsurface sensing and surface automation, collapsing the traditional separation between mechanical installation and intelligent production management into unified well construction platforms.
Plug-and-perf systems are automating stage isolation and perforation deployment through wireline-conveyed dissolvable tools that eliminate millout operations. Permian Basin operators with 50+ stage laterals are adopting these systems to compress completion schedules from fourteen days to nine days per well. The technology is automating labor-intensive intervention steps while reducing mechanical risk in extended-reach horizontals.
OSHA blowout prevention standards are tightening surface equipment inspection intervals and mandating real-time pressure monitoring redundancy on all fracturing spreads. Service companies must now deploy dual-independent BOP control systems and certified third-party verification of ram integrity. Land operations in Texas and New Mexico face the steepest compliance cost escalation as state regulators align with federal enforcement protocols.
Integrated service contracts are displacing discrete equipment rentals as E&P procurement teams consolidate vendor relationships. Majors now bundle fracturing, coiled tubing, and wireline under single accountability structures with shared incentive metrics. This consolidation is most advanced among Delaware Basin independents seeking to reduce administrative overhead and improve operational coordination across multi-well pads.
Well Completion Market Segmentation
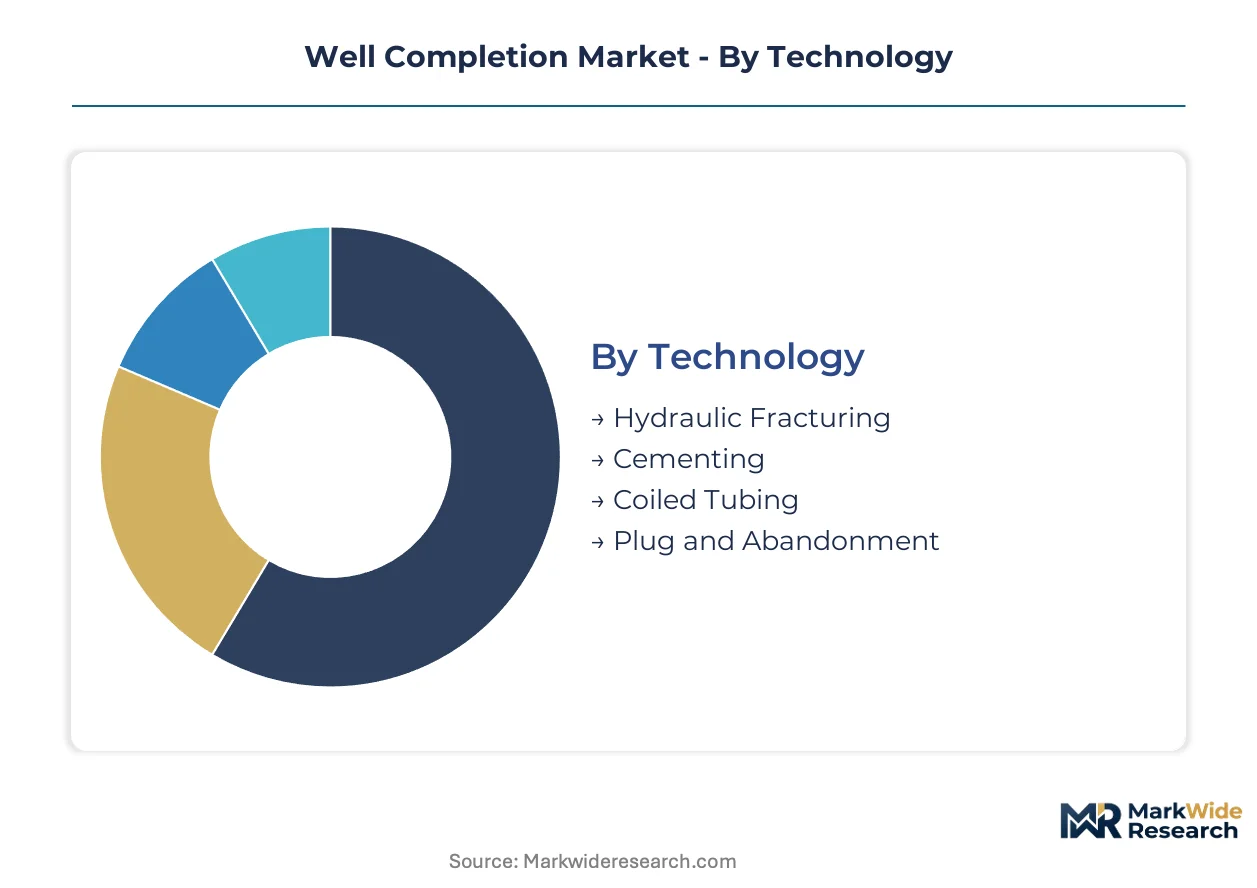
Well completion segmentation reveals how service intensity, regulatory pressure, and reservoir complexity fragment procurement decisions across operator types. Technology choices determine capital allocation between new well construction and intervention economics, while application splits expose divergent margin structures between land and marine environments.
Technology:
Hydraulic fracturing operates as a standalone high-volume service with discrete equipment mobilization, whereas cementing and coiled tubing embed more tightly into integrated well construction sequences.
- Hydraulic Fracturing:High-pressure fluid injection creates conductive fracture networks in tight formations, requiring 15,000+ psi pumping capacity and proppant logistics at scale. Demand concentrates in US Permian Basin superpads where stage counts per lateral now exceed 60, driven by EPA methane monitoring mandates that favor fewer, larger completions over scattered single-well programs.
- Cementing:Zonal isolation through casing cementation demands API Specification 10A compliance for temperature stability above 200°C in deep wells. Gulf of Mexico deepwater projects absorb premium slurry formulations with gas-tight mechanical properties, constrained by BSEE well integrity regulations that mandate cement bond verification before production startup.
- Coiled Tubing:Continuous pipe deployment enables live-well intervention without killing the wellbore, supporting re-fracturing campaigns in mature shale assets.
- Plug and Abandonment:Regulatory-mandated well decommissioning requires mechanical or cement barriers across all productive intervals to prevent aquifer contamination.
Volume placements concentrate in Hydraulic Fracturing; the faster expansion belongs to Coiled Tubing.
Service Type:
Cost tier differentiation separates commoditized pumping labor from proprietary chemistry and diagnostics that command performance-based pricing.
- Completion Services:Integrated casing, cementing, and perforation installation delivered through single-source contracts. North American independents in the Delaware Basin now bundle these services to compress cycle times between spud and first production, pressured by lease expiration clauses and pad drilling coordination requirements.
- Stimulation Services:Fracture design, fluid chemistry, and proppant selection constitute the highest-value service layer in unconventional development. Argentina Vaca Muerta operators seek technology transfer partnerships to replicate North American multistage techniques, constrained by local supply chain gaps in high-pressure pumping equipment.
- Workover Services:Remedial operations restore production from damaged or depleted wells through recompletion or artificial lift installation.
- Intervention Services:Live-well diagnostics and remediation using coiled tubing or wireline conveyance.
Revenue gravity sits with Stimulation Services; the steepest expansion trajectory appears in Intervention Services as operators prioritize recompletion over new drilling.
Application:
Margin structure inverts between high-volume onshore operations and specification-intensive offshore environments where metallurgy and subsea integration dominate procurement.
- Onshore:Land-based drilling and completion across conventional and unconventional reservoirs accounts for the majority of service demand. US operators in Texas and New Mexico deploy electric fracturing fleets to comply with state air quality regulations while reducing diesel logistics costs at multi-well pads.
- Offshore:Platform-based development in shallower waters requires completion hardware rated for salt spray corrosion and marine logistics constraints. North Sea projects face EU methane regulations and CSRD sustainability reporting that extend to supply chain emissions from service providers.
- Deep Water:Subsea completions with subsea trees and tieback systems demand high-specification metallurgy for pressure ratings exceeding 15,000 psi.
- Shale Gas:Unconventional gas-focused development applies multistage fracturing techniques to low-permeability reservoirs.
Activity volume concentrates in Onshore; premium margins concentrate in Deep Water.
End User:
Customer type determines contracting structure, with integrated majors favoring long-term integrated service agreements and independents trading price against operational flexibility.
- Oil Producers:Integrated and independent operators focused on crude extraction drive demand for high-intensity fracturing in tight oil basins. US majors now mandate API Q2 certification across all completion suppliers, disqualifying smaller fabricators lacking documented quality management systems.
- Gas Producers:Dry gas and liquids-rich gas operators prioritize cost efficiency in lower-margin commodity environments. Appalachian Basin producers face FERC pipeline capacity constraints that limit completion activity to periods of favorable basis differentials.
- Independent Operators:Privately held and publicly traded E&Ps without downstream integration dominate US shale development.
- Service Companies:Equipment rental firms and specialized contractors that subcontract to larger integrated service providers.
Procurement volume concentrates among Oil Producers; the fastest share gains belong to Independent Operators consolidating vendor relationships into single-accountability structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Permian Basin proppant logistics and Appalachian pipeline constraints anchor completion demand geography. EPA methane rules and state-level air quality mandates reshape equipment specifications across producing regions. Service intensity concentrates where pad drilling multiplies stage counts per surface location.
United States
Permian Basin superpads drive fracturing demand with 60+ stage laterals per well. EPA methane regulations mandate continuous monitoring equipment on all new completions. Midland-Odessa service yards concentrate electric fleet deployments for emissions compliance.
Canada
Montney and Duvernay shale development sustains coiled tubing intervention demand for re-fracturing campaigns. Alberta Energy Regulator well integrity standards exceed federal baseline requirements. Calgary service company headquarters coordinate cross-border equipment pooling with US Rocky Mountain operations.
Argentina
Vaca Muerta shale development remains completion-service constrained with foreign operators seeking technology transfer. Neuquén Province production sharing contracts require local supplier participation thresholds. YPF-Loma Campana cluster anchors pilot multistage fracturing programs replicating Permian techniques.
Saudi Arabia
Onshore tight gas development drives demand for high-pressure pumping capacity in unconventional reservoirs. Saudi Aramco well integrity specifications align with API Q2 certification mandates. Dhahran-Riyadh corridor concentrates service provider joint venture negotiations for technology localization.
China
Fuling and Weirong shale gas fields expand multistage completion adoption in Sichuan Basin. MEE emissions standards tighten equipment specifications for turbine-powered fracturing fleets. Chongqing equipment manufacturing clusters develop indigenous high-pressure pump manufacturing capacity.
Well Completion Market Vendor Landscape
Global majors compete with regional champions across technology licensing and service bundling dimensions. The vendor base organizes into three tiers: integrated oilfield service conglomerates with full completion portfolios, specialized equipment fabricators focused on discrete components, and regional service contractors with basin-specific logistics advantages. Competitive moves concentrate on integrated contract structures that bundle multiple service lines and electrified fleet deployments that preempt regulatory compliance costs.
Within the integrated service tier, Schlumberger, Halliburton, and Baker Hughes exemplify archetypes of technology bundling, manufacturing scale, and intelligent systems specialization respectively. These Houston-headquartered entities occupy positions that span the full completion value chain from casing installation through production optimization. Their competitive positioning reflects decades of accumulated pressure pumping capacity, proprietary chemistry formulations, and digital platform integration rather than discrete equipment rental economics.
| Leading Market Players |
|---|
| Schlumberger |
| Halliburton |
| Baker Hughes |
| Weatherford International |
| NOV |
| National Oilwell Varco |
| Welltec |
| Superior Energy Services |
| Packers Plus Energy Services |
| Others |
Supply Flow & Price Mechanics
Captive proppant production and in-house chemical formulation anchor Halliburton's supply position while insulating its pricing power from Northern White Sand rail logistics volatility. This backward integration into critical inputs enables service providers to bundle pumping capacity with guaranteed material availability, compressing procurement cycles for Permian Basin operators facing lease expiration pressures.
Pricing Analysis
Equipment warranty and field service bundling separate integrated contract premiums from discrete rental dayrates. Three-tier pricing structure across premium, standard, and economy levels reflects API Q2 certification status and pumping fleet electrification. Cost compression in standard-tier hydraulic fracturing is intensifying because excess 2014-2018 vintage horsepower capacity continues to suppress recovery. Independent operators in the Delaware Basin exhibit highest price sensitivity, while deepwater majors prioritize specification compliance over unit economics.
Supply Chain Analysis
Direct-to-pad logistics channels handle superpad demand clusters, while third-party proppant distributors serve scattered single-well programs. High-pressure pump manufacturing concentrates in the United States, China, and Germany. Ceramic proppant supply draws from bauxite processing in Arkansas and kaolin deposits in Georgia. Single-source vulnerability pervades specialized alloy forging for subsea completion hardware. Distribution runs through Houston-headquartered service company networks with basin-specific yard infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into proppant mining and chemical synthesis is accelerating as service providers seek to defend margin structures against commodity volatility and logistics disruption. Control over these upstream inputs determines competitive position in integrated contract negotiations.
For Market Incumbents: Acquire Northern White Sand mining assets and regional brown sand processing capacity to secure proppant supply autonomy. Invest in API Q2 certification infrastructure for supplier network qualification. Electrified fleet deployment and methane monitoring equipment manufacturing represent defensive capacity against EPA compliance cost escalation and diesel logistics inflation. For New Entrants and Emerging Players: Launch via technology licensing partnerships in Argentina Vaca Muerta, where completion-service constraints and local supplier participation thresholds create protected market access. Target recompletion intervention services in mature US shale assets where capital discipline favors workover economics over new drilling. Emphasize coiled tubing re-fracturing expertise as the go-to-market wedge against integrated service bundling. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated service conglomerates seeking intelligent completion technology and permanent downhole monitoring capabilities. Long-term viability favors specialists with fiber-optic sensing integration and remote actuation platforms. Watch for inflection in Argentina production sharing contract renegotiations as the signal for Neuquén Basin service demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Electrified Fleet Deployment | Natural gas turbine and grid-tied electric pumping units reduce EPA methane compliance costs and diesel logistics burden. |
| Proppant Supply Integration | Captive mining and processing capacity insulates service margins from Northern White Sand rail bottleneck volatility. |
| Intelligent Completion Technology | Permanent downhole monitoring and remote flow control differentiate Baker Hughes positioning in premium offshore contracts. |
| Argentina Technology Transfer | Foreign operator partnerships in Vaca Muerta replicate Permian multistage techniques while meeting local content requirements. |
| Re-fracturing Service Specialization | Coiled tubing intervention captures capital reallocation from new drilling to recompletion in mature shale assets. |
Methodological Framework
Document review covered SEC 10-K filings, EPA enforcement records, and API specification documentation, complemented by interviews with pressure pumping operations directors, E&P procurement managers, and coiled tubing service supervisors. Secondary validation drew from BSEE well integrity reports, railroad commission production data, and state environmental agency permitting databases. Bottom-up equipment fleet counts and top-down operator capital expenditure triangulation anchored market sizing.
Segment-level value outputs reflect analytical framework integration across technology, service type, application, and end-user dimensions over the projection horizon. CAGRs were derived from equipment intensity per well, stage count trajectories, and basin-level activity forecasts. Proppant volume per stage, lateral length extension rates, and electric fleet penetration curves constituted primary forecast inputs.
Regulatory enforcement intensity, commodity price volatility, and workforce availability are the dominant revision risks that could alter trajectory assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Small Scale LNG (SSLNG) Market
Oil & Gas
Oil and Gas Automation Market
Oil & Gas
Asia-Pacific Oil and Gas Storage Tank Market
Oil & Gas
Europe Oil and Gas Electric Submersible Pump Market
Oil & Gas
Casing and Cementation Hardware Market
Oil & Gas
Ecuador Oil and Gas Midstream Market
Oil & Gas
Wired Drill Pipe Sales Market
Oil & Gas
India Artificial Lift Systems Market
Oil & Gas
Oil and Gas Hose Assemblies Market
Oil & Gas
Natural Gas Market
Oil & Gas
Pipeline Integrity Market
Oil & Gas
Asia-Pacific Oil Country Tubular Goods Market
Oil & Gas
Malaysia Oilfield Services Market
Oil & Gas
South America LNG Bunkering Market
Oil & Gas
Gold Mining Market
Oil & Gas
Australia LNG Bunkering Market