
 Kuwait Oil and Gas Market | 2026-2036
Kuwait Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Kuwait Oil and Gas Market Foresight
Aftermarket reservoir management services is reconfiguring margin pools across Kuwait's upstream sector. Kuwait Petroleum Corporation leverages integrated field development to sustain long-term production targets. Schlumberger NV anchors technical service capacity through specialized well intervention and digital subsurface solutions. Kuwait Oil Company dominates onshore heavy crude operations across the Burgan and Minagish fields.
Kuwait oil and gas encompasses the exploration, extraction, processing, and distribution of hydrocarbon resources including crude oil with API gravities ranging from heavy to light sweet grades, natural gas with associated and non-associated sources, and refined petroleum products manufactured through atmospheric distillation, catalytic cracking, and hydrocracking units. The sector serves power generation, industrial manufacturing, maritime bunkering, and petrochemical synthesis. Upstream exploration and production activities occupy the largest value share given Kuwait's position among top-tier crude exporters, while enhanced oil recovery technology represents the fastest-expanding technology segment as mature fields require pressure maintenance and thermal stimulation. Petrochemicals within the product dimension command premium margins through downstream integration at the Al-Zour complex.
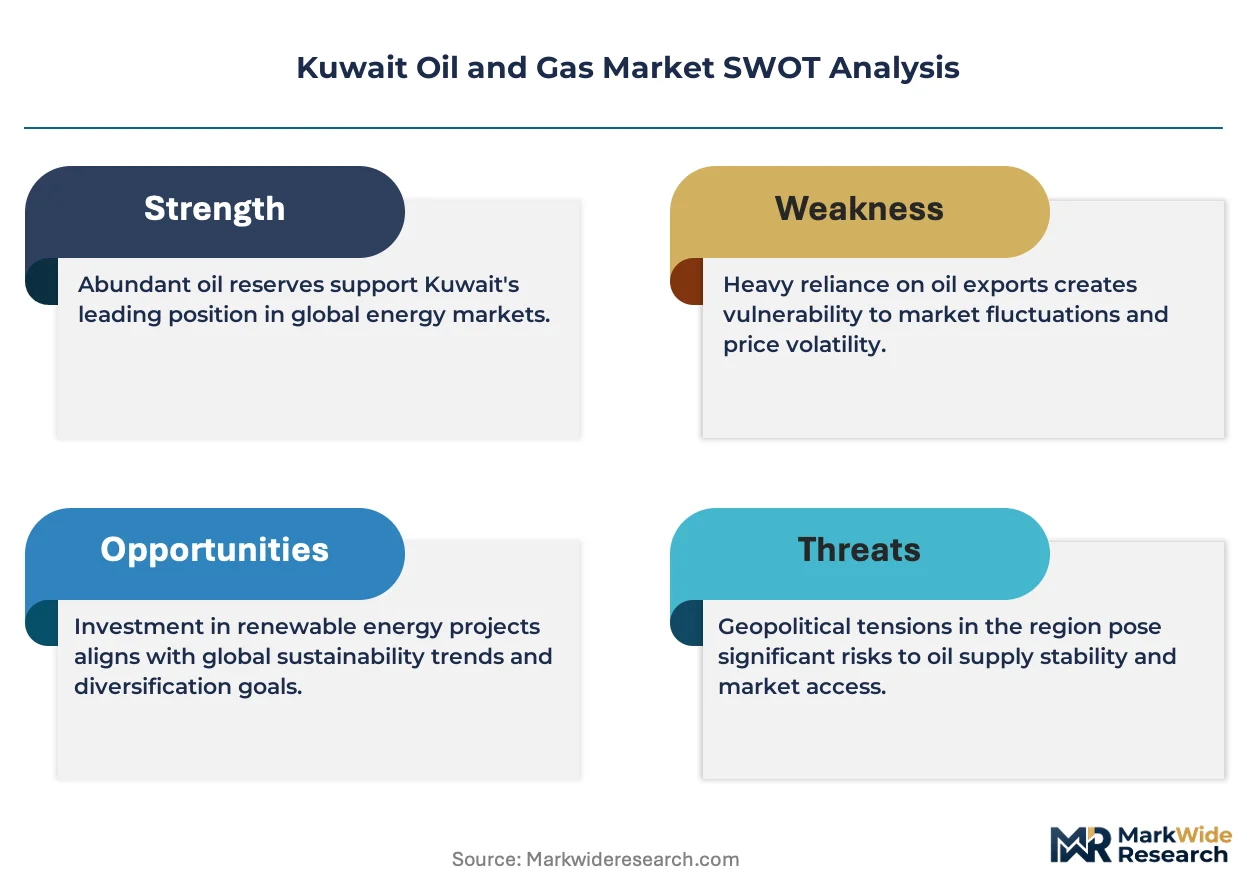
Kuwait's Ministry of Oil and the Partnerships Technical Bureau govern concession terms and international joint venture structures, while the Environment Public Authority enforces air emissions standards and flare gas reduction mandates that shape field development economics. The country's central environmental regulator imposes water discharge protocols that affect offshore platform design and coastal refinery operations. Stakeholders must monitor how domestic content requirements and international partnership frameworks evolve to determine capital allocation between conventional production expansion and advanced recovery investments.
Market Dynamics
Enhanced oil recovery technology deployment is concentrating capital allocation across Kuwait's mature onshore fields, with thermal stimulation and pressure maintenance systems reconfiguring production economics at Burgan and Minagish.
Growth Catalysts
- Petrochemical Feedstock Expansion:Industrial demand from downstream synthesis operations at Al-Zour is pulling additional natural gas liquids and naphtha volumes through integrated refinery complexes.
- Partnerships Technical Bureau Frameworks:International joint venture structures are unlocking foreign technical capacity for heavy crude redevelopment and offshore exploration access.
- Flare Gas Reduction Mandates:Environment Public Authority enforcement is accelerating gas capture infrastructure investment and associated petroleum gas utilization projects.
Market Restraints
- Capital Intensity of Thermal EOR:Steam flood and chemical injection programs require sustained multi-year investment cycles before production response materializes.
- Water Discharge Protocols:Coastal refinery and offshore platform design must incorporate tertiary treatment systems that elevate engineering costs.
- Carbon Black Substitution Pressure:Specialty-grade carbon black from delayed coker units faces displacement from furnace-grade imports in tire manufacturing applications.
Strategic Opportunities
- Domestic Content Requirements:Local workforce and supplier mandates create captive contracting opportunities for engineering and fabrication services.
- Digital Subsurface Convergence:Integration of reservoir simulation with real-time well intervention data is opening predictive maintenance service lines.
- Ahmadi Governorate Cluster Proximity:Concentrated demand around Mina Al-Ahmadi enables logistics optimization for equipment and chemical supply.
Industry Challenges
- Specialized EOR Engineering Talent:Thermal recovery and chemical flooding expertise remains concentrated among a limited pool of international specialists.
- Legacy SCADA Integration:New digital oilfield platforms must interface with decades-old control systems at mature production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kuwait Oil and Gas Market |
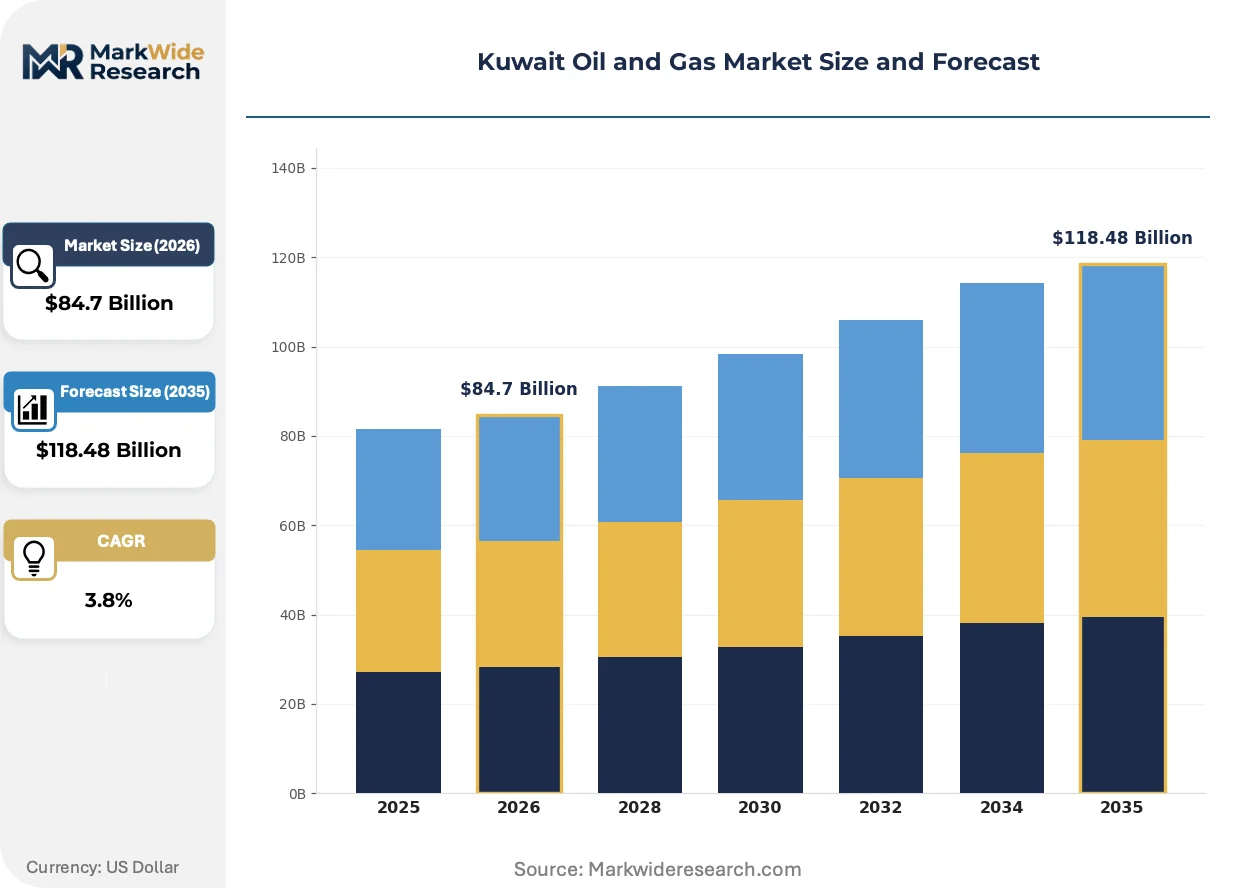
| Market Size in 2026 | $84.7 Billion |
| Market Size in 2035 | $118.48 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Exploration, Production, Refining, Distribution Product: Cruude Oil, Natural Gas, Petrochemicals, LPG Technology: Upstream, Midstream, Downstream, Enhanced Oil Recovery End User: Utilities, Industrial, Transport, Residential |
| Companies Covered | Kuwait Gulf Oil Company, BP plc, Kuwait Petroleum Corporation, Saipem SpA, Schlumberger NV, Kuwait Oil Company, Chevron Corporation, Kuwait Oil Tanker Company, Kuwait Integrated Petroleum Industries Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kuwait Oil and Gas Market Shifts & Advancements
Digital subsurface technologies are compressing decision cycles across Kuwait's upstream operations, with real-time data streams reshaping how reservoir management services are contracted and delivered.
Reservoir simulation software paired with downhole fiber-optic sensing is digitizing how Kuwait Oil Company monitors steam front propagation in heavy oil zones. Field teams at Burgan are deploying these systems to optimize injection patterns without conventional well intervention. The technology is digitizing margin capture for service providers who can bundle hardware installation with analytics subscriptions.
Environment Public Authority flare gas reduction mandates are forcing gas gathering network expansion across southern Kuwait fields. Operators must install compression and treatment capacity that meets emissions thresholds before production license renewal. Heavy crude facilities face the steepest compliance timelines given their elevated associated gas volumes.
Aftermarket reservoir management contracts are unbundling from integrated field development agreements. Kuwait Petroleum Corporation now procures surveillance and optimization services separately from drilling and completion packages. This shift is most visible at Minagish, where specialized vendors compete on production uplift guarantees rather than equipment supply.
Kuwait Oil and Gas Market Segmentation
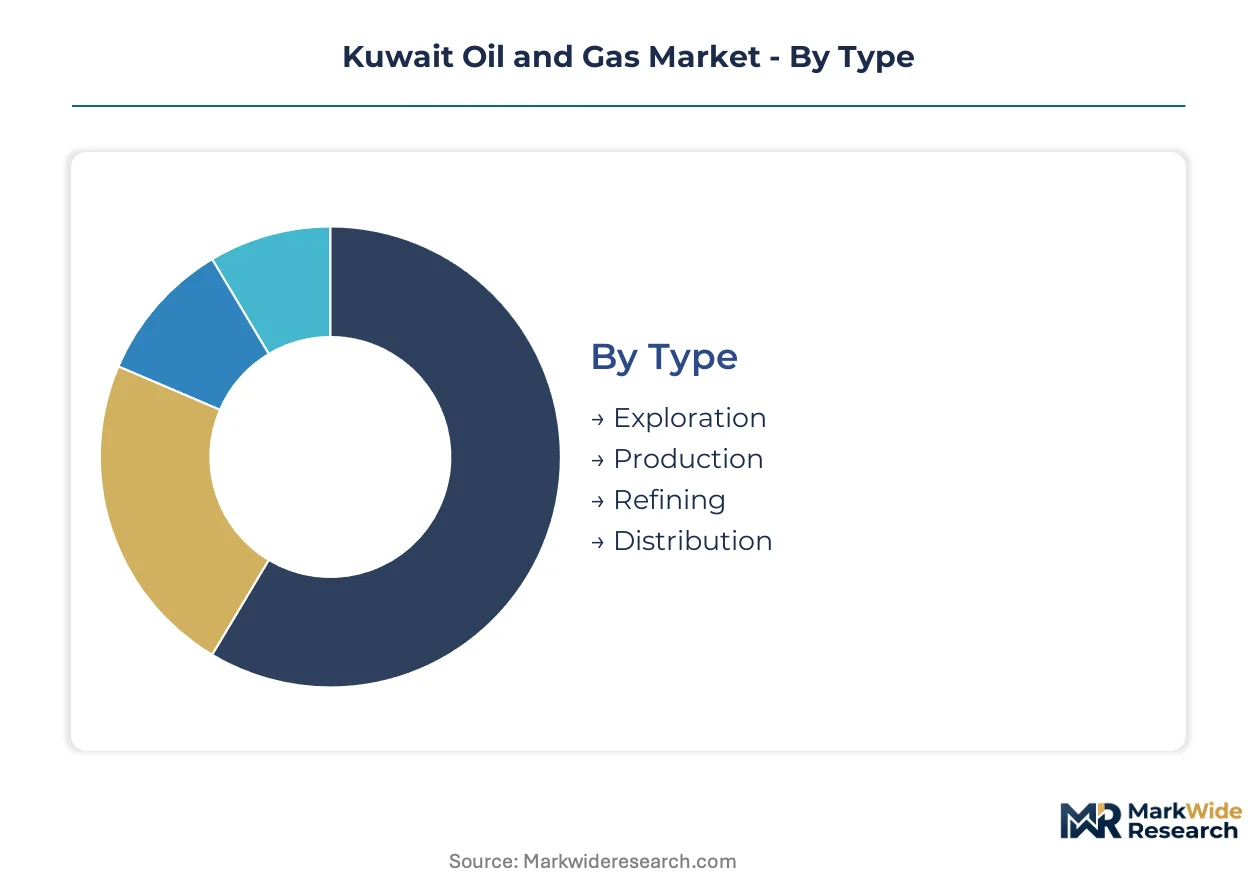
Kuwait's oil and gas market segments reflect distinct capital cycles, regulatory exposure, and technology intensity. Understanding how value pools distribute across these dimensions enables precise targeting of investment and contracting decisions.
Type:
Cost tier differentiation across the value chain determines margin capture and partnership structure for international investors.
- Exploration:Seismic surveying and wildcat drilling targeting deep carbonate reservoirs and offshore structures. Licensing rounds under Partnerships Technical Bureau frameworks concentrate activity in northern and offshore concessions where reservoir complexity demands foreign technical participation.
- Production:Sustained extraction from Burgan, Minagish, and Raudhatain fields through primary, secondary, and tertiary recovery methods. Kuwait Oil Company operates the majority of onshore heavy crude capacity with integrated artificial lift and surface facility management.
- Refining:Atmospheric distillation, catalytic cracking, and hydrocracking at Mina Al-Ahmadi, Mina Abdullah, and Al-Zour complexes. The Al-Zour refinery anchors downstream expansion with residue conversion capacity processing heavy Kuwait Export Crude into low-sulfur products.
- Distribution:Pipeline networks, marine terminals, and product storage connecting production to export markets and domestic demand centers.
Production holds installed capacity. Refining is rotating up the share rankings.
Product:
Application-specific demand patterns shape procurement priorities and infrastructure investment sequencing across Kuwait's hydrocarbon output.
- Crude Oil:Heavy sour grades (API 28-32) from Burgan and lighter offshore varieties. Export orientation dominates with term contracts to Asian refiners, while domestic supply feeds the Al-Zour complex.
- Natural Gas:Associated gas from heavy oil fields and non-associated volumes from Jurassic reservoirs. Power generation and petrochemical feedstock pull concentrate demand in the Ahmadi Governorate industrial cluster.
- Petrochemicals:Olefins, aromatics, and derivative products manufactured at integrated refining-chemical complexes. The Al-Zour petrochemicals project expands ethylene and polyethylene capacity for regional export markets.
- LPG:Propane and butane fractions recovered from gas processing plants. Residential cooking and industrial heating applications drive seasonal demand variation.
Crude Oil holds installed capacity. Petrochemicals is rotating up the share rankings.
Technology:
Volume throughput and asset maturity dictate technology deployment priorities across Kuwait's hydrocarbon infrastructure.
- Upstream:Reservoir characterization, drilling, and completion systems for oil and gas extraction. Digital subsurface convergence through real-time monitoring and predictive analytics is compressing decision cycles at mature fields.
- Midstream:Gathering systems, processing facilities, and export infrastructure. Gas compression and treatment capacity expansion accelerates under Environment Public Authority flare reduction mandates.
- Downstream:Refining, petrochemical synthesis, and product finishing operations. Integration complexity rises with residue upgrading and clean fuels production requirements.
- Enhanced Oil Recovery:Thermal stimulation, chemical flooding, and pressure maintenance for mature field redevelopment. Steam flood deployment at Burgan heavy oil zones represents the steepest expansion trajectory as production response justifies multi-year capital cycles.
Upstream holds installed capacity. Enhanced Oil Recovery is rotating up the share rankings.
End User:
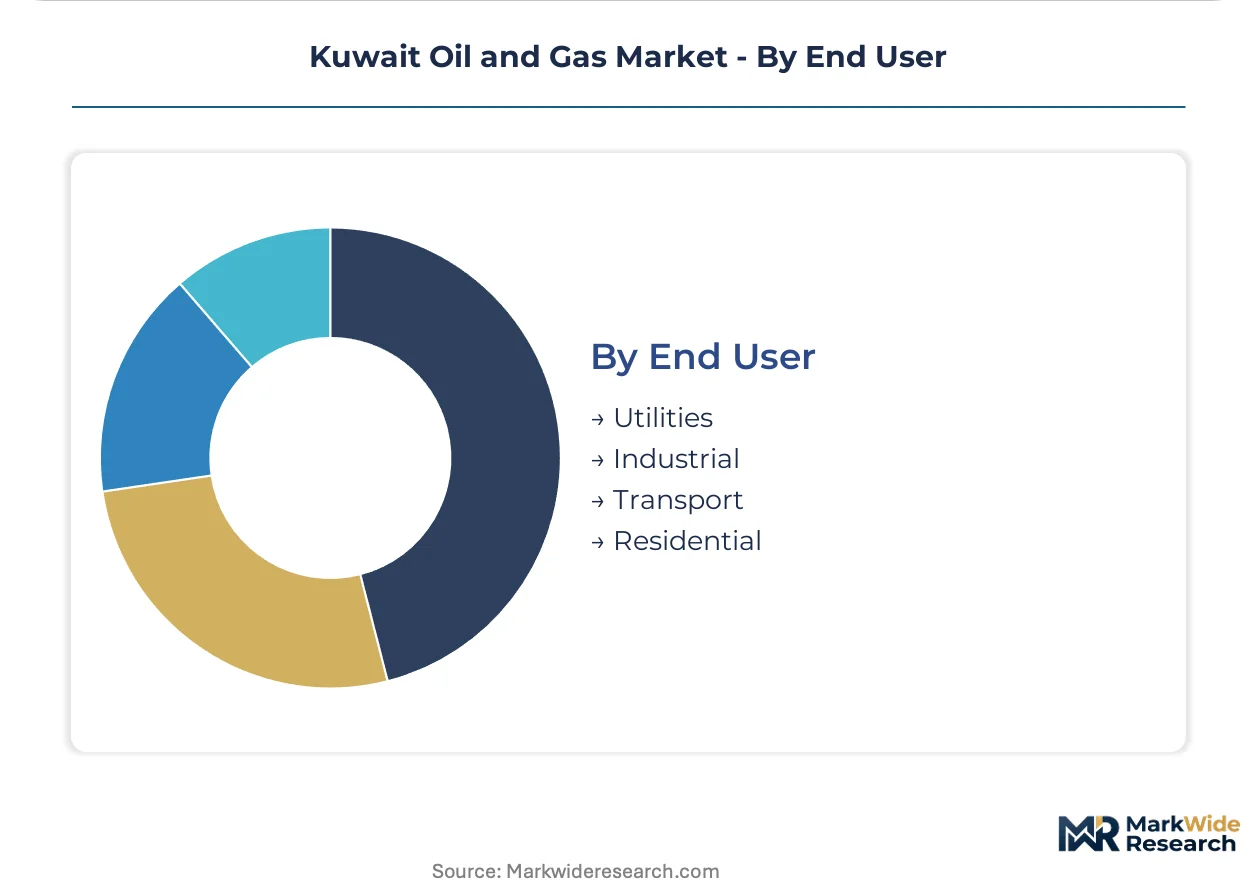
Customer type concentration determines pricing power, contract duration, and service level requirements across demand segments.
- Utilities:Power and water generation facilities consuming natural gas and residual fuel oil. Ministry of Electricity and Water procurement dominates with long-term supply agreements indexed to crude benchmarks.
- Industrial:Petrochemical plants, cement kilns, and manufacturing operations requiring process heat and feedstock. Al-Zour complex integration creates captive demand for refinery intermediates and natural gas liquids.
- Transport:Marine bunkering at Mina Al-Ahmadi and domestic road fuel distribution. Low-sulfur fuel oil and diesel specifications align with International Maritime Organization standards.
- Residential:LPG for cooking and heating in urban and suburban Kuwait. Seasonal consumption peaks drive inventory management requirements at distribution terminals.
Utilities hold installed capacity. Industrial is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kuwait's oil and gas consumption mix diverges from regional peers through its heavy orientation toward petrochemical feedstock and power generation, rather than export-dominated configurations seen elsewhere in the Gulf.
Al Ahmadi Governorate
Industrial demand from the Al-Zour refinery complex and Mina Al-Ahmadi petrochemical facilities concentrates natural gas and naphtha consumption in this coastal zone. The Environment Public Authority enforces flare gas reduction mandates that shape infrastructure investment timelines. The Ahmadi industrial cluster anchors downstream integration with ethylene and polyethylene capacity expansion underway.
Al Jahra Governorate
Heavy crude production from the Burgan field drives associated gas recovery and thermal stimulation operations across this northern producing region. Kuwait Oil Company manages steam flood deployment under enhanced oil recovery licensing frameworks. The Burgan field complex represents the largest concentration of mature heavy oil redevelopment activity.
Al Farwaniyah Governorate
Logistics and equipment supply chains serving southern oil fields cluster around this central transport corridor. Domestic content requirements from the Partnerships Technical Bureau channel local workforce and supplier mandates through contracting vehicles. Distribution terminals and service company headquarters concentrate near Kuwait International Airport connectivity.
Hawalli Governorate
Technical service providers and engineering consultancies supporting offshore exploration locate administrative functions in this commercial district. The Partnerships Technical Bureau structures international joint venture access for deep carbonate and offshore concession work. Corporate offices for field development contractors cluster near financial and diplomatic infrastructure.
Kuwait Oil and Gas Market Competitive Landscape
Capability concentration sits with international technical specialists; scale advantage sits with national integrated operators. The market structures around a dominant national champion controlling upstream production and downstream refining, with tiered service providers competing for specialized contracts. Three archetypes define competitive positioning: integrated national oil companies, international technical service specialists, and engineering-construction contractors. Dominant moves include strategic partnerships for heavy crude redevelopment and capacity expansion in gas processing and petrochemical integration.
Within the national integrated tier, Kuwait Petroleum Corporation and Kuwait Oil Company anchor state-controlled production and refining operations. Schlumberger NV and Saipem SpA represent international technical capacity deployed through specialized well intervention, digital subsurface solutions, and major construction contracting. BP plc and Chevron Corporation occupy positions as foreign partners under Partnerships Technical Bureau frameworks for concession access and technical collaboration.
| Leading Market Players |
|---|
| Kuwait Gulf Oil Company |
| BP plc |
| Kuwait Petroleum Corporation |
| Saipem SpA |
| Schlumberger NV |
| Kuwait Oil Company |
| Chevron Corporation |
| Kuwait Oil Tanker Company |
| Kuwait Integrated Petroleum Industries Company |
| Others |
Supply & Pricing Matrix
Mina Al-Ahmadi's concentrated refining and export terminal capacity anchors Kuwait's hydrocarbon pricing power, with throughput volumes at this coastal cluster directly conditioning term contract negotiations with Asian offtakers. The Ahmadi Governorate's integrated petrochemical complex creates captive demand pull that insulates domestic producers from spot market volatility.
Pricing Analysis
Long-term offtake agreements dominate Kuwait's crude export structure, with term contracts to Asian refiners indexed to regional benchmarks and adjusted for quality differentials. Price differentiation rests on API gravity and sulfur content grades, with heavy sour Burgan crude trading at widening discounts to lighter offshore varieties. Cost compression in thermal EOR operations is intensifying because steam flood programs require sustained capital deployment before production response materializes. National oil companies exhibit lowest price sensitivity given integrated refining capacity, while independent traders show highest responsiveness to quality-adjusted differentials.
Supply Chain Analysis
Export control regimes on advanced subsurface technologies limit specialized well intervention equipment flows into Kuwait's mature field redevelopment programs. Geographic supply concentration draws from the United States, Norway, and the United Arab Emirates for high-pressure pumping units and fiber-optic sensing systems. Raw material dependencies include specialized alloy tubulars, thermal stimulation chemicals, and digital oilfield software licenses. Single-source vulnerability runs through limited qualified vendors for thermal EOR engineering services. Distribution runs through Mina Al-Ahmadi marine terminals for crude exports and Ahmadi Governorate pipeline networks for domestic refinery feedstock.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kuwait's oil and gas sector rewards entities that control scarce thermal recovery engineering talent and digital subsurface integration capabilities, with these skill gaps constraining field redevelopment timelines.
For Market Incumbents: Harden technical service capacity through captive development of steam flood engineering expertise before international specialists consolidate market position. Secure exclusive partnerships with fiber-optic sensing providers to lock in predictive maintenance service lines. Prioritize backward integration into gas compression equipment fabrication to meet Environment Public Authority flare reduction mandates without import dependency. For New Entrants and Emerging Players: Northern Kuwait's underpenetrated deep carbonate formations offer concession access points where foreign technical participation remains essential under Partnerships Technical Bureau frameworks. Target aftermarket reservoir management contracts at Minagish where Kuwait Petroleum Corporation has unbundled surveillance services from integrated field development agreements. Establish digital subsurface analytics capabilities as the primary go-to-market wedge against established well intervention incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-capture play because enhanced oil recovery deployment creates decades-long service relationships with production uplift guarantees. Focus acquisition screening on specialized thermal recovery engineering boutiques and real-time monitoring technology providers. Watch for Partnerships Technical Bureau licensing round announcements as the signal for accelerated foreign joint venture formation.| Strategic Initiative | Industry Significance |
|---|---|
| Enhanced Oil Recovery Capacity Buildout | Steam flood deployment at Burgan heavy oil zones justifies multi-year capital cycles with production-linked returns. |
| Digital Subsurface Technology Licensing | Real-time fiber-optic sensing integration compresses decision cycles for Kuwait Oil Company reservoir management. |
| Gas Capture Infrastructure Partnership | Compression and treatment capacity expansion accelerates under Environment Public Authority flare reduction enforcement. |
| Backward Integration into Specialty Chemicals | Domestic content requirements create captive contracting opportunities for thermal stimulation chemical supply. |
| Petrochemical Integration Joint Venture | Al-Zour complex ethylene capacity expansion pulls additional naphtha volumes through integrated refining operations. |
Research Methodology
The analysis maps upstream production, downstream refining, and enhanced oil recovery technology segments, each validated through reservoir engineers, procurement officers at Kuwait Petroleum Corporation, technical service contractors, and Environment Public Authority regulators. Primary interviews with field development specialists and secondary validation through customs data, Partnerships Technical Bureau concession filings, and national oil company annual disclosures established baseline metrics. Bottom-up field-level production estimates and top-down macroeconomic triangulation anchored value projections.
Assumptions held crude benchmark pricing relationships and regulatory enforcement timelines fixed while varying enhanced oil recovery adoption rates and international joint venture formation pace across the projection horizon. Segmentation modeling incorporated technology type, product grade, and end-use sector dimensions. CAGRs derived from production volume trajectories at Burgan and Minagish fields, petrochemical capacity expansion schedules at Al-Zour, and flare gas reduction infrastructure deployment timelines.
The forecast holds incumbent behavior within observed patterns; aggressive technology licensing moves by international service providers would shift outcomes beyond projected ranges. Material shifts in Partnerships Technical Bureau foreign participation rules or Environment Public Authority emissions enforcement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
AI in Oil and Gas Market
Oil & Gas
East Africa Oil and Gas Market
Oil & Gas
Global LNG Liquefaction Equipment Market
Oil & Gas
Bunker Liners Market
Oil & Gas
Mining and Oil & Gas Fasteners Market
Oil & Gas
Thailand Oil and Gas Market
Oil & Gas
Drilling and Completion Fluids Market
Oil & Gas
Oil and Gas EPC Market
Oil & Gas
Brazil Oil and Gas Midstream Market
Oil & Gas
Qatar Oil and Gas Market
Oil & Gas
Sucker Rod Market
Oil & Gas
Italy Oil and Gas Upstream Market
Oil & Gas
GCC Natural Gas Market
Oil & Gas
Oil and Gas Cloud Applications Market
Oil & Gas
Oil and Gas Pipeline Management Software Market
Oil & Gas
United States Onshore Drilling Fluid Market