
 Latin America Positive Displacement Pumps Market | 2026-2036
Latin America Positive Displacement Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Positive Displacement Pumps Market Foresight
Municipal water utilities are collapsing their historical preference for centrifugal systems in favor of positive displacement technologies for sludge handling and chemical dosing. Flowserve Corporation leverages its aftermarket service density across Mexican refinery corridors to sustain recurring revenue streams. Xylem Inc anchors its position through electric-drive diaphragm pump portfolios tailored to Brazilian sanitation concessions. Alfa Laval AB specializes in hygienic screw pump configurations that dominate food and beverage processing lines across Argentina's Pampas dairy belt.
Positive displacement pumps trap fixed fluid volumes within cavities formed by gears, screws, pistons, or flexible diaphragms, then force discharge through mechanically sealed chambers operating at pressures from 50 to 10,000 psi depending on configuration. These systems handle viscous, shear-sensitive, or entrained-solid fluids that degrade in centrifugal impeller environments, serving primary roles in hydrocarbon transfer, precise chemical metering, and sanitary product circulation. Gear pumps occupy the largest installed base across Latin American lubricant blending and hydraulic power units due to their simplicity and tolerance for high-viscosity mineral oils. Diaphragm pumps represent the fastest-expanding category, driven by chemical-resistant elastomer advances that extend mean time between failures in corrosive wastewater streams. Piston pumps command premium pricing in high-pressure oilfield injection service where Brazil's pre-salt developments demand API 674 compliance.
Brazil's CONAMA and Mexico's NOM frameworks mandate tertiary treatment standards that force utilities toward precision metering pumps with certified leakage containment. ANVISA sanitary regulations in Brazil and COFEPRIS standards in Mexico dictate surface finish and material traceability requirements that filter out uncertified suppliers from pharmaceutical and food-grade pump procurement. Argentina's IRAM standards and Chile's SEC certifications add compliance layering that favors established multinational documentation capabilities over regional fabricators. Stakeholders must monitor how pending Mercosur technical harmonization affects mutual recognition of pressure equipment certifications across the customs union.
Market Dynamics
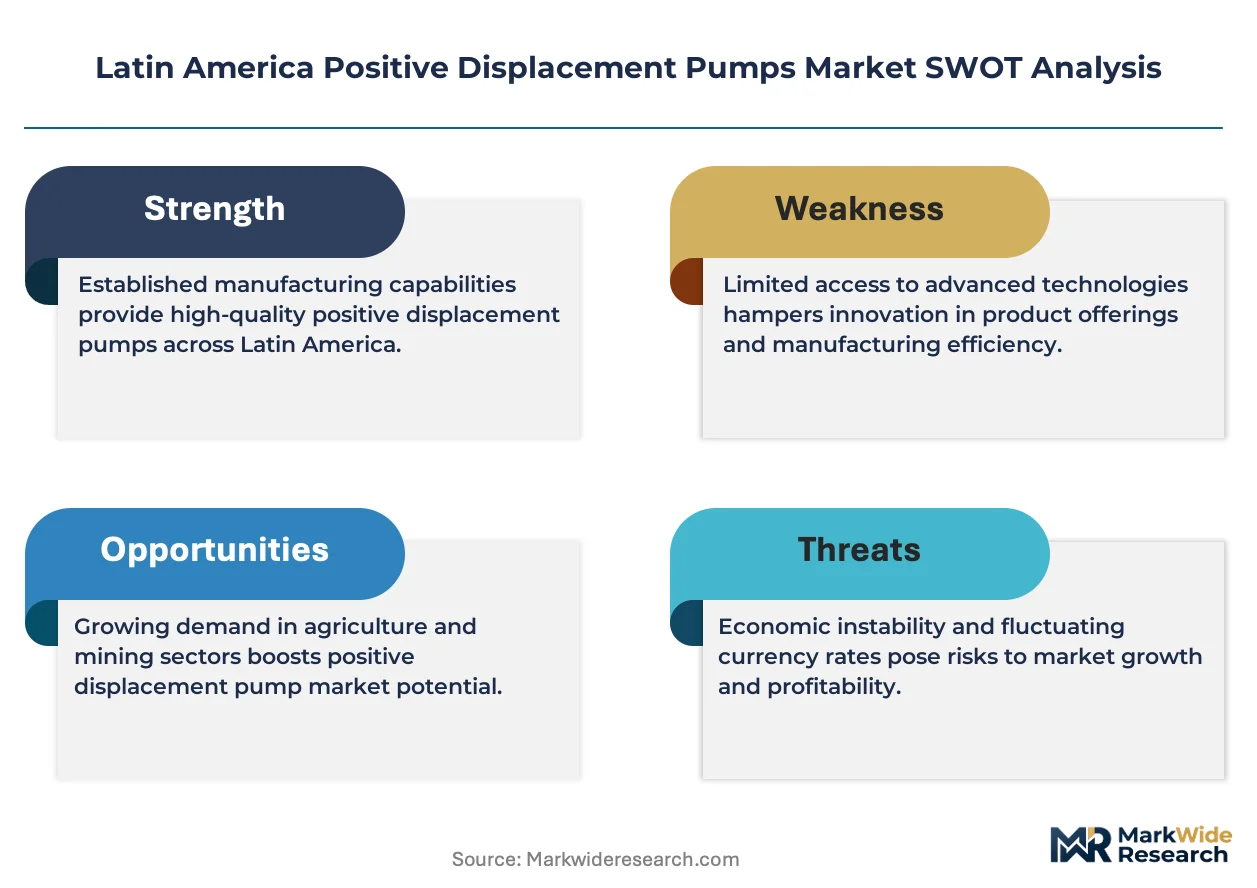
Brazil's CONAMA tertiary treatment mandates and Mexico's NOM effluent standards are collapsing historical centrifugal preferences across municipal procurement offices, forcing specification rewrites toward diaphragm and screw pump architectures.
Growth Catalysts
- CONAMA Resolution 430 compliance deadlines:Brazilian sanitation utilities face hard 2025-2026 deadlines for tertiary treatment upgrades, triggering replacement waves in São Paulo and Rio de Janeiro state water authorities.
- Pre-salt chemical injection intensity:Brazil's offshore carbonate reservoirs demand high-pressure piston pump systems for CO2 and produced water reinjection, sustaining API 674 specification procurement.
- Peristaltic hose advances:New elastomer formulations extending mean time between failures in corrosive wastewater streams are displacing legacy pump types across Mexican industrial parks.
Market Restraints
- Specialized alloy cost volatility:Duplex stainless steel and super-duplex material inputs for corrosive service pumps expose fabricators to nickel and molybdenum price swings without pass-through mechanisms in municipal tenders.
- Import dependency for precision components:High-tolerance screw pump profiles and ceramic-coated plungers concentrate supply in German and Italian machining clusters, creating lead time vulnerability for Andean buyers.
- Centrifugal legacy lock-in:Decades of centrifugal specification in Brazilian irrigation and cooling water systems create engineering resistance to positive displacement alternatives despite superior viscosity handling.
Strategic Opportunities
- Colombian unconventional development:Emerging heavy oil thermal recovery projects in the Llanos Basin present untapped demand for high-temperature progressive cavity pump systems.
- Electric-drive diaphragm convergence:Integration of variable frequency drives with smart pressure feedback loops enables precision chemical dosing that opens pharmaceutical and food-grade niches previously served by pneumatic systems.
- Chilean lithium extraction expansion:Brine pumping and reagent injection stages in Atacama salar operations require corrosion-resistant positive displacement architectures with ANSII/ASME certification.
Industry Challenges
- Cross-border certification friction:Argentina's IRAM pressure equipment standards and Chile's SEC electrical safety certifications create duplicative testing burdens for pumps sourced from Brazilian manufacturing bases.
- Retrofit integration complexity:Positive displacement systems demand fundamentally different piping configurations, pulsation dampening, and control logic than the centrifugal infrastructure dominating existing Latin American industrial plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Positive Displacement Pumps Market |
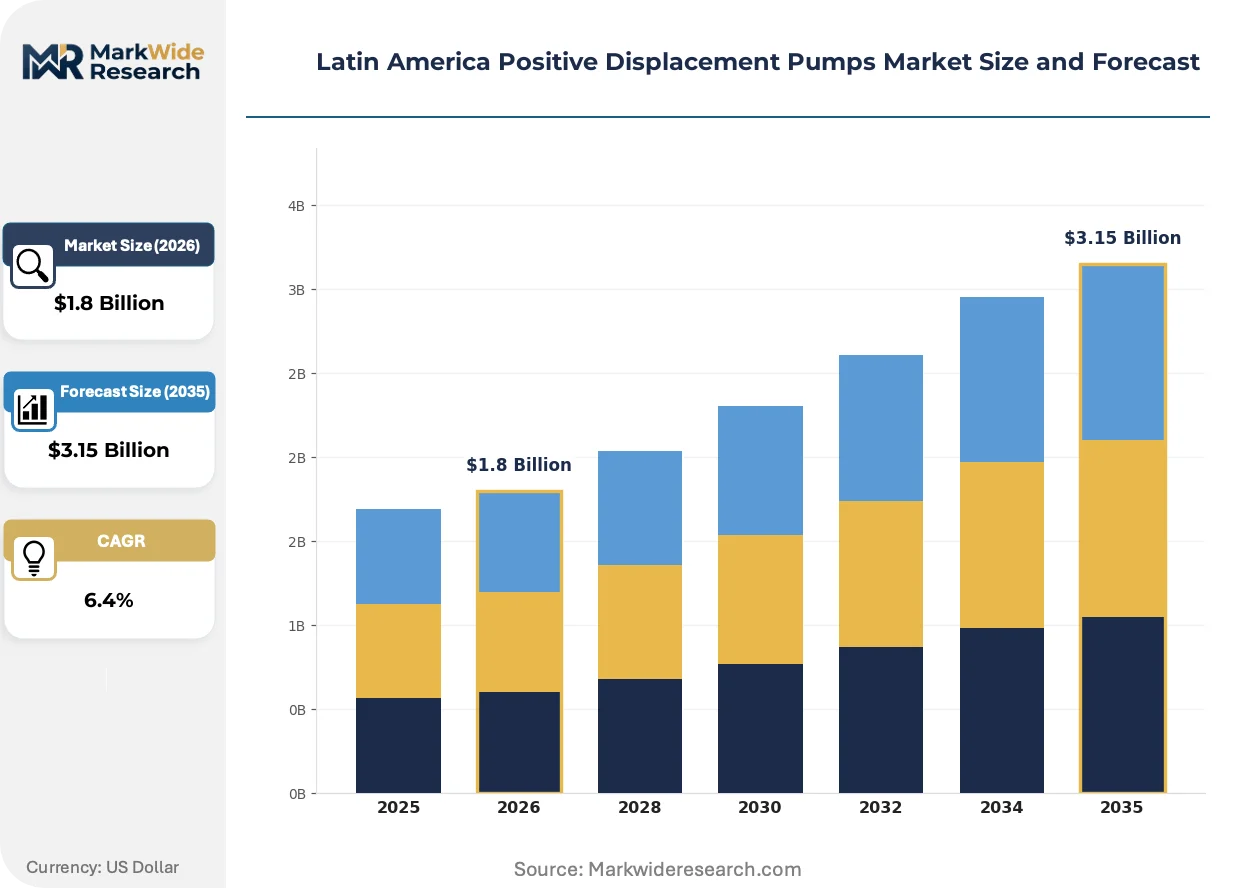
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gear Pumps, Diaphragm Pumps, Screw Pumps, Piston Pumps End User: Oil & Gas, Water Treatment, Food & Beverage, Chemicals Technology: Hydraulic, Pneumatic, Electric, Mechanical Application: Transfer, Metering, Mixing, Circulation |
| Companies Covered | The Weir Group PLC, Pentair Plc, Flowserve Corporation, Dover Corporation, IDEX, Xylem Inc, Atlas Copco, Alfa Laval AB, SPX FLOW Inc, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Positive Displacement Pumps Market Shifts & Advancements
Smart actuation and material science advances are compressing maintenance intervals while expanding the fluid viscosity and solids tolerance envelope of positive displacement architectures across Latin American process industries.
Perfluoroelastomer (FFKM) diaphragm compounds with enhanced chemical resistance are supplanting traditional PTFE and EPDM configurations in Brazilian petrochemical and pharmaceutical dosing applications. São Paulo state chemical processors are specifying these materials for sulfuric acid and solvent transfer duties previously requiring exotic metal pump constructions. The shift is compressing total cost of ownership calculations and narrowing the price gap between polymer-lined and solid alloy pump architectures.
Brazil's ANVISA sanitary regulations and Mexico's COFEPRIS pharmaceutical manufacturing standards are mandating surface finish documentation and material traceability to ASTM or DIN standards. These frameworks are filtering uncertified regional fabricators from food-grade and injectable drug pump procurement, concentrating specification authority with multinational suppliers possessing established quality management systems. Argentine dairy processors and Mexican vaccine manufacturers now require 3.1 mill certificates and Ra 0.8 surface specifications as baseline bid qualifications.
After-sales service unbundling is disrupting traditional pump procurement patterns across Mexican refinery corridors. State oil company maintenance divisions are separating hardware purchase from long-term service agreements, forcing original equipment manufacturers to compete with independent service providers for overhaul and spare parts revenue. Pemex's Tula and Salamanca refinery complexes now tender pump supply and maintenance as distinct lots, compressing bundled margin structures that historically subsidized competitive hardware pricing.
Latin America Positive Displacement Pumps Market Segmentation
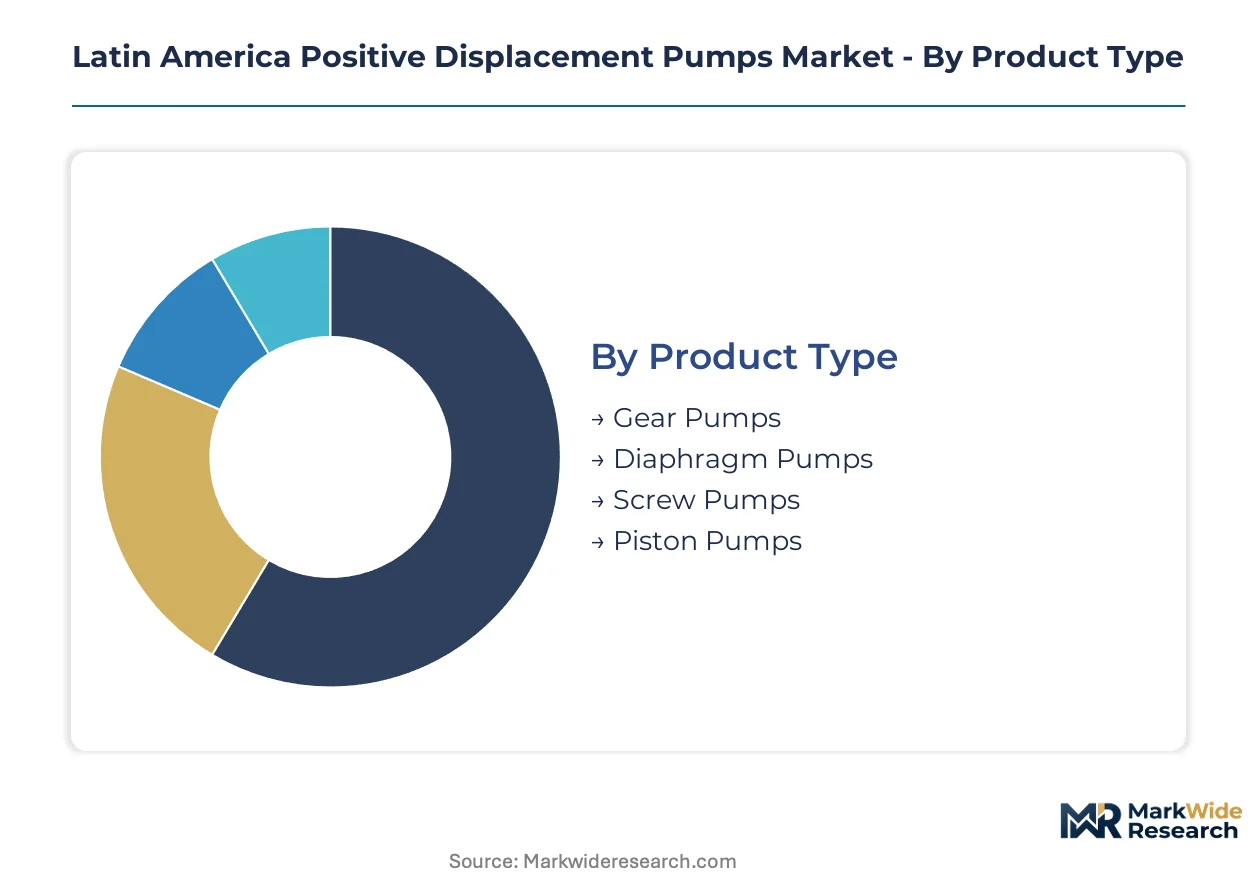
Positive displacement pump procurement across Latin America fragments across four distinct classification axes. Each dimension captures different buyer priorities: fluid handling physics, operational energy source, industrial deployment context, and precise functional role within process sequences.
Product Type:
Premium margin pools concentrate in high-pressure piston architectures and corrosion-resistant diaphragm configurations, while gear pumps compete on volume throughput.
- Diaphragm Pumps:Elastomer-lined chambers isolate process fluid from mechanical drive components, enabling zero-leakage handling of corrosive chemistries. São Paulo state chemical processors and Mexican refinery wastewater units are specifying FFKM and PTFE diaphragm compounds under CONAMA and NOM discharge mandates, displacing legacy packed plunger designs in sulfuric acid and caustic soda service.
- Piston Pumps:Reciprocating plungers or pistons generate pressures exceeding 5,000 psi through precision-machined bores and ceramic-coated surfaces. Brazil's pre-salt carbonate reservoirs demand API 674-compliant high-pressure injection systems for CO2 and produced water reinjection, sustaining premium pricing tiers unavailable to lower-pressure alternatives.
- Gear Pumps:Intermeshing rotors trap fluid between gear teeth and housing walls, delivering pulse-free flow ideal for high-viscosity mineral oils and lubricant blending. These units dominate installed base across Brazilian hydraulic power units and Argentine agricultural equipment manufacturing.
- Screw Pumps:Single or multiple helical rotors convey fluid axially with minimal shear, serving hygienic product transfer in Argentina's Pampas dairy belt and viscous crude handling in Colombia's Llanos Basin thermal recovery projects.
Gear pumps hold installed capacity across Latin American lubricant blending infrastructure. Diaphragm pumps are rotating up the share rankings on chemical resistance specification.
End User:
Volume concentration tracks municipal procurement cycles, while value concentration aligns with hydrocarbon extraction intensity and sanitary processing certification requirements.
- Oil & Gas:Upstream, midstream, and downstream hydrocarbon operations require pressure-rated positive displacement systems for multiphase transfer, chemical injection, and refined product loading. Brazil's pre-salt developments and Colombia's heavy oil thermal recovery projects sustain demand for high-specification piston and progressive cavity architectures.
- Water Treatment:Municipal utilities and industrial effluent facilities deploy diaphragm and peristaltic systems for precise chemical dosing and sludge handling. CONAMA Resolution 430 compliance deadlines across São Paulo and Rio de Janeiro state authorities are collapsing historical centrifugal preferences in tertiary treatment specifications.
- Food & Beverage:ANVISA and COFEPRIS sanitary mandates require surface finish documentation to Ra 0.8 specifications and 3.1 mill material certificates, filtering procurement toward multinational suppliers with established quality management systems in Brazilian dairy and Mexican beverage processing.
- Chemicals:Petrochemical clusters across Brazil's Southeast industrial corridor demand corrosion-resistant pump configurations for acid transfer, solvent circulation, and precise reagent metering in polymer and specialty chemical production.
Water treatment holds installed capacity across municipal procurement offices. Oil & gas is rotating up the share rankings on pre-salt injection intensity.
Technology:
Energy source selection determines maintenance intervals, precision capability, and integration complexity with existing plant automation infrastructure.
- Electric:Variable frequency drive integration enables precise flow control and smart pressure feedback loops, opening pharmaceutical and food-grade niches previously served by pneumatic alternatives. Brazilian sanitation concessions are specifying electric-drive diaphragm portfolios for chemical dosing accuracy.
- Hydraulic:Fluid power actuation delivers high force density for high-pressure applications where electrical hazards prohibit standard motor configurations, sustaining presence in offshore platform and refinery process units.
- Pneumatic:Compressed air drive provides intrinsic safety in explosive atmospheres but faces displacement by electric alternatives as VFD costs decline and precision requirements tighten across Mexican pharmaceutical manufacturing.
- Mechanical:Direct shaft coupling to prime movers persists in simple transfer duties and remote locations lacking reliable electrical infrastructure, particularly in Argentine agricultural and Colombian heavy oil field applications.
Pneumatic systems hold installed capacity across legacy explosive atmosphere specifications. Electric drive is rotating up the share rankings on precision dosing convergence.
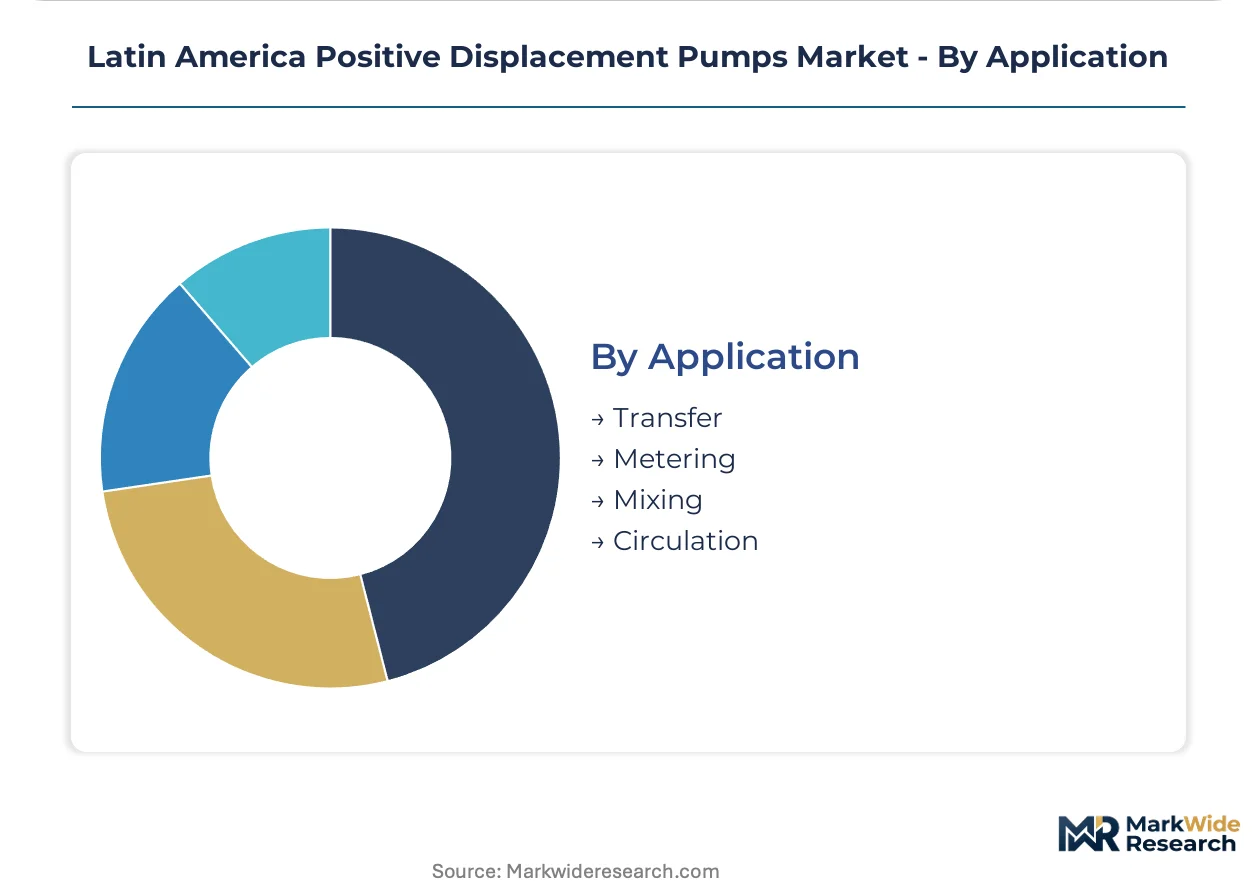
Application:
Functional role within process sequences determines pump specification priority: accuracy for metering, reliability for transfer, homogeneity for mixing, and temperature control for circulation.
- Metering:Precision dosing applications demand pulsation dampening, stroke adjustment mechanisms, and calibration protocols for chemical injection, pharmaceutical formulation, and water treatment reagent addition. CONAMA and NOM tertiary treatment standards are accelerating specification of positive displacement alternatives for accurate polymer and chlorine dosing.
- Transfer:Bulk fluid movement between storage, processing, and distribution points prioritizes volumetric efficiency and viscosity handling over precision, serving crude oil pipeline injection and lubricant blending operations.
- Circulation:Continuous loop operation for temperature control, filtration, and homogeneous blending requires sustained duty cycles with minimal shear degradation, common in hygienic food processing and polymer reactor temperature management.
- Mixing:In-line blending and additive incorporation demand controlled turbulence generation without phase separation, deployed in fuel additive injection and specialty chemical formulation.
Transfer applications hold installed capacity across hydrocarbon logistics infrastructure. Metering is rotating up the share rankings on environmental compliance specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentration clusters around municipal water authorities in Brazil and Mexico, with industrial demand radiating from São Paulo's chemical corridor and the Gulf Coast refinery belt.
Brazil
Pre-salt carbonate reservoirs drive high-pressure piston pump procurement for CO2 and produced water reinjection. ANVISA sanitary regulations filter uncertified suppliers from pharmaceutical and food-grade pump procurement. São Paulo state's Southeast industrial corridor dominates chemical processing and petrochemical cluster demand.
Mexico
Refinery modernization and unconventional resource development sustain demand for corrosion-resistant diaphragm configurations. NOM effluent standards accelerate replacement cycles in municipal wastewater treatment. Pemex's Tula and Salamanca refinery complexes drive aftermarket service unbundling trends.
Argentina
IRAM pressure equipment standards create compliance layering that favors multinational documentation capabilities. Pampas dairy belt operations specify hygienic screw pump configurations with 3.1 mill material certificates. Buenos Aires province chemical processors drive FFKM diaphragm adoption for sulfuric acid transfer.
Chile
Atacama salar lithium extraction operations require corrosion-resistant positive displacement architectures with ANSI/ASME certification. SEC electrical safety certifications add testing burdens for pumps sourced from regional manufacturing bases. Antofagasta Region mining and chemical processors concentrate brine pumping demand.
Colombia
Llanos Basin heavy oil thermal recovery projects present emerging demand for high-temperature progressive cavity pump systems. National environmental authority resolutions mandate tertiary treatment standards in Bogotá and Medellín municipal utilities. Caribbean Coast petrochemical installations drive gear pump procurement for lubricant blending.
Latin America Positive Displacement Pumps Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with established aftermarket service networks. Market structure concentrates specification authority with multinational suppliers possessing quality management systems and certification documentation capabilities. Two strategic archetypes dominate: full-service pump system integrators with dense regional service footprints, and specialized hygienic equipment fabricators targeting food and pharmaceutical niches. Competitive moves center on separating hardware supply from long-term service agreements and expanding electric-drive portfolio integration with variable frequency drive technology.
Among diversified industrial conglomerates, Flowserve Corporation, Xylem Inc, and Alfa Laval AB occupy positions exemplifying distinct competitive vectors. Flowserve represents the full-service archetype with refinery corridor aftermarket density. Xylem anchors the electric-drive diaphragm convergence for municipal sanitation concessions. Alfa Laval exemplifies hygienic specialization with screw pump configurations serving dairy and pharmaceutical processing lines.
| Leading Market Players |
|---|
| The Weir Group PLC |
| Pentair Plc |
| Flowserve Corporation |
| Dover Corporation |
| IDEX |
| Xylem Inc |
| Atlas Copco |
| Alfa Laval AB |
| SPX FLOW Inc |
| Others |
Supply & Pricing Matrix
Ninety-to-120-day lead times for high-tolerance screw pump profiles and ceramic-coated plungers concentrate pricing power with German and Italian machining clusters, while Brazilian and Mexican buyers absorb premium markups for expedited delivery against CONAMA and NOM compliance deadlines. This supply concentration compresses margin structures for regional fabricators lacking pass-through mechanisms in municipal tenders, forcing specification authority toward multinational suppliers with captive European supply relationships.
Pricing Analysis
Electric-drive diaphragm systems with integrated variable frequency drives command 25-40% premiums over pneumatic alternatives, while legacy mechanical-drive gear pumps compete at economy tiers across Argentine agricultural equipment channels. Three-tier pricing structure across premium, standard, and economy levels separates API 674-certified piston pumps for Brazil's pre-salt injection service from sanitary screw configurations for ANVISA-regulated dairy processing and commodity gear pumps for lubricant blending. Cost compression in standard-tier diaphragm pumps is intensifying because São Paulo state chemical processors are consolidating procurement volumes under framework agreements. Municipal water utilities exhibit highest price sensitivity due to fixed-budget tender structures, while pharmaceutical manufacturers under COFEPRIS mandates demonstrate lowest sensitivity due to certification-driven specification lock-in.
Supply Chain Analysis
Germany, Italy, and the United States anchor precision component fabrication for high-tolerance screw pump profiles, ceramic-coated plungers, and super-duplex alloy castings. Latin American pump assemblers draw from these inputs for corrosion-resistant diaphragm compounds, precision-machined gear sets, and elastomer formulations. Single-source vulnerability concentrates in German machining clusters for API 674-compliant high-pressure injection systems, exposing Brazilian pre-salt operators to lead time volatility. Distribution runs through authorized distributor networks serving refinery corridors and municipal procurement offices, with aftermarket service unbundling disrupting traditional bundled hardware-service margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation across regulatory certification tiers creates niche opportunities as ANVISA, COFEPRIS, and NOM frameworks filter uncertified regional fabricators from pharmaceutical and food-grade procurement, concentrating specification authority with documented quality management systems.
For Market Incumbents: Secure aftermarket service density across Mexican refinery corridors and Brazilian pre-salt logistics bases before independent service providers capture overhaul revenue under Pemex's unbundled tender structures. Deepen backward integration into elastomer compounding for FFKM diaphragm formulations to defend margin position against specialty polymer suppliers. Certification investment in IRAM and SEC cross-border recognition protocols represents the critical lever for Argentine and Chilean market access. For New Entrants and Emerging Players: Aftermarket service gaps in Colombia's emerging Llanos Basin thermal recovery projects and Chilean lithium extraction operations present white-space targets where incumbent coverage remains thin. Electric-drive diaphragm portfolios with smart pressure feedback loops offer the most penetrable wedge against pneumatic legacy systems in Mexican pharmaceutical manufacturing. A go-to-market angle anchored to ANSII/ASME certification for brine pumping applications unlocks Antofagasta Region mining procurement channels. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-monetized pump divisions lacking dedicated aftermarket service infrastructure. Long-term viability over a multi-year horizon hinges on exposure to pre-salt injection intensity and lithium extraction expansion rather than municipal water treatment cyclicality. Consolidation signals to monitor include framework agreement awards by São Paulo state sanitation authorities that concentrate procurement with documented quality management systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elastomer Compounding | Captive FFKM formulation capacity insulates Brazilian petrochemical pump margins from specialty polymer price volatility. |
| Cross-Border Certification Harmonization | IRAM-SEC mutual recognition protocols reduce duplicative testing burdens for pumps sourced from Brazilian manufacturing bases. |
| Electric-Drive Portfolio Expansion | VFD-integrated diaphragm systems displace pneumatic alternatives in COFEPRIS-regulated pharmaceutical dosing applications. |
| Aftermarket Service Unbundling Response | Separate hardware and service tender participation preserves Pemex refinery corridor revenue streams against independent competitors. |
| High-Temperature Progressive Cavity Development | Thermal recovery-rated architectures capture Colombian Llanos Basin heavy oil extraction demand. |
Research Methodology
Cross-validation between primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads and secondary sources including customs/trade data, SEC 10-K filings, and ANVISA certification registries anchors the qualitative findings. Bottom-up triangulation across equipment installation databases and top-down validation through national sanitation authority procurement records ensure segmentation integrity. Stakeholder conversations spanned Brazilian pre-salt operators, Mexican refinery maintenance divisions, Argentine dairy processors, and Chilean lithium extraction developers.
Sensitivity analysis around nickel and molybdenum price volatility, CONAMA compliance deadline shifts, and electric-drive adoption curves informs the analytical framework across the projection horizon. Segmentation dimensions modeled include pump architecture type, end-use industry, drive technology, functional application role, and regional regulatory cluster. CAGRs derive from equipment replacement cycle analysis, tertiary treatment upgrade pipelines, and hydrocarbon extraction intensity projections. Industry-specific forecast inputs incorporate API 674 specification procurement rates and ANVISA/COFEPRIS certification penetration trends.
Forecasts assume regulatory continuity in Brazil's CONAMA framework, Mexico's NOM standards, and Argentina's IRAM protocols; material policy shifts would require re-modeling. Commodity price volatility in specialized alloys and cross-border certification friction represent specific risk factors that could revise trajectory assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Water Desalination Pumps Market
Pumps and Control Devices
Global Industrial Submersible Pumps Market
Pumps and Control Devices
Global Compressor Control Systems Market
Pumps and Control Devices
Plunger Pumps Market
Pumps and Control Devices
Positive Displacement (PD) Sanitary Pumps Market
Pumps and Control Devices
Marine Pump Market
Pumps and Control Devices
Global Smart Pumps Market
Pumps and Control Devices
Pool Heat Pumps Market
Pumps and Control Devices
Liquid Ring Vacuum Pump Market
Pumps and Control Devices
Latin America Centrifugal Pumps Market
Pumps and Control Devices
Dewatering Pumps Market
Pumps and Control Devices
Water Pump Market
Pumps and Control Devices
Cone Penetrometer Market
Pumps and Control Devices
Melt & Gear Pump Market
Pumps and Control Devices
Ultra High Pressure Water Pump Market
Pumps and Control Devices
Global Self Priming Pumps Market