
 Sudan Oil and Gas Market | 2026-2036
Sudan Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Sudan Oil and Gas Market Analytics
Pipeline infrastructure and coastal export terminals is tilting toward Red Sea corridor prioritization as Sudan reconfigures crude evacuation routes. China National Petroleum Corporation leverages its equity stakes in Block 1/2/4 and Block 6 concessions to sustain production plateau levels across mature fields. Petronas anchors downstream activity through its involvement in Khartoum refinery operations and fuel distribution networks. Greater Nile Petroleum Operating Company competes on operational efficiency across the Muglad Basin's high-temperature, high-pressure reservoirs.
Sudan oil and gas encompasses the exploration, extraction, processing, and distribution of hydrocarbon resources including Nile Blend and Dar Blend crude oils with API gravities ranging from 20 to 33 degrees, primarily serving regional fuel supply and limited export markets. Crude oil dominates production volumes but carries mature-field decline rates requiring enhanced recovery interventions. Natural gas remains underdeveloped structurally, with associated gas flaring regulations now pressuring operators to commercialize stranded gas for power generation feedstock. Refining capacity constraints create margin pools in refined products, where Khartoum Refinery Co. occupies a bottleneck position between upstream supply and domestic transportation and industrial end users.
Sudan's Ministry of Energy and Mining and the national petroleum regulator govern licensing rounds, production-sharing contracts, and environmental compliance for upstream operators. The country's national standards body aligns technical specifications with API and ASTM benchmarks for refined product quality, while the central bank's foreign exchange controls shape equipment import timelines and contractor payment cycles. Stakeholders must monitor whether fiscal term renegotiations and infrastructure security arrangements stabilize sufficiently to sustain capital deployment into exploratory drilling and midstream expansion programs.
Market Dynamics
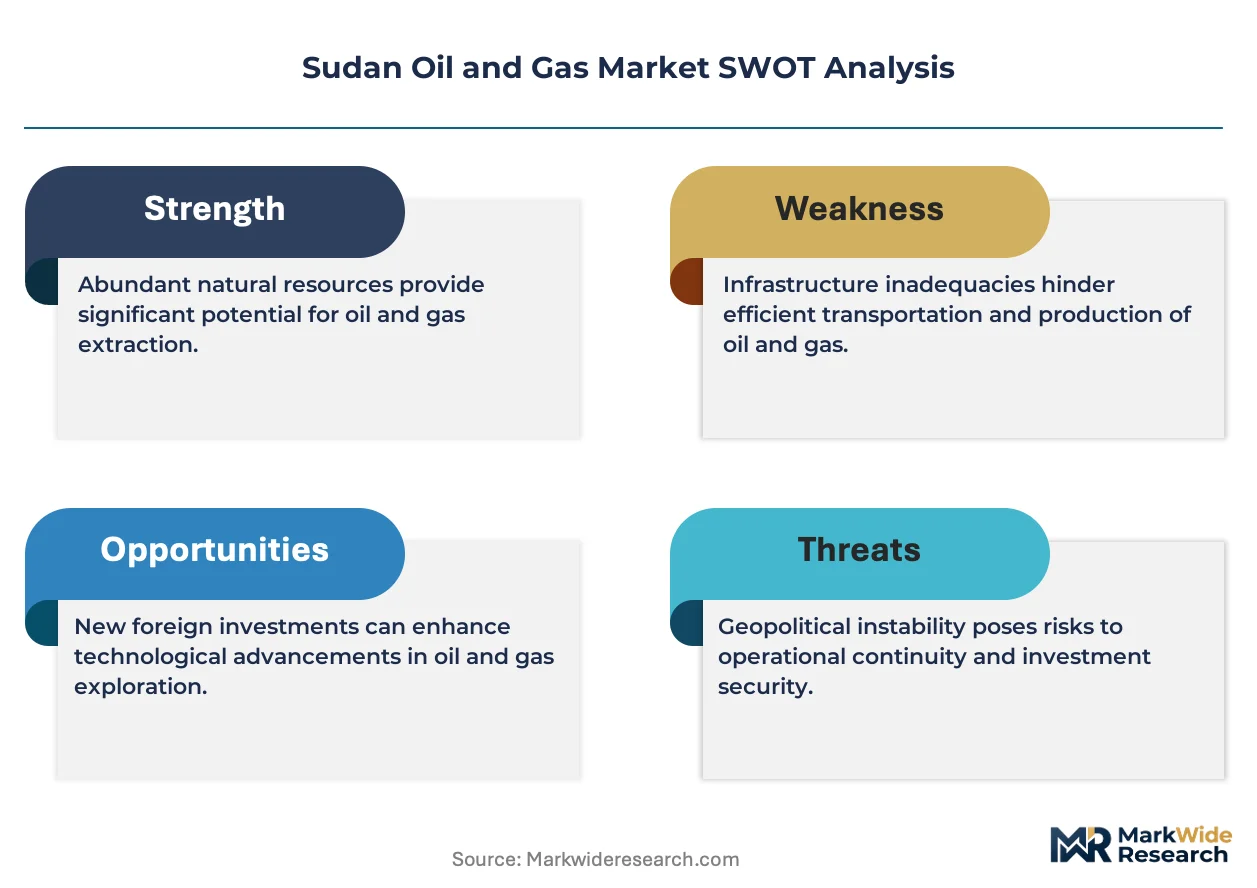
Upstream licensing reforms by Sudan's Ministry of Energy and Mining are recalibrating capital deployment timelines, while associated gas flaring regulations force operators to commercialize stranded reserves or face operational penalties.
Growth Catalysts
- Grid electrification targets:Power generation utilities are expanding hydrocarbon procurement as national electrification programs advance, creating sustained offtake demand for natural gas and fuel oil.
- Streamlined licensing frameworks:Sudan's Ministry of Energy and Mining has reduced bureaucratic friction for production-sharing contracts, shortening approval cycles for exploratory drilling programs.
- Red Sea corridor prioritization:Pipeline infrastructure reconfiguration toward Port Sudan terminals is opening alternative crude evacuation routes that bypass traditional chokepoints.
Market Restraints
- Mature-field decline rates:Crude oil production from the Muglad Basin requires enhanced oil recovery interventions as reservoir pressure depletes, elevating capital intensity per barrel.
- Foreign exchange controls:The central bank's import licensing requirements delay equipment procurement timelines and disrupt contractor payment cycles for international service providers.
- Refining capacity bottlenecks:Khartoum Refinery Co.'s limited throughput creates margin compression for upstream operators unable to access premium product markets.
Strategic Opportunities
- Stranded gas commercialization:Associated gas capture mandates create feedstock supply for power generation expansion in Khartoum state and surrounding industrial zones.
- Enhanced recovery partnerships:Thermal and chemical EOR technologies offer production plateau extension for China National Petroleum Corporation-operated mature fields in Block 1/2/4.
- Downstream distribution networks:Fuel retail infrastructure gaps outside Khartoum present white space for logistics operators establishing regional storage and transport capacity.
Industry Challenges
- High-temperature reservoir engineering:Muglad Basin's high-pressure formations demand specialized drilling fluids and completion technologies that strain local technical capacity.
- Security infrastructure deployment:Pipeline protection and facility safeguarding require sustained operational expenditure that elevates breakeven thresholds for marginal field development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sudan Oil and Gas Market |
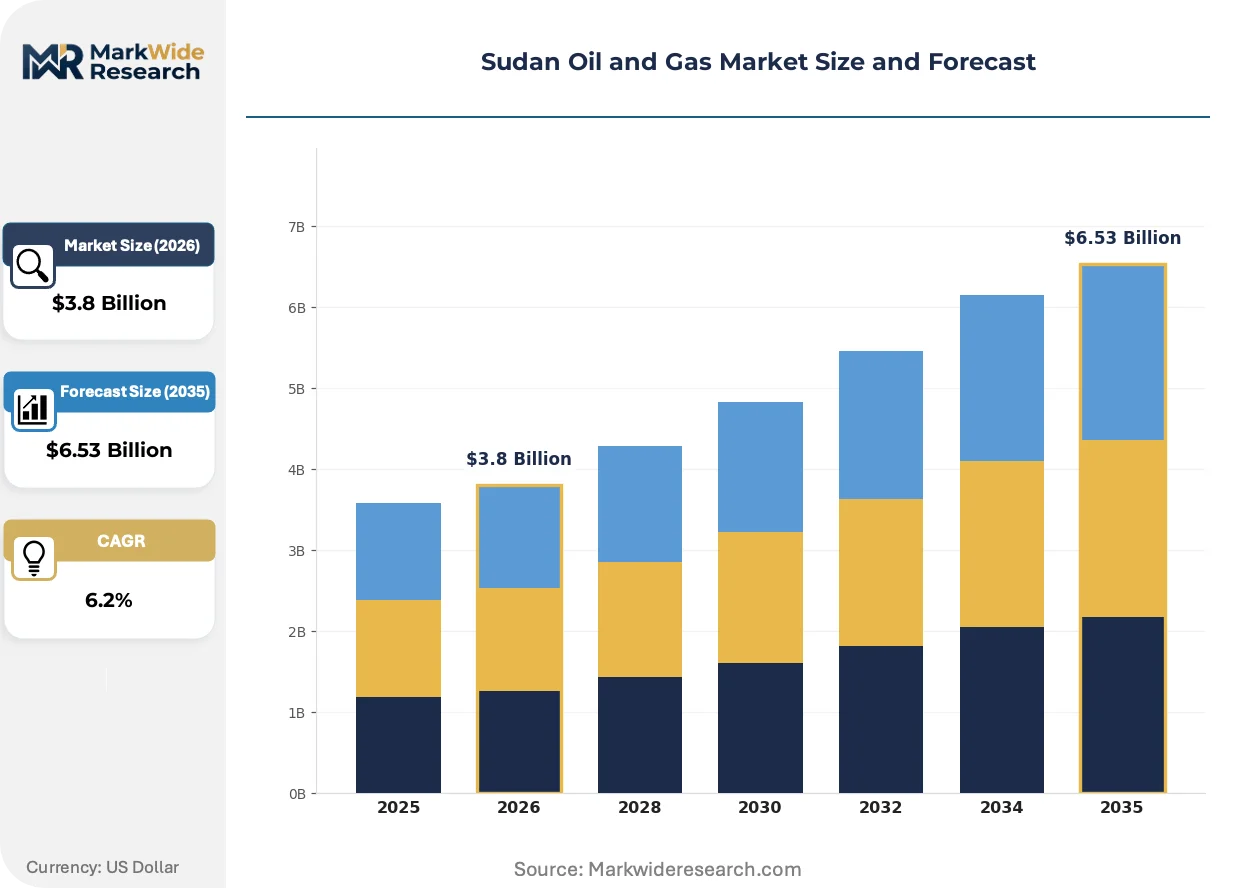
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude Oil, Natural Gas, Refined Products, LPG Application: Power Generation, Industrial Use, Transportation, Residential Heating Technology: Exploration, Drilling, Production, Refining End User: Power Companies, Manufacturing Firms, Oil Distributors, Households |
| Companies Covered | Sudan National Petroleum Corporation, China National Petroleum Corporation, Petronas, Petrodar Operating Company, Oil and Natural Gas Corporation, Greater Nile Petroleum Operating Company, Sunagas, JSC Zarubezhneft, Khartoum Refinery Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sudan Oil and Gas Market Evolving Landscape
Digital reservoir characterization and gas monetization technologies are displacing conventional field management approaches across Sudan's mature producing assets. Regulatory pressure on flaring is accelerating adoption of capture and processing infrastructure.
Enhanced oil recovery is hybridizing thermal injection with chemical flooding protocols to sustain output from Block 6 and Greater Nile Petroleum Operating Company concessions. Operators are deploying these methods in the Muglad Basin's heavy crude reservoirs where natural drive mechanisms have depleted. This convergence is compressing decline curves and extending productive field life without full redevelopment.
Sudan's Ministry of Energy and Mining has enacted associated gas utilization mandates that prohibit routine flaring from new production facilities. The regulation forces operators to install compression and processing infrastructure or face production quota penalties. Khartoum state industrial consumers are responding by negotiating long-term gas supply agreements that displace fuel oil in power generation feedstock.
Industrial offtake contracting is consolidating around term supply agreements with Khartoum-based refineries and petrochemical consumers. Spot market participation is contracting as buyers seek volume security amid foreign exchange volatility. Cement and steel manufacturers in the capital region are driving this behavioral shift, locking in multi-year fuel supply arrangements that bypass traditional distributor intermediaries.
Sudan Oil and Gas Market Segmentation
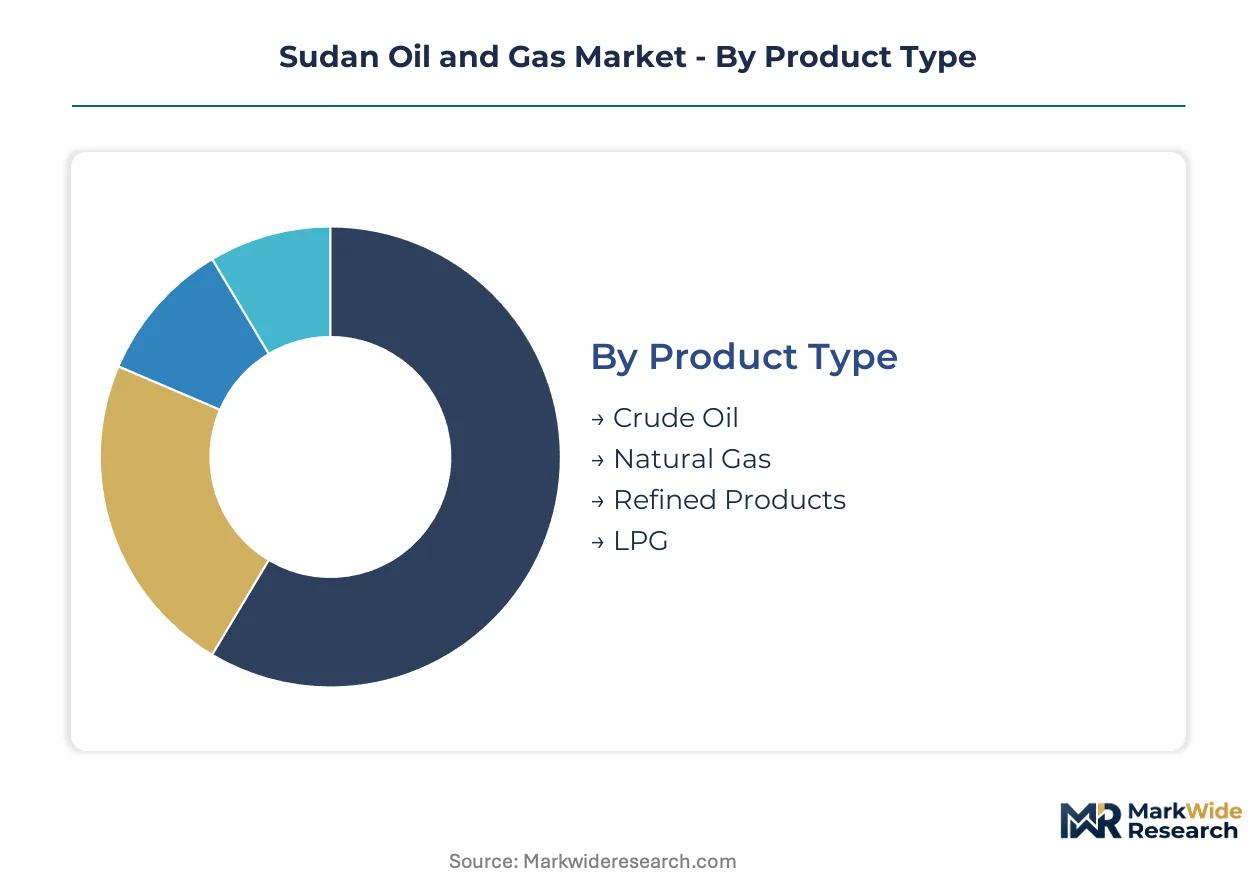
Segmentation reveals how hydrocarbon value flows through Sudan's energy system, from reservoir characteristics shaping upstream investment to end-use contracting patterns determining offtake reliability. Each dimension exposes distinct margin pools and capital deployment risks for operators navigating licensing reforms and infrastructure bottlenecks.
Product Type:
Cost tier differentiation separates commodity-grade feedstocks from processed fuels with premium placement in domestic supply chains.
- Crude Oil:Nile Blend and Dar Blend crudes with API gravities spanning 20 to 33 degrees dominate upstream production volumes. Khartoum Refinery Co. processes these grades for regional distribution, though mature-field decline rates in the Muglad Basin force enhanced recovery investments to sustain throughput.
- Natural Gas:Associated gas streams from oil production fields remain structurally underdeveloped, with flaring regulations now pressuring operators toward commercialization. Power generation utilities in Khartoum state negotiate term supply agreements to displace fuel oil in baseload electricity production.
- Refined Products:Diesel, gasoline, and fuel oil output from Khartoum refinery operations supply transportation and industrial thermal demand.
- LPG:Bottled gas distribution serves residential cooking and heating needs outside grid-connected urban centers.
Crude oil commands the established base. The steepest expansion runs through natural gas commercialization as flaring mandates tighten.
Application:
Volume concentration patterns track electrification infrastructure buildout and industrial clustering geography across Sudan's economic core.
- Power Generation:National grid expansion targets drive sustained hydrocarbon procurement from thermal utilities. Sudan's Ministry of Energy and Mining prioritizes gas-to-power projects to reduce fuel oil dependency in baseload generation.
- Industrial Use:Cement and steel manufacturers in Khartoum state lock in multi-year fuel supply arrangements that bypass traditional distributor intermediaries. Foreign exchange volatility accelerates this shift toward term contracting.
- Transportation:Road freight and passenger vehicle fleets consume diesel and gasoline volumes distributed through retail networks.
- Residential Heating:Seasonal demand spikes in northern states rely on kerosene and LPG distribution outside pipeline infrastructure reach.
Power generation anchors procurement volumes. Industrial use is gaining share fastest as manufacturing capacity expands around Khartoum.
Technology:
Maturity gradients separate frontier exploration from reservoir management disciplines requiring specialized technical capacity.
- Exploration:Seismic surveying and wildcat drilling programs target untested structures in peripheral basins beyond the Muglad production core. Sudan's Ministry of Energy and Mining streamlined licensing frameworks to compress approval cycles for new concession awards.
- Drilling:High-temperature, high-pressure formations demand specialized drilling fluids and completion technologies that strain local service provider capabilities. International contractors face payment cycle disruptions from central bank foreign exchange controls.
- Production:Thermal and chemical enhanced oil recovery methods extend field life in Block 1/2/4 and Block 6 concessions.
- Refining:Khartoum Refinery Co.'s limited throughput capacity creates bottlenecks between upstream supply and product market access.
Production technology commands the established base. Exploration activity is climbing the fastest as licensing reforms attract foreign capital.
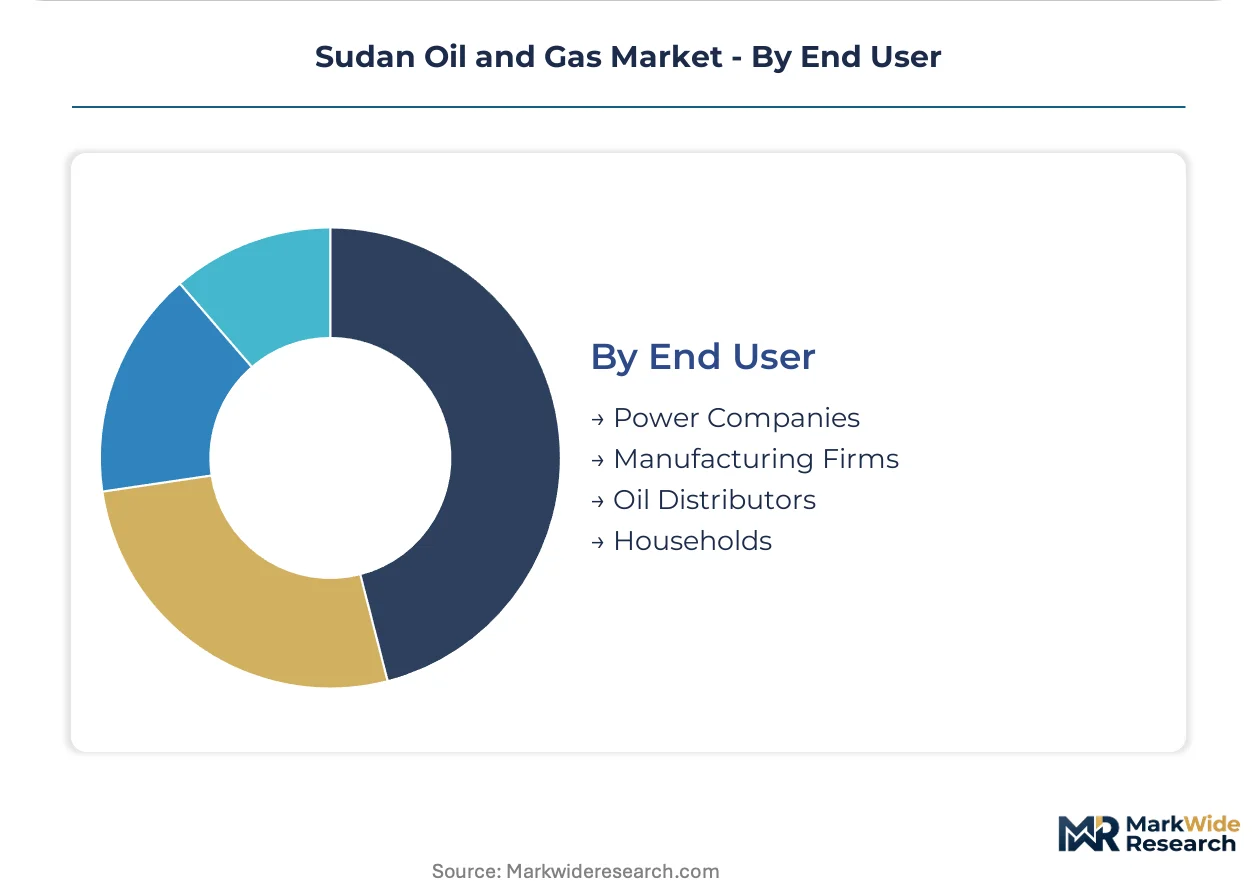
End User:
Customer type determines contracting structure, with institutional offtakers securing volume priority over fragmented household demand.
- Power Companies:Grid operators negotiate long-term supply agreements for natural gas and fuel oil feedstock. Associated gas capture mandates from Sudan's Ministry of Energy and Mining align operator incentives with utility procurement needs.
- Manufacturing Firms:Cement and steel producers consolidate purchasing through direct refinery relationships, displacing distributor intermediaries. Spot market participation contracts as buyers seek price predictability.
- Oil Distributors:Wholesale and retail logistics operators manage product movement from refinery gates to end-use points.
- Households:LPG cylinder distribution and kerosene retail serve energy access needs in peri-urban and rural settlements.
Power companies command the established base. Manufacturing firms show the steepest procurement expansion as industrial clustering accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greater Nile Oil Pipeline anchors Sudan's crude evacuation capacity, linking Muglad Basin production zones to Port Sudan terminals on the Red Sea coast. This infrastructure corridor concentrates upstream investment flows and shapes sub-regional development priorities across Sudan's energy geography.
Khartoum State
Industrial clustering around the capital drives concentrated demand for refined products and natural gas feedstock. Sudan's Ministry of Energy and Mining directs licensing reforms toward gas-to-power projects that displace fuel oil in baseload generation. The Khartoum Refinery Co. facility processes Nile Blend crude for distribution across the metropolitan industrial zone.
White Nile State
Agricultural processing and limited manufacturing sustain modest diesel and fuel oil consumption outside the capital corridor. The state's petroleum regulator coordinates with Khartoum on product allocation quotas during supply disruptions. Jabalain and Kosti industrial areas host cement manufacturers negotiating direct refinery supply contracts.
Sennar State
Sugar processing complexes and irrigation infrastructure anchor seasonal fuel demand patterns in this agricultural heartland. Central bank foreign exchange controls delay equipment imports for distributed power generation assets. Sennar Dam vicinity industrial users rely on fuel oil shipments via White Nile river transport.
Red Sea State
Port Sudan terminal infrastructure and coastal refining prospects position this zone for export-oriented hydrocarbon development. The Ministry of Energy and Mining prioritizes pipeline protection investments along the crude evacuation corridor. Suakin and Port Sudan harbor zones concentrate maritime logistics capacity for regional product trade.
South Kordofan State
Peripheral basin exploration targets and security infrastructure requirements elevate capital costs for frontier development. Production-sharing contract terms from Sudan's Ministry of Energy and Mining must compensate for elevated operational risk profiles. Heglig field vicinity maintains residual production from mature Block 1/2/4 concessions.
Sudan Oil and Gas Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the service and equipment layers. The Sudan oil and gas market structures around state-affiliated entities holding concession rights, international oil companies operating production blocks, and specialized midstream operators managing evacuation infrastructure. Three archetypes dominate: national oil companies with licensing authority, international operators with technical capacity for mature-field management, and downstream processors controlling product market access. Competitive dynamics center on production-sharing contract renegotiation and enhanced recovery technology partnerships.
Within the international operator tier, China National Petroleum Corporation and Petronas exemplify the capital-deployment archetype for mature basin development. Greater Nile Petroleum Operating Company occupies a position bridging operational execution and consortium coordination across high-temperature reservoir environments. Sudan National Petroleum Corporation anchors the state-affiliated tier, representing concession authority and regulatory interface functions. Khartoum Refinery Co., Ltd. sits within the downstream bottleneck position, controlling product market access between upstream supply and domestic offtake demand.
| Leading Market Players |
|---|
| Sudan National Petroleum Corporation |
| China National Petroleum Corporation |
| Petronas |
| Petrodar Operating Company |
| Oil and Natural Gas Corporation |
| Greater Nile Petroleum Operating Company |
| Sunagas |
| JSC Zarubezhneft |
| Khartoum Refinery Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Khartoum Refinery Co.'s chronic undercapacity relative to Muglad Basin crude output concentrates pricing power with downstream gatekeepers while forcing upstream operators into discount negotiations for unprocessed barrels. This utilization gap shapes supplier behavior through term-contracting cascades and feeds back into capital allocation decisions that favor midstream infrastructure over exploratory drilling.
Pricing Analysis
Volume-discount tiering structures separate term-contract industrial offtakers from spot-market participants across Sudan's refined product distribution. Power generation utilities and cement manufacturers locking in multi-year fuel oil agreements command price advantages over fragmented transport operators purchasing diesel through distributor intermediaries. Price differentiation rests on offtake reliability and direct refinery access, with Khartoum-based manufacturing firms least sensitive to marginal price shifts due to embedded switching costs, while rural LPG distributors face acute margin compression from central bank foreign exchange delays.
Supply Chain Analysis
Upstream feedstock flows from Muglad Basin production zones through the Greater Nile Oil Pipeline corridor toward Port Sudan terminals, creating geographic concentration across Sudan's Red Sea evacuation route. Crude oil, associated gas streams, and specialized drilling fluids anchor material dependencies, with high-temperature reservoir chemicals sourced through constrained import channels. Single-source vulnerability runs through pipeline protection infrastructure along contested transit zones. Distribution feeds from Khartoum Refinery Co. through state-allocated product quotas to regional storage depots and licensed retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sudan's oil and gas market functions as a regulatory entrenchment story where production-sharing contract terms and licensing authority create defendable positions for established operators. The Ministry of Energy and Mining's gatekeeping role erects structural barriers that compound with technical capacity requirements for high-pressure reservoir management.
For Market Incumbents: Insulate concession positions through enhanced recovery technology partnerships that extend Block 1/2/4 and Block 6 field life, while securing pipeline protection service agreements that neutralize security infrastructure cost escalation. Foreign exchange volatility threatens equipment procurement timelines; vertical integration into local drilling fluid formulation reduces import licensing exposure. For New Entrants and Emerging Players: White Nile State's agricultural processing corridor offers stranded gas commercialization opportunities where power generation utilities seek feedstock alternatives to fuel oil. Direct contracting with cement manufacturers in Jabalain and Kosti industrial zones bypasses Khartoum distributor bottlenecks. Technical service specialization in high-temperature completion technologies addresses capability gaps that strain local contractor capacity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across enhanced oil recovery sub-segments as thermal and chemical injection methods displace conventional well management. Long-term viability favors operators with demonstrated reservoir characterization capabilities and established Ministry relationships. Acquisition targets should display operational track records in Muglad Basin high-pressure formations alongside secured term offtake agreements. The signal to monitor is licensing round participation rates from Asian national oil companies as foreign capital deployment sentiment indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Associated Gas Capture Infrastructure | Flaring regulations force compression and processing investment to avoid production quota penalties from Sudan's Ministry of Energy and Mining. |
| Enhanced Recovery Partnership | Thermal-chemical hybrid methods extend productive life of CNPC-operated mature fields in Block 1/2/4 concessions. |
| Downstream Distribution Expansion | Fuel retail infrastructure gaps outside Khartoum create white space for logistics operators establishing regional storage capacity. |
| Direct Industrial Offtake Contracting | Cement and steel manufacturers lock in multi-year supply arrangements that displace traditional distributor intermediaries. |
| Pipeline Protection Investment | Security infrastructure deployment along Greater Nile corridor elevates breakeven thresholds but secures crude evacuation reliability. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with upstream operations managers, downstream procurement leads at Khartoum-based refineries, power utility planning officers, and petroleum regulator officials; and secondary validation through Sudan Ministry of Energy and Mining licensing disclosures, central bank foreign exchange policy circulars, and regional energy trade databases. Bottom-up field-level production estimates triangulated against top-down sectoral demand projections from grid electrification program documentation.
Forecast inputs incorporated crude output decline curves, refinery throughput constraints, and gas commercialization timelines across the projection horizon. Segmentation dimensions spanned product type, application end-use, technology maturity tier, and state-level demand concentration. CAGRs derived from regression analysis of historical production data against infrastructure investment cycles, with enhanced recovery deployment rates and associated gas capture mandates serving as key model sensitivities.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Asian national oil companies or accelerated licensing reform implementation would shift outcomes. Political transition risk and foreign exchange control volatility represent primary forecast revision triggers. Cross-checking against regional crude export parity pricing and competing East African gas-to-power project timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Underreamers Market
Oil & Gas
Asia-Pacific Oilfield Chemicals Market
Oil & Gas
Global Oil and Gas Analytics Market
Oil & Gas
Russian Federation Oil and Gas Midstream Market
Oil & Gas
Coal Mining Market
Oil & Gas
Drilling Mud Desander and Desilter Market
Oil & Gas
Oil and Gas Digital Rock Analysis Market
Oil & Gas
Norway Oilfield Equipment Rental Services Market
Oil & Gas
Oil & Gas Equipment MRO Market
Oil & Gas
Drilling Bits Market
Oil & Gas
Oil and Gas Midstream Market
Oil & Gas
3D Printing in Oil and Gas Market
Oil & Gas
Digital Twin in Oil and Gas Market
Oil & Gas
Australia Oil and Gas Market
Oil & Gas
North America Completion Equipment and Services Market
Oil & Gas
United States Natural Gas Market