
 Intelligent Completion Sales Market | 2026-2036
Intelligent Completion Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Completion Sales Market Insights
Digital twin integration and IoT-enabled downhole sensors is rewriting field architecture standards for intelligent completion systems. Schlumberger leverages its vertical integration across hardware and cloud platforms to anchor premium positioning in subsea deployments. Halliburton sustains R&D intensity in real-time diagnostics, while Baker Hughes competes through manufacturing scale in North American shale basins.
Intelligent completion systems combine remotely operated downhole valves, pressure-temperature sensors, and surface-controlled flow chokes to optimize hydrocarbon recovery without well intervention. These assemblies typically operate at pressures exceeding 10,000 psi and temperatures above 150°C, enabling zonal management in multilateral wells. Smart Sensors and Automation Tools command the largest share of product revenues as operators prioritize downhole measurement fidelity. Cloud-based and Hybrid deployment models are expanding fastest, driven by edge-to-cloud data pipelines that reduce latency in critical flow decisions.
API specification Q1 for downhole equipment and NORSOK U-001 subsea standards shape product certification requirements across major producing regions. The US Bureau of Safety and Environmental Enforcement mandates real-time monitoring capabilities for deepwater operations in the Gulf of Mexico. Stakeholders must weigh captive software development against platform partnerships as edge analytics becomes the primary battleground for differentiation.
Market Dynamics
Real-time reservoir monitoring is compressing the operational feedback loop between surface control rooms and downhole flow conditions, forcing suppliers to embed edge computing capabilities directly into subsea hardware architectures.
Growth Catalysts
- API Specification Q1:Mandatory downhole equipment certification for Gulf of Mexico deepwater projects accelerates replacement cycles for legacy completion assemblies.
- Subsea tieback expansion:Brazil's pre-salt basin developments require zonal isolation systems capable of managing multilateral well complexity at extreme depths.
- Digital twin platforms:Cloud-based reservoir simulation is pulling demand for sensor-integrated completions that feed live data into predictive models.
Market Restraints
- High-grade alloy supply:Inconel 718 and titanium billet shortages from specialty metallurgy suppliers create 18-24 month procurement lead times for critical downhole components.
- NORSOK U-001 compliance:Norwegian subsea equipment standards impose testing protocols that extend product qualification timelines by 8-14 months versus conventional specifications.
- Subsea installation vessel scarcity:North Sea and West Africa contractor fleets operate at 94% utilization, constraining deployment velocity for intelligent completion systems.
Strategic Opportunities
- Middle East brownfield revitalization:Saudi Aramco's mature field redevelopment programs create retrofit demand for remotely operated inflow control devices in carbonate reservoirs.
- CCS-compatible completions:Carbon capture and storage well architectures require pressure-rated smart packers capable of monitoring CO2 plume migration over decades.
- Geothermal crossover applications:High-temperature downhole sensors developed for hydrocarbon extraction are migrating into enhanced geothermal system deployments in Nevada and Turkey.
Industry Challenges
- Cross-disciplinary engineering talent:Petroleum engineers with firmware development competency remain scarce, slowing product teams integrating mechanical valve systems with embedded analytics.
- Legacy SCADA integration:Brownfield installations in the North Sea require protocol translation layers between proprietary 1990s surface control systems and modern IP-based downhole networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Completion Sales Market |
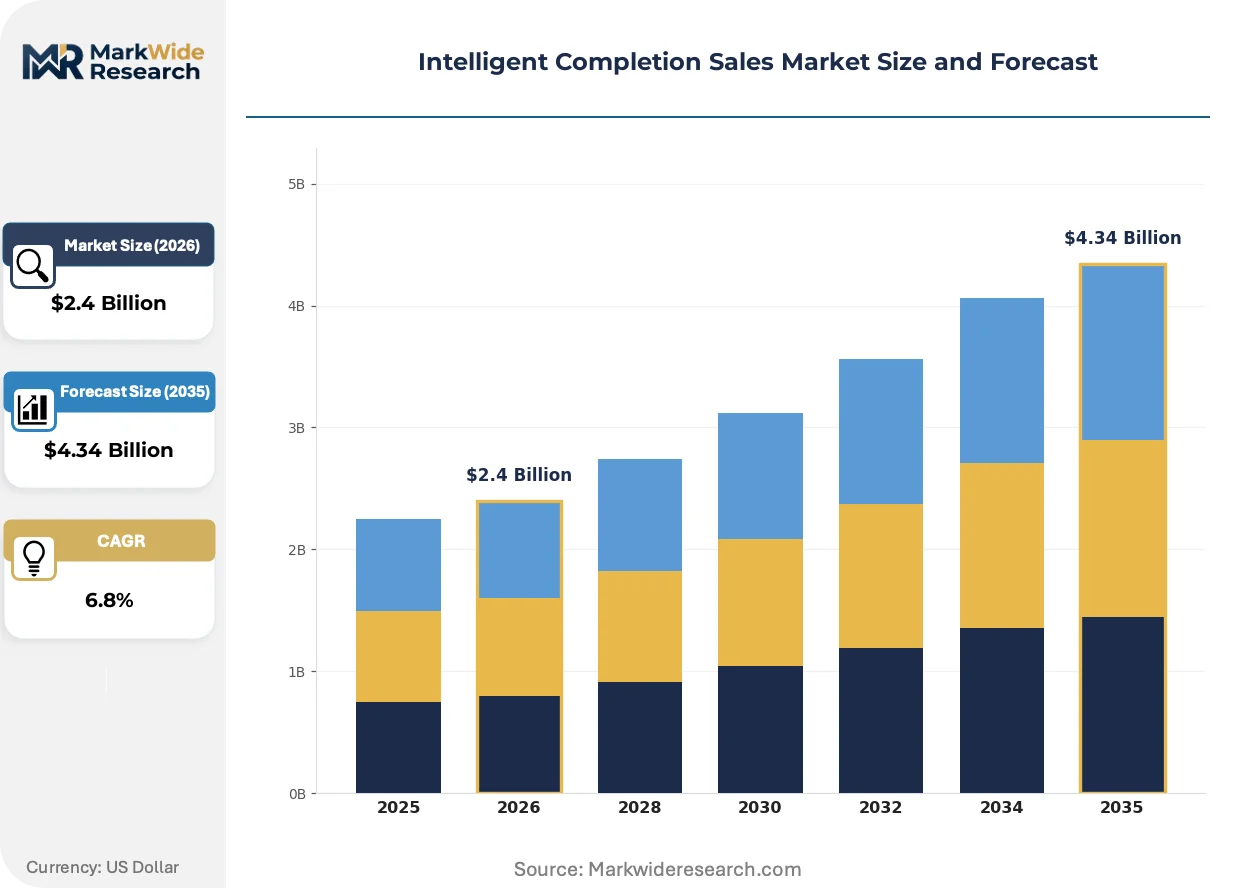
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Sensors, Automation Tools, Software Platforms, Data Analytics Deployment Model: On-premise, Cloud-based, Hybrid, Edge Computing End User Type: Oil & Gas, Mining, Utilities, Manufacturing Service Type: Consulting, Maintenance, Integration, Training |
| Companies Covered | Schlumberger, Halliburton, Baker Hughes, Weatherford, National Oilwell Varco, Omega Well Intervention, Packers Plus Energy Services, Praxis, Tendeka, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Completion Sales Market Trends and Innovations
Intelligent completion architectures are converging around three vectors: sensor miniaturization at extreme pressures, autonomous valve actuation without hydraulic umbilicals, and predictive maintenance algorithms trained on decade-long well performance datasets.
Downhole fiber-optic pressure-temperature sensing is migrating from discrete measurement points to continuous distributed monitoring along entire laterals. Permian Basin operators are retrofitting existing wells with fiber-enabled completions to eliminate production logging runs. This distributed architecture is compressing the total cost of reservoir surveillance by eliminating repeated wireline interventions.
The US Bureau of Safety and Environmental Enforcement now mandates real-time annular pressure monitoring for all subsea completions in water depths exceeding 400 meters. This regulatory shift forces suppliers to certify dual-redundant sensor configurations and automated surface shut-in protocols. Gulf of Mexico project teams are responding by specifying intelligent completions with integrated safety instrumented systems from initial procurement.
Integrated service contracting is displacing component-level purchasing for deepwater developments. Brazilian pre-salt operators now procure full intelligent completion systems bundled with installation, commissioning, and 10-year performance guarantees. This model concentrates supplier risk but locks in long-term aftermarket revenue streams for technology providers with local service infrastructure.
Intelligent Completion Sales Market Segmentation
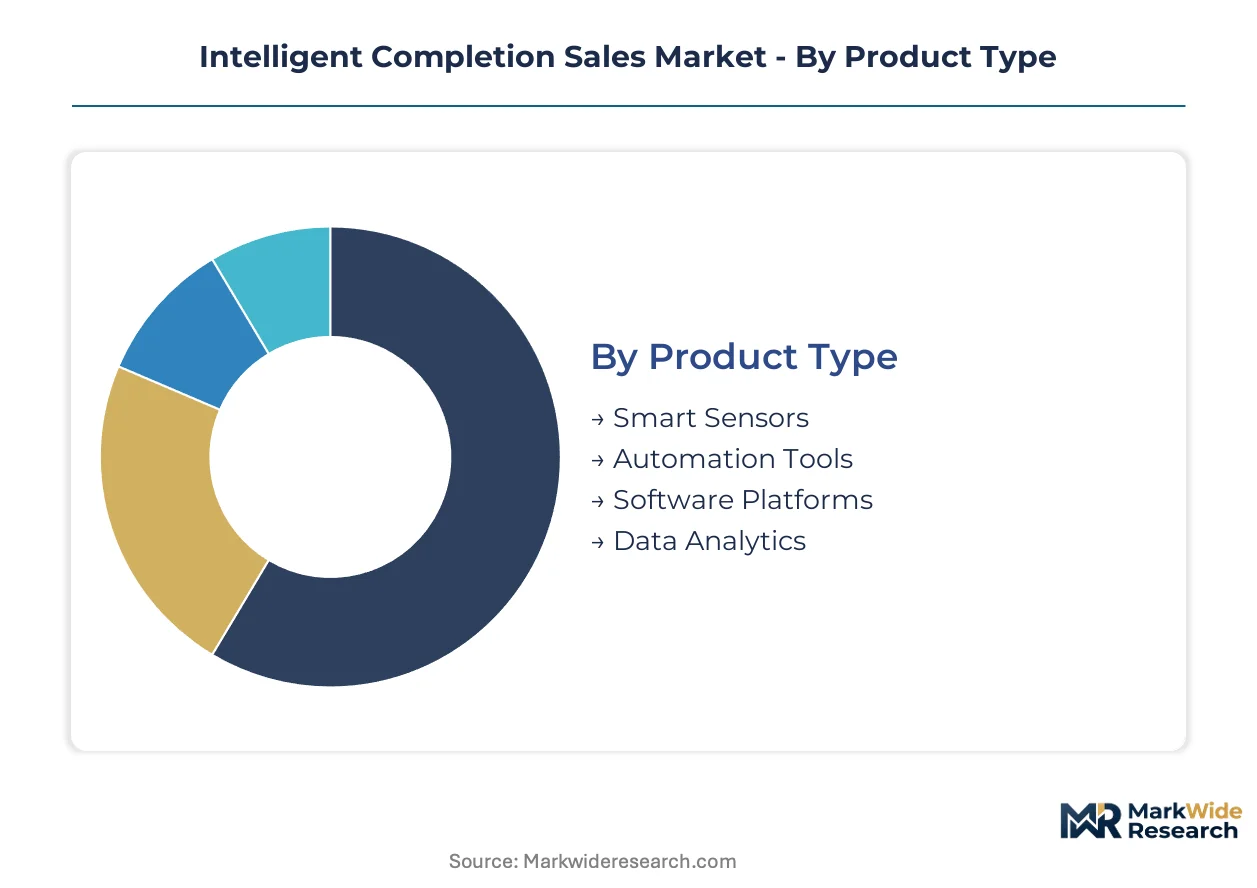
Intelligent completion architectures vary dramatically across operational contexts, from deepwater subsea tiebacks requiring extreme-pressure hardware to brownfield retrofits demanding protocol translation layers. Segment boundaries reflect divergent procurement patterns between integrated service contracts and component-level purchasing, with deployment complexity driving distinct margin structures across each category.
Product Type:
Upstream operators deploy these technologies across a spectrum from discrete measurement points to fully autonomous zonal control systems.
- Smart Sensors:Fiber-optic and electronic pressure-temperature transducers operate above 150°C and 10,000 psi, feeding real-time data into surface control rooms. Gulf of Mexico deepwater projects drive procurement volumes as the US Bureau of Safety and Environmental Enforcement mandates dual-redundant annular pressure monitoring for subsea completions below 400 meters.
- Automation Tools:Remotely operated downhole valves and surface-controlled flow chokes enable zonal isolation without well intervention. Brazil's pre-salt basin developments concentrate demand for multilateral well complexity management at extreme depths.
- Software Platforms:Cloud-based reservoir simulation engines integrate live downhole feeds into predictive maintenance algorithms.
- Data Analytics:Edge computing modules embedded directly into subsea hardware compress latency for critical flow decisions.
Established volume favors Smart Sensors; emerging adoption favors Data Analytics.
Deployment Model:
Architecture choices reflect latency requirements, data sovereignty constraints, and the availability of subsea fiber infrastructure.
- Cloud-based:Reservoir simulation platforms aggregate decade-long well performance datasets to train predictive maintenance algorithms. Norwegian operators under NORSOK U-001 standards favor this model for centralized asset management across the North Sea.
- Hybrid:Edge-to-cloud pipelines process time-sensitive flow decisions locally while archiving historical data remotely. This architecture is expanding most quickly as subsea tieback projects require both real-time responsiveness and long-term analytics retention.
- On-premise:Legacy SCADA integration in mature North Sea fields demands localized control systems.
- Edge Computing:Autonomous valve actuation without hydraulic umbilicals depends on embedded processing power at the wellhead.
Legacy infrastructure locks in On-premise; capital commitments favor Hybrid architectures.
End User Type:
Customer engineering specifications diverge sharply between hydrocarbon extraction and adjacent resource industries.
- Oil & Gas:Subsea completions, multilateral wells, and zonal isolation systems dominate procurement volumes. Deepwater developments in the US Gulf of Mexico and Brazil's pre-salt basin anchor hardware demand for extreme-pressure, high-temperature assemblies.
- Mining:Inflow control devices adapt to slurry flow management in hard-rock extraction.
- Utilities:Carbon capture and storage well architectures require pressure-rated smart packers for CO2 plume monitoring.
- Manufacturing:Geothermal crossover applications in Nevada and Turkey repurpose high-temperature downhole sensors for enhanced geothermal systems.
Upstream hydrocarbon investment concentrates in Oil & Gas; energy transition capital flows toward Utilities.
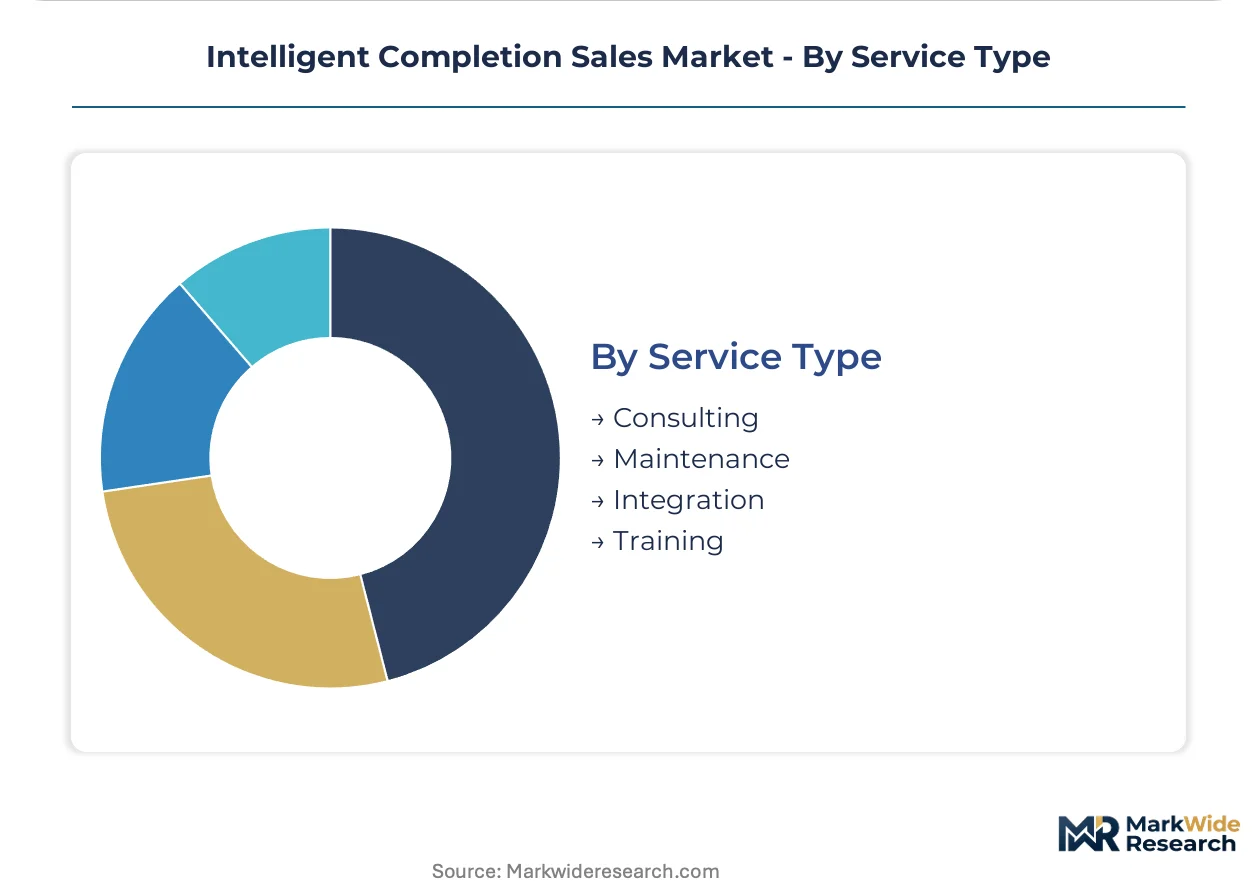
Service Type:
Procurement models shift from component sales toward integrated performance guarantees spanning installation through decade-long operation.
- Integration:Protocol translation layers bridge proprietary 1990s surface control systems with modern IP-based downhole networks in brownfield retrofits. North Sea operators specifically require this capability for legacy SCADA interoperability.
- Maintenance:Long-term service contracts lock in aftermarket revenue through 10-year performance guarantees bundled with initial system procurement.
- Consulting:Petroleum engineers with firmware development competency advise on mechanical-electrical system convergence.
- Training:Cross-disciplinary skill development addresses scarcity of talent combining reservoir engineering with embedded analytics.
Integrated contracting elevates Integration services; talent scarcity sustains Training demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Intelligent completion hardware flows predominantly from US Gulf Coast fabrication yards to deepwater projects offshore Brazil and West Africa. Norwegian engineering houses export subsea control systems to North Sea operators under stringent NORSOK certification regimes. Chinese manufacturers are scaling capacity for Middle East brownfield retrofit programs.
United States
Deepwater developments in the Gulf of Mexico drive procurement of extreme-pressure zonal isolation systems. The Bureau of Safety and Environmental Enforcement mandates real-time annular pressure monitoring for all subsea completions below 400 meters water depth. Houston anchors the largest concentration of intelligent completion engineering and fabrication capacity serving Atlantic Basin projects.
Brazil
Pre-salt basin multilateral wells require automation tools capable of managing reservoir complexity at 2,000+ meter depths. ANP regulatory frameworks mandate local content thresholds that shape supplier qualification processes. Rio de Janeiro hosts integrated service contracting headquarters bundling installation with decade-long performance guarantees.
Norway
North Sea brownfield retrofits demand protocol translation layers bridging legacy SCADA with modern IP-based downhole networks. NORSOK U-001 subsea equipment standards extend product qualification timelines versus conventional specifications. Stavanger concentrates engineering talent for cross-disciplinary petroleum-firmware system integration.
Saudi Arabia
Mature carbonate reservoir redevelopment programs create demand for remotely operated inflow control devices. The national oil company prioritizes local manufacturing partnerships under Vision 2030 industrialization targets. Dhahran serves as the procurement hub for intelligent completion systems across Arabian Peninsula brownfield assets.
United Kingdom
Decommissioning timelines and remaining field life economics favor retrofit over greenfield intelligent completion deployment. HSE offshore safety regulations influence sensor redundancy specifications for North Sea subsea installations. Aberdeen maintains service infrastructure for integrated contracting models spanning installation through long-term operation.
Intelligent Completion Sales Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Vertically integrated energy service conglomerates anchor premium positioning through captive hardware and software platforms. Mid-scale engineering specialists concentrate on regional certification expertise and local service infrastructure. Competitive moves center on integrated performance contracting bundling installation with multi-year aftermarket commitments, alongside edge analytics partnerships that embed predictive algorithms directly into subsea hardware.
Among US-based energy service providers, Schlumberger, Halliburton, and Baker Hughes occupy positions representing distinct strategic archetypes. Schlumberger exemplifies vertical integration spanning downhole hardware through cloud-based reservoir simulation platforms. Halliburton anchors real-time diagnostics specialization with sustained R&D intensity in sensor-integrated flow control. Baker Hughes represents manufacturing scale advantages serving high-volume North American shale basin requirements. These three entities collectively illustrate how channel control, technology specialization, and production scale define competitive positioning in intelligent completion markets.
| Leading Market Players |
|---|
| Schlumberger |
| Halliburton |
| Baker Hughes |
| Weatherford |
| National Oilwell Varco |
| Omega Well Intervention |
| Packers Plus Energy Services |
| Praxis |
| Tendeka |
| Others |
Pricing and Supply Chain Analysis
Inconel 718 and titanium billet shortages from US, German, and Japanese specialty metallurgy suppliers concentrate upstream margin capture, forcing completion system assemblers to absorb 18-24 month procurement lead times or pass alloy premiums through to deepwater project budgets.
Pricing Analysis
Next-generation fiber-optic distributed sensing systems command 40-60% premiums over discrete electronic pressure-temperature transducers, while prior-generation hydraulic valve actuation assemblies face accelerating price erosion. Project-based contracting with 10-year performance guarantees dominates deepwater procurement, with price differentiation anchored in NORSOK U-001 certification tier and local content compliance thresholds. Cost compression in standard-grade onshore shale completions is intensifying as Baker Hughes and Weatherford compete on manufacturing scale. National oil companies in the Middle East exhibit highest price sensitivity, prioritizing brownfield retrofit economics over premium sensor fidelity.
Supply Chain Analysis
US export controls on advanced downhole fiber-optic sensing technology limit flows to Chinese manufacturers, constraining Middle East brownfield retrofit programs. Component fabrication concentrates in the United States, Norway, and China, with subsea control module assembly drawing from Singaporean and UK engineering hubs. Critical dependencies include high-grade nickel superalloys, hermetic feedthrough connectors, and sapphire pressure transducer substrates. Single-source vulnerability in subsea installation vessel fleets—operating at 94% utilization in the North Sea and West Africa—creates deployment bottlenecks. Distribution runs through integrated service contractors bundling hardware with commissioning and long-term aftermarket commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Intelligent completion markets reward service-attach models where predictive maintenance software subscriptions and 10-year performance guarantees expand recurring revenue faster than capital equipment sales.
For Market Incumbents: Entrench position through captive edge analytics development and exclusive partnerships with subsea installation vessel operators. Schlumberger's vertical integration across hardware and cloud platforms demonstrates how controlling both sensor manufacturing and reservoir simulation software raises switching costs. Incumbents must defend against emerging specialists in CCS-compatible smart packer technology by accelerating certification investment under evolving carbon storage regulations. For New Entrants and Emerging Players: Middle East brownfield revitalization programs in mature carbonate reservoirs represent the most penetrable entry point, with Saudi Aramco's local manufacturing partnerships under Vision 2030 creating qualification pathways for regional engineering specialists. Geothermal crossover applications in Nevada and Turkey offer second-mover advantage in repurposing hydrocarbon-hardened sensors for enhanced geothermal systems. New entrants should pursue joint development agreements with national oil companies seeking to diversify supplier bases beyond integrated service conglomerates. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale engineering specialists with NORSOK U-001 certification expertise and established local service infrastructure in Brazil or Norway. Long-term viability across the analysis window hinges on exposure to subsea tieback expansion rather than North American shale cyclicality. The signal to watch is ANP local content threshold adjustments, which would force integrated contractors to acquire Brazilian engineering capabilities rather than qualify new entrants organically.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Performance Contracting | Bundling installation with decade-long guarantees locks in aftermarket revenue streams for technology providers. |
| Edge Analytics Partnership | Embedding predictive algorithms directly into subsea hardware compresses latency for critical flow decisions. |
| CCS-Compatible Product Line | Pressure-rated smart packers for CO2 plume monitoring capture energy transition capital flows into carbon storage. |
| Local Content Qualification | Brazilian ANP thresholds and Saudi Vision 2030 targets mandate regional engineering presence for project access. |
| Fiber-Optic Sensing Scale-Up | Distributed pressure-temperature monitoring along entire laterals eliminates repeated wireline intervention costs. |
Research Methodology
Desk research of regulatory filings from the US Bureau of Safety and Environmental Enforcement, ANP local content directives, and NORSOK U-001 technical specifications preceded structured interviews with subsea project engineers, intelligent completion product managers, procurement officers at national oil companies, and aftermarket service directors. Secondary validation drew from customs trade data for high-grade alloy imports, offshore project development databases, and SEC filings from publicly traded energy service providers. Bottom-up segment sizing triangulated against top-down expenditure forecasts from reservoir simulation platform disclosures.
Assumptions held fixed include current regulatory mandates for real-time annular pressure monitoring in Gulf of Mexico deepwater and prevailing NORSOK certification timelines; variables tested include subsea installation vessel availability, Inconel 718 supply elasticity, and national oil company local content enforcement intensity. The analytical framework modeled product type, deployment model, end user industry, and service type dimensions across the projection horizon. CAGRs derived from historical intelligent completion procurement patterns and disclosed capital expenditure plans for pre-salt and Gulf of Mexico developments.
Macroeconomic conditions sit as an overlay; deviation in Brent crude price trajectories, offshore drilling rig dayrates, or carbon credit pricing mechanisms would shift the trajectory. Material shifts in US export control scope for downhole sensing technology or ANP local content threshold adjustments would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Rotary Steerable System Market
Oil & Gas
Logging While Drilling (LWD) Market
Oil & Gas
Oil and Gas Downhole Vibration Monitoring and Control System Market
Oil & Gas
Oil and Gas Well Conductor Installation Services Market
Oil & Gas
Oil and Gas Refinery Maintenance Services Market
Oil & Gas
Asia-Pacific Digital Oilfield Market
Oil & Gas
North America Digital Oilfield Market
Oil & Gas
Subsea Well Intervention Market
Oil & Gas
Copper Mining Market
Oil & Gas
East Africa Oil and Gas Market
Oil & Gas
Modular Refinery Market
Oil & Gas
Well Cementing Market
Oil & Gas
Middle East and Africa Digital Oilfield Market
Oil & Gas
Global Oilfield Stimulation Chemicals Market
Oil & Gas
Sucker Rod Market
Oil & Gas
Connected Oil and Gas Market