
 Urinary Bag Market | 2026-2036
Urinary Bag Market Size, Share, and Industry Trends Forecast 2026-2036
Urinary Bag Market Analytics
Silicone is broadening its addressable share as manufacturers phase out natural latex to mitigate allergy risks and extend wear-time economics. Coloplast A/S anchors Scandinavian production capacity for premium silicone leg bags. Cardinal Health leverages hospital distributor relationships to secure contract volume across integrated delivery networks. Hollister Incorporated specializes in hydrocolloid-adhesion interfaces that reduce peristomal complications in extended-use applications.
A urinary bag is a closed-collection reservoir, typically fabricated from PVC, silicone, or ethylene vinyl acetate film, with a nominal capacity between 350 mL and 2,000 mL and an anti-reflux valve to prevent retrograde contamination; its primary function is to store and meter urine output from indwelling or external catheters in acute and chronic care settings. Leg bags occupy the highest-margin tier due to ambulatory-patient premium pricing and repeat-purchase frequency. Homecare end users represent the fastest-expanding demand pool as reimbursement shifts favor community-based catheter management over institutional stays.
The FDA enforces biocompatibility and sterility standards under 21 CFR Part 820 quality-system regulations, while the EU Medical Device Regulation mandates clinical-evaluation documentation and unique device identification for Class IIa collection devices. ISO 10993 cytotoxicity testing shapes material-selection decisions across both jurisdictions, effectively filtering PVC formulations with high plasticizer migration profiles. Stakeholders must monitor reimbursement-coding revisions for intermittent catheterization supplies, as payor bundling decisions will determine whether standalone urinary bag claims retain separate payment status.
Market Dynamics
Reimbursement migration from inpatient to outpatient settings is compressing hospital purchasing cycles while amplifying durable medical equipment procurement through home medical equipment distributors. This structural shift forces manufacturers to reconfigure channel economics around Medicare Part B billing codes rather than institutional procurement frameworks.
Growth Catalysts
- ISO 10993 biocompatibility mandates:Cytotoxicity testing requirements under FDA and EU MDR frameworks are accelerating silicone formulation adoption and phasing out high-plasticizer PVC alternatives across Class IIa collection devices.
- Home medical equipment distributors:Medicare reimbursement for intermittent catheterization supplies is pulling volume through specialized durable medical equipment channels serving community-based patient management.
- Aging population outpatient preference:Demographic pressure across OECD markets is shifting catheter management from acute facilities toward ambulatory and residential care settings.
Market Restraints
- Medical-grade silicone supply concentration:Specialty elastomer production clusters in Germany and Japan create input vulnerability for manufacturers dependent on platinum-catalyzed formulations.
- EU MDR clinical evaluation documentation:Extended conformity assessment timelines for Class IIa devices are delaying market entry and freezing product line extensions.
- Reusable external catheter systems:Silicone sheath alternatives with multi-day wear cycles threaten single-use leg bag attachment frequency in select ambulatory patient segments.
Strategic Opportunities
- India's PLI scheme for medical devices:Production-linked incentive structures for domestic manufacturing create tariff-advantaged export capacity targeting Middle East and Southeast Asian markets.
- Telehealth-integrated remote monitoring:Convergence of Bluetooth-enabled volume sensors with urinary collection systems enables reimbursement capture under remote patient monitoring CPT codes.
- Direct-to-patient subscription models:E-commerce platforms bypassing traditional durable medical equipment intermediaries are capturing cash-pay segments in Australia and Canada.
Industry Challenges
- Polymer formulation chemist scarcity:Specialized expertise in platinum-cured silicone rheology and plasticizer-free PVC stabilization is concentrated among aging technical workforces in the United States and Germany.
- Unique device identification serialization:EU MDR and FDA UDI implementation requires capital-intensive labeling infrastructure and database integration that mid-tier manufacturers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urinary Bag Market |
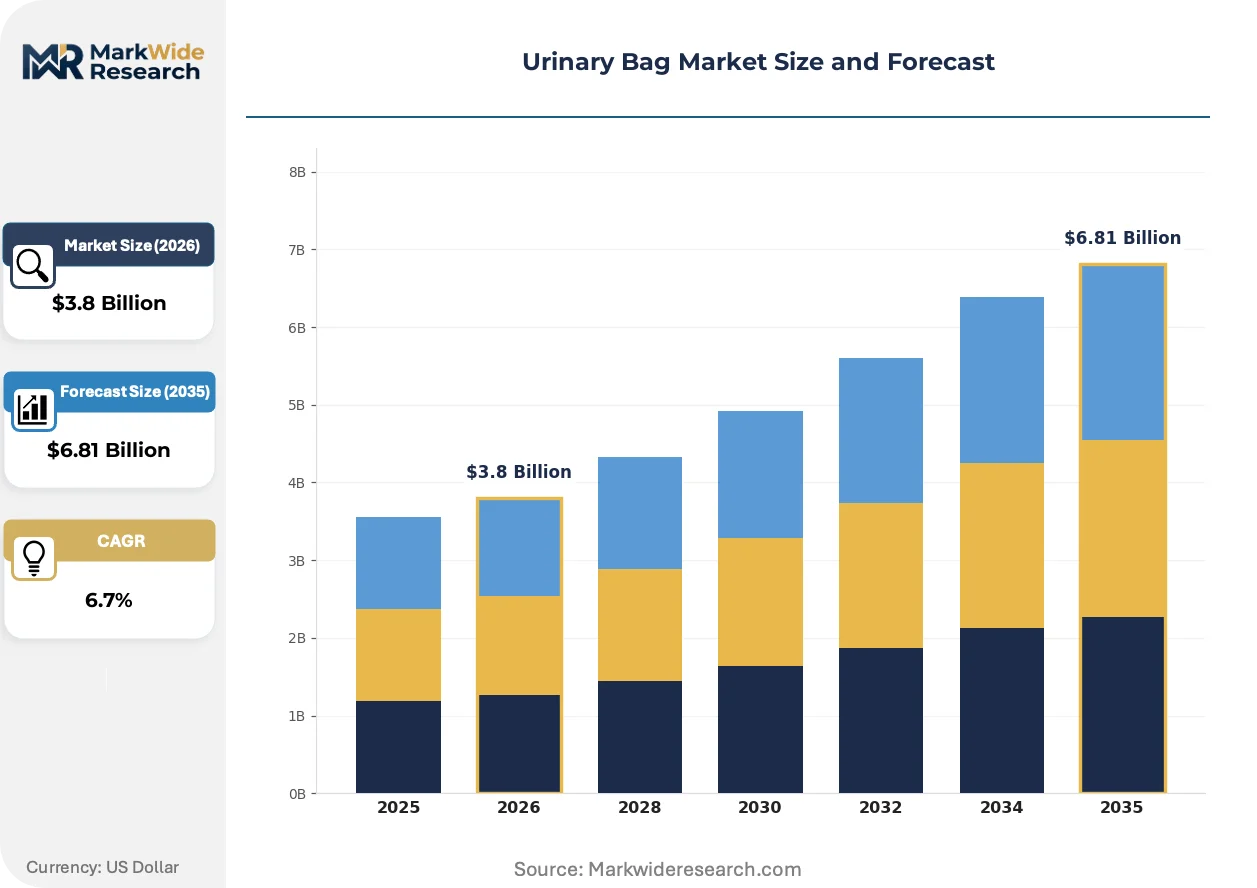
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Bags, Leg Bags, Night Bags, Catheter Bags Material: Latex, PVC, Silicone, Ethylene Vinyl Acetate End User: Hospitals, Homecare, Nursing Facilities, Outpatient Clinics Distribution Channel: Online Retail, Pharmacies, Medical Supply Stores, Hospital Distributors |
| Companies Covered | ConvaTec Group PLC, Coloplast A/S, Cardinal Health, Teleflex Incorporated, Hollister Incorporated, Medline Industries, BD, Flexicare Medical Limited, Manfred Sauer GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urinary Bag Market Evolving Landscape
Material science advances and regulatory harmonization pressures are compressing legacy formulation timelines while opening premium positioning for biocompatible alternatives. Channel digitization and remote monitoring integration are redefining value capture beyond the physical device.
Platinum-cured silicone elastomers are electrifying extended-wear catheter system design by enabling 7-day wear cycles without material degradation. Homecare patients and spinal cord injury rehabilitation centers are adopting these formulations at accelerated rates. This technology is electrifying margin structures by reducing replacement frequency while commanding 40-60% price premiums over standard PVC alternatives.
EU MDR Class IIa clinical evaluation requirements are forcing manufacturers to generate post-market surveillance data for legacy collection devices previously grandfathered under the Medical Device Directive. The industrial consequence is documentation backlogs and notified body bottlenecks extending conformity timelines by 12-18 months. Leg bag manufacturers with established quality management systems under ISO 13485 are absorbing compliance costs more readily than smaller competitors, consolidating supply-side concentration.
Hospital procurement committees are unbundling urinary collection systems from catheter kits to optimize formulary flexibility and reduce waste from mismatched component sizing. Integrated delivery networks in the United States are replacing bundled contracts with line-item purchasing through specialized urology distributors. This pattern is most visible in Medicare Advantage plan networks where utilization management programs scrutinize component-level spending.
Urinary Bag Market Segmentation
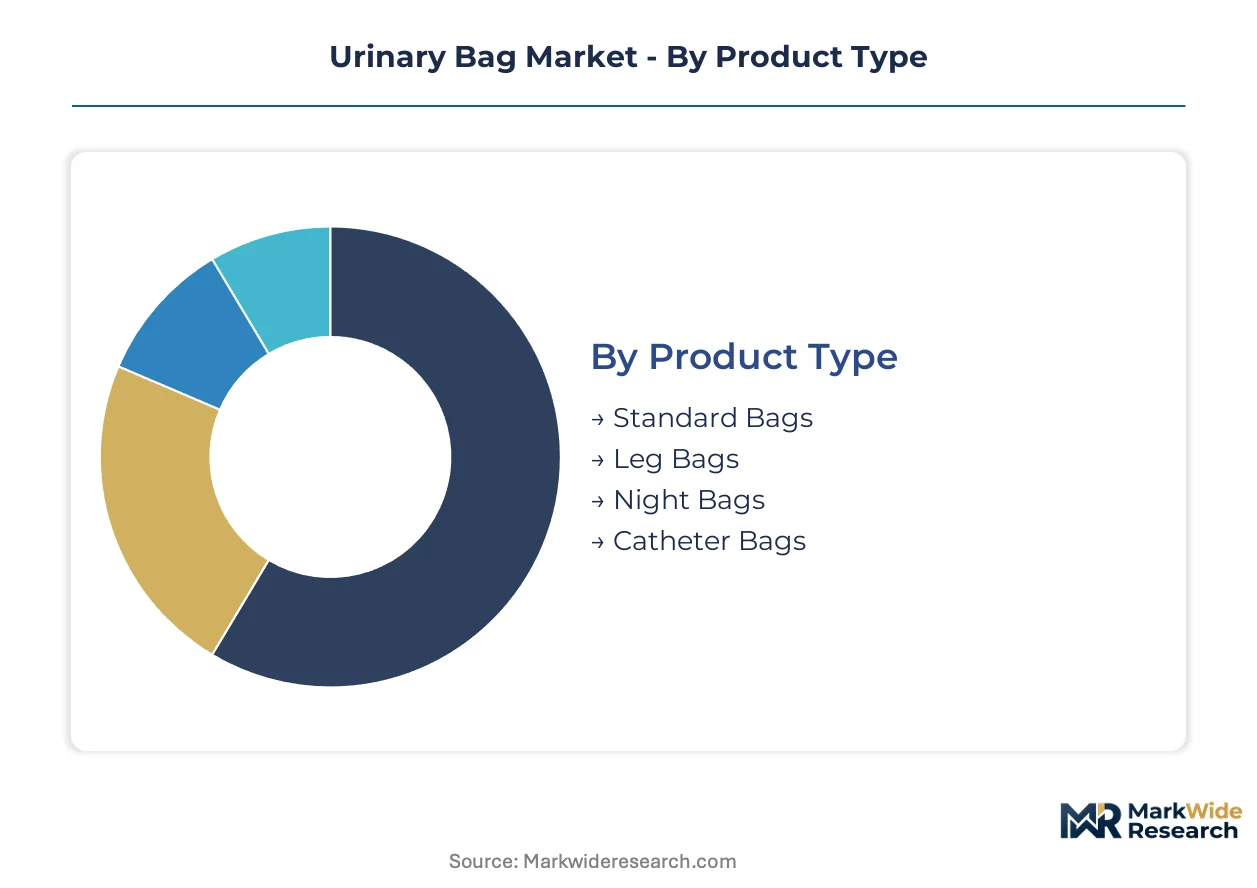
Urinary bag procurement patterns diverge sharply between acute care bulk purchasing and ambulatory premium segments. Manufacturers configure production lines around material biocompatibility tiers and reimbursement channel economics rather than uniform specifications.
Product Type:
Volume concentration sits with bedside drainage systems, while margin capture concentrates in mobile configurations enabling patient mobility.
- Leg Bags:These 350-750 mL capacity reservoirs attach to the thigh or calf via adjustable straps, fabricated from platinum-cured silicone or low-plasticizer PVC with anti-reflux valves. Demand clusters in spinal cord injury rehabilitation centers and Medicare Part B homecare channels where ambulatory independence drives premium pricing. Wear-time economics favor 5-7 day replacement cycles.
- Night Bags:High-volume 2,000 mL reservoirs with extended tubing connect to indwelling catheters for supine drainage. Palliative care hospices and long-term nursing facilities in Germany and Japan specify these for nocturnal output management, reducing caregiver intervention frequency.
- Standard Bags:Bedside collection systems with 1,500-2,000 mL nominal capacity serve acute hospital wards through group purchasing organization contracts.
- Catheter Bags:Specialized reservoirs integrate directly with intermittent catheterization systems for clean technique protocols in outpatient urology clinics.
Mature deployment sits with Standard Bags through established hospital procurement frameworks. Newer deployment is concentrated in Leg Bags as homecare reimbursement expands community-based catheter management.
Material:
Regulatory pressure on plasticizer migration is compressing PVC dominance while elevating silicone positioning in extended-wear applications.
- Silicone:Platinum-cured elastomers deliver 7-day wear cycles without material degradation or allergenic response. ISO 10993 cytotoxicity compliance positions these formulations for FDA Class IIa and EU MDR Class IIa device classifications. Spinal cord injury patients and homecare settings in the United States absorb 40-60% price premiums for reduced replacement frequency.
- PVC:Plasticized polyvinyl chloride dominates hospital bulk purchasing through cost-minimization protocols, though DEHP and DINP plasticizer restrictions under REACH and state-level US prohibitions are narrowing addressable applications.
- Latex:Natural rubber formulations persist in emerging market price-sensitive segments despite Type I hypersensitivity liability.
- Ethylene Vinyl Acetate:Copolymer films offer intermediate flexibility and clarity for single-use drainage systems in cost-constrained institutional settings.
Material transition concentrates in Silicone as biocompatibility mandates harden. Latex retains residual positioning only where allergy screening infrastructure remains underdeveloped.
End User:
Reimbursement migration from inpatient to outpatient settings is redistributing volume across channel economics.
- Homecare:Medicare Part B durable medical equipment billing and equivalent national health service provisions in France and Australia are pulling catheter management into residential settings. Patients with neurogenic bladder dysfunction and post-prostatectomy recovery represent concentrated demand pools.
- Hospitals:Acute care facilities remain volume anchors through emergency department admission protocols and surgical recovery units, though length-of-stay compression is constraining per-patient consumption.
- Nursing Facilities:Long-term care institutions in Japan and Germany manage chronic catheter populations through formulary contracts with specialized urology distributors.
- Outpatient Clinics:Ambulatory surgery centers and urology practices handle intermittent catheterization training and supply dispensing under bundled payment models.
Homecare represents the steepest expansion trajectory as aging demographics and reimbursement policy converge. Hospital volume is plateauing under utilization management pressure.
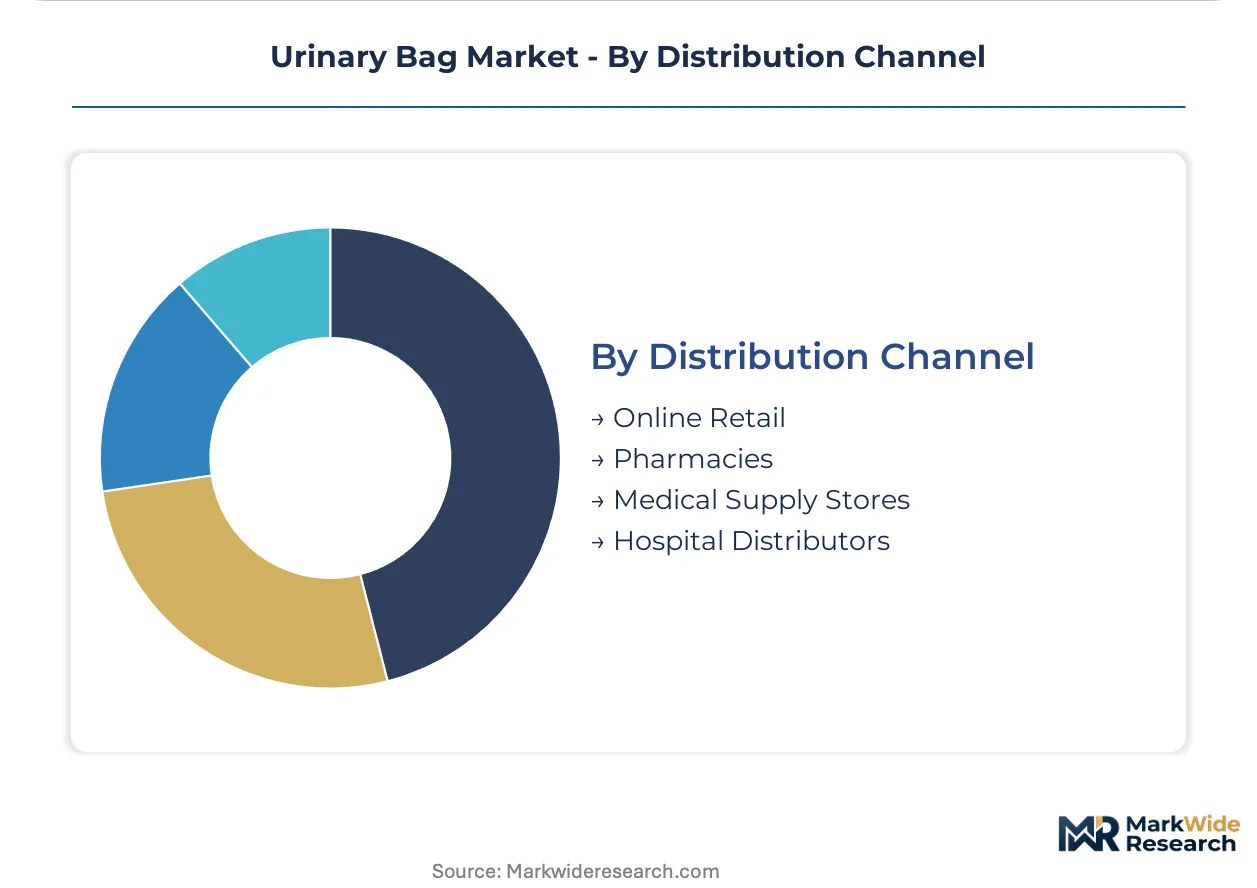
Distribution Channel:
Channel bifurcation separates institutional procurement from patient-direct fulfillment.
- Hospital Distributors:Cardinal Health and McKesson contract with integrated delivery networks for formulary-managed bulk supply, capturing acute care volume through line-item purchasing unbundled from catheter kits.
- Medical Supply Stores:Specialized durable medical equipment retailers in Australia and Canada serve walk-in patients with cash-pay and private insurance transactions.
- Pharmacies:Community pharmacy chains in France and Germany dispense reimbursed supplies through national health service protocols.
- Online Retail:Direct-to-patient subscription platforms bypass traditional intermediaries, capturing recurring revenue in cash-pay segments with automated replenishment algorithms.
Established procurement runs through Hospital Distributors. Channel experimentation concentrates in Online Retail as patient self-management autonomy expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for urinary bags concentrates in aging OECD markets where homecare reimbursement infrastructure is mature. Medicare Part B in the United States and national health service provisions in Western Europe pull catheter management into residential settings. Emerging markets in Asia and the Middle East are building institutional procurement frameworks.
United States
Spinal cord injury rehabilitation centers and post-prostatectomy patients drive leg bag consumption through Medicare Part B durable medical equipment billing. FDA enforcement of ISO 10993 biocompatibility standards under 21 CFR Part 820 accelerates silicone formulation adoption. Minnesota and Ohio host concentrated medical device manufacturing clusters supplying integrated delivery networks.
Germany
Long-term nursing facilities and palliative care hospices specify high-volume night bags for nocturnal output management. EU MDR Class IIa clinical evaluation documentation requirements extend conformity assessment timelines for collection devices. Baden-Württemberg and North Rhine-Westphalia anchor specialty elastomer production for platinum-cured silicone formulations.
Japan
Aging demographics and extended life expectancy expand chronic catheter populations in nursing facilities. PMDA alignment with ISO 10993 cytotoxicity testing shapes material-selection decisions for domestic manufacturers. The Kanto region around Tokyo concentrates urology distributor networks serving institutional procurement channels.
India
Price-sensitive institutional demand in tier-2 and tier-3 cities sustains PVC and latex formulation volumes. CDSCO medical device rules and the PLI scheme for domestic manufacturing create tariff-advantaged export capacity. Gujarat and Maharashtra are developing medical device parks targeting Middle East and Southeast Asian markets.
Australia
Community-based catheter management through national health service reimbursement drives homecare segment expansion. TGA conformity assessment requirements for Class IIa devices mirror EU MDR biocompatibility frameworks. New South Wales and Victoria concentrate specialized durable medical equipment retailers serving cash-pay and private insurance segments.
Urinary Bag Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. The market exhibits tiered concentration with premium silicone leg bags dominated by Scandinavian and North American specialists, while bulk PVC bedside systems flow through hospital distributor oligopolies. Two strategic archetypes define competitive positioning: integrated medical device conglomerates leveraging distributor relationships, and focused urology specialists commanding premium pricing through material innovation. M&A activity targets regional distributors with established Medicare billing infrastructure, while capacity expansion concentrates in German and Japanese specialty elastomer clusters.
Among Scandinavian-based specialists, Coloplast A/S anchors premium silicone production capacity for extended-wear applications. Cardinal Health occupies a position at the scale-driven end, leveraging hospital distributor relationships across integrated delivery networks. Hollister Incorporated exemplifies the hydrocolloid-adhesion specialist archetype, with product configurations targeting peristomal complication reduction in extended-use settings.
| Leading Market Players |
|---|
| ConvaTec Group PLC |
| Coloplast A/S |
| Cardinal Health |
| Teleflex Incorporated |
| Hollister Incorporated |
| Medline Industries |
| BD |
| Flexicare Medical Limited |
| Manfred Sauer GmbH |
| Others |
Value Network & Pricing Analysis
Medicare Part B durable medical equipment billing concentration in the United States anchors contract-based pricing for leg bag procurement, locking manufacturers into multi-year formulary agreements with specialized distributors rather than spot-market transactions. This purchasing archetype compresses margin flexibility for mid-tier suppliers while rewarding scale players with volume guarantees.
Pricing Analysis
Volume concentrates in standard PVC bedside systems sold through hospital group purchasing organization contracts, while margin capture clusters in platinum-cured silicone leg bags commanding premium positioning through extended wear-time economics. Price differentiation rests on ISO 10993 biocompatibility certification tier and Medicare reimbursement coding status rather than brand premium alone. Pricing pressure stems from EU MDR conformity assessment cost absorption and plasticizer-free PVC formulation R&D outlays. Homecare patients exhibit lowest price sensitivity for silicone alternatives, while acute care procurement committees drive aggressive cost minimization in bulk PVC purchasing.
Supply Chain Analysis
Specialized polymer chemist availability constrains manufacturing expansion in Germany's Baden-Württemberg cluster and Japan's Kanto region, where platinum-catalyzed silicone expertise concentrates among aging technical workforces. Geographic supply concentration sits with Germany, Japan, and the United States for medical-grade elastomer production. Raw material dependencies draw from platinum catalysts, high-purity silicone monomers, and DEHP-free plasticizer alternatives. Supply chain risk hinges on single-source vulnerability for platinum-catalyzed formulations. Distribution runs through hospital distributor oligopolies and durable medical equipment retailers serving Medicare Part B channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where EU MDR documentation burdens and UDI serialization capital requirements are forcing sub-scale manufacturers toward exit or acquisition. Regulatory compliance cost absorption favors integrated players with established ISO 13485 quality management systems.
For Market Incumbents: Hedge against silicone supply concentration by securing long-term offtake agreements with German and Japanese specialty elastomer producers or cultivating backward integration into platinum-cured formulation capacity. Prioritize reimbursement strategy investment to defend Medicare Part B billing code positioning against payor bundling threats. Channel control through direct-to-patient subscription platforms offers margin defense against distributor compression. For New Entrants and Emerging Players: Durable medical equipment retailers in Australia's New South Wales and Victoria represent the most penetrable channel archetype for cash-pay segment entry. Target India's PLI scheme for tariff-advantaged export capacity serving Middle East and Southeast Asian price-sensitive institutional markets. A telehealth-integrated remote monitoring angle with Bluetooth-enabled volume sensors enables reimbursement capture under remote patient monitoring CPT codes, bypassing entrenched distributor relationships. For Investors and Strategic Acquirers: The window for entry favors mid-tier manufacturers with established EU MDR technical documentation and Medicare billing infrastructure already in place. Long-term viability across the analysis window rests on acquiring targets with quality management system maturity rather than pure capacity scale. The signal to watch is FDA reimbursement coding revisions for intermittent catheterization supplies, where standalone urinary bag claim status loss would trigger sector-wide repricing.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Completion | Accelerates market access for Class IIa collection devices ahead of notified body bottlenecks. |
| Platinum-Cured Silicone Capacity Expansion | Captures extended-wear premium positioning as ISO 10993 compliance hardens material requirements. |
| Direct-to-Patient Subscription Platform Launch | Bypasses durable medical equipment intermediaries in Australia's cash-pay and private insurance segments. |
| Telehealth Remote Monitoring Integration | Enables reimbursement capture under Medicare remote patient monitoring CPT codes. |
| India PLI Scheme Manufacturing Footprint | Creates tariff-advantaged export capacity targeting Middle East and Southeast Asian institutional procurement. |
Research Methodology
FDA 510(k) filings, CMS Medicare reimbursement databases, and EU MDR notified body documentation formed the secondary backbone for market sizing and regulatory trajectory assessment. Primary interviews with hospital purchasing committee members, durable medical equipment distributor contract managers, biomedical engineers specializing in urology devices, and GPO formulary directors validated volume assumptions and pricing dynamics. Bottom-up unit economics triangulated against top-down reimbursement flow analysis to anchor market value estimates.
Historical trendline analysis of Medicare Part B durable medical equipment spending patterns and hospital procurement contract cycles informed the projection framework across the analysis window. Segmentation modeling incorporated product type, material biocompatibility tier, end-use setting, and distribution channel economics. CAGRs derived from regression analysis of reimbursement policy shifts, aging demographic trajectories, and material substitution elasticities. Industry-specific forecast inputs included ISO 10993 testing adoption curves and EU MDR conformity assessment timeline bottlenecks.
Caveats apply where FDA reimbursement coding revisions, platinum catalyst supply disruptions, or EU MDR notified body capacity constraints could materially shift the outlook. Forecasts reflect assumptions regarding Medicare Part B billing code stability and silicone formulation cost curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Nephrology and Urology Incontinence Devices Market
Urology
India Urology Market
Urology
Benign Prostatic Hyperplasia Market
Urology
Renal Cyst Treatment Market
Urology
Urinary Incontinence Market
Urology
Urology Disposables Market
Urology
Ureter Cancer Treatment Market
Urology
Chronic Pyelonephritis Treatment Market
Urology
Uraemia Treatment Market
Urology
Uropathy Treatment Market
Urology
Global Bladder Scanner Market
Urology
Ureterorenoscopes Market
Urology
Nordic Urinary Catheters Market
Urology
Global Nephrology and Urology Devices Market
Urology
Acute Pyelonephritis Treatment Market
Urology
Urinary Incontinence Treatment Drugs Market