
 Cystectomy Market | 2026-2036
Cystectomy Market Size, Share, and Industry Trends Forecast 2026-2036
Cystectomy Market Analysis
Oncology departments within hospital systems is recalibrating capital allocation toward minimally invasive platforms. Intuitive Surgical leverages its installed base of da Vinci systems to sustain recurring instrument revenue across high-volume urology centers. Boston Scientific Corporation competes through integrated energy and visualization portfolios that anchor open and laparoscopic cystectomy workflows. Medtronic navigates the robotic-assisted segment through strategic positioning of its Hugo platform in European and select Asian markets.
Cystectomy denotes surgical removal of part or all of the urinary bladder, typically performed under general anesthesia with operative durations ranging from four to eight hours depending on technique complexity and need for urinary diversion reconstruction. The procedure serves definitive treatment for muscle-invasive bladder cancer and end-stage benign bladder conditions. Robotic-assisted surgery commands premium capital expenditure but captures favorable margin pools through disposable instrument cycles and service contracts, while open surgery retains dominance in emergent cases and resource-constrained settings. Ambulatory surgical centers represent the fastest-growing end user channel as payers push same-day discharge protocols and site-of-care economics shift.
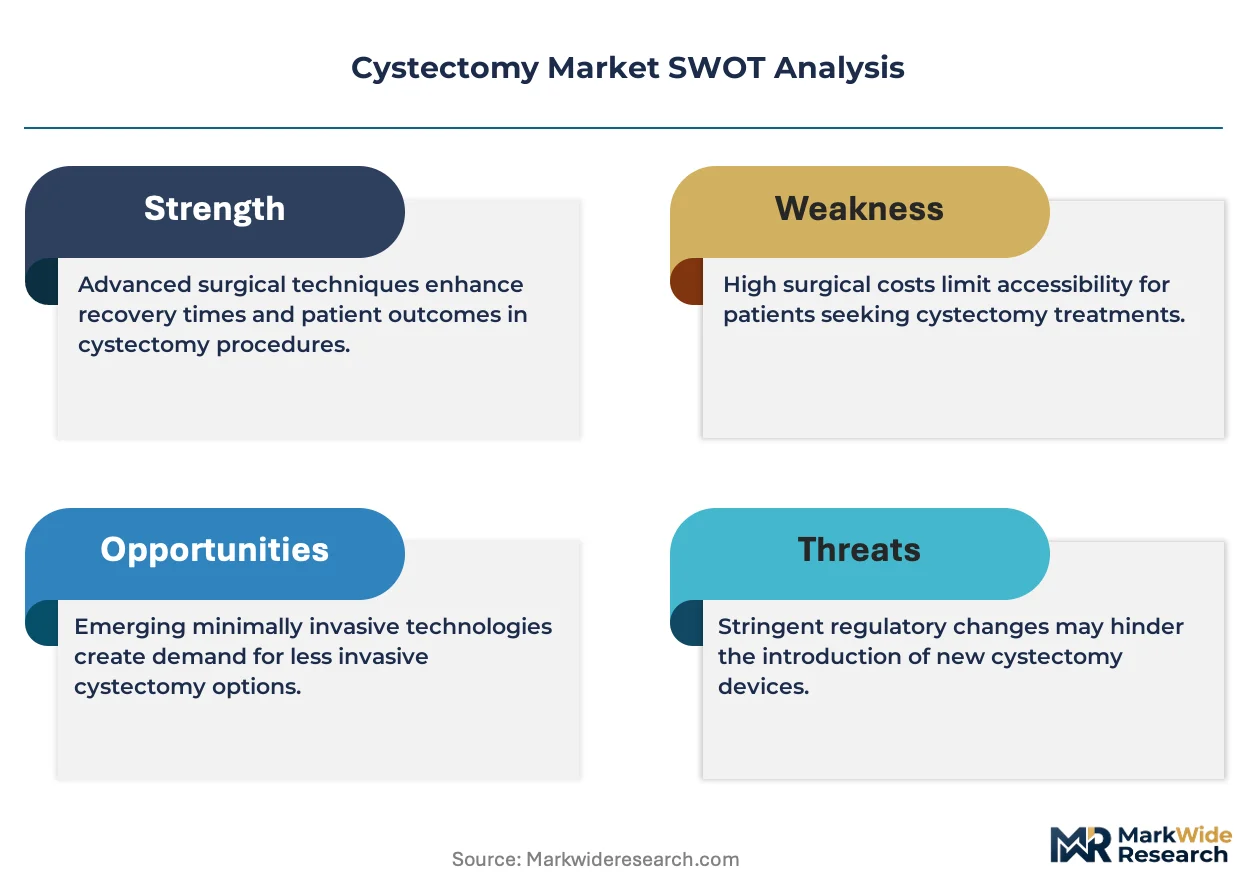
FDA 510(k) premarket notification and EU MDR technical documentation requirements impose substantial clinical validation burdens on novel cystectomy devices, particularly robotic platforms seeking equivalence claims. Japan's PMDA and Germany's BfArM enforce additional country-specific quality management audits that delay market entry for non-established manufacturers. Stakeholders must monitor reimbursement parity between robotic and conventional techniques across public and private payer systems, as coverage decisions will determine adoption velocity irrespective of technical superiority claims.
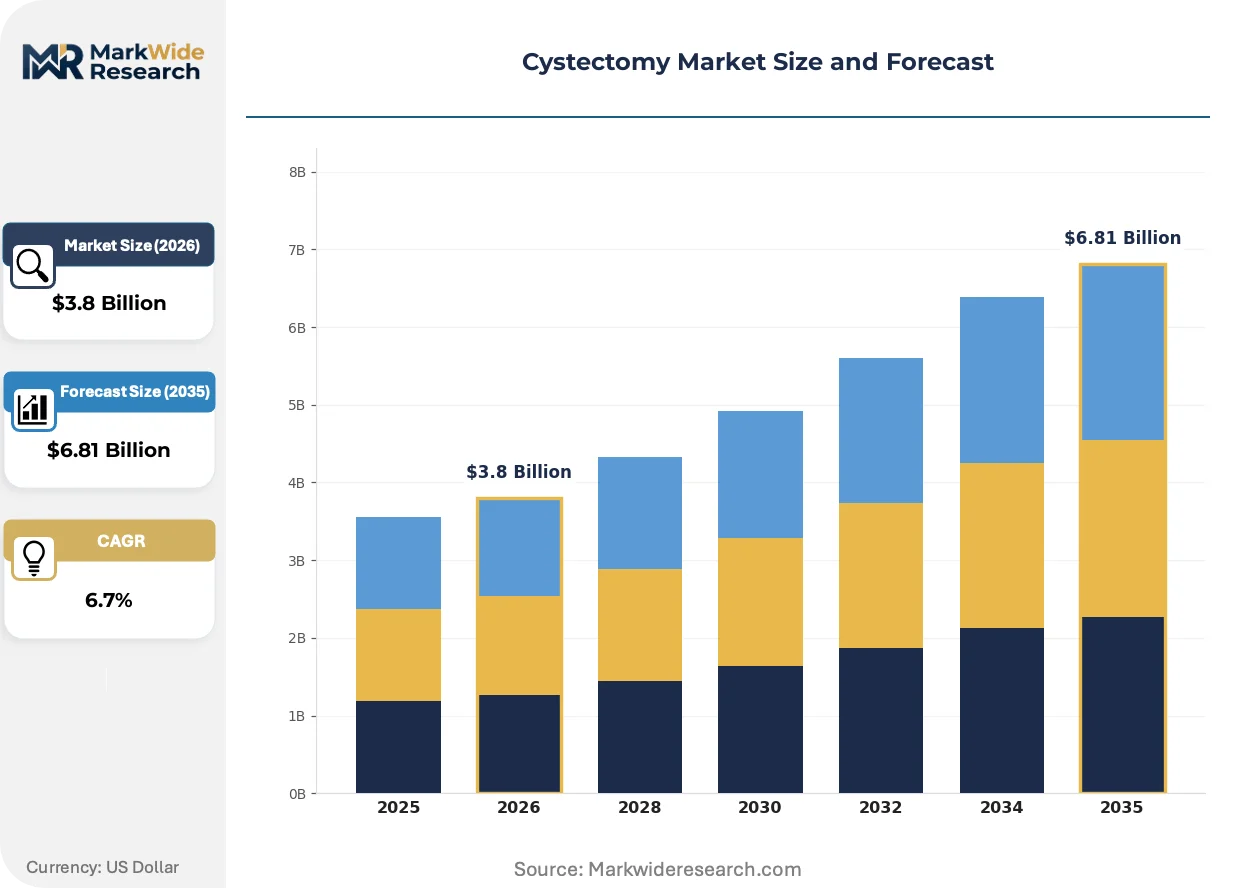
Market Dynamics
Robotic-assisted surgical platforms are compressing operative timelines while expanding the addressable patient pool for minimally invasive bladder removal, forcing capital equipment cycles and training infrastructure to synchronize across hospital systems.
Growth Catalysts
- EU MDR conformity pathways:Streamlined technical documentation for established predicate devices accelerates clearance timelines for next-generation robotic platforms in European urology centers.
- Ambulatory surgical centers:Payer-mandated same-day discharge protocols in the United States are expanding procedure volumes outside traditional hospital settings.
- Fluorescence-guided imaging:Near-infrared visualization technologies enhance oncologic margin assessment during nerve-sparing cystectomy procedures.
Market Restraints
- Capital intensity:Robotic system acquisition costs exceed $2 million per installation, constraining penetration in publicly funded healthcare systems.
- Supply concentration:Single-source dependence for proprietary instrument cartridges creates procurement vulnerability for high-volume academic medical centers.
- Technical limitation:Current platforms lack haptic feedback mechanisms critical for delicate ureteral dissection in salvage cystectomy cases.
Strategic Opportunities
- Japan's aging demographics:PMDA fast-track designations for cancer surgery devices open pathways for robotic platform manufacturers in an underpenetrated market.
- Telepresence surgery:5G-enabled remote proctoring converges with cloud-based analytics to extend specialist expertise to community hospitals.
- India's PLI scheme:Domestic production incentives for medical devices reduce import duty burdens and localize service infrastructure.
Industry Challenges
- Surgeon training pipelines:Proctored case volume requirements for robotic certification create bottlenecks as residency programs retool curricula.
- Integration complexity:Legacy electronic health record systems resist seamless data capture from robotic console analytics modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cystectomy Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Surgery, Laparoscopic Surgery, Robotic-Assisted Surgery, Transurethral Resection End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Institutions Indication: Bladder Cancer, Bladder Dysfunction, Neurogenic Bladder, Inflammation Technique: Partial Cystectomy, Radical Cystectomy, Urinary Diversion Procedures, Bladder Augmentation |
| Companies Covered | Intuitive Surgical, Boston Scientific Corporation, Medtronic, Zimmer Biomet, Zephyr Surgical Implants, Richard Wolf GmbH, Titan Medical USA Inc., TransEnterix Surgical, Inc., Asensus Surgical US, Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cystectomy Market Emerging Trajectories
Surgical robotics, intraoperative imaging, and care delivery models are converging to redefine where and how cystectomy procedures are performed. These shifts are compressing recovery timelines while redistributing economic value across the care continuum.
Single-port robotic platforms are modularizing the physical footprint required for radical cystectomy, enabling deployment in smaller operating suites previously unsuitable for multi-arm systems. Community hospitals in Germany and Japan are piloting these compact configurations to retain complex urology cases locally. The technology is modularizing capital deployment decisions by separating core platform investment from procedure-specific instrument suites.
Japan's PMDA has tightened software validation requirements for AI-assisted surgical planning tools used in preoperative staging of muscle-invasive bladder cancer. Manufacturers must now submit standalone clinical evidence for algorithm-driven margin prediction modules. Urology departments are responding by embedding regulatory affairs specialists within clinical engineering teams to accelerate submission readiness.
Hospital buyers are consolidating vendor relationships through integrated service contracts that bundle robotic maintenance, disposable supply, and surgeon training into single-source agreements. Independent ambulatory centers are displacing this model with pay-per-use arrangements that transfer utilization risk to platform vendors. This behavioral shift is most pronounced in the United States, where site-of-care economics increasingly determine equipment placement decisions.
Cystectomy Market Segmentation
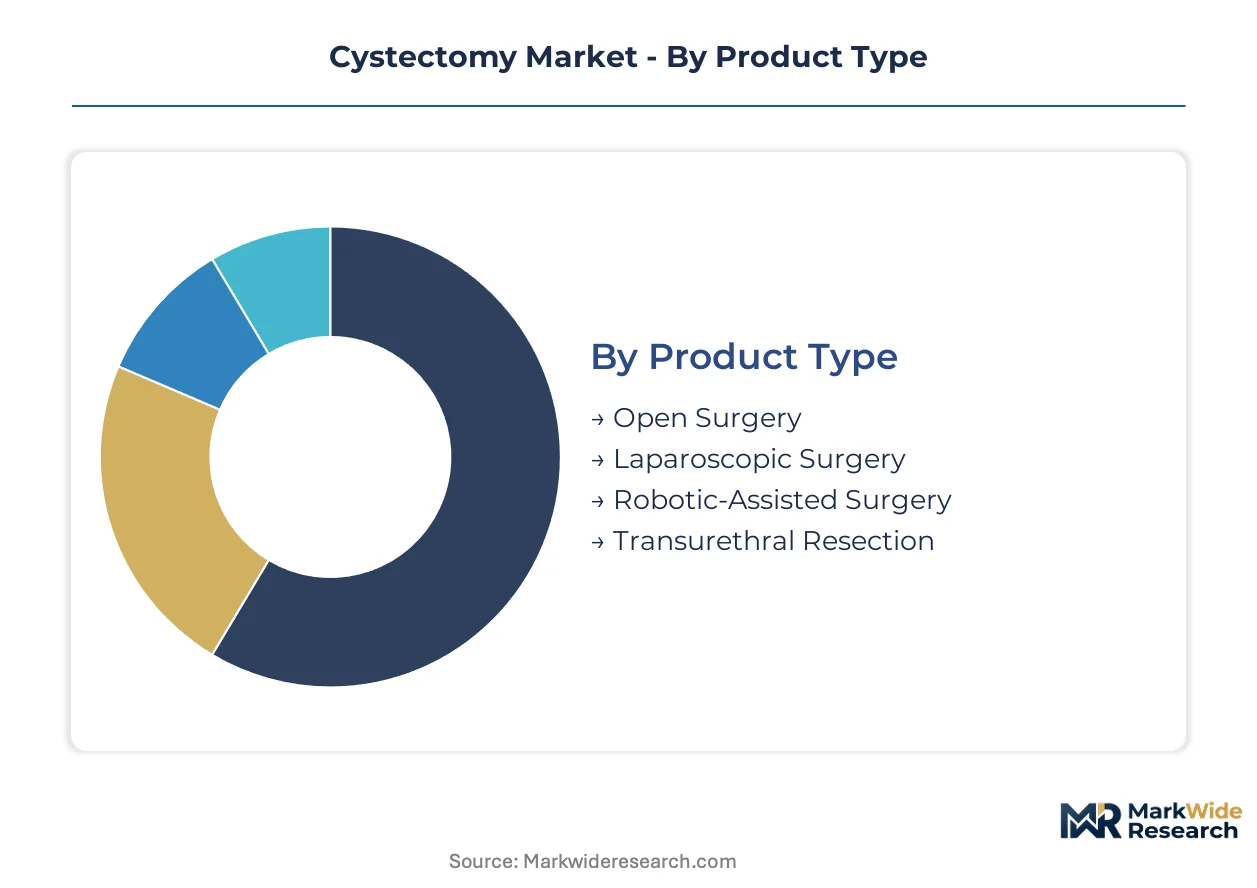
Segmentation in the cystectomy market reveals how capital allocation, reimbursement pathways, and clinical complexity intersect to determine where value concentrates. Understanding these divisions exposes which configuration choices drive margin capture versus volume expansion.
Product Type:
Supply concentration in robotic platforms creates asymmetric procurement leverage for established manufacturers while emergent techniques struggle for capital access.
- Robotic-Assisted Surgery:Multi-arm platforms with proprietary instrument ecosystems command premium capital expenditure through disposable cartridge cycles and long-term service contracts. Demand clusters in academic medical centers across the United States, Germany, and Japan where favorable reimbursement and training infrastructure align. Supply concentration in single-source instrument dependencies creates procurement vulnerability for high-volume centers.
- Open Surgery:Conventional laparotomy with direct manual dissection retains dominance in emergent cases, salvage procedures, and resource-constrained settings lacking robotic infrastructure. Volume concentrates in publicly funded healthcare systems where capital intensity constrains platform adoption. Technique familiarity among senior urologists sustains its position in complex reconstructions.
- Laparoscopic Surgery:Multi-port minimally invasive approach using standard energy and visualization equipment.
- Transurethral Resection:Endoscopic technique reserved for diagnostic staging and non-muscle-invasive disease management.
Today's leader: Robotic-Assisted Surgery. Tomorrow's challenger: Laparoscopic Surgery.
End User:
Site-of-care economics are redistributing procedure volumes away from traditional inpatient settings toward specialized outpatient facilities.
- Hospitals:Integrated health systems with emergency departments and intensive care units manage complex radical cystectomies requiring extended postoperative monitoring. Capital equipment concentration in university-affiliated centers across the United States, Germany, and Japan sustains robotic program development. Reimbursement parity debates between robotic and conventional techniques directly impact equipment procurement cycles.
- Ambulatory Surgical Centers:Specialized facilities focused on same-day discharge protocols capture select partial cystectomy and diagnostic procedures. Payer-mandated site-of-care shifts in the United States accelerate volume migration. Lower overhead structures enable competitive pricing for standardized cases.
- Clinics:Outpatient settings handle preoperative staging and postoperative surveillance rather than definitive surgical intervention.
- Research Institutions:Academic centers generate clinical evidence for novel techniques and train subsequent generations of robotic surgeons.
Ambulatory Surgical Centers are expanding most quickly. Hospitals retain margin dominance.
Indication:
Oncologic applications concentrate revenue while benign conditions drive procedural volume through recurrence patterns.
- Bladder Cancer:Muscle-invasive urothelial carcinoma and high-risk non-muscle-invasive disease failing intravesical therapy constitute the primary surgical indication. Radical cystectomy with pelvic lymphadenectomy and urinary diversion represents definitive oncologic treatment. Screening program intensity in Japan and Germany sustains early-stage detection and curative intervention rates.
- Neurogenic Bladder:Spinal cord injury and multiple sclerosis-related detrusor dysfunction drive reconstructive procedures including augmentation cystoplasty. Pediatric and young adult demographics in specialized centers create longitudinal care relationships. Medicare and private payer coverage for quality-of-life interventions varies substantially by jurisdiction.
- Bladder Dysfunction:Refractory overactive bladder and interstitial cystitis refractory to conservative management.
- Inflammation:Chronic cystitis and radiation-induced bladder contracture requiring diversion or reconstruction.
Bladder Cancer anchors revenue concentration. Neurogenic Bladder offers steepest expansion trajectory in specialized centers.
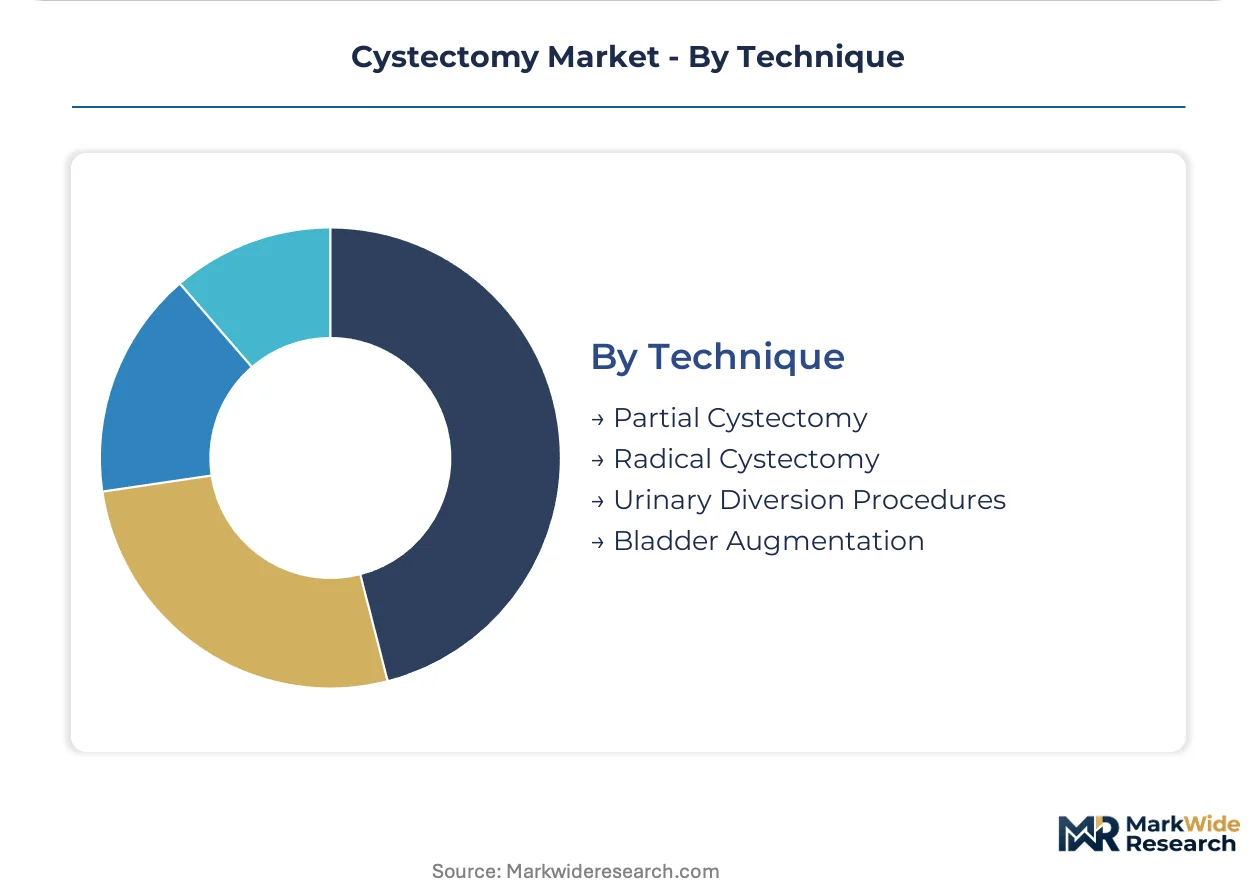
Technique:
Procedure complexity tiers create distinct training requirements, equipment dependencies, and reimbursement coding structures.
- Radical Cystectomy:Complete bladder removal with bilateral pelvic lymphadenectomy and urinary diversion reconstruction constitutes the most complex urologic oncology procedure. Operative duration extends six to eight hours with substantial blood loss risk and inpatient recovery requirements. Fellowship-trained surgeons at high-volume centers achieve superior oncologic and functional outcomes.
- Urinary Diversion Procedures:Ileal conduit, continent catheterizable reservoir, and orthotopic neobladder construction determine postoperative quality of life. Patient selection criteria including renal function, manual dexterity, and cancer stage guide diversion choice. Reimbursement coding complexity creates administrative burden for coding and prior authorization.
- Partial Cystectomy:Segmental bladder resection for solitary tumors in favorable locations.
- Bladder Augmentation:Enterocystoplasty to increase functional capacity in neurogenic or contracted bladders.
Radical Cystectomy commands premium reimbursement. Urinary Diversion Procedures differentiate outcomes most sharply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where cystectomy device manufacturers establish technical documentation and clinical validation operations, with cost-of-compliance gaps between the FDA and EU MDR driving strategic relocation of quality management functions.
United States
Academic medical centers in Cleveland, Houston, and New York sustain the highest robotic cystectomy volumes through bundled payment contracts with commercial insurers. FDA 510(k) premarket notification pathways impose substantial predicate-device equivalence burdens on novel platforms. The Cleveland Clinic and MD Anderson Cancer Center anchor multicenter clinical trials for next-generation single-port systems.
Germany
University hospitals in Heidelberg, Munich, and Berlin drive European adoption of fluorescence-guided cystectomy techniques through national bladder cancer screening programs. BfArM enforces country-specific quality management audits that delay market entry for non-established robotic manufacturers. The Heidelberg University Hospital cluster coordinates EU MDR technical documentation for predicate-device equivalence claims.
Japan
Aging demographics in Tokyo, Osaka, and Nagoya sustain procedure volume growth for muscle-invasive bladder cancer interventions. PMDA fast-track designations for cancer surgery devices accelerate regulatory timelines for robotic platform manufacturers. The University of Tokyo Hospital anchors clinical validation studies for nerve-sparing robotic techniques in the Asia-Pacific region.
India
Private hospital chains in Mumbai, Delhi, and Bengaluru expand robotic urology programs through medical tourism contracts with Gulf state patients. The PLI scheme for domestic medical device production reduces import duty burdens on capital equipment. Apollo Hospitals and Max Healthcare in Delhi-NCR pilot telepresence proctoring for community surgeon training.
United Kingdom
NHS England's specialized commissioning framework concentrates radical cystectomies in 13 designated cancer centers across London, Manchester, and Birmingham. NICE technology appraisals determine reimbursement parity between robotic and open techniques. The Royal Marsden and University College London Hospitals anchor clinical evidence generation for single-port platform adoption.
Cystectomy Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated system vendors commanding premium positions in academic medical centers while component suppliers capture volume in cost-constrained settings. Market structure tilts toward oligopoly in robotic platforms due to proprietary instrument ecosystems, while open and laparoscopic equipment markets sustain more fragmented competition. Three archetypes dominate: full-stack robotic integrators, modular visualization specialists, and disposable instrument contract manufacturers. Competitive moves concentrate on strategic partnerships for training infrastructure and geographic licensing for regulatory fast-track access.
Among North American platform developers, Intuitive Surgical and Titan Medical USA Inc. occupy positions at opposite ends of the commercialization spectrum, with the former exemplifying installed-base leverage through recurring revenue models and the latter representing venture-stage single-port specialization. Medtronic anchors the European-Asian nexus through its Hugo platform positioning. Richard Wolf GmbH exemplifies the German Mittelstand archetype of family-owned precision engineering in endoscopic visualization systems.
| Leading Market Players |
|---|
| Intuitive Surgical |
| Boston Scientific Corporation |
| Medtronic |
| Zimmer Biomet |
| Zephyr Surgical Implants |
| Richard Wolf GmbH |
| Titan Medical USA Inc. |
| TransEnterix Surgical, Inc. |
| Asensus Surgical US, Inc |
| Others |
Supply Flow & Price Mechanics
Single-port robotic platform miniaturization is compressing capital deployment thresholds while concentrating procurement leverage among established instrument cartridge suppliers. This technological shift simultaneously reduces per-suite infrastructure costs and tightens vendor lock-in through proprietary disposable ecosystems.
Pricing Analysis
Distributor margins on robotic instrument cartridges absorb substantial channel economics before hospital procurement committees negotiate final pricing. Three-tier pricing structure across premium multi-arm platforms, standard laparoscopic configurations, and economy open-surgery instrument sets reflects certification grade and after-sales service bundling. Pricing pressure stems from payer-mandated site-of-care shifts toward ambulatory centers with lower overhead tolerance. Academic medical centers demonstrate least price sensitivity due to bundled payment contracts, while publicly funded systems in Germany and India exhibit highest sensitivity to capital expenditure thresholds.
Supply Chain Analysis
Precision servo motor and optical sensor supply rests on Japanese and German specialty component manufacturers with limited alternative sourcing. Proprietary instrument cartridge production draws from Taiwan semiconductor foundries for embedded control chips, US-based polymer suppliers for biocompatible housings, and Swiss precision machining for articulating wrist mechanisms. Single-source vulnerability concentrates in FDA-validated sterilization packaging with extended qualification timelines. Distribution runs through regional medical device distributors holding GPO contracts with major hospital systems, with direct manufacturer relationships reserved for high-volume academic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cystectomy device market functions as a regulatory compounder where EU MDR conformity acceleration and Japan PMDA fast-track pathways compound demand for validated robotic platforms. These regulatory milestones create procurement urgency among hospital systems seeking competitive positioning.
For Market Incumbents: Deepen backward integration into precision servo motor production to reduce exposure to Japanese component supply bottlenecks. Expand training infrastructure partnerships with residency programs to lock in surgeon preference formation before emerging single-port platforms achieve commercial scale. Defend instrument cartridge revenue streams through exclusive GPO contract renewals that bundle maintenance and disposable supply.
For New Entrants and Emerging Players: Launch via pay-per-use arrangements targeting independent ambulatory surgical centers in the United States where capital constraints exclude traditional platform procurement. Prioritize India's private hospital chains in Mumbai and Delhi-NCR for medical tourism robotics contracts with Gulf state patient flows. Pursue PMDA fast-track designation for nerve-sparing technique modules to establish Asia-Pacific clinical evidence generation.
For Investors and Strategic Acquirers: Valuations sit cheapest among contract manufacturers of disposable robotic instruments with established FDA master files and EU MDR technical documentation. Long-term viability centers on regulatory asset accumulation rather than pure technology differentiation. Acquisition targets should demonstrate completed BfArM quality audits or PMDA software validation for AI-assisted modules. Watch for reimbursement parity decisions between robotic and open techniques as the inflection signal determining adoption velocity irrespective of clinical outcomes data.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Completion | Accelerates predicate-device clearance timelines for next-generation platforms in Heidelberg and Munich university hospitals. |
| Single-Port Platform Miniaturization | Enables deployment in smaller German and Japanese operating suites previously unsuitable for multi-arm systems. |
| Integrated Service Contract Consolidation | Bundles robotic maintenance, disposable supply, and surgeon training into single-source agreements for academic centers. |
| Telepresence Proctoring Infrastructure | Extends specialist expertise from Tokyo and Osaka to community hospitals via 5G-enabled remote training. |
| PMDA Fast-Track Designation Pursuit | Opens regulatory pathways for cancer surgery devices in Japan's underpenetrated robotic cystectomy market. |
Methodological Framework
Multiple input streams — structured interviews with urology department heads, procurement committee deliberations, and regulatory affairs specialists — were reconciled against secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, and hospital capital equipment expenditure records. Bottom-up procedure volume estimates from Germany, Japan, and the United States were triangulated with top-down market sizing derived from manufacturer reported installed base and instrument cartridge recurring revenue disclosures.
Historical robotic adoption curves in prostatectomy were cross-referenced against expert panel inputs on cystectomy-specific training pipeline constraints. Segmentation modeling incorporated product type, end user channel, oncologic indication, and procedural technique complexity across the projection horizon. CAGRs were derived from equipment replacement cycles, reimbursement parity trajectory assumptions, and demographic procedure volume elasticity in aging populations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under reimbursement non-parity scenarios or protracted EU MDR documentation delays. A small set of named triggers — CMS technology add-on payment decisions, BfArM audit timeline shifts, and PMDA software validation requirement changes — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Urinary Retention Therapeutics Market
Urology
India Urology Device Market
Urology
Ureteral Obstruction Market
Urology
India Urology Market
Urology
Urothelial Carcinoma Treatment Market
Urology
Global Castrate Resistant Prostate Cancer Market
Urology
Urinary Tract Infection (UTI) Market
Urology
Transrectal Ultrasound Market
Urology
Urinary Incontinence Treatment Drugs Market
Urology
Global Benign Prostatic Hyperplasia Treatment Market
Urology
Urology Devices Market
Urology
Asia-Pacific Bladder Disorders Market
Urology
Acute Pyelonephritis Treatment Market
Urology
Primary Aldosteronism Market
Urology
Complicated Urinary Tract Infections Treatment Market
Urology
Acquired Cystic Kidney Disease Treatment Market