
 Non-Metastatic Castration-Resistant Prostate Cancer (NMCRPC) Therapeutics Market | 2026-2036
Non-Metastatic Castration-Resistant Prostate Cancer (NMCRPC) Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Metastatic Castration-Resistant Prostate Cancer (NMCRPC) Therapeutics Market Analytics
Software-defined dosing protocols and remote patient monitoring subscriptions are decoupling therapeutic value from the physical drug vial in NMCRPC care. Johnson & Johnson leverages its integrated oncology ecosystem to sustain high-touch patient management programs. Pfizer anchors its position through deep urology-specialist relationships and companion diagnostic alignment.
Non-metastatic castration-resistant prostate cancer therapeutics comprise pharmaceutical agents that suppress androgen receptor signaling despite castrate testosterone levels, typically formulated as small-molecule inhibitors with defined half-lives enabling once-daily oral administration. These agents halt disease progression to metastasis, preserving quality-adjusted life years in a patient population with rising prostate-specific antigen but no detectable metastatic lesions on conventional imaging. Hormonal therapies occupy the dominant revenue position due to established clinical utility and broad prescriber familiarity, while targeted therapies represent the fastest-expanding category as precision biomarker selection narrows eligible populations and commands premium positioning. Injectable delivery modes retain substantial share in hospital settings, though oral formulations are displacing infusion-dependent regimens in outpatient and home care environments.
FDA breakthrough therapy designation and EMA priority medicines pathways compress development timelines and shape payer negotiations for novel NMCRPC agents. The EPA and OSHA frameworks govern active pharmaceutical ingredient manufacturing standards, affecting contract manufacturer selection and facility qualification for cytotoxic hormone synthesis. Stakeholders must monitor evolving radiographic progression-free survival endpoints and their acceptance by national health technology assessment bodies.
Market Dynamics
FDA breakthrough therapy designation is compressing commercialization timelines for novel androgen receptor inhibitors, while Medicare reimbursement structures in the United States concentrate demand around premium-priced hormonal protocols. Hospital-based oncology departments are restructuring formularies around progression-free survival endpoints.
Growth Catalysts
- Accelerated Approval Pathways:FDA breakthrough therapy designation and EMA priority medicines status compress Phase III-to-launch intervals for novel NMCRPC agents, rewarding sponsors with earlier revenue recognition and priority review vouchers.
- Biomarker-Enriched Trials:Radiographic progression-free survival endpoints validated by national health technology assessment bodies expand reimbursable indications for next-generation hormonal therapies in presymptomatic patient populations.
- Integrated Care Models:Johnson & Johnson's high-touch patient management programs demonstrate improved adherence metrics, prompting competing health systems to replicate wraparound oncology service architectures.
Market Restraints
- API Manufacturing Concentration:EPA and OSHA frameworks governing cytotoxic hormone synthesis restrict contract manufacturer qualification to a limited base of North American and European facilities, creating single-source vulnerabilities.
- Reimbursement Compression:Medicare's inflation rebate provisions under the Inflation Reduction Act erode net pricing power for oral androgen receptor inhibitors launched after statutory reference price benchmarks.
- Diagnostic Fragmentation:Heterogeneous prostate-specific antigen testing protocols across community urology practices delay uniform patient identification for NMCRPC intervention windows.
Strategic Opportunities
- Home-Based Administration:Oral formulation dominance enables displacement of infusion-dependent regimens into outpatient and home care environments, capturing margin from hospital facility fees.
- Companion Diagnostic Alignment:Precision biomarker selection narrows eligible populations for targeted therapies, commanding premium positioning and favorable pharmacy benefit manager tiering.
- Remote Monitoring Integration:Software-defined dosing protocols and subscription-based patient monitoring decouple therapeutic value from physical drug vials, creating recurring revenue architectures.
Industry Challenges
- Endpoint Harmonization:Evolving radiographic progression-free survival definitions across FDA, EMA, and national health technology assessment bodies force redundant clinical program designs and protocol amendments.
- Specialist Access Constraints:Deep urology-specialist relationships held by entrenched incumbents create formidable barriers for novel market entrants seeking prescriber mindshare and formulary inclusion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Metastatic Castration-Resistant Prostate Cancer (NMCRPC) Therapeutics Market |
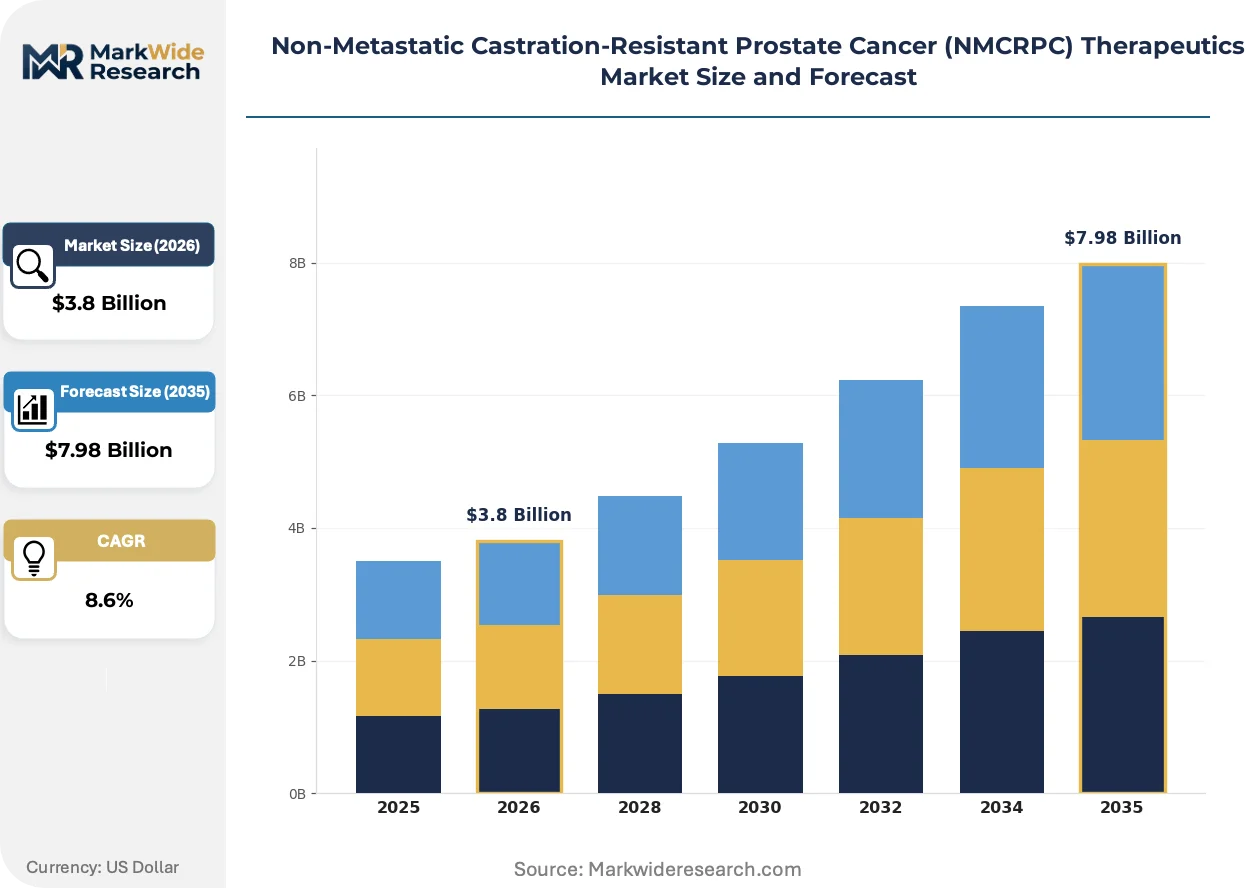
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormonal Therapies, Targeted Therapies, Chemotherapies, Immunotherapies Delivery Mode: Oral, Injectable, Intravenous, Transdermal End User: Hospitals, Clinics, Home Care, Research Laboratories Therapy Area: Urology, Oncology, Endocrinology, Pain Management |
| Companies Covered | Johnson & Johnson, Astellas Pharma, Pfizer, Bayer AG, AstraZeneca, Novartis AG, Sanofi S.A., Merck & Co., GlaxoSmithKline PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Metastatic Castration-Resistant Prostate Cancer (NMCRPC) Therapeutics Market Evolving Landscape
Next-generation hormonal protocols are redefining therapeutic value in NMCRPC care, unifying pharmacologic intervention with digital patient management infrastructure. Three convergent developments are restructuring competitive positioning and commercial architecture.
Positron emission tomography with prostate-specific membrane antigen radiotracers is unifying diagnostic precision with therapeutic decision-making, enabling earlier detection of micrometastatic disease before conventional imaging. Academic medical centers in the United States and Germany are adopting PSMA-PET as the standard of care for biochemical recurrence staging. This technology is compressing the non-metastatic treatment window and reshaping trial enrollment criteria for castration-resistant indications.
EMA's evolving health technology assessment harmonization initiatives are standardizing radiographic progression-free survival evidentiary requirements across EU member states. Pharmaceutical sponsors now face unified endpoint negotiation with centralized payer bodies rather than fragmented national assessments. France, Germany, and Italy are consolidating early access pathways under the EU joint clinical assessment framework, accelerating or delaying market entry based on single HTA determinations.
Hospital procurement committees are consolidating oncology formulary decisions under centralized pharmacy and therapeutics structures, displacing individual prescriber autonomy with protocol-driven algorithmic prescribing. Integrated delivery networks in the United States are implementing mandatory prior authorization for androgen receptor inhibitor selection based on biomarker status. This concentration is most visible in Medicare Advantage–dominated regions where risk-bearing entities optimize pharmaceutical spend through narrow therapeutic substitution policies.
Non-Metastatic Castration-Resistant Prostate Cancer (NMCRPC) Therapeutics Market Segmentation
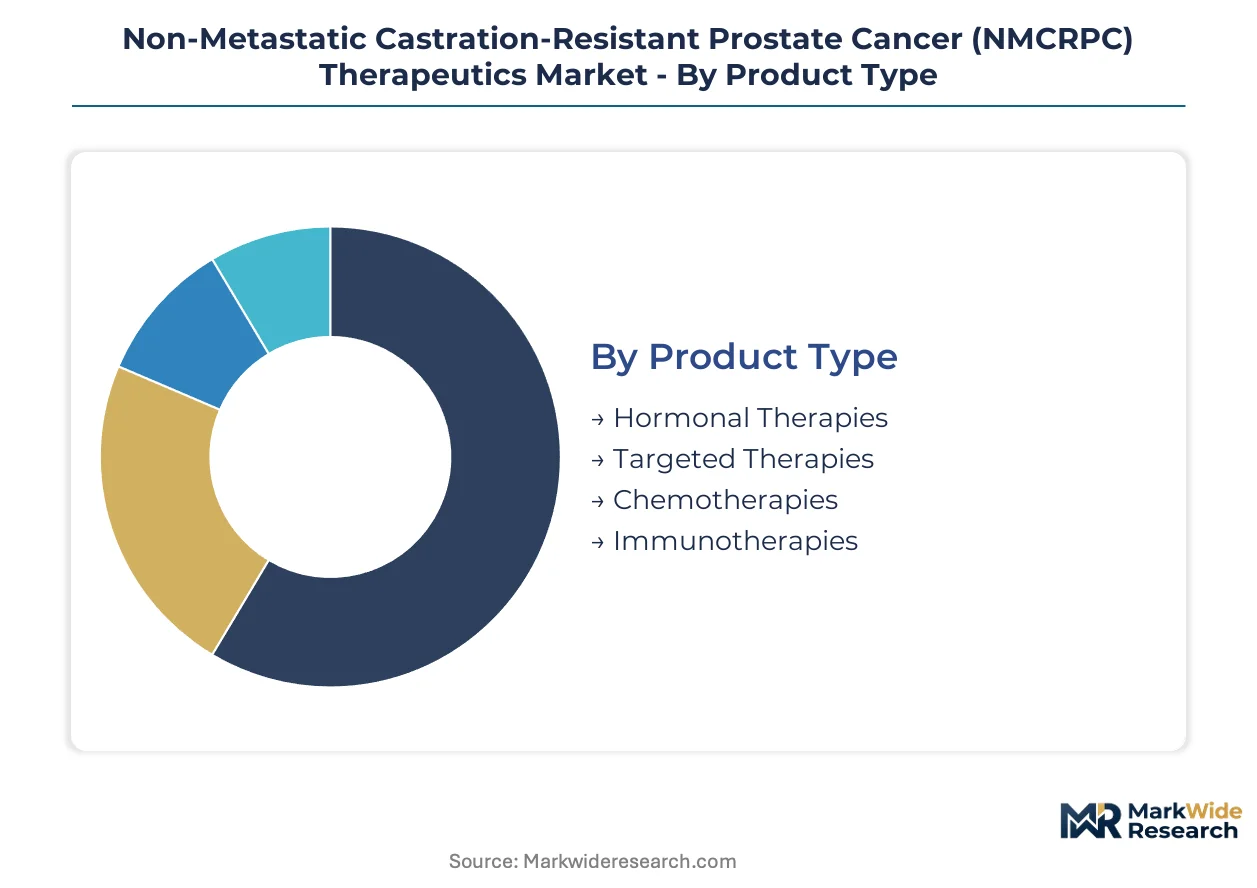
Segmentation in NMCRPC therapeutics reveals how capital allocation, reimbursement pathways, and patient access constraints fragment commercial opportunity. Manufacturers must align formulation investments with specific care settings and prescriber specialties to capture value.
Product Type:
Capital intensity varies sharply across therapeutic modalities, with small-molecule manufacturing demanding specialized containment infrastructure for cytotoxic hormone synthesis.
- Hormonal Therapies:Androgen receptor inhibitors formulated as once-daily oral tablets dominate hospital formularies due to established progression-free survival data. Medicare reimbursement in the United States concentrates demand around premium-priced next-generation agents like darolutamide and enzalutamide, though the Inflation Reduction Act's rebate provisions compress net margins for newer entrants.
- Targeted Therapies:Precision agents requiring companion diagnostic alignment command the steepest R&D investment but deliver premium positioning through biomarker-selected populations. Academic medical centers in Germany and the United States are piloting PSMA-directed radioligand therapies that blur diagnostic and therapeutic boundaries.
- Chemotherapies:Cytotoxic regimens retain niche utility in rapidly progressing disease despite toxicity profiles that limit outpatient adoption.
- Immunotherapies:Checkpoint inhibitors and cancer vaccines remain investigational for NMCRPC, with clinical programs focused on combination hormonal protocols.
Most installed capacity flows through Hormonal Therapies. Expansion is steepest in Targeted Therapies.
Delivery Mode:
Route of administration determines site-of-care economics and patient adherence architecture, with oral formulations displacing infusion-dependent revenue models.
- Oral:Small-molecule inhibitors with defined half-lives enable home-based administration, capturing margin from eliminated hospital facility fees. Johnson & Johnson's patient management programs demonstrate improved adherence through digital reminder infrastructure.
- Injectable:Depot formulations sustain therapeutic levels over extended intervals, suiting patients with polypharmacy complexity or cognitive impairment. Community urology clinics in the United States favor injectable protocols where nursing support ensures compliance monitoring.
- Intravenous:Infusion-dependent regimens concentrate in hospital oncology departments with pharmacy and therapeutics committee oversight.
- Transdermal:Patch-based delivery remains limited by skin permeability constraints for large-molecule hormonal agents.
Volume concentrates in Oral formulations. Steepest patient preference shift is occurring in Injectable alternatives.
End User:
Care setting selection reflects disease staging precision, reimbursement mechanics, and prescriber specialty density across geographic markets.
- Hospitals:Integrated delivery networks with centralized pharmacy and therapeutics structures mandate prior authorization for androgen receptor inhibitor selection. Medicare Advantage–dominated regions in the United States exhibit the most concentrated formulary control.
- Clinics:Community urology practices handle the majority of biochemical recurrence monitoring, though heterogeneous PSA testing protocols delay uniform NMCRPC identification.
- Home Care:Remote patient monitoring subscriptions and software-defined dosing protocols are decoupling therapeutic value from physical drug vials in this channel.
- Research Laboratories:Academic medical centers in Germany and the United States drive PSMA-PET adoption for micrometastatic detection, compressing trial enrollment windows.
Patient volume flows predominantly through Hospitals. Fastest structural change is occurring in Home Care.
Therapy Area:
Specialty referral patterns and prescriber relationship depth determine competitive access, with urology-oncology interface creating the most contested patient handoffs.
- Urology:Deep specialist relationships held by Pfizer and Johnson & Johnson create formidable barriers for novel entrants seeking prescriber mindshare. Community practices in the United States retain biochemical recurrence patients until radiographic progression triggers oncology referral.
- Oncology:Hospital-based departments restructure formularies around progression-free survival endpoints, with EMA health technology assessment harmonization standardizing evidentiary requirements across EU member states.
- Endocrinology:Castration maintenance protocols and bone health management intersect with NMCRPC care in academic medical centers.
- Pain Management:Skeletal-related event prevention and palliative intervention address quality-adjusted life year preservation in later disease stages.
Treatment initiation concentrates in Urology. Referral acceleration is most pronounced in Oncology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting active pharmaceutical ingredient manufacturing toward jurisdictions with streamlined environmental compliance frameworks, compressing cost structures for cytotoxic hormone synthesis while FDA and EMA pathways accelerate commercialization timelines in premium markets.
United States
Medicare reimbursement structures concentrate demand for next-generation androgen receptor inhibitors, with Medicare Advantage plans implementing narrow therapeutic substitution policies in risk-bearing regions. The FDA's breakthrough therapy designation compresses Phase III-to-launch intervals, rewarding sponsors with priority review vouchers. Academic medical centers in Boston and Houston drive PSMA-PET adoption for micrometastatic detection, compressing trial enrollment windows for NMCRPC indications.
Germany
EMA health technology assessment harmonization standardizes radiographic progression-free survival evidentiary requirements across EU member states, creating unified endpoint negotiation with centralized payer bodies. The country's national pharmaceutical regulator accelerates early access pathways under the EU joint clinical assessment framework. Pharmaceutical clusters in Munich and Heidelberg anchor precision biomarker research, with university hospitals piloting PSMA-directed radioligand therapies.
Japan
PMDA's sakigake designation system accelerates regulatory review for innovative oncology agents, aligning commercialization timelines with Western markets. METI's industrial policy supports domestic manufacturing capacity for high-potency hormonal APIs. The Kanto region around Tokyo hosts concentrated urology-oncology specialist networks, with major university hospitals restructuring formularies around progression-free survival endpoints.
United Kingdom
NICE technology appraisals determine reimbursable indications for novel hormonal therapies, with cost-effectiveness thresholds shaping market access negotiations. The MHRA's post-Brexit regulatory autonomy enables tailored approval pathways for breakthrough NMCRPC agents. London's integrated delivery networks implement mandatory prior authorization for androgen receptor inhibitor selection based on biomarker status.
Switzerland
Swissmedic's streamlined marketing authorization procedures attract pharmaceutical sponsors seeking rapid European market entry, with pricing freedom enabling premium positioning for targeted therapies. The country's concentrated pharmaceutical manufacturing base in Basel supports specialized containment infrastructure for cytotoxic hormone synthesis. Academic medical centers in Zurich and Geneva drive companion diagnostic alignment for precision NMCRPC treatment selection.
Non-Metastatic Castration-Resistant Prostate Cancer (NMCRPC) Therapeutics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated pharmaceutical conglomerates dominating hospital formulary decisions while specialized oncology biotechs capture premium positioning through biomarker-selected indications. Market structure concentrates around three strategic archetypes: diversified healthcare conglomerates with deep urology-specialist relationships, precision oncology specialists with companion diagnostic alignment, and API-focused contract manufacturers with cytotoxic containment capabilities. Dominant competitive moves include strategic partnerships for remote patient monitoring integration and capacity expansion for oral small-molecule manufacturing.
Within the diversified healthcare conglomerate tier, Johnson & Johnson and Pfizer exemplify archetypes built on high-touch patient management programs and deep prescriber relationships respectively. Astellas Pharma occupies a position representing precision oncology specialists with established androgen receptor inhibitor portfolios. These three entities anchor competitive dynamics through differentiated approaches to formulary access and adherence infrastructure.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Astellas Pharma |
| Pfizer |
| Bayer AG |
| AstraZeneca |
| Novartis AG |
| Sanofi S.A. |
| Merck & Co. |
| GlaxoSmithKline PLC |
| Others |
Value Network & Pricing Analysis
Oral formulation dominance in NMCRPC therapeutics is compressing hospital facility fees while concentrating manufacturing investment in North American and European cytotoxic containment facilities. This shift simultaneously elevates patient adherence economics and restricts API sourcing flexibility under EPA and OSHA frameworks.
Pricing Analysis
Hospital pharmacy and therapeutics committee markups dominate channel economics, with three-tier pricing structure across premium, standard, and economy levels stratifying by biomarker selection precision and companion diagnostic bundling. Price differentiation hinges on radiographic progression-free survival data maturity and Medicare Advantage formulary tier placement. Pricing pressure stems from the Inflation Reduction Act's inflation rebate provisions compressing net margins for newer oral androgen receptor inhibitors. Community urology practices exhibit highest price sensitivity due to limited prior authorization infrastructure, while integrated delivery networks negotiate steepest discounts through narrow therapeutic substitution policies.
Supply Chain Analysis
Specialized containment workforce availability in Switzerland and Germany anchors high-potency hormonal API production, with North American facilities absorbing regulatory compliance cost premiums. Active pharmaceutical ingredient synthesis draws from cytotoxic hormone precursors sourced through qualified contract manufacturers in Basel and Munich clusters. Single-source vulnerability concentrates in EPA-permitted facilities handling androgen receptor inhibitor intermediates. Distribution runs through hospital procurement committees and specialty pharmacy networks with cold-chain requirements for injectable depot formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The NMCRPC therapeutics market functions as a regulatory compounder, with FDA breakthrough therapy designation and EMA priority medicines status accelerating commercialization timelines and compressing competitive entry windows.
For Market Incumbents: Anticipate reimbursement compression from Medicare inflation rebate provisions by deepening vertical integration into companion diagnostic development and securing proprietary biomarker platforms. Prioritize capacity expansion in Swiss and German cytotoxic manufacturing clusters to preempt API supply constraints. Counter emerging precision oncology biotechs through wraparound patient management program differentiation and urology-specialist relationship lock-in. For New Entrants and Emerging Players: Specialty pharmacy distributors represent the most accessible channel partnership for oral formulation penetration against entrenched hospital formulary control. Target home care administration white space enabled by software-defined dosing protocol integration. Pursue EMA joint clinical assessment framework early access pathways in Germany as the lowest-friction European entry point, leveraging PSMA-PET diagnostic alignment for premium positioning. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap precision oncology specialists with Phase II radiographic progression-free survival data and companion diagnostic partnerships but limited commercial infrastructure. Long-term viability centers on biomarker-enriched trial design capabilities and health technology assessment negotiation track records across EU member states. Watch for PSMA-PET standardization adoption curves as the signal indicating trial enrollment compression and treatment window contraction.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Alignment | Precision biomarker selection narrows eligible populations and commands favorable pharmacy benefit manager tiering. |
| Remote Patient Monitoring Integration | Software-defined dosing protocols decouple therapeutic value from physical drug vials, creating recurring revenue architectures. |
| EMA Priority Medicines Pathway Pursuit | Centralized EU joint clinical assessment framework accelerates market entry across France, Germany, and Italy. |
| High-Potency API Manufacturing Scale-Up | Swiss and German containment facility investment preempts EPA-permitted capacity constraints for cytotoxic hormone synthesis. |
| Urology-Specialist Relationship Deepening | Community practice formulary influence retains biochemical recurrence patients before oncology referral triggers. |
Research Methodology
Direct dialogue with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers grounded qualitative insights, cross-referenced against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient flow modeling and top-down pharmaceutical spend analysis triangulated market sizing across treatment line, dosage form, administration route, and regional regulatory cluster dimensions.
Segment-level value projections across the analysis window integrated epidemiological incidence data, treatment penetration curves, and pricing elasticity parameters by payer type. CAGRs derived from regression-adjusted historical analogs and scenario-weighted regulatory approval timelines. Modeled inputs included radiographic progression-free survival endpoint acceptance rates by national health technology assessment bodies and Medicare Advantage formulary control concentration indices.
Revisions become necessary when FDA breakthrough therapy designation criteria shift, EMA health technology assessment harmonization initiatives stall, or PSMA-PET standardization adoption materially deviates from academic medical center pilot trajectories. Forecasts reflect assumptions about reimbursement stability and diagnostic protocol uniformity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Global Castrate Resistant Prostate Cancer Market
Urology
LAMEA Transrectal Ultrasound Market
Urology
Primary Aldosteronism Market
Urology
Genitourinary Cancers Treatment Market
Urology
Urinary Incontinence Market
Urology
Urology Surgery Supplies Market
Urology
Global Benign Prostatic Hyperplasia Treatment Market
Urology
Single Use Cystoscope Market
Urology
Cystoscope Market
Urology
Complicated Urinary Tract Infections Treatment Market
Urology
Global Urinary Tract Infections Therapeutics Market
Urology
Pelvic Cancer Induced Hemorrhegic Cystitis Market
Urology
Urinary Incontinence Therapeutics Market
Urology
Urinary Incontinence Treatment Drugs Market
Urology
Disposable Ureteroscope Market
Urology
US Urology Devices Market