
 Australia Animal Protein Market | 2026-2036
Australia Animal Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Animal Protein Market Outlook
Foodservice buyers are rotating toward premium grass-fed and antibiotic-free animal protein offerings as institutional procurement policies tighten sustainability criteria. Kerry Group plc leverages its ingredient technology portfolio to supply flavor and texture solutions that differentiate processed meat applications for Australian manufacturers. Fonterra Co-operative Group Limited anchors its position through dairy-derived protein streams that compete alongside traditional meat proteins in functional food formulations. Noumi Limited specializes in nutritional dairy and whey protein isolates that extend into sports nutrition and clinical nutrition channels domestically.
Animal protein encompasses the edible muscle tissue, connective tissue, and associated proteins derived from livestock and poultry species, typically comprising 18-25% protein by wet weight with complete essential amino acid profiles critical for human nutrition. Beef and poultry categories dominate Australian production volume, with beef retaining premium export positioning while poultry captures cost-sensitive domestic consumption through intensive farming scale. Processing type segmentation reveals fresh and frozen channels commanding margin pools in retail and foodservice, whereas cured and processed formats concentrate demand among food manufacturers seeking extended shelf-life inputs for ready-meal and snack applications.
Food Standards Australia New Zealand (FSANZ) sets maximum residue limits and labeling requirements that directly shape product formulation decisions across the supply chain. The Australian Department of Agriculture, Fisheries and Forestry administers export registration and biosecurity protocols that determine market access eligibility for protein shipments to key trading partners. Safe Work Australia mandates processing facility standards that influence capital allocation toward automation and worker safety infrastructure. Stakeholders must monitor evolving state-based environmental regulations governing feedlot runoff and methane accounting, as these frameworks will increasingly determine production cost structures and geographic licensing for new capacity.
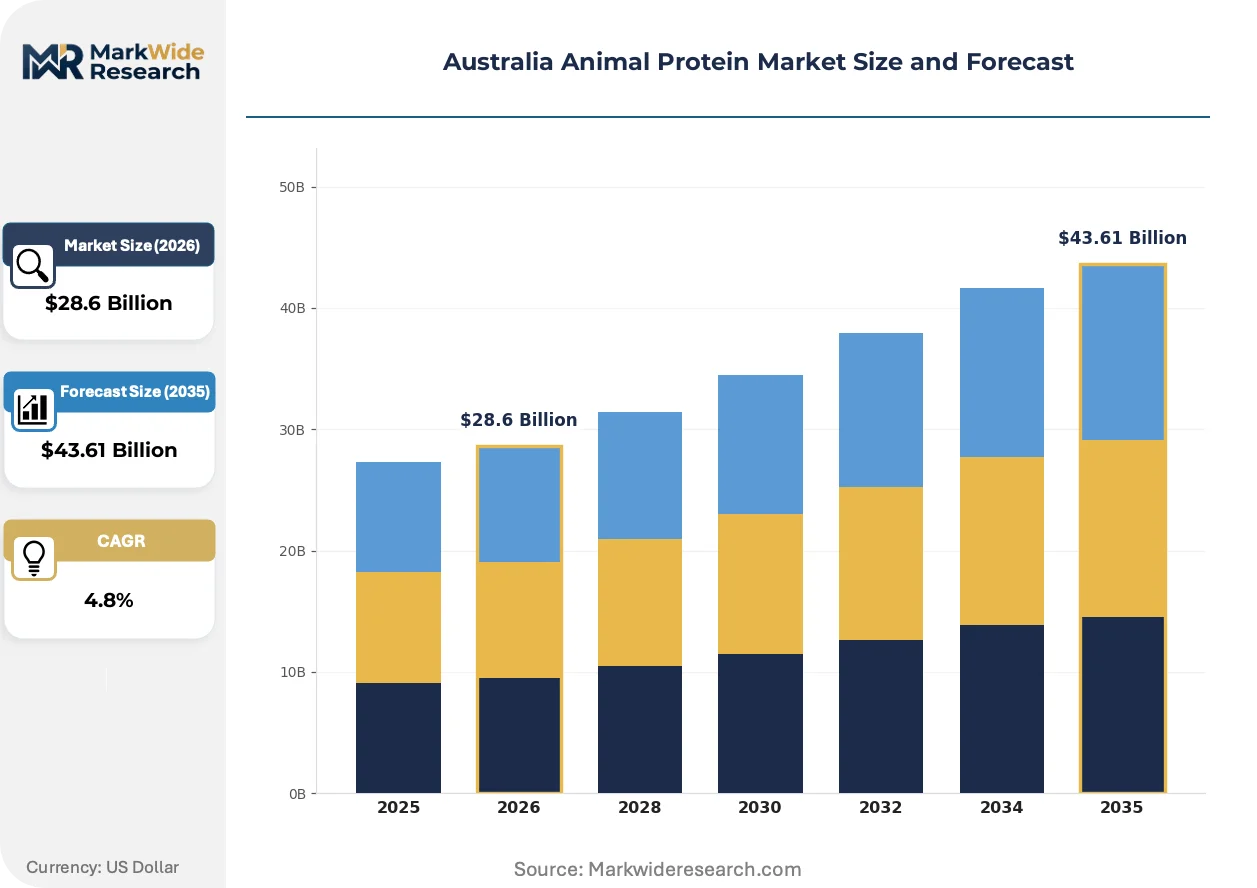
Market Dynamics
Biosecurity modernization under the Australian Department of Agriculture, Fisheries and Forestry is compressing traceability timelines from farm gate to export certification, forcing capital redeployment toward automated compliance infrastructure and real-time chain-of-custody systems.
Growth Catalysts
- Clean-label procurement mandates:Food manufacturers across ready-meal and sports nutrition verticals are specifying grass-fed and antibiotic-free inputs, pulling premium animal protein volumes through Queensland and New South Wales processing clusters.
- Codex Alimentarius alignment:Export certification harmonization with international food safety standards is unlocking market access eligibility for Australian beef and poultry shipments to previously restricted trading partners.
- Feedlot infrastructure concentration:Eastern seaboard clustering of red meat processing capacity around Brisbane and Sydney corridors is generating scale economies in cold-chain logistics and byproduct utilization.
Market Restraints
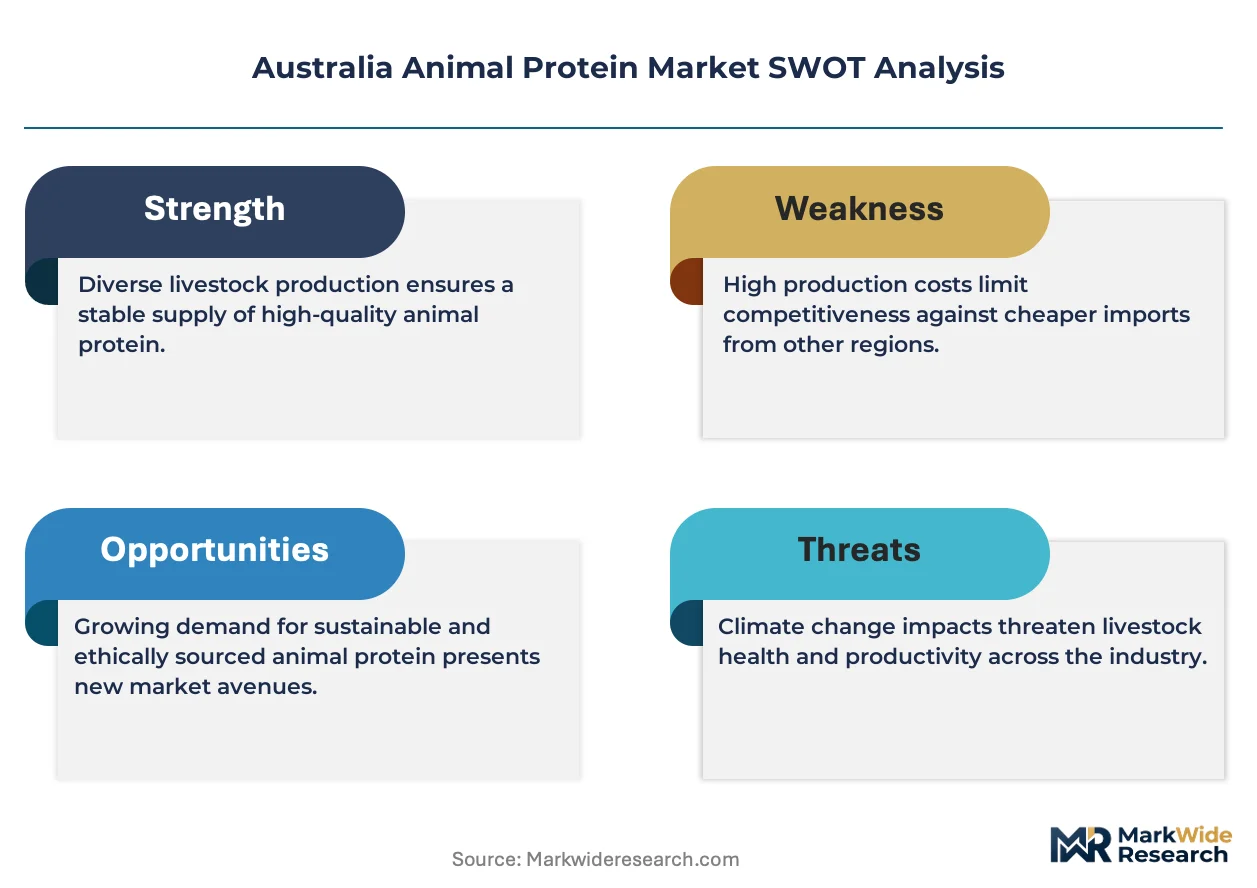
- Feed grain price volatility:Wheat and sorghum input costs fluctuate with global commodity markets, compressing feedlot margin structures and forcing hedging complexity onto mid-scale processors.
- Queensland-New South Wales supply concentration:Overreliance on eastern states for both cattle finishing and slaughter capacity creates geographic vulnerability to drought, flood, and transport disruption events.
- Methane accounting requirements:Emerging state-based environmental regulations governing feedlot emissions are adding compliance layers that delay facility licensing and inflate project development timelines.
Strategic Opportunities
- Western Australia capacity expansion:Underdeveloped feedlot and processing infrastructure in the west offers greenfield sites with lower land costs and proximity to Asian export shipping lanes.
- Clinical nutrition channel development:Dairy-derived protein isolates from whey and casein streams are penetrating hospital and aged-care nutrition formulations, extending beyond traditional sports nutrition positioning.
- Automation technology convergence:Integration of robotics with blockchain traceability systems enables real-time carcass tracking that satisfies both FSANZ requirements and premium export buyer specifications.
Industry Challenges
- Veterinary pharmaceutical residue compliance:FSANZ maximum residue limit testing protocols require laboratory infrastructure and trained personnel that smaller processors struggle to maintain.
- Safe Work Australia facility standards:Mandated worker safety capital expenditure for automation and ergonomic redesign strains balance sheets of family-owned abattoirs with limited access to project finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Animal Protein Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Poultry, Pork, Lamb Distribution Channel: Retail, Foodservice, E-commerce, Wholesale End User: Households, Restaurants, Food Manufacturers, Institutions Processing Type: Fresh, Frozen, Cured, Processed |
| Companies Covered | Kerry Group plc, Freedom Foods Group Limited, Fonterra Co-operative Group Limited, Gelita AG, Royal FrieslandCampina NV, Saputo Inc., Glanbia PLC, Noumi Limited, Groupe Lactalis, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Animal Protein Market Strategic Shifts
Processing technology and regulatory transparency requirements are converging to reshape how Australian animal protein moves from farm to finished product, with automation and digital traceability now baseline competitive requirements rather than differentiators.
Blockchain-enabled carcass tracking systems are miniaturizing compliance documentation from batch-level to individual-animal granularity. Major retail chains and export buyers are mandating this granularity for premium tier procurement. The technology is compressing audit timelines from weeks to hours while elevating data infrastructure to core operational capability.
FSANZ is tightening maximum residue limit enforcement for hormonal growth promotants and antibiotics, with expanded testing protocols scheduled for implementation across registered establishments. This regulatory pressure is accelerating investment in rapid diagnostic equipment and in-house laboratory capacity. Beef export segments targeting European Union and Japanese buyers face the steepest compliance ramps.
Foodservice procurement is consolidating toward direct processor relationships that bypass traditional wholesale intermediaries. Institutional buyers in healthcare and education sectors are negotiating multi-year supply agreements with specified welfare and sustainability credentials. This channel restructuring is most visible in Sydney and Melbourne metropolitan procurement offices where sustainability criteria now outweigh price in tender evaluations.
Australia Animal Protein Market Segmentation
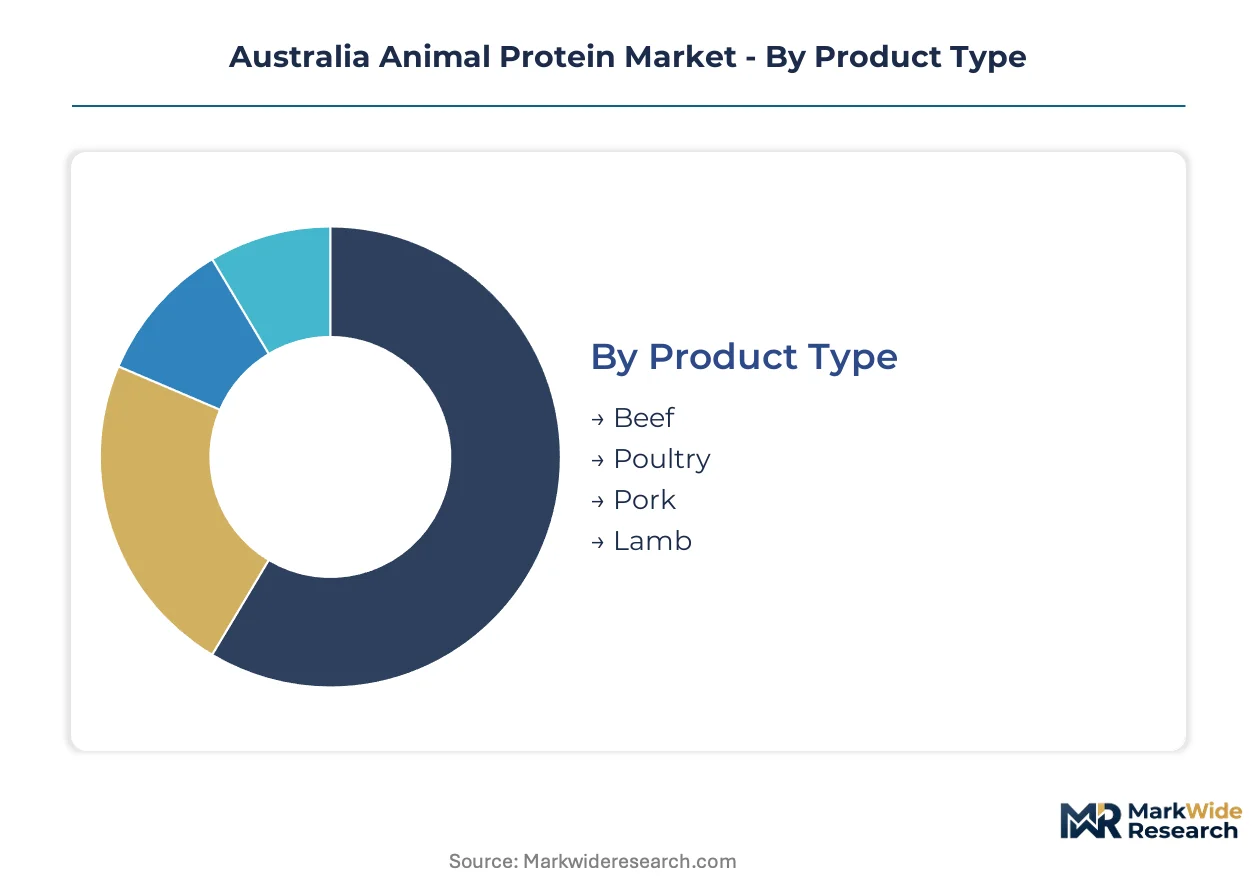
Animal protein segmentation in Australia reflects dual demand currents: export certification requirements pulling premium grades toward Asian markets, while domestic consumption patterns concentrate volume in cost-efficient formats. Understanding these segment boundaries clarifies where capital deployment and regulatory compliance investments yield differentiated returns.
Product Type:
Beef and poultry dominate export ledgers, while pork and lamb serve distinct domestic and premium niche positions with varying geographic reach.
- Beef:Grass-fed and grain-finished categories carry divergent certification requirements under FSANZ and Codex Alimentarius protocols. Queensland feedlots supply the bulk of export-certified volume, with grass-fed premiums commanding position in Japanese and Korean procurement tenders.
- Poultry:Intensive farming scale delivers cost structures that dominate domestic retail and foodservice channels. New South Wales processing clusters around Sydney generate the volume concentration necessary for national distribution efficiency.
- Pork:Smaller herd scale relative to beef and poultry constrains export competitiveness; domestic consumption absorbs nearly all production through fresh and processed retail formats.
- Lamb:Seasonal production patterns and premium positioning limit volume but sustain margin pools in Middle Eastern export markets and domestic foodservice.
Beef commands the established base. The steepest expansion runs through poultry.
Distribution Channel:
Channel selection determines margin capture, with direct relationships compressing intermediary costs while wholesale retains relevance for fragmented buyer bases.
- Retail:Supermarket chains specify welfare and sustainability credentials that cascade back to processor procurement policies. Coles and Woolworths dominate volume, with private-label expansion squeezing branded supplier margins.
- Foodservice:Direct processor relationships are displacing traditional wholesale intermediaries as institutional buyers consolidate procurement. Healthcare and education sectors in Sydney and Melbourne metropolitan areas now specify multi-year supply agreements with traceability requirements.
- E-commerce:Subscription and direct-to-consumer models are gaining traction in premium grass-fed and specialty product tiers, though cold-chain logistics constrain geographic reach.
- Wholesale:Traditional intermediaries retain relevance for independent butchers and smaller foodservice operators lacking scale for direct processor negotiations.
Retail channels absorb the volume base. Foodservice direct procurement is climbing the fastest.
End User:
User categories exhibit diverging specification intensity, with institutional buyers tightening sustainability criteria while household price sensitivity sustains commodity volume.
- Households:Price elasticity dominates purchasing decisions at retail, though premium tier penetration is expanding in metropolitan markets. Weekly consumption patterns concentrate demand in fresh and frozen formats.
- Restaurants:Menu cost pressures favor poultry for volume applications, with beef and lamb reserved for premium positioning. Sustainability credentials are increasingly visible in tender evaluations for chain procurement.
- Food Manufacturers:Ready-meal and sports nutrition verticals specify clean-label inputs that pull grass-fed and antibiotic-free volumes through Queensland and New South Wales processing clusters.
- Institutions:Healthcare and aged-care facilities are expanding dairy-derived protein utilization alongside traditional meat proteins, with clinical nutrition formulations penetrating hospital channels.
Households anchor volume absorption. Food manufacturers are gaining share fastest.
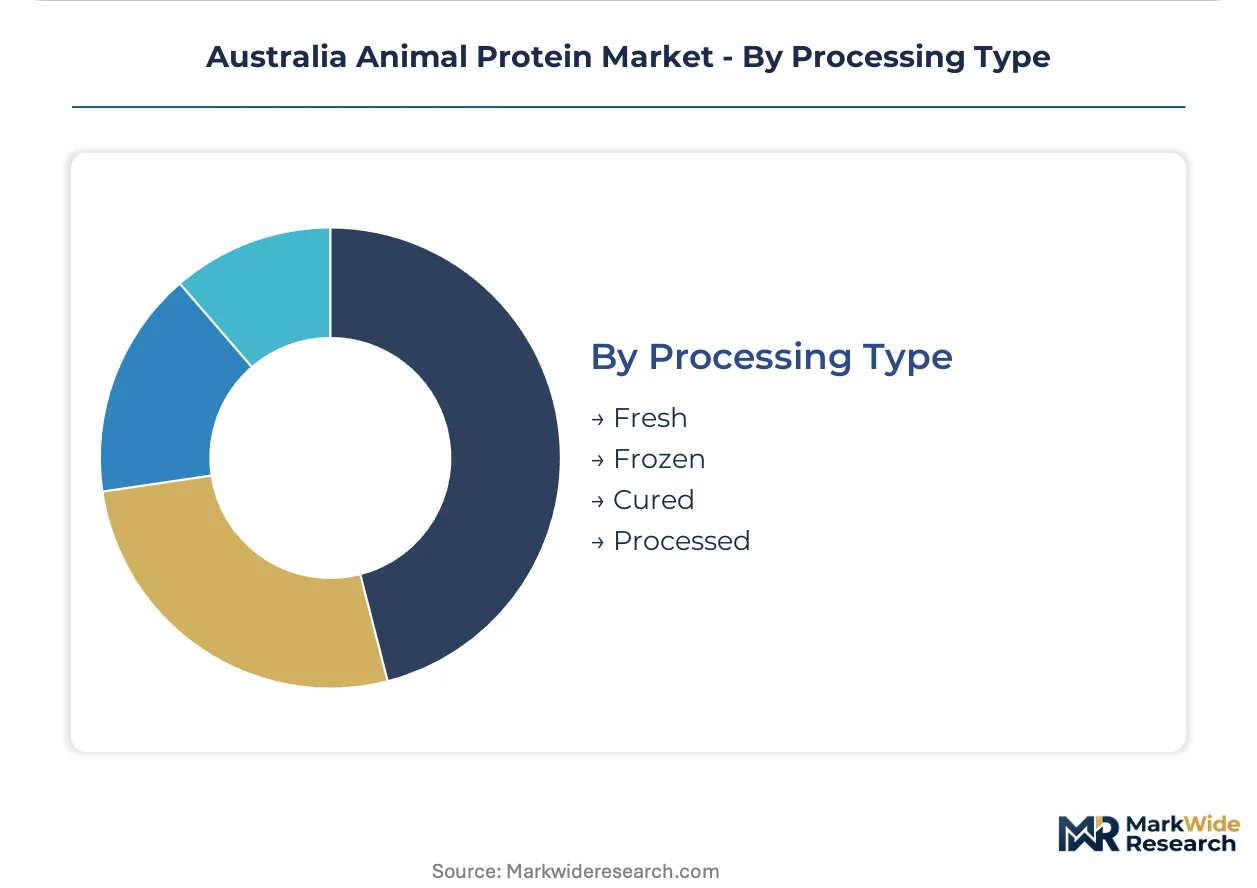
Processing Type:
Processing intensity correlates with shelf-life requirements and value-add capture, with fresh formats commanding retail premiums while cured and processed formats serve manufacturer input demand.
- Fresh:Short shelf-life constraints concentrate production near population centers, with Brisbane and Sydney corridors dominating cold-chain distribution. Retail margins peak in this category.
- Frozen:Extended storage enables geographic arbitrage and export buffer capacity, with port-proximate cold storage infrastructure determining competitive positioning.
- Cured:Extended shelf-life formats serve food manufacturer demand for ready-meal inputs, with sodium reduction trends reshaping formulation requirements.
- Processed:Further-processed categories including portioned and value-added products capture margin through labor substitution, with automation investments compressing unit costs.
Fresh formats retain the volume base. Processed value-added categories are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Brisbane's refrigerated export terminals anchor Queensland's dominance in chilled beef shipments to Northeast Asian markets. Eastern seaboard cold-chain infrastructure concentrates slaughter and processing capacity within a 500-kilometer radius of Sydney and Brisbane.
New South Wales
Sydney metropolitan foodservice procurement offices drive demand for premium grass-fed certification and antibiotic-free supply chains. Food Standards Australia New Zealand (FSANZ) maximum residue limit enforcement shapes processor investment in rapid diagnostic laboratory capacity. The Riverina feedlot corridor around Wagga Wagga concentrates grain-finishing infrastructure that supplies export-certified beef volumes.
Queensland
Brisbane processing clusters capture scale economies in byproduct rendering and cold storage that underpin national distribution efficiency. The Australian Department of Agriculture, Fisheries and Forestry administers export registration protocols that determine market access eligibility for shipments to Japan and Korea. Darling Downs feedlots supply the bulk of grain-finished cattle that meet Codex Alimentarius certification requirements for premium export tiers.
Victoria
Melbourne's institutional procurement offices in healthcare and education sectors specify multi-year supply agreements with traceability requirements that bypass traditional wholesale channels. Safe Work Australia mandates processing facility automation standards that influence capital allocation toward robotics and ergonomic redesign. Gippsland dairy processing infrastructure supports whey and casein protein isolate production for clinical nutrition formulations.
Western Australia
Perth's proximity to Asian export shipping lanes offers freight cost advantages for chilled beef shipments to China and Southeast Asia. State-based environmental regulations governing feedlot runoff and methane accounting remain less developed than eastern jurisdictions, accelerating greenfield project timelines. The Peel region and Albany corridor host emerging feedlot capacity that diversifies geographic supply concentration risk.
South Australia
Adelaide's food manufacturing sector absorbs lamb and pork volumes for processed meat applications and ready-meal inputs. The state's grain belt supplies feed wheat and barley that reduce input cost exposure to eastern seaboard transport bottlenecks. Murray Bridge processing facilities leverage port access through Port Adelaide for Middle Eastern lamb export consignments.
Australia Animal Protein Market Competitive Environment
Concentration sits with diversified ingredient technology groups and dairy cooperative structures that span protein streams beyond traditional meat categories. The market structure tiers between multinational flavor and texture solution providers, Australasian dairy cooperatives with whey processing capabilities, and specialized nutritional isolate producers. Strategic moves center on backward integration into captive dairy protein supply and automation technology partnerships that satisfy FSANZ traceability mandates.
Among Irish and Australasian ingredient specialists, Kerry Group plc, Fonterra Co-operative Group Limited, and Noumi Limited occupy positions that exemplify divergent competitive archetypes. Kerry Group plc represents the multinational flavor and texture technology tier that supplies differentiated solutions to Australian meat processors. Fonterra Co-operative Group Limited anchors the dairy cooperative structure with integrated whey and casein protein streams that compete alongside traditional meat proteins. Noumi Limited exemplifies the domestic nutritional specialist archetype focused on whey protein isolates for sports and clinical nutrition channels.
| Leading Market Players |
|---|
| Kerry Group plc |
| Freedom Foods Group Limited |
| Fonterra Co-operative Group Limited |
| Gelita AG |
| Royal FrieslandCampina NV |
| Saputo Inc. |
| Glanbia PLC |
| Noumi Limited |
| Groupe Lactalis |
| Others |
Value Chain & Pricing Dynamics
Codex Alimentarius certification alignment gates both processor qualification and price tier access for Australian beef and poultry exports, compressing supply eligibility while widening premiums for compliant operators. FSANZ maximum residue limit enforcement creates parallel domestic qualification barriers that stratify pricing power across processing establishments.
Pricing Analysis
Volume-discount tiering structures dominate procurement contracts between major retail chains and Queensland-New South Wales processors, with three-tier pricing separating grass-fed premium from grain-finished standard and commodity economy grades. Price differentiation rests on certification grade and geographic delivery cost to Asian export terminals. Cost compression in economy tiers is intensifying because feed grain price volatility transfers directly to feedlot margin structures. Household retail segments exhibit highest price sensitivity, while institutional foodservice buyers in Sydney and Melbourne demonstrate lowest sensitivity when sustainability credentials are specified.
Supply Chain Analysis
Strategic stockpiling of frozen buffer inventory dominates over just-in-time fresh distribution due to seasonal production patterns and export shipment scheduling requirements. Geographic supply concentrates in Queensland, New South Wales, and Victoria, with Western Australia emerging as diversification geography. Raw material dependencies center on wheat and sorghum feed grains, live cattle procurement, and veterinary pharmaceutical inputs. Single-source vulnerability runs through eastern seaboard cold-chain infrastructure concentration. Distribution feeds from processor direct relationships into retail chain distribution centers and institutional procurement offices, bypassing traditional wholesale intermediaries for volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, where FSANZ export registration and Codex Alimentarius compliance create switching costs that lock in established processor-buyer relationships.
For Market Incumbents: Compound certification advantages by deepening backward integration into captive feedlot supply and automation technology partnerships that satisfy real-time traceability mandates. Defend against emerging Western Australia greenfield entrants by securing multi-year supply agreements with institutional buyers before geographic diversification accelerates. Prioritize laboratory capacity investment as FSANZ expands residue testing protocols. For New Entrants and Emerging Players: Differentiate on Western Australia geographic positioning with lower land costs and reduced methane accounting compliance layers relative to eastern jurisdictions. Target clinical nutrition channel development where dairy-derived protein isolates from whey and casein streams penetrate hospital and aged-care formulations beyond traditional meat protein positioning. Pursue direct processor relationships with Perth-based healthcare procurement offices as entry vector. For Investors and Strategic Acquirers: FSANZ tightening of maximum residue limit enforcement reshapes the acquisition landscape toward processors with in-house laboratory infrastructure and rapid diagnostic capabilities. Long-term viability favors operators with integrated feedlot-to-processing traceability systems that satisfy both domestic and premium export buyer specifications. Acquisition target archetype: mid-scale processors with underutilized capacity and export registration eligibility. Signal to watch: state-based environmental regulation implementation timelines affecting feedlot licensing velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Feedlot Supply | Secures grain-finished cattle volumes that meet Codex Alimentarius certification requirements for Japanese and Korean export tiers. |
| Blockchain-Enabled Carcass Tracking Deployment | Compresses audit timelines from weeks to hours while satisfying FSANZ traceability mandates and retail chain procurement specifications. |
| Western Australia Greenfield Capacity Expansion | Captures freight cost advantages to Asian shipping lanes with less developed environmental compliance frameworks accelerating project timelines. |
| Clinical Nutrition Channel Development | Extends whey and casein protein isolate positioning beyond sports nutrition into hospital and aged-care formulation partnerships. |
| Automation Technology Partnership Formation | Addresses Safe Work Australia facility standards while reducing labor-dependent processing costs in family-owned abattoir operations. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs export records, FSANZ establishment registrations, and Australian Bureau of Agricultural and Resource Economics data. Primary interviews incorporated feedlot operators, red meat processing facility managers, retail chain category buyers, and foodservice procurement directors across Queensland, New South Wales, Victoria, and Western Australia. Secondary validation drew from Australian Department of Agriculture export certification databases, Codex Alimentarius standards documentation, and state environmental regulation filings. Bottom-up volume modeling triangulated against top-down consumption expenditure estimates.
Segmentation dimensions modeled span product type, processing type, distribution channel, and end-user category across the projection horizon. Beef and poultry volume trajectories incorporated feedlot capacity utilization rates, grain input cost assumptions, and export market access eligibility under evolving biosecurity protocols. CAGR derivation weighted historical production growth patterns against regulatory inflection points including methane accounting implementation timelines and residue limit enforcement expansion. Industry-specific forecast inputs captured cold-chain infrastructure investment pipelines and institutional procurement policy shifts toward sustainability-specified supply agreements.
Material uncertainties — feed grain commodity price volatility, drought and flood frequency in eastern production corridors, and state regulatory divergence on emissions accounting — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued Codex Alimentarius alignment and stable Asian market access conditions. Revision becomes warranted when biosecurity protocol changes or trade policy shifts alter export certification eligibility thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Fish Feed Market
Agriculture and Agri Products
Clover Leaf Oil Market
Agriculture and Agri Products
Rutin Market
Agriculture and Agri Products
Global Quail Eggs Market
Agriculture and Agri Products
Palm Kernel Expeller Market
Agriculture and Agri Products
Egypt Compound Feed Market
Agriculture and Agri Products
Lucerne Market
Agriculture and Agri Products
Animal Derivatives Market
Agriculture and Agri Products
Arnica Oil Market
Agriculture and Agri Products
Middle East Animal Protein Market
Agriculture and Agri Products
Forage Feed Market
Agriculture and Agri Products
North America Compound Feed Market
Agriculture and Agri Products
Asia Pacific Poultry Feed Market
Agriculture and Agri Products
Saudi Arabia Alfalfa Market
Agriculture and Agri Products
Asia-Pacific Compound Feed Market
Agriculture and Agri Products
Brazil Compound Feed Market