
 Russia Compound Feed Market | 2026-2036
Russia Compound Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Compound Feed Market Analytics
The gap between premium additive-enhanced formulations and basic commodity blends is consolidating as Russian livestock operations scale up. Cherkizovo Group leverages captive feed mills to control input costs across its poultry and pork divisions. Cargill Inc. sustains its position through imported vitamin premix expertise and technical advisory services to mid-sized farms. Alltech Inc. differentiates by specializing in yeast-based additives that improve rumen efficiency for cattle ranchers.
Compound feed denotes industrially blended rations combining grains, protein meals, fats, oils, vitamins, and minerals into nutritionally complete or supplementary formulations, typically pelleted or mash-processed to specified moisture and particle-size tolerances, serving commercial livestock operations as the primary input for controlled growth rates and feed conversion ratios. Complete feed dominates volume as integrated poultry and swine operations demand turnkey nutritional solutions, while premix feed captures disproportionate margin pools due to technical complexity and import dependency for micronutrient sourcing. Aquaculture end users represent the fastest-growing demand channel as Russian fish farming expands in the Far East and Black Sea basins.
Russia's Federal Service for Veterinary and Phytosanitary Surveillance (Rosselkhoznadzor) enforces feed safety certification and import quarantine rules that restrict certain genetically modified ingredient flows, while national technical regulations (GOST standards) mandate labeling and compositional disclosures. The Central Bank of Russia's monetary policy indirectly shapes working capital cycles for feed distributors and grain traders. Stakeholders must monitor how import substitution mandates evolve for amino acids and vitamins, as domestic synthesis capacity expansion will reshape procurement economics and supplier selection criteria.
Market Dynamics
Rosselkhoznadzor's feed safety certification mandates are compressing procurement timelines as Russian livestock operators rebuild supply chains around GOST-compliant sourcing. The Central Bank's monetary stance shapes working capital cycles for grain traders and feed distributors.
Growth Catalysts
- Livestock sector modernization:Poultry and swine operations are scaling up compound feed procurement as integrated agroholdings consolidate production capacity in the Central Federal District.
- Rosselkhoznadzor enforcement:Mandatory feed safety protocols elevate quality benchmarks and filter out informal suppliers from commercial channels.
- Aquaculture expansion:Fish farming operations in the Far East and Black Sea basins generate new demand for species-specific formulations.
Market Restraints
- Micronutrient import dependency:Domestic synthesis capacity for amino acids and vitamins remains limited, exposing processors to currency volatility and supply disruption.
- GMO ingredient restrictions:Rosselkhoznadzor quarantine rules block certain genetically modified feed flows, constraining formulation flexibility and input sourcing.
- Grain price volatility:Wheat and barley constitute the bulk of compound feed volume, tying processor margins to weather-driven harvest fluctuations.
Strategic Opportunities
- Import substitution mandates:Federal incentives for domestic vitamin and amino acid production will reshape supplier selection criteria and procurement economics.
- Yeast-based additive adoption:Cattle ranchers in the Volga Federal District are testing rumen efficiency enhancers as a pathway to reduce grain intensity.
- Premix technical services:Mid-sized farms seek advisory support for micronutrient optimization, creating margin pools beyond commodity blending.
Industry Challenges
- Veterinary certification timelines:Rosselkhoznadzor documentation requirements delay product launches and extend inventory holding periods for distributors.
- Legacy equipment retrofit costs:Pelleting and mash-processing lines require capital investment to meet updated GOST moisture and particle-size tolerances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Compound Feed Market |
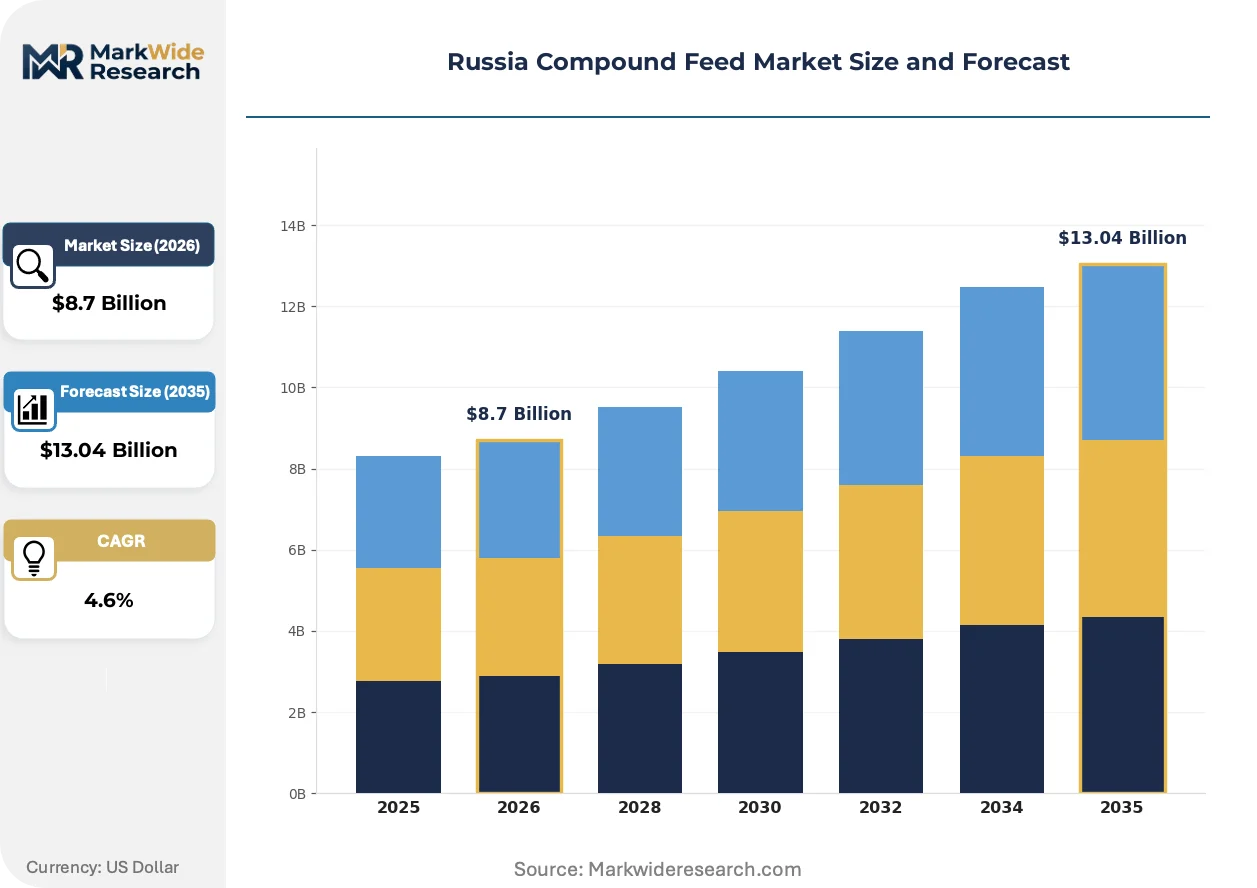
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Complete Feed, Supplementary Feed, Concentrate Feed, Premix Feed End User: Poultry Farmers, Swine Producers, Cattle Ranchers, Aquaculture Ingredient Type: Grains, Protein Meals, Fats & Oils, Vitamins & Minerals Distribution Channel: Direct Sales, Retail Outlets, Online Sales, Dealers |
| Companies Covered | Charoen Pokphand Foods, Cherkizovo Group, Cargill Inc., Kent Feeds, Hueber Feed LLC, SHV (Nutreco NV), Alltech Inc., ForFarmers, Archer Daniels Midland Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Compound Feed Market Evolving Landscape
Precision formulation technologies are reshaping how Russian feed processors balance cost control against nutritional performance. Digital tools now penetrate quality assurance and supply planning functions.
Near-infrared spectroscopy is absorbing quality control workflows across compound feed mills. Large integrated poultry operations deploy inline NIR systems to verify protein and moisture content in real time. This technology is absorbing the role of laboratory batch testing and compressing release-to-market cycles from days to hours.
Rosselkhoznadzor's updated GOST labeling mandates force compositional disclosure down to additive levels. Feed manufacturers must reconfigure packaging lines and database systems to capture traceability data. Premix suppliers face the steepest compliance burden due to micronutrient complexity and import documentation requirements.
Long-term supply agreements are displacing spot market purchasing among Central Federal District agroholdings. Procurement teams lock in grain volumes six to twelve months forward to hedge against ruble volatility. This shift concentrates negotiating power with large integrated operators and squeezes margin flexibility for independent mills serving fragmented pork and dairy farms.
Russia Compound Feed Market Segmentation
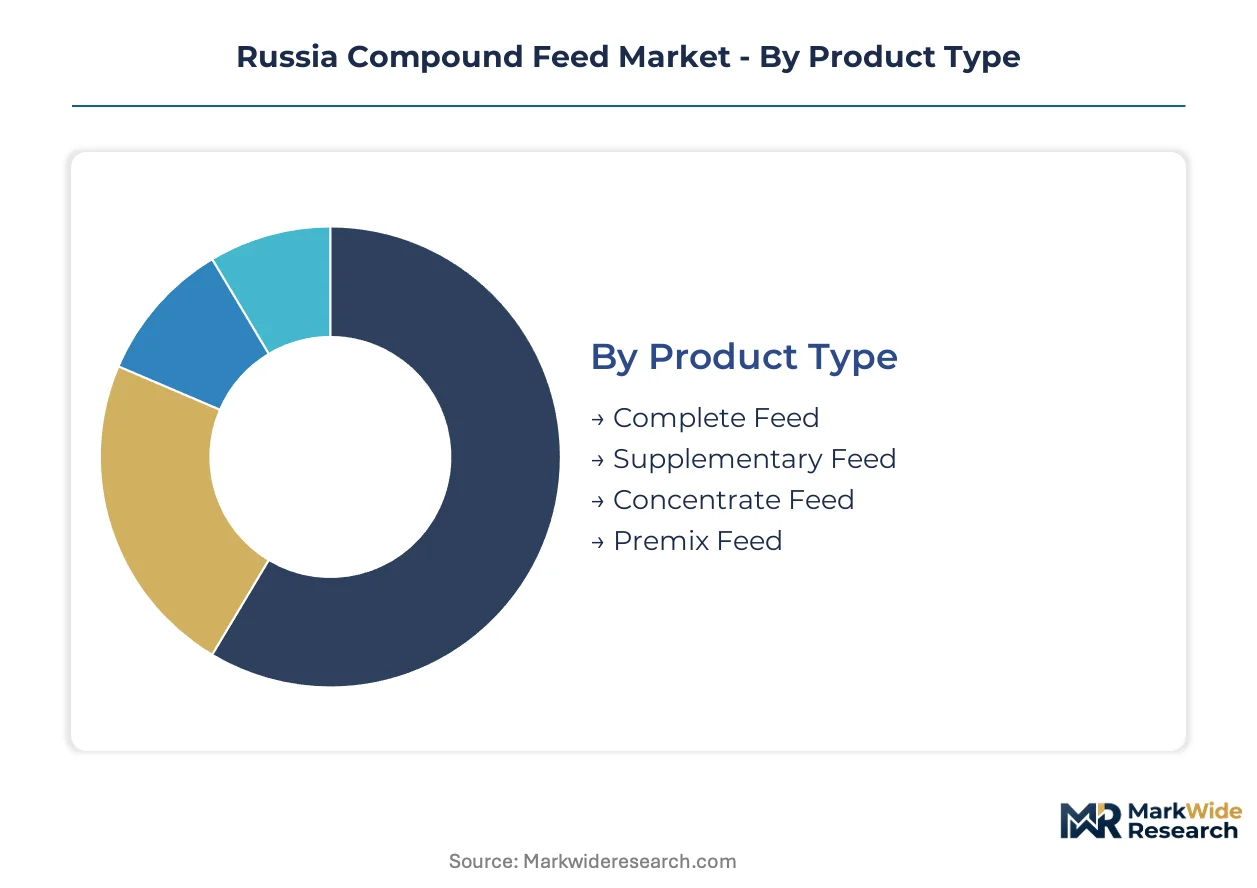
Segmentation reveals how capital deployment and regulatory compliance reshape procurement patterns across Russian livestock operations. Distinct product tiers, end-use channels, and distribution pathways command divergent margin structures and working capital intensity.
Product Type:
Capital intensity escalates sharply from commodity blending to precision micronutrient synthesis, with premix manufacturing demanding specialized laboratory infrastructure and import-linked supply chains.
- Complete Feed:Industrially formulated rations deliver turnkey nutritional solutions with specified protein, energy, and mineral profiles in pelleted or mash form. Central Federal District poultry agroholdings source complete feed to streamline procurement and eliminate on-farm mixing labor.
- Premix Feed:Concentrated micronutrient blends requiring precise dosing equipment and technical advisory support for proper integration. Rosselkhoznadzor's GOST labeling mandates impose traceability documentation burdens that favor suppliers with captive laboratory capabilities.
- Supplementary Feed:Nutritional add-ons designed to complement base rations rather than replace them, typically deployed by mid-sized dairy operations.
- Concentrate Feed:High-protein, high-energy formulations mixed on-farm with locally sourced roughage, common among Volga Federal District cattle ranchers.
Complete feed absorbs the bulk of installed capacity; premix feed is expanding most quickly.
End User:
Customer scale and integration level determine formulation complexity, with vertically integrated operations demanding species-specific precision while fragmented producers prioritize cost minimization.
- Poultry Farmers:The dominant demand channel, with integrated broiler and layer operations specifying amino acid-optimized rations for feed conversion efficiency. Cherkizovo Group and comparable agroholdings in the Central Federal District drive volume procurement through captive mill relationships.
- Aquaculture:Species-specific formulations for salmonids, carp, and sturgeon operations in the Far East and Black Sea basins. Fish farmers require floating and sinking pellet variants with precise lipid profiles, creating formulation complexity that commands technical service premiums.
- Swine Producers:Operations ranging from large-scale commercial units to backyard farms, with disease pressure driving demand for acidifier-enhanced formulations.
- Cattle Ranchers:Beef and dairy operations in the Volga and Southern Federal Districts, increasingly testing yeast-based rumen efficiency additives to reduce grain intensity.
Poultry farmers absorb the bulk of installed capacity; aquaculture is gaining share fastest.
Ingredient Type:
Input sourcing geography and price volatility exposure differentiate ingredient strategies, with domestic grain abundance contrasting against import-dependent micronutrient vulnerability.
- Grains:Wheat, barley, and corn constitute the caloric foundation, with Black Sea harvest fluctuations directly compressing processor margins. Central Federal District mills maintain six-to-twelve-month forward contracts to hedge currency and weather risk.
- Vitamins & Minerals:Micronutrient premixes rely heavily on imported synthesis, exposing formulators to ruble volatility and Rosselkhoznadzor quarantine documentation requirements.
- Protein Meals:Soybean and sunflower meals provide amino acid density, with GMO restrictions constraining certain import flows.
- Fats & Oils:Energy-dense additives including tallow, vegetable oils, and fish oil for aquaculture applications.
Grains absorb the bulk of installed capacity; vitamins and minerals command the steepest price premiums.
Distribution Channel:
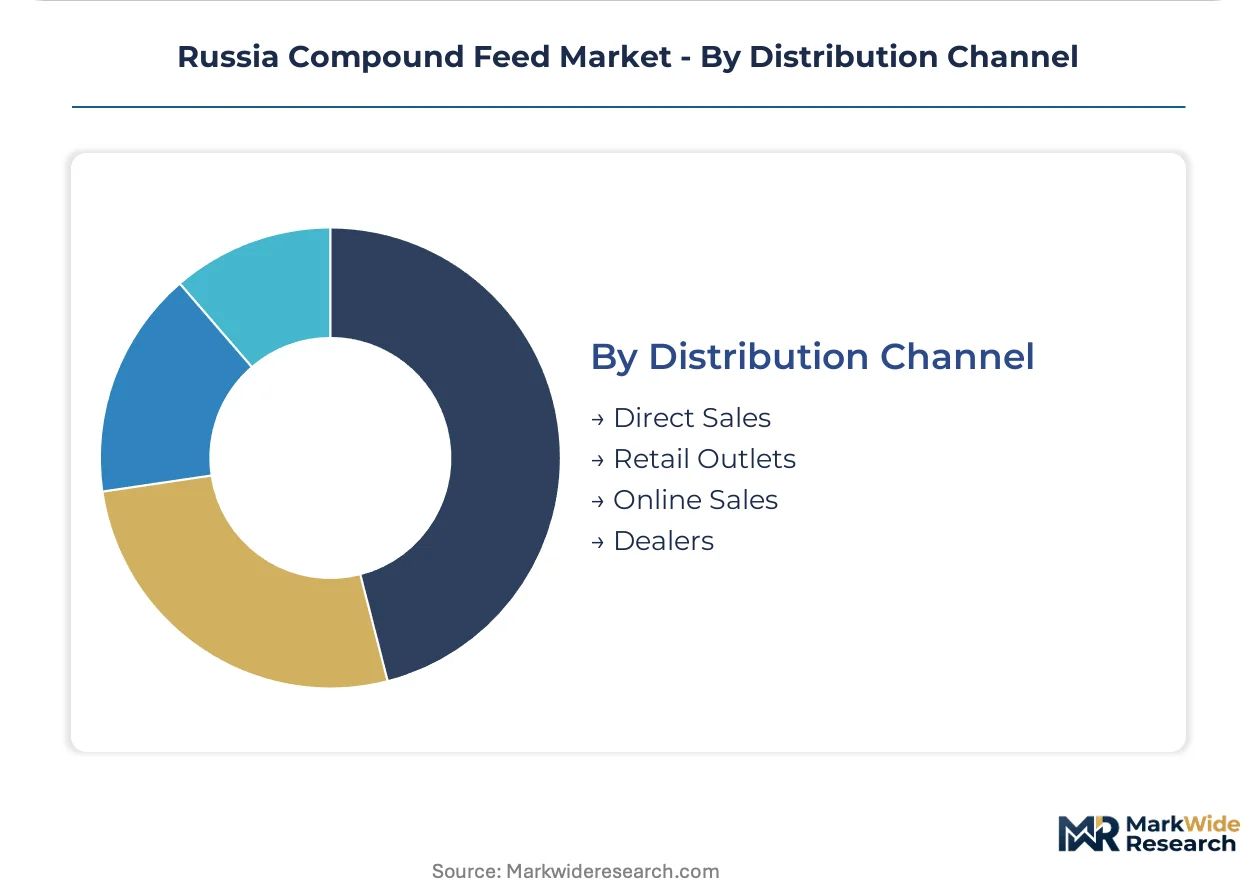
Channel selection reflects customer scale and technical service requirements, with large operators bypassing intermediaries while fragmented farms rely on dealer networks for credit and logistics.
- Direct Sales:Long-term supply agreements between integrated agroholdings and captive or dedicated feed mills, concentrating negotiating power with volume purchasers.
- Dealers:Regional distributors providing credit terms, last-mile delivery, and technical advisory to mid-sized pork and dairy farms lacking procurement sophistication.
- Retail Outlets:Agricultural supply stores serving smallholder and backyard livestock operations with bagged product.
- Online Sales:Emerging channel for premix and additive procurement, constrained by Rosselkhoznadzor documentation requirements for veterinary-certified products.
Direct sales absorb the bulk of installed capacity; dealer networks retain relevance in fragmented dairy and pork geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Moscow anchors Russia's compound feed procurement as integrated agroholdings cluster within the Central Federal District, driving volume concentration and quality standard enforcement across the national market.
Central Federal District
Poultry agroholdings in Moscow Oblast and surrounding regions consume the bulk of compound feed output as livestock operations modernize. Rosselkhoznadzor's GOST certification mandates filter informal suppliers from commercial channels. Cherkizovo Group operates captive feed mills across this corridor to control input costs.
Volga Federal District
Cattle ranchers in this region test yeast-based rumen efficiency additives to reduce grain intensity in beef and dairy operations. The national veterinary regulator enforces feed safety protocols that elevate quality benchmarks for local processors. Samara and Kazan host mid-sized feed mills serving fragmented pork farms through dealer networks.
Southern Federal District
Grain abundance in Krasnodar Krai and Rostov Oblast underpins feed processor margins, though weather-driven harvest fluctuations create volatility. Import substitution mandates for amino acids and vitamins reshape procurement economics as domestic synthesis capacity expands. Large integrated operators in this corridor lock in six-to-twelve-month forward grain contracts.
Far East Federal District
Aquaculture operations in Primorsky Krai generate demand for species-specific formulations as Russian fish farming scales up. Rosselkhoznadzor quarantine rules constrain certain genetically modified ingredient flows, limiting formulation flexibility. Vladivostok serves as the distribution hub for floating and sinking pellet variants.
Northwestern Federal District
Dairy operations around Saint Petersburg source supplementary feed to complement base rations, prioritizing cost minimization over precision formulation. The Central Bank's monetary stance shapes working capital cycles for regional feed distributors. Legacy equipment retrofit costs challenge pelleting lines to meet updated moisture tolerances.
Russia Compound Feed Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technical service and micronutrient sourcing capabilities, with premix specialists commanding disproportionate returns. The vendor base stratifies into three tiers: integrated agroholdings with captive mills, multinational premix suppliers leveraging import expertise, and regional commodity blenders serving fragmented farms. Two archetypes dominate: vertically integrated livestock operators controlling upstream feed supply, and technical advisory specialists monetizing formulation complexity. Capacity consolidation and import substitution partnerships represent the dominant competitive moves reshaping supplier selection criteria.
Within the integrated agroholding tier, Cherkizovo Group exemplifies backward integration into captive feed production. Among multinational premix specialists, Cargill Inc. and Alltech Inc. occupy positions anchored in imported vitamin expertise and yeast-based additive technology respectively. These three entities represent distinct strategic archetypes: domestic vertical integration, global supply chain leverage, and specialized rumen efficiency solutions.
| Leading Market Players |
|---|
| Charoen Pokphand Foods |
| Cherkizovo Group |
| Cargill Inc. |
| Kent Feeds |
| Hueber Feed LLC |
| SHV (Nutreco NV) |
| Alltech Inc. |
| ForFarmers |
| Archer Daniels Midland Company |
| Others |
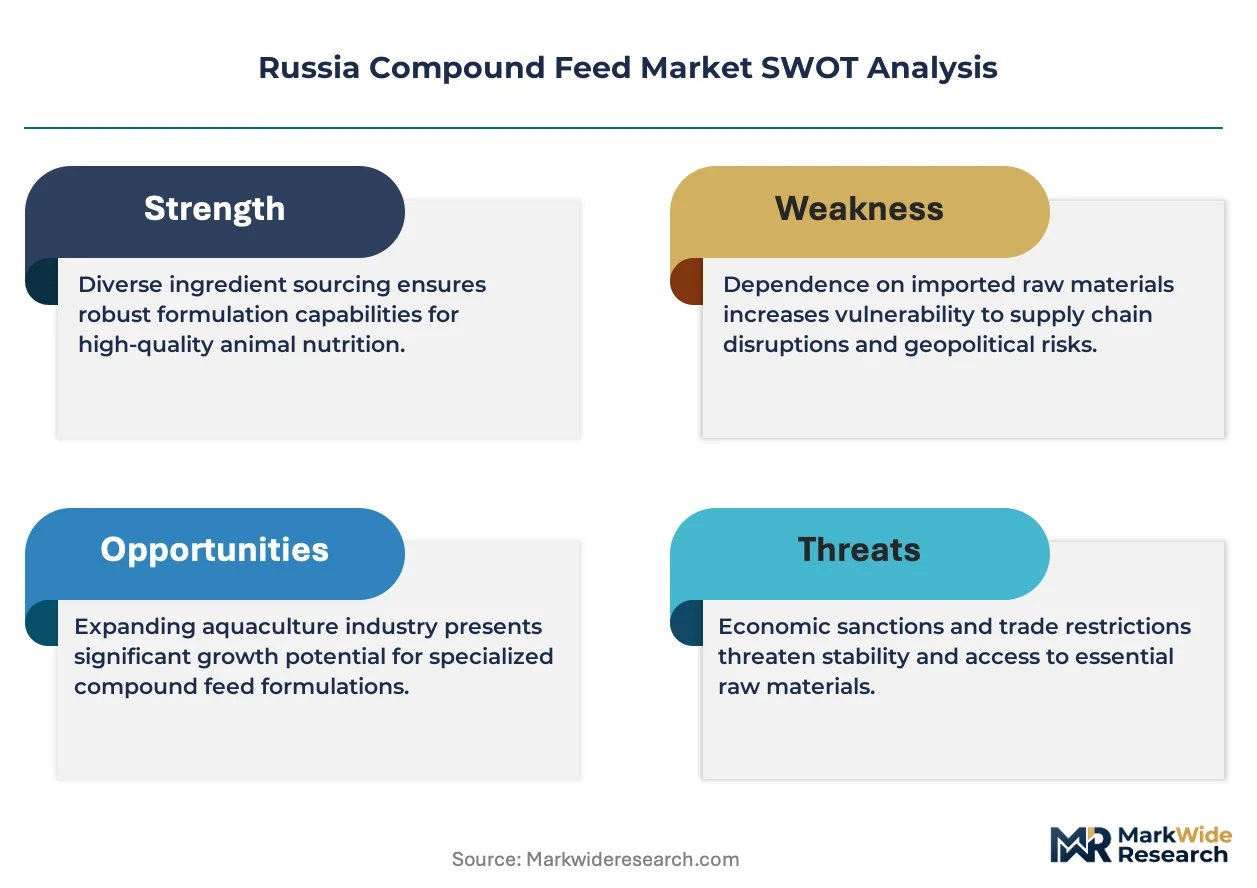
Value Network & Pricing Analysis
Premium-additive formulations and commodity grain blends diverge sharply in procurement economics as Russian livestock operators scale. This bifurcation concentrates pricing power with premix specialists commanding technical service premiums while grain traders compete on volume throughput. Rosselkhoznadzor certification requirements filter informal suppliers from commercial channels, compressing margin flexibility for independent mills.
Pricing Analysis
Yield-linked pricing anchors premix contracts as cattle ranchers and poultry agroholdings tie payments to feed conversion ratios and weight gain outcomes. Three-tier pricing structure across premium, standard, and economy levels separates GOST-certified complete feeds from basic commodity blends and uncertified regional products. Pricing pressure stems from ruble volatility against vitamin and amino acid import costs, squeezing processor margins. Smallholder dairy operations in the Northwestern Federal District exhibit highest price sensitivity, while integrated Central Federal District poultry holdings prioritize conversion efficiency over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese and European vitamin synthesis capacity, where Rosselkhoznadzor quarantine documentation creates procurement bottlenecks. Domestic wheat and barley from Krasnodar Krai and Rostov Oblast feeds from Black Sea harvests, while protein meals draw from Argentine and Brazilian soybean flows. Tariff exposure on micronutrient imports compounds currency risk for premix formulators. Distribution runs through direct long-term agreements between captive mills and agroholdings, with dealer networks retaining relevance in fragmented pork and dairy geographies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's compound feed sector is consolidating as Rosselkhoznadzor certification mandates and import substitution pressures force subscale mills toward exit. Federal incentives for domestic amino acid synthesis will accelerate this filtering mechanism.
For Market Incumbents: Acquire laboratory and premix formulation capabilities to capture technical service margins as import substitution reshapes supplier economics. Cherkizovo Group's captive mill model demonstrates how upstream control over grain procurement insulates against Black Sea harvest volatility. Invest in NIR spectroscopy infrastructure to compress quality assurance cycles and defend position against multinational premix specialists.
For New Entrants and Emerging Players: The mid-market gap between economy-grade commodity blends and premium premix services offers white-space opportunity in yeast-based rumen efficiency additives for Volga Federal District cattle ranchers. Target aquaculture formulations in Primorsky Krai as fish farming scales with limited incumbent technical presence. Lead with species-specific advisory services rather than commodity volume to bypass entrenched grain trader relationships.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated agroholdings seeking backward integration into feed supply. The five-to-ten year viability window favors premix specialists with captive laboratory infrastructure and Rosselkhoznadzor certification track records. Watch federal import substitution disbursement flows as the inflection signal for domestic synthesis capacity buildout timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Procurement | Cherkizovo Group's captive mill model locks in input cost control across poultry and pork divisions. |
| Premix Laboratory Certification Investment | Rosselkhoznadzor GOST traceability mandates favor suppliers with in-house micronutrient testing infrastructure. |
| Yeast-Based Additive R&D Partnership | Alltech's rumen efficiency technology targets grain intensity reduction for Volga Federal District cattle operations. |
| Long-Term Grain Supply Agreements | Southern Federal District processors hedge ruble volatility through six-to-twelve-month forward contracts with Krasnodar Krai elevators. |
| Aquaculture Technical Service Expansion | Far East fish farming growth creates demand for floating pellet formulation expertise with lipid profile optimization. |
Research Methodology
Rosselkhoznadzor regulatory filings, Russian Federal Customs Service trade data, and GOST standard documentation formed the secondary backbone of this analysis. Primary interviews with feed mill operations directors, procurement leads at Central Federal District agroholdings, Rosselkhoznadzor certification auditors, and veterinary nutritionists provided ground-truth validation. Bottom-up capacity estimates from regional mill surveys were triangulated against top-down grain consumption flow analysis.
Historical trendline analysis of compound feed output, grain price indices, and livestock inventory data established baseline growth patterns across the projection horizon. Segmentation modeling incorporated product type tiers, end-user species channels, ingredient sourcing geographies, and distribution pathway structures. CAGRs were derived from elasticity-adjusted demand projections tied to poultry and aquaculture expansion rates, with ruble-dollar exchange rate scenarios informing import-dependent premix cost trajectories.
Inputs from Rosselkhoznadzor enforcement records and Central Bank monetary policy statements were available through the study window; gaps in real-time micronutrient import cost data introduce uncertainty bands around premix pricing forecasts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Honeysuckle Market
Agriculture and Agri Products
Europe Guar Market
Agriculture and Agri Products
North America Bonsai Market
Agriculture and Agri Products
Date Palm Market
Agriculture and Agri Products
Palm Kernel Expeller Market
Agriculture and Agri Products
Rice-Based Products Market
Agriculture and Agri Products
North America Hemp Market
Agriculture and Agri Products
Organic Soymeal Market
Agriculture and Agri Products
Dairy Cattle Feed Market
Agriculture and Agri Products
Alfalfa Protein Concentrate Market
Agriculture and Agri Products
Global Palm Oil Market
Agriculture and Agri Products
Africa Olive Market
Agriculture and Agri Products
Alfalfa Hay Market
Agriculture and Agri Products
Mexico Compound Feed Market
Agriculture and Agri Products
France Animal Protein Market
Agriculture and Agri Products
Asia Pacific Poultry Feed Market