
 Mushroom Cultivation Market | 2026-2036
Mushroom Cultivation Market Size, Share, and Industry Trends Forecast 2026-2036
Mushroom Cultivation Market Analysis
REACH substrate-traceability rules are consolidating the cost-of-entry calculus for European mushroom growers. Monterey Mushrooms leverages vertical integration across composting and distribution to sustain margin control in North America. Monaghan Group anchors its position through specialized spawn genetics and climate-controlled Irish production. South Mill Champs competes via extensive retail and foodservice channel control across the eastern United States.
Mushroom cultivation denotes the controlled biological propagation of fungal fruiting bodies on prepared substrates such as straw, sawdust, or composted manure, typically requiring humidity of 80-95% and temperatures between 15-25°C depending on species, for commercial harvest of edible or medicinal biomass. Oyster mushrooms lead volume in developing markets due to low substrate cost and short cropping cycles, while shiitake commands premium positioning in East Asian export channels. Controlled environment technology is displacing traditional farming in high-wage economies as labor scarcity and energy efficiency standards reshape unit economics.
The EU Green Deal and REACH frameworks constrain substrate sourcing and chemical input protocols for growers serving European buyers, while the FDA and USDA enforce HACCP and organic certification standards that determine market access for US-oriented producers. China's MEE enforces dual carbon goals that are elevating energy costs for industrial-scale controlled environment operations. Stakeholders must monitor regulatory divergence between jurisdictions to decide whether to specialize in single-market compliance or absorb the capital burden of multi-standard certification.
Market Dynamics
Controlled environment agriculture technology is compressing the labor dependency of mushroom cultivation while EU REACH substrate-traceability mandates are elevating compliance capital requirements for indoor operators.
Growth Catalysts
- Functional food demand expansion:Nutraceuticals manufacturers are absorbing expanded specialty mushroom output as adaptogenic and nootropic applications broaden across wellness categories.
- EU Green Deal waste-recovery mandates:Composted agricultural residue protocols are creating circular economy incentives for substrate producers serving indoor cultivation facilities.
- China's export infrastructure:Shiitake and enoki processing clusters in Fujian and Shandong provinces are anchoring refrigerated logistics networks into East Asian retail channels.
Market Restraints
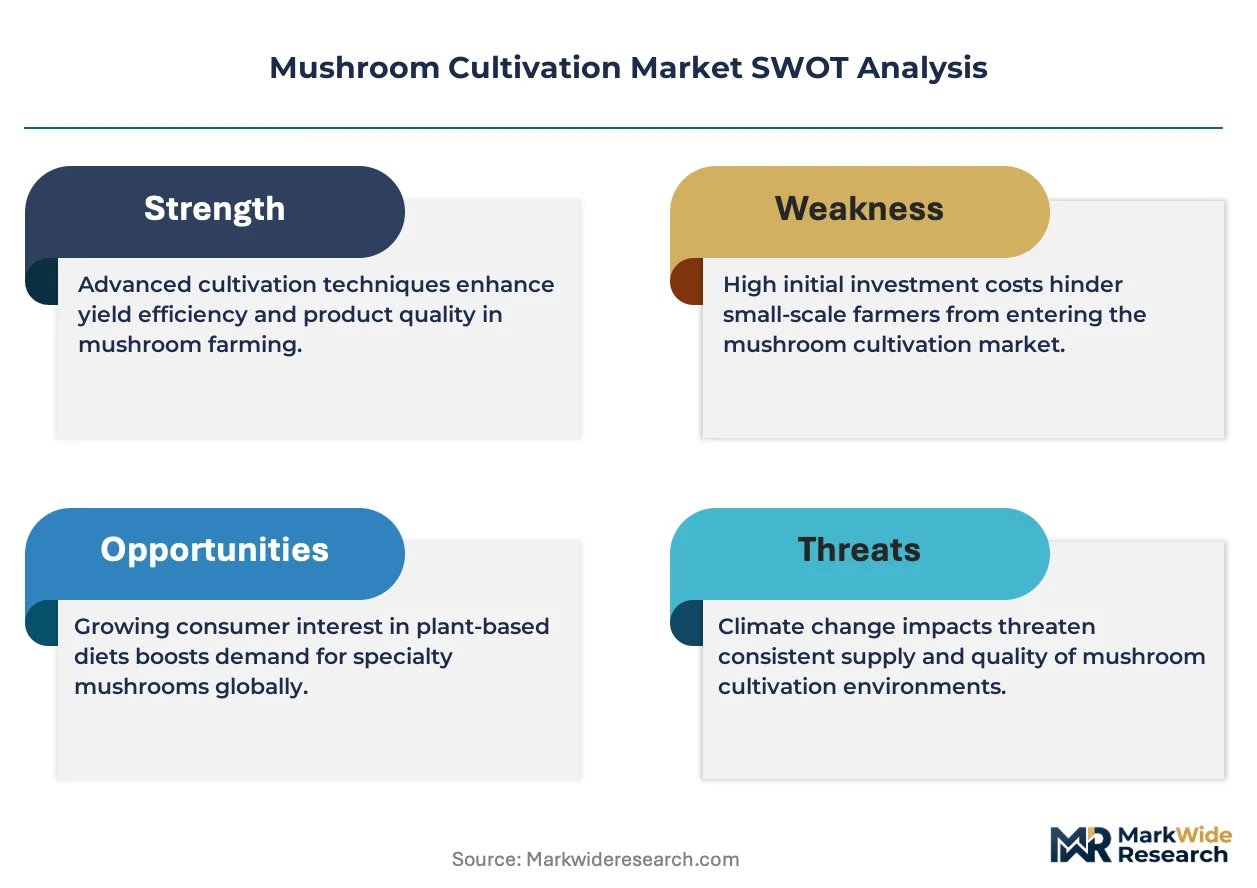
- Energy cost volatility:Climate-controlled operations face margin compression from electricity price swings affecting humidity and temperature maintenance systems.
- Spawn genetics concentration:Proprietary strain development resides with a limited number of specialized laboratories, creating supply vulnerability for commercial growers.
- Perishable logistics constraints:Fresh mushroom shelf-life limitations restrict distribution radius and create spoilage losses in underdeveloped cold-chain corridors.
Strategic Opportunities
- Medicinal extract applications:Beta-glucan and triterpene isolation for pharmaceutical adjuvants represents underexploited value-add processing beyond whole-food sales.
- Urban vertical farming integration:Rooftop and repurposed industrial facilities in high-density metropolitan zones are enabling proximity sourcing for restaurant and retail channels.
- USDA organic certification premium capture:Certified organic substrate protocols command price differentiation in North American natural food retail segments.
Industry Challenges
- Mycology technician scarcity:Specialized expertise in sterile inoculation technique and contamination control remains concentrated among aging practitioner cohorts.
- Multi-standard certification burden:Simultaneous compliance with FDA HACCP, USDA organic, and EU organic equivalence creates documentation complexity for export-oriented operators.
- Climate system capex intensity:Automated humidity and CO2 management infrastructure demands upfront capital deployment that strains mid-scale facility expansions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mushroom Cultivation Market |
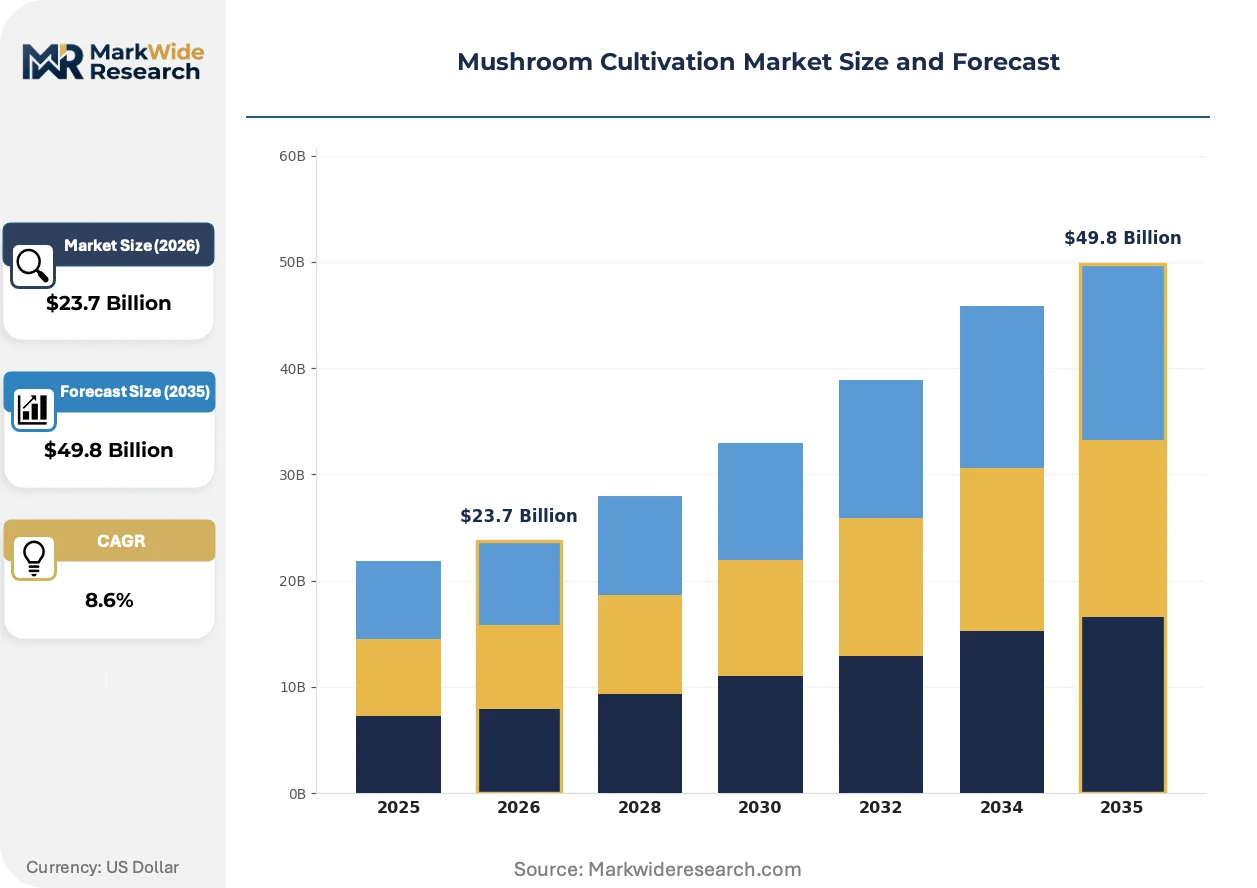
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oyster Mushrooms, Shiitake Mushrooms, Agaricus Mushrooms, Enoki Mushrooms Production Technology: Organic Farming, Hydroponics, Controlled Environment, Traditional Farming End Use: Food Processing, Pharmaceuticals, Nutraceuticals, Dietary Supplements Distribution Channel: Retail Stores, Online Sales, Wholesale Markets, Food Service |
| Companies Covered | Monterey Mushrooms, Monaghan Group, South Mill Champs, Greenyard, Bonduelle Group, Costa Group, Mycelia, Walsh Mushrooms Group, CMP Mushroom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mushroom Cultivation Market Emerging Trajectories
Biological efficiency optimization and regulatory traceability requirements are converging to reshape cultivation infrastructure investment priorities across substrate preparation through post-harvest handling.
Sensor-integrated climate management systems are consolidating operational control for multi-zone growing facilities. Large-scale indoor operators in the Netherlands and Belgium are deploying IoT-enabled environmental monitoring to compress labor inputs per kilogram of harvested biomass. This consolidation of data-driven cultivation is enabling precise strain-specific parameter adjustment that was previously dependent on experienced grower intuition.
REACH chemical input restrictions are tightening substrate sterilization protocols for European market access. ECHA substance authorization requirements are phasing out legacy fumigants used in compost preparation, forcing adoption of steam-based or biological pasteurization methods. Irish and Polish exporters are absorbing retrofit costs to maintain retail channel positioning in German and French distribution networks.
Direct procurement from cultivation cooperatives is shortening traditional wholesale intermediary chains. Foodservice distributors in metropolitan US markets are establishing volume contracts with regional growing associations, bypassing centralized produce auctions. This disintermediation concentrates price negotiation leverage with multi-location restaurant groups while compressing margins for legacy produce wholesalers dependent on spot-market purchasing.
Mushroom Cultivation Market Segmentation
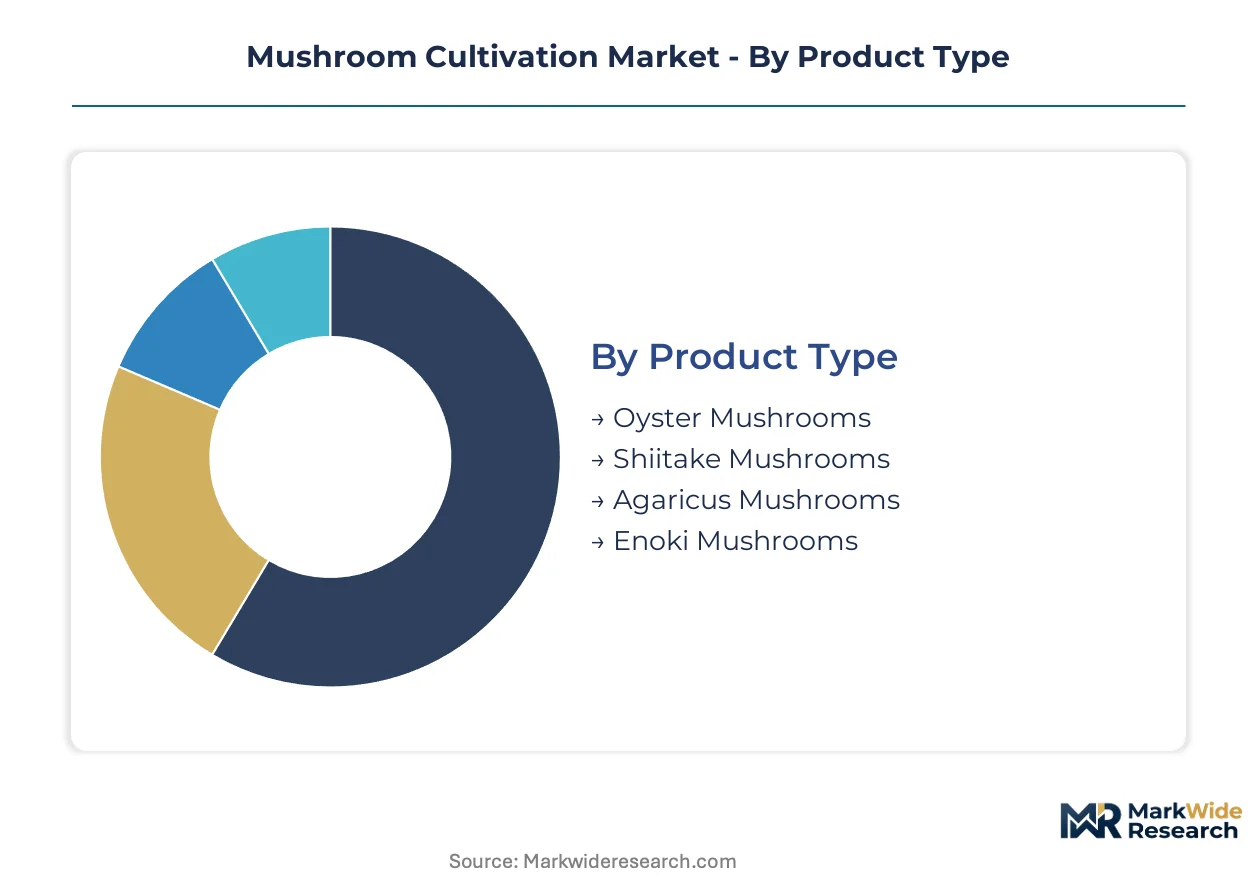
Mushroom cultivation segmentation reveals how substrate costs, climate control requirements, and shelf-life constraints partition buyers across distinct operational models. Each dimension carries specific capital intensity and regulatory exposure that determines viable scale and geographic positioning.
Product Type:
Buyers differentiate by substrate availability, cropping cycle length, and export logistics infrastructure.
- Shiitake Mushrooms:Hardwood log or sawdust block cultivation demands 6-12 month spawn run periods before fruiting. Fujian and Shandong provinces anchor export volume into Japanese and Korean retail channels where whole-cap presentation commands premium positioning.
- Oyster Mushrooms:Straw or cottonseed hull substrates enable 3-4 week cropping cycles with minimal climate infrastructure. Developing market smallholders favor this variety for low capital entry, though perishability restricts distribution radius without refrigerated logistics.
- Agaricus Mushrooms:Composted manure-based substrate requires specialized Phase I and Phase II preparation facilities. North American and European industrial operators concentrate here due to established foodservice demand for white and brown button varieties.
- Enoki Mushrooms:Bottle-cultured in climate-controlled facilities with precise CO2 management for elongated stem morphology. Chinese producers dominate export supply through automated bottle-filling and harvesting systems.
Volume sits with Agaricus in mature Western markets; growth tilts toward Shiitake in East Asian export corridors.
Production Technology:
Technology choice maps to labor cost structures and energy price volatility exposure.
- Controlled Environment:Automated humidity, temperature, and CO2 systems enable year-round production regardless of external climate. Dutch and Belgian operators deploy multi-zone IoT monitoring to compress labor inputs per kilogram harvested.
- Traditional Farming:Seasonal outdoor or simple shed cultivation leverages natural climate windows with minimal capital deployment. Indian and Vietnamese smallholders maintain cost competitiveness through family labor and local substrate sourcing.
- Organic Farming:Certified substrate protocols prohibit synthetic chemical inputs, requiring third-party audit trails. USDA and EU organic equivalence standards create documentation burden for export-oriented operators.
- Hydroponics:Nutrient film or deep water culture systems for mushroom cultivation remain niche, primarily deployed in experimental urban vertical farming installations where space constraints override substrate cost considerations.
Controlled Environment captures margin in high-wage economies; Traditional Farming retains volume in labor-abundant regions.
End Use:
End-use segmentation separates commodity food sales from extract-based value-add processing with divergent certification requirements.
- Food Processing:Canned, dried, and frozen mushroom products for retail and foodservice channels. Chinese and Polish processors dominate private-label supply to European and North American supermarket chains.
- Nutraceuticals:Whole mushroom powders and capsules positioned in functional food and wellness categories. Lion's Mane and Reishi varieties lead here, with beta-glucan content verification driving supplier selection.
- Pharmaceuticals:Isolated compounds for pharmaceutical adjuvants and therapeutic applications. Triterpene extraction from Ganoderma lucidum concentrates in specialized Chinese and Japanese facilities with GMP certification.
- Dietary Supplements:Blended formulations combining multiple mushroom species with vitamins and minerals. Direct-to-consumer brands in North America source extracts through contract manufacturers with NSF or USP verification.
Food Processing holds current volume concentration; Nutraceuticals exhibits the steepest expansion trajectory as adaptogenic positioning broadens.
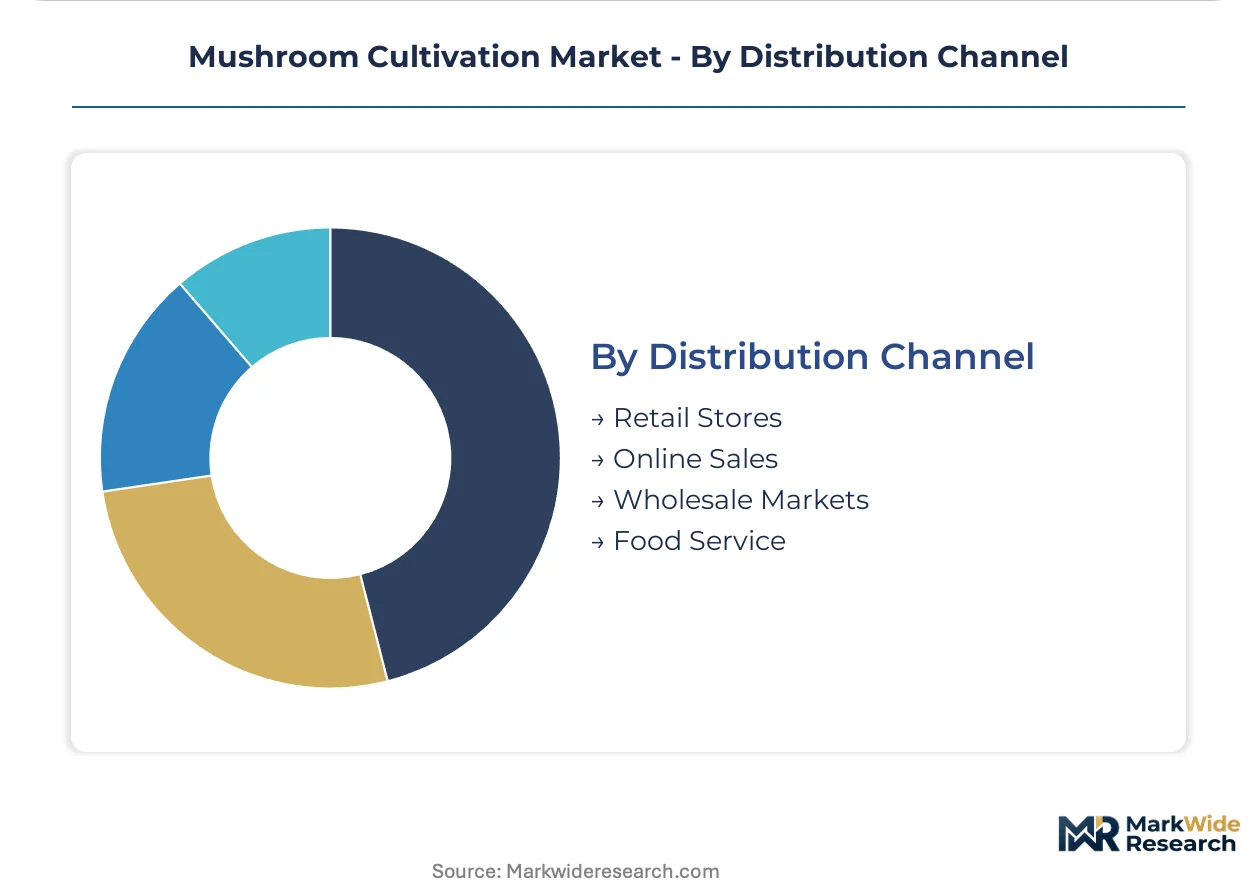
Distribution Channel:
Channel selection determines margin retention, working capital requirements, and brand exposure.
- Wholesale Markets:Centralized produce auctions and terminal markets handle bulk volume for fresh mushroom distribution. Traditional intermediaries in European and North American supply chains face margin compression from direct procurement trends.
- Food Service:Direct contracts with restaurant groups, institutional caterers, and ready-meal manufacturers. US metropolitan distributors increasingly source through regional growing cooperatives, bypassing legacy auction systems.
- Retail Stores:Supermarket produce sections and natural food chains with organic and conventional positioning. Private-label programs dominate volume, though branded specialty packs gain shelf space in premium segments.
- Online Sales:Direct-to-consumer fresh delivery and dried supplement e-commerce. Cold-chain logistics investments enable fresh mushroom subscription models in dense urban corridors.
Wholesale Markets retain volume throughput; Online Sales gains share fastest in supplement and dried product categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the dominant share of global mushroom cultivation output, with Fujian and Shandong provinces driving shiitake and enoki export volume. Four additional national markets anchor regional specialization across substrate sourcing, climate-controlled production, and nutraceutical processing.
China
Domestic consumption of shiitake and enoki varieties anchors volume, while refrigerated logistics networks from Fujian and Shandong provinces supply Japanese and Korean retail channels. The MEE enforces dual carbon goals that elevate energy costs for industrial-scale controlled environment operations. Automated bottle-filling systems in Zhangzhou cluster dominate enoki export morphology standards.
United States
Foodservice distributors in metropolitan corridors source directly from regional growing cooperatives, compressing legacy wholesale auction margins. The FDA enforces HACCP standards that determine market access for fresh and processed mushroom products. Monterey Mushrooms maintains vertical integration across composting and distribution to sustain margin control from Pennsylvania to California.
Netherlands
IoT-enabled environmental monitoring in multi-zone facilities compresses labor inputs per kilogram of Agaricus biomass harvested. The EU Green Deal and REACH frameworks constrain substrate sourcing protocols for operators serving German and French retail channels. Westland municipality clusters deploy sensor-integrated climate management to enable precise strain-specific parameter adjustment.
Ireland
Specialized spawn genetics and climate-controlled production anchor premium positioning in British supermarket private-label programs. ECHA substance authorization requirements phase out legacy fumigants, forcing steam-based pasteurization retrofits. Monaghan Group facilities in Monaghan and Cavan counties absorb these compliance costs to maintain retail channel positioning.
Poland
Composted agricultural residue protocols create circular economy incentives for substrate producers serving indoor cultivation facilities. EU organic equivalence standards create documentation burden for export-oriented operators accessing German distribution networks. Podlaskie Voivodeship clusters specialize in white button varieties for Central European foodservice contracts.
Mushroom Cultivation Market Vendor Landscape
North American producers anchor one tier through extensive retail and foodservice channel control; European specialists hold positioning through regulatory compliance infrastructure and spawn genetics concentration. The vendor base splits between vertically integrated composting-to-distribution operators and regional cooperative networks. Three archetypes dominate: climate-controlled facility operators, substrate-integrated supply chain controllers, and spawn genetics laboratories. Competitive moves concentrate on direct procurement disintermediation and multi-standard certification capacity expansion.
Among Irish and Belgian climate-controlled specialists, Monaghan Group and Mycelia occupy positions within the spawn genetics and environmental management tier. Monterey Mushrooms anchors the North American integrated supply chain archetype through captive composting and distribution assets. These three entities exemplify how regulatory compliance infrastructure and channel control separate sustainable margin positions from commodity pressure.
| Leading Market Players |
|---|
| Monterey Mushrooms |
| Monaghan Group |
| South Mill Champs |
| Greenyard |
| Bonduelle Group |
| Costa Group |
| Mycelia |
| Walsh Mushrooms Group |
| CMP Mushroom |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists in Ireland and Poland anchor supply discipline through multi-generational substrate sourcing relationships, compressing price volatility for contracted retail channels while spot-market exposure concentrates with auction-dependent wholesalers.
Pricing Analysis
Short lead-time premiums dominate fresh mushroom contracting, with foodservice distributors paying 15-25% markups for 48-hour harvest-to-delivery guarantees versus standard 5-7 day wholesale auction cycles. Three-tier pricing structure across premium, standard, and economy levels separates USDA organic certified product from conventional indoor-grown and imported traditional farm output. Pricing pressure stems from energy cost volatility in climate-controlled facilities, particularly for Dutch and Belgian operators facing EU ETS carbon pricing. Smallholder traditional farming segments exhibit highest price sensitivity due to perishability constraints and absence of cold-chain investment.
Supply Chain Analysis
Reverse-logistics flows for spent substrate composting create circular economy value recovery, with Irish and Polish operators selling post-harvest compost to agricultural distributors as soil amendments. Supply concentrates in China, the Netherlands, and the United States, with Fujian province bottle-culture systems and Westland municipality climate facilities anchoring global enoki and Agaricus volume. Raw material dependencies include hardwood sawdust for shiitake blocks, wheat straw for oyster varieties, and poultry manure for Agaricus compost. Single-source vulnerability concentrates in proprietary spawn genetics laboratories in Belgium and Ireland. Distribution runs through direct procurement contracts between metropolitan foodservice distributors and regional growing cooperatives, bypassing legacy wholesale auctions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Controlled environment agriculture technology is displacing traditional farming as IoT-enabled climate management compresses labor inputs and elevates biological efficiency beyond legacy grower intuition capabilities.
For Market Incumbents: Lock in spawn genetics exclusivity through long-term licensing with Belgian and Irish laboratories, insulating against supply vulnerability as proprietary strain concentration intensifies. Defend margin position by absorbing REACH-compliant steam pasteurization retrofits before ECHA substance authorization deadlines eliminate legacy fumigant protocols for European market access.
For New Entrants and Emerging Players: Enter via urban vertical farming installations in high-density metropolitan corridors, exploiting proximity sourcing premiums for restaurant and retail channels that bypass refrigerated logistics infrastructure requirements. Target nutraceuticals extraction processing, where beta-glucan and triterpene isolation for pharmaceutical adjuvants remains underexploited beyond whole-food sales, with direct-to-consumer supplement brands offering contract manufacturing entry points.
For Investors and Strategic Acquirers: FDA HACCP certification expansions by mid-scale operators is the leading indicator that margin compression from multi-standard compliance burden is creating acquisition opportunities for capital-rich consolidators. Five-to-ten year viability favors climate-controlled facility operators with captive composting assets and established retail channel contracts over substrate-dependent traditional farming exposure. Monitor EU organic equivalence documentation investments as early signals of export-oriented operators positioning for German and French distribution network access.
| Strategic Initiative | Industry Significance |
|---|---|
| Spawn Genetics Licensing Agreement | Proprietary strain access from Mycelia or Monaghan Group laboratories secures supply chain resilience against contamination risk. |
| Climate Facility Capacity Expansion | Multi-zone IoT deployment in Dutch Westland or Belgian Limburg clusters compresses labor cost per kilogram harvested. |
| REACH Compliance Retrofit Program | Steam-based pasteurization adoption ahead of ECHA fumigant phase-out maintains German retail channel positioning. |
| Direct Procurement Partnership | Volume contracts with US metropolitan restaurant groups bypass legacy produce auction margin compression. |
| Nutraceuticals Extraction Scale-Up | Beta-glucan isolation capacity for Lion's Mane and Reishi varieties captures functional food wellness category expansion. |
Methodological Framework
Multi-period observation of spawn pricing volatility, energy cost trajectories, and refrigerated logistics capacity utilization anchored the trend analysis, supplemented by interviews with cultivation facility operators, spawn genetics laboratory technical directors, foodservice procurement managers at metropolitan distributor groups, and nutraceuticals contract manufacturing executives. Secondary validation drew from USDA organic certification databases, ECHA substance authorization registers, FDA HACCP inspection records, and Chinese MEE dual carbon policy enforcement disclosures. Bottom-up facility capacity modeling triangulated against top-down segment demand projections.
Segment-weighting across product type, production technology, end-use application, and distribution channel dimensions structured the analytical framework throughout the projection horizon. CAGRs derived from biological efficiency improvement curves, substrate cost trajectories, and regulatory compliance capital deployment patterns. Industry-specific forecast inputs incorporated EU Green Deal waste-recovery mandate implementation timelines and China's export infrastructure expansion in Fujian and Shandong provinces.
Revisions become necessary when energy price volatility exceeds modeled scenarios, REACH chemical input restrictions accelerate beyond ECHA substance authorization schedules, or spawn genetics laboratory consolidation creates supply disruption. Practitioners should monitor MEE dual carbon enforcement intensity, FDA HACCP audit frequency changes, and direct procurement contract penetration rates in US metropolitan corridors for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Seaweed Algae Market
Agriculture and Agri Products
South America Swine Feed Premix Market
Agriculture and Agri Products
Rutin Market
Agriculture and Agri Products
Palm Kernel Expeller Market
Agriculture and Agri Products
Flower Pot Market
Agriculture and Agri Products
Africa Rice Market
Agriculture and Agri Products
South America Compound Feed Market
Agriculture and Agri Products
Europe Guar Market
Agriculture and Agri Products
Plant Antifreeze Market
Agriculture and Agri Products
Genetically Modified Feed Market
Agriculture and Agri Products
Pure Plant Oil Market
Agriculture and Agri Products
Cashew Market
Agriculture and Agri Products
LAMEA Artificial Humus Market
Agriculture and Agri Products
Brazil Cashew Market
Agriculture and Agri Products
Organic Cassava Flour Market
Agriculture and Agri Products
Malaysia Floriculture Market