
 Ethiopia Agriculture Sector Market | 2026-2036
Ethiopia Agriculture Sector Market Size, Share, and Industry Trends Forecast 2026-2036
Ethiopia Agriculture Sector Market Insights
Buyer concentration among food processing enterprises is broadening as multinational offtakers and domestic millers fragment procurement across smallholder cooperatives rather than large estate farms. Ethio Agri-CEFT leverages its integrated outgrower network to secure consistent sesame and pulse volumes. Horizon Plantations PLC anchors the commercial horticulture segment through controlled-environment rose and vegetable production near Ziway. Olam International Limited competes via its Addis Ababa-based sourcing infrastructure that connects Ethiopian oilseeds to Asian crushing markets.
The Ethiopia Agriculture Sector encompasses crop cultivation, livestock rearing, and allied activities across diverse agro-ecological zones ranging from 150 meters below sea level in the Danakil Depression to over 4,000 meters in the Bale highlands, with teff, maize, and coffee serving as the dominant commercial outputs for domestic food security and foreign exchange generation. Cereals occupy the largest production footprint yet generate thin margins due to fragmented landholding patterns averaging under one hectare. Oilseeds command premium export prices through niche organic and traceability certifications. Precision Agriculture represents the fastest-growing technology segment as satellite-based variable-rate input applications spread through ATA-subsidized service providers.
The Ethiopian Agricultural Transformation Agency coordinates digital extension standards while the Ethiopian Standards Agency enforces Codex-aligned maximum residue limits for export-bound consignments, tightening market access requirements for smallholders supplying European retailers. The Ministry of Agriculture's fertilizer subsidy reforms and the central bank's export retention account rules jointly reshape working capital availability across the value chain. Stakeholders must monitor whether the government's commodity exchange modernization delivers transparent price discovery for cooperative sellers or reinforces intermediary capture.
Market Dynamics
Smallholder cooperative networks are fragmenting procurement power away from large estate farms, forcing food processors to build distributed sourcing infrastructure across Ethiopia's highland cereal belts and Rift Valley corridors.
Growth Catalysts
- ATA Digital Extension Standards:Satellite-based variable-rate input applications spread through subsidized service providers, accelerating precision agriculture uptake among teff and maize cultivators in Oromia.
- Export Retention Account Rules:Ethiopia's central bank reforms improve working capital availability for oilseed exporters targeting Asian crushing markets through traceability-linked consignments.
- Highland Cereal Demand:Domestic millers fragment procurement across cooperative networks, broadening buyer concentration and creating volume anchors for smallholder aggregation.
Market Restraints
- Fertilizer Subsidy Volatility:Ministry of Agriculture reforms create input cost uncertainty for fragmented landholders averaging under one hectare.
- Codex MRL Compliance:Ethiopian Standards Agency enforcement tightens market access for smallholders supplying European retailers, raising technical barriers to organic certification.
- Intermediary Capture Risk:Commodity exchange modernization may reinforce middleman control rather than deliver transparent price discovery for cooperative sellers.
Strategic Opportunities
- Rift Valley Horticulture Corridors:Controlled-environment rose and vegetable production near Ziway offers premium export positioning through proximity to Addis Ababa air freight infrastructure.
- Oilseed Organic Certification:Niche traceability standards command premium prices in Asian markets, creating white space for sesame and pulse outgrower networks.
- Precision Agriculture Convergence:Satellite imagery integration with mobile extension platforms enables input optimization across diverse agro-ecological zones from Danakil to Bale highlands.
Industry Challenges
- Digital Extension Capacity:Agricultural Transformation Agency program scale exceeds trained agronomist availability for last-mile smallholder support.
- Cooperative Financial Integration:Working capital gaps persist between fertilizer subsidy disbursement and harvest cash flows for sub-hectare landholders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethiopia Agriculture Sector Market |
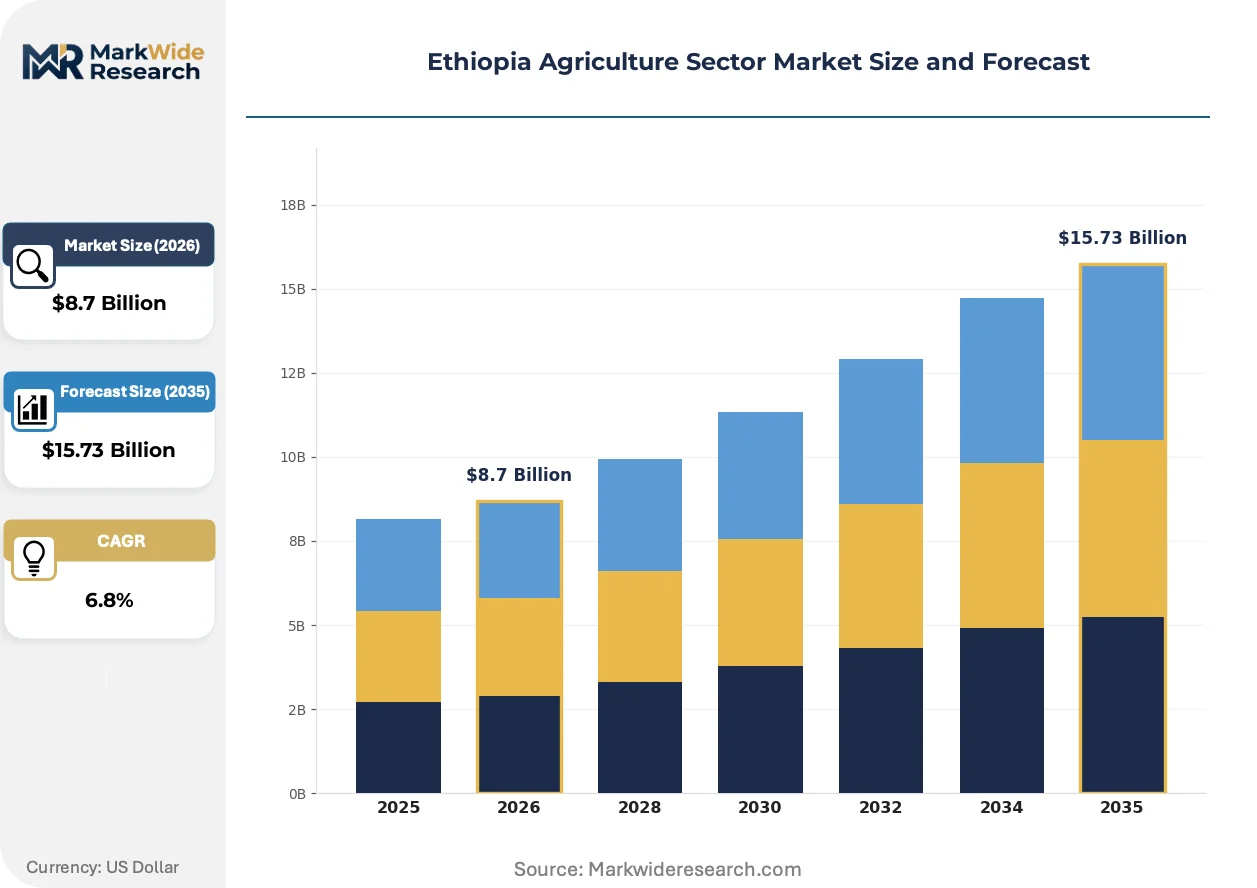
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cereals, Pulses, Oilseeds, Vegetables End Use Industry: Food Processing, Livestock Feed, Export, Biofuels Technology: Conventional Farming, Organic Farming, Hydroponics, Precision Agriculture Distribution Channel: Wholesale, Retail, Direct Sales, Online Platforms |
| Companies Covered | Ethio Agri-CEFT, Horizon Plantations PLC, Belayneh Kindie Group, ACOS Ethiopia PLC, Louis Dreyfus Company, Olam International Limited, Awash Wine Share Company, Jittu Horticulture PLC, Adam Horticulture PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethiopia Agriculture Sector Market Trends and Innovations
Technology diffusion and regulatory tightening are compressing traditional value chain margins while opening premium segments for certified, traceable production.
Satellite-based variable-rate input technology is overtaking blanket fertilizer recommendations across Ethiopia's highland cereal zones. ATA-subsidized service providers deploy imagery-guided application to teff and maize cooperatives in Oromia. The shift is compressing input waste margins while concentrating technical service revenue among digitized agronomy firms.
Ethiopian Standards Agency enforcement of Codex-aligned maximum residue limits tightens export-bound consignment requirements. Smallholders supplying European retailers face stepped-up laboratory testing and documentation burdens. Oilseed segments targeting organic certification invest in segregated handling infrastructure to maintain traceability premiums.
Food processors unbundle after-sales extension from input sales, charging separately for agronomic advisory tied to offtake guarantees. Domestic millers and multinational buyers build captive agronomist networks to secure consistent smallholder volumes. The model concentrates most visibly in sesame and pulse supply chains serving Asian crushing markets.
Ethiopia Agriculture Sector Market Segmentation
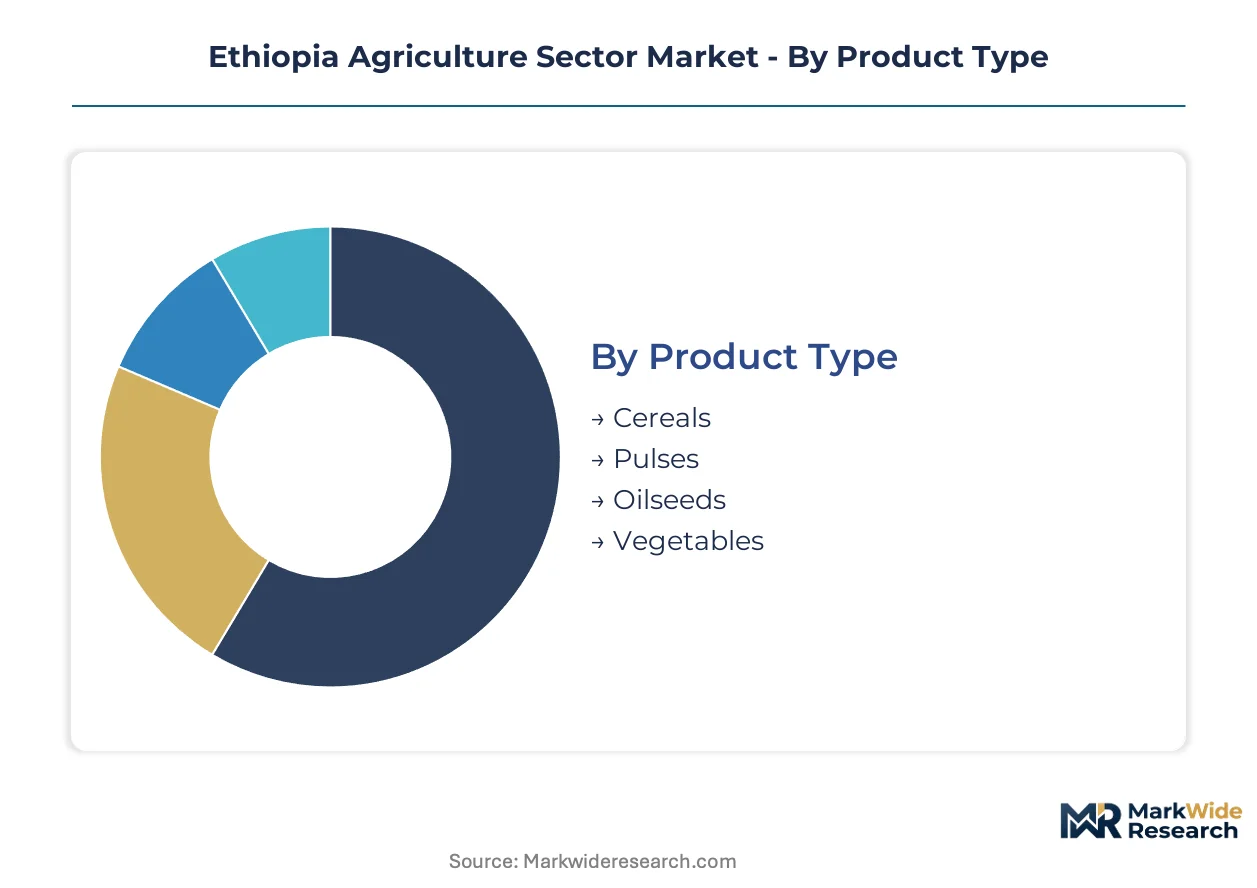
Segmentation in Ethiopia's agriculture sector reveals how certification requirements, distribution logistics, and technology access stratify competitive positioning across smallholder cooperatives and commercial estates. Understanding these divisions exposes where Ethiopian Standards Agency enforcement creates barriers versus where Agricultural Transformation Agency subsidies accelerate uptake.
Product Type:
Cereals and oilseeds carry distinct Ethiopian Standards Agency documentation burdens for export-bound consignments, while pulses and vegetables face divergent domestic versus international compliance pathways.
- Cereals:Teff and maize dominate production across Oromia's highland belts, with domestic millers fragmenting procurement through cooperative networks. Ethiopian Standards Agency maximum residue limits apply selectively to export-designated volumes, leaving most output for domestic food security exempt from laboratory testing.
- Oilseeds:Sesame and niger seed command premium positioning through organic and traceability certifications targeting Asian crushing markets. Segregated handling infrastructure maintains certification integrity from farm gate to Addis Ababa export terminals.
- Pulses:Chickpea and lentil cultivation concentrates in moisture-reliable highland zones, serving both domestic protein demand and Middle Eastern import markets with lower documentation thresholds than European destinations.
- Vegetables:Rift Valley corridor production near Ziway supplies controlled-environment roses and vegetables to air freight infrastructure, with perishability dictating expedited cold chain compliance rather than residue testing.
Cereals sit at the top of the volume ranking, with oilseeds climbing the fastest on traceability-linked premium positioning.
End Use Industry:
Cost tier differentiation separates working capital-intensive export channels from subsidy-dependent domestic supply.
- Food Processing:Domestic millers and multinational offtakers build distributed sourcing infrastructure across cooperative networks, unbundling extension services from input sales to secure consistent smallholder volumes.
- Livestock Feed:Oilseed cake and cereal bran byproducts flow to emerging commercial dairy and poultry operations in peri-urban zones around Addis Ababa and Hawassa.
- Export:Central bank export retention account rules reshape working capital availability for oilseed and pulse consignments targeting Asian and Middle Eastern markets.
- Biofuels:Jatropha and castor cultivation for biodiesel feedstock remains marginal, constrained by land tenure insecurity and competing food security priorities in national policy.
Food processing anchors volume absorption, with export channels gaining share fastest on foreign exchange retention incentives.
Technology:
Application suitability varies dramatically across Ethiopia's elevation gradient from Danakil Depression to Bale highlands.
- Conventional Farming:Blanket fertilizer recommendations and rain-fed cultivation persist across fragmented sub-hectare holdings, dominating cereal production in moisture-reliable zones.
- Organic Farming:Segregated certification pathways for sesame and pulses command price premiums in European and North American retail channels, requiring multi-year transition periods and third-party audit compliance.
- Hydroponics:Controlled-environment vegetable and flower production clusters near Ziway and Holeta, leveraging proximity to Addis Ababa air freight for perishable export consignments.
- Precision Agriculture:Satellite-based variable-rate input applications spread through ATA-subsidized service providers, concentrating technical service revenue among digitized agronomy firms in Oromia's teff and maize zones.
Conventional farming retains dominant volume position, with precision agriculture expanding most quickly on digital extension subsidy availability.
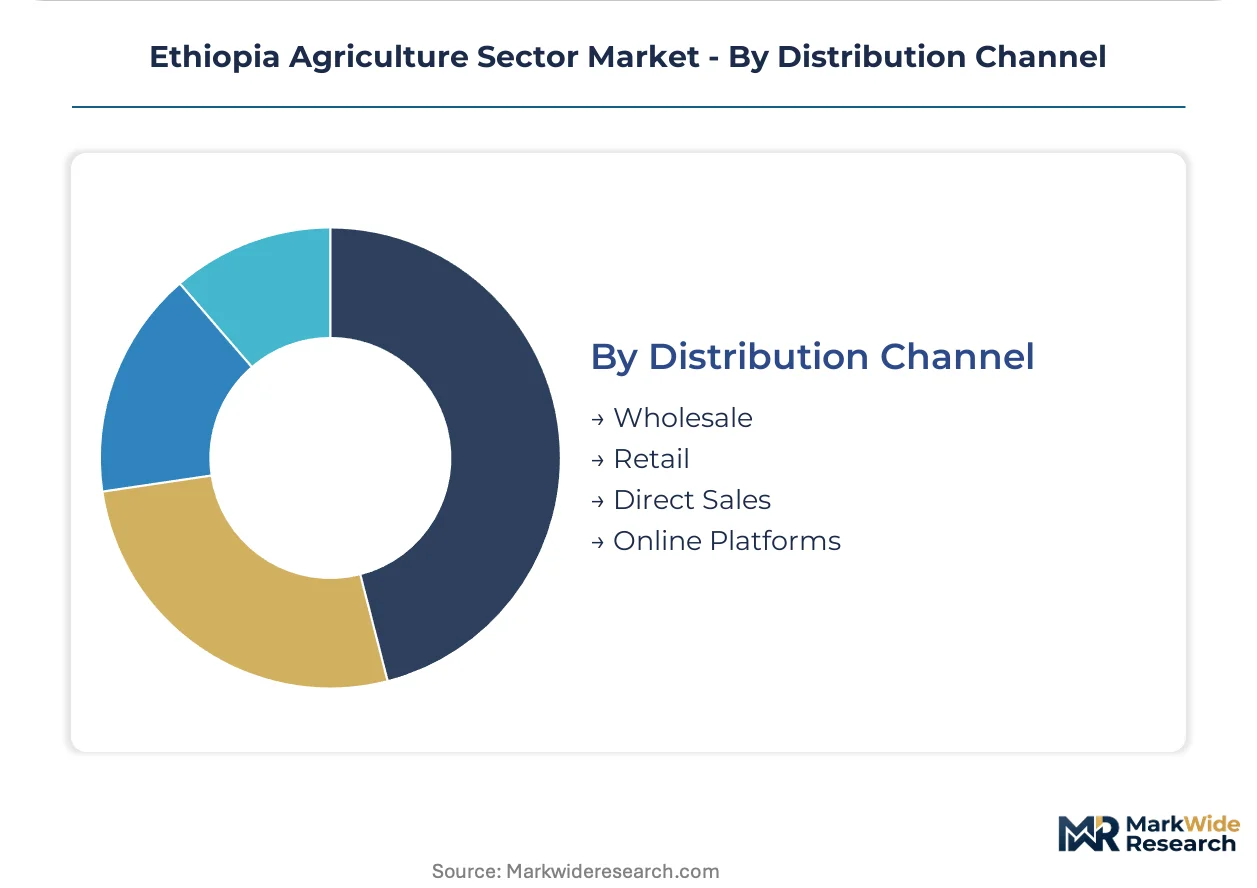
Distribution Channel:
Customer type and geography jointly determine channel selection, with cooperative aggregation altering traditional intermediary structures.
- Wholesale:Cooperative unions and agricultural marketing cooperatives aggregate sub-hectare production for bulk sale to processors and exporters, fragmenting traditional trader dominance.
- Retail:Urban market stalls and small-town shops distribute cereals and vegetables to domestic consumers, with price discovery shaped by commodity exchange modernization efforts.
- Direct Sales:Contract farming arrangements between commercial estates and multinational buyers bypass intermediary layers, most visible in sesame and pulse supply chains.
- Online Platforms:Mobile-based market information services and emerging e-commerce channels connect peri-urban producers to urban consumers, constrained by payment infrastructure and logistics reliability.
Wholesale channels handle peak volume flows, with direct sales gaining traction fastest on processor demand for traceability documentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smallholder cooperative networks and commercial estate operations anchor agricultural output across Ethiopia's diverse agro-ecological zones, from highland cereal belts to Rift Valley horticulture corridors.
Oromia Region
Teff and maize cultivation dominates Oromia's highland cereal belts, with domestic millers fragmenting procurement through cooperative networks. The Ethiopian Agricultural Transformation Agency subsidizes satellite-based variable-rate input applications across the region. Precision agriculture service providers concentrate technical capacity in the Arsi and Bale zones, displacing blanket fertilizer recommendations.
Southern Nations, Nationalities, and Peoples' Region
Coffee production and enset cultivation anchor livelihoods across SNNPR's moisture-reliable highlands, with cooperative unions aggregating sub-hectare harvests for export channels. The Ethiopian Standards Agency enforces Codex-aligned maximum residue limits for European-bound consignments. Sidama and Gedeo zones host segregated handling infrastructure for specialty-grade arabica.
Amhara Region
Sesame and niger seed production concentrates in Amhara's western lowlands, supplying Asian crushing markets through traceability-linked outgrower networks. Central bank export retention account rules reshape working capital availability for oilseed exporters. The Metema and Humera corridors maintain organic certification pathways for premium positioning.
Tigray Region
Sorghum and finger millet cultivation persists across Tigray's moisture-stressed highlands, with food security priorities dominating domestic procurement. Ministry of Agriculture fertilizer subsidy reforms create input cost uncertainty for fragmented landholders. The Mekelle corridor hosts emerging commercial dairy operations serving peri-urban demand.
Central Ethiopia Region
Controlled-environment rose and vegetable production clusters near Ziway and Holeta, leveraging proximity to Addis Ababa air freight infrastructure. Perishability dictates expedited cold chain compliance rather than residue testing for Rift Valley horticulture exports. Horizon Plantations PLC anchors commercial estate capacity in this corridor.
Ethiopia Agriculture Sector Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Ethiopia's agriculture sector, creating a tiered structure where procurement scale and certification capability separate competitive positions. The vendor base spans integrated outgrower networks, commercial estate operators, and multinational sourcing infrastructure. Three archetypes dominate: domestic cooperative-integrated processors, controlled-environment commercial estates, and Asian-market-facing oilseed exporters. Competitive moves concentrate on backward integration into smallholder aggregation and segregated handling infrastructure for organic certification.
Within the integrated outgrower tier, Ethio Agri-CEFT represents cooperative-linked procurement architecture, while Horizon Plantations PLC exemplifies controlled-environment commercial estate positioning. Among multinational sourcing operations, Olam International Limited occupies a position connecting Ethiopian oilseeds to Asian crushing markets through Addis Ababa-based infrastructure.
| Leading Market Players |
|---|
| Ethio Agri-CEFT |
| Horizon Plantations PLC |
| Belayneh Kindie Group |
| ACOS Ethiopia PLC |
| Louis Dreyfus Company |
| Olam International Limited |
| Awash Wine Share Company |
| Jittu Horticulture PLC |
| Adam Horticulture PLC |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between organic oilseeds and conventional cereals manifests in both pricing power and supply chain architecture across Ethiopia's agricultural sector. Premium traceability-linked sesame and pulse consignments command structured offtake premiums through segregated handling infrastructure, while commodity teff and maize flow through fragmented cooperative networks with thin margin profiles.
Pricing Analysis
Capacity additions in Oromia's precision agriculture zones are reshaping price floors for highland cereal producers as satellite-based input optimization spreads. The dominant pricing structure runs on contract-based long-term offtake agreements between processors and cooperative unions, with price differentiation driven by organic certification tier and volume scale. Pricing pressure stems from fertilizer subsidy volatility and fragmented landholding patterns, with domestic millers exhibiting highest price sensitivity while Asian-facing oilseed exporters absorb certification costs for premium positioning.
Supply Chain Analysis
Regional distribution centers in Addis Ababa and Hawassa anchor hub-and-spoke patterns for perishable horticulture exports, while cooperative unions aggregate sub-hectare production across highland cereal belts. Geographic supply concentrates in Ethiopia's Oromia, Amhara, and Central regions, with raw material dependencies on urea and DAP fertilizers, improved seed varieties, and cold chain equipment. Single-source vulnerability runs through the Addis Ababa air freight corridor for Rift Valley rose exports. Distribution runs through wholesale cooperative channels for bulk cereals and direct sales contracts for traceable oilseeds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ethiopia's agriculture sector operates as a stable compounder anchored by persistent domestic food security demand and expanding export retention incentives for oilseed and pulse value chains.
For Market Incumbents: Deepen backward integration into smallholder outgrower networks to secure consistent organic sesame and pulse volumes against emerging regional competitors. Invest in segregated handling infrastructure for Codex MRL compliance to defend European retail channel access. Expand precision agriculture service capacity in Oromia before ATA subsidy windows narrow. For New Entrants and Emerging Players: Agricultural cooperatives in moisture-reliable SNNPR highlands represent the most penetrable aggregation target for specialty coffee and enset value chains. Target contract farming arrangements with domestic millers seeking volume anchors outside established Oromia supply bases. Launch mobile-based extension services bundled with input financing to capture last-mile smallholder relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where working capital gaps persist between fertilizer subsidy disbursement and harvest cash flows for sub-hectare landholders. The sector's long-term viability rests on digital extension scale and export infrastructure modernization rather than commodity price cycles. Acquisition targets should demonstrate captive outgrower networks with existing organic certification pathways. Watch for central bank export retention rule adjustments as the key inflection signal for oilseed processor valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Outgrower Networks | Secures volume consistency for Ethio Agri-CEFT and Horizon Plantations PLC against cooperative fragmentation. |
| Segregated Handling Infrastructure Investment | Enables Olam International Limited to maintain organic certification integrity for Asian crushing market premiums. |
| Precision Agriculture Service Expansion | Concentrates technical revenue among digitized agronomy firms as ATA subsidies accelerate satellite-based uptake. |
| Export Retention Account Optimization | Reshapes working capital availability for oilseed exporters targeting Middle Eastern and Asian destination markets. |
| Mobile Extension Platform Development | Connects peri-urban producers to urban consumers through emerging e-commerce channels around Addis Ababa. |
Research Methodology
Coverage spans Ethiopia's highland cereal belts, Rift Valley horticulture corridors, and western lowland oilseed zones, with primary inputs from each agro-ecological cluster. The analysis combines structured interviews with cooperative union managers, agricultural extension officers, oilseed export procurement leads, and domestic miller operations directors with secondary validation from Ethiopian Agricultural Transformation Agency program documentation, Ethiopian Standards Agency regulatory filings, and central bank export retention rule disclosures. Bottom-up cooperative production estimates triangulate against top-down commodity flow assessments across the analysis window.
Granularity-level modeling disaggregates volume and value outputs by product type, end-use industry, technology tier, and distribution channel, with additional segmentation by regional agro-ecological zone. CAGRs derive from trend extrapolation of historical production data adjusted for policy intervention effects and infrastructure buildout timelines. Key forecast inputs include fertilizer subsidy disbursement patterns, export retention account utilization rates, and precision agriculture service provider expansion trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Ministry of Agriculture input policy shifts and commodity exchange modernization effectiveness. Outputs reflect documented assumptions around smallholder technology adoption curves and cooperative financial integration progress. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Frozen Egg Market
Agriculture and Agri Products
Poultry Fat Market
Agriculture and Agri Products
Saudi Arabia Agriculture Market
Agriculture and Agri Products
Flower and Ornamental Plants Market
Agriculture and Agri Products
Non GMO Soybean Market
Agriculture and Agri Products
United Kingdom Poultry Meat Market
Agriculture and Agri Products
Colombia Hemp Market
Agriculture and Agri Products
North America Palm Oil Market
Agriculture and Agri Products
Australia Lime Market
Agriculture and Agri Products
Organic Soybean Market
Agriculture and Agri Products
Feed Protein Market
Agriculture and Agri Products
Mushroom Cultivation Market
Agriculture and Agri Products
Live Goods Market
Agriculture and Agri Products
Canada Ornamental Horticulture Market
Agriculture and Agri Products
Okara Market
Agriculture and Agri Products
Post-Harvest Treatment Market