
 Japan Floriculture Market | 2026-2036
Japan Floriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Floriculture Market Foresight
Domestic chrysanthemum and rose production in Aichi Prefecture is decoupling from seasonal import cycles as heated greenhouse capacity expands year-round. Takii & Co., Ltd leverages its century-old breeding programs to dominate proprietary cultivar development for potted orchids. Sakata Seed Corporation anchors the bedding plant supply chain through integrated seed-to-seedling operations across Shizuoka and Ibaraki. Suntory Flowers Ltd differentiates via patented blue rose genetics and controlled-environment propagation systems that command premium wholesale pricing at Ota Market.
Japan floriculture encompasses the commercial cultivation, post-harvest handling, and distribution of ornamental crops including cut flowers, potted plants, bedding plants, and bulbs, with production cycles governed by photoperiod sensitivity, temperature forcing protocols, and vase-life extension treatments. The sector serves residential interiors, commercial property staging, ceremonial events, and urban landscaping maintenance. Cut flowers generate the highest revenue velocity through Tokyo's auction halls, while potted plants capture expanding margin pools as corporate wellness programs and apartment gardening trends accelerate. Bedding plants face structural pressure from imported Dutch bulb competition, though domestic nurseries retain local-delivery advantages for landscaping contracts.
METI enforces plant variety protection under Japan's Seed and Seedlings Law, while the Ministry of Agriculture, Forestry and Fisheries administers GAP certification and phytosanitary export standards that determine market access for domestic growers. PMDA oversight intersects where floral extracts enter cosmetic and pharmaceutical supply chains, creating dual compliance pathways for vertically integrated producers. Stakeholders must monitor METI's evolving carbon-accounting rules for heated greenhouse operations, as energy-cost reporting requirements will reshape investment decisions in protected-culture infrastructure.
Market Dynamics
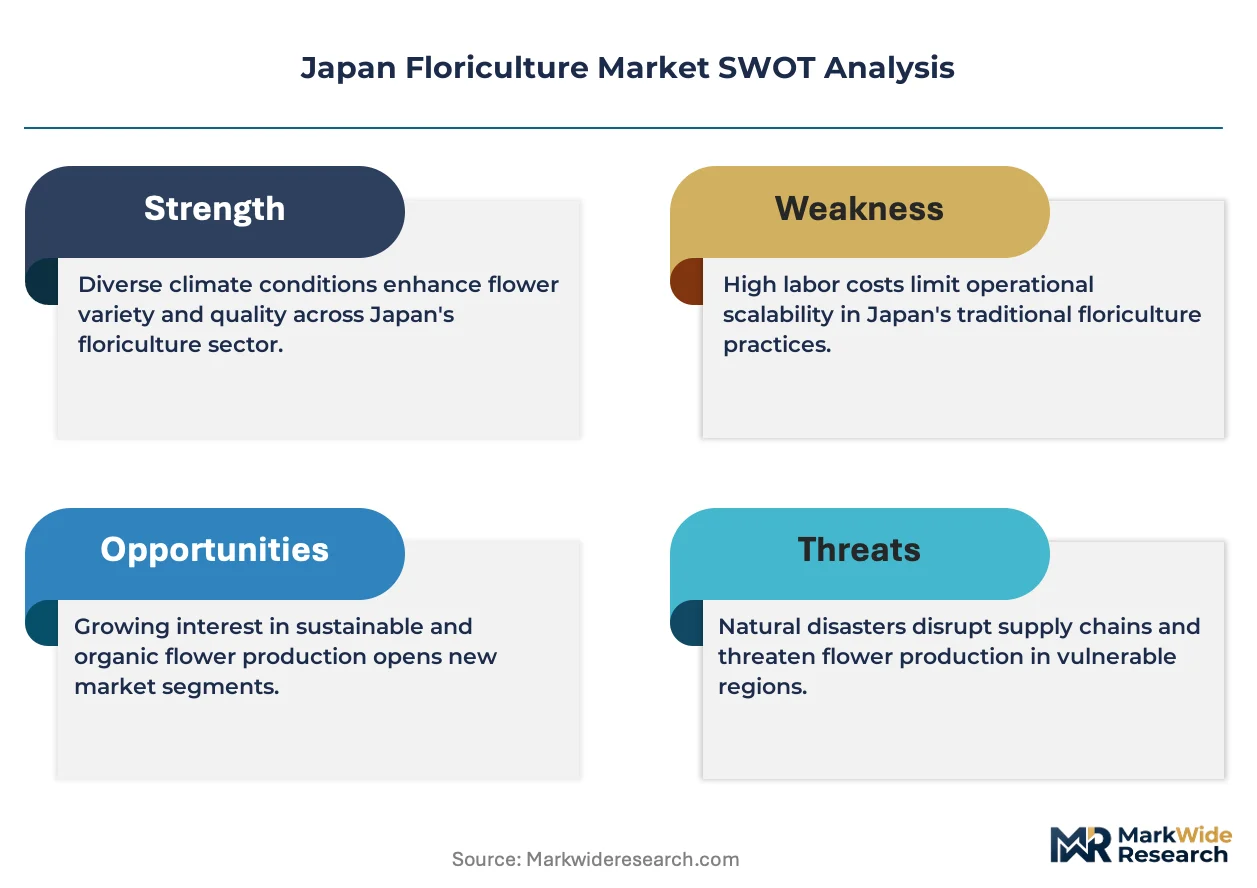
Japan's floriculture sector is undergoing a structural transformation as heated greenhouse capacity in Aichi and Shizuoka prefectures decouples domestic chrysanthemum and rose production from seasonal import dependency. This capital-intensive shift toward year-round controlled-environment agriculture is redrawing procurement relationships between growers, wholesale auction houses, and luxury hospitality buyers in Tokyo and Osaka.
Growth Catalysts
- Corporate Wellness Programs:Japanese corporations are expanding biophilic office installations, driving contract demand for low-maintenance potted orchids and foliage plants that require minimal facility management intervention.
- METI Carbon-Accounting Rules:The Ministry of Economy, Trade and Industry's evolving greenhouse energy-cost reporting requirements are accelerating investment in efficient LED supplemental lighting and geothermal heating systems.
- Ceremonial Event Density:Tokyo's concentration of luxury hotels and wedding venues sustains premium cut-flower throughput at Ota Market, anchoring national price benchmarks for rose and lily varieties.
Market Restraints
- Natural Gas Price Volatility:Heated greenhouse operations in Ibaraki and Chiba face margin compression from fossil fuel input cost swings, forcing growers to delay expansion capex during price spikes.
- Dutch Bulb Import Dominance:Bedding plant nurseries in Shizuoka confront structural displacement from low-cost tulip and hyacinth bulb imports arriving through Yokohama port terminals.
- MAFF Pesticide Threshold Tightening:Japan's Ministry of Agriculture, Forestry and Fisheries updated GAP certification residue limits are disqualifying smaller domestic farms lacking precision spray technology.
Strategic Opportunities
- Kansai Underpenetration:Osaka's wholesale flower volume trails Tokyo by a significant multiple, creating white space for direct-to-florist logistics networks bypassing auction intermediaries.
- Pharmaceutical Extract Channels:PMDA oversight of floral-derived cosmetic ingredients creates dual compliance pathways for vertically integrated producers cultivating Rosa rugosa and lavender for extraction supply chains.
- Apartment Gardening Subscription Models:Tokyo's dense residential tower stock supports recurring-revenue services delivering seasonal potted plants to balcony growers, displacing traditional retail purchase patterns.
Industry Challenges
- Skilled Forcing Technician Scarcity:Mastery of photoperiod manipulation and temperature forcing protocols for year-round chrysanthemum production is concentrated among aging growers in Aichi Prefecture.
- Variety Protection Licensing Complexity:METI enforcement of Japan's Seed and Seedlings Law creates friction for smaller nurseries seeking access to proprietary cultivars controlled by established breeding programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Floriculture Market |
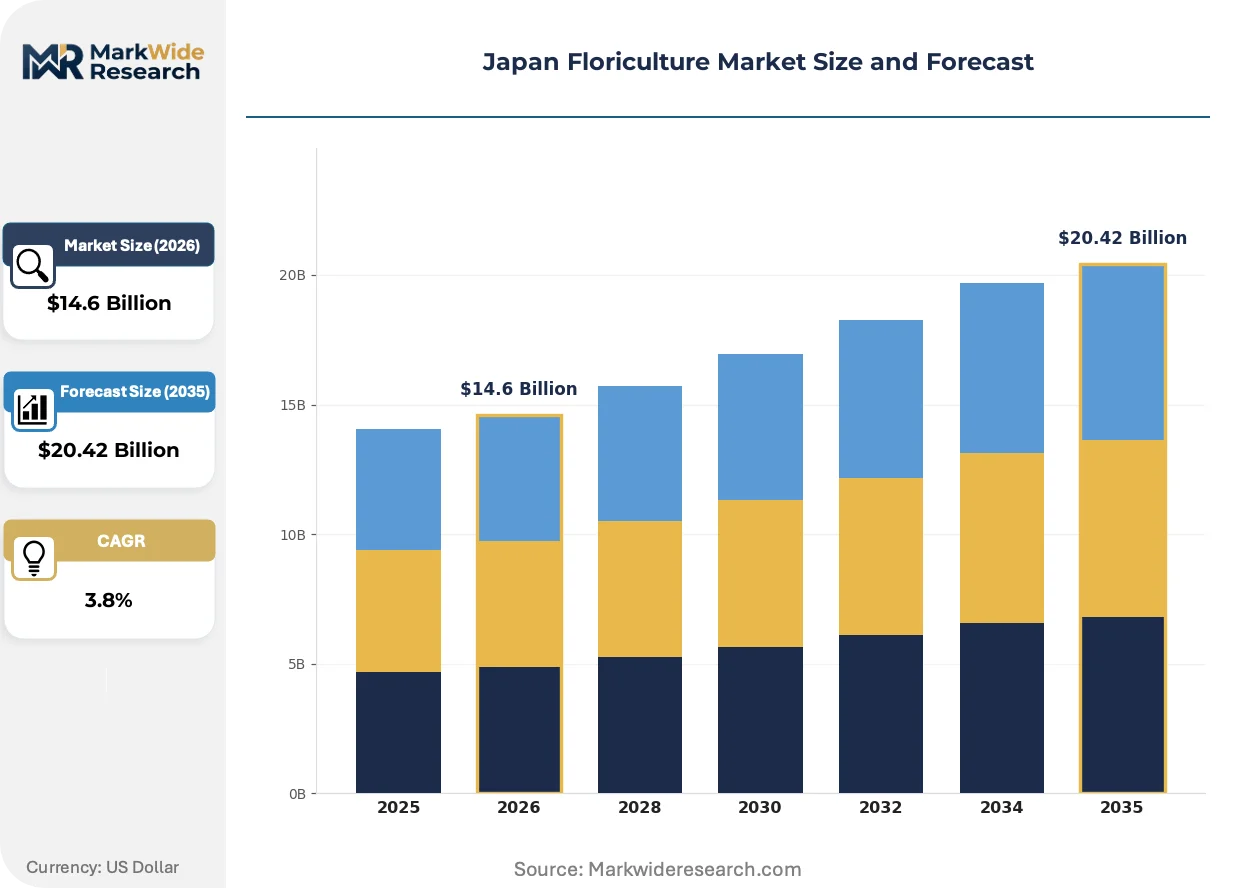
| Market Size in 2026 | $14.6 Billion |
| Market Size in 2035 | $20.42 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cut Flowers, Potted Plants, Bedding Plants, Bulbs Distribution Channel: Wholesale, Retail Outlets, Online Stores, Nurseries Customer Type: Retail Consumers, Event Planners, Businesses, Florists End Use: Residential, Commercial, Events, Landscaping |
| Companies Covered | Hokkaido Green Co., Ltd, Takii & Co., Ltd, Ota Floriculture Auction Co., Ltd, Sakata Seed Corporation, Fuji Flower Industry Co., Ltd, Dümmen Orange, Shiraishi Flower Farm Co., Ltd, Suntory Flowers Ltd, Kawachiya Nursery Co., Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Floriculture Market Shifts & Advancements
Automation and regulatory compliance are converging to reshape production economics and distribution architecture across Japan's ornamental crop value chain. Three distinct vectors are compressing traditional operating models while opening premium positioning pathways.
Robotic transplanting and spacing systems are automating labor-intensive greenhouse operations in Shizuoka and Ibaraki prefectures. Large-scale potted plant producers are deploying vision-guided automation at accelerating pace. This technology is automating the precise handling of delicate orchid seedlings that previously required skilled manual intervention, compressing per-unit labor costs and enabling 24-hour production cycles.
Japan's Ministry of Agriculture, Forestry and Fisheries tightened GAP certification requirements are mandating digital pesticide application logging and residue testing documentation. Domestic flower farms must now maintain traceability systems from propagation through post-harvest treatment. Smallholder operations in Chiba Prefecture are consolidating or exiting as compliance timelines expose capability gaps in record-keeping infrastructure.
Luxury hotel chains in Tokyo and Osaka are consolidating floral procurement through direct contracts with designated growers, bypassing Ota Market auction intermediaries. This disintermediation compresses price discovery transparency but secures variety consistency and vase-life guarantees for lobby installations. The shift is most visible in Roppongi and Ginza districts where international hospitality groups standardize global brand aesthetics across properties.
Japan Floriculture Market Segmentation
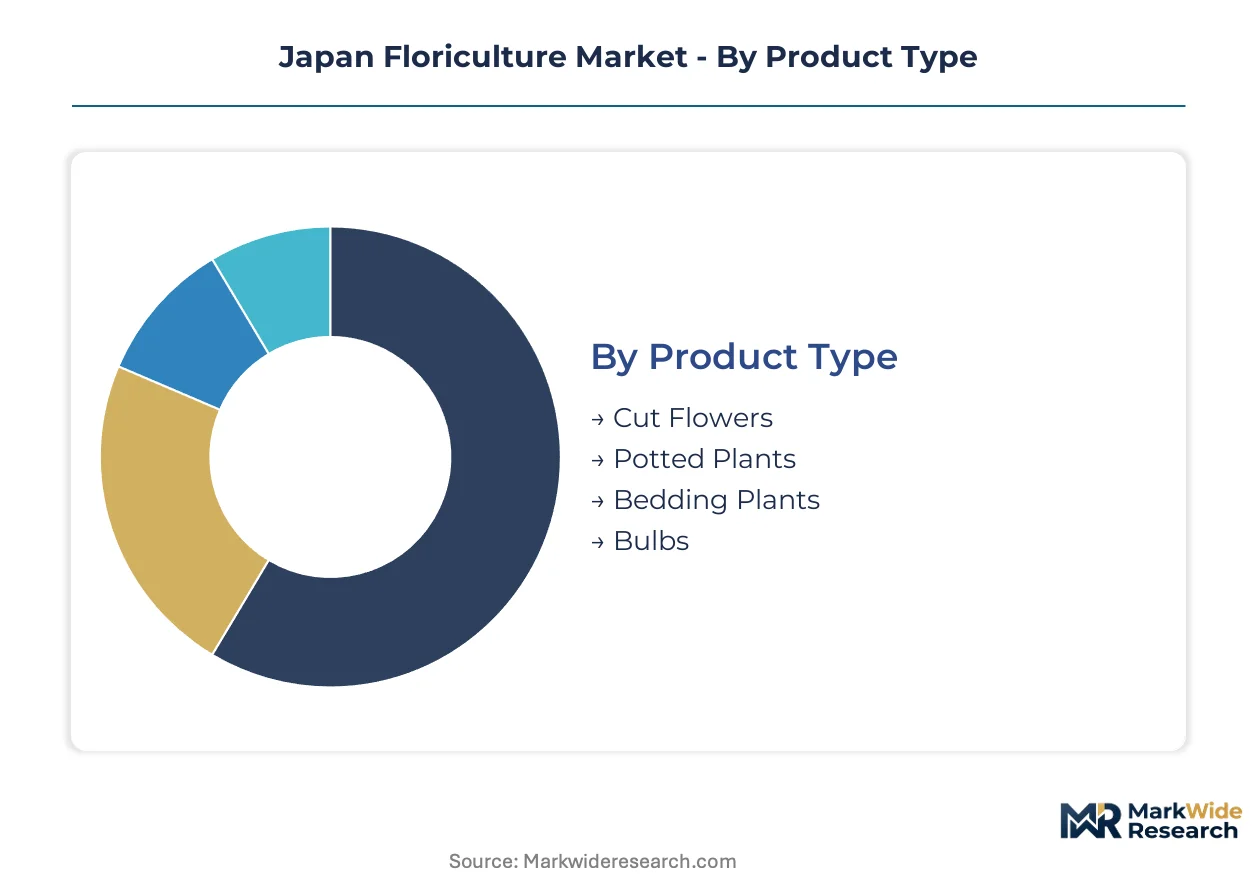
Japan's floriculture value chain fragments across product form, procurement pathway, and buyer sophistication. Each segmentation dimension reveals distinct margin structures and regulatory exposure profiles that determine competitive positioning for domestic growers and importers alike.
Product Type:
Supply concentration in heated greenhouse infrastructure across Aichi and Shizuoka prefectures determines which product categories capture year-round domestic production versus seasonal import dependency.
- Cut Flowers:Chrysanthemums, roses, and lilies dominate Tokyo's Ota Market auction volumes. Luxury hospitality procurement in Tokyo's Roppongi and Ginza districts sustains premium pricing for vase-life-extended varieties.
- Potted Plants:Orchids and foliage plants command expanding margin pools through corporate wellness programs. Takii & Co.'s proprietary cultivar development anchors supply security for biophilic office installations requiring minimal facility management.
- Bedding Plants:Seasonal annuals and perennials face structural pressure from Dutch bulb imports through Yokohama port terminals. Domestic nurseries in Ibaraki retain local-delivery advantages for municipal landscaping contracts.
- Bulbs:Tulip and hyacinth propagation concentrates among specialized growers with forcing expertise. METI plant variety protection enforcement limits access to proprietary genetics for smaller operations.
Today's leader: Cut Flowers. Tomorrow's challenger: Potted Plants.
Distribution Channel:
Channel economics in Japan's floriculture sector stratify by buyer scale, cold-chain requirements, and the regulatory burden of MAFF GAP certification documentation.
- Wholesale:Tokyo's Ota Market and Osaka's wholesale halls set national price benchmarks through auction-based price discovery. Large-volume transactions require phytosanitary compliance and residue documentation that smaller farms struggle to maintain.
- Retail Outlets:Department store flower shops and supermarket floral sections serve impulse purchases and gift occasions. Shrinkage management and daily replenishment logistics favor suppliers with regional distribution centers.
- Online Stores:Subscription models for apartment gardening and corporate plant leasing bypass traditional retail markups. Last-mile delivery networks in Tokyo's dense residential tower stock enable recurring-revenue capture.
- Nurseries:Direct-to-landscaper and direct-to-florist relationships in Kansai bypass auction intermediaries. Technical consultation services on plant forcing protocols differentiate full-service nurseries from commodity suppliers.
Wholesale channels retain volume dominance while online stores gain share fastest among urban retail consumers.
Customer Type:
Buyer sophistication and contract scale determine whether procurement flows through auction intermediaries or direct grower relationships.
- Retail Consumers:Individual purchasers favor convenience-oriented channels with immediate availability. Ceremonial gift occasions drive concentrated demand spikes around cultural holidays.
- Event Planners:Wedding venues and corporate event coordinators require variety consistency and vase-life guarantees. Direct contracts with designated growers secure aesthetic standardization across multi-property hospitality groups.
- Businesses:Corporate wellness programs and lobby staging contracts favor low-maintenance potted orchids with scheduled replacement services. Biophilic installation specifications increasingly specify GAP-certified sourcing.
- Florists:Independent shops and chain florists split procurement between auction volume purchases and nursery direct relationships. Technical knowledge of forcing protocols distinguishes professional buyers from retail consumers.
Businesses command the steepest expansion trajectory as corporate wellness adoption accelerates.
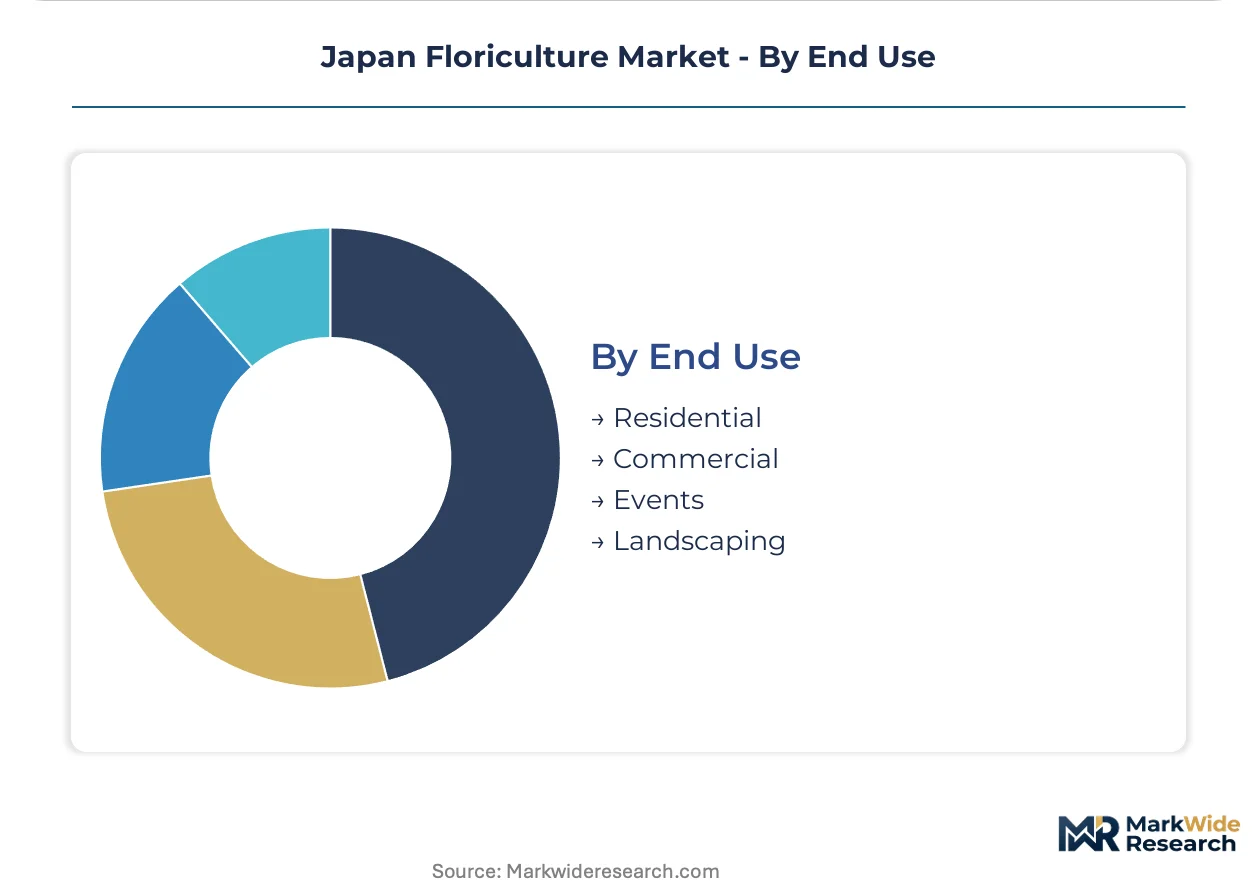
End Use:
Application context dictates product specifications, replacement frequency, and the premium capture potential of specialized cultivars.
- Residential:Apartment balcony gardening and interior plant styling drive demand for compact potted varieties. Subscription delivery models displace traditional retail purchase patterns in Tokyo's dense housing stock.
- Commercial:Office biophilic installations and hotel lobby staging require consistent visual impact with minimal maintenance intervention. Long-term service contracts favor suppliers with captive greenhouse capacity.
- Events:Wedding floral design and corporate function staging concentrate demand in Tokyo and Osaka metropolitan areas. Seasonal peak management challenges growers without year-round forcing capability.
- Landscaping:Municipal contracts and commercial property maintenance favor bedding plants with established local nursery supply chains. Dutch bulb import competition pressures domestic propagation economics.
Commercial applications anchor revenue stability while residential channels show the most rapid model innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration within Japan follows regulatory-arbitrage logic as MAFF's tightened GAP certification thresholds concentrate compliant capacity in prefectures with established precision-agriculture infrastructure. Heated greenhouse operators in Aichi and Shizuoka capture margin advantages from year-round forcing capability that smaller Chiba farms cannot replicate.
Kanto/Tokyo
Tokyo's Ota Market sets national price benchmarks through auction-based price discovery for cut flowers. METI's carbon-accounting rules for greenhouse energy costs accelerate LED retrofit investments across Ibaraki and Chiba heated operations. The Roppongi and Ginza hospitality corridors sustain premium procurement for lobby installations through direct grower contracts.
Kansai/Osaka
Osaka's wholesale flower volume trails Tokyo significantly, creating white space for direct-to-florist logistics networks. Corporate wellness programs in Osaka's central business district drive contract demand for low-maintenance potted orchids. Sakai and Kobe port infrastructure supports import competition for bedding plant varieties.
Chubu/Nagoya
Aichi Prefecture dominates domestic chrysanthemum and rose production through expanded heated greenhouse capacity decoupled from seasonal import cycles. Takii & Co.'s century-old breeding programs anchor proprietary cultivar development from headquarters operations. Nagoya's logistics connectivity enables just-in-time delivery to Tokyo auction houses.
Kyushu
Fukuoka's subtropical climate supports outdoor bulb propagation with lower heating cost exposure than northern prefectures. MAFF phytosanitary export standards compliance concentrates among larger operations with dedicated testing infrastructure. Kumamoto and Kagoshima farms supply regional retail chains with reduced cold-chain complexity.
Hokkaido
Hokkaido Green Co. leverages cool summer conditions for field-grown lily and gladiolus production with minimal climate-control energy inputs. Shorter growing seasons limit year-round forcing capability compared to southern prefectures. Sapporo's concentrated urban demand supports specialized cut-flower logistics bypassing Tokyo auction intermediaries.
Japan Floriculture Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue subscription-based residential services and pharmaceutical extract channels. The market structure stratifies across three tiers: integrated breeding-to-distribution conglomerates, regional greenhouse operators with captive forcing expertise, and import-dependent wholesalers facing margin compression from auction disintermediation. Dominant competitive moves include backward integration into proprietary genetics and strategic partnerships with hospitality procurement consortia.
Within the integrated breeding tier, Takii & Co., Ltd and Sakata Seed Corporation exemplify century-old seed-to-market control over proprietary cultivar pipelines. Suntory Flowers Ltd occupies a distinct position through patented floral genetics and controlled-environment propagation systems. These three entities anchor the premium segment where variety protection enforcement under METI's Seed and Seedlings Law creates structural barriers for smaller nurseries seeking comparable market access.
| Leading Market Players |
|---|
| Hokkaido Green Co., Ltd |
| Takii & Co., Ltd |
| Ota Floriculture Auction Co., Ltd |
| Sakata Seed Corporation |
| Fuji Flower Industry Co., Ltd |
| Dümmen Orange |
| Shiraishi Flower Farm Co., Ltd |
| Suntory Flowers Ltd |
| Kawachiya Nursery Co., Ltd |
| Others |
Supply & Pricing Matrix
Tokyo LNG futures pricing cascades through Japan's floriculture supply chain, compressing margins at heated greenhouse operations in Ibaraki and Chiba while concentrating pricing power among Aichi and Shizuoka growers with geothermal and LED retrofits. This energy-cost divergence stratifies the market into three distinct procurement tiers.
Pricing Analysis
Distributor margins at Ota Market auction houses capture 15-25% spreads between grower receipts and florist purchases, with direct-to-hotel contracts bypassing this layer entirely. Three-tier pricing structure across premium, standard, and economy levels reflects GAP certification status, vase-life extension treatment, and volume commitment scale. Cost compression in standard-tier chrysanthemums is intensifying because Dutch import competition through Yokohama port terminals forces domestic growers to absorb freight differentials. Event planners and luxury hospitality buyers exhibit the lowest price sensitivity, while municipal landscaping contracts show acute responsiveness to per-stem differentials.
Supply Chain Analysis
Single-source vulnerability sits with Dutch bulb suppliers controlling 60-70% of global tulip and hyacinth propagation genetics, forcing Japanese bedding plant nurseries into royalty-dependent licensing structures. Domestic supply draws from heated greenhouse concentration in Aichi, Shizuoka, and Ibaraki prefectures, with propagation stock resting on Takii and Sakata breeding programs. Tariff exposure through Yokohama and Kobe port terminals for imported cut flowers creates margin volatility during yen depreciation cycles. Distribution runs through Tokyo's Ota Market auction halls for price discovery, with direct contracts disintermediating wholesale layers for premium hospitality procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's floriculture sector offers geographic-arbitrage positioning between Kansai's underdeveloped wholesale infrastructure and Tokyo's auction-saturated density, exploiting the logistics cost differential that favors direct-to-florist networks in Osaka.
For Market Incumbents: Deepen backward integration into proprietary cultivar development to escape royalty burdens on Dutch bulb genetics, while consolidating heated greenhouse capacity in Aichi and Shizuoka to capture METI carbon-accounting compliance advantages over Chiba competitors facing natural gas price volatility. For New Entrants and Emerging Players: Enter via apartment gardening subscription models targeting Tokyo's dense residential tower stock, exploiting the white space in recurring-revenue plant leasing that incumbent wholesalers have ceded to retail channels, with last-mile delivery partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale greenhouse operators in Kansai possessing GAP certification infrastructure but lacking brand recognition, as Osaka corporate wellness program adoption accelerates and direct procurement relationships displace auction intermediaries. Watch METI's enforcement timeline for greenhouse energy-cost reporting as the inflection signal for capital allocation toward LED and geothermal retrofits.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Cultivar Development | Takii and Sakata breeding programs lock in variety protection royalties that smaller nurseries cannot replicate under METI's Seed and Seedlings Law enforcement. |
| Direct-to-Hospitality Contracts | Roppongi and Ginza hotel chains bypass Ota Market intermediaries to secure vase-life guarantees and aesthetic standardization across multi-property portfolios. |
| LED Retrofit Investment | METI carbon-accounting rules for greenhouse energy costs favor growers with efficient supplemental lighting systems in Aichi and Shizuoka prefectures. |
| Subscription Service Launch | Tokyo apartment density enables recurring-revenue capture from balcony gardening services displacing traditional retail purchase patterns. |
| GAP Certification Consolidation | MAFF's tightened pesticide residue thresholds disqualify smaller Chiba farms lacking precision spray technology and digital logging infrastructure. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with greenhouse operations managers, Ota Market auction house executives, hotel procurement directors, and MAFF regulatory affairs officers with secondary validation through MAFF agricultural statistics, METI energy consumption surveys, Japan Flower Auction Association transaction records, and customs import data. Bottom-up grower capacity assessments and top-down wholesale volume estimates were triangulated to constrain forecast variance.
Segment-weighting approaches modeled product type splits across cut flowers, potted plants, bedding plants, and bulbs, with distribution channel dynamics and customer sophistication tiers as cross-cutting dimensions. CAGRs were derived from production capacity trajectories, import substitution elasticities, and corporate wellness program adoption curves across the projection horizon. Forecast inputs incorporated heated greenhouse expansion timelines, METI regulatory enforcement schedules, and hospitality procurement contract renewal patterns.
Inputs from MAFF and METI statistical releases were available through the study window; gaps in real-time auction transaction pricing and private hospitality contract terms introduce uncertainty bands around wholesale volume estimates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Uncaria Tomentosa Market
Agriculture and Agri Products
Guarana Market
Agriculture and Agri Products
Rapeseed Oil Market
Agriculture and Agri Products
Elaeis Guineensis Kernel Oil Market
Agriculture and Agri Products
Henequen Market
Agriculture and Agri Products
Mexico Compound Feed Market
Agriculture and Agri Products
Feed Protein Market
Agriculture and Agri Products
Boswellia Market
Agriculture and Agri Products
Cassava Starch Market
Agriculture and Agri Products
Sugar Cane Market
Agriculture and Agri Products
Marine Algae Market
Agriculture and Agri Products
Residential Organic Compost Market
Agriculture and Agri Products
United States Floriculture Market
Agriculture and Agri Products
High Fiber Feed Market
Agriculture and Agri Products
North America Swine Feed Premix Market
Agriculture and Agri Products
Vietnam Shrimp Feed Market