
 South America Poultry Feed Market | 2026-2036
South America Poultry Feed Market Size, Share, and Industry Trends Forecast 2026-2036
South America Poultry Feed Market Analytics
Subscription-based feed formulation software is consolidating how nutritionists and procurement teams interact with suppliers across South America. Cargill, Incorporated leverages its digital platforms to lock in recurring advisory revenue from large integrators. BRF S.A. anchors its competitive stance through captive feed mills that supply its vertically owned poultry operations. De Heus Animal Nutrition extends its footprint by specializing in customized premix services for mid-sized farms in Brazil's interior.
South America poultry feed comprises scientifically formulated rations combining corn, soybean meal, amino acids, vitamins, and minerals to optimize bird growth rates and feed conversion ratios across broiler and layer operations. Pellet form dominates industrial-scale consumption because pelleting reduces feed waste and improves nutrient digestibility in automated systems. Broiler feed captures the largest volume share due to Brazil and Argentina's export-oriented meat production, while layer feed generates steadier margin pools from contracted egg supply chains. Soybean meal remains the irreplaceable protein anchor, though regional price volatility pushes integrators toward alternative ingredient trials.
Brazil's MAPA enforces mycotoxin thresholds and traceability rules that elevate compliance costs for imported premixes and domestic millers alike. Argentina's SENASA oversees feed safety protocols that restrict certain growth promoters, aligning gradually with Codex Alimentarius guidelines. Stakeholders must monitor how these regulatory frameworks evolve, as compliance investments will separate integrated operators from fragmented backyard producers unable to absorb certification burdens.
Market Dynamics
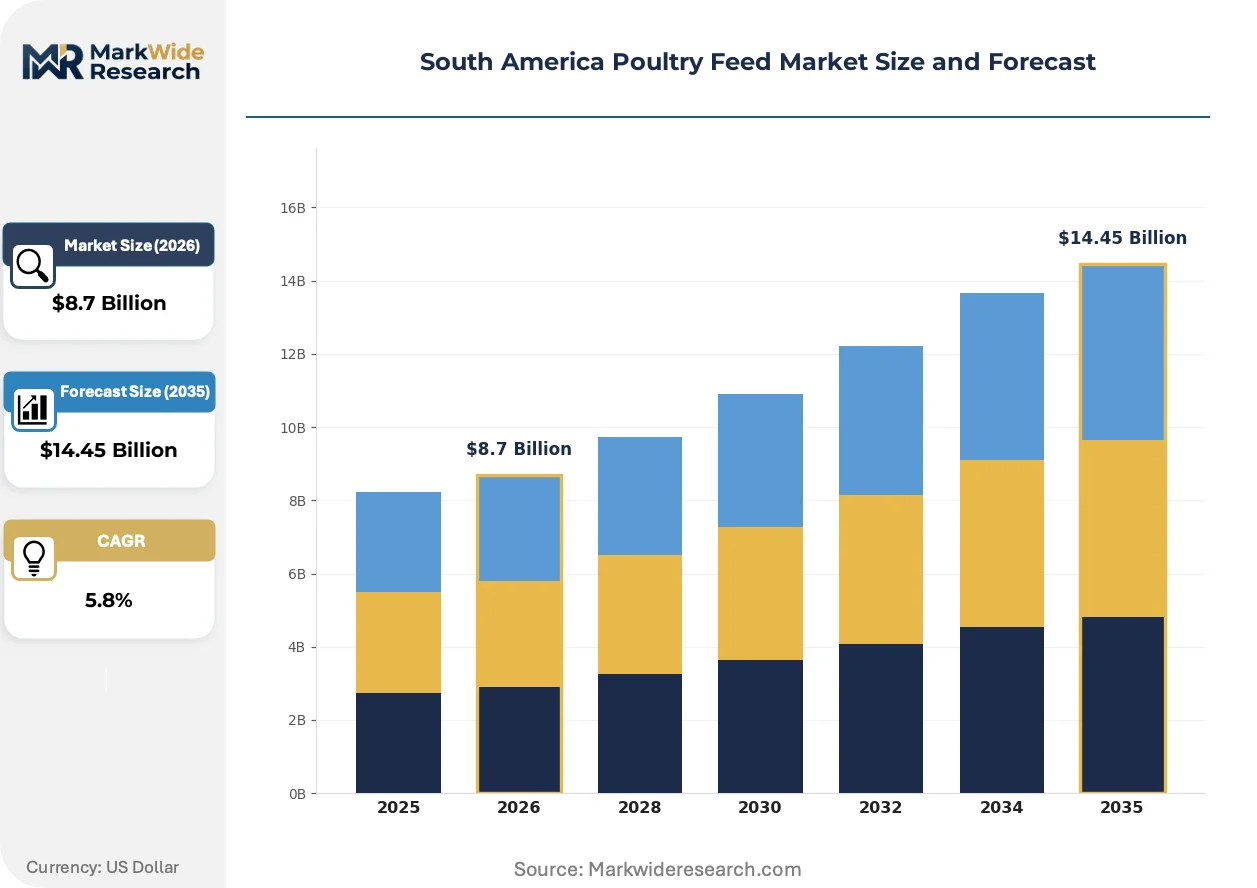
Brazil's MAPA enforcement of stricter mycotoxin thresholds is forcing millers and integrators to restructure quality assurance protocols, elevating capital requirements and compressing margins for non-compliant operators across the region.
Growth Catalysts
- Export-oriented broiler production:Santa Catarina and Paraná processing clusters drive bulk feed procurement from integrated operations serving Middle Eastern and Asian meat buyers.
- MAPA's traceability mandates:Brazil's federal agriculture ministry requires documented supply chain records, advantaging large millers with existing digital infrastructure over fragmented competitors.
- Pelleting technology diffusion:Automated pelleting lines reduce feed waste and improve digestibility, compelling mid-sized Argentine farms to upgrade from mash-based systems.
Market Restraints
- Soybean meal price volatility:Argentina's crushing sector concentration exposes Brazilian integrators to input cost spikes during drought cycles in the Pampas grain belt.
- Import dependency for amino acids:Lysine and methionine supply concentrates among Chinese and Southeast Asian manufacturers, creating foreign exchange and logistics vulnerabilities.
- SENASA growth promoter restrictions:Argentina's national food safety agency limits certain antibiotic feed additives, narrowing formulation options for cost-conscious producers.
Strategic Opportunities
- Brazil's interior states:Mato Grosso and Goiás poultry expansion lags feed mill density, creating white space for localized premix and concentrate distribution.
- Subscription formulation platforms:Nutrition software-as-a-service locks in recurring revenue from integrators seeking real-time diet optimization against volatile ingredient costs.
- Precision fermentation proteins:Alternative amino acid production methods promise supply chain decoupling from agricultural commodity cycles.
Industry Challenges
- Mycotoxin testing capacity:Certified laboratory infrastructure remains concentrated in São Paulo and Buenos Aires, creating sample backlogs for interior millers.
- Legacy mill automation gaps:Older Brazilian facilities lack integrated batching and pelleting controls, complicating MAPA compliance documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Poultry Feed Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Layer Feed, Broiler Feed, Starter Feed, Grower Feed Form: Pellets, Crumbles, Mash, Liquid Ingredient: Corn, Soybean Meal, Wheat, Fish Meal End User: Poultry Farms, Feed Mills, Integrators, Others |
| Companies Covered | Cargill, Incorporated, ADM, Alltech, Nutreco, Land O’ Lakes Inc., BRF S.A., JBS S.A., Bunge Limited, De Heus Animal Nutrition, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Poultry Feed Market Evolving Landscape
Digital advisory platforms and precision nutrition tools are compressing the traditional separation between feed formulation expertise and procurement execution across South American poultry operations.
Near-infrared spectroscopy coupled with cloud-based formulation algorithms is unifying real-time ingredient quality assessment with diet adjustment protocols. Large Brazilian integrators deploy these systems across multiple feed mills simultaneously. The technology is unifying previously siloed nutrition and purchasing functions into single workflow platforms.
Argentina's SENASA alignment with Codex Alimentarius guidelines restricts certain antibiotic growth promoters in broiler rations. Feed compounders reformulate with acidifiers and phytogenics to maintain performance metrics. Layer operations in Buenos Aires province face the steepest reformulation costs due to extended production cycles.
Buyer concentration among vertically integrated meatpackers compresses switching options for independent feed suppliers. Contract structures now bundle nutrition advisory with physical feed delivery, displacing spot-market transactions. Chilean layer producers demonstrate this shift most visibly, with egg supply chains consolidating around single-source feed partnerships.
South America Poultry Feed Market Segmentation
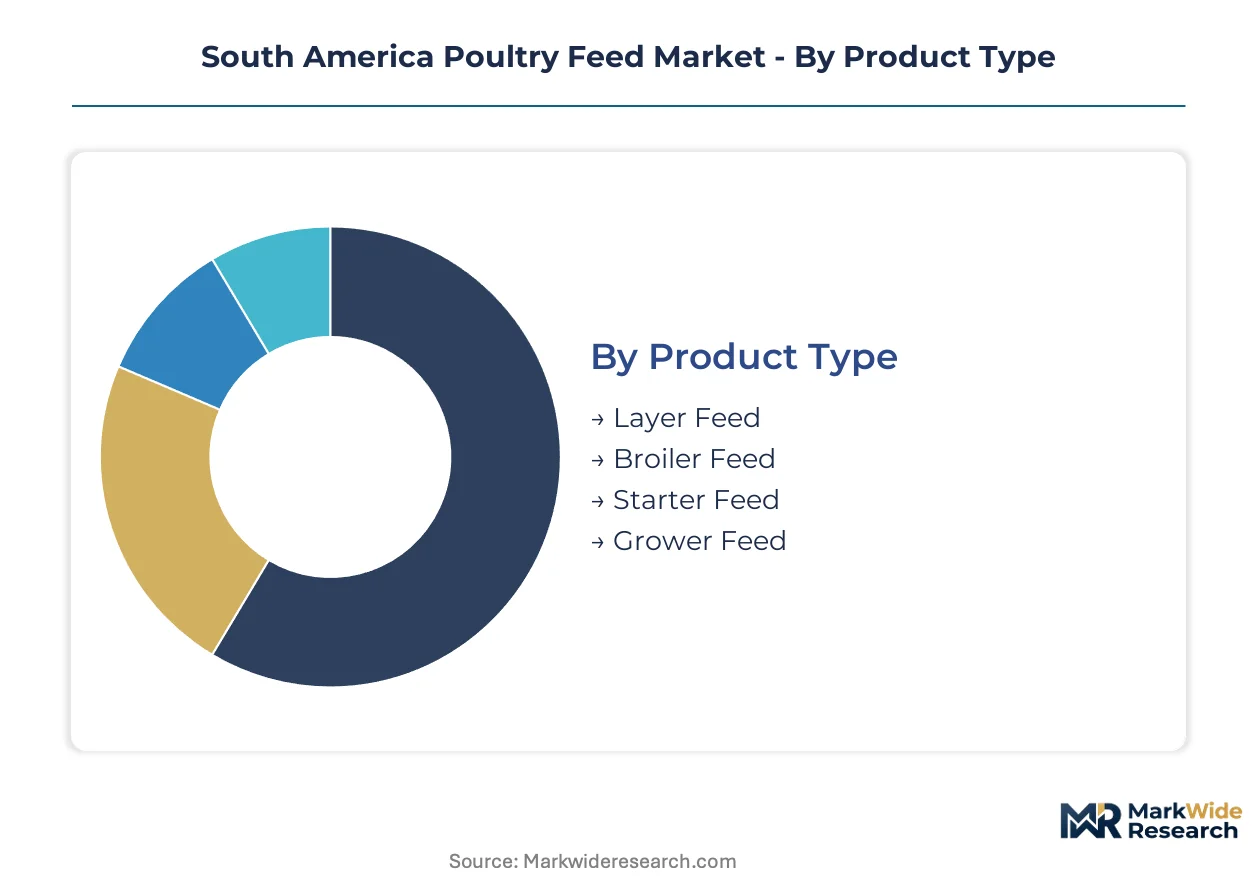
South America's poultry feed segmentation reflects capital deployment patterns across Brazil and Argentina's integrated supply chains. Feed form and ingredient sourcing decisions determine equipment investment requirements and working capital intensity for millers serving export-oriented broiler operations.
Product Type:
Capital intensity varies sharply across life-stage formulations, with grower and broiler feeds demanding the largest pelleting line investments.
- Broiler Feed:High-density formulations optimize feed conversion ratios for export-weight birds bound for Middle Eastern and Asian markets. Santa Catarina processing clusters drive concentrated procurement from vertically integrated operations with dedicated feed mill capacity.
- Layer Feed:Steadier margin pools emerge from extended production cycles in Buenos Aires province egg supply chains, though lower per-ton throughput requirements reduce capital intensity versus broiler formulations. SENASA growth promoter restrictions elevate reformulation costs for these longer-cycle rations.
- Starter Feed:Precision-milled crumbles with elevated amino acid density for chick development phases.
- Grower Feed:Transition formulations bridging starter and finisher nutrient profiles for mid-cycle weight gain.
Broiler feed absorbs the bulk of installed capacity; layer feed is expanding most quickly.
Form:
Processing technology differentiation separates industrial-scale operators from backyard producers unable to justify automated equipment.
- Pellets:Extruded cylindrical forms reduce feed waste and improve nutrient digestibility in automated distribution systems. Paraná's largest integrators have standardized on pelleting lines to meet MAPA traceability documentation requirements.
- Crumbles:Broken pellet fragments sized for starter-phase chicks, requiring dedicated crumbling rolls downstream of pelleting units. Argentine mid-sized farms in Córdoba province increasingly specify crumbles to reduce selective feeding behavior.
- Mash:Unprocessed ground mixtures retain lower capital barriers for legacy facilities.
- Liquid:Pumpable nutrient suspensions for specialized additive delivery systems.
Pellet capacity dominates mill infrastructure investment; crumbles are gaining share fastest among starter-phase formulations.
Ingredient:
Input cost volatility and supply security shape procurement strategies across Brazil's southern states and Argentina's Pampas grain belt.
- Soybean Meal:Irreplaceable protein anchor supplying essential amino acid profiles for optimal bird growth. Argentina's crushing sector concentration exposes Brazilian integrators to price spikes during drought cycles.
- Corn:Primary energy source with regional price advantages in Mato Grosso production zones. MAPA mycotoxin thresholds force elevated testing expenditure for imported shipments.
- Wheat:Alternative carbohydrate source when corn basis widens in southern Brazilian markets.
- Fish Meal:Premium protein additive for specialized breeder rations with limited regional production.
Soybean meal commands the largest procurement expenditure; corn is climbing fastest as interior state poultry expansion reduces transport costs.
End User:
Customer scale and integration depth determine formulation complexity and advisory service bundling.
- Integrators:Vertically controlled operations combining feed milling with owned processing plants and contract grower networks. BRF S.A. and similar groups operate captive mills with nutrition teams optimizing diets against real-time ingredient assays.
- Feed Mills:Independent compounders serving fragmented farm bases with standardized formulations and spot-market pricing. These operators face margin compression from MAPA compliance documentation requirements.
- Poultry Farms:Direct procurement relationships with millers for owned-flock operations without captive milling capacity.
- Others:Specialty producers including hatcheries and research facilities with low-volume, high-specification requirements.
Integrators concentrate the largest formulation volumes; independent feed mills are consolidating fastest under regulatory compliance pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil produces the majority of South America's poultry feed yet Argentina's crushing sector supplies critical protein inputs, creating a cross-border production dependency that shapes regional trade flows.
Brazil
Santa Catarina and Paraná host dense clusters of industrial broiler operations that drive concentrated feed procurement from vertically integrated mills. MAPA enforces mycotoxin thresholds and traceability mandates that elevate compliance costs for domestic millers and imported premix suppliers alike. São Paulo state's laboratory infrastructure concentrates testing capacity, leaving interior millers in Mato Grosso and Goiás facing sample backlogs during peak harvest periods.
Argentina
The Pampas grain belt anchors regional soybean meal supply, though drought cycles expose Brazilian integrators to acute price volatility. SENASA restricts certain antibiotic growth promoters in feed formulations, compelling compounders to reformulate with acidifiers and phytogenics. Córdoba province's mid-sized farms increasingly specify crumbles over mash to reduce selective feeding behavior in starter-phase chicks.
Chile
Layer operations in the Central Valley demonstrate the most visible consolidation around single-source feed partnerships, displacing spot-market transactions. The country's national food safety agency maintains alignment with Codex Alimentarius guidelines that limit residual antibiotics in egg supply chains. Santiago's feed mills bundle nutrition advisory with physical delivery, locking in extended contracts with contracted egg producers.
Colombia
Poultry expansion in the Cundinamarca and Antioquia departments lags behind feed mill density, creating distribution white space for premix and concentrate suppliers. The national agricultural institute enforces grain quality standards that intersect with regional mycotoxin protocols. Bogotá's procurement teams increasingly trial alternative amino acid sources to hedge against lysine and methionine import dependencies.
Peru
Coastal desert valleys concentrate layer operations that depend on imported feed ingredients due to limited domestic grain production. The country's sanitary authority oversees feed safety protocols that restrict certain growth promoters, narrowing formulation options for cost-conscious producers. Lima's integrators face higher logistics costs that compress margins relative to southern cone competitors.
South America Poultry Feed Market Competitive Landscape
Top-tier vendors anchor integrated supply chains with captive milling capacity, while independent compounders serve fragmented farm bases with standardized formulations. Mid-sized specialists occupy positions in customized premix services and digital advisory platforms. The vendor base stratifies across three archetypes: multinational agribusiness conglomerates with regional crushing assets, domestic integrators with backward integration into feed production, and nutrition-focused specialists with formulation software subscriptions. Dominant competitive moves include geographic expansion into Brazil's interior states and technology licensing for automated pelleting lines.
Among Dutch-origin specialists, De Heus Animal Nutrition exemplifies the customized premix archetype for mid-sized Brazilian farms. Cargill, Incorporated and BRF S.A. occupy positions at opposite ends of the integration spectrum—Cargill as a multinational agribusiness with digital platform leverage, BRF as a domestic integrator with captive mill networks. These three represent the primary competitive vectors shaping procurement relationships across the region.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| ADM |
| Alltech |
| Nutreco |
| Land O' Lakes Inc. |
| BRF S.A. |
| JBS S.A. |
| Bunge Limited |
| De Heus Animal Nutrition |
| Others |
Value Network & Pricing Analysis
Chicago Board of Trade corn futures volatility cascades through South American poultry feed pricing tiers, compressing margins for independent compounders while integrators with captive crushing assets buffer input cost spikes through backward integration into grain origination.
Pricing Analysis
Margin tightening in standard-grade broiler formulations reflects Argentine soybean meal basis widening during Pampas drought cycles. Three-tier pricing structure across premium-certified, standard-compliant, and economy-grade formulations separates MAPA-traceable integrator supply from spot-market mash. Cost-down pressure on independent feed mills accelerates because SENASA documentation requirements force quality-assurance investments that fragment producers cannot amortize. Contract grower networks exhibit highest price sensitivity; vertically owned operations least.
Supply Chain Analysis
Direct-to-integrator channels handle bulk formulated feed procurement from Santa Catarina processing clusters. Geographic supply concentrates in Brazil's southern states, Argentina's Pampas grain belt, and Paraguay's expanding soy frontier. Raw material dependencies rest on imported lysine and methionine from Southeast Asian manufacturers, regional corn harvests, and Argentine crushing output. Single-source vulnerability in amino acid supply creates foreign exchange exposure. Distribution runs through captive mill networks for large integrators and regional depots for independent compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South American poultry feed is transitioning from commodity spot transactions to subscription-based nutrition platforms, with cloud-based formulation software displacing legacy advisory relationships between nutritionists and procurement teams.
For Market Incumbents: Acquire digital formulation platform capabilities to lock in recurring revenue streams from integrator clients. Integrators like BRF S.A. must defend against SaaS-based competitors by deepening in-house nutrition analytics infrastructure. MAPA compliance documentation investments create barriers that captive mill networks can leverage against fragmented independent compounders. For New Entrants and Emerging Players: E-commerce premix distribution routes offer lowest-friction entry into Brazil's interior states where feed mill density lags poultry expansion. Mato Grosso and Goiás present penetrable white space for localized concentrate suppliers. Target mid-sized farms seeking customized starter-phase formulations without captive milling infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor independent Brazilian compounders facing MAPA compliance cost burdens in São Paulo-adjacent regions. Long-term viability hinges on feed mill automation technology and digital advisory platform integration. Watch precision fermentation protein commercialization as supply-chain-decoupling inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Origination | Captive corn and soybean supply buffers Brazilian integrators against CBOT volatility and Argentine drought cycles. |
| Cloud-Based Formulation Platform Deployment | Real-time diet optimization locks in recurring advisory revenue from large Santa Catarina processing clusters. |
| Automated Pelleting Line Upgrade | MAPA traceability documentation compliance compels legacy Brazilian facilities to modernize batching controls. |
| Precision Fermentation Protein Partnership | Alternative amino acid production methods promise decoupling from agricultural commodity price cycles. |
| Interior State Distribution Network Buildout | Localized premix capacity in Mato Grosso captures poultry expansion ahead of feed mill density. |
Research Methodology
USDA GAIN reports, ANVISA regulatory filings, and Brazilian customs trade data formed the secondary backbone for supply chain mapping and input cost modeling. Primary interviews with feed mill operations managers, poultry integrator procurement directors, MAPA compliance officers, nutrition software platform developers, and Argentine crushing sector executives validated secondary findings. Bottom-up volume estimates from state-level poultry flock data triangulated against top-down value projections from feed production statistics.
Bottom-up modeling aggregated individual facility capacity and utilization rates across Brazil's southern states and Argentina's Pampas region. Segmentation dimensions included feed form, life-stage formulation, ingredient composition, and end-user integration depth. CAGRs derived from trend extrapolation of poultry flock expansion rates and feed conversion ratio improvements. Industry-specific forecast inputs encompassed MAPA regulatory compliance cost trajectories and precision fermentation protein commercialization timelines across the projection horizon.
The model holds under stable Brazilian real exchange rate conditions and consistent MAPA enforcement intensity; deviation in Argentine drought frequency or amino acid import disruption would shift volume and value outputs. Forecasts reflect documented assumptions about technology adoption curves and regulatory implementation pace. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
South America Cashew Market
Agriculture and Agri Products
Europe Alfalfa Hay Market
Agriculture and Agri Products
North America Bonsai Market
Agriculture and Agri Products
Australia Compound Feed Market
Agriculture and Agri Products
Consumer Floriculture Market
Agriculture and Agri Products
Egypt Compound Feed Market
Agriculture and Agri Products
Canada Ornamental Horticulture Market
Agriculture and Agri Products
France Alfalfa Hay Market
Agriculture and Agri Products
Africa Orange Market
Agriculture and Agri Products
Henequen Market
Agriculture and Agri Products
Indonesia Bamboos Market
Agriculture and Agri Products
Livestock and Meat Market
Agriculture and Agri Products
Live Goods Market
Agriculture and Agri Products
Fermented Soybean Meal Protein for Animal Feed Market
Agriculture and Agri Products
Europe Guar Market
Agriculture and Agri Products
Cassava Starch Market