
 Europe Poultry Feed Market | 2026-2036
Europe Poultry Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Poultry Feed Market Foresight
Premium antibiotic-free feed specification tiers is unwinding conventional commodity pricing across the European supply base. Cargill Incorporated leverages its transcontinental grain origination network to secure non-GMO soybean flows into western European compound plants. De Heus Animal Nutrition anchors its position through backward integration into Dutch premix manufacturing, while Nutreco NV differentiates via marine-derived omega-3 enrichment technologies for premium broiler contracts.
Europe poultry feed comprises nutritionally complete rations formulated from cereal grains, protein meals, vitamins, and functional additives to optimize feed conversion ratios and carcass yield in broiler, layer, and turkey operations. Manufacturing employs thermal conditioning and pelleting at temperatures exceeding 80 degrees Celsius to deactivate anti-nutritional factors and improve starch gelatinization for intestinal absorption. Complete feed dominates volume flows through integrated poultry operations, while organic feed registers the fastest structural expansion as German and French retailers enforce cage-free and organic shelf-space commitments. Protein meals, particularly soybean meal and rapeseed meal, command the densest margin pools due to EU import dependence and sustainability certification premiums.
EMA feed additive authorizations, EU Green Deal methane-reduction targets, and national implementations of the F-Gas Regulation shape formulation choices and capital allocation across the value chain. REACH compliance for novel enzymes and mycotoxin binders extends development timelines, pushing smaller millers toward licensed premix suppliers rather than proprietary formulation. Stakeholders must monitor the interplay between deforestation-free supply chain mandates and Black Sea grain corridor stability when committing to multi-year protein sourcing contracts.
Market Dynamics
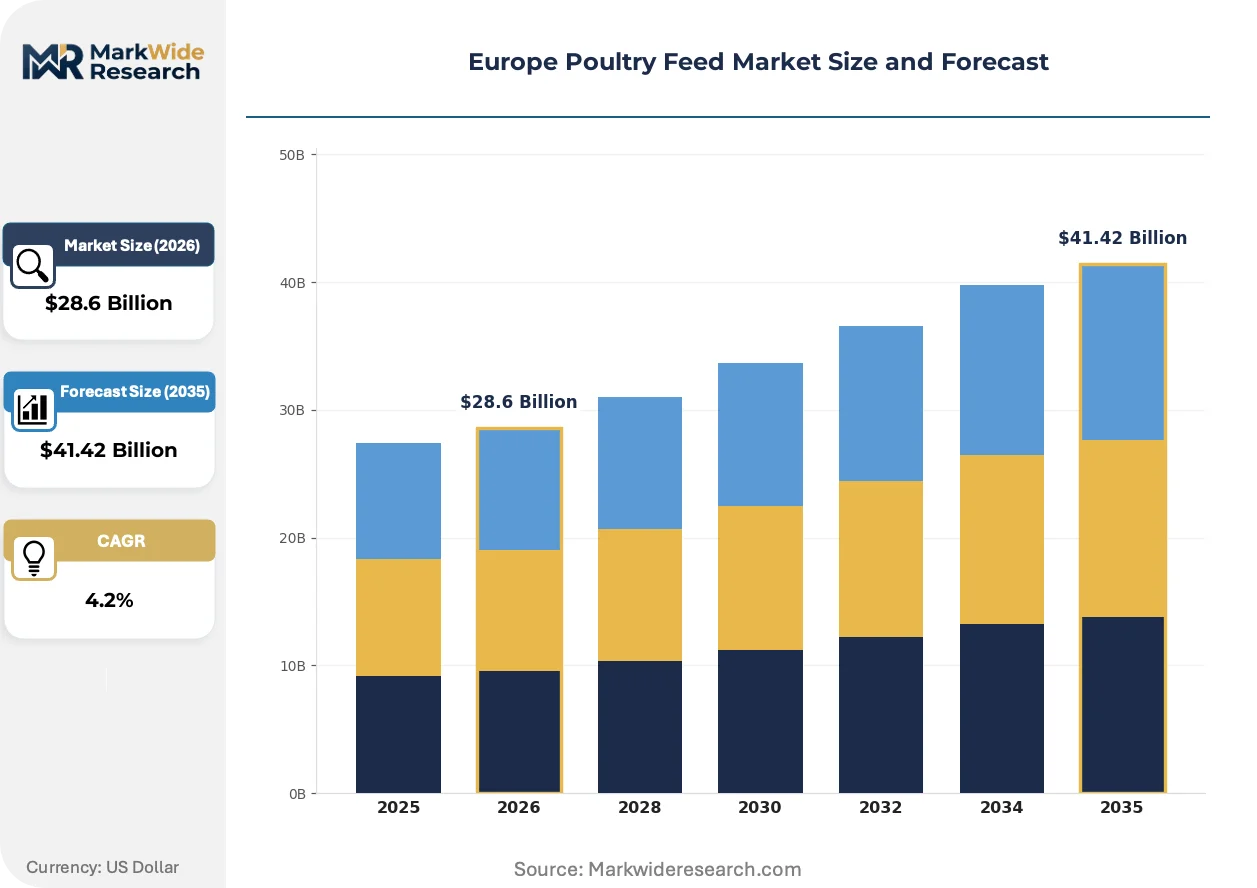
The EU Green Deal's Farm to Fork Strategy is compressing formulation timelines as integrators retrofit compound plants to meet deforestation-free protein mandates and methane-reduction targets. This regulatory pressure is redrawing procurement geography and capital allocation across the European supply base.
Growth Catalysts
- REACH-authorized enzyme portfolios:Novel carbohydrases and phytases approved by ECHA are unlocking nutrient digestibility gains in wheat-barley rations, trimming feed conversion ratios for Dutch and Danish broiler operations.
- Organic retail shelf-space mandates:German and French supermarket chains are enforcing cage-free and organic protein commitments, pulling compound feed demand toward certified non-GMO and insect-protein formulations.
- Black Sea grain corridor flows:Stabilized Ukrainian corn and wheat exports through Romanian and Polish ports are diversifying cereal sourcing for Spanish and Italian millers.
Market Restraints
- Soybean meal import dependence:European crushing capacity covers under half of protein meal demand, exposing margin pools to Brazilian and Argentinian export volatility and sustainability certification premiums.
- EMA additive authorization timelines:Novel mycotoxin binders and gut health modifiers face 18-24 month evaluation windows, freezing formulation innovation for smaller independent mills.
- Natural gas price sensitivity:Pelleting and thermal conditioning operations consume substantial energy inputs, compressing operating margins when TTF hub prices spike.
Strategic Opportunities
- Polish and Romanian greenfield capacity:Underpenetrated compound feed production in eastern Europe offers location economics for Black Sea grain origination and lower labor costs.
- Insect protein regulatory opening:EFSA novel food approvals for black soldier fly meal in poultry rations create formulation white space for domestic protein sourcing.
- Precision nutrition service models:Real-time flock monitoring combined with dynamic ration adjustment is creating subscription revenue streams for integrated nutrition advisors.
Industry Challenges
- Formulation chemist scarcity:Expertise in amino acid optimization and anti-nutritional factor mitigation is concentrating at large premix suppliers, constraining independent mill R&D.
- Multi-standard audit fatigue:Simultaneous compliance with RSPO, FEFAC Soy Sourcing Guidelines, and national organic schemes is extending certification timelines and raising administrative burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Poultry Feed Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $41.42 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Complete Feed, Medicated Feed, Specialty Feed, Organic Feed Ingredient Type: Cereal Grains, Protein Meals, Vitamins, Additives End User: Poultry Farmers, Feed Millers, Livestock Producers, Retailers Distribution Channel: Online Retail, Direct Sales, Distributors, Agricultural Stores |
| Companies Covered | Cargill Incorporated, Terrena, Royal Agrifirm Group, De Heus Animal Nutrition, Danish Agro, ForFarmers, Nutreco NV, Alltech Inc., Archer Daniels Midland Co., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Poultry Feed Market Shifts & Advancements
Digital feeding systems and novel protein sources are compressing the gap between genetic potential and realized flock performance. These shifts are redrawing supplier relationships and investment priorities across the value chain.
Precision liquid feeding technology is miniaturizing nutrient delivery from bulk silo operations to individual pen-level dosing. Broiler integrators in the Netherlands and Belgium are piloting sensor-driven systems that adjust lysine and methionine ratios hourly based on real-time weight gain data. This granularity is miniaturizing the economic unit of feed optimization from barn-level to bird-level, eroding the value of standardized compound rations.
EMA's streamlined feed additive authorization pathway is accelerating market entry for novel enzymes and postbiotic formulations. The regulatory shift compresses development timelines from 36 months toward 18 months for qualified submissions. Layer operations in France and Germany are the primary beneficiaries, integrating gut health modifiers ahead of antibiotic-free production mandates.
Retailer-driven procurement consolidation is compressing supplier lists as supermarket chains demand single-point accountability for deforestation-free and welfare-compliant protein. French and UK poultry integrators are responding by awarding multi-year compound feed contracts to vertically integrated nutrition houses with captive premix and grain origination capabilities. This concentration is displacing spot-market relationships and fragmenting the independent mill sector.
Europe Poultry Feed Market Segmentation
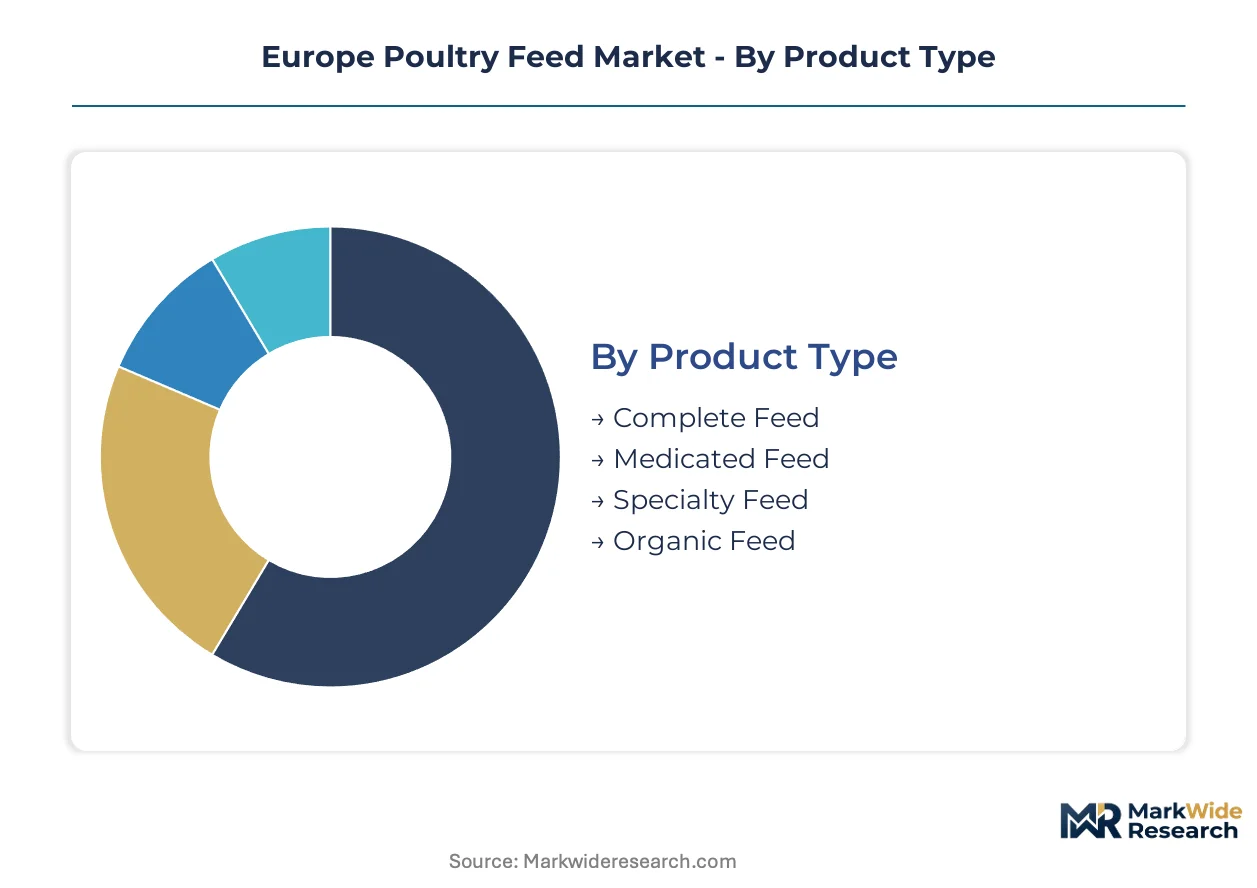
Segmentation in the Europe poultry feed market reveals how regulatory pressure and supply chain configuration concentrate margin pools across distinct product tiers and customer channels. Understanding these divisions exposes where EMA authorization timelines and deforestation-free mandates reshape procurement geography.
Product Type:
EMA feed additive authorizations and EU Green Deal methane targets differentiate formulation complexity across product tiers, with compliance costs stratifying competitive positioning.
- Complete Feed:Nutritionally balanced rations incorporating cereal grains, protein meals, and micronutrients in single-pellet form. Dutch and Spanish broiler integrators concentrate procurement here as Farm to Fork Strategy audits demand full traceability from compound plants.
- Specialty Feed:Functional formulations targeting antibiotic-free production, omega-3 enrichment, or gut health modulation. French layer operations pull demand fastest as retailer welfare mandates tighten ahead of national implementation schedules.
- Medicated Feed:Veterinary prescription rations containing coccidiostats or therapeutic additives under strict withdrawal protocols. Regulatory concentration at EMA level limits formulation flexibility for smaller millers.
- Organic Feed:Certified non-GMO rations excluding synthetic amino acids and pesticides. German supermarket shelf-space commitments accelerate adoption despite 15-30% cost premiums over conventional equivalents.
Established volume favors complete feed; emerging adoption favors organic feed.
Ingredient Type:
Cost tier differentiation separates commodity inputs from value-added functional ingredients, with import dependence and sustainability certification reshaping procurement risk profiles.
- Protein Meals:Soybean meal and rapeseed meal deliver essential amino acids for muscle deposition and egg production. Crushing capacity constraints across the region expose margin pools to Brazilian export volatility and RSPO certification premiums.
- Additives:Enzymes, mycotoxin binders, and postbiotic formulations optimize nutrient digestibility and flock health. REACH authorization timelines compress development windows, pushing innovation toward large premix suppliers with regulatory affairs capacity.
- Cereal Grains:Wheat, corn, and barley provide metabolizable energy as ration foundations. Black Sea corridor stability through Romanian ports diversifies sourcing for Polish and Italian millers.
- Vitamins:Fat-soluble and water-soluble micronutrients preventing deficiency disorders in high-density production systems. Concentrated manufacturing in China and Germany creates supply concentration risk.
Volume concentration sits with cereal grains; steepest expansion trajectory belongs to additives.
End User:
Customer type determines service intensity and contract structure, with integration level dictating whether procurement flows through spot markets or multi-year supply agreements.
- Poultry Farmers:Broiler, layer, and turkey operations purchasing finished compound feed or concentrates for on-farm mixing. French and UK integrators are consolidating supplier lists under retailer-driven accountability mandates.
- Feed Millers:Independent and integrated compound plants formulating rations for captive use or third-party sale. REACH compliance costs are fragmenting the independent sector toward licensed premix dependence.
- Livestock Producers:Diversified operations with poultry as secondary species, often sourcing through agricultural cooperatives.
- Retailers:Supermarket chains and protein brands specifying deforestation-free and welfare-compliant feed for contracted supply chains.
Procurement scale favors poultry farmers; contract complexity favors retailers.
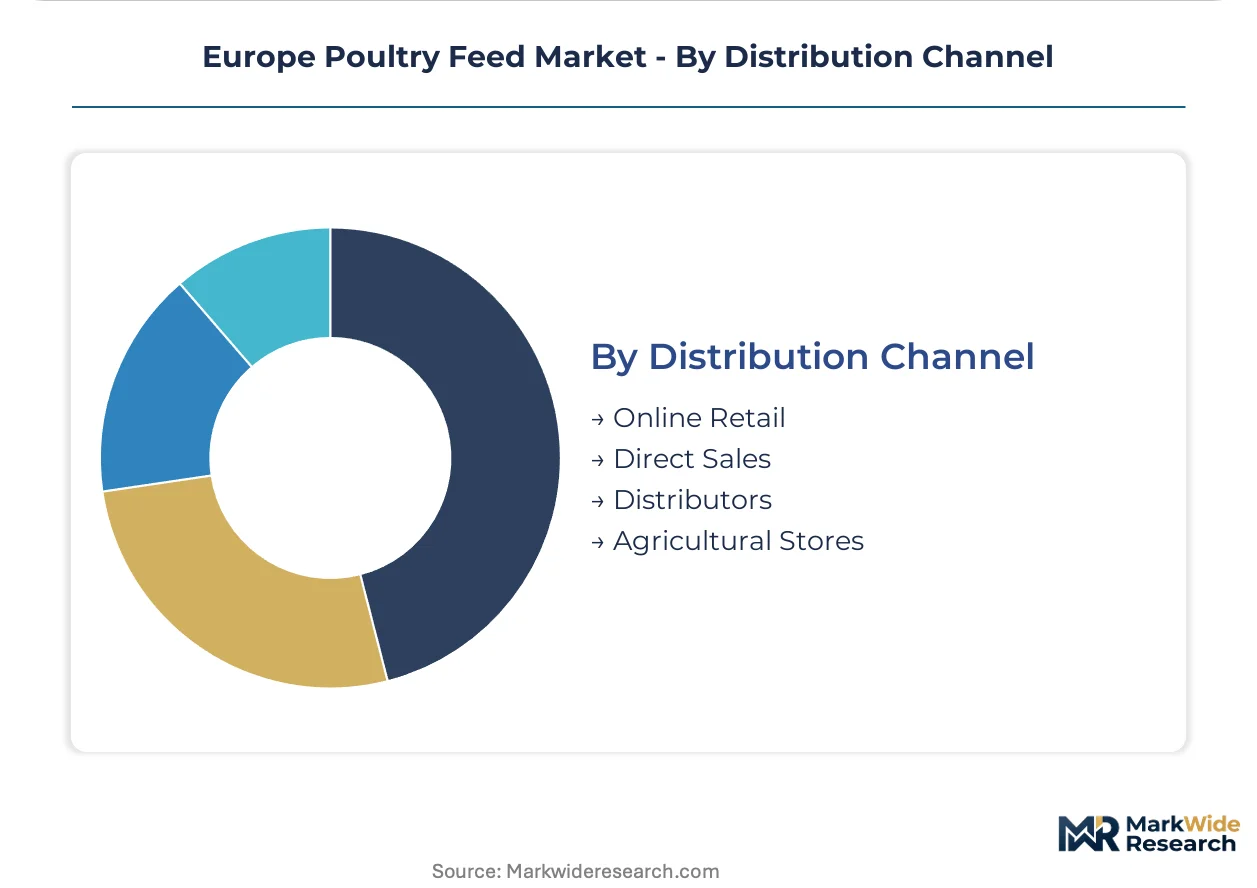
Distribution Channel:
Channel selection reflects customer scale and geographic concentration, with digital platforms gaining traction in fragmented farming regions.
- Direct Sales:Long-term supply contracts between compound plants and integrated poultry operations. Netherlands and Belgium lead contract penetration as precision nutrition services bundle with physical delivery.
- Distributors:Regional wholesalers stocking standard formulations for independent farmers. Eastern European underpenetration creates location economics for greenfield capacity.
- Agricultural Stores:Cooperative and independent retailers serving smallholder operations with bagged feed and nutritional advice.
- Online Retail:E-commerce platforms for specialty and organic feed in remote farming regions.
Relationship density favors direct sales; platform adoption favors online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compound feed milling capacity clusters in northwestern Europe, with Dutch and German plants commanding the densest margin pools through captive premix integration and precision nutrition services. Southern and eastern European markets exhibit underpenetrated production relative to broiler integration growth, creating location economics for greenfield investment.
Netherlands
Precision liquid feeding pilots and real-time flock monitoring concentrate demand among Dutch broiler integrators seeking bird-level nutrient optimization. EMA feed additive authorizations accelerate adoption of novel enzymes and postbiotic formulations in layer operations. The Gelderland and Overijssel provinces host the region's densest compound plant networks, with backward integration into premix manufacturing tightening supply chain control.
Germany
Organic retail shelf-space mandates from supermarket chains pull compound feed demand toward certified non-GMO and insect-protein formulations. The EU Green Deal's Farm to Fork Strategy compresses formulation timelines as integrators retrofit plants for deforestation-free protein compliance. Lower Saxony and North Rhine-Westphalia anchor production gravity, with agricultural cooperatives consolidating procurement for diversified livestock operations.
France
Retailer-driven procurement consolidation compresses supplier lists as chains demand single-point accountability for welfare-compliant protein sourcing. ANSM and national organic scheme audits extend certification timelines for antibiotic-free production mandates. The Brittany and Pays de la Loire regions concentrate broiler integration operations, with marine-derived omega-3 enrichment technologies differentiating premium contract tiers.
Spain
Broiler integration operations expand compound feed procurement as the EU Green Deal tightens environmental compliance requirements for protein sourcing. Black Sea grain corridor flows through Mediterranean ports diversify cereal sourcing for Catalan and Aragonese millers. The Ebro Valley and Catalonia host expanding captive feed production tied to vertically integrated poultry operations.
Poland
Eastern Europe's fastest-growing compound feed demand reflects broiler integration expansion and proximity to Black Sea grain origination. Lower labor costs and underpenetrated production capacity attract greenfield investment from western European nutrition houses. The Greater Poland and Lower Silesian voivodeships concentrate emerging milling clusters serving both domestic integrators and export-oriented operations.
Europe Poultry Feed Market Competitive Landscape
Concentration sits with transcontinental grain traders and vertically integrated nutrition houses that combine captive premix manufacturing with precision nutrition services. The supplier base stratifies across three tiers: global traders with origination networks, regional compounders with backward integration, and specialty premix houses with regulatory affairs capacity. Dominant competitive moves include multi-year contract awards from retailer-driven procurement consolidation and licensed premix partnerships that displace independent mill R&D.
Among Dutch-based integrated nutrition houses, De Heus Animal Nutrition and Nutreco NV exemplify the backward integration archetype, combining captive premix production with marine-derived functional ingredient portfolios. Cargill Incorporated anchors the transcontinental trader tier, leveraging grain origination networks to secure non-GMO soybean flows into western European compound plants. These three entities represent distinct positioning vectors—captive manufacturing, functional differentiation, and supply security—around which mid-scale independent millers and regional distributors orbit.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Terrena |
| Royal Agrifirm Group |
| De Heus Animal Nutrition |
| Danish Agro |
| ForFarmers |
| Nutreco NV |
| Alltech Inc. |
| Archer Daniels Midland Co. |
| Others |
Supply & Pricing Matrix
Ninety-day soybean meal inventory cycles concentrate pricing power with Brazilian and Argentinian exporters, compressing European compound feed margins when Black Sea grain corridor disruptions extend cereal lead times. Dutch and Spanish integrators absorb these shocks through multi-year contract structures, while independent millers face spot-market volatility.
Pricing Analysis
The EU Green Deal's Farm to Fork Strategy dictates the pricing tier structure across the European poultry feed supply base. Three-tier pricing structure across premium, standard, and economy levels separates RSPO-certified antibiotic-free formulations from conventional commodity rations. Price differentiation hinges on sustainability certification premiums and captive premix integration depth. Cost compression in standard-tier complete feed is intensifying because natural gas price spikes elevate thermal conditioning expenses. Smallholder cooperatives exhibit highest price sensitivity; vertically integrated broiler operations demonstrate lowest.
Supply Chain Analysis
Strategic stockpiling of Brazilian soybean meal dominates inventory strategy, with Dutch and German integrators maintaining 60-90 day buffers against export volatility. Supply concentrates in Brazil, Argentina, and Ukraine for protein meals and cereal grains. Raw material dependencies center on non-GMO soybean flows, Black Sea wheat and corn, and marine-derived omega-3 sources. Single-source vulnerability in Brazilian crushing capacity exposes margin pools to sustainability certification disruptions. Distribution runs through direct sales contracts between compound plants and integrated poultry operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
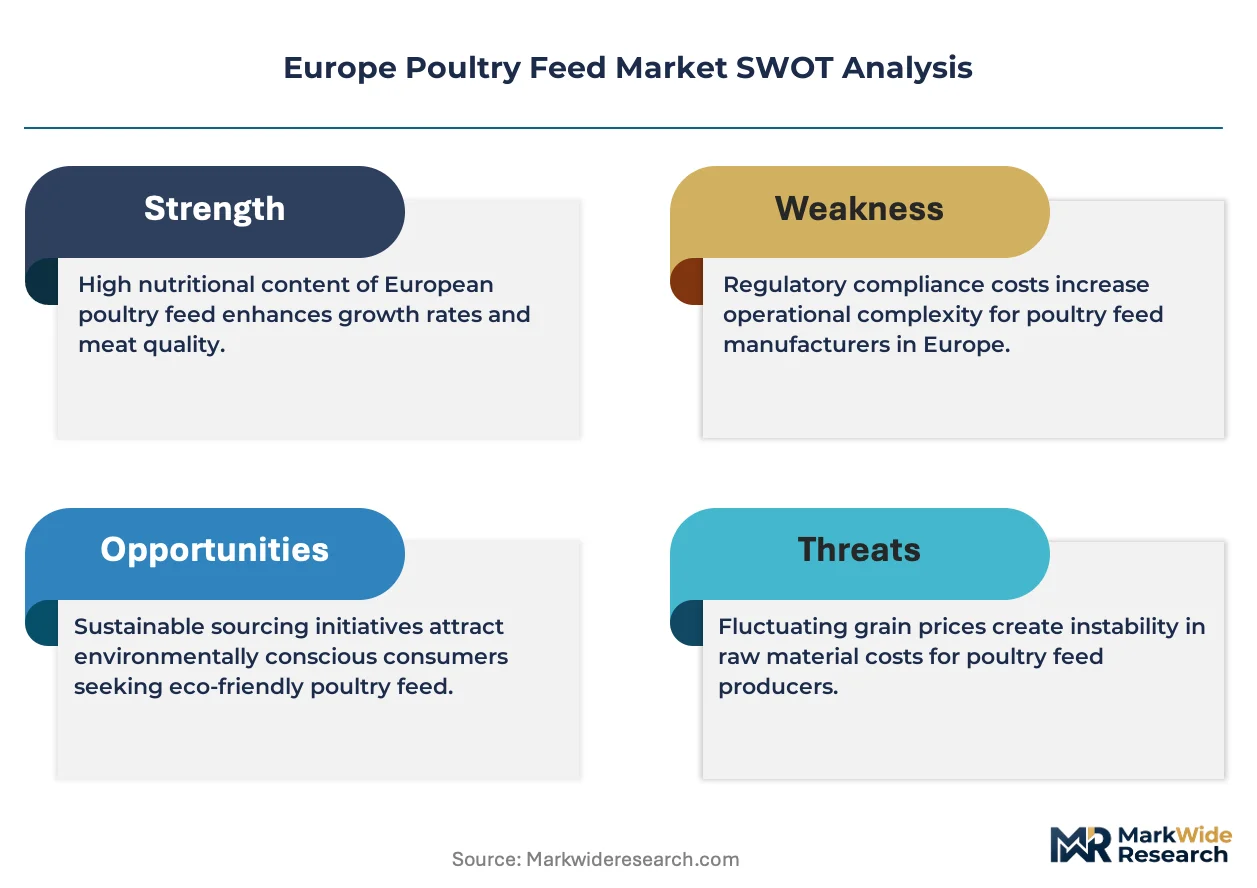
This market functions as a defensive-moat story anchored in regulatory entrenchment. EMA feed additive authorization timelines and REACH compliance costs create structural barriers that concentrate formulation expertise at large premix suppliers.
For Market Incumbents: Compound defensive positioning through captive premix manufacturing expansion in Poland and Romania, where Black Sea grain origination advantages meet underpenetrated production capacity. Deepen backward integration into novel enzyme portfolios before EMA streamlined pathways accelerate competitor entry. Threat vectors include insect protein regulatory opening and precision liquid feeding technology displacement of standardized rations.
For New Entrants and Emerging Players: Differentiate on domestic protein sourcing through black soldier fly meal formulations as EFSA novel food approvals create formulation white space. Target Polish and Romanian greenfield capacity zones where lower labor costs and proximity to Ukrainian grain flows offset incumbent scale advantages. Go-to-market angle: subscription-based precision nutrition services bundling real-time flock monitoring with dynamic ration adjustment.
For Investors and Strategic Acquirers: Carve-out targets emerge from agricultural cooperatives and independent millers facing REACH compliance cost fragmentation toward licensed premix dependence. Long-term viability favors vertically integrated nutrition houses with captive grain origination and regulatory affairs capacity. Signal to monitor: EMA authorization velocity for postbiotic gut health modifiers as inflection indicator for formulation innovation returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Premix Manufacturing | Captive supply of REACH-authorized enzymes tightens margin control for Dutch compounders. |
| Black Sea Grain Corridor Sourcing Expansion | Romanian and Polish port access diversifies cereal procurement for Spanish millers. |
| Insect Protein Formulation Development | EFSA novel food approvals for black soldier fly meal enable domestic protein substitution. |
| Precision Nutrition Service Launch | Real-time flock monitoring subscription models erode value of standardized compound rations. |
| Deforestation-Free Certification Investment | RSPO and FEFAC Soy Sourcing Guidelines compliance secures retailer procurement consolidation. |
Research Methodology
Initial hypotheses were tested against primary input from compound feed plant managers, poultry integration procurement directors, EMA regulatory affairs specialists, and agricultural cooperative supply planners, then refined through secondary validation. Primary fieldwork drew from structured interviews across Dutch, German, French, Spanish, and Polish operations. Secondary sources encompassed EU trade statistics, FEFAC annual feed reports, EMA feed additive authorization databases, and national agricultural ministry production records. Bottom-up volume modeling triangulated against top-down expenditure estimates across the analysis window.
Variance decomposition separated volume drivers from price effects across product type, ingredient category, end-user integration level, and distribution channel dimensions. CAGRs derived from segment-level growth rate reconciliation against aggregate market trajectory. Industry-specific forecast inputs incorporated Black Sea grain corridor throughput assumptions and EMA authorization pipeline velocity for novel enzymes and postbiotic formulations.
Forecasts assume regulatory continuity in EU Green Deal implementation, REACH enforcement, and EMA feed additive pathways; material policy shifts would require re-modeling. Specific risk factors include deforestation-free mandate acceleration, natural gas price volatility affecting thermal conditioning costs, and Brazilian export disruption. Revision becomes warranted when Black Sea grain corridor stability indicators cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Feed Protein Market
Agriculture and Agri Products
Rutin Market
Agriculture and Agri Products
Lucerne Market
Agriculture and Agri Products
Middle East Animal Protein Market
Agriculture and Agri Products
Spain Compound Feed Market
Agriculture and Agri Products
Dairy Cattle Feed Market
Agriculture and Agri Products
Compound Feed Market
Agriculture and Agri Products
Cambodia Agriculture Market
Agriculture and Agri Products
Chaga Mushroom Market
Agriculture and Agri Products
Canada Bamboos Market
Agriculture and Agri Products
Global Industrial Hemp Market
Agriculture and Agri Products
Japan Compound Feed Market
Agriculture and Agri Products
Residential Organic Compost Market
Agriculture and Agri Products
Tarragon Market
Agriculture and Agri Products
Colombia Hemp Market
Agriculture and Agri Products
Sophora Japonica Market